
 Vision Care Market | 2026-2036
Vision Care Market Size, Share, and Industry Trends Forecast 2026-2036
Vision Care Market Intelligence
Digital surfacing technology for ophthalmic lenses is tilting the production process from mass manufacturing towards highly personalized, patient-specific designs. EssilorLuxottica leverages its vast retail footprint and brand portfolio to dominate both lens and frame segments. Meanwhile, Alcon Inc. specializes in surgical products and advanced contact lens technologies for medical applications. The Zeiss Group competes on the basis of precision optics and diagnostic instrumentation, anchoring its position in the premium segment.
Vision care encompasses products and services designed to correct refractive errors, treat eye diseases, and enhance visual performance. This includes ophthalmic lenses fabricated from materials like high-index plastics or Trivex, and contact lenses made from silicone hydrogel polymers that offer high oxygen permeability. While eyeglasses and contact lenses constitute the largest product segments, myopia control applications represent the fastest-growing area of treatment. Sales are increasingly moving towards online retailers and large optical chains, shifting volume from independent optometry clinics.
Market access is governed by stringent medical device regulations, including the FDA's 510(k) pathway in the United States and the CE marking requirements under the MDR in Europe. In China, the NMPA enforces its own set of standards for product registration, creating distinct compliance hurdles for manufacturers. Stakeholders must now decide how to balance investments in therapeutic innovations against the expansion of direct-to-consumer digital sales channels.
Market Dynamics
The central force reshaping the vision care market is the industrial shift from mass manufacturing to patient-specific production. Digital surfacing technology enables highly personalized ophthalmic lenses, directly meeting demand for customized visual correction and therapeutic applications.
Growth Catalysts
- Myopia Control Innovations:Specialized lenses and therapies for pediatric populations address rising myopia prevalence, creating a major new treatment segment.
- Aging Demographics:In economies like Japan, rising presbyopia incidence sustains demand for advanced progressive and multifocal lens technologies.
- Digital Eye Strain:Pervasive screen time drives sales of lenses with blue-light filtering and anti-fatigue designs to mitigate computer vision syndrome.
Market Restraints
- High Material Costs:The expense of inputs like high-index plastics limits affordability of advanced lenses for mass-market consumers.
- Regulatory Friction:Navigating divergent pathways like the FDA's 510(k) and Europe's MDR creates significant time and cost barriers for new entrants.
- Channel Consolidation:The market power of large optical chains shifts sales from independent optometrists, applying price pressure on lens suppliers.
Strategic Opportunities
- Smart Contact Lenses:Integrating biosensors for health monitoring like glucose tracking opens a new market at the intersection of vision care and medtech.
- Direct-to-Consumer Expansion:Online sales channels allow manufacturers to bypass traditional retail, engage consumers directly, and capture higher margins.
- Pediatric Myopia in Asia:Advanced myopia control solutions can address the significant, underpenetrated pediatric market in countries with high prevalence.
Industry Challenges
- Divergent Global Standards:Manufacturers must manage distinct compliance hurdles for product registration, including the NMPA in China, the FDA in the US, and CE marking in Europe.
- Digital Investment Balancing:Stakeholders face difficult capital allocation decisions between therapeutic R&D and building costly direct-to-consumer digital sales infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vision Care Market |
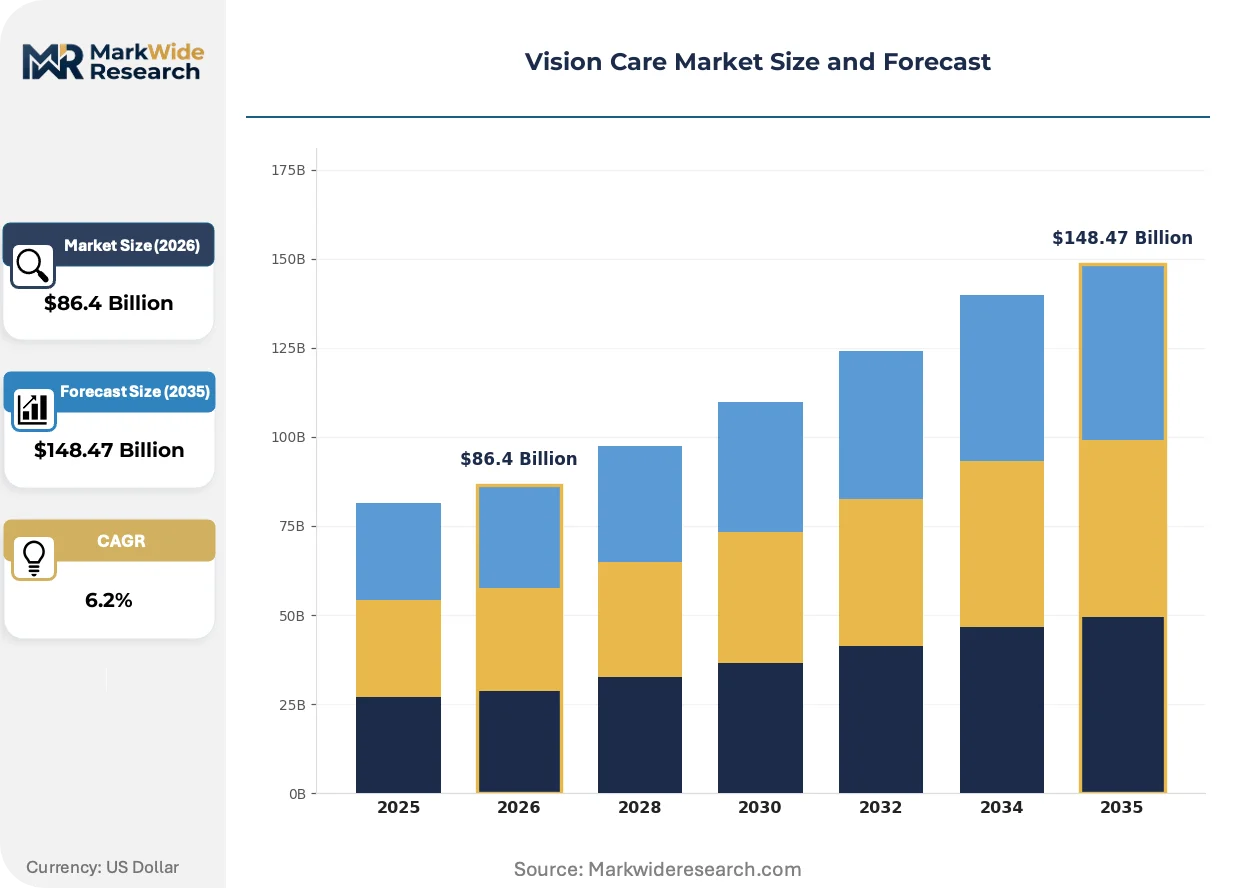
| Market Size in 2026 | $86.4 Billion |
| Market Size in 2035 | $148.47 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Eyeglasses, Contact Lenses, Sunglasses, Eye Drops, Optical Instruments Application: Myopia Control, Presbyopia Correction, Cataract Surgery, Glaucoma Management, Dry Eye Treatment End User: Optometry Clinics, Ophthalmology Centers, Retail Optical Stores, Online Retailers Distribution Channel: Specialty Stores, E-commerce Platforms, Pharmacies, Hospitals, Optical Chains |
| Companies Covered | Bausch + Lomb, Hoya Corp., EssilorLuxottica, Menicon, Zeiss Group, Alcon Inc., CooperVision, Seiko Optical Products, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vision Care Market Strategic Shifts & Innovations
Personalization is redefining the vision care industry, moving it beyond simple refractive correction. The sector is integrating advanced digital fabrication with biosensing capabilities, creating new paradigms for treatment and proactive health management.
Digital surfacing technology facilitates the fabrication of ophthalmic lenses based on precise, individual patient data like eye rotation and frame fit. High-end optometry clinics are rapidly adopting this process for complex progressive and specialized lenses. This level of customization is rendering obsolete the one-size-fits-all, mass-manufacturing model for premium lens production.
Europe's Medical Device Regulation (MDR) imposes stricter clinical evidence and post-market surveillance requirements for products like contact lenses. This forces manufacturers to generate more extensive safety data, increasing compliance costs and development timelines. The advanced contact lens segment is most affected, with some firms rationalizing portfolios to manage the regulatory burden.
Consumer purchasing behavior is shifting decisively toward online retailers and large optical chains for both eyeglasses and contact lenses. This channel disintermediation challenges the traditional product sales model of independent optometry clinics. The trend is most visible in the United States and Germany, where e-commerce is mature and consumers prioritize convenience.
Vision Care Market Segmentation
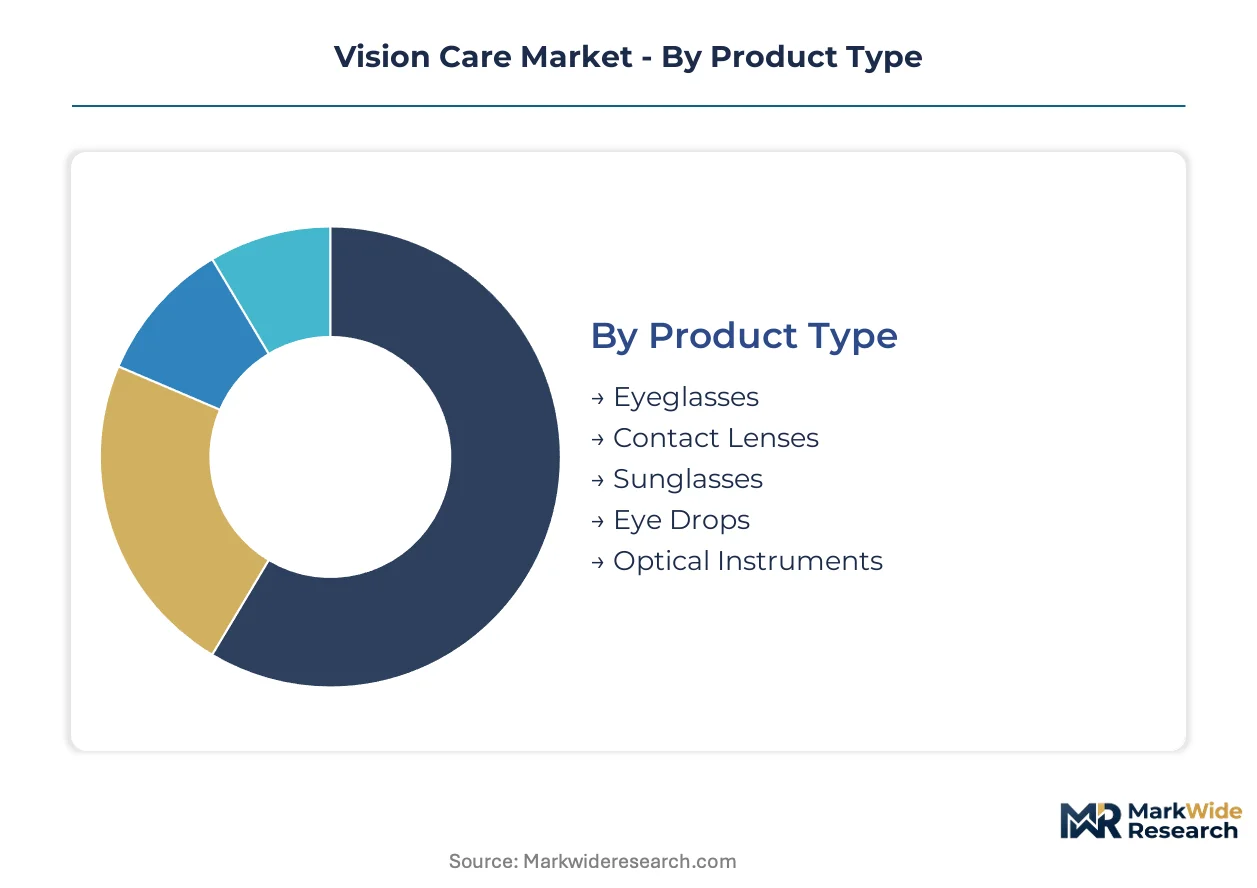
The vision care market's segmentation reveals the diverse product ecosystem and evolving consumer engagement models. Understanding these distinct segments allows stakeholders to identify areas of rapid expansion and areas where established product categories maintain market dominance.
Product Type:
The turnover cycle varies significantly across product types, from frequently replaced contact lenses to durable optical instruments.
- Eyeglasses:These products include ophthalmic lenses fabricated from high-index plastics or Trivex, set in various frame designs. Demand concentrates in developed economies like Germany and Japan due to aging demographics and increasing screen time.
- Contact Lenses:Made from silicone hydrogel polymers, these lenses offer high oxygen permeability for vision correction and medical applications. Technological advancements in smart contact lenses, integrating biosensors for health monitoring, create new product categories.
- Sunglasses:These eyewear products provide protection from UV radiation and glare, often incorporating prescription lenses. Fashion trends and outdoor activities drive consumer purchasing decisions.
- Eye Drops:Formulations for lubricating eyes, reducing redness, or delivering medication for conditions like glaucoma. Over-the-counter and prescription options serve diverse patient needs.
- Optical Instruments:Diagnostic equipment like phoropters, slit lamps, and retinal cameras used by optometrists and ophthalmologists. Precision optics and advanced diagnostic capabilities define this segment.
Eyeglasses dominate the installed base. Contact Lenses is where expansion concentrates.
Application:
Volume distribution across applications highlights both established treatments and emerging therapeutic areas within vision care.
- Myopia Control:Specialized lenses and therapies, often targeting pediatric populations, aim to slow the progression of nearsightedness. Rising myopia prevalence globally, particularly in Asia, drives significant demand for these solutions.
- Presbyopia Correction:This segment involves advanced progressive and multifocal lens technologies designed to correct age-related farsightedness. Aging demographics in countries like Japan sustain a consistent demand for these sophisticated products.
- Cataract Surgery:Products and services related to the surgical removal of cataracts and implantation of intraocular lenses. This segment addresses a common age-related eye condition.
- Glaucoma Management:Pharmaceutical treatments and surgical interventions for glaucoma, a group of eye conditions that damage the optic nerve. Regular monitoring and long-term treatment characterize this application.
- Dry Eye Treatment:Solutions ranging from artificial tears to prescription medications addressing chronic dry eye syndrome. Increased screen time contributes to the prevalence of this condition.
Presbyopia Correction accounts for the largest volume in adult refractive correction. Myopia Control represents the fastest-growing trajectory.
End User:
Customer types delineate where vision care products and services are consumed, reflecting shifts in purchasing behavior.
- Optometry Clinics:Independent practices providing comprehensive eye exams, refractive correction, and fitting of eyeglasses and contact lenses. These clinics historically served as primary sales channels.
- Ophthalmology Centers:Medical facilities specializing in eye disease diagnosis, treatment, and surgical procedures. These centers often leverage advanced diagnostic instrumentation and surgical products.
- Retail Optical Stores:Brick-and-mortar outlets, including large optical chains like those leveraged by EssilorLuxottica, offering frames, lenses, and eye care services. These stores capture significant consumer volume.
- Online Retailers:E-commerce platforms facilitating direct-to-consumer sales of contact lenses, eyeglasses, and accessories. This channel disintermediation challenges traditional product sales models in the United States and Germany.
Retail Optical Stores command the largest customer base for product sales. Online Retailers are gaining share fastest.
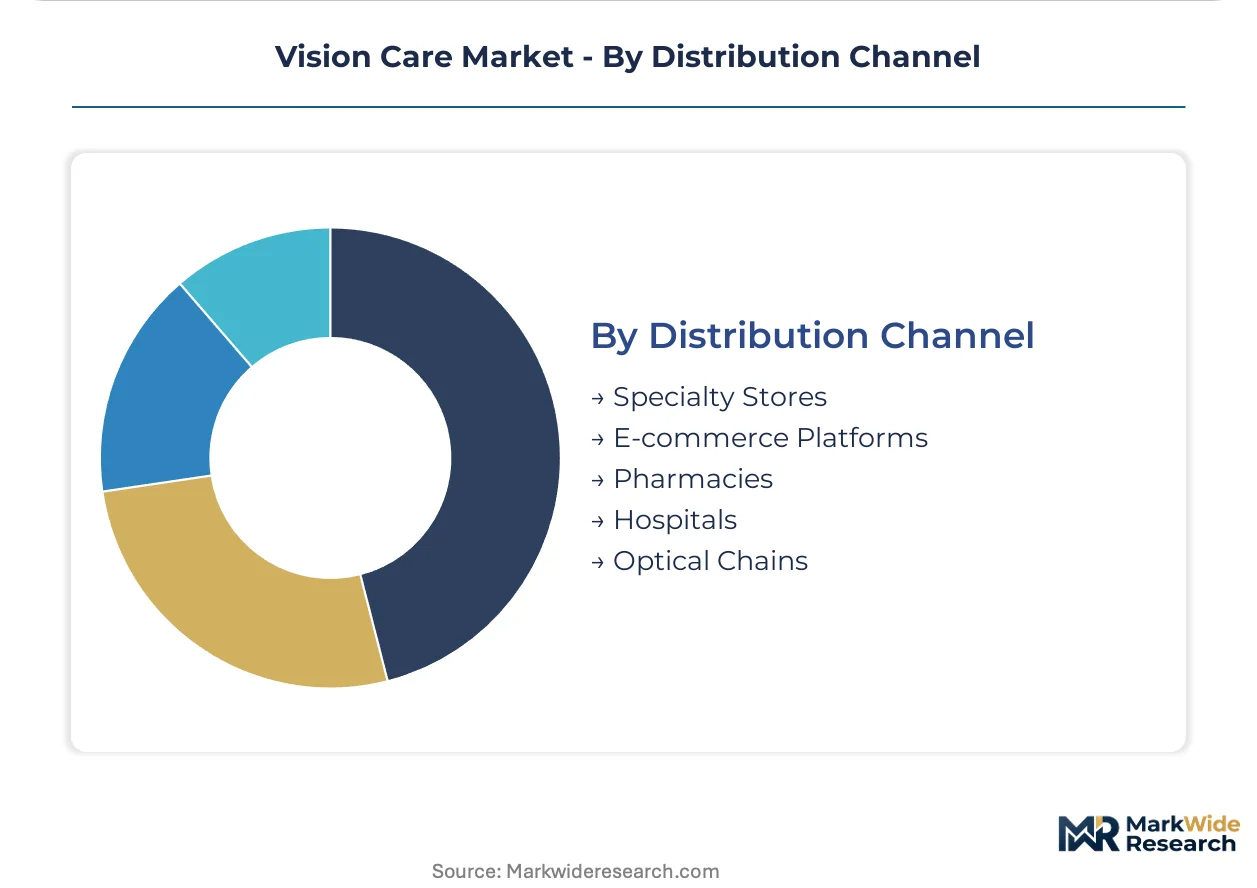
Distribution Channel:
Margin structures vary significantly across distribution channels, influencing manufacturer strategies for market access.
- Specialty Stores:Retail outlets focusing exclusively on eyewear, often providing personalized service and premium product selections. These stores cater to discerning customers.
- E-commerce Platforms:Digital marketplaces and direct-to-consumer websites where manufacturers and retailers sell vision care products. This channel allows manufacturers to bypass traditional retail and capture higher margins.
- Pharmacies:Retail pharmacies offering a limited selection of contact lenses, reading glasses, and eye drops. These outlets provide convenience for basic vision care needs.
- Hospitals:Medical institutions where ophthalmological services, including surgeries and advanced treatments, are performed. Hospitals serve as a critical channel for specialized medical vision care.
- Optical Chains:Large, multi-location retail networks that consolidate purchasing power and apply price pressure on lens suppliers. These chains shift sales volume from independent optometry clinics.
Optical Chains distribute the highest volume of products. E-commerce Platforms offer manufacturers the most direct margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Developed economies with aging populations and high digital screen time represent a significant concentration of vision care demand. These regions exhibit a strong need for advanced refractive correction, specialized therapies for age-related conditions, and solutions for digital eye strain. Consumers in these markets also show a preference for personalized vision solutions and convenient purchasing channels.
United States
United States consumers exhibit strong demand for advanced contact lenses and multifocal solutions driven by aging demographics and extensive screen use. The FDA's 510(k) pathway governs medical device approvals, influencing market entry and innovation. California's technology hubs foster development of smart contact lenses and digital eye care platforms.
Germany
German demand for vision care products is sustained by an aging population and increasing digital eye strain. CE marking requirements under Europe's MDR impose stringent standards for product safety and performance. Munich's precision optics industry contributes significantly to advanced ophthalmic lens production.
Japan
Japan experiences consistent demand for advanced progressive and multifocal lens technologies due to its rapidly aging demographics. The PMDA regulates medical devices, impacting product registration and market access for innovations. Tokyo's medical technology sector drives research into diagnostic instrumentation and specialized lens designs.
China
China presents significant demand for myopia control solutions, particularly within its large pediatric population, alongside growing digital eye strain. The NMPA enforces specific standards for product registration, creating compliance hurdles for manufacturers. Shanghai's medical device industry actively develops and localizes advanced vision care technologies.
India
India shows a substantial need for basic refractive correction and growing interest in advanced vision solutions due to increasing disposable income. The CDSCO regulates medical devices, establishing guidelines for manufacturing and sales of vision care products. Bengaluru's healthcare technology startups focus on developing affordable and accessible eye care diagnostics.
Vision Care Market Key Industry Players
Channel-controlling players compete with product-specialist players in the vision care market, creating a tiered competitive landscape. This market structure features vertically integrated giants alongside niche technology providers and diagnostic instrument manufacturers. Strategic archetypes include diversified optical conglomerates, advanced contact lens specialists, and precision optics manufacturers. Dominant competitive moves involve strategic partnerships for technological integration and portfolio diversification into therapeutic innovations.
Within the diversified optical conglomerates, EssilorLuxottica exemplifies a vertically integrated model, leveraging its vast retail footprint and extensive brand portfolio across both frames and lenses. This company's market presence spans multiple product categories and distribution channels. Alcon Inc. occupies a position as a specialist in surgical products and advanced contact lens technologies, anchoring its focus on medical applications and innovation in medical-grade materials. The Zeiss Group sits within the premium segment, representing precision optics and diagnostic instrumentation manufacturing expertise for high-end ophthalmic solutions.
| Leading Market Players |
|---|
| Bausch + Lomb |
| Hoya Corp. |
| EssilorLuxottica |
| Menicon |
| Zeiss Group |
| Alcon Inc. |
| CooperVision |
| Seiko Optical Products |
| Johnson & Johnson |
| Others |
Cost & Logistics Intelligence
Regulatory friction across diverse global pathways significantly determines both pricing tier spreads and the overall vision care supply chain shape.
Pricing Analysis
Cost-plus contract patterns with material indexation often govern pricing for high-volume lens procurement. Pricing stratifies across premium, standard, and economy tiers, driven by customization level for digital surfacing and brand premium for precision optics. Channel consolidation, particularly through large optical chains, exerts downward pressure on lens supplier pricing. Online retailers represent the most price-sensitive buyer segment, while independent optometry clinics often command higher prices for specialized, patient-specific products.
Supply Chain Analysis
Export-control regimes for specialized ophthalmic components limit global technology flows, influencing regional production hubs. Supply concentrates in countries like Germany for precision optics, Japan for advanced lens materials, and China for high-volume manufacturing. Raw material dependencies include high-index plastics, silicone hydrogel polymers, and biosensors for smart lenses. Regulatory restriction, such as CE marking under Europe's MDR, creates a structural risk for market access. Large optical chains and online retailers dominate downstream distribution, shifting volume from traditional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
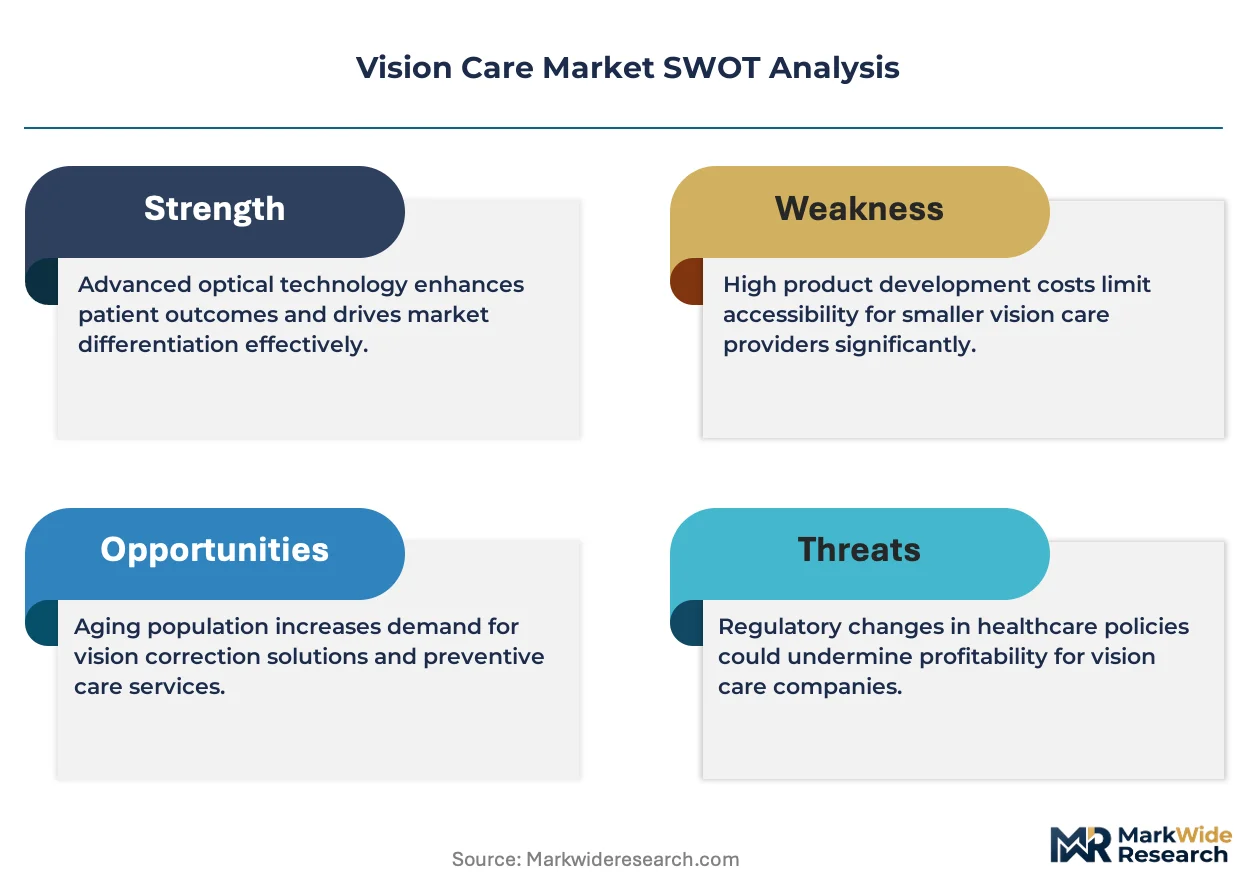
The vision care market represents a high-growth disruption, driven by the technological inflection of smart contact lenses.
For Market Incumbents:
Insulate core revenue streams by leveraging existing retail footprints and brand portfolios. Invest in R&D for therapeutic innovations like myopia control and advanced lens materials. Strengthen channel control against digital disintermediation and price pressure from large optical chains. Strategic partnerships with medtech firms for biosensor integration can expand product capabilities.
For New Entrants and Emerging Players:
Pursue white-space opportunities in underpenetrated segments with innovative go-to-market strategies. Pediatric myopia control in high-prevalence Asian markets offers significant unaddressed demand. The intersection of vision care and medtech with smart contact lenses presents a fertile ground for novel solutions. Direct-to-consumer digital sales channels bypass traditional retail and capture higher margins.
For Investors and Strategic Acquirers:
The market sits at a dynamic growth phase that favors niche technology providers and therapeutic innovators. Long-term viability is sustained by aging demographics, rising myopia prevalence, and increasing digital eye strain. Specialized firms developing advanced digital surfacing technology or biosensor-integrated contact lenses represent attractive acquisition archetypes. Watch for increased regulatory approvals for novel myopia control solutions or smart lens functionalities as key inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Surfacing Technology Integration | Enhances personalization for ophthalmic lenses, meeting demand for patient-specific designs. |
| Myopia Control R&D | Addresses rising pediatric myopia prevalence, creating a major new treatment segment. |
| Smart Contact Lens Development | Opens a new market at the intersection of vision care and health monitoring. |
| Direct-to-Consumer Channel Expansion | Allows manufacturers to bypass traditional retail and capture higher margins directly. |
| Regulatory Pathway Streamlining | Facilitates faster market access for innovative products across diverse geographies. |
Research Approach
The analysis maps distinct vision care sub-sectors, each validated through extensive primary interviews with industry stakeholders. We engaged optometrists, ophthalmologists, optical chain executives, lens manufacturers, and regulatory affairs specialists. Secondary data sources included FDA 510(k) clearances, CE marking databases, NMPA product registrations, and company annual reports. A bottom-up and top-down approach triangulated market data for robust validation.
Assumptions regarding technological advancements and market dynamics were held constant across the analysis window for the forecast framework. The analytical framework covers the entire projection horizon. Segmentation dimensions modeled include product type, application, end-user, distribution channel, and geographic region. Compound annual growth rates were derived from historical trends, market growth drivers, and expert projections. Key forecast inputs included myopia prevalence rates and aging population statistics.
Macroeconomic conditions sit as an overlay; deviation in global economic stability or healthcare spending would shift the trajectory. Forecasts reflect assumptions regarding regulatory stability and consumer behavior. Unexpected regulatory changes, rapid shifts in consumer purchasing behavior, or significant material cost fluctuations pose risks. Material shifts in regulatory landscapes or core material science would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Ophthalmology Diagnostics and Surgical Devices Market
Ophthalmology
Corneal Edema Treatment Market
Ophthalmology
Brazil Ophthalmic Devices Market
Ophthalmology
USA Ophthalmic Devices Market
Ophthalmology
Global Ophthalmology Market
Ophthalmology
Global Ophthalmic Sutures Market
Ophthalmology
Meibomian Gland Dysfunction Treatment Market
Ophthalmology
Vitreous Detachment Treatment Market
Ophthalmology
Laser Indirect Ophthalmoscope Market
Ophthalmology
Eye Care Surgical Market
Ophthalmology
Ophthalmic Ultrasound Systems Market
Ophthalmology
Vitrectomy Machines Market
Ophthalmology
Ophthalmic Femtosecond Lasers Market
Ophthalmology
Tonometry Market
Ophthalmology
Sodium Hyaluronate Eye Drops Market
Ophthalmology
Synoptophore Market