
 Asia-Pacific Oilfield Auxiliary Rental Equipment Market | 2026-2036
Asia-Pacific Oilfield Auxiliary Rental Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Oilfield Auxiliary Rental Equipment Market Analytics
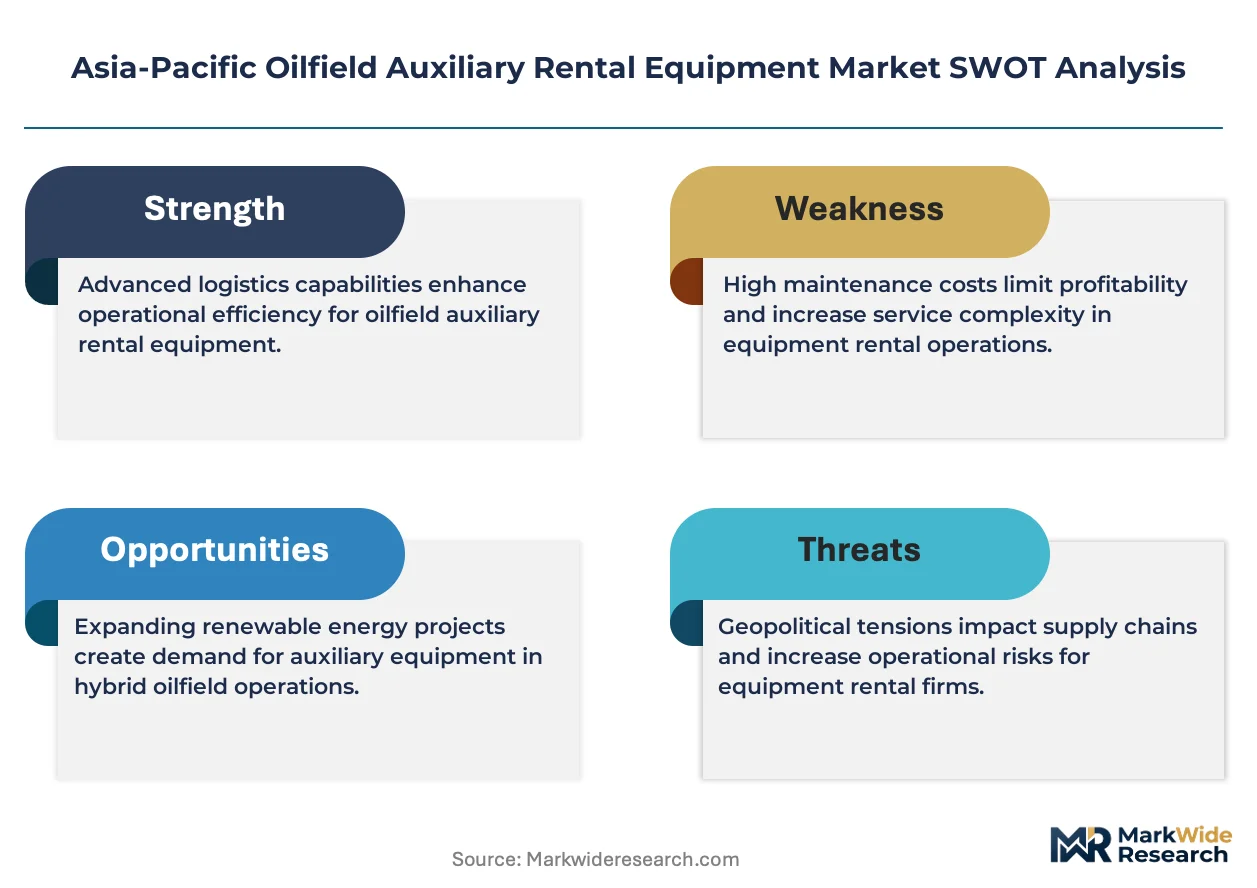
Australian offshore fabricators is repositioning capacity toward subsea support vessels and modular platform components. Schlumberger leverages its integrated drilling support portfolio across Southeast Asian contract rounds. Baker Hughes sustains compressor rental dominance through localized service hubs in Perth and Singapore. National Oilwell Varco anchors its position in mobile offshore unit auxiliary systems across the region's shallow-water developments.
Asia-Pacific oilfield auxiliary rental equipment encompasses temporary mechanical, electrical, and fluid-handling systems—typically rated for 5,000–15,000 psi operating pressure and certified for H2S service—that oil and gas operators lease rather than own to preserve capital flexibility and reduce maintenance liability. These systems serve drilling, completion, and production phases where asset utilization rates fluctuate with reservoir economics and regulatory cycles. Generators and compressors command the largest equipment-type revenue pools due to their universal need across onshore and offshore installations, while pumps exhibit faster structural growth tied to hydraulic fracturing adoption in Australia's unconventional plays. Offshore operators represent the most concentrated end-user segment by value, though drilling contractors generate higher transaction frequency and shorter rental durations that compress working-capital cycles.
MEE enforces China's dual carbon goals through emissions intensity benchmarks that favor newer, more efficient auxiliary equipment over legacy diesel-powered fleets. Australia's NOPSEMA mandates well-control equipment certification that elevates rental standards for BOP handling and pressure-testing auxiliaries. India's CEA electrical safety codes govern generator deployments in Assam and Mumbai High fields, creating compliance-driven replacement cycles. Stakeholders must track how Indonesia's upstream regulator revises local-content thresholds for imported rental equipment, as this determines whether global suppliers establish domestic assembly or cede share to emerging local fabricators.
Market Dynamics
China's dual carbon goals under MEE oversight are compressing demand for legacy diesel-powered auxiliary fleets while accelerating specifications for electrified, lower-emission rental equipment across drilling and production contracts.
Growth Catalysts
- Deepwater exploration off Australia's northwest shelf:Subsea handling systems face concentrated demand as operators lease modular BOP and riser auxiliary packages rather than own depreciating assets.
- MEE emissions intensity benchmarks:China's enforcement of dual carbon goals favors newer auxiliary equipment with certified fuel efficiency, creating replacement cycles for rental providers with compliant fleets.
- Hydraulic fracturing adoption:Australia's unconventional plays in the Cooper and Canning basins drive structural growth for high-pressure pump rentals rated above 10,000 psi.
Market Restraints
- Steel alloy input volatility:Pressure-rated vessel and piping fabrication depends on chromium-molybdenum alloy pricing that fluctuates with stainless steel commodity cycles.
- NOPSEMA certification friction:Australia's well-control equipment mandates extend rental equipment commissioning timelines by 15-30 days for BOP handling auxiliaries.
- Electrification capex gap:Battery-hybrid auxiliary systems carry 40-60% higher rental rates than diesel equivalents, limiting adoption among cost-sensitive drilling contractors.
Strategic Opportunities
- Indonesia's local-content threshold revisions:SKK Migas regulatory shifts may force global suppliers toward domestic assembly partnerships or cede share to emerging fabricators in Batam and Surabaya.
- Modular platform component demand:Australian offshore fabricators repositioning toward subsea support vessels create white space for integrated auxiliary system leasing.
- CEA electrical safety compliance:India's generator deployment codes in Assam and Mumbai High fields drive compliance-driven replacement cycles for certified rental fleets.
Industry Challenges
- H2S service technician scarcity:Sour gas certification requirements for auxiliary equipment maintenance outpace regional training pipeline capacity.
- Legacy fleet integration complexity:Electrified auxiliary systems face interoperability friction with existing diesel-powered rig power distribution architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Oilfield Auxiliary Rental Equipment Market |
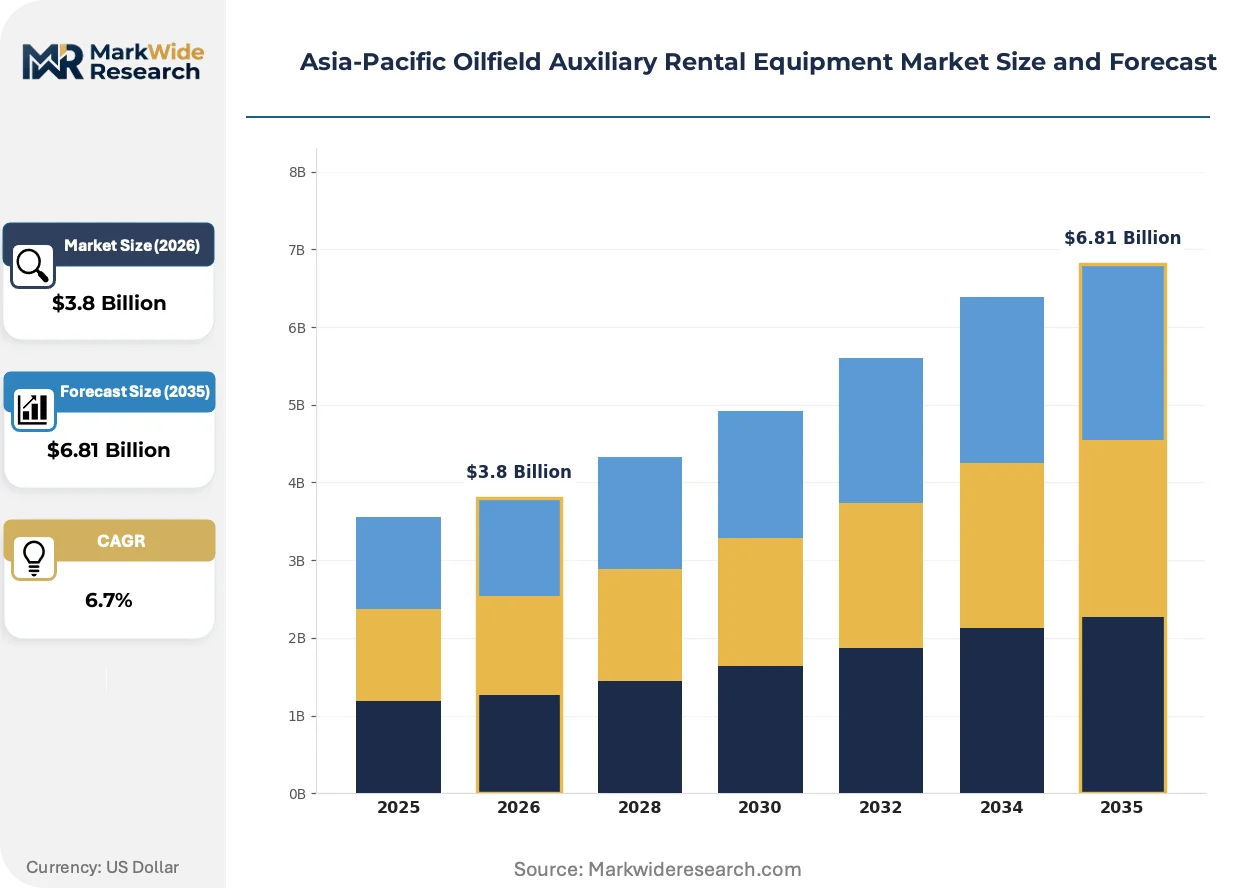
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Generators, Compressors, Pumps, Tankers Service Type: Drilling Support, Maintenance, Transport, Logistics End User: Oil Explorers, Drilling Contractors, Service Companies, Offshore Operators Installation Type: Onshore, Offshore, Mobile, Fixed |
| Companies Covered | Schlumberger, Halliburton, Baker Hughes, Weatherford International, National Oilwell Varco, Oil States International, Superior Energy Services, TechnipFMC, China National Petroleum Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Oilfield Auxiliary Rental Equipment Market Evolving Landscape
Equipment standardization and digital monitoring integration are compressing rental cycle variability while enabling outcome-based performance guarantees that shift risk from operators to rental providers.
Subsea handling systems are modularizing around standardized interface specifications that allow rapid reconfiguration between drilling, completion, and intervention modes. Offshore contractors in Australia's northwest shelf are adopting these packages at accelerating pace to reduce mobilization downtime between well phases. This standardization is modularizing supplier value chains by decoupling pressure-control skids from power-generation modules.
MEE's dual carbon enforcement is tightening emissions intensity benchmarks for auxiliary equipment deployed in China's onshore and offshore fields. The regulation compresses allowable fuel consumption per operating hour, effectively disqualifying pre-2015 diesel generator fleets from new contract eligibility. Drilling contractors in Sichuan and Bohai Bay are responding by specifying Tier 4 final or hybrid-electric auxiliary packages in tender documents.
Performance-based rental contracts are displacing traditional day-rate structures for high-utilization auxiliary categories like compressors and generators. National oil companies in Indonesia and Malaysia are unbundling maintenance liability from capital expenditure, transferring uptime risk to rental providers. This shift concentrates most visibly in offshore Malaysia where Petronas contract templates now mandate availability guarantees above 95% for critical power auxiliaries.
Asia-Pacific Oilfield Auxiliary Rental Equipment Market Segmentation
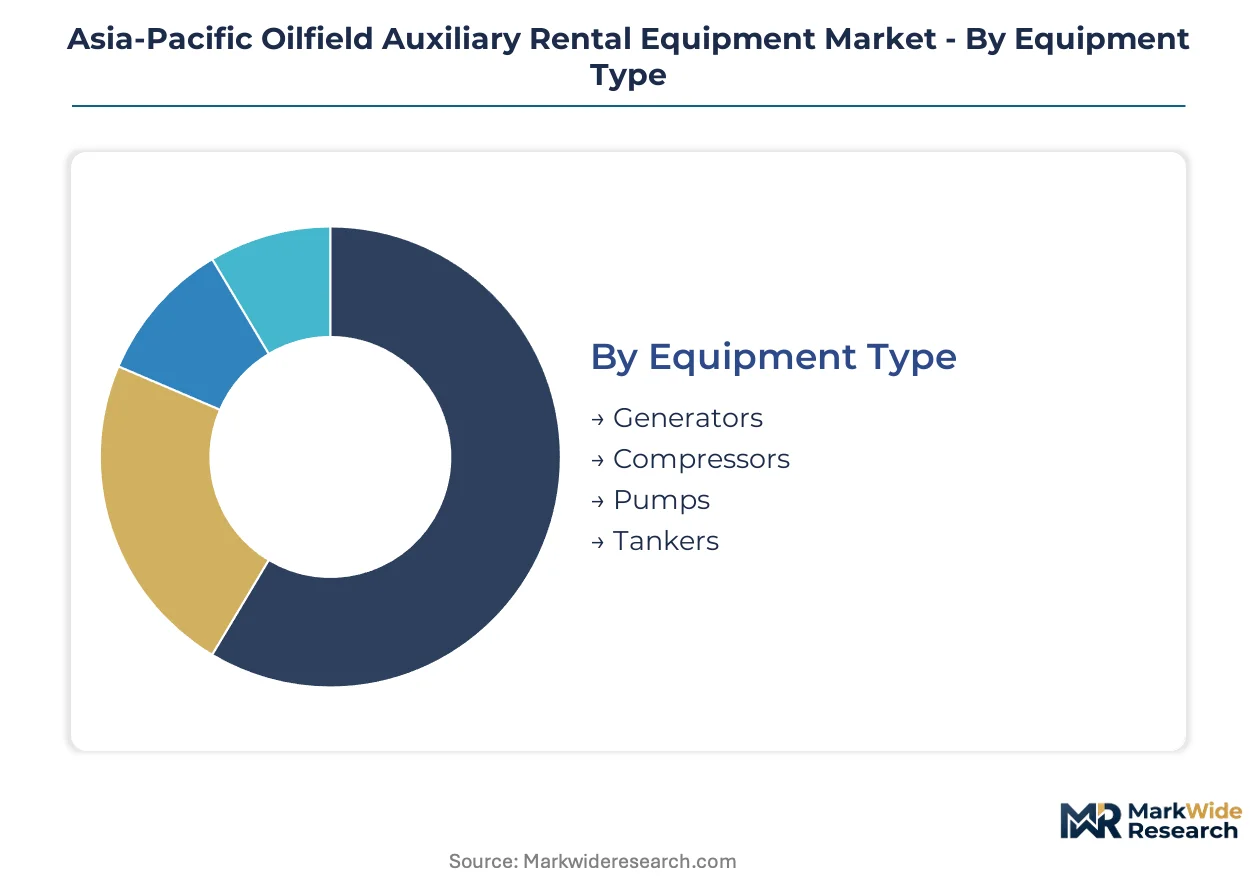
Equipment specification tiers and service intensity levels determine rental economics across Asia-Pacific oilfield operations. Segmentation reveals where capital flexibility versus ownership trade-offs concentrate by deployment context.
Equipment Type:
Pressure ratings and power density specifications define rental premiums and utilization cycles across the category.
- Generators:Diesel and hybrid-electric power units rated 500kW–2MW serve drilling rig electrification and platform backup systems. Demand concentrates in Australia's northwest shelf developments where MEE emissions benchmarks in China simultaneously accelerate hybrid specifications and disqualify pre-2015 diesel fleets from new tenders.
- Compressors:Reciprocating and centrifugal units handle gas lift, pipeline injection, and wellhead pressure maintenance. Offshore operators in Indonesia's maturing basins drive concentrated demand for modular compressor skids with H2S service certification.
- Pumps:High-pressure positive displacement and centrifugal systems rated 5,000–15,000 psi handle drilling mud circulation, cementing, and hydraulic fracturing. Australia's Cooper and Canning basin unconventional plays are expanding most quickly for pump rentals above 10,000 psi.
- Tankers:Pressure vessels and atmospheric storage tanks handle completion fluids, produced water, and chemical storage. Mobile tanker demand tracks Indonesian offshore installation activity.
Mature deployment sits with Generators. Newer deployment is concentrated in Pumps.
Service Type:
Contract duration and technical liability allocation shape margin structures across service tiers.
- Drilling Support:BOP handling, pressure testing, and well control auxiliary systems command the highest rental rates due to NOPSEMA certification requirements. Australia's offshore contractors generate concentrated demand for modular drilling support packages.
- Maintenance:Scheduled overhaul and emergency repair services for rented auxiliary fleets. Service companies in Malaysia and Thailand are expanding maintenance outsourcing to preserve operational uptime.
- Transport:Heavy-lift and specialized haulage for auxiliary equipment mobilization between well sites. Mobile installation demand in Indonesia drives regional transport contract growth.
- Logistics:Inventory management, warehousing, and just-in-time equipment positioning. Offshore operators are consolidating logistics under integrated rental providers to reduce mobilization friction.
Established revenue concentration rests with Drilling Support. Emerging contract volume is shifting toward Logistics.
End User:
Capital intensity and asset utilization patterns differentiate rental behavior across customer types.
- Oil Explorers:Independent and national oil companies leasing auxiliary systems for appraisal and development drilling. China's onshore explorers under MEE oversight are specifying Tier 4 final equipment in Sichuan and Bohai Bay tenders.
- Drilling Contractors:Rig operators renting auxiliary equipment on well-by-well contracts. Transaction frequency runs highest here, though rental durations compress working-capital cycles.
- Service Companies:Completion and intervention specialists requiring specialized pumps and pressure-control skids. Hydraulic fracturing adoption in Australia is expanding service company pump rental demand.
- Offshore Operators:Platform and FPSO owners leasing critical power and compression auxiliaries. This segment commands the largest revenue concentration by value, with Petronas in Malaysia mandating 95% availability guarantees for critical power systems.
Volume leadership belongs to Offshore Operators. Transaction velocity peaks with Drilling Contractors.
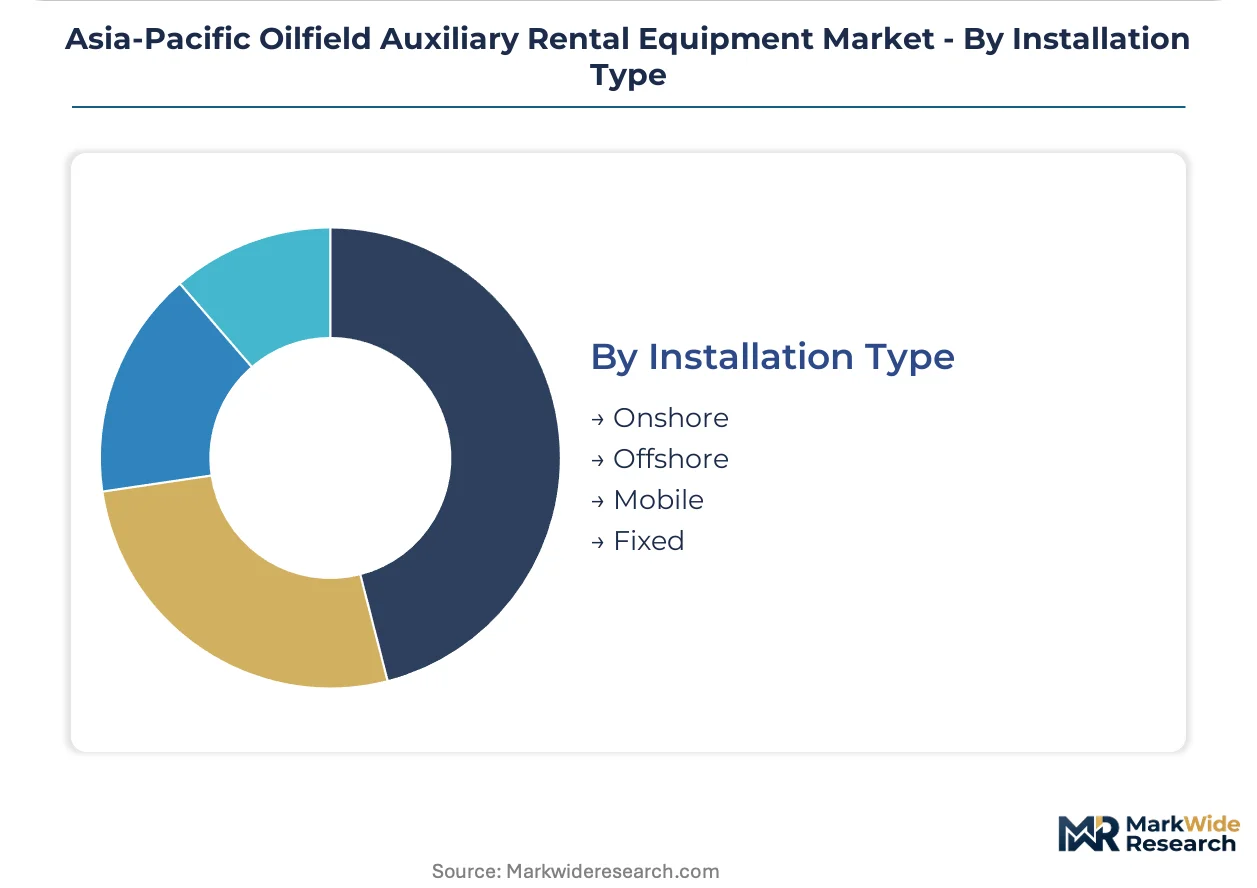
Installation Type:
Mobility requirements and environmental exposure determine equipment specification and rental terms.
- Onshore:Fixed-position auxiliary systems for drilling pads and production facilities. India's CEA electrical safety codes in Assam and Mumbai High fields drive compliance-driven replacement cycles for certified generator fleets.
- Offshore:Platform-mounted and subsea auxiliary systems with marine-grade corrosion protection. Australia's northwest shelf deepwater exploration concentrates demand for subsea handling system rentals.
- Mobile:Skid-mounted and trailer-transportable units for rapid wellsite relocation. Indonesia's maturing offshore basins are expanding mobile installation equipment demand.
- Fixed:Permanent installation auxiliary systems tied to production infrastructure. Long-term contracts characterize this tier, with lower rental premiums but extended duration commitments.
Contract value aggregates in Offshore. Flexibility premiums concentrate in Mobile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chromium-molybdenum alloy supply from Australian and Chinese steel mills anchors fabrication capacity for pressure-rated auxiliary vessels across the region.
Australia
Deepwater exploration off the northwest shelf drives concentrated demand for subsea handling system rentals. NOPSEMA mandates well-control equipment certification that extends commissioning timelines for BOP handling auxiliaries. Perth anchors regional service hub activity where fabricators reposition toward subsea support vessels.
China
Onshore explorers in Sichuan and Bohai Bay specify Tier 4 final equipment under tightening MEE emissions intensity benchmarks. The dual carbon goals disqualify pre-2015 diesel generator fleets from new contract eligibility. Beijing-Tianjin-Hebei industrial corridors concentrate domestic manufacturing of electrified auxiliary packages.
Indonesia
Maturing offshore basins expand demand for mobile installation equipment with rapid wellsite relocation capability. SKK Migas revises local-content thresholds that may force global suppliers toward domestic assembly partnerships. Batam and Surabaya emerge as fabrication centers where emerging local suppliers compete for import substitution.
India
CEA electrical safety codes govern generator deployments in Assam and Mumbai High fields, creating compliance-driven replacement cycles. Onshore drilling contractors face capital constraints that favor rental over ownership for auxiliary fleets. Maharashtra and Gujarat host the primary equipment staging and maintenance infrastructure.
Malaysia
Petronas contract templates mandate availability guarantees above 95% for critical power auxiliaries, shifting uptime risk to rental providers. Offshore operators consolidate logistics under integrated rental providers to reduce mobilization friction. Kuala Lumpur anchors regional procurement decision-making for Southeast Asian contract rounds.
Asia-Pacific Oilfield Auxiliary Rental Equipment Market Competitive Landscape
Global majors compete with regional champions across integrated service portfolios versus specialized equipment categories. The vendor base organizes around three tiers: full-service energy technology conglomerates with drilling-to-production coverage, standalone rental specialists with fleet-heavy balance sheets, and national oil company affiliates with captive domestic demand. Two dominant competitive moves define current positioning: strategic partnerships with offshore fabricators to secure modular platform contracts, and geographic expansion through localized service hubs to satisfy Indonesia's local-content thresholds.
Within the integrated technology tier, Schlumberger, Baker Hughes, and National Oilnow Varco occupy positions that exemplify divergent strategic emphases. Schlumberger represents the drilling support portfolio breadth archetype across Southeast Asian contract rounds. Baker Hughes anchors compressor rental dominance through established presence in Perth and Singapore service hubs. National Oilwell Varco sits within the mobile offshore unit auxiliary systems specialization, particularly across shallow-water developments. These three entities collectively illustrate how global scale interfaces with regional compliance requirements and basin-specific demand profiles.
| Leading Market Players |
|---|
| Schlumberger |
| Halliburton |
| Baker Hughes |
| Weatherford International |
| National Oilwell Varco |
| Oil States International |
| Superior Energy Services |
| TechnipFMC |
| China National Petroleum Corporation |
| Others |
Value Network & Pricing Analysis
Chromium-molybdenum alloy price indices from Australian and Chinese steel mills cascade directly into three-tier pricing structures across premium, standard, and economy equipment tiers. Pressure-rated vessel fabricators pass alloy volatility through to rental rates, while MEE emissions benchmarks in China compress allowable premiums for legacy diesel fleets.
Pricing Analysis
Warranty and maintenance bundling separates premium rental tiers from unbundled economy offerings. Contract-based long-term offtake dominates, with price differentiation driven by NOPSEMA certification grade and after-sales service intensity. Cost compression in standard-tier generator rentals is intensifying because drilling contractors face working-capital constraints. Offshore operators show lowest price sensitivity due to uptime guarantee requirements, while onshore drilling contractors in India and Indonesia exhibit highest sensitivity.
Supply Chain Analysis
Direct-to-operator channels handle fleet-scale demand from national oil companies, while specialized distributors serve fragmented drilling contractors. Manufacturing concentrates in China, Australia, and Singapore. Fabrication draws from chromium-molybdenum alloys, high-pressure seals, and marine-grade electrical components. Single-source vulnerability sits with Australian steel mill supply for pressure-rated vessels. Distribution runs through Perth, Singapore, and Batam hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing upstream control over alloy supply and fabrication capacity to defend margin position against commodity volatility.
For Market Incumbents: Anticipate SKK Migas local-content threshold enforcement by securing domestic assembly partnerships in Batam or Surabaya. Backward integration into chromium-molybdenum alloy sourcing hedges against steel price volatility. Certification investment in Tier 4 final and hybrid-electric fleets preserves contract eligibility under tightening MEE benchmarks.
For New Entrants and Emerging Players: Launch via modular platform component leasing to Australian offshore fabricators repositioning toward subsea support vessels. White space concentrates in mobile installation equipment for Indonesia's maturing basins. The most penetrable segment is hydraulic fracturing pump rentals above 10,000 psi in Australia's Cooper and Canning basins.
For Investors and Strategic Acquirers: Distressed-cycle entries favor fleet-heavy rental specialists with established NOPSEMA certification in Australian northwest shelf operations. Long-term viability hinges on electrification capex recovery and hybrid fleet depreciation schedules. Watch SKK Migas local-content enforcement intensity as inflection indicator for import substitution momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Assembly Partnership | SKK Migas local-content thresholds force global suppliers toward Batam fabrication joint ventures. |
| Hybrid Fleet Certification | MEE dual carbon benchmarks disqualify pre-2015 diesel generators from Sichuan and Bohai Bay tenders. |
| Subsea Handling System Modularization | Australian northwest shelf operators lease standardized BOP packages to reduce mobilization downtime. |
| Alloy Supply Integration | Upstream control over chromium-molybdenum sourcing buffers Perth and Singapore fabricators against steel volatility. |
| Performance-Based Contracting | Petronas 95% availability guarantees shift uptime risk from offshore operators to rental providers. |
Research Methodology
Multi-period observation of MEE enforcement intensity, NOPSEMA certification timelines, and SKK Migas regulatory revisions anchored the trend analysis, supplemented by interviews with drilling contractors, offshore operators, equipment procurement managers, and fabrication facility directors. Secondary validation drew from customs trade data, CEA electrical safety code filings, steel mill production reports, and upstream contract award databases. Bottom-up equipment fleet sizing and top-down regional expenditure estimates were triangulated.
The input-output matrix framed demand modeling across equipment type, service tier, end-user category, and installation mobility. Segmentation dimensions included pressure rating specifications, emissions certification grade, and contract duration structure. CAGRs were derived from equipment replacement cycle analysis and regulatory-driven fleet turnover rates. Forecast inputs incorporated hydraulic fracturing adoption curves in Australian basins and electrification capex recovery assumptions.
Regulatory enforcement delays, alloy price volatility spikes, and technician certification pipeline constraints are the dominant revision risks to base-case projections. Forecasts reflect assumptions about MEE benchmark stringency and SKK Migas threshold implementation pace. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Fittings Market
Oil & Gas
Digital Oil Rigs Market
Oil & Gas
Algeria Oil and Gas Downstream Market
Oil & Gas
Liquefied Natural Gas Market
Oil & Gas
Subsea Flowlines Market
Oil & Gas
North America Perforating Gun Market
Oil & Gas
Sudan Oil and Gas Market
Oil & Gas
Oil and Gas Digital Rock Analysis Market
Oil & Gas
Canada Oil and Gas Upstream Market
Oil & Gas
Southeast Asia LNG Market
Oil & Gas
Coiled Tubing System Market
Oil & Gas
Digital Oilfield Services Market
Oil & Gas
Oil and Gas Accumulators Market
Oil & Gas
Sensors in Oil and Gas Market
Oil & Gas
Kazakhstan Oil and Gas Downstream Market
Oil & Gas
North America Oil and Gas Storage Tank Market