
 Sand Screen Sales Market | 2026-2036
Sand Screen Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Sand Screen Sales Market Insights
Modular screen panel configurations bundled with quick-change frame systems is realigning buyer preference away from standalone component purchases. Sandvik AB leverages its metallurgical expertise to sustain premium positioning in high-wear mining applications. RHEWUM GmbH anchors its competitive stance through precision-engineered composite screen technologies for fine-separation tasks. Trelleborg differentiates via advanced polymer formulations that extend operational life in corrosive oilfield brines.
Sand screens are engineered filtration barriers, typically constructed from woven stainless steel wire mesh or sintered metal composites with aperture tolerances measured in microns, designed to block formation sand and particulate ingress while permitting hydrocarbon or fluid flow. Wire mesh screens dominate installed base volumes across mature oilfields where standardization reduces inventory complexity, while composite screens represent the fastest-expanding category as operators pursue weight reduction and corrosion resistance in deepwater and high-pressure deployments. The mining application segment commands substantial replacement demand due to abrasive wear cycles, whereas the water treatment end-use channel shows rising interest in retrofit installations as municipalities upgrade aging intake infrastructure.
API 19SS governs sand control screen design verification and performance testing for US oilfield service procurement, while China's MEE enforces stricter effluent standards that push water treatment facilities toward higher-efficiency screen media. ISO 17824 provides international baseline criteria for sand screen qualification that shapes cross-border supplier eligibility. Stakeholders must monitor evolving regulatory thresholds for particulate emissions and screen disposal to anticipate product redesign cycles and certification investments.
Market Dynamics
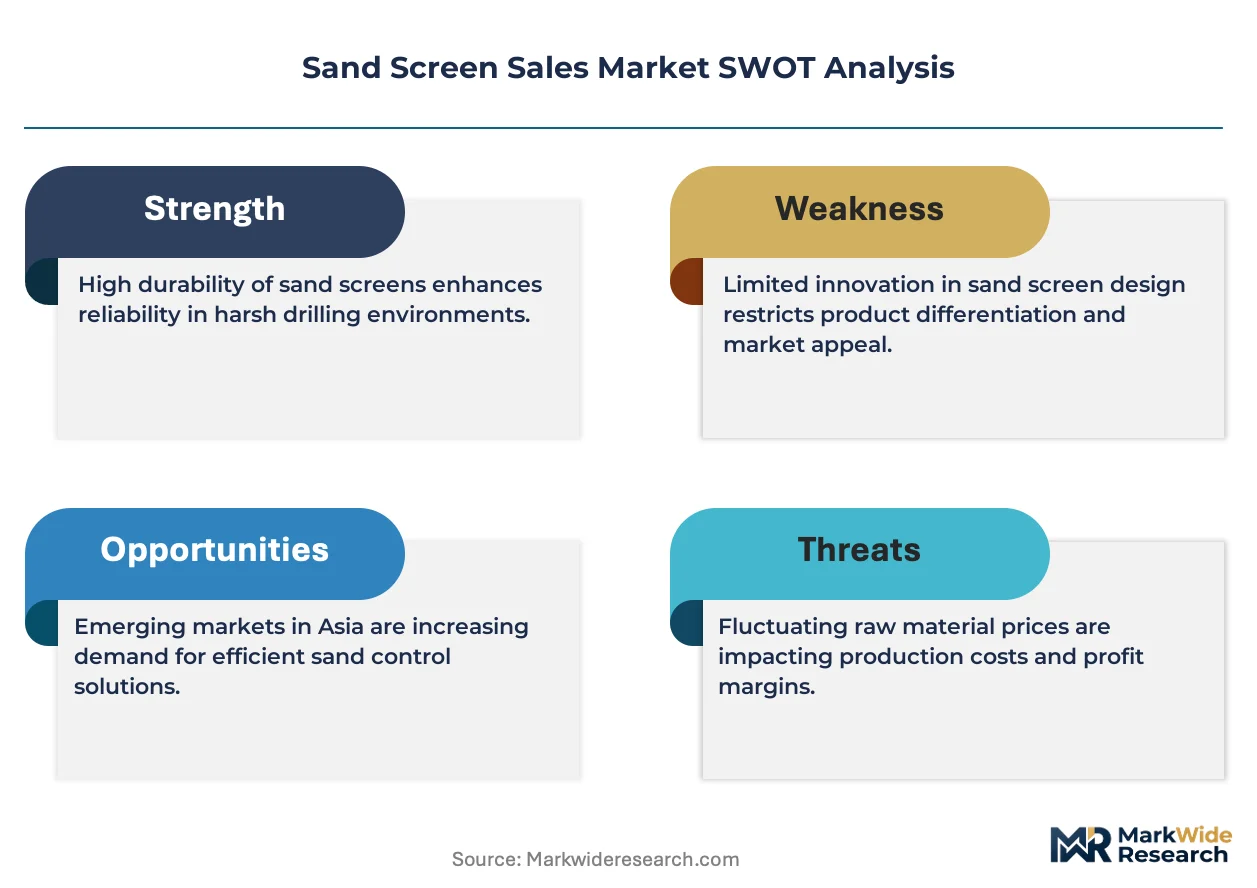
Modular screen panel configurations bundled with quick-change frame systems are realigning buyer preference away from standalone component purchases across oilfield and mining procurement channels. This structural shift toward integrated filtration solutions is compressing margins for pure-play mesh suppliers while rewarding systems integrators with captive metallurgy capabilities.
Growth Catalysts
- API 19SS compliance mandates:United States hydraulic fracturing operators now require certified sand control screen design verification, forcing equipment upgrades across Permian Basin well completions.
- Sichuan shale gas corridor expansion:China's national energy security priorities are accelerating horizontal drilling programs that consume premium mesh configurations at triple the rate of conventional vertical wells.
- Composite screen material advances:Polymer-matrix filtration media are penetrating deepwater deployments where weight reduction and corrosion resistance justify 40% unit cost premiums over wire mesh alternatives.
Market Restraints
- Nickel alloy price volatility:Austenitic stainless steel input costs fluctuate with London Metal Exchange spot pricing, squeezing margin predictability for woven wire manufacturers.
- MEE effluent standard tightening:China's Ministry of Ecology and Environment protocols are extending product redesign cycles by 8-14 months as suppliers recalibrate aperture tolerances for water treatment retrofit installations.
- Wire mesh installed base lock-in:Mature oilfield operators in Texas and Oklahoma face switching costs from standardized inventory systems that resist composite screen migration despite performance advantages.
Strategic Opportunities
- Sub-Saharan African mining greenfield projects:Copper and gold extraction ventures in Zambia and the Democratic Republic of Congo lack established screen supply relationships, creating first-mover positioning for composite technology specialists.
- Desalination membrane pre-filtration:Saudi Arabia and UAE municipal water authorities are specifying 50-micron rated screens as mandatory upstream protection for reverse osmosis trains.
- ISO 17824 certification arbitrage:Cross-border suppliers without baseline qualification face exclusion from Nigerian and Brazilian national oil company tenders, rewarding early certification investment.
Industry Challenges
- Precision welding skill scarcity:Automated seam welding of 25-micron aperture wire mesh requires technicians trained on laser micro-joining equipment that few vocational programs currently cover.
- API 19SS testing facility bottlenecks:Third-party verification laboratories in Houston and Aberdeen operate at 4-6 month backlogs, delaying product launches for modified screen geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sand Screen Sales Market |
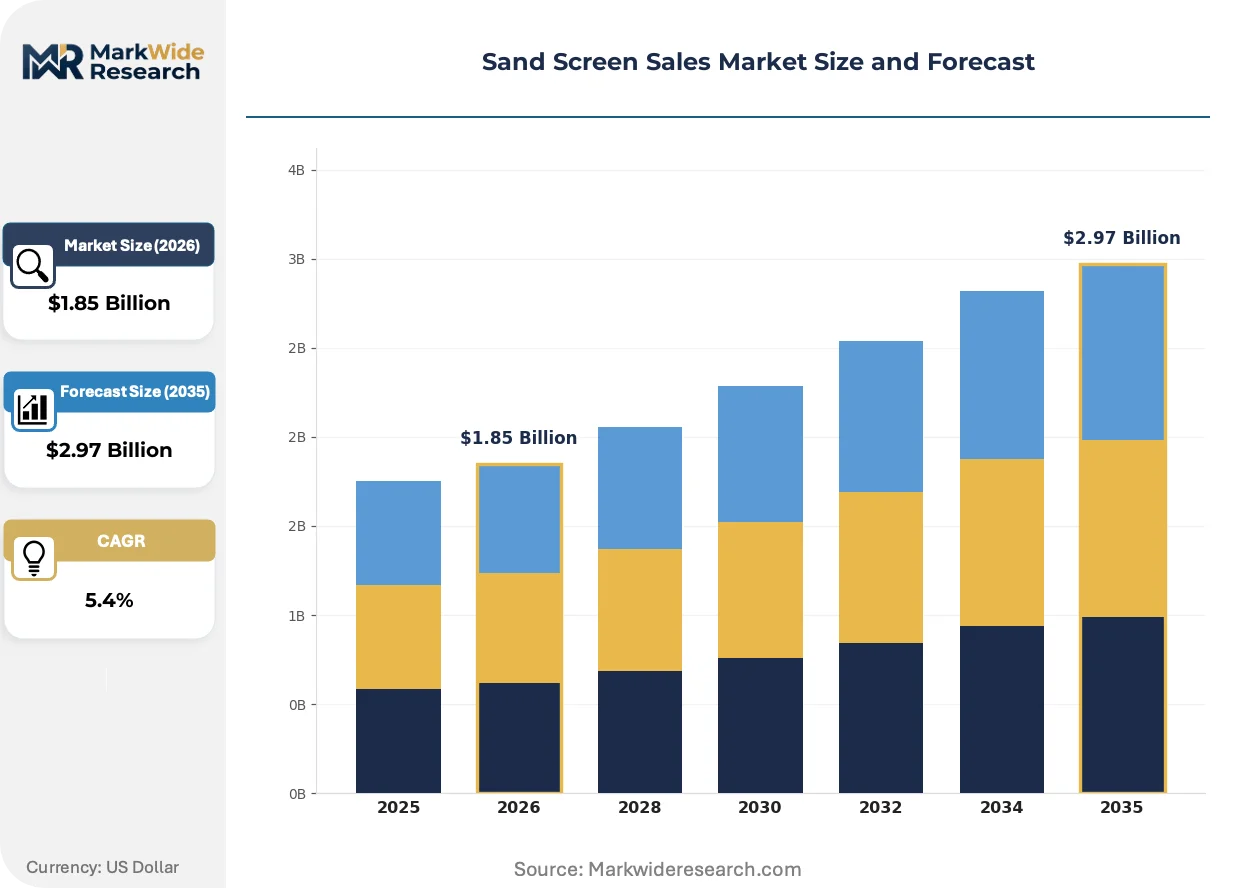
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wire Mesh Screens, Composite Screens, Metal Screens, Specialty Screens Application: Oil & Gas, Water Treatment, Mining, Geotechnical End User: Contractors, Municipalities, Oil Producers, Mining Companies Installation Type: Permanent Installation, Temporary Installation, Retrofit Installation, Modular Installation |
| Companies Covered | Sandvik AB, Komatsu Ltd., Terex Corporation, Deister Machine Company, John Deere, RHEWUM GmbH, SKF, Trelleborg, Freudenberg Sealing Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sand Screen Sales Market Trends and Innovations
Material substitution and regulatory compression are simultaneously reshaping product development roadmaps and procurement qualification protocols across sand screen manufacturing. Suppliers must now optimize for corrosion resistance, weight reduction, and rapid regulatory compliance in parallel rather than sequentially.
Sintered metal fiber filtration media are overtaking traditional woven wire mesh in high-pressure subsea completions where packer failure risks demand absolute particulate exclusion. Deepwater operators in the Gulf of Mexico and offshore Brazil specify these materials for Christmas tree protection systems despite 60% higher unit costs. The technology is overtaking conventional solutions by eliminating the structural weak points of wire weave intersections under cyclic loading.
China's MEE environmental compliance protocols are extending beyond effluent standards into manufacturing process oversight, requiring screen producers to document smelting energy intensity and wastewater treatment throughput. Facilities in Jiangsu and Shandong provinces face unannounced inspections that audit chromium electroplating bath chemistry. Water treatment end-users in the Yangtze River basin now prioritize suppliers with verified closed-loop plating systems, creating procurement preference bifurcation.
Aftermarket service unbundling is fragmenting historical bundled maintenance contracts as Permian Basin operators internalize screen changeout crews and purchase consumable panels directly. Independent rental companies in Midland and Odessa now stock quick-change frame systems that bypass original equipment manufacturer service networks. This pattern is most visible among top-20 US shale producers who have consolidated procurement functions into centralized supply chain towers with direct vendor negotiation authority.
Sand Screen Sales Market Segmentation
Sand screen procurement patterns diverge sharply between commodity-driven replacement cycles and engineered-system deployments. Understanding these splits allows suppliers to align metallurgy investments with margin profiles and regulatory qualification requirements.
Product Type:
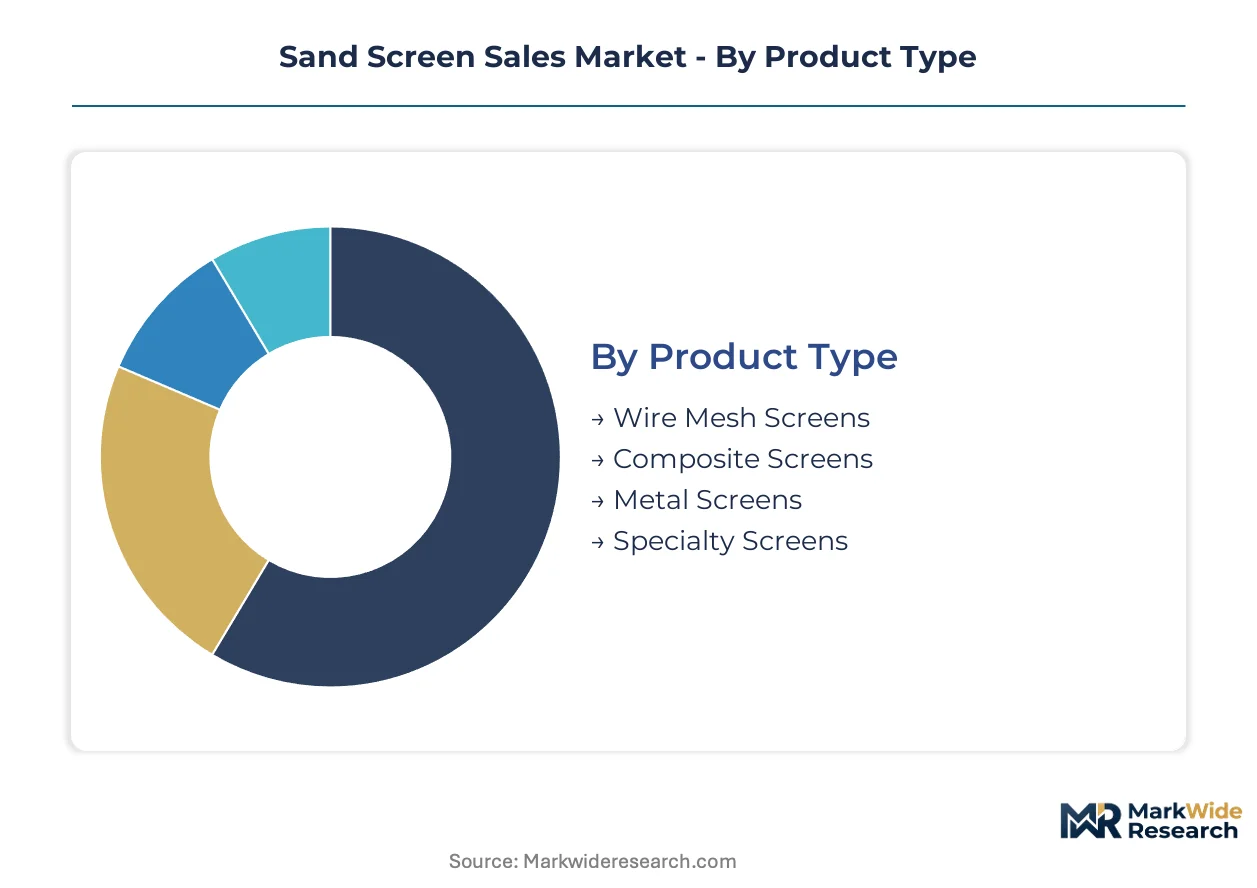
Wire mesh configurations dominate unit volumes across established oilfields, while composite formulations command premium positioning in frontier drilling environments.
- Wire Mesh Screens:Woven stainless steel or nickel-alloy constructions with aperture tolerances calibrated to API 19SS specifications. Demand concentrates in Permian Basin well completions where standardized inventory systems reduce procurement complexity for mature operators.
- Composite Screens:Polymer-matrix filtration media reinforced with carbon fiber or glass fiber substrates. Deepwater deployments in the Gulf of Mexico specify these for Christmas tree protection systems, accepting unit cost premiums in exchange for weight reduction and corrosion immunity.
- Metal Screens:Sintered metal fiber or perforated sheet constructions offering absolute particulate exclusion. Sichuan shale gas operators specify these for high-pressure horizontal completions.
- Specialty Screens:Ceramic-coated or elastomer-encapsulated variants for extreme pH or temperature regimes. Geothermal and heavy oil thermal recovery projects in California and Alberta drive niche procurement.
Today's leader: Wire Mesh Screens. Tomorrow's challenger: Composite Screens.
Application:
End-use concentration tilts toward hydrocarbon extraction, though water infrastructure retrofit cycles are accelerating screen media replacement demand.
- Oil & Gas:Sand control completions, production well maintenance, and injection well protection across conventional and unconventional reservoirs. Horizontal drilling programs in Texas and Sichuan consume mesh at triple the rate of vertical wells.
- Water Treatment:Intake screening, membrane pre-filtration, and effluent polishing for municipal and industrial facilities. MEE protocols in China's Yangtze River basin push facilities toward 50-micron rated specifications.
- Mining:Mineral processing circuits, tailings dewatering, and heap leach recovery systems. Copper and gold extraction ventures in Zambia and the Democratic Republic of Congo drive greenfield procurement.
- Geotechnical:Groundwater monitoring wells, landfill leachate collection, and soil stabilization drainage. European infrastructure projects specify these for EU Green Deal compliance in subsurface contamination control.
Oil & Gas anchors current revenue. Water Treatment shows the steepest expansion trajectory as regulatory tightening accelerates retrofit investment.
End User:
Procurement authority is migrating from decentralized field operations toward centralized supply chain towers with direct vendor negotiation capability.
- Contractors:Oilfield service companies and water infrastructure construction firms purchasing on project-specific specifications. Permian Basin completions contractors now bundle quick-change frame systems with consumable panel orders.
- Municipalities:City and regional water authorities managing intake and treatment infrastructure. Saudi Arabia and UAE municipal authorities mandate 50-micron screens as mandatory upstream protection for reverse osmosis trains.
- Oil Producers:Integrated and independent exploration and production companies with captive procurement functions. Top-20 US shale producers have internalized screen changeout crews and bypass OEM service networks.
- Mining Companies:Copper, gold, and iron ore operators with abrasive wear-driven replacement cycles. Sub-Saharan African greenfield ventures lack established supply relationships, creating first-mover positioning opportunities.
Oil Producers command the largest contract values. Contractors are gaining procurement influence through project bundling and aftermarket service unbundling.
Installation Type:
Deployment architecture determines supplier margin structure, with permanent installations favoring qualification-heavy incumbents and modular systems rewarding rapid-response fabricators.
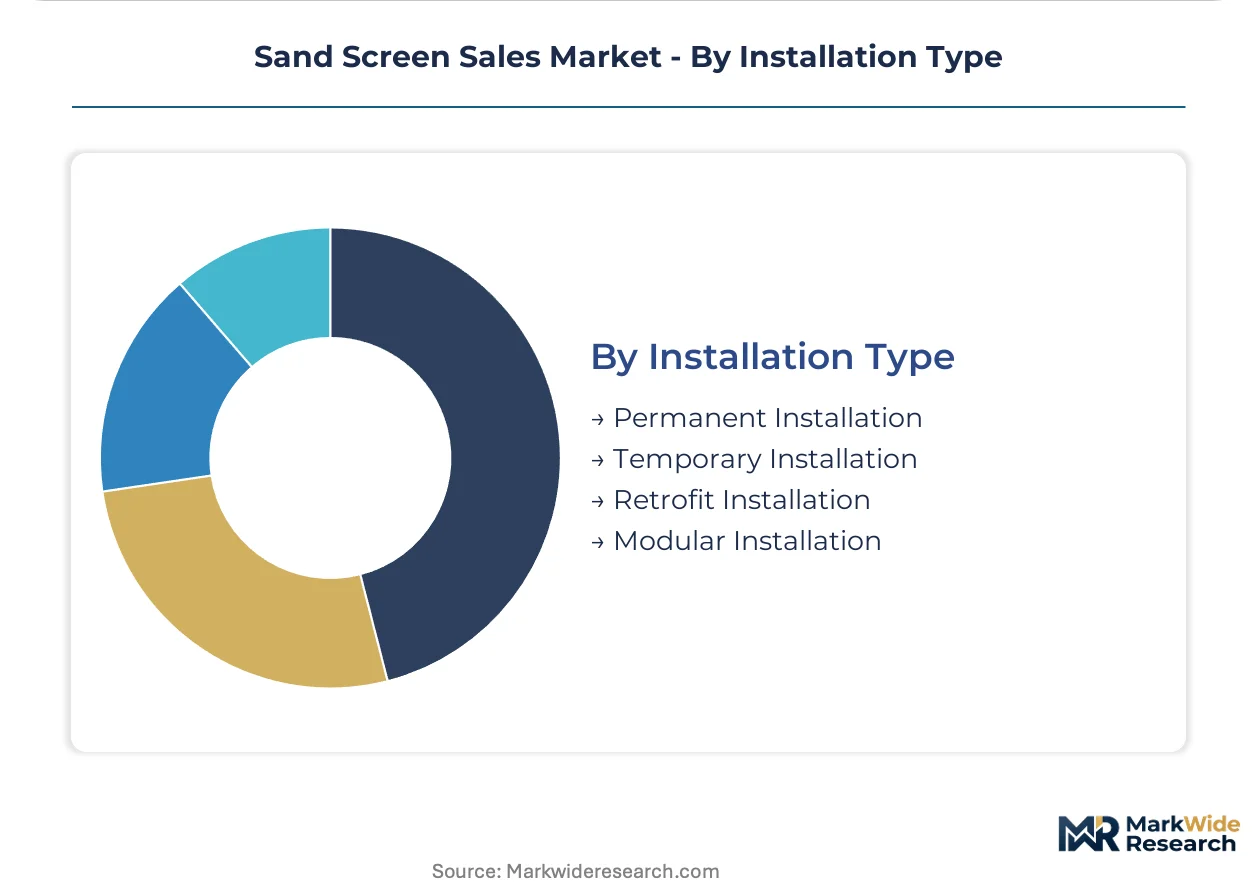
- Permanent Installation:Gravel-packed or standalone screens cemented into wellbore annuli for field life. API 19SS certification requirements extend design verification cycles for these critical-path components.
- Temporary Installation:Removable screens for workover operations, well testing, or pilot production phases. Rental companies in Midland and Odessa stock these for short-cycle shale completions.
- Retrofit Installation:Replacement screens for aging infrastructure without full system replacement. China's MEE effluent standards extend redesign cycles by 8-14 months as suppliers recalibrate aperture tolerances.
- Modular Installation:Quick-change panel systems compatible with standardized frame geometries. This configuration is realigning buyer preference away from standalone component purchases across oilfield and mining channels.
Permanent Installation retains the deepest supplier relationships. Modular Installation is displacing conventional procurement patterns fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The sand screen industry traces its commercial origins to North American oilfield service clusters established during the mid-20th century Permian Basin drilling boom. Early wire mesh fabrication techniques developed in Texas and Oklahoma subsequently diffused to European mining equipment centers and Asia-Pacific industrial corridors. Today's procurement geography reflects this lineage while responding to shale revolution dynamics and environmental regulatory tightening.
United States
Permian Basin horizontal drilling programs consume premium mesh configurations at triple the rate of conventional vertical wells. API 19SS certification mandates now govern sand control screen procurement across Texas and Oklahoma completions. Midland and Odessa rental companies stock quick-change frame systems that bypass original equipment manufacturer service networks.
China
Sichuan shale gas corridor expansion drives demand for high-pressure metal screens in horizontal completions. MEE effluent standards extend product redesign cycles by 8-14 months as suppliers recalibrate aperture tolerances. Jiangsu and Shandong province facilities face unannounced inspections auditing chromium electroplating bath chemistry.
Germany
Precision-engineered composite screen technologies serve fine-separation tasks across European mining and industrial filtration channels. REACH compliance protocols shape material substitution decisions for polymer-matrix filtration media. Industrial fabricators in North Rhine-Westphalia anchor supply relationships for sub-Saharan African greenfield mining ventures.
Saudi Arabia
Municipal water authorities mandate 50-micron rated screens as mandatory upstream protection for reverse osmosis desalination trains. SFDA-adjacent procurement standards influence material qualification protocols for oilfield service applications. Eastern Province industrial zones concentrate fabrication capacity serving both domestic energy and water infrastructure retrofit cycles.
Brazil
Deepwater pre-salt development programs specify sintered metal fiber filtration media for Christmas tree protection systems. ANVISA-aligned import regulations shape cross-border supplier eligibility for national oil company tenders. Offshore supply clusters in Rio de Janeiro state coordinate logistics for high-pressure subsea completion equipment.
Sand Screen Sales Market Competitive Landscape
Premium-margin players sit above commodity-margin players across metallurgical capability and certification depth. The vendor base stratifies into three tiers: integrated mining equipment conglomerates with captive screen divisions, specialized filtration technology houses with polymer-matrix expertise, and regional fabrication shops serving replacement cycles. Consolidation pressure concentrates among mid-scale wire mesh suppliers facing nickel alloy price volatility. Dominant competitive moves include strategic partnerships with oilfield service companies and backward integration into precision welding equipment.
Within the metallurgical-specialist tier, Sandvik AB and RHEWUM GmbH exemplify divergent capability anchors. Sandvik AB represents integrated materials science positioning spanning mining and oilfield channels. RHEWUM GmbH occupies a position among precision-engineered composite technology specialists. Trelleborg sits within the advanced polymer formulation segment serving corrosive environment applications. These three entities collectively illustrate how competitive positioning fragments across material science vectors rather than consolidating around unified technology platforms.
| Leading Market Players |
|---|
| Sandvik AB |
| Komatsu Ltd. |
| Terex Corporation |
| Deister Machine Company |
| John Deere |
| RHEWUM GmbH |
| SKF |
| Trelleborg |
| Freudenberg Sealing Technologies |
| Others |
Pricing and Supply Chain Analysis
Sintered metal fiber filtration media adoption in Gulf of Mexico deepwater completions simultaneously compresses wire mesh margins and concentrates supply relationships among metallurgical specialists with precision welding capabilities. This technology transition rewards suppliers with captive laser micro-joining equipment while penalizing commodity mesh fabricators facing nickel alloy price volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates API 19SS-certified sintered metal screens from commodity wire mesh and unbranded regional alternatives. Price differentiation hinges on certification depth and after-sales service bundling, with OEM-integrated maintenance contracts commanding 25-40% premiums over panel-only transactions. Cost compression in standard wire mesh intensifies because Permian Basin operators have internalized changeout crews and bypass service networks. Municipal water authorities in the Middle East show least price sensitivity due to membrane protection requirements, while mining contractors in Sub-Saharan Africa negotiate hardest on unit economics.
Supply Chain Analysis
China's MEE manufacturing process oversight and unannounced facility inspections are reshaping sourcing patterns for chromium electroplating and polymer-matrix filtration media. Supply concentrates in Germany for precision-engineered composite technologies, China for wire mesh fabrication serving Sichuan shale gas demand, and the United States for API-certified subsea completion screens. Raw material flows draw from nickel alloy smelters in Jiangsu province, carbon fiber substrate producers in North Rhine-Westphalia, and austenitic stainless steel mills in Texas. Single-source vulnerability runs through laser micro-joining equipment suppliers, with automated seam welding systems anchored in Japanese and German industrial centers. Distribution runs through oilfield service company procurement towers, independent rental networks in Midland-Odessa, and direct municipal tender processes in Saudi Arabia and UAE.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sand screen market has entered a late-cycle quality phase where API 19SS certification and composite material expertise separate viable suppliers from margin-compressed commodity players. Demand is concentrating in premium mesh configurations for horizontal drilling programs and deepwater Christmas tree protection systems.
For Market Incumbents: Lock in API 19SS certification depth through third-party verification laboratory relationships in Houston and Aberdeen, where 4-6 month testing backlogs create defensive moats against unqualified entrants. Backward integration into precision welding equipment and laser micro-joining technician training programs protects against skill scarcity threatening production scalability. Composite technology specialists from polymer-matrix backgrounds represent the most credible substitution threat to wire mesh incumbents in deepwater deployments. For New Entrants and Emerging Players: Sintered metal fiber filtration media for subsea high-pressure completions offers the most penetrable white-space target, as incumbent wire mesh suppliers lack metallurgical expertise for absolute particulate exclusion applications. Sub-Saharan African copper and gold extraction ventures in Zambia and the Democratic Republic of Congo lack established supply relationships and procurement standardization, creating first-mover positioning opportunities. A technology-first go-to-market angle through ISO 17824 certification arbitrage unlocks Nigerian and Brazilian national oil company tenders that exclude uncertified cross-border suppliers. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale wire mesh suppliers facing nickel alloy price volatility and Permian Basin procurement consolidation, while composite technology specialists with polymer-matrix expertise command scarcity premiums. The long-term viability window favors suppliers with dual capability across wire mesh replacement cycles and composite frontier deployments. Watch API 19SS testing facility capacity expansion in Houston as the inflection signal—backlog reduction would erode certification moats and accelerate commodity competition.| Strategic Initiative | Industry Significance |
|---|---|
| API 19SS Certification Investment | Third-party verification in Houston and Aberdeen unlocks Permian Basin and Gulf of Mexico procurement mandates. |
| Backward Integration into Precision Welding | In-house laser micro-joining equipment mitigates technician scarcity threatening 25-micron aperture production. |
| Composite Technology Partnership | Polymer-matrix filtration media alliances penetrate deepwater weight-sensitive deployments accepting 40% cost premiums. |
| Sub-Saharan African Market Entry | Greenfield copper and gold ventures in Zambia and DRC lack established supplier relationships and procurement standardization. |
| ISO 17824 Pre-Certification | Early qualification investment excludes competitors from Nigerian and Brazilian national oil company tender processes. |
Research Methodology
Coverage spans North America, China, Germany, Saudi Arabia, and Brazil, with primary inputs from each region's dominant procurement clusters. The research combines structured interviews with oilfield service procurement directors, sand screen manufacturing plant managers, municipal water authority engineering leads, mining operations maintenance heads, and third-party testing laboratory technical directors. Secondary validation draws from API 19SS standard documentation, MEE environmental compliance filings, ISO 17824 certification registries, SEC 10-K filings from listed mining equipment conglomerates, and customs trade data for nickel alloy wire mesh imports. Bottom-up demand modeling across well completion counts and top-down supply capacity verification triangulate market sizing.
Granularity-level modeling extends to product type (wire mesh, composite, metal, specialty), application (oil and gas, water treatment, mining, geotechnical), end user (contractors, municipalities, oil producers, mining companies), and installation architecture (permanent, temporary, retrofit, modular). CAGRs derive from segmented volume and value projections across the analysis window, with cross-segment reconciliation ensuring internal consistency. Industry-specific forecast inputs include Permian Basin horizontal drilling intensity, Sichuan shale gas corridor well completion schedules, and Saudi Arabia desalination membrane pre-filtration procurement cycles.
The model holds under stable API 19SS certification requirements and MEE environmental enforcement continuity; deviation in nickel alloy price volatility or unannounced Chinese manufacturing facility closure triggers would shift supplier margin distributions and procurement timelines. Forecasts reflect documented assumptions regarding technology substitution rates and regulatory implementation schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Exploration and Drilling Security Market
Oil & Gas
Australia LNG Bunkering Market
Oil & Gas
United States Liner Hanger System Market
Oil & Gas
United States Onshore Drilling Fluid Market
Oil & Gas
Malaysia Oilfield Services Market
Oil & Gas
Russian Federation Oil and Gas Market
Oil & Gas
North America Proppants Market
Oil & Gas
Oil and Gas Refinery Maintenance Services Market
Oil & Gas
North America Directional Drilling Services Market
Oil & Gas
Leak Detection for Oil & Gas Market
Oil & Gas
Oil Tank Rotating Stacker Market
Oil & Gas
Chemical Enhanced Oil Recovery (EOR) Market
Oil & Gas
Well Casing Market
Oil & Gas
Oil and Gas Automation and Instrumentation Market
Oil & Gas
Canada Oil and Gas Market
Oil & Gas
North America Seismic Services Market