
 Middle-East and Africa Frac Stack Market | 2026-2036
Middle-East and Africa Frac Stack Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Frac Stack Market Insights
Buyer concentration among Middle-Eastern national oil companies is decoupling from traditional service-provider relationships as ADNOC and Saudi Aramco diversify vendor pools. Halliburton Company leverages integrated project management capabilities to anchor long-term contracts in Saudi Arabia's unconventional gas fields. Schlumberger Limited differentiates through real-time frac stack monitoring systems that sustain premium positioning with independent producers in Oman. NOV Inc. competes on modular equipment architectures that reduce rig-up time for tight-oil campaigns in the UAE.
A frac stack is a pressure-control assembly installed atop a wellhead during hydraulic fracturing operations, typically rated to 15,000 psi and comprising isolation valves, frac heads, and flow-crosses engineered from alloy steel forgings. Its primary purpose is to direct high-pressure fracturing fluid into the wellbore while enabling rapid intervention and zone isolation across multi-stage completions. Hydraulic fracturing equipment dominates product-type revenue given the scale of Saudi Arabia's Jafurah development, though coiled tubing equipment represents the fastest-growing category as operators adopt continuous-mix techniques for tight-gas reservoirs. Onshore applications absorb the majority of installation demand, while modular configurations gain share by cutting mobilization costs for independent producers operating marginal fields.
API 6A standards govern pressure-boundary design and material traceability for frac stacks deployed across Middle-Eastern fields, with Saudi Aramco's in-kingdom total value add program and ADNOC's local manufacturing requirements shaping procurement compliance. The UAE's regulatory framework for well integrity and Egypt's petroleum ministry oversight of unconventional testing protocols add compliance layers that favor vendors with regional certification depth. Stakeholders must monitor how Saudi Arabia's gas expansion targets and Egypt's Western Desert tight-oil pilots alter equipment specification priorities across the supplier base.
Market Dynamics
ADNOC and Saudi Aramco are decoupling vendor relationships from traditional service providers, forcing frac stack suppliers to rebuild procurement credentials around local content mandates and modular deployment capabilities.
Growth Catalysts
- Jafurah Gas Development:Saudi Arabia's unconventional gas expansion is pulling high-pressure frac stack assemblies into multi-well pad configurations designed for tight-gas reservoirs.
- API 6A Certification Alignment:Material traceability and pressure-boundary design standards are compressing supplier qualification timelines for national oil company procurement cycles.
- Coiled Tubing Integration:Continuous-mix fracturing techniques are absorbing specialized frac head configurations that enable rapid zone isolation across extended-reach laterals.
Market Restraints
- Alloy Steel Forging Concentration:Supply of high-pressure valve forgings concentrates among a limited set of European and Asian metallurgical suppliers, creating input bottlenecks.
- In-Kingdom Value-Add Mandates:Saudi Aramco's local manufacturing requirements impose capital intensity on foreign vendors without established Saudi fabrication partnerships.
- Technical Specification Divergence:ADNOC's well integrity protocols differ materially from Egyptian petroleum ministry testing standards, fragmenting certification compliance costs.
Strategic Opportunities
- Egypt Western Desert Tight-Oil:Pilot programs in unconventional testing zones are opening demand for mobile frac stack skids suited to marginal field economics.
- Modular Equipment Architectures:Rig-up time compression through standardized flow-cross configurations is enabling independent producers to access previously uneconomic tight-gas targets.
- Oman Independent Producer Segment:Real-time monitoring system integration is creating service differentiation opportunities outside national oil company procurement channels.
Industry Challenges
- API 6A Certification Timeline Compression:Material qualification and pressure-testing protocols for 15,000 psi assemblies are extending vendor onboarding cycles beyond operator drilling schedules.
- Multi-Stage Completion Integration:Frac stack compatibility with intelligent wellhead systems requires firmware coordination that legacy equipment suppliers struggle to execute.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Frac Stack Market |
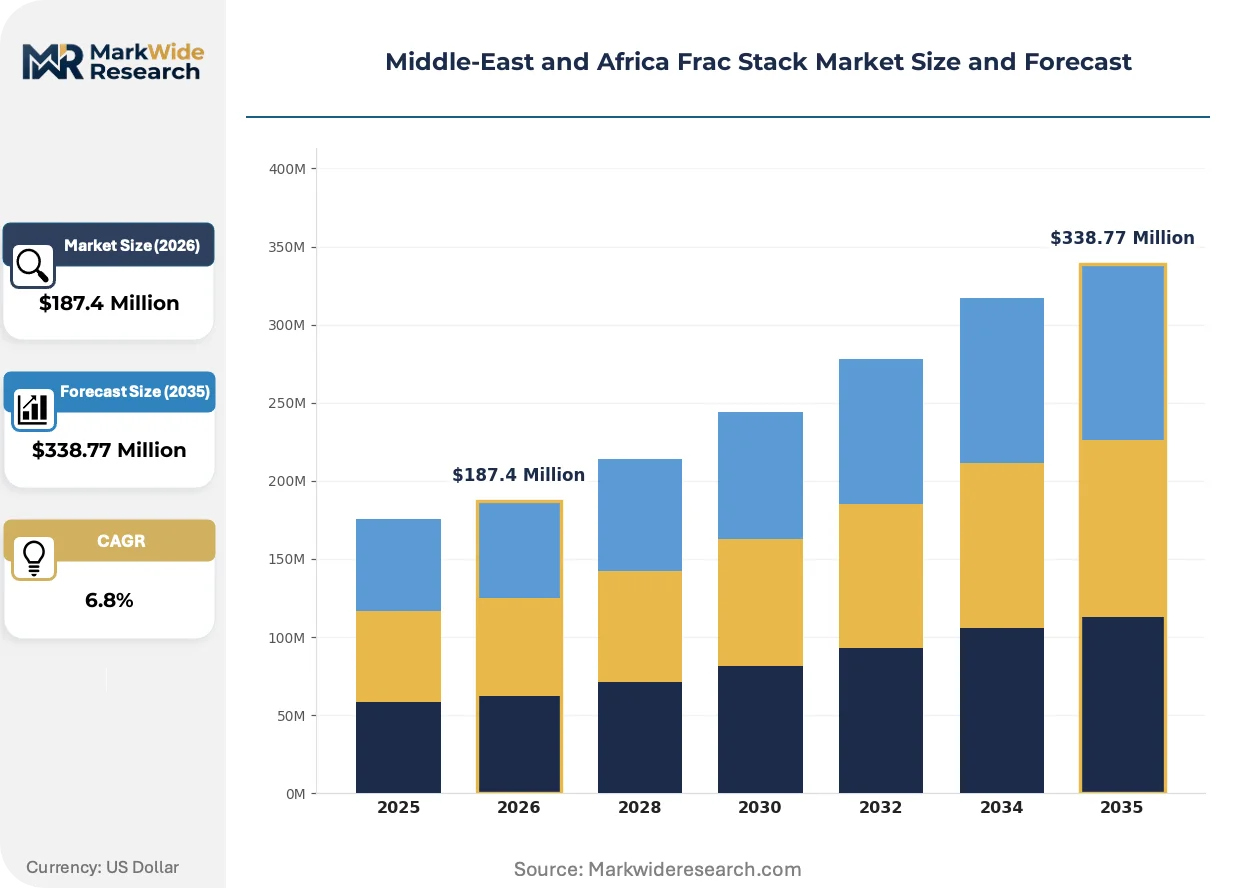
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Fracturing Equipment, Cementing Equipment, Coiled Tubing Equipment, Other Equipment Application: Onshore, Offshore, Shale Gas, Tight Oil End User: Oil Companies, Gas Companies, Service Providers, Independent Producers Installation: Temporary, Permanent, Modular, Reconcilable |
| Companies Covered | Halliburton Company, Schlumberger Limited, NOV Inc., Baker Hughes Company, Cactus Inc., National Energy Services Reunited Corp., Oil States International Inc., The Weir Group PLC, SPM Oil & Gas Inc., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Frac Stack Market Trends and Innovations
Equipment architecture and procurement protocols are converging around speed-to-deploy metrics, with operators prioritizing configurations that compress mobilization timelines and reduce surface footprint.
Modular frac stack assemblies with standardized isolation valve manifolds are absorbing capital allocation from conventional built-up configurations. Independent producers in the UAE's Al Dhafra basin are specifying these systems for tight-oil campaigns requiring rapid rig-up between stages. The technology is absorbing market share by cutting mobilization costs and enabling batch completions that align with tight-gas development economics.
Saudi Aramco's in-kingdom total value add program is reshaping supplier qualification requirements for pressure-control equipment. Vendors must now demonstrate local fabrication capacity and material traceability through Saudi-based entities to maintain procurement eligibility. Frac stack providers with established regional certification depth are consolidating preferred supplier status while competitors face exclusion from unconventional gas tenders.
Service unbundling is fragmenting traditional integrated provider relationships in Oman. Independent producers are separating frac stack procurement from pumping services, creating direct equipment purchase channels that bypass bundled contracting models. This pattern is most visible among tight-gas operators seeking equipment ownership to control maintenance cycles and reduce standby charges during completion delays.
Middle-East and Africa Frac Stack Market Segmentation
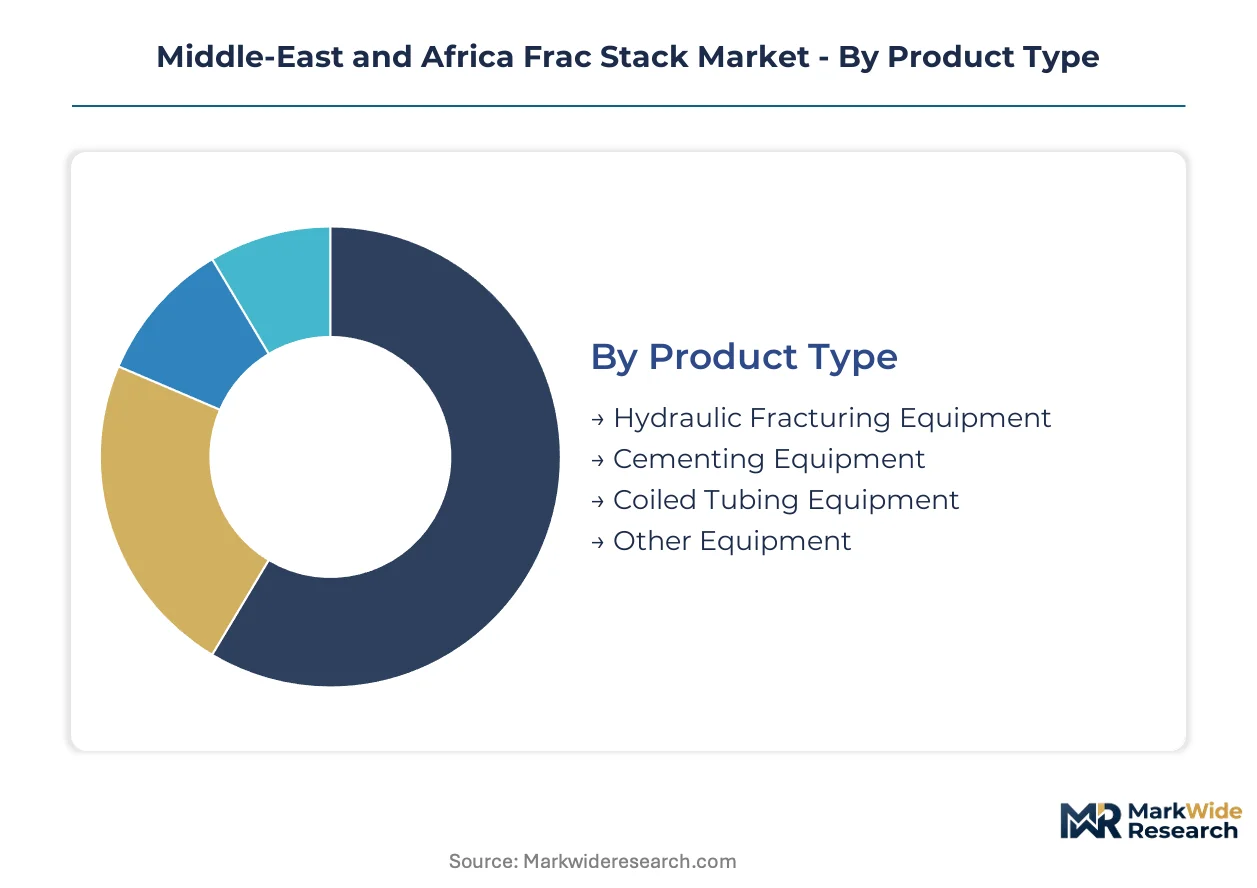
Frac stack specification diverges sharply across Middle-Eastern and African basins, with Saudi Aramco and ADNOC procurement mandates forcing vendors to align product architectures with local content rules and pressure-rating requirements. Equipment customization versus standardization trade-offs determine vendor qualification success across unconventional gas and tight-oil development programs.
Product Type:
Standardization pressure from national oil company procurement compresses design variation, yet reservoir-specific pressure ratings and flow-cross configurations sustain customization premiums for high-specification deployments.
- Hydraulic Fracturing Equipment:High-pressure assemblies rated to 15,000 psi dominate Saudi Arabia's Jafurah gas field installations, with alloy steel forgings and API 6A certification forming baseline procurement requirements. Demand concentrates in multi-well pad configurations where isolation valve manifolds enable rapid stage transitions across extended-reach laterals.
- Coiled Tubing Equipment:Continuous-mix frac head configurations absorb the steepest demand growth as UAE and Oman operators adopt live-well intervention techniques for tight-gas reservoirs. Specialized flow-cross designs integrate with real-time monitoring systems that independent producers in Oman's interior basins specify for batch completion economics.
- Cementing Equipment:Pressure-control heads engineered for zonal isolation during plug-and-perf operations serve secondary cementing applications in Egypt's Western Desert pilots.
- Other Equipment:Auxiliary flow-control components including crossovers and adapters round out procurement packages for marginal field operators seeking modular compatibility.
Most installed capacity flows through hydraulic fracturing equipment. Expansion is steepest in coiled tubing equipment.
Application:
Surface constraints and reservoir depth dictate equipment mobility requirements, with desert terrain accessibility and offshore platform load limits fragmenting specification standards.
- Onshore:Mobile skid-mounted frac stacks with rapid rig-up capabilities anchor Saudi Arabia's unconventional gas expansion, where Jafurah basin contractors specify 72-hour mobilization timelines between multi-well pads. ADNOC's Al Dhafra tight-oil campaigns absorb modular configurations that independent producers deploy without integrated service bundling.
- Tight Oil:High-pressure frac heads with intelligent wellhead compatibility gain share in UAE marginal fields where batch completion economics require stage isolation precision. Egyptian Western Desert pilot programs specify mobile units for testing protocols under petroleum ministry oversight.
- Shale Gas:Multi-stage isolation systems align with Saudi Aramco's gas production targets, though Jafurah field procurement channels favor integrated project management over direct equipment purchase.
- Offshore:Compact footprint frac stacks with crane-lift modularization serve limited Arabian Gulf platform workovers where deck space constraints override land-based mobility priorities.
Onshore deployments absorb the majority of capital allocation. Tight oil applications are gaining share fastest among independent producer segments.
End User:
Procurement authority concentration among national oil companies decouples equipment specification from service provider recommendations, creating direct vendor relationships previously mediated by integrated contractors.
- Oil Companies:Saudi Aramco and ADNOC direct purchasing programs for Jafurah and Al Dhafra developments specify API 6A traceability and in-kingdom fabrication partnerships as non-negotiable qualification criteria.
- Gas Companies:Unconventional gas specialists in Qatar and Oman prioritize real-time monitoring integration for reservoir characterization during extended-reach completions.
- Independent Producers:Omani tight-gas operators and UAE marginal field developers are unbundling frac stack procurement from pumping services to control maintenance cycles and eliminate standby charges.
- Service Providers:Halliburton and Schlumberger equipment leasing programs retain relevance where operators prefer operational outsourcing over capital deployment.
Oil companies command the largest equipment procurement volumes. Independent producers are expanding their share of direct equipment purchases most aggressively.
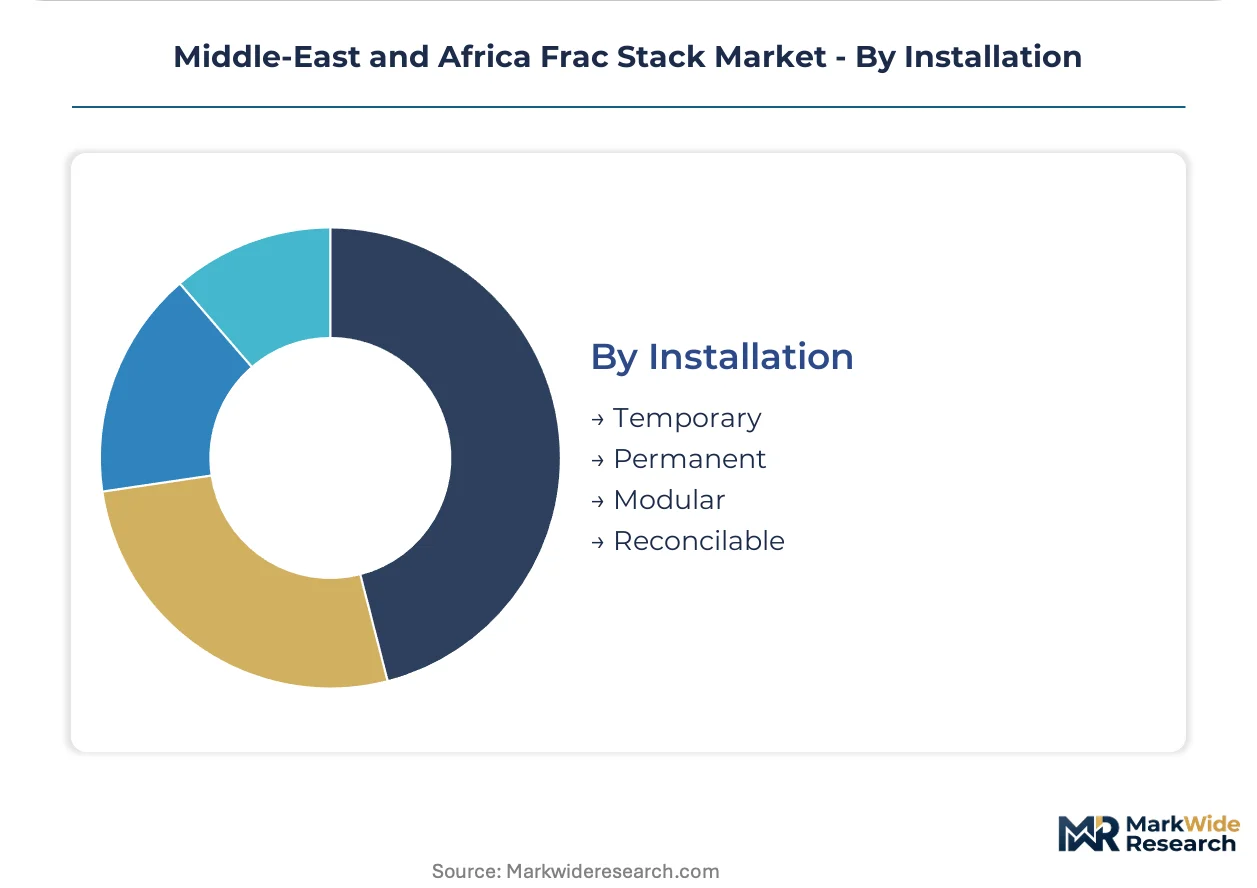
Installation:
Capital intensity versus operational flexibility trade-offs determine whether operators purchase, lease, or specify reusable configurations across drilling campaign timelines.
- Modular:Standardized isolation valve manifolds and flow-cross configurations enable independent producers in UAE's Al Dhafra basin to compress rig-up time and batch-complete tight-oil stages without integrated service dependencies.
- Temporary:Short-duration rentals for Egyptian Western Desert testing programs and Oman exploration wells minimize capital commitment where reservoir economics remain unproven.
- Permanent:Fixed installations anchor Saudi Aramco's long-duration Jafurah gas production pads where wellhead integration with intelligent completion systems justifies sunk equipment costs.
- Reconcilable:Hybrid purchase-lease structures emerging among mid-size UAE operators balance balance-sheet treatment with operational flexibility for multi-campaign deployment.
Modular installations are capturing share fastest from conventional temporary configurations. Permanent installations retain dominance in Saudi Arabia's large-scale gas developments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's unconventional gas expansion dwarfs Egyptian pilot programs in scale, yet both markets impose distinct certification burdens that fragment supplier qualification timelines across the Middle-East and Africa region.
Saudi Arabia
Jafurah basin tight-gas development absorbs the majority of high-pressure frac stack assemblies rated to 15,000 psi. Saudi Aramco's in-kingdom total value add program mandates local fabrication partnerships and material traceability through Saudi-based entities. Eastern Province clusters anchor multi-well pad configurations where 72-hour mobilization timelines compress equipment deployment cycles.
United Arab Emirates
ADNOC's Al Dhafra tight-oil campaigns drive demand for modular skid-mounted configurations that independent producers deploy without integrated service bundling. The UAE's regulatory framework for well integrity adds compliance layers favoring vendors with regional certification depth. Abu Dhabi industrial zones concentrate procurement channels where batch completion economics require stage isolation precision.
Oman
Interior basin tight-gas operators are unbundling frac stack procurement from pumping services to control maintenance cycles and eliminate standby charges. Petroleum Development Oman oversees exploration protocols that specify real-time monitoring integration for reservoir characterization. Muscat-based service corridors channel equipment to extended-reach laterals where continuous-mix techniques gain share.
Egypt
Western Desert unconventional testing programs specify mobile frac stack units suited to marginal field economics where reservoir economics remain unproven. The petroleum ministry's oversight of tight-oil pilots imposes technical specification divergence from Gulf standards. Cairo-Alexandria logistics corridors handle procurement for desert terrain installations requiring rapid rig-up capabilities.
South Africa
Karoo basin shale gas exploration licenses remain stalled, constraining equipment demand to conventional workover applications. The country's petroleum regulator oversees well integrity standards that reference API 6A protocols without local content mandates. Johannesburg-based distributors maintain standby inventory for marginal onshore campaigns awaiting upstream investment revival.
Middle-East and Africa Frac Stack Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement channels reshaped by national oil company vendor diversification. Market structure tilts toward consolidated tiering where integrated service providers anchor long-term contracts while independent equipment fabricators capture modular deployment opportunities. Three archetypes dominate: full-service project managers, real-time monitoring integrators, and modular architecture specialists. Capacity expansion through regional fabrication partnerships and technology licensing for intelligent wellhead compatibility represent the dominant competitive moves.
Among Houston-based integrated service providers, Halliburton Company and Schlumberger Limited exemplify the project management archetype that anchors unconventional gas tenders. NOV Inc. occupies a position within the modular equipment tier where standardized flow-cross configurations reduce rig-up time. These three entities represent distinct strategic postures: bundled operational outsourcing, premium monitoring system integration, and capital-light equipment architecture.
| Leading Market Players |
|---|
| Halliburton Company |
| Schlumberger Limited |
| NOV Inc. |
| Baker Hughes Company |
| Cactus Inc. |
| National Energy Services Reunited Corp. |
| Oil States International Inc. |
| The Weir Group PLC |
| SPM Oil & Gas Inc. |
| Others |
Pricing and Supply Chain Analysis
Backward integration into alloy steel forging capacity anchors supply security for frac stack manufacturers serving Saudi Aramco and ADNOC procurement channels. This upstream control over high-pressure valve forgings simultaneously insulates margin structures from European and Asian metallurgical supplier bottlenecks while supporting premium positioning against vendors dependent on spot-market sourcing.
Pricing Analysis
Capacity additions in Saudi Arabia's Eastern Province industrial zones are reshaping price floors for API 6A-certified frac stack assemblies. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth and local content compliance, with Saudi Aramco's in-kingdom total value add mandates compressing margins for foreign fabricators lacking domestic partnerships. Price erosion runs through the standard tier as modular equipment architectures proliferate. Independent producers in Oman's interior basins exhibit highest price sensitivity, while national oil companies prioritize qualification depth over unit cost.
Supply Chain Analysis
Saudi Aramco's in-kingdom total value add program and ADNOC's local manufacturing requirements are fragmenting sourcing geography across the Middle-East frac stack supply base. High-pressure alloy steel forgings draw from specialized European and Asian metallurgical suppliers, while final assembly concentrates in Saudi Arabia's Eastern Province and Abu Dhabi's industrial zones. Single-source vulnerability concentrates in 15,000 psi valve forging capacity. Distribution runs through national oil company procurement channels and independent producer direct purchase programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through regulatory layering, with API 6A certification timelines and local content mandates from Saudi Aramco and ADNOC creating qualification barriers that sustain incumbent advantage.
For Market Incumbents: Anchor preferred supplier status by deepening regional fabrication partnerships in Saudi Arabia's Eastern Province and securing intelligent wellhead firmware compatibility ahead of multi-stage completion integration requirements. Certification investment represents the critical defensive lever against modular equipment specialists unbundling procurement from integrated service contracts. For New Entrants and Emerging Players: Begin with Egypt's Western Desert tight-oil pilots and UAE marginal field operators seeking mobile frac stack skids outside national oil company procurement channels. These testing programs offer the most penetrable entry points. Direct equipment purchase channels bypassing bundled contracting models provide the optimal go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where API 6A certification depth and regional fabrication capacity concentrate among a limited vendor set serving Saudi Arabia's Jafurah expansion. Long-term viability favors equipment fabricators with demonstrated local content compliance. The signal to watch is ADNOC and Saudi Aramco vendor diversification pace accelerating beyond current procurement channel fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Fabrication Partnership | Establishes procurement eligibility under Saudi Aramco in-kingdom total value add mandates. |
| API 6A Certification Investment | Compresses vendor onboarding timelines to match national oil company drilling schedules. |
| Modular Equipment Architecture Development | Enables independent producer segment capture through rig-up time reduction. |
| Intelligent Wellhead Integration | Aligns frac stack compatibility with multi-stage completion firmware requirements. |
| Real-Time Monitoring System Licensing | Differentiates positioning in Oman's unbundled procurement channels. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with equipment procurement managers at national oil companies, frac stack engineering directors, aftermarket service heads, and regulatory compliance officers with secondary validation through API certification databases, Saudi Aramco supplier qualification records, ADNOC procurement disclosures, and petroleum ministry filings from Egypt and Oman. Bottom-up equipment deployment estimates and top-down market sizing triangulated across data streams.
Segment-weighted modeling distributed value across hydraulic fracturing equipment, coiled tubing equipment, cementing equipment, and auxiliary flow-control components, with further disaggregation by onshore versus offshore application, tight oil versus shale gas reservoir type, and modular versus temporary versus permanent installation configuration. CAGRs derived from regression analysis against drilling campaign timelines and unconventional development acceleration curves, with pressure-rating specification shifts and local content mandate compliance timelines serving as industry-specific forecast inputs across the projection horizon.
Several conditions sit outside the modeled scope, including potential regulatory divergence in Egyptian petroleum ministry testing protocols, alloy steel forging supply disruptions from European or Asian metallurgical suppliers, and Karoo basin shale gas license revival in South Africa. Forecasts reflect documented assumptions around national oil company procurement pace and vendor diversification thresholds. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Integrated Gas System Market
Oil & Gas
HPHT Cubic Press Market
Oil & Gas
Downhole Drilling Tools Market
Oil & Gas
Southeast Asia Oil and Gas Market
Oil & Gas
Oilfield Casing Spools Market
Oil & Gas
Oil and Gas Digital Rock Analysis Market
Oil & Gas
Asphaltene Inhibitors Market
Oil & Gas
Digital Twin in Oil and Gas Market
Oil & Gas
Cuttings Re-Injection Services Market
Oil & Gas
LAMEA Oilfield Auxiliary Rental Equipment Market
Oil & Gas
Kuwait Oil and Gas Market
Oil & Gas
Leak Detection for Oil & Gas Market
Oil & Gas
Containment and Handling Drilling Waste Management Market
Oil & Gas
Smart Oilfield Market
Oil & Gas
Oil and Gas Seals Market
Oil & Gas
North America Perforating Gun Market