
 Downhole Tools Market | 2026-2036
Downhole Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Downhole Tools Market Intelligence
Offshore drilling expansion in Guyana and Brazil is narrowing the technology gap between major service providers and specialized tool manufacturers. This trend creates opportunities for focused vendors to challenge incumbents in niche applications. SLB leverages its extensive R&D in digital and measurement-while-drilling technologies. Baker Hughes Company differentiates with its portfolio of advanced drilling and completion tools, while Halliburton competes on integrated service delivery.
Downhole tools are specialized mechanical and electronic devices deployed inside a wellbore during oil and gas operations. These instruments are engineered to function reliably under extreme high-pressure, high-temperature (HPHT) conditions, often exceeding 15,000 psi and 350°F. Measurement While Drilling (MWD) and Logging While Drilling (LWD) technologies command significant investment for real-time reservoir evaluation. In application segments, well completion and intervention tools represent a consistent source of recurring revenue for service companies.
Well integrity rules from the U.S. EPA and offshore safety directives in Europe mandate the use of certified, high-performance equipment to prevent blowouts and leaks. International Organization for Standardization (ISO) standards for packers and completion tools govern product design and material traceability. These regulatory frameworks increase the cost of compliance but also create barriers to entry. Operators must decide whether to invest in proprietary intelligent completion systems or rely on standardized tools from major service providers.
Market Dynamics
The push into ultra-deepwater and complex high-pressure, high-temperature geologies defines the market's trajectory. This relentless search for new reserves, particularly in offshore basins like Brazil's pre-salt, demands continuous innovation in tool reliability and performance under extreme conditions.
Growth Catalysts
- Intelligent Completions:The integration of downhole sensors with real-time data analytics enables operators to perform precise reservoir management, maximizing hydrocarbon recovery from complex wellbores.
- Offshore Expansion:Exploration and production activities in new deepwater frontiers, including the prolific basins offshore Guyana and Suriname, create sustained demand for advanced drilling and completion toolsets.
- Well Integrity Mandates:Strict regulations from the U.S. EPA and offshore safety directives in Europe require certified, high-performance equipment to prevent environmental releases and ensure operational safety.
Market Restraints
- Compliance Costs:Adherence to International Organization for Standardization (ISO) standards for packers and completion tools imposes significant design, testing, and material traceability costs on manufacturers.
- Material Limitations:The extreme HPHT conditions found in deep gas wells and geothermal projects test the physical limits of current elastomers and metal alloys used in tool construction.
- Technology Concentration:Advanced Measurement While Drilling (MWD) and Logging While Drilling (LWD) technologies remain concentrated among a few large service companies, limiting access for smaller operators.
Strategic Opportunities
- Geothermal Energy:Adapting downhole tools originally designed for oil and gas for use in high-temperature geothermal well construction and monitoring opens a new adjacent market.
- Digital Twin Integration:The convergence of downhole sensor data with surface-level digital twin models presents an opportunity for predictive maintenance and fully autonomous well optimization.
- Mature Field Rejuvenation:Deploying modern intervention and stimulation tools in aging oilfields offers a significant opportunity to enhance production and extend the economic life of existing assets.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of field engineers and data scientists capable of deploying and interpreting data from sophisticated intelligent completion systems hinders adoption.
- Legacy System Integration:Integrating modern digital downhole tools with older, proprietary surface control systems presents significant technical and software compatibility challenges for operators.
- HPHT Qualification Delays:The lengthy and expensive process to qualify new tool designs for extreme high-pressure, high-temperature service can significantly delay the introduction of new technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Downhole Tools Market |
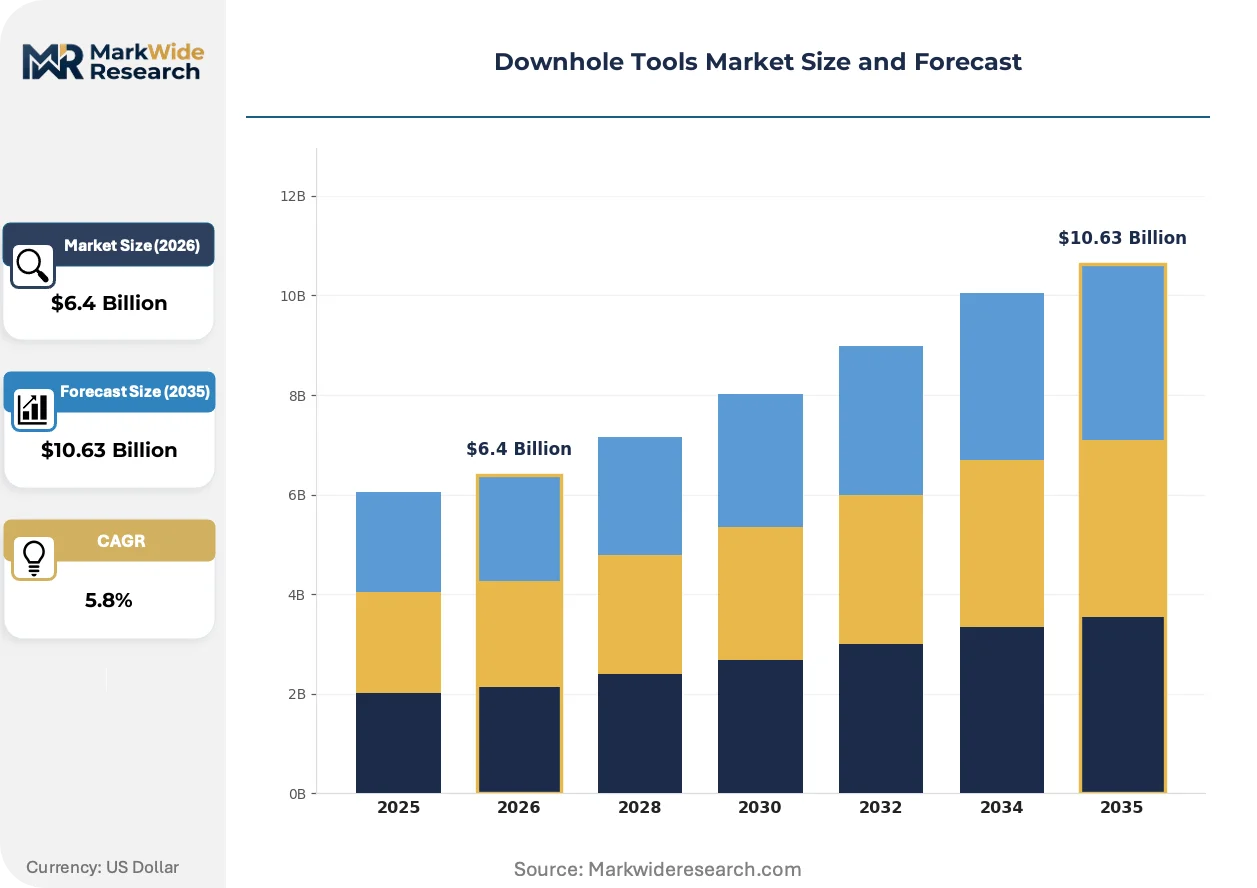
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $10.63 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
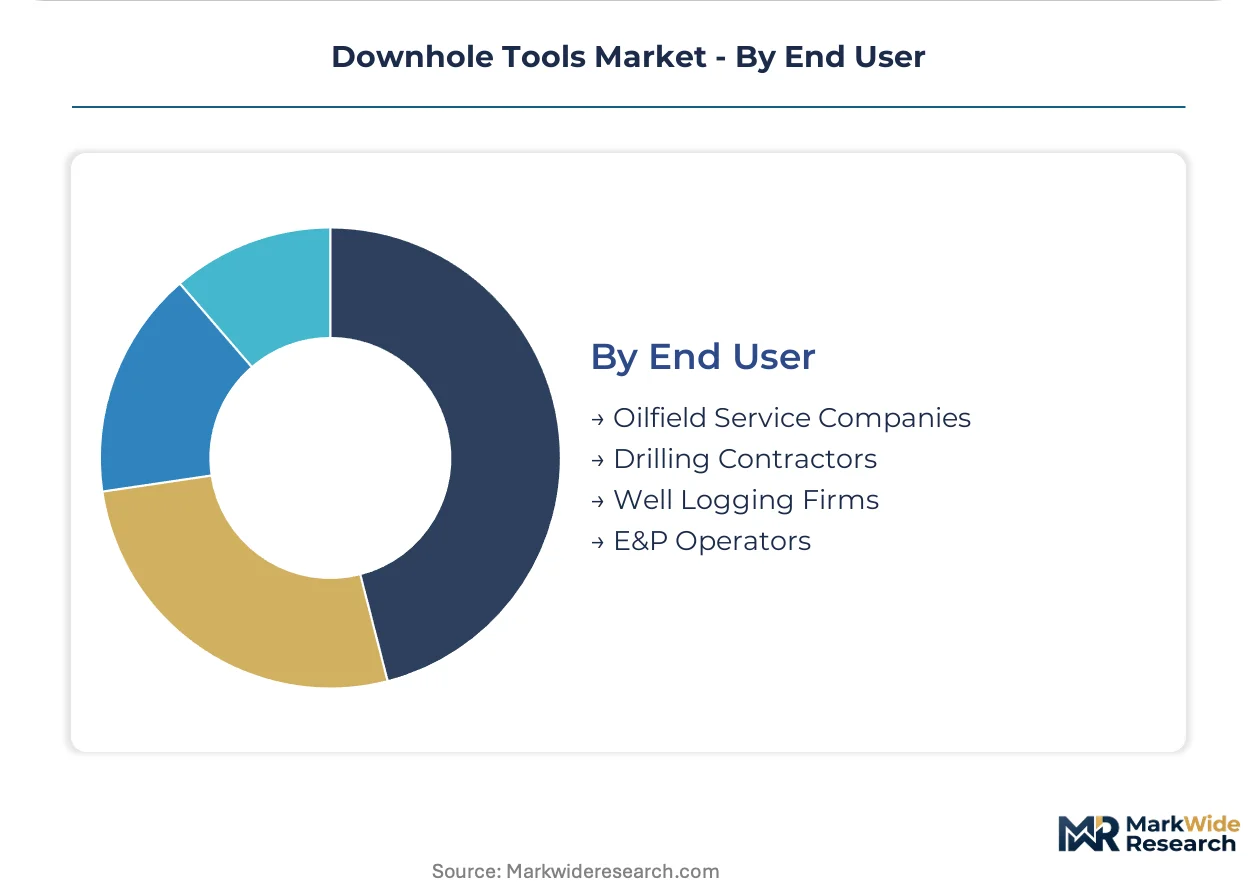
| Segmentation | Product Type: Drilling Stabilizers, Packer Tools, Fishing Tools, Perforating Guns, Completion Tools Technology: Measurement While Drilling, Logging While Drilling, Intelligent Completion, Hydraulic Tools, Mechanical Tools Application: Exploration, Well Intervention, Reservoir Evaluation, Production Optimization, Well Completion End User: Oilfield Service Companies, Drilling Contractors, Well Logging Firms, E&P Operators |
| Companies Covered | SLB, Baker Hughes Company, Halliburton, Weatherford, NOV, TechnipFMC, Hunting PLC, Tenaris, Schlumberger Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Downhole Tools Market Strategic Shifts & Innovations
The functional evolution of downhole equipment reflects a fundamental shift from purely mechanical devices to integrated electromechanical systems. This transition is driven by the operational demand for real-time reservoir insight and automated well control to improve recovery and efficiency.
Fiber-optic sensing provides distributed temperature and acoustic data along the entire wellbore. E&P operators are deploying this technology in unconventional and deepwater wells to monitor hydraulic fracturing and production flow. This technology is hybridizing traditional point-measurement sensors with continuous, full-wellbore surveillance, enabling a more holistic view of reservoir dynamics.
New European Union directives on methane emissions are compelling operators to improve well integrity monitoring and verification. This directly increases the requirement for reliable packers, plugs, and safety valves that can provide long-term sealing assurance. Well completion and intervention segments are most affected, responding with enhanced product certification and lifecycle tracking.
A clear behavioral change sees operators shifting from discrete tool purchases to performance-oriented service contracts. This model disrupts the traditional rental channel, with service providers now assuming more risk and responsibility for achieving specific operational outcomes like production uplift. The model is gaining traction in mature basins like the North Sea where maximizing efficiency is paramount.
Downhole Tools Market Segmentation
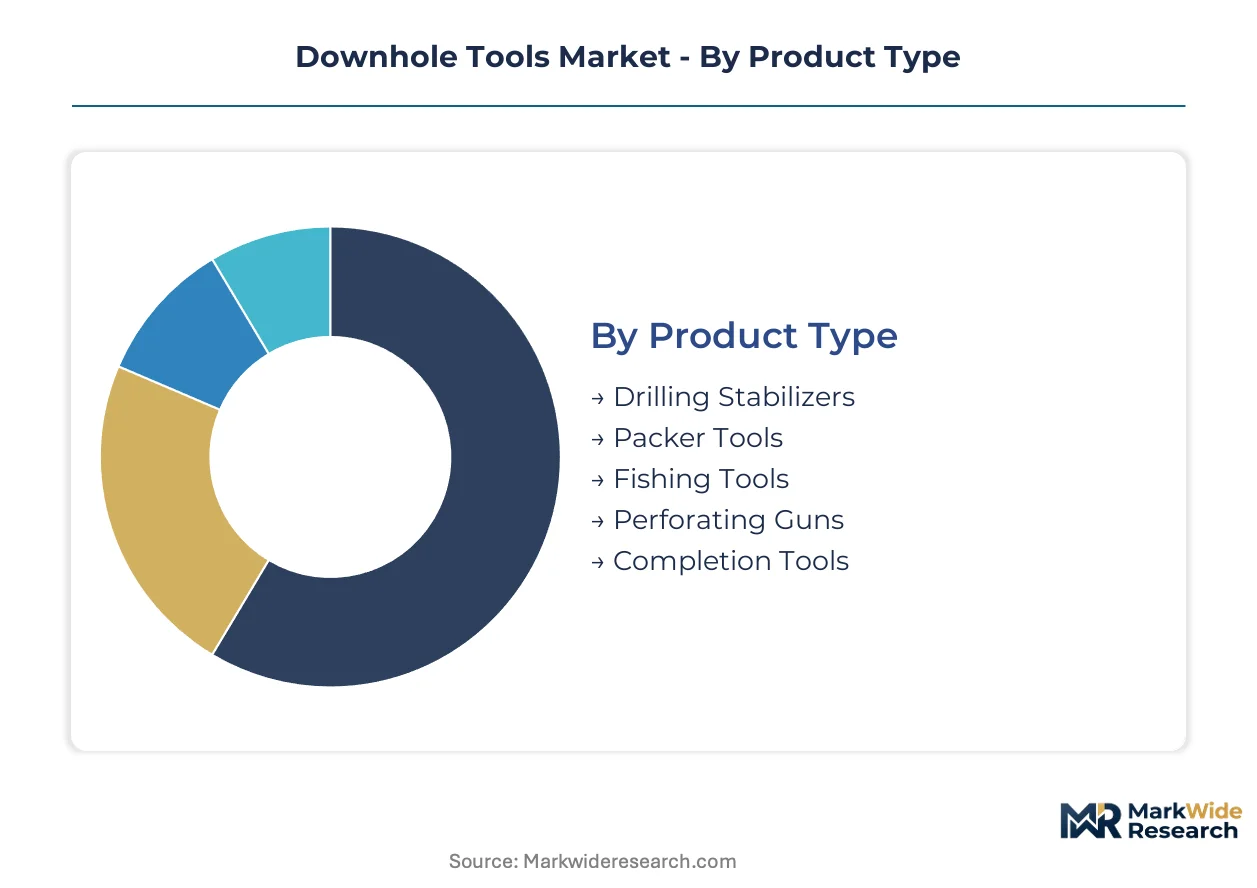
The Downhole Tools Market segmentation provides a granular view of the specialized equipment and services essential for oil and gas exploration and production. This categorization helps operators and service providers understand the specific technological demands and application nuances across the wellbore lifecycle, from initial drilling to late-life intervention.
Product Type:
The downhole tools market addresses a broad use-case spectrum, ranging from initial well construction to long-term asset management and intervention.
- Completion Tools:Completion Tools are critical for optimizing hydrocarbon flow and ensuring well integrity over the production lifecycle, often integrating intelligent sensors for real-time monitoring. Demand for these sophisticated systems is concentrating in deepwater projects like Brazil's pre-salt, driven by the need for maximum recovery in complex reservoirs.
- Drilling Stabilizers:Drilling Stabilizers maintain borehole trajectory and reduce vibration during drilling operations, improving efficiency and extending drill bit life. Their application is crucial in highly deviated and horizontal wells, particularly in North American shale plays, to achieve precise well placement.
- Packer Tools:Packer Tools provide zonal isolation within the wellbore, preventing fluid migration and enabling selective production or injection operations.
- Fishing Tools:Fishing Tools are specialized devices used to retrieve lost or stuck equipment from the wellbore, minimizing operational delays.
- Perforating Guns:Perforating Guns create communication channels between the wellbore and the reservoir formation, facilitating hydrocarbon flow.
Established volume favors Drilling Stabilizers; emerging adoption favors Completion Tools.
Technology:
Technology segmentation reflects the diverse application requirements across the downhole operational lifecycle, from real-time data acquisition to mechanical intervention.
- Measurement While Drilling:Measurement While Drilling (MWD) systems provide real-time data on downhole conditions, including trajectory, pressure, and temperature, enabling immediate adjustments to drilling parameters. E&P operators in the North Sea prioritize MWD for optimizing well placement and reducing non-productive time.
- Intelligent Completion:Intelligent Completion technologies integrate downhole sensors, control lines, and valves to allow remote monitoring and manipulation of reservoir flow. Their deployment is expanding in ultra-deepwater fields offshore Guyana, driven by the need for dynamic reservoir management.
- Logging While Drilling:Logging While Drilling (LWD) provides formation evaluation data in real-time, aiding geosteering and reservoir characterization.
- Hydraulic Tools:Hydraulic Tools utilize fluid pressure for actuation, performing tasks such as setting packers or operating downhole valves.
- Mechanical Tools:Mechanical Tools rely on physical force and movement for their operation, commonly used for setting plugs or engaging components.
Digital integration drives demand for Intelligent Completion, while reliability remains key for Hydraulic Tools.
Application:
The market's application landscape is shaped by the volume and complexity of activities throughout the well's lifecycle, from initial resource identification to sustained production.
- Well Completion:Well Completion involves installing equipment to enable controlled hydrocarbon flow from the reservoir to the surface, crucial for long-term production. This segment generates consistent recurring revenue for service companies, particularly in mature basins requiring sustained asset performance.
- Well Intervention:Well Intervention encompasses remedial operations performed on existing wells to restore or enhance production, including workovers and stimulation treatments. Operators in aging fields, such as those in the Gulf of Mexico, rely heavily on these tools to extend economic life and maximize recovery.
- Exploration:Exploration applications involve tools used during the initial drilling phase to identify and evaluate potential hydrocarbon reservoirs.
- Reservoir Evaluation:Reservoir Evaluation focuses on tools that gather data about formation characteristics, fluid properties, and pressure regimes to optimize development strategies.
- Production Optimization:Production Optimization tools are deployed to improve the efficiency and output of producing wells, often through artificial lift or flow control.
Sustained operational efficiency relies on Well Completion, with Well Intervention supporting long-term asset value.
End User:
The end-user segment reflects the varied customer types procuring downhole tools, each with distinct operational needs and procurement models.
- E&P Operators:E&P Operators are the primary decision-makers for well construction and production strategies, directly influencing tool selection and technology adoption. These companies often invest in proprietary intelligent completion systems to manage their assets in regions like the North Sea.
- Oilfield Service Companies:Oilfield Service Companies provide integrated services and specialized equipment to E&P operators, often leveraging extensive R&D in digital and measurement-while-drilling technologies. Major players like SLB and Baker Hughes Company define this segment's competitive landscape.
- Drilling Contractors:Drilling Contractors specialize in the physical drilling of wells, requiring robust and reliable drilling stabilizers and associated tools.
- Well Logging Firms:Well Logging Firms focus on data acquisition and analysis, driving demand for advanced Measurement While Drilling and Logging While Drilling technologies.
Direct procurement channels are essential for E&P Operators, while specialized services are procured by Oilfield Service Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Downhole Tools Market exhibits significant regional variations in demand, driven by diverse exploration and production activities. Supply-side capabilities are increasingly concentrated in areas with complex deepwater projects and stringent regulatory environments. This concentration supports specialized manufacturing and service delivery for challenging operational conditions.
Brazil
Demand for completion tools concentrates in Brazil's pre-salt basins, driven by ultra-deepwater exploration. ANVISA regulations ensure the certification of high-performance equipment for these challenging deepwater operations. The Campos Basin offshore Rio de Janeiro leads in deploying intelligent completion systems for complex reservoirs.
United States
Well intervention and production optimization activities drive tool demand in the United States, particularly in mature fields. U.S. EPA well integrity rules mandate certified equipment to prevent environmental releases. The Gulf of Mexico sees significant deployment of modern intervention tools to extend asset life.
Norway
Offshore drilling expansion in the North Sea sustains demand for advanced downhole tools in Norway. EU directives on methane emissions compel operators to improve well integrity monitoring and verification. Stavanger serves as a hub for specialized service companies focusing on intelligent completion technologies.
Guyana
Exploration and production activities in new deepwater frontiers create sustained demand for advanced drilling and completion toolsets in Guyana. The country's petroleum legislation emphasizes safe and efficient offshore operations. The Liza field offshore Guyana is a key area for deploying dynamic reservoir management technologies.
United Kingdom
Mature basin rejuvenation efforts in the North Sea drive consistent demand for well completion and intervention tools in the United Kingdom. Offshore safety directives from the UK's Health and Safety Executive mandate robust equipment for deepwater projects. Aberdeen remains a critical operational center for deploying advanced downhole technologies.
Downhole Tools Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, focusing on niche applications. The Downhole Tools Market exhibits a tiered structure, with a few large oilfield service companies dominating integrated service delivery. These major players leverage extensive research and development in digital and measurement-while-drilling technologies to offer comprehensive solutions. Mid-sized specialized tool manufacturers challenge incumbents by focusing on specific applications like intelligent completion technologies. Strategic partnerships and technology licensing are common competitive moves to expand market reach and capabilities.
Within the integrated service provider archetype, SLB exemplifies a company leveraging extensive research and development in digital and measurement-while-drilling technologies. Baker Hughes Company occupies a position defined by its comprehensive portfolio of advanced drilling and completion tools, serving complex deepwater projects. Halliburton represents a major player competing on integrated service delivery, addressing a wide range of operational requirements across the wellbore lifecycle, particularly in mature basins. These global entities anchor the market's technological advancements and service offerings for E&P operators.
| Leading Market Players |
|---|
| SLB |
| Baker Hughes Company |
| Halliburton |
| Weatherford |
| NOV |
| TechnipFMC |
| Hunting PLC |
| Tenaris |
| Schlumberger Limited |
| Others |
Cost & Logistics Intelligence
Regulatory chokepoints, particularly around well integrity and extreme operating conditions, determine both pricing tier spreads and the specialized supply chain shape for downhole tools. These stringent requirements necessitate high-cost materials and extensive certification processes, directly impacting final product pricing and limiting the number of qualified suppliers.
Pricing Analysis
ISO standards for packers and completion tools dictate the pricing tier structure for certified equipment. Contract-based long-term service agreements, often with project-based components, dominate the market's pricing model. Price differentiation stems from certification levels and the inclusion of comprehensive after-sales service packages. Pricing softness emerges from increased competition among specialized tool manufacturers in niche applications. E&P Operators demonstrate lower price sensitivity for critical intelligent completion tools, while smaller operators seek more cost-effective, standardized solutions.
Supply Chain Analysis
Single-source vulnerability for specialized components, such as high-temperature elastomers and advanced sensor electronics, defines critical nodes in the supply chain. Geographic supply concentration includes manufacturing hubs in the United States, specialized engineering firms across Europe, and component suppliers in Asia. HPHT qualification delays present a significant structural risk, impacting time-to-market for new technologies. Distribution runs primarily through direct sales channels to E&P operators and integrated oilfield service companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Downhole Tools Market presents a fragmentation opportunity; ultra-deepwater project complexity creates distinct niches for specialized tool development and service delivery.
For Market Incumbents:
Pre-empt emerging specialized tool manufacturers by strategically acquiring niche technology firms focused on intelligent completion systems. Invest heavily in digital twin integration capabilities to counter technology concentration among a few players and enhance predictive maintenance offerings. Develop advanced material science R&D to overcome current elastomer and metal alloy limitations in HPHT environments. Reinforce existing service delivery networks in prolific offshore basins like Brazil's pre-salt to maintain market share against new entrants.
For New Entrants and Emerging Players:
Underpenetration in geothermal energy applications presents a clear entry point for adapting existing oil and gas HPHT tools. Target the well intervention segment in mature fields by offering performance-oriented service contracts that guarantee production uplift. Focus on developing specialized fiber-optic sensing solutions for continuous, full-wellbore surveillance in unconventional plays. Leverage agile development cycles to bring certified, high-performance equipment to market faster than traditional incumbents.
For Investors and Strategic Acquirers:
EU methane emission directives reshape the acquisition landscape for well integrity solutions, creating long-term viability for specialized sealing technologies. Seek out mid-cap firms with strong intellectual property in advanced materials or real-time data analytics for intelligent completions. The signal to watch is the increasing adoption rate of autonomous well optimization systems in deepwater projects. Evaluate companies demonstrating robust product certification and lifecycle tracking capabilities in regulated markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Niche Technology Firms | Secures specialized intelligent completion IP and accelerates market entry into high-growth segments. |
| Investment in Digital Twin Integration | Enables predictive maintenance and autonomous well optimization, enhancing operational efficiency for E&P operators. |
| Development of Advanced HPHT Materials | Overcomes current physical limits, allowing tool deployment in ultra-deepwater and geothermal applications. |
| Expansion into Geothermal Tool Adaptation | Opens a new adjacent market for existing downhole tool expertise, diversifying revenue streams. |
| Focus on Performance-Oriented Service Contracts | Aligns service provider incentives with operator production outcomes, fostering long-term client relationships. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews to gather qualitative and quantitative insights. This included E&P engineers, oilfield service company R&D leads, regulatory compliance officers, and drilling contractors. Secondary validation drew from industry association reports, patent databases, technical conference proceedings, and public financial disclosures, ensuring a robust data foundation. The analysis employed both bottom-up aggregation and top-down market sizing techniques for comprehensive triangulation.
The calibration approach integrated historical market data with forward-looking projections across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, end-user, and regional demand patterns. Compound annual growth rates were derived by assessing market drivers, restraints, and strategic opportunities. Key industry-specific forecast inputs included E&P capital expenditure trends and global offshore rig count fluctuations.
Macroeconomic conditions sit as an overlay; deviation in global energy prices or geopolitical stability would shift the trajectory. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Material shifts in major deepwater project approvals or sudden regulatory changes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Deepwater and Ultra-Deepwater Exploration and Production Market
Oil & Gas
Leak Detection for Oil & Gas Market
Oil & Gas
Europe Seismic Survey Market
Oil & Gas
Nigeria Oil and Gas Upstream Market
Oil & Gas
Casing and Cementation Hardware Market
Oil & Gas
India Artificial Lift Systems Market
Oil & Gas
Oil and Gas Corrosion Protection Market
Oil & Gas
Gabon Oil and Gas Market
Oil & Gas
Copper Mining Market
Oil & Gas
Iran Oil and Gas Exploration and Production Market
Oil & Gas
Oil and Gas Downhole Vibration Monitoring and Control System Market
Oil & Gas
Frac Tree Market
Oil & Gas
Canada Oil and Gas Upstream Market
Oil & Gas
Russian Federation Oil and Gas Upstream Market
Oil & Gas
Mineral Oil and Mineral Spirit Market
Oil & Gas
Europe Natural Gas Market