
 Australia LNG Bunkering Market | 2026-2036
Australia LNG Bunkering Market Size, Share, and Industry Trends Forecast 2026-2036
Australia LNG Bunkering Market Outlook
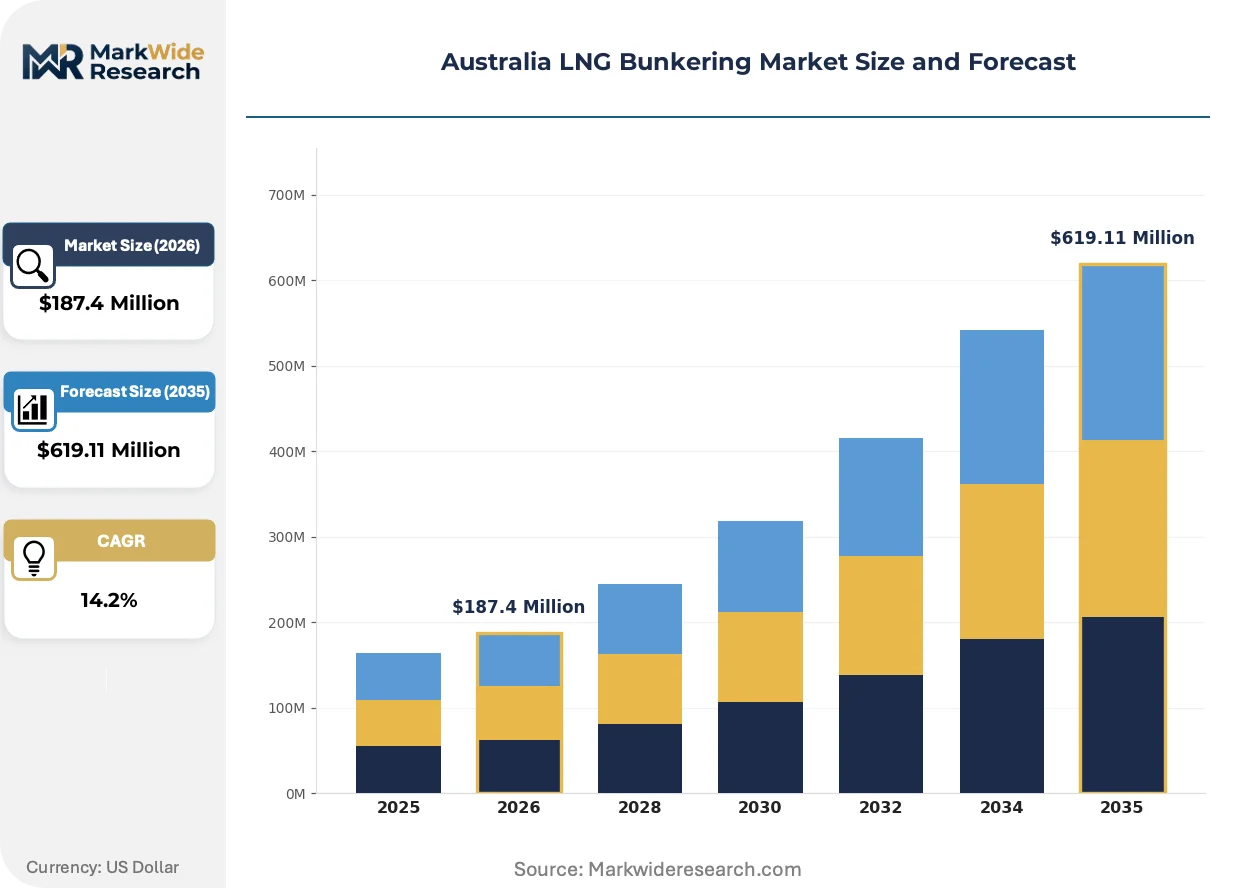
Australian east coast gas producers is pivoting toward marine fuel applications as domestic LNG export capacity exceeds contracted offtake. Woodside Petroleum Ltd leverages its Pluto LNG infrastructure to supply bunkering volumes through Gladstone. Shell plc anchors its position with integrated trading and shipping operations across Australian ports. EVOL LNG competes through specialized cryogenic logistics and small-scale delivery systems.
Australia LNG bunkering denotes the transfer of liquefied natural gas as marine fuel to vessels, stored at minus 162 degrees Celsius in double-walled vacuum-insulated tanks and vaporized through high-pressure regasification skids before engine injection. The practice displaces residual fuel oil to comply with sulfur emission limits in coastal waters. Mobile bunkering leads service type deployment due to flexibility at ports lacking fixed infrastructure. Ship-to-ship transfer represents the fastest-expanding bunkering method as it minimizes vessel downtime during cargo operations. High-pressure delivery dominates for dual-fuel engine configurations now standard in newbuild tankers.
The Australian Maritime Safety Authority enforces sulfur oxide emission control areas extending two hundred nautical miles from the coastline, directly compelling vessel operators to adopt LNG-compatible propulsion. ISO 20519 standards govern bunkering system design and operational safety protocols, while the International Maritime Organization's carbon intensity regulations tighten further compliance requirements. Stakeholders must monitor port infrastructure investment decisions at Brisbane, Newcastle, and Fremantle to determine where supply capacity crystallizes first.
Market Dynamics
The Australian Maritime Safety Authority's emission control area mandates are compressing vessel operators' fuel choices, forcing accelerated adoption of LNG-compatible propulsion systems along coastal trade routes. This regulatory pressure intersects with Gladstone's surplus export capacity to reshape marine fuel supply geography.
Growth Catalysts
- IMO Carbon Intensity Regulations:The International Maritime Organization's tightening carbon intensity indicators mandate measurable emissions reductions for vessels calling at Australian ports, compelling fleet operators to evaluate LNG propulsion against residual fuel alternatives.
- Queensland Export Corridor Concentration:Gladstone's established LNG export infrastructure provides ready cryogenic storage and regasification assets that marine fuel suppliers can repurpose for bunkering operations without greenfield capital deployment.
- Dual-Fuel Engine Technology:Newbuild tankers and container vessels now standardize high-pressure LNG injection systems, creating built-in demand for compatible bunkering infrastructure at Port Botany and Port of Brisbane.
Market Restraints
- Cryogenic Infrastructure Cost Structure:Double-walled vacuum-insulated storage tanks and specialized regasification skids require capital intensity that exceeds conventional marine fuel terminal investments by substantial multiples.
- East Coast Supply Concentration:Domestic LNG production capacity clusters heavily around Gladstone and the Queensland coast, leaving Western Australian and South Australian ports dependent on higher-cost distributed supply chains.
- Methane Slip Technical Limitation:Unburned methane emissions from dual-fuel engines reduce the effective greenhouse gas advantage of LNG propulsion, complicating compliance claims under emerging lifecycle accounting frameworks.
Strategic Opportunities
- Fremantle Port Infrastructure Gap:Western Australia's container and bulk trade volumes currently lack dedicated LNG bunkering facilities, creating first-mover positioning for suppliers willing to deploy mobile cryogenic logistics systems.
- Ship-to-Ship Transfer Method:This bunkering approach minimizes vessel downtime during cargo operations and enables service at anchorages without fixed terminal infrastructure, expanding addressable vessel categories.
- ISO 20519 Standardization Tailwind:International standardization of bunkering system design and operational safety protocols reduces regulatory friction for cross-border fleet operators, accelerating adoption confidence among container shipping lines.
Industry Challenges
- Cryogenic Engineering Skill Gap:Specialized technicians capable of maintaining minus 162 degree Celsius storage systems and high-pressure regasification equipment remain scarce in Australian maritime labor markets.
- Port Authority Coordination Complexity:Simultaneous scheduling of cargo operations, pilotage services, and bunkering transfers requires real-time integration between terminal operators, port authorities, and vessel agents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia LNG Bunkering Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Bunkering, Shore-to-Ship, Ship-to-Ship, Port Operations Bunkering Method: High-Pressure, Low-Pressure, Cryogenic, Gravity Feed End User: Shipping Companies, Charters, Vessel Operators, Freight Forwarders Vessel Type: Bulk Carriers, Tankers, Ferries, Offshore Support Vessels |
| Companies Covered | Oceania Marine Energy, EVOL LNG, Woodside Petroleum Ltd, Shell plc, Kanfer Shipping, Siem Offshore Inc, Norwest Energy NL, Chevron Corporation, Gas Energy Australia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia LNG Bunkering Market Strategic Shifts
Digital monitoring systems and automated custody transfer protocols are reshaping how LNG bunkering operations verify fuel quality and quantity, reducing dispute resolution overhead in high-value marine fuel transactions.
High-pressure LNG delivery systems are converging with dual-fuel engine architectures to enable direct injection at pressures exceeding 300 bar, eliminating the fuel-air mixing limitations of earlier low-pressure designs. Container shipping lines operating out of Port Botany are specifying these configurations in newbuild contracts. This technological alignment is compressing the competitive window for residual fuel oil suppliers in Australian coastal trades.
The Australian Maritime Safety Authority's sulfur oxide emission control area extension to two hundred nautical miles is mandating fuel switching for all vessels transiting Australian coastal waters. This regulatory boundary forces fleet operators to either install exhaust scrubbing systems or convert to LNG propulsion. Bulk carriers and tankers with regular Australia-Asia routes are disproportionately affected, with many opting for LNG-compatible newbuilds rather than retrofitting existing vessels.
Container shipping lines are consolidating fuel procurement decisions at regional headquarters rather than delegating to individual vessel masters, centralizing contract negotiations with LNG suppliers across multiple Australian port calls. This purchasing concentration shifts bargaining power toward large fleet operators and away from fragmented bunker traders. The practice is most visible among Asia-Pacific headquartered shipping groups with sustained volume commitments through Port of Brisbane and Port Botany.
Australia LNG Bunkering Market Segmentation
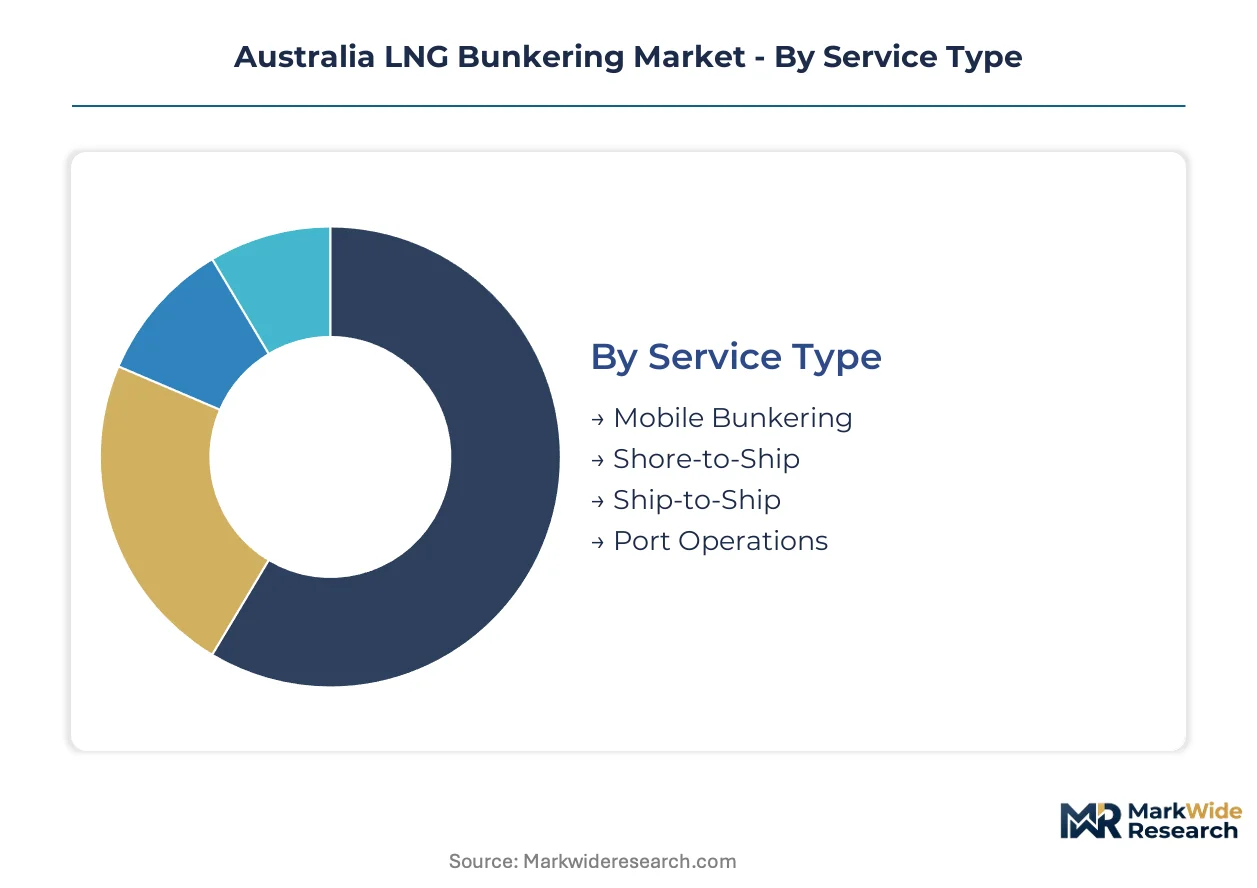
Segmentation reveals how LNG bunkering infrastructure investment concentrates around specific operational models and vessel categories. Supply-side configuration differs sharply across service types and bunkering methods, shaping where capital deployment yields fastest returns.
Service Type:
Gladstone's cryogenic storage assets and Queensland's export corridor concentration determine which service models achieve viable unit economics.
- Mobile Bunkering:Specialized cryogenic road tankers and portable regasification skids deliver LNG directly to vessels at anchorages lacking fixed infrastructure. Port Botany and Port of Brisbane container terminals rely on this flexibility while permanent facilities remain under construction.
- Ship-to-Ship:Dedicated LNG bunker vessels transfer fuel alongside cargo operations, eliminating port congestion and minimizing vessel downtime. This method is expanding most quickly among Asia-Pacific container lines with regular Australia-Asia routes.
- Shore-to-Ship:Fixed terminal infrastructure with dedicated loading arms serves vessels berthed at specialized LNG jetties. Fremantle and Newcastle ports lack this capacity, constraining adoption.
- Port Operations:Integrated terminal services bundle bunkering with pilotage, tugs, and cargo handling under unified scheduling. Australian Maritime Safety Authority coordination requirements add operational complexity.
Mobile bunkering absorbs the bulk of installed capacity; ship-to-ship transfer is expanding most quickly.
Bunkering Method:
Engine technology specifications and fuel system architecture drive method selection across the Australian fleet.
- High-Pressure:Delivery at 300 bar enables direct injection into dual-fuel engines without pre-mixing limitations. Newbuild tankers and container vessels from Korean and Chinese yards now standardize this configuration for Australian coastal trades.
- Cryogenic:Minus 162 degree Celsius transfer maintains LNG in liquid phase through vacuum-insulated lines and specialized coupling systems. EVOL LNG and Woodside Petroleum deploy this method for small-scale deliveries along the Queensland coast.
- Low-Pressure:Fuel-air mixing in engine cylinders suits older dual-fuel retrofits and auxiliary power units. Methane slip concerns limit compliance advantages under emerging lifecycle accounting frameworks.
- Gravity Feed:Elevation-differential transfer eliminates pumping equipment for small-volume deliveries to ferries and offshore support vessels. Limited to vessels with compatible tank configurations.
High-pressure delivery dominates newbuild specifications; cryogenic transfer gains share fastest among specialized suppliers.
End User:
Procurement centralization concentrates contract negotiations among fleet operators with sustained Australian port exposure.
- Shipping Companies:Asia-Pacific headquartered container lines consolidate fuel procurement at regional headquarters, negotiating multi-port supply agreements across Port Botany, Port of Brisbane, and Gladstone.
- Vessel Operators:Bulk carrier and tanker managers with regular Australia-Asia routes evaluate LNG propulsion against scrubber installations under Australian Maritime Safety Authority emission control mandates.
- Charters:Time-charter and voyage-charter parties face split incentive problems where fuel cost responsibility does not align with capital expenditure decisions for engine technology.
- Freight Forwarders:Logistics coordinators influence carrier selection based on emissions reporting requirements from Australian import and export shippers.
Shipping companies absorb the bulk of contracted volume; vessel operators are expanding their LNG-compatible fleet fastest.
Vessel Type:
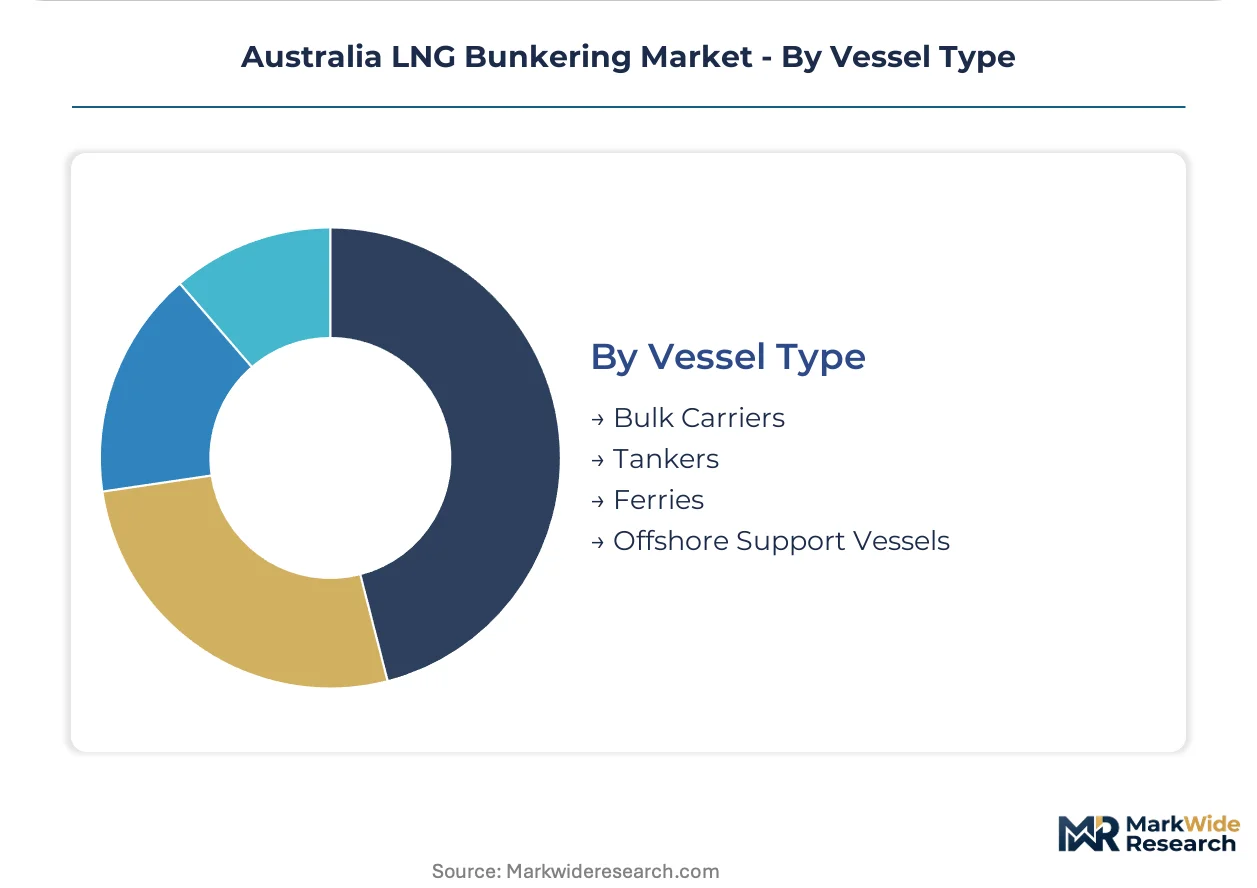
Trade route regularity and fuel consumption profiles determine which vessel categories justify LNG propulsion investment.
- Container Vessels:High-frequency Australia-Asia services with predictable port rotations achieve fastest payback on dual-fuel engine capital. Port Botany and Port of Brisbane handle the majority of this traffic.
- Bulk Carriers:Iron ore and coal trades from Western Australia face longer intervals between Australian port calls, complicating bunkering logistics despite high fuel consumption.
- Tankers:Product and chemical tankers with coastal distribution routes fall under Australian Maritime Safety Authority sulfur oxide emission control area requirements for two hundred nautical miles.
- Ferries:High-speed passenger and vehicle services in Queensland and Western Australia operate on fixed routes enabling dedicated shore-to-ship infrastructure.
- Offshore Support Vessels:Supply boats servicing Gladstone's LNG export facilities leverage proximity to cryogenic storage for convenient refueling.
Container vessels absorb the bulk of high-pressure delivery infrastructure; bulk carriers are adopting LNG propulsion fastest among retrofit candidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gladstone's export corridor anchors Australia's LNG bunkering geography, with cryogenic infrastructure repurposing surplus export capacity for marine fuel applications along the Queensland coast.
New South Wales
Container shipping lines at Port Botany drive demand for mobile bunkering systems while permanent infrastructure remains under construction. The Australian Maritime Safety Authority's emission control area mandates compel vessel operators to adopt LNG-compatible propulsion for coastal trades. Sydney's port cluster concentrates procurement negotiations among Asia-Pacific headquartered fleet operators.
Queensland
Gladstone's established LNG export terminals provide ready cryogenic storage assets that marine fuel suppliers redirect toward bunkering operations without greenfield investment. The state's surplus domestic production capacity exceeds contracted offtake, freeing volumes for marine fuel applications. Brisbane's container terminal expansion parallels rising LNG fuel contract volumes from regional shipping lines.
Western Australia
Fremantle's container and bulk trade volumes currently lack dedicated LNG bunkering facilities, creating positioning opportunities for mobile cryogenic logistics deployers. The state's iron ore export dominance complicates bunkering economics given irregular vessel rotations between Australian and Asian ports. Perth's industrial corridor remains dependent on higher-cost distributed supply chains from Queensland production centers.
Victoria
Melbourne's port infrastructure faces scheduling complexity between cargo operations, pilotage services, and bunkering transfers requiring real-time coordination. The state's manufacturing heritage supplies specialized technicians for minus 162 degree Celsius storage maintenance, partially offsetting national skill scarcity. Bass Strait offshore support vessel operators evaluate dedicated shore-to-ship infrastructure for fixed route operations.
South Australia
Adelaide's port facilities remain peripheral to current LNG bunkering investment flows given distance from Queensland supply sources and limited container trade volumes. The state's defense shipbuilding programs at Osborne generate prospective demand for cryogenic marine fuel applications. Spencer Gulf bulk commodity exports face longer intervals between port calls, complicating bunkering logistics despite regulatory pressure from Australian Maritime Safety Authority mandates.
Australia LNG Bunkering Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized cryogenic logistics and small-scale delivery configurations. The supplier base clusters around integrated oil majors with trading and shipping operations, domestic gas producers repurposing export infrastructure, and specialized marine fuel logistics operators. Three archetypes dominate: vertically integrated energy conglomerates with captive LNG supply, regional gas producers leveraging proximity to export terminals, and dedicated bunkering service providers with mobile delivery systems. Capacity expansion and strategic port partnerships constitute the dominant competitive vectors as operators race to secure positioning at Brisbane, Newcastle, and Fremantle.
Among integrated energy majors, Shell plc and Chevron Corporation exemplify the trading-and-shipping archetype with cross-port operational coordination. Woodside Petroleum Ltd anchors the domestic producer tier through Pluto LNG infrastructure repurposing at Gladstone. EVOL LNG occupies the specialized logistics position with cryogenic road tanker and portable regasification capabilities for ports lacking fixed terminals. These three patterns illustrate how supply-side configuration differs sharply across operational models, shaping where capital deployment yields fastest returns in the Australian coastal trade corridor.
| Leading Market Players |
|---|
| Oceania Marine Energy |
| EVOL LNG |
| Woodside Petroleum Ltd |
| Shell plc |
| Kanfer Shipping |
| Siem Offshore Inc |
| Norwest Energy NL |
| Chevron Corporation |
| Gas Energy Australia |
| Others |
Value Chain & Pricing Dynamics
A certification-grade divergence between ISO 20519-compliant cryogenic systems and non-standard mobile configurations manifests in both pricing premiums and supply chain sourcing patterns across Australian ports. Premium-tier suppliers bundle engineering validation with custody transfer protocols while economy operators unbundle cryogenic maintenance from base delivery rates.
Pricing Analysis
Service bundling separates fixed-terminal shore-to-ship contracts from unbundled mobile bunkering rates where cryogenic logistics and regasification skids carry separate line items. Three-tier pricing structure across premium, standard, and economy levels reflects certification status, with Australian Maritime Safety Authority compliance validation commanding material premiums. Pricing pressure stems from Gladstone's surplus export capacity freeing volumes for marine fuel applications. Container shipping lines at Port Botany exhibit lowest price sensitivity given procurement centralization, while independent vessel operators in Fremantle remain most cost-conscious.
Supply Chain Analysis
Specialized cryogenic technicians cluster in Victoria's manufacturing corridor and Queensland's Gladstone export zone, constraining workforce availability for Western Australian expansion. LNG production concentrates in Australia and Qatar, with cryogenic storage vessels and high-pressure regasification skids sourced from South Korea and Japan. Single-source vulnerability runs through Korean shipyard capacity for bunker vessel construction. Distribution runs through integrated oil majors with captive supply, regional gas producers repurposing export terminals, and specialized logistics operators with mobile delivery fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australian LNG bunkering market functions as a cost-of-compliance story where Australian Maritime Safety Authority emission control area mandates create a regulatory moat favoring players with certified cryogenic infrastructure and validated operational protocols.
For Market Incumbents: Acquire mobile cryogenic logistics fleets to preempt Fremantle positioning before permanent infrastructure crystallizes. Secure long-term supply agreements with Gladstone export terminal operators to lock in feedstock cost advantages against emerging traders. Backward integration into cryogenic road tanker manufacturing mitigates equipment lead time risks from Korean suppliers. For New Entrants and Emerging Players: ISO 20519 standardization in Australian waters opens a window for specialized compliance consulting bundled with bunkering operations. Target Western Australia's Fremantle container trade with portable regasification systems before integrated majors deploy fixed terminals. Lead with ship-to-ship transfer capabilities to minimize port authority coordination burdens that favor established operators. For Investors and Strategic Acquirers: Re-rating potential sits with specialized cryogenic logistics operators given Australian Maritime Safety Authority enforcement tightening and container line procurement centralization. Five-to-ten year viability hinges on methane slip mitigation technology maturation. Monitor dual-fuel engine order books at Korean and Chinese shipyards as inflection signal for bunkering infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Infrastructure Buildout | Fixed terminal investment at Fremantle captures Western Australia container trade before mobile competitors consolidate. |
| Ship-to-Ship Transfer Capability | Bunker vessel deployment minimizes port congestion and expands addressable vessel categories beyond berthed ships. |
| ISO 20519 Certification Investment | Operational safety validation reduces regulatory friction for cross-border fleet operators at Port Botany. |
| Feedstock Supply Integration | Long-term offtake agreements with Gladstone export terminals secure cost-competitive LNG supply volumes. |
| Cryogenic Workforce Development | Victoria technician training partnerships address national skill scarcity for minus 162 degree Celsius system maintenance. |
Study Parameters
Independent corroboration across Australian Maritime Safety Authority regulatory filings, port authority infrastructure investment disclosures, and container shipping line newbuild specifications underwrites the qualitative findings. Primary interviews with marine fuel procurement managers, cryogenic logistics operators, and dual-fuel engine technical directors combined with secondary validation from SEC filings of integrated oil majors, Australian Bureau of Statistics trade data, and International Maritime Organization regulatory updates. Bottom-up vessel fleet analysis and top-down fuel consumption modeling triangulate volume estimates.
Rate-of-change decomposition separates regulatory mandate timing, dual-fuel engine installation curves, and port infrastructure commissioning schedules across the projection horizon. Segmentation dimensions modeled include service type, bunkering method, vessel category, and regional port cluster. CAGRs derive from compounding annual installation rates against fleet turnover assumptions. Cryogenic storage capacity additions and high-pressure delivery system deployment counts serve as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for methane slip mitigation would alter the outlook for LNG propulsion competitiveness under lifecycle accounting frameworks. Forecasts reflect assumptions regarding Australian Maritime Safety Authority enforcement consistency and container line procurement centralization trends. Material deviation in dual-fuel engine order book trajectories or Queensland export terminal capacity utilization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Tight Gas Market
Oil & Gas
Asia-Pacific Intelligent Pigging Market
Oil & Gas
Distributed Fiber Optic Sensor in Oil & Gas Market
Oil & Gas
North America Completion Equipment and Services Market
Oil & Gas
Enclosed Flares Market
Oil & Gas
Iron Ore Mining Market
Oil & Gas
Indonesia Coal Market
Oil & Gas
Oil Tank Rotating Stacker Market
Oil & Gas
Digital Twin in Oil and Gas Market
Oil & Gas
Asia-Pacific Oilfield Auxiliary Rental Equipment Market
Oil & Gas
Southeast Asia Oil and Gas EPC Market
Oil & Gas
Romania Oil and Gas Downstream Market
Oil & Gas
CO2 EOR Market
Oil & Gas
Sand Control Screens Market
Oil & Gas
Offshore Drilling Fluid Market
Oil & Gas
Republic of Congo Oil and Gas Market