
 Middle East and Africa Pipeline Maintenance Market | 2026-2036
Middle East and Africa Pipeline Maintenance Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Pipeline Maintenance Market Insights
The EU Green Deal's extraterritorial carbon border adjustments is decoupling European-bound crude certification from conventional maintenance practices across Middle East and Africa export corridors. Halliburton Company leverages its integrated wellbore-to-terminal service architecture to sustain long-term contracts in Saudi Arabia's Ghawar field complex. BP PLC anchors its regional maintenance footprint through joint venture structures in Oman and Iraq, while Rezayat Group competes on localized fabrication and rapid-response repair capabilities across the Gulf Cooperation Council states.
Middle East and Africa pipeline maintenance encompasses the systematic inspection, cleaning, rehabilitation, and repair of hydrocarbon and water transmission infrastructure operating at pressures typically ranging from 50 to 200 bar, utilizing inline inspection tools, robotic crawlers, and sensor networks to ensure structural integrity and flow assurance across thousands of kilometers of buried and subsea lines. Smart pigging technology dominates the technology segment due to its established track record in detecting metal loss and deformation across Saudi Aramco's Master Gas System, while drone-based aerial surveillance represents the fastest-growing inspection modality as operators seek to reduce manned aerial patrol costs over remote desert and offshore routes. The service type dimension shows rehabilitation outpacing routine cleaning as decades-old carbon steel lines across Libya and Nigeria require composite sleeve repairs and cathodic protection upgrades to extend remaining operational life.
Saudi Arabia's national oil company imposes internal standards that exceed minimum SAMR requirements, compelling maintenance contractors to achieve third-party ISO 9001 and API Q2 certifications before qualifying for upstream service awards. Nigeria's Department of Petroleum Resources enforces pipeline integrity management regulations modeled on US DOT PHMSA frameworks, requiring leak detection system upgrades across the Niger Delta trunk network. Stakeholders must monitor how Egypt's petroleum ministry integrates climate disclosure requirements into concession renewal terms, as this will reshape contractor qualification criteria across the Eastern Mediterranean gas corridor.
Market Dynamics
Smart pigging systems are displacing manual inspection protocols across Saudi Aramco's Master Gas System, compressing defect detection timelines from weeks to days while forcing contractor recertification around API Q2 and ISO 9001 standards.
Growth Catalysts
- Nigeria's DPR Integrity Mandates:Leak detection system upgrades across the Niger Delta trunk network are mandating inline inspection tool deployment, creating immediate service demand for qualified contractors.
- Composite Sleeve Rehabilitation:Decades-old carbon steel infrastructure across Libya requires cathodic protection upgrades and composite repairs, extending operational life without full line replacement.
- Saudi Eastern Province Concentration:Saudi Aramco maintains the world's largest crude oil pipeline network, driving concentrated procurement of drone-based aerial surveillance and robotic crawler services.
Market Restraints
- Specialized Equipment Import Dependence:Magnetic flux leakage tool fabrication concentrates in North American and European supply bases, exposing contractors to currency volatility and extended lead times.
- Desert Terrain Access Limitations:Remote pipeline corridors across the Rub' al Khali and Sahara restrict mobilization logistics, inflating per-kilometer inspection costs versus temperate climate benchmarks.
- EU Green Deal Carbon Border Adjustments:Extraterritorial certification requirements are decoupling European-bound crude from conventional maintenance practices, forcing documentation system overhauls.
Strategic Opportunities
- UAE Offshore Drone Surveillance:Abu Dhabi National Oil Company is expanding unmanned aerial patrol coverage over subsea pipeline corridors, reducing manned helicopter exposure.
- Egypt Climate Disclosure Integration:The petroleum ministry is embedding emissions reporting into concession renewal terms, creating first-mover advantage for contractors with verified carbon accounting capabilities.
- Sensor-Analytics Convergence:Real-time vibration monitoring fused with predictive algorithms enables shift from scheduled maintenance to condition-based intervention models.
Industry Challenges
- API Q2 Certification Bottlenecks:Third-party quality management accreditation requires 12-18 month validation cycles, delaying contractor qualification for Saudi upstream awards.
- Legacy Cathodic Protection Integration:New impressed current systems must interface with 1970s-era sacrificial anode networks across aging Nigerian trunk lines, complicating retrofit engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Pipeline Maintenance Market |
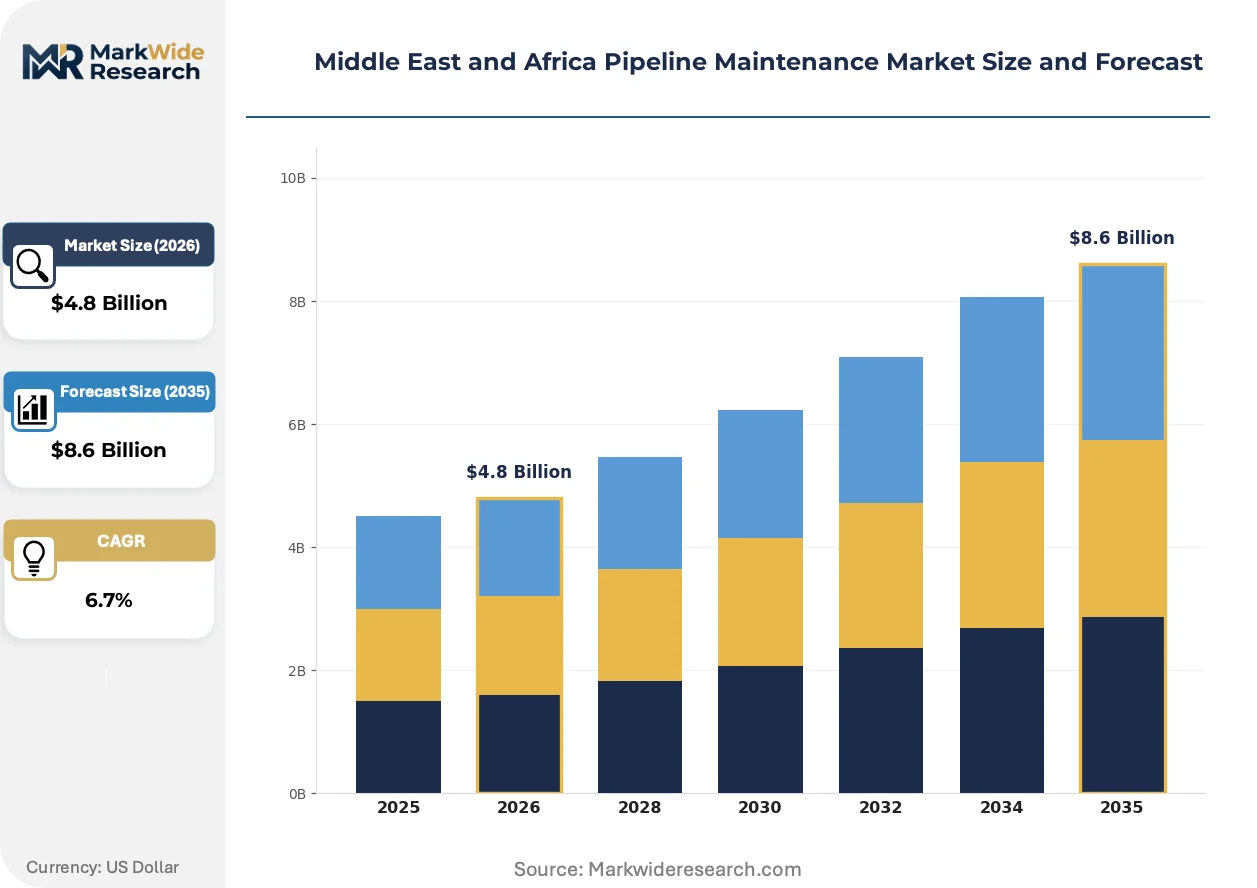
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inspection, Cleaning, Rehabilitation, Repair Technology: Smart Pigs, Robots, Sensors, Drones End User: Oil & Gas Companies, Water Utilities, Municipalities, Industrial Facilities Application: Leak Detection, Corrosion Management, Flow Assurance, Maintenance Planning |
| Companies Covered | Saudi Aramco, ExxonMobil Corporation, BP PLC, Halliburton Company, Rezayat Group, Arabian Pipes Company, OLEUM Process & Pipeline Services, Frontier Pipeline Services, STATS Group, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Pipeline Maintenance Market Trends and Innovations
Inspection modality diversification is fragmenting service procurement, with operators unbundling previously integrated maintenance packages and awarding discrete technology contracts to specialized providers.
Ultrasonic testing smart pigs are integrating acoustic resonance mapping with onboard data processing, enabling real-time wall-thickness analysis without surface excavation. Saudi Aramco's Eastern Province trunk lines are deploying these tools at 18-month intervals, down from 36-month legacy cycles. This compression is integrating predictive maintenance workflows directly into control room operations, collapsing the gap between detection and intervention.
Saudi Arabia's national oil company has imposed internal standards exceeding minimum SAMR requirements, compelling maintenance contractors to achieve third-party ISO 9001 certification before qualifying for upstream service awards. This regulatory layering is filtering out mid-tier service providers lacking quality management infrastructure. Nigerian operators are responding by adopting US DOT PHMSA-modeled frameworks, creating transatlantic regulatory convergence across export corridors.
Service unbundling is fragmenting long-term maintenance contracts into discrete technology-specific awards, with drone surveillance, inline inspection, and rehabilitation services now procured separately. This disaggregation favors specialized providers with single-modality depth over integrated generalists. The shift is most visible in UAE offshore operations, where ADNOC has separated aerial patrol from subsea inspection contracts.
Middle East and Africa Pipeline Maintenance Market Segmentation
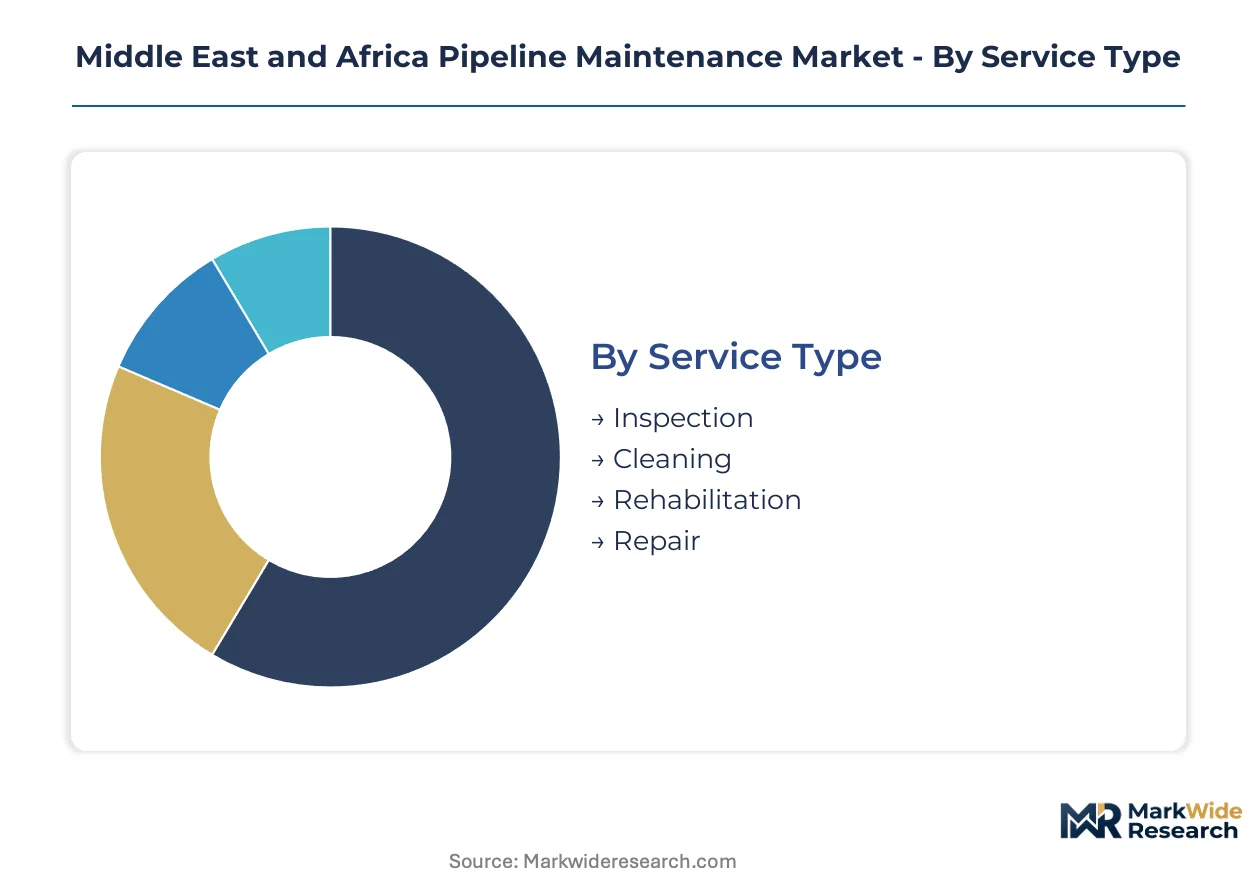
Segmentation in pipeline maintenance reflects how operators balance standardized inspection protocols against site-specific engineering requirements. Procurement patterns diverge sharply between high-volume crude trunk lines demanding continuous monitoring and intermittent municipal water networks requiring reactive intervention models.
Service Type:
Customization intensity varies from routine standardized cleaning cycles to engineered rehabilitation solutions tailored to specific corrosion profiles and pressure ratings.
- Inspection:Inline smart pigging dominates high-pressure hydrocarbon corridors, with Saudi Aramco's Master Gas System mandating 18-month inspection intervals using magnetic flux leakage and ultrasonic testing tools. Nigerian operators under DPR mandates are retrofitting leak detection systems across Niger Delta trunk lines, accelerating contractor qualification demand.
- Rehabilitation:Composite sleeve repairs and cathodic protection upgrades extend operational life of 1970s-era carbon steel infrastructure without full line replacement. Libya's aging desert pipelines and Nigerian offshore trunk lines concentrate demand for engineered retrofit solutions addressing metal loss and coating degradation.
- Cleaning:Gel pig and brush pig programs remove wax, scale, and debris to restore flow efficiency in crude and multiphase lines. Standardized protocols apply across routine maintenance schedules.
- Repair:Emergency response capabilities span hot tapping, line stopping, and sectional replacement for integrity failures. ADNOC and Saudi Aramco maintain pre-qualified rapid-response contractor panels for critical trunk line incidents.
Leading the category by volume: Inspection. Growing fastest: Rehabilitation.
Technology:
Technology selection tracks the shift from manual intervention toward autonomous systems reducing personnel exposure in remote desert and offshore environments.
- Smart Pigs:Magnetic flux leakage and ultrasonic testing tools detect metal loss, deformation, and crack anomalies across buried and subsea lines. Saudi Aramco's Eastern Province network represents the densest deployment globally, with inspection cycles compressing from 36 to 18 months.
- Drones:Unmanned aerial surveillance is expanding fastest across UAE offshore corridors and Saudi desert routes, displacing manned helicopter patrols. ADNOC's subsea pipeline monitoring programs are separating aerial contracts from subsea inspection awards.
- Robots:Robotic crawlers access unpiggable lines and complex geometries where inline tools cannot operate. Deployment concentrates in refinery interconnects and terminal manifolds.
- Sensors:Distributed acoustic sensing and fiber-optic temperature monitoring enable real-time leak detection and third-party intrusion alerts. Integration with SCADA systems is advancing across Egyptian gas corridors.
Smart pigs anchor procurement spend. Drone deployment is climbing the fastest.
End User:
End-user segmentation reveals divergent procurement sophistication, with national oil companies imposing certification barriers that filter mid-tier providers.
- Oil & Gas Companies:Saudi Aramco, ADNOC, and Nigerian majors drive technology adoption, mandating API Q2 and ISO 9001 certification for upstream service awards. Internal standards exceed minimum regulatory requirements, concentrating procurement among qualified international and regional contractors.
- Water Utilities:Municipal and regional water transmission operators maintain lower pressure infrastructure with less frequent inspection regimes. Demand concentrates in Saudi Arabia's Riyadh and Jeddah distribution networks.
- Municipalities:Urban water and wastewater pipeline networks require reactive maintenance models with limited predictive capabilities. Procurement fragmentation characterizes this segment.
- Industrial Facilities:Refinery and petrochemical complex operators maintain captive maintenance capabilities for process piping, supplementing with external specialists for turnaround inspections.
Oil and gas operators command the largest contract values. Water utilities are gaining share fastest as Saudi Arabia expands desalination distribution infrastructure.
Application:
Application focus determines technology bundling, with leak detection and corrosion management increasingly unbundled into discrete specialized contracts.
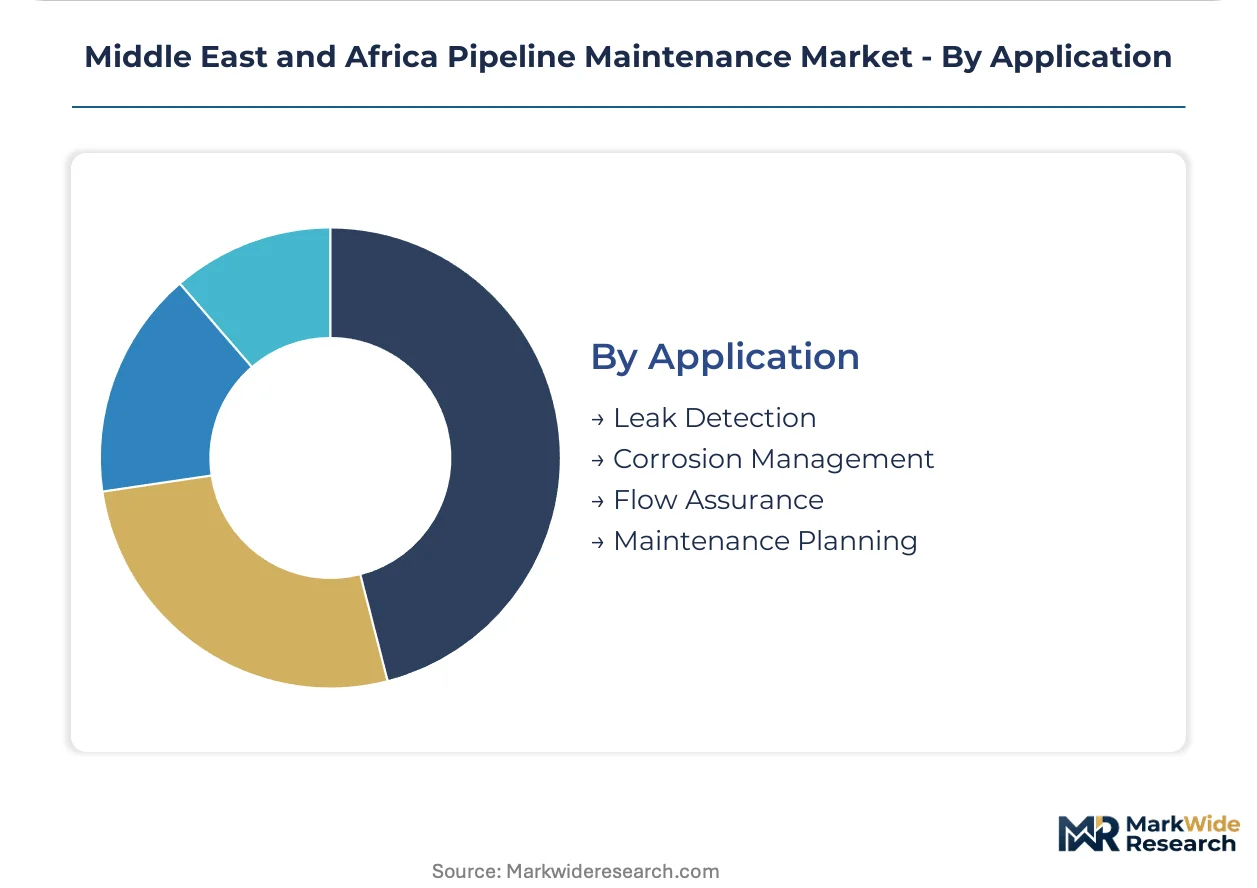
- Corrosion Management:Cathodic protection system design, monitoring, and retrofit dominates rehabilitation spend across Libya's aged carbon steel network and Nigerian coastal trunk lines. External coating assessment and internal corrosion inhibitor injection programs complete the scope.
- Leak Detection:DPR-mandated system upgrades across Nigeria are forcing inline inspection tool deployment and real-time monitoring integration. Acoustic sensors and computational pipeline monitoring are displacing legacy pressure-point analysis.
- Flow Assurance:Wax management, hydrate prevention, and slugging mitigation maintain throughput in multiphase and heavy crude lines. Chemical injection and thermal management programs support mechanical solutions.
- Maintenance Planning:Predictive analytics and risk-based inspection scheduling are shifting operators from time-based to condition-based intervention models, collapsing detection-to-repair timelines.
Corrosion management leads application spend. Leak detection is expanding most quickly amid regulatory enforcement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Middle East and Africa pipeline maintenance market reflects a stark production-to-consumption asymmetry: crude extraction concentrates in Saudi Arabia's Eastern Province and Nigeria's Niger Delta, while refining capacity and end-use demand fragment across North Africa and the Gulf Cooperation Council states. This geographic split shapes where inspection technology deploys versus where rehabilitation services concentrate.
Saudi Arabia
Saudi Aramco's Master Gas System and Ghawar field complex drive the densest smart pigging deployment globally, with inspection cycles compressing from 36 to 18 months. The Saudi Arabian Standards, Metrology and Quality Organization (SASO) mandates API Q2 and ISO 9001 certification for upstream contractors, filtering mid-tier providers from procurement panels. Eastern Province trunk lines concentrate demand for robotic crawler services and drone-based aerial surveillance across desert corridors.
United Arab Emirates
ADNOC's offshore pipeline networks in Abu Dhabi generate concentrated demand for unmanned aerial patrol systems displacing manned helicopter coverage. The UAE's petroleum regulator requires leak detection system upgrades across subsea export corridors, accelerating inline inspection tool procurement. Dubai and Abu Dhabi serve as procurement hubs where international contractors establish regional headquarters to access Gulf-wide service awards.
Nigeria
Niger Delta trunk lines suffering from decades of deferred maintenance now face Department of Petroleum Resources mandates modeled on US DOT PHMSA frameworks, forcing leak detection system retrofits. The country's national petroleum regulator requires inline inspection tool deployment across onshore and offshore networks. Lagos and Port Harcourt anchor contractor mobilization points for West African offshore maintenance campaigns.
Egypt
Egypt's petroleum ministry is embedding climate disclosure requirements into concession renewal terms across the Eastern Mediterranean gas corridor, reshaping contractor qualification criteria. The country's natural gas transmission network requires cathodic protection upgrades and composite sleeve repairs on aging carbon steel infrastructure. Cairo-based procurement offices coordinate maintenance programs spanning the Nile Delta and Red Sea offshore fields.
Libya
Libya's desert pipeline infrastructure, dating to the 1970s, requires extensive composite rehabilitation and impressed current cathodic protection systems to extend operational life. The National Oil Corporation maintains fragmented maintenance schedules amid political instability, creating sporadic demand spikes for rapid-response repair capabilities. Sirte Basin and Murzuq Basin production corridors concentrate the limited inspection activity that proceeds.
Middle East and Africa Pipeline Maintenance Market Competitive Landscape
The competitive structure tilts toward integrated service conglomerates with wellbore-to-terminal capabilities, though specialized inspection technology providers are carving discrete contract positions. Tier-one contractors leverage long-term framework agreements with national oil companies, while mid-tier regional fabricators compete on rapid-response mobilization and localized content requirements. Two strategic archetypes dominate: integrated oilfield service conglomerates bundling maintenance with upstream operations, and specialized pipeline technology vendors unbundling discrete inspection modalities. Competitive moves center on API Q2 certification achievement and drone surveillance capability acquisition.
Among integrated service providers, Halliburton Company and BP PLC exemplify the conglomerate archetype, leveraging joint venture structures and long-term framework agreements to anchor regional positions. Halliburton occupies a position within the premium-tier contractor segment through its integrated wellbore-to-terminal service architecture. BP PLC sits within the international oil company tier, maintaining regional maintenance footprints through partnership structures in Oman and Iraq. Rezayat Group represents the localized fabricator archetype, competing on rapid-response repair capabilities and Gulf Cooperation Council market proximity.
| Leading Market Players |
|---|
| Saudi Aramco |
| ExxonMobil Corporation |
| BP PLC |
| Halliburton Company |
| Rezayat Group |
| Arabian Pipes Company |
| OLEUM Process & Pipeline Services |
| Frontier Pipeline Services |
| STATS Group |
| Others |
Pricing and Supply Chain Analysis
Specialized inline inspection technicians concentrated in Houston and Aberdeen feed labor-cost differentials that widen pricing-tier spreads between API Q2-certified premium contractors and uncertified economy providers across Saudi Arabia and Nigeria.
Pricing Analysis
Margin tightening in the economy tier traces to Nigerian operators substituting uncertified local contractors for DPR-mandated leak detection upgrades. Three-tier pricing structure across premium, standard, and economy levels segments on API Q2 certification status and equipment import origin. Cost-down pressure on mid-tier providers accelerates because Saudi Aramco's 18-month inspection cycle compression demands capital-intensive smart pig fleets. Water utilities exhibit highest price sensitivity; national oil companies prioritize certification compliance over unit cost.
Supply Chain Analysis
Workforce availability for magnetic flux leakage tool fabrication concentrates in the United States, Germany, and Norway, constraining regional manufacturing scale-up. Supply chains draw from North American and European bases for specialized inline inspection tools, high-grade composite sleeve materials, and drone sensor payloads. Single-source vulnerability concentrates in magnetic flux leakage sensor arrays, where two German suppliers dominate global output. Distribution runs through Dubai and Abu Dhabi procurement hubs serving Gulf-wide maintenance campaigns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where contractors capturing in-house smart pig manufacturing secure cost advantages against import-dependent competitors.
For Market Incumbents: Anticipate certification inflation by pre-emptively acquiring API Q2 auditing capabilities before Saudi Aramco tightens contractor panels. Consolidate position through backward integration into composite sleeve fabrication, neutralizing raw material lead time volatility. Counter emerging drone surveillance specialists by bundling aerial patrol with subsea inspection contracts.
For New Entrants and Emerging Players: The 40-60 percent price-point gap between premium API Q2-certified incumbents and uncertified economy providers creates entry space for mid-tier specialists. Target Egypt's Eastern Mediterranean gas corridor where climate disclosure requirements filter legacy contractors. Penetrate through sensor-analytics convergence offerings that bypass capital-intensive smart pig fleet requirements.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized drone surveillance providers given ADNOC's unmanned aerial patrol expansion across subsea corridors. Long-term viability favors contractors with verified carbon accounting capabilities as Egypt and Saudi Arabia embed emissions reporting into concession terms. Monitor API Q2 certification backlog duration as inflection indicator for contractor scarcity premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| API Q2 Certification Investment | Saudi Aramco's internal standards exceed SAMR minimums, filtering mid-tier providers from upstream awards. |
| Drone Surveillance Capability Buildout | ADNOC's subsea pipeline monitoring programs separate aerial contracts from traditional inspection awards. |
| Composite Sleeve Manufacturing Integration | Libya's 1970s-era carbon steel infrastructure demands engineered retrofit solutions without full replacement. |
| Sensor-Analytics Platform Development | Predictive algorithms enable shift from scheduled maintenance to condition-based intervention models. |
| Climate Disclosure System Implementation | Egypt's petroleum ministry embeds emissions reporting into concession renewal terms across gas corridors. |
Research Methodology
Regulatory filings from Nigeria's Department of Petroleum Resources, Saudi Arabian Standards Organization directives, and ADNOC procurement disclosures formed the secondary backbone for demand quantification. Primary interviews with pipeline integrity managers, maintenance procurement officers at national oil companies, smart pig equipment manufacturers, and cathodic protection engineering specialists validated segment assumptions. Bottom-up project pipelines and top-down hydrocarbon throughput models were triangulated against contractor capacity disclosures.
Historical inspection cycle compression trends and regulatory mandate implementation timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, technology modality, end-user sophistication tier, and application focus. CAGRs were derived from regression analysis of inspection frequency intensification and rehabilitation backlog accumulation. Forecast inputs incorporated DPR compliance deadlines and Saudi Aramco Master Gas System expansion schedules.
Inputs from Nigerian regulatory filings and Saudi procurement panels were available through the study window; gaps in Libyan National Oil Corporation maintenance expenditure data introduce uncertainty bands around North African projections. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and equipment import license processing efficiency. Material deviation in API Q2 certification timeline acceleration or EU Green Deal carbon border adjustment implementation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Modular Gas Processing Plants Market
Oil & Gas
Oil Tank Rotating Stacker Market
Oil & Gas
Drill Collar Market
Oil & Gas
Colombia Oil and Gas Downstream Market
Oil & Gas
South-East Asia Oil and Gas Pipeline Market
Oil & Gas
Norway Oil and Gas Upstream Market
Oil & Gas
Oil & Gas Defoaming Separator Market
Oil & Gas
Gold Mining Market
Oil & Gas
China Oil and Gas Market
Oil & Gas
Subsea Manifolds Market
Oil & Gas
Well Testing Services Market
Oil & Gas
AI in Oil and Gas Market
Oil & Gas
Europe Oilfield Chemicals Market
Oil & Gas
Angola Oil and Gas Upstream Market
Oil & Gas
Indonesia Oil and Gas Midstream Market
Oil & Gas
Downhole Drilling Tools Market