
 Indonesia Coal Market | 2026-2036
Indonesia Coal Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Coal Market Outlook
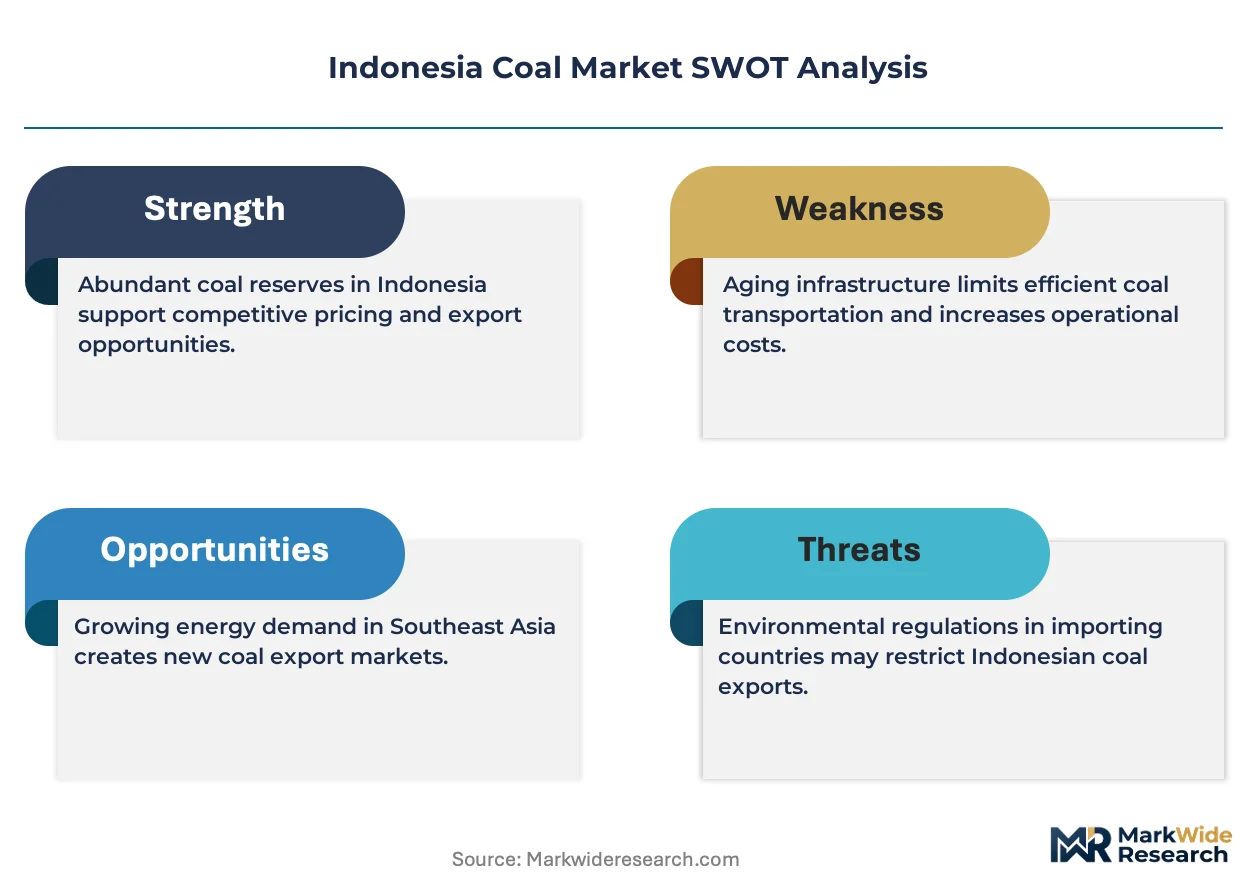
Mining engineer shortages across East Kalimantan is redrawing operational timelines and forcing automation investments. PT Bumi Resources Tbk leverages its sprawling open-pit complexes to sustain output despite labor constraints. PT Adaro Energy Indonesia Tbk anchors its position through ultra-low-pollution Envirocoal branding that commands premium pricing in selective Asian markets. PT Bayan Resources Tbk specializes in high-calorific export blends that dominate niche industrial contracts in Northeast Asia.
Indonesia coal encompasses sub-bituminous and bituminous sedimentary deposits with typical calorific values of 4,200–6,500 kcal/kg, extracted primarily through open-cut truck-and-shovel methods for power station feed and metallurgical blending. Steam coal shipments to power generation utilities constitute the largest volume pool, though margins compress against domestic price caps. Coking coal for steel manufacturing represents the fastest-expanding value segment as domestic blast furnace projects advance, while anthracite remains marginal due to limited recoverable reserves. Exporters face structurally thinner returns as the domestic market obligation progressively tightens available free-on-board volumes.
Indonesia's Ministry of Energy and Mineral Resources enforces the domestic market obligation under Ministerial Regulation No. 1395 K/30/MEM/2018, compelling producers to reserve defined percentages for local power and industry. The country's national environmental regulator, the Ministry of Environment and Forestry, tightens mine rehabilitation bonds and water discharge standards that elevate compliance costs for smaller operators. BIS-equivalent SNI certification requirements for coal quality testing shape contract enforceability in cross-border trade. Stakeholders must track regulatory enforcement intensity in Kalimantan against the pace of mine-mouth power commissioning to anticipate export volume availability.
Market Dynamics
The domestic market obligation policy enforced by Indonesia's Ministry of Energy and Mineral Resources is systematically redirecting export-grade coal toward mine-mouth power stations, tightening seaborne availability and compressing free-on-board margins across Kalimantan mining complexes.
Growth Catalysts
- Mine-mouth electrification:Java and Sumatra power generation utilities anchor expanding offtake volumes as the national electrification program advances rural grid connectivity.
- Domestic Market Obligation framework:Ministerial Regulation No. 1395 K/30/MEM/2018 compels producers to reserve defined percentages for local power and industry, securing captive demand.
- Blast furnace steel expansion:Domestic metallurgical coal consumption accelerates as Indonesian steelmakers commission new coking coal-dependent capacity.
Market Restraints
- Export volume caps:Progressive DMO tightening structurally limits free-on-board shipments available for seaborne trade.
- Mine rehabilitation bonds:The Ministry of Environment and Forestry elevates upfront capital requirements for smaller Kalimantan operators.
- Natural gas substitution:LNG-fired power projects in Java threaten baseload coal burn at the margin.
Strategic Opportunities
- Envirocoal premium positioning:Ultra-low-pollution thermal coal variants command pricing power in selective Northeast Asian utility tenders.
- East Kalimantan automation:Mining engineer shortages accelerate autonomous truck-and-shovel deployment, resetting cost curves.
- High-calorific industrial blends:Specialized export coals penetrate niche cement and chemical feedstock contracts in Japan and South Korea.
Industry Challenges
- Water discharge compliance:Tightened effluent standards from the Ministry of Environment and Forestry extend permitting timelines for new pit development.
- SNI certification complexity:BIS-equivalent quality testing requirements create contract enforceability friction in cross-border trade documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Coal Market |
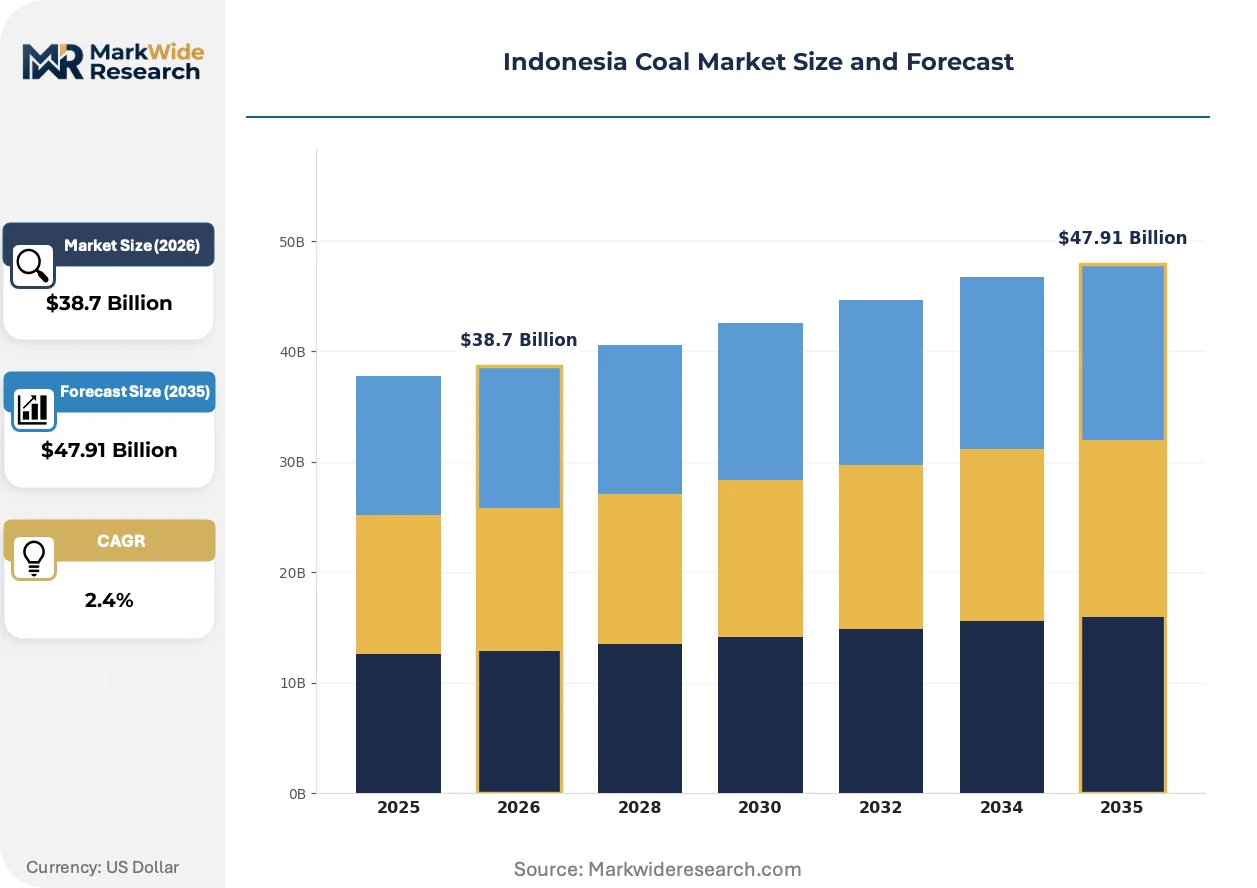
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $47.91 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steam Coal, Coking Coal, Anthracite, Bituminous Application: Power Generation, Cement Production, Steel Manufacturing, Industrial Heating End User: Utilities, Manufacturing, Construction, Exporters Distribution Channel: Direct Sales, Distributors, Online Platforms, Exports |
| Companies Covered | PT Bumi Resources Tbk, PT Adaro Energy Indonesia Tbk, PT Bayan Resources Tbk, PT Bukit Asam Tbk, PT Indo Tambangraya Megah Tbk, Kaltim Prima Coal, Berau Coal Energy, Indika Energy, Harum Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Coal Market Strategic Shifts
Automation systems and environmental compliance technologies are actively reshaping extraction economics across Indonesian coal basins, while regulatory enforcement intensity and buyer procurement sophistication accelerate operational differentiation.
Autonomous haulage systems are supplanting conventional truck-and-shovel operations at East Kalimantan open-pit complexes. PT Bumi Resources Tbk and tier-one operators deploy driverless fleets to offset acute mining engineer shortages. This technology compression is narrowing the labor cost advantage that historically protected smaller contractors.
Indonesia's Ministry of Energy and Mineral Resources is tightening DMO enforcement through digital production tracking and export license conditioning. Smaller producers face disproportionate compliance burden as bond requirements and verification protocols intensify. Export-oriented miners are responding by deepening mine-mouth power joint ventures to satisfy domestic obligation while preserving foreign currency revenue streams.
Japanese and South Korean utilities are unbundling long-term offtake contracts into shorter-duration tenders with stringent quality variability penalties. Spot-indexed procurement is displacing annual volume commitments at major Northeast Asian power generators. This behavioral shift concentrates price risk with Indonesian exporters while rewarding producers with certified SNI testing infrastructure and flexible blending capabilities.
Indonesia Coal Market Segmentation
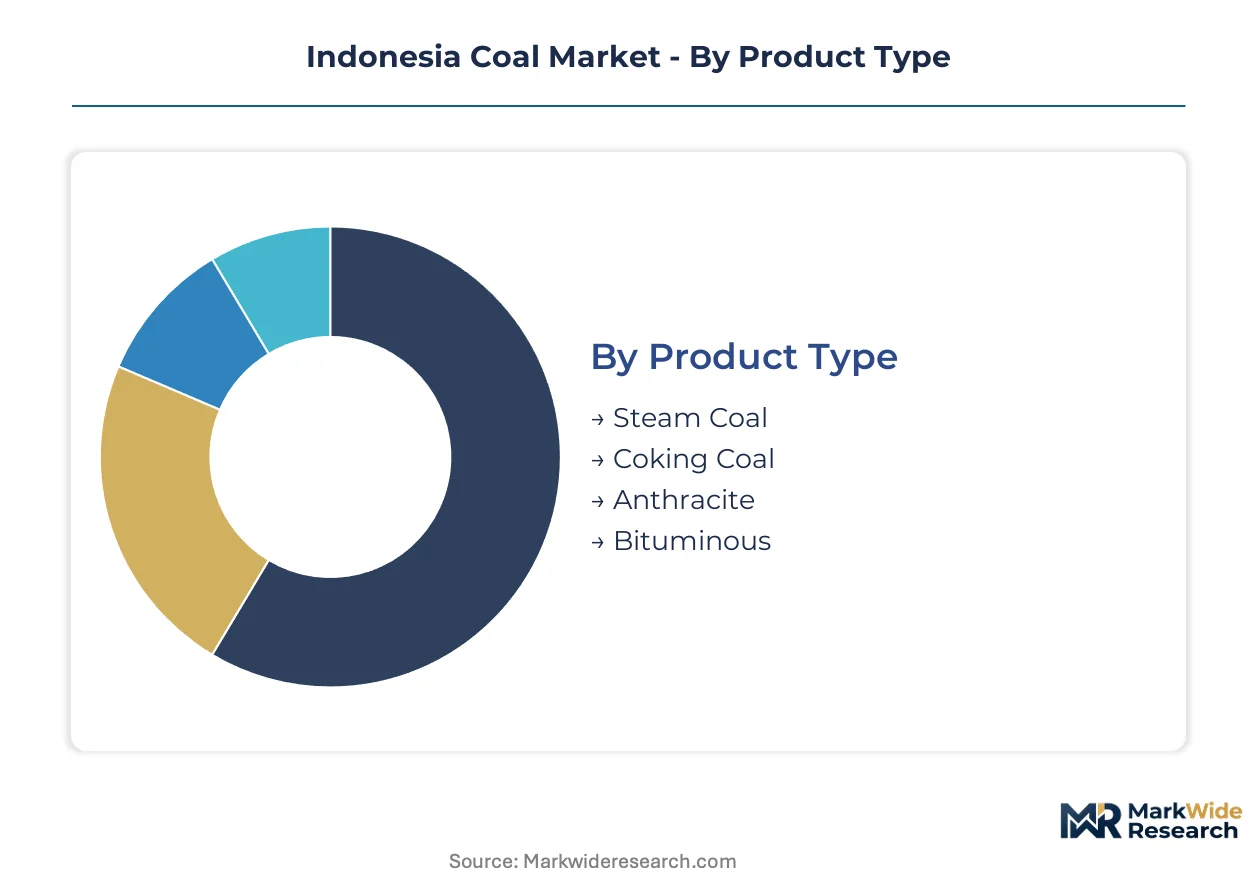
Segmentation in Indonesian coal reveals how regulatory obligation and calorific grade reshape profit pools. Producers navigate divergent margin structures across thermal and metallurgical grades while domestic market obligation rules redirect volume flows.
Product Type:
Margin pools concentrate in metallurgical grades where blast furnace expansion in Java creates captive demand, while thermal coal faces price compression from domestic market obligation caps.
- Steam Coal:Sub-bituminous deposits with calorific values of 4,200–5,500 kcal/kg dominate East Kalimantan extraction. Mine-mouth power stations in Java and Sumatra anchor offtake volumes under domestic market obligation enforcement, compressing free-on-board margins for export-oriented producers.
- Coking Coal:Bituminous metallurgical grades command premium positioning as domestic steelmakers commission new blast furnace capacity. The Ministry of Energy and Mineral Resources' obligation framework secures captive supply chains for emerging industrial clusters.
- Anthracite:Limited recoverable reserves constrain production scale across Indonesian basins.
- Bituminous:Intermediate calorific grades serve industrial blending requirements in cement and chemical feedstock applications.
Steam coal holds installed capacity. Coking coal is rotating up the share rankings.
Application:
Cost tier differentiation separates baseload power consumption from premium industrial feedstock markets.
- Power Generation:State-owned Perusahaan Listrik Negara anchors contract volumes through mine-mouth purchasing arrangements. Rural electrification programs in eastern Indonesia extend transmission infrastructure, tightening domestic market obligation compliance requirements for Kalimantan producers.
- Steel Manufacturing:Emerging blast furnace projects in Cilegon and Kalimantan drive metallurgical coal consumption acceleration. Japanese and South Korean steelmakers source high-calorific Indonesian blends for coke oven charging.
- Cement Production:Clinker kilns in Java consume medium-grade thermal coal for process heat.
- Industrial Heating:Chemical and ceramics manufacturers procure standardized calorific grades through direct contracting.
Power generation commands volume dominance. Steel manufacturing is climbing the fastest trajectory.
End User:
Customer type segmentation reflects the bifurcation between regulated domestic obligation and export market pricing power.
- Utilities:Perusahaan Listrik Negara and regional power developers secure priority supply under domestic market obligation enforcement. Mine-mouth joint ventures with PT Bumi Resources Tbk and PT Adaro Energy Indonesia Tbk lock in long-term feedstock security.
- Exporters:Northeast Asian utilities and Indian power generators compete for shrinking free-on-board volumes. Spot-indexed procurement patterns concentrate price risk with Indonesian sellers.
- Manufacturing:Cement and chemical producers negotiate direct supply contracts bypassing distributor markups.
- Construction:Small-scale industrial users access coal through regional distributor networks.
Utilities hold contracted volume priority. Exporters are rotating up the share rankings.
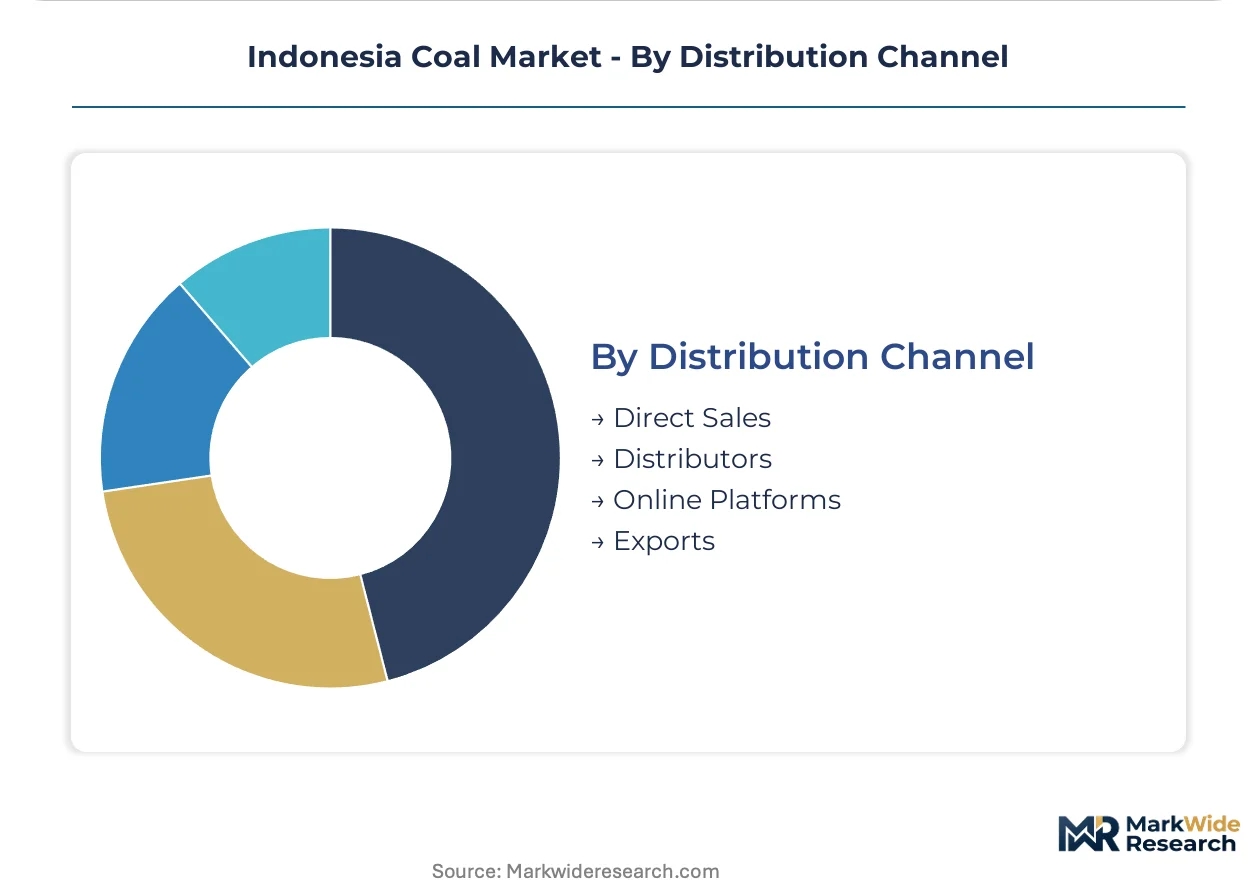
Distribution Channel:
Supply concentration shapes channel economics, with direct sales capturing margin from obligation-compliant producers.
- Direct Sales:Mine-mouth power stations and major industrial consumers negotiate long-term offtake agreements. PT Bayan Resources Tbk and tier-one operators bypass intermediaries to preserve margin on high-calorific export blends.
- Exports:Seaborne shipments through Balikpapan and Tarakan terminals face progressive volume tightening from domestic market obligation enforcement. Japanese and South Korean utility tenders demand certified SNI quality documentation.
- Distributors:Regional aggregators serve construction and small manufacturing demand in Sumatra and Sulawesi.
- Online Platforms:Emerging digital procurement channels facilitate spot market matching for standardized thermal grades.
Direct sales hold infrastructure lock-in. Exports is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's Ministry of Energy and Mineral Resources anchors production governance through domestic market obligation enforcement. The country's coal basins concentrate in Kalimantan and Sumatra, where mine-mouth power stations and export terminals reshape regional flow patterns.
East Kalimantan
Mine-mouth power stations at Sangatta and Bengalon anchor captive offtake volumes. The Ministry of Energy and Mineral Resources' digital production tracking tightens export license conditioning for producers operating here. PT Bumi Resources Tbk leverages sprawling open-pit complexes at Sangatta to sustain output despite acute mining engineer shortages.
South Sumatra
State-owned Perusahaan Listrik Negara contracts anchor thermal coal demand for Java grid interconnection. Domestic market obligation enforcement redirects export-grade deposits toward local power plants at Tanjung Enim. PT Bukit Asam Tbk operates integrated mining-rail-power infrastructure across the Bukit Asam coalfield.
Central Kalimantan
High-calorific bituminous deposits serve metallurgical blending requirements for Japanese and South Korean steelmakers. The Ministry of Environment and Forestry's tightened mine rehabilitation bonds elevate upfront capital requirements for new pit development. PT Adaro Energy Indonesia Tbk positions ultra-low-pollution Envirocoal variants from Central Kalimantan operations.
North Kalimantan
Seaborne export terminals at Tarakan and Malinau face progressive volume tightening from domestic market obligation enforcement. BIS-equivalent SNI certification requirements shape contract enforceability for shipments bound for Northeast Asian utilities. PT Bayan Resources Tbk specializes in high-calorific export blends from Tabang and other North Kalimantan concessions.
South Kalimantan
Cement producers in Java consume medium-grade thermal coal from Martapura and Binuang deposits for clinker kiln process heat. The Ministry of Environment and Forestry's water discharge standards extend permitting timelines for new pit development. Smaller operators face disproportionate compliance burden as verification protocols intensify.
Indonesia Coal Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across Indonesian coal basins. Tier-one operators with integrated mine-mouth power joint ventures capture margin from domestic market obligation compliance, while specialized exporters concentrate on high-calorific niche contracts. Strategic differentiation separates automation-enabled scale players, ultra-low-emission brand specialists, and metallurgical blend exporters. Competitive moves concentrate on mine-mouth power joint ventures and autonomous haulage deployment.
Among Indonesia-based producers, PT Bumi Resources Tbk exemplifies the scale-driven archetype through sprawling open-pit complexes, while PT Adaro Energy Indonesia Tbk occupies a position within the environmental differentiation tier through ultra-low-pollution coal branding. PT Bayan Resources Tbk represents the high-calorific export specialization archetype.
| Leading Market Players |
|---|
| PT Bumi Resources Tbk |
| PT Adaro Energy Indonesia Tbk |
| PT Bayan Resources Tbk |
| PT Bukit Asam Tbk |
| PT Indo Tambangraya Megah Tbk |
| Kaltim Prima Coal |
| Berau Coal Energy |
| Indika Energy |
| Harum Energy |
| Others |
Value Chain & Pricing Dynamics
SNI certification requirements from Indonesia's Ministry of Energy and Mineral Resources gate both supply qualification into Northeast Asian utility tenders and price differentiation between certified and uncertified export blends. This dual-gating mechanism concentrates pricing power with tier-one operators possessing in-house testing infrastructure while compressing margins for smaller Kalimantan producers facing third-party verification costs.
Pricing Analysis
East Kalimantan mine-mouth contracts trade at structural discounts to North Kalimantan free-on-board export quotes, reflecting domestic market obligation price caps against seaborne spot-indexed procurement. Pricing stratifies across premium Envirocoal variants, standard 4,200–5,500 kcal/kg thermal grades, and economy mine-mouth supply bound for Perusahaan Listrik Negara. Margins are tightening due to progressive DMO volume tightening that redirects export-grade coal toward captive power stations. State-owned utilities exhibit lowest price sensitivity through long-term offtake security, while Northeast Asian spot buyers demonstrate acute responsiveness to calorific variability penalties.
Supply Chain Analysis
Balikpapan and Tarakan terminal congestion underwrites export scheduling premiums for producers with dedicated berth access. Supply concentrates in East Kalimantan and South Sumatra, with bituminous metallurgical grades drawing from Central Kalimantan deposits. Diesel fuel, explosives, and tire consumables constitute critical input dependencies for open-pit truck-and-shovel operations. Single-source vulnerability runs through concentrated haul road and barge loading infrastructure serving Sangatta and Bengalon complexes. Distribution runs through direct mine-mouth sales to Perusahaan Listrik Negara, seaborne exports via Kalimantan terminals, and regional distributor networks for construction and small manufacturing demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia coal sits in early-cycle expansion as domestic blast furnace steel capacity commissions and mine-mouth electrification extends grid connectivity across eastern provinces. Metallurgical coal penetration accelerates as the fastest-climbing value segment.
For Market Incumbents: Fortify mine-mouth power joint ventures to satisfy domestic market obligation while preserving foreign currency revenue streams from residual export volumes. Deepen autonomous haulage deployment across East Kalimantan complexes to offset mining engineer shortages and reset unit cost curves against labor-inflated contractors. Prioritize SNI certification infrastructure investment to maintain contract enforceability in Japanese and South Korean utility tenders. For New Entrants and Emerging Players: High-calorific industrial blend specialization for cement and chemical feedstock contracts in Japan and South Korea represents the most penetrable white-space, as tier-one operators concentrate on utility-scale thermal offtake. Central Kalimantan metallurgical deposits offer lower regulatory enforcement intensity relative to established East Kalimantan basins. Pursue direct contracting relationships with clinker kiln operators and coke oven charge buyers bypassing aggregator markups. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automation-enabled open-pit complexes as autonomous truck-and-shovel deployment resets competitive cost structures. Long-term viability over a 5-10 year window favors vertically integrated mine-mouth power operators with locked-in domestic obligation compliance. Target acquisition archetypes include tier-two Kalimantan producers with rehabilitation bond shortfalls facing forced exit. Monitor DMO enforcement intensity through digital production tracking rollouts as the primary inflection signal for export volume availability.| Strategic Initiative | Industry Significance |
|---|---|
| Mine-Mouth Power Joint Venture | Secures captive offtake under DMO enforcement while preserving foreign currency export revenue streams. |
| Autonomous Haulage Deployment | PT Bumi Resources Tbk and tier-one operators offset mining engineer shortages through driverless fleet adoption. |
| Envirocoal Premium Positioning | Ultra-low-pollution variants command pricing power in selective Northeast Asian utility tenders. |
| High-Calorific Export Specialization | PT Bayan Resources Tbk penetrates niche cement and chemical feedstock contracts in Japan and South Korea. |
| SNI Certification Infrastructure | BIS-equivalent quality testing capabilities shape contract enforceability in cross-border trade documentation. |
Study Parameters
A spread of perspectives from mine operations managers, utility procurement officers at Perusahaan Listrik Negara, EPC contractors developing mine-mouth stations, and coal trading desks at Northeast Asian utilities converged on the working assumptions. Secondary validation drew from Ministry of Energy and Mineral Resources production disclosures, customs export data, IEA coal market reports, and SEC filings from listed Indonesian producers. Bottom-up volume modeling triangulated against top-down sectoral demand projections.
Segmentation dimensions modeled span calorific grade tier, application end-use, customer type, and distribution channel across the projection horizon. CAGRs were derived from production capacity trajectories, electrification program commissioning schedules, and steel capacity expansion timelines. Industry-specific forecast inputs incorporated DMO enforcement intensity scenarios and autonomous haulage adoption curves.
Underlying assumptions cover regulatory enforcement continuity, mine-mouth power project completion rates, and Northeast Asian import demand stability, with deviation risk concentrated in LNG substitution acceleration and rehabilitation bond policy tightening. Practitioners should keep alternative scenarios live as Ministry of Environment and Forestry water discharge standards and digital production tracking enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
South-East Asia Oil and Gas Pipeline Market
Oil & Gas
Mexico Oil and Gas Downstream Market
Oil & Gas
Coal Seam Gas Market
Oil & Gas
South America Deep Water and Ultra Deep Water Exploration and Production (Eandp) Market
Oil & Gas
Chemical Enhanced Oil Recovery (EOR) Market
Oil & Gas
Big Data in Oil and Gas Exploration and Production Market
Oil & Gas
North America Artificial Lift Systems Market
Oil & Gas
Oil and Gas Swell Packers Market
Oil & Gas
India Oil and Gas Market
Oil & Gas
South America Intelligent Pigging Market
Oil & Gas
Southeast Asia Oil and Gas Upstream Market
Oil & Gas
Oil and Gas Gasket Market
Oil & Gas
Oil and Gas Processing Seals Market
Oil & Gas
Oilwell Completion Tools Market
Oil & Gas
Oilfield Air Drilling Market
Oil & Gas
Middle-East Oil Country Tubular Goods (OCTG) Market