
 Low-Grade Glioma Therapeutics Market | 2026-2036
Low-Grade Glioma Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Grade Glioma Therapeutics Market Foresight
Academic medical center neuro-oncology departments is consolidating referral pathways for molecularly characterized low-grade gliomas, shifting patient volume toward institutions with integrated pathology and clinical trial infrastructure. Hoffmann-La Roche Ltd. leverages its companion diagnostic ecosystem to anchor precision oncology positioning in this indication. Servier sustains European market presence through its established neuro-oncology portfolio and regulatory engagement with EMA. Novartis competes via broad oncology infrastructure and pediatric trial networks across North American and European sites.
Low-grade glioma therapeutics encompass pharmacologic and biologic interventions targeting WHO grade I–II diffuse gliomas, including IDH-mutant astrocytomas and oligodendrogliomas, with therapeutic mechanisms spanning cytotoxic, targeted, and emerging immunomodulatory pathways designed to delay malignant transformation and preserve neurological function. Targeted therapy segments lead value generation as IDH inhibitors and MAPK pathway modulators command premium positioning against conventional cytotoxic alternatives. Oral delivery modes attract development investment due to patient compliance advantages in chronic pediatric and young-adult populations, while convection-enhanced delivery remains investigational with concentrated academic research activity. The regulatory status landscape stratifies commercially, with FDA-approved therapies occupying established reimbursement channels and investigational agents capturing venture funding toward registrational trials.
FDA pediatric oncology priority review vouchers and EMA's Paediatric Investigation Plans shape clinical trial investment and development timelines for low-grade glioma drug candidates. The EU AI Act and FDA guidance on real-world evidence introduce compliance complexity for digital biomarker integration and post-approval monitoring systems. Stakeholders must monitor regulatory convergence on molecular diagnostic requirements and adaptive trial designs to anticipate competitive access conditions.
Market Dynamics
Molecular diagnostic integration is restructuring competitive access in low-grade glioma therapeutics, as academic medical centers consolidate referrals around institutions possessing integrated pathology and clinical trial infrastructure.
Growth Catalysts
- FDA pediatric priority review vouchers:These incentives accelerate development timelines for low-grade glioma drug candidates by compressing regulatory review periods and attracting venture investment toward registrational trials.
- Convection-enhanced delivery research:Academic neurosurgery departments are advancing investigational delivery methods that bypass the blood-brain barrier, opening new therapeutic modalities for diffuse gliomas.
- IDH mutation testing penetration:Pathology laboratories are expanding molecular characterization capacity, creating patient stratification that enables precision oncology enrollment and targeted therapy adoption.
Market Restraints
- Clinical trial recruitment scarcity:The rare incidence of pediatric low-grade gliomas limits patient availability across competing investigational protocols, elongating enrollment timelines.
- Reimbursement uncertainty for companion diagnostics:Payers exhibit inconsistent coverage determination for molecular profiling tests, creating friction in precision medicine adoption pathways.
- Biomarker validation costs:The capital intensity of prospective clinical validation for IDH and MAPK pathway markers constrains smaller diagnostic developers.
Strategic Opportunities
- EMA Paediatric Investigation Plans:These regulatory frameworks create structured development pathways that reward early pediatric trial commitment with market exclusivity extensions.
- Real-world evidence integration:The FDA's evolving guidance on digital biomarkers enables post-approval monitoring systems that can support label expansion without prospective trials.
- Japan's centralized referral networks:METI-supported rare disease hubs concentrate patient volumes, creating efficient trial site activation for sponsors with established PMDA relationships.
Industry Challenges
- Neuro-oncology subspecialist scarcity:The limited pipeline of fellowship-trained physicians constrains site expansion for molecularly guided treatment protocols.
- Adaptive trial design complexity:Statistical and operational expertise for master protocol implementation remains concentrated at select academic institutions, limiting sponsor options.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Grade Glioma Therapeutics Market |
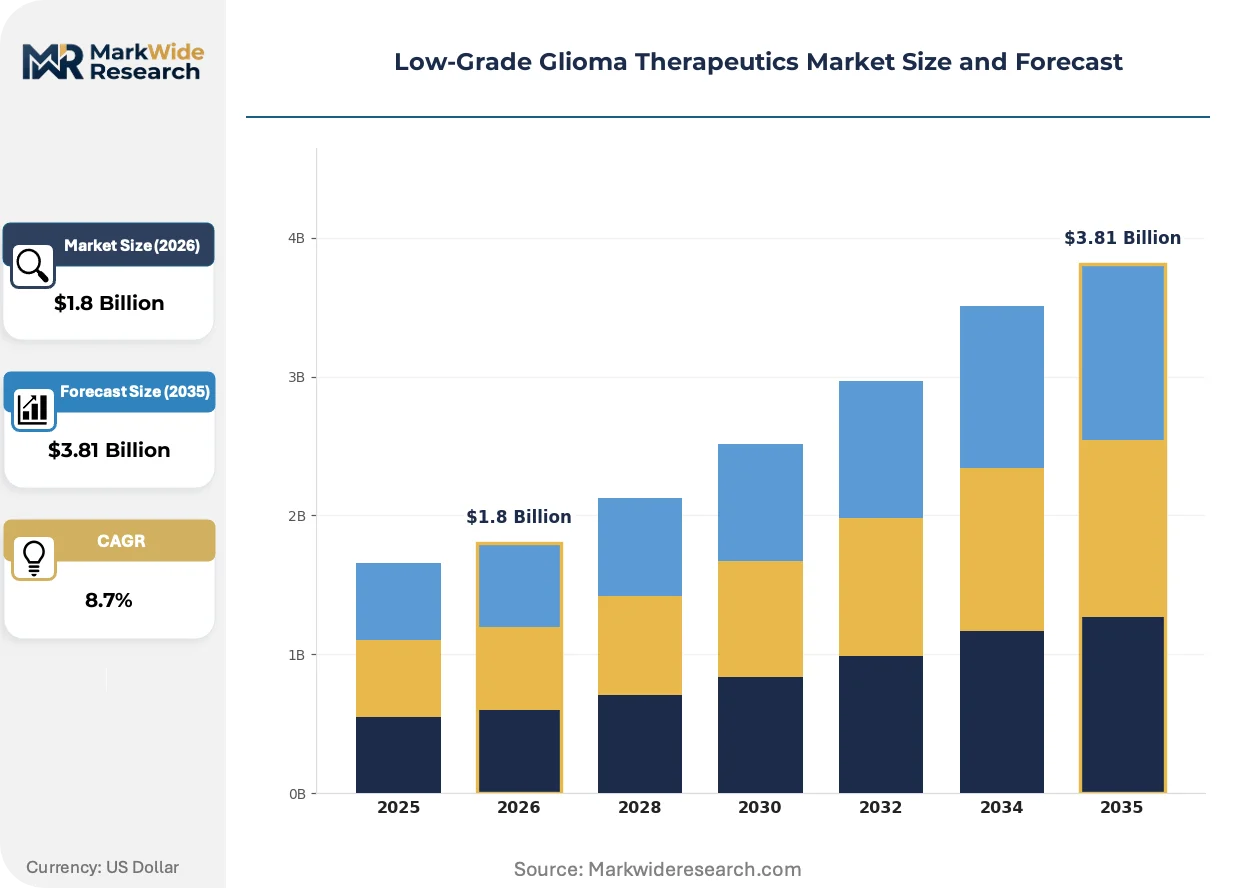
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Surgery, Radiation Therapy, Chemotherapy, Targeted Therapy Delivery Mode: Intravenous, Oral, Intra-arterial, Convection-Enhanced End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Research Institutions Regulatory Status: FDA Approved, Clinical Trial, Investigational, Off-Label |
| Companies Covered | Day One Biopharmaceuticals, Servier, Hoffmann-La Roche Ltd., Novartis, AnHeart Therapeutics, BeiGene, SpringWorks Therapeutics, Incyte Corporation, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Grade Glioma Therapeutics Market Shifts & Advancements
Next-generation sequencing and artificial intelligence are converging to transform how diffuse gliomas are molecularly characterized and treated, compressing the timeline from biopsy to targeted therapy selection.
Multi-omics profiling platforms are rewriting treatment planning in academic neuro-oncology departments. These integrated systems combine genomic, transcriptomic, and epigenomic data to predict therapeutic response. Major pediatric cancer centers are adopting these platforms within eighteen-month implementation cycles. The technology is rewriting competitive positioning by enabling sponsors to pre-screen patients for biomarker-driven trials before referral.
The EU AI Act's risk classification framework for medical decision-support software is reshaping development investment in Europe. Algorithmic tools that assist radiographic monitoring or molecular interpretation now face conformity assessment requirements. Developers targeting the German and French markets are restructuring quality management systems to satisfy notified body expectations.
Hospital procurement for neuro-oncology therapeutics is consolidating around integrated supply agreements that bundle molecular diagnostics with drug access. Academic medical centers in the United States are replacing fragmented purchasing with sole-source arrangements covering pathology, pharmacy, and clinical trial infrastructure. This consolidation is most visible at National Cancer Institute-designated centers seeking operational efficiency.
Low-Grade Glioma Therapeutics Market Segmentation
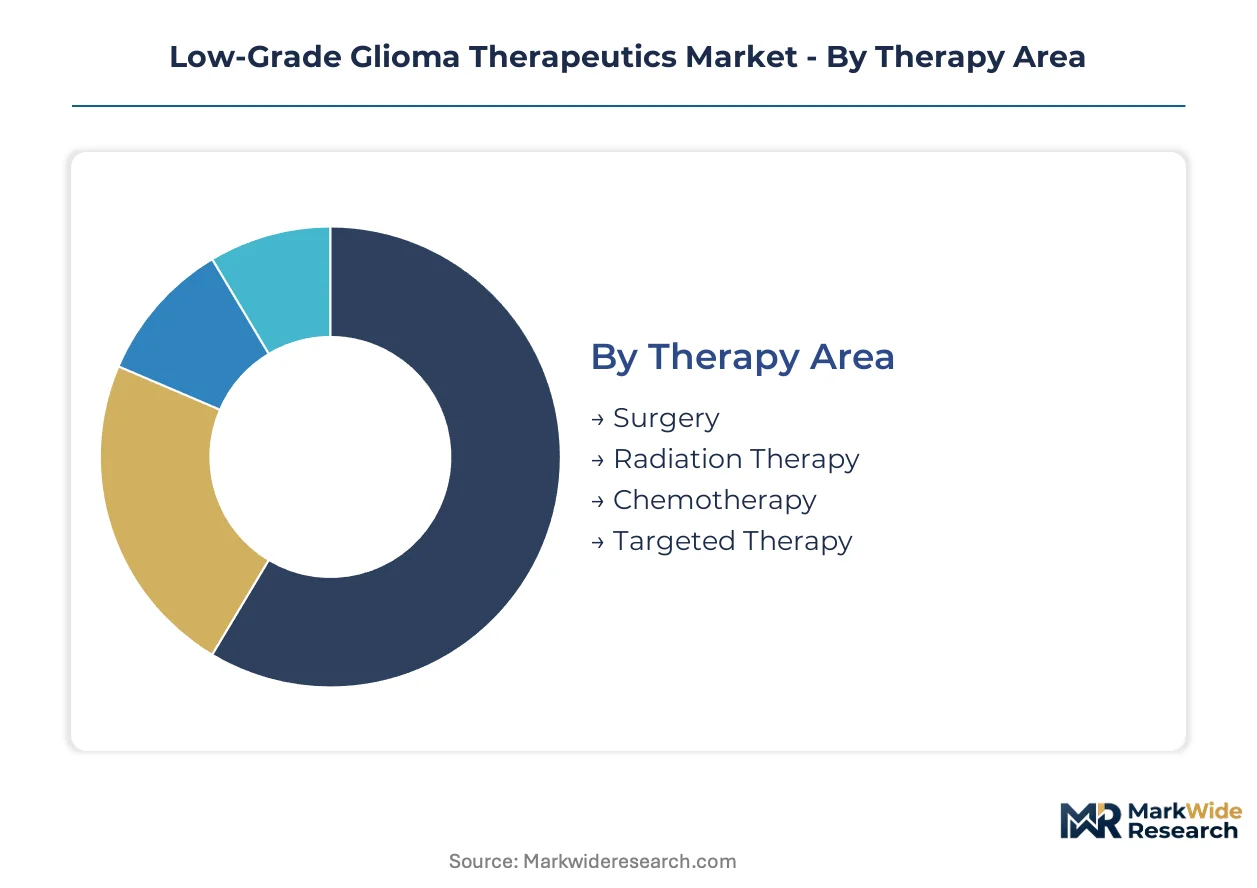
Segmentation in low-grade glioma therapeutics reveals how treatment decisions cascade from molecular diagnosis through site-of-care selection. Each dimension captures distinct procurement logic, reimbursement pathways, and patient access constraints that shape commercial strategy.
Therapy Area:
Treatment selection pivots on IDH mutation status and patient age, with molecular profiling now preceding modality decisions at academic centers.
- Surgery:Maximal safe resection remains first-line for accessible tumors, with intraoperative MRI and fluorescence guidance concentrating at NCI-designated centers in the United States. Residual tumor volume directly determines adjuvant therapy intensity.
- Targeted Therapy:IDH inhibitors and MAPK pathway modulators command premium formulary positioning against cytotoxic alternatives, with oral dosing enabling chronic administration in pediatric populations. Academic medical centers with integrated pathology infrastructure capture prescriber concentration.
- Radiation Therapy:Proton beam facilities in Boston and Philadelphia attract referral volume for pediatric cases seeking reduced neurocognitive sequelae.
- Chemotherapy:Temozolomide and vincristine-based protocols persist in resource-constrained settings and for molecularly uncharacterized cases.
Targeted therapy leads on scale; surgery leads on momentum as molecular guidance expands resectability criteria.
Delivery Mode:
Route selection balances blood-brain barrier penetration, treatment duration, and site-of-care economics.
- Oral:Patient compliance advantages in chronic pediatric and young-adult populations drive development investment, with IDH inhibitors and MEK inhibitors formulated for outpatient administration. Home dispensing reduces hospital day utilization.
- Intravenous:Cytotoxic agents and biologics requiring therapeutic drug monitoring concentrate infusion capacity at academic medical centers with neuro-oncology pharmacy specialization.
- Convection-Enhanced:Investigational delivery bypassing the blood-brain barrier remains confined to NIH-funded trials and select academic neurosurgery departments.
- Intra-arterial:Superselective delivery for recurrent tumors concentrates at centers with interventional neuroradiology subspecialization.
Intravenous delivery leads on scale; oral formulations gain share fastest as precision oncology shifts toward chronic management.
End User:
Care site selection follows molecular diagnostic capability and clinical trial access, with referral networks consolidating around integrated centers.
- Hospitals:Academic medical centers with embedded pathology and phase I-II infrastructure capture the majority of molecularly characterized cases. Integrated supply agreements bundle diagnostics with therapeutic access.
- Research Institutions:St. Jude Children's Research Hospital and Dana-Farber Cancer Institute anchor pediatric neuro-oncology trial networks, concentrating biobanking and longitudinal outcome data.
- Specialty Clinics:Community neuro-oncology practices handle stable disease surveillance and treatment-naive cases without complex molecular profiles.
- Ambulatory Surgical Centers:Limited to stereotactic biopsy and shunt procedures; therapeutic intervention remains hospital-based.
Hospitals lead on scale; research institutions lead on momentum as trial enrollment becomes treatment standard.
Regulatory Status:
Reimbursement certainty and prescriber confidence stratify sharply across development stages.
- FDA Approved:Established therapies occupy preferential formulary tiers with prior authorization pathways streamlined at major payers. IDH inhibitors carry companion diagnostic requirements.
- Clinical Trial:Pediatric priority review vouchers accelerate sponsor investment, with academic centers competing for limited patient volume across competing master protocols.
- Investigational:Single-center INDs and expanded access programs concentrate at institutions with established FDA relationships.
- Off-Label:Bevacizumab and other agents persist in progressive disease despite limited prospective evidence, with coverage determinations varying by payer.
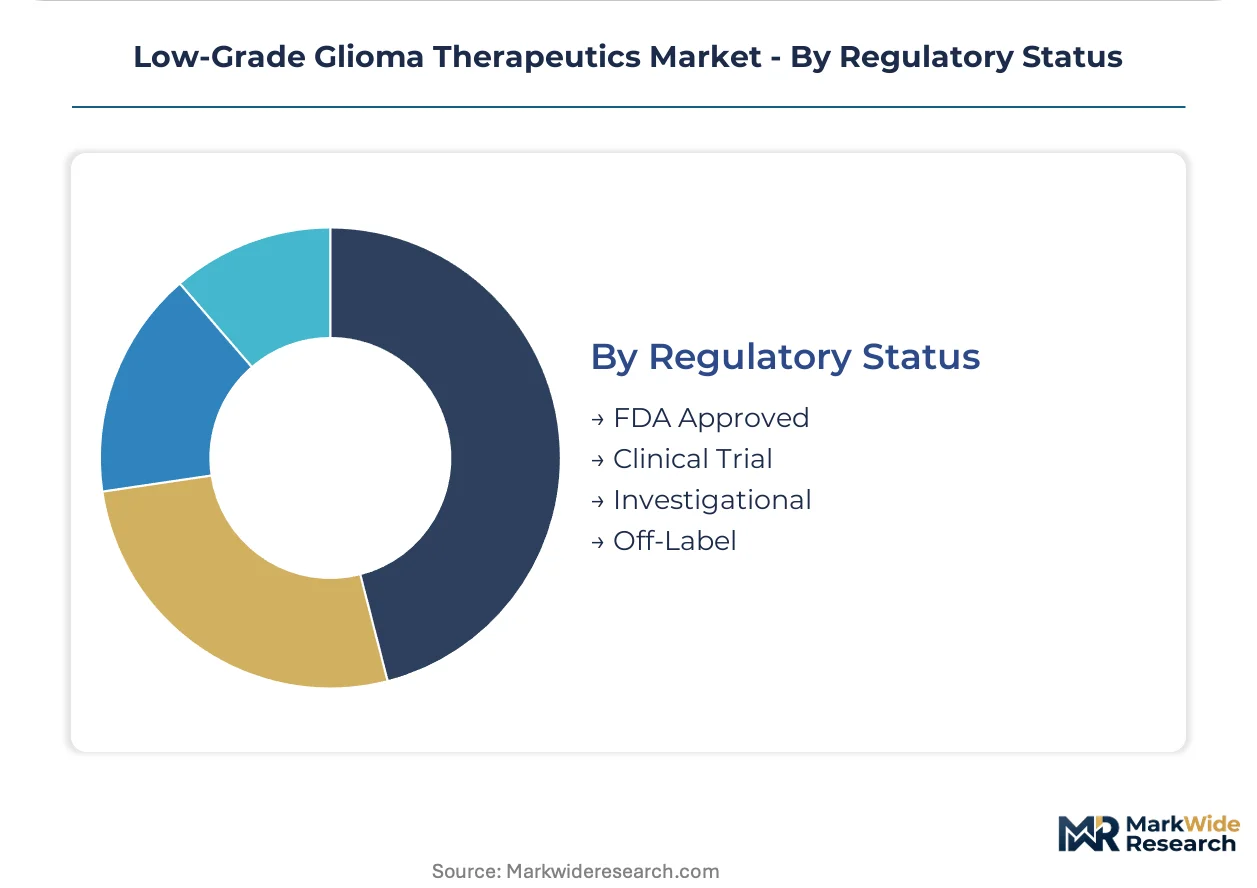
FDA approved therapies lead on scale; clinical trial access leads on momentum as regulatory incentives reshape development priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Philadelphia corridor anchors neuro-oncology infrastructure concentration for low-grade glioma therapeutics, with proton beam facilities and integrated academic medical centers driving referral consolidation. Molecular diagnostic capability and pediatric trial access stratify patient volume across national healthcare systems.
United States
Academic medical centers in Boston, Philadelphia, and Houston concentrate proton beam capacity and phase I-II trial infrastructure for pediatric low-grade gliomas. The FDA pediatric priority review voucher program accelerates sponsor investment toward registrational trials. St. Jude Children's Research Hospital and Dana-Farber Cancer Institute anchor longitudinal outcome databases that shape biomarker validation standards.
Germany
Heidelberg and Berlin university hospitals integrate molecular pathology with neuro-oncology departments, creating efficient referral pathways for IDH-mutant glioma characterization. EMA Paediatric Investigation Plans structure development timelines that reward early pediatric trial commitment. The country's centralized rare disease networks concentrate patient volumes at NCI-designated equivalent centers.
Japan
Tokyo and Osaka metropolitan areas host METI-supported rare disease hubs that streamline patient identification for molecularly guided protocols. PMDA relationships with established sponsors accelerate trial site activation for pediatric brain tumor indications. National health insurance coverage for companion diagnostics reduces friction in precision medicine adoption.
United Kingdom
London and Manchester academic medical centers compete for European trial enrollment through integrated pathology and biobanking infrastructure. NHS England's specialized commissioning frameworks concentrate low-grade glioma care at designated neuro-oncology centers. The country's early access to medicines scheme creates regulatory pathways for investigational IDH inhibitors.
Switzerland
Basel and Zurich anchor pharmaceutical R&D concentration with established neuro-oncology trial networks. Swissmedic's alignment with EMA procedures enables parallel regulatory submissions for pediatric indications. The country's precision medicine initiatives support molecular diagnostic integration at university hospital networks.
Low-Grade Glioma Therapeutics Market Competitive Landscape
Strategic partnerships dominate the current landscape as developers seek access to academic trial infrastructure and companion diagnostic ecosystems. The market structure concentrates around three tiers: integrated pharmaceutical conglomerates with broad oncology portfolios, mid-cap precision oncology specialists, and emerging biotechs with single-asset strategies. Two archetypes define competitive positioning: those anchoring precision medicine through diagnostic-therapeutic bundling, and those competing via pediatric trial network density. M&A activity and technology licensing agreements represent the dominant competitive moves as sponsors secure molecular platform access.
Within the integrated pharmaceutical tier, Hoffmann-La Roche Ltd. and Novartis occupy positions defined by companion diagnostic infrastructure and pediatric trial network reach. Servier exemplifies the European mid-cap archetype with sustained neuro-oncology portfolio presence and EMA regulatory engagement. Day One Biopharmaceuticals represents the emerging precision oncology specialist archetype, with development focus concentrated on pediatric and young-adult indications. These three company types illustrate how competitive positioning stratifies across diagnostic integration capability, geographic regulatory relationships, and therapeutic modality specialization.
| Leading Market Players |
|---|
| Day One Biopharmaceuticals |
| Servier |
| Hoffmann-La Roche Ltd. |
| Novartis |
| AnHeart Therapeutics |
| BeiGene |
| SpringWorks Therapeutics |
| Incyte Corporation |
| Eli Lilly and Company |
| Others |
Supply & Pricing Matrix
Convection-enhanced delivery research is simultaneously elevating R&D cost structures and concentrating manufacturing partnerships around academic medical centers with specialized neurosurgery infrastructure. This technological transition reshapes procurement economics as sponsors negotiate sole-source agreements for investigational device components while payers scrutinize value-based pricing for precision oncology agents.
Pricing Analysis
Companion diagnostic bundling with targeted therapies anchors pricing structures in this market, with IDH inhibitor regimens commanding premium positioning against cytotoxic alternatives. Price differentiation stems from biomarker stratification and site-of-care delivery economics, with oral formulations reducing hospital day utilization costs. Pricing pressure stems from reimbursement uncertainty for molecular profiling tests, compressing margins on diagnostic-therapeutic packages. Community oncology practices exhibit highest price sensitivity due to limited prior authorization infrastructure, while NCI-designated centers absorb premium pricing through bundled supply agreements.
Supply Chain Analysis
Active pharmaceutical ingredient production for IDH and MAPK pathway modulators rests on specialized contract manufacturers in Switzerland, Ireland, and the United States. Supply chains draw from rare starting materials including fluorinated intermediates and chiral building blocks, with synthesis complexity limiting qualified supplier pools. Single-source vulnerability concentrates around companion diagnostic reagent production, where ISO 13485-certified facilities face capacity constraints. Distribution runs through specialty pharmacy networks with cold-chain capabilities, concentrating downstream control at three national distributors with oncology accreditation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through diagnostic-therapeutic integration, as sponsors capture value from companion test adoption that reduces payer uncertainty and accelerates prior authorization.
For Market Incumbents: Anchor precision oncology positioning through exclusive pathology partnerships that lock in molecular diagnostic volume ahead of competitor trial enrollment. Consolidate manufacturing relationships with FDA-registered contract manufacturers to secure capacity for pediatric priority review voucher-triggered launches. Counter emerging biotech threats by pre-empting academic medical center sole-source agreements before registrational data readouts. For New Entrants and Emerging Players: Telemedicine-enabled patient identification platforms offer the lowest-friction entry vector for molecularly characterized low-grade glioma cohorts. Target community neuro-oncology practices in the United States with limited trial infrastructure, where remote molecular profiling partnerships can pre-screen patients for academic center referral. Deploy field-based medical science liaisons to educate pathologists on IDH mutation testing protocols, building prescriber relationships ahead of commercial infrastructure. For Investors and Strategic Acquirers: Roll-up economics work for precision oncology platform companies because biomarker-driven trial enrollment creates durable competitive moats around academic medical center relationships. Five-to-ten year viability hinges on regulatory exclusivity extensions through pediatric investigation plan completion. Monitor FDA pediatric priority review voucher award velocity as the inflection signal for sponsor investment intensity and valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-development | FDA alignment on IDH mutation testing standards accelerates targeted therapy label expansions. |
| Academic Medical Center Partnership | Sole-source agreements with NCI-designated centers concentrate molecularly characterized patient volume. |
| Pediatric Investigation Plan Execution | EMA compliance unlocks market exclusivity extensions for low-grade glioma indications. |
| Real-World Evidence Infrastructure | Digital biomarker integration supports post-approval label expansion without prospective trials. |
| Specialty Pharmacy Network Expansion | Oral oncology dispensing capabilities reduce site-of-care costs and improve pediatric compliance. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with neuro-oncology department heads, regulatory affairs leads at sponsors, pathology laboratory directors, hospital pharmacy procurement managers, and payer access specialists with secondary validation. Sources included FDA pediatric oncology guidance documents, EMA Paediatric Investigation Plan submissions, ClinicalTrials.gov protocol registrations, and formulary coverage determinations at major national payers. Bottom-up patient volume estimates and top-down therapeutic class spending reconciled through iterative triangulation.
Historical reference periods anchored the forecast window to documented regulatory approval timelines and pediatric priority review voucher award patterns. Segmentation modeling spanned therapy area, delivery mode, end user, and regulatory status dimensions across the projection horizon. CAGRs derived from patient incidence projections, molecular testing penetration curves, and pricing assumptions for precision oncology agents. Forecast inputs incorporated IDH mutation prevalence data and academic medical center referral network expansion rates.
The model assumes a particular technology adoption path; alternative pathways for convection-enhanced delivery commercialization would alter the outlook for blood-brain barrier penetration therapies. Forecasts reflect assumptions regarding regulatory convergence on molecular diagnostic requirements and adaptive trial design acceptance. Trial enrollment velocity, companion diagnostic reimbursement decisions, and pediatric priority review voucher policy adjustments warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Advanced Basal Cell Carcinoma Market
Specialty Medicine
Global Sarcopenia Treatment Market
Specialty Medicine
Global Major Depressive Disorder (MDD) Market
Specialty Medicine
Neurodegenerative Disease Market
Specialty Medicine
Anaplastic Large Cell Lymphoma (ALCL) Therapeutics Market
Specialty Medicine
Veno-Occlusive Hepatic Disease Therapeutics Market
Specialty Medicine
Primary Sclerosing Cholangitis Treatment Market
Specialty Medicine
Bipolar Disorders Treatment Market
Specialty Medicine
Eosinophilic Granulomatosis with Polyangiitis Treatment Market
Specialty Medicine
Asia-Pacific Primary Angle-Closure Glaucoma Market
Specialty Medicine
Hypophosphatasia Treatment Market
Specialty Medicine
Generalized Myasthenia Gravis (GMG) Management Market
Specialty Medicine
Cholangitis Market
Specialty Medicine
Multiple Sclerosis Market
Specialty Medicine
Pleural Diseases Therapeutics Market
Specialty Medicine
Middle-East and Africa Colorectal Cancer Market