
 Global Primary Immunodeficiency Therapeutics Market | 2026-2036
Global Primary Immunodeficiency Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Primary Immunodeficiency Therapeutics Market Foresight
The end-use vertical mix in primary immunodeficiency care is broadening as specialty clinics expand subcutaneous immunoglobulin programs and hematology centers build dedicated cellular therapy units. CSL Behring leverages its plasma collection infrastructure across North America and Europe to sustain supply security for immunoglobulin therapies. Takeda Pharmaceutical Company anchors its position through rare disease specialization in humoral immunodeficiency portfolios. Baxter International competes on delivery device innovation for home-based subcutaneous administration.
Primary immunodeficiency therapeutics comprise biologic and cellular interventions that restore, replace, or correct defective immune function in patients with inborn errors of immunity, with immunoglobulin products requiring cold-chain maintenance at two to eight degrees Celsius and viral inactivation steps during fractionation. The primary commercial purpose centers on preventing recurrent infections, organ damage, and mortality in antibody-deficient patient populations. Immunoglobulin therapy occupies the largest revenue pool due to chronic lifetime administration requirements, while gene therapy represents the fastest-expanding segment as lentiviral vector manufacturing scales and regulatory pathways clarify. Hematopoietic stem cell transplantation retains concentrated margin capture at quaternary referral centers despite procedure volume constraints.
The FDA's orphan drug exclusivity provisions and EMA's PRIME eligibility criteria shape clinical trial investment and accelerated assessment pathways for novel primary immunodeficiency modalities. Japan's PMDA Sakigake designation and reimbursement premium for pediatric rare diseases further steer development priorities toward severe combined immunodeficiency and Wiskott-Aldrich syndrome indications. Stakeholders must monitor how payer evidence requirements for gene therapy durability evolve against traditional immunoglobulin replacement benchmarks.
Market Dynamics
Gene therapy manufacturing scale-up is compressing development timelines for severe combined immunodeficiency while immunoglobulin supply security concerns force plasma collection infrastructure expansion across North America and Europe.
Growth Catalysts
- FDA Orphan Drug Exclusivity:Seven-year market exclusivity provisions accelerate investment in novel primary immunodeficiency modalities by de-risking clinical development economics for rare disease indications.
- Subcutaneous delivery platforms:Home administration devices reduce infusion center burden and expand patient eligibility for immunoglobulin replacement therapy across pediatric and adult populations.
- Japan's PMDA Sakigake designation:Priority review and reimbursement premiums for pediatric rare diseases redirect pipeline focus toward Wiskott-Aldrich syndrome and severe combined immunodeficiency.
Market Restraints
- Plasma fractionation concentration:Dependence on North American and European plasma collection networks creates supply vulnerability during donor recruitment disruptions or geopolitical trade friction.
- Cold-chain infrastructure gaps:Immunoglobulin stability requirements at two to eight degrees Celsius limit distribution reach in regions lacking validated temperature-controlled logistics.
- Gene therapy durability uncertainty:Long-term expression data gaps for lentiviral vectors delay payer confidence and reimbursement decisions versus established immunoglobulin benchmarks.
Strategic Opportunities
- Brazil's ANVISA rare disease pathway:Accelerated approval mechanisms for inborn errors of immunity open Latin America's largest patient population to novel biologic entry.
- Point-of-care diagnostic integration:Next-generation sequencing platforms in hematology centers enable newborn screening expansion and presymptomatic therapy initiation.
- EMA PRIME eligibility:Enhanced scientific advice and accelerated assessment for severe combined immunodeficiency gene therapies compress regulatory timelines versus standard centralized procedures.
Industry Challenges
- Vector manufacturing talent scarcity:Lentiviral production expertise concentrates at contract development organizations with GMP viral vector experience, constraining sponsor capacity build-out.
- Reimbursement evidence complexity:Payer demands for gene therapy cost-effectiveness modeling against lifetime immunoglobulin costs require novel health economic frameworks without established precedents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Primary Immunodeficiency Therapeutics Market |
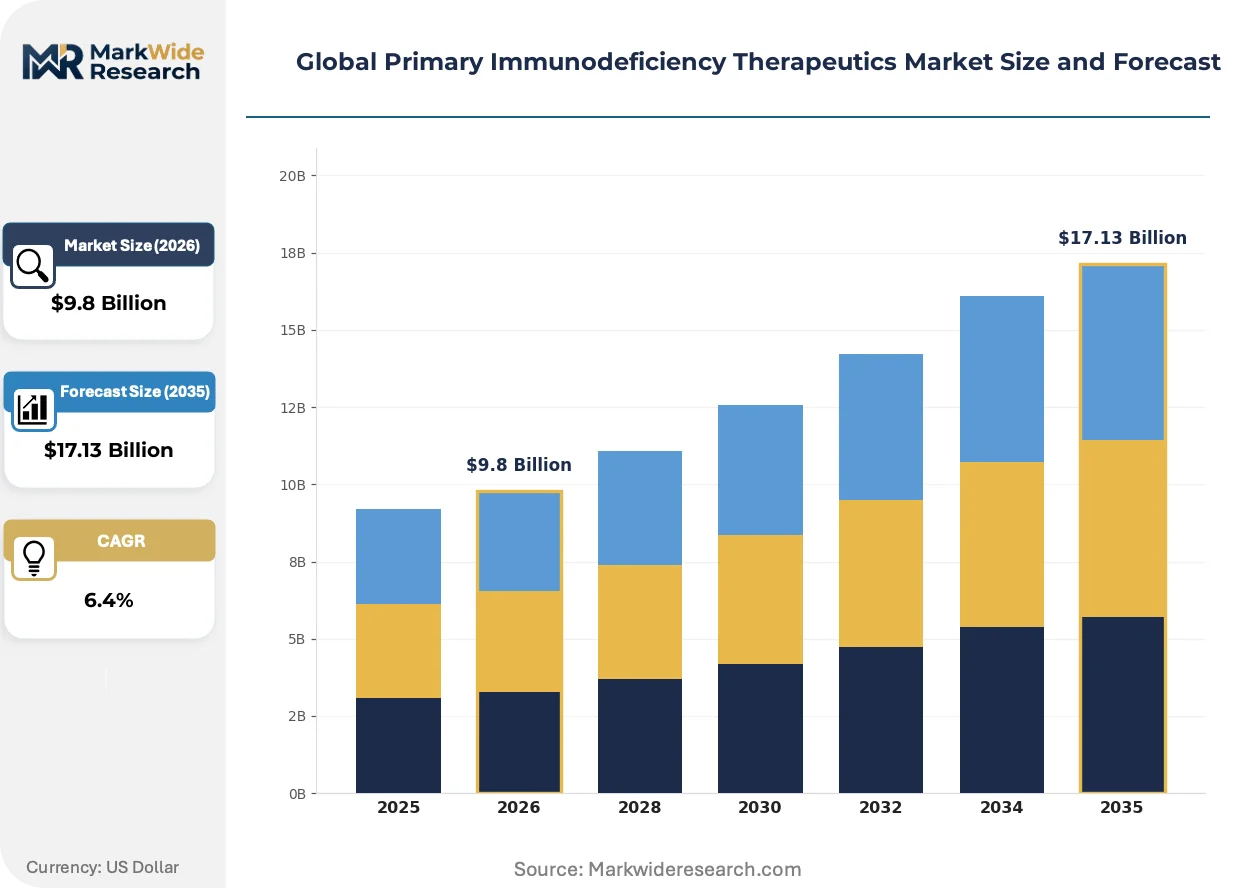
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoglobulin Therapy, Enzyme Replacement, Gene Therapy, Hematopoietic Stem Cell Transplantation Therapy Area: Humoral Immunodeficiencies, Cellular Immunodeficiencies, Combined Immunodeficiencies, Phagocytic Disorders End User: Specialty Clinics, Research Institutions, Diagnostic Laboratories, Hematology Centers Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Oral |
| Companies Covered | Baxter International, Takeda Pharmaceutical Company, CSL Behring, Octapharma, Biotest, Grifols, ADMA Biologics, Kedrion Biopharma, Bio Products Laboratory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Primary Immunodeficiency Therapeutics Market Shifts & Advancements
Manufacturing and delivery technologies are compressing the gap between laboratory proof-of-concept and commercial scalability for curative primary immunodeficiency interventions.
Automated closed-system bioreactors for lentiviral vector production are rewriting the economics of gene therapy supply. Contract manufacturers in the United States and Switzerland are deploying these platforms to reduce cleanroom footprint and contamination risk. The shift is enabling sponsor companies to retain process control while avoiding capital-intensive facility construction.
EMA's Advanced Therapy Medicinal Products framework is harmonizing manufacturing standards across European Union member states for gene-modified cellular therapies. The regulation mandates centralized manufacturing site inspections and batch release procedures. German and French reference hospitals are consolidating hematopoietic stem cell transplantation programs to align with these centralized compliance requirements.
Patient advocacy networks are driving demand for treatment site density expansion beyond quaternary academic centers. Home nursing services and specialty infusion clinics are displacing hospital-based immunoglobulin administration in the United States and Germany. This channel migration is most visible in antibody deficiency indications where chronic therapy creates cumulative travel burden for rural patient populations.
Global Primary Immunodeficiency Therapeutics Market Segmentation
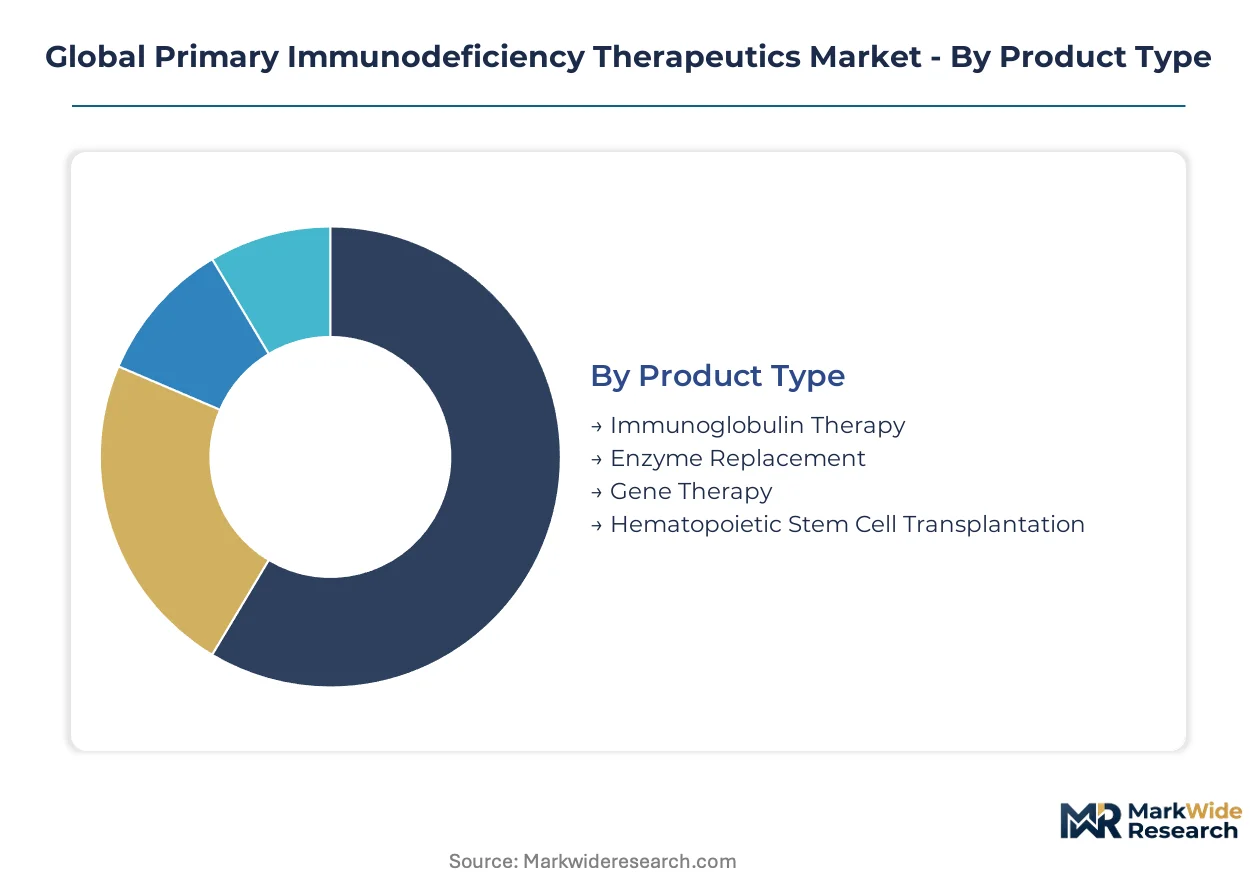
Segmentation in primary immunodeficiency therapeutics reveals how treatment selection varies by disease mechanism, care setting, and patient capability. Each dimension carries distinct supply chain requirements and reimbursement pathways that shape commercial strategy.
Product Type:
Buyers differentiate primarily by treatment duration and curative intent, with chronic replacement therapies demanding supply security and one-time interventions requiring outcome guarantees.
- Immunoglobulin Therapy:Plasma-derived polyclonal antibodies administered chronically to restore humoral immunity in antibody-deficient patients. Demand concentrates in the United States and Germany where home infusion nursing networks and subcutaneous delivery devices have expanded patient eligibility beyond hospital settings. Cold-chain requirements at two to eight degrees Celsius constrain distribution reach in regions lacking validated temperature-controlled logistics.
- Gene Therapy:Lentiviral vector-mediated gene transfer targeting hematopoietic stem cells for curative correction of inborn errors of immunity. Manufacturing scale-up at contract development organizations in Switzerland and the United States is compressing development timelines for severe combined immunodeficiency indications. Payer confidence remains contingent on long-term expression data versus established immunoglobulin replacement benchmarks.
- Enzyme Replacement:Recombinant proteins addressing metabolic defects in specific immunodeficiency subtypes such as adenosine deaminase deficiency.
- Hematopoietic Stem Cell Transplantation:Allogeneic cell replacement performed at quaternary referral centers with concentrated margin capture despite procedure volume constraints.
Immunoglobulin Therapy leads volumes today; Gene Therapy is gaining share fastest.
Therapy Area:
Clinical presentation severity and diagnostic accessibility determine where development investment concentrates across immune system compartments.
- Humoral Immunodeficiencies:Antibody production defects including common variable immunodeficiency and X-linked agammaglobulinemia representing the largest addressable population. Newborn screening expansion in hematology centers is enabling presymptomatic therapy initiation. CSL Behring and Takeda Pharmaceutical Company anchor commercial positions through plasma collection infrastructure and rare disease specialization respectively.
- Combined Immunodeficiencies:Defects affecting both cellular and humoral immunity such as severe combined immunodeficiency and Wiskott-Aldrich syndrome. Japan's PMDA Sakigake designation and reimbursement premium for pediatric rare diseases is redirecting pipeline focus toward these indications. EMA PRIME eligibility provides enhanced scientific advice and accelerated assessment pathways.
- Cellular Immunodeficiencies:T-cell and natural killer cell dysfunction requiring specialized diagnostic workup at reference hospitals.
- Phagocytic Disorders:Neutrophil and macrophage defects including chronic granulomatous disease with concentrated treatment at academic medical centers.
Humoral Immunodeficiencies dominates current revenue; Combined Immunodeficiencies shows the steepest expansion trajectory.
End User:
Care setting capabilities determine which delivery modes and therapy types each channel can economically support.
- Specialty Clinics:Dedicated immunology service lines expanding subcutaneous immunoglobulin programs across developed markets. Home nursing services are displacing hospital-based administration in the United States and Germany for antibody deficiency indications where chronic therapy creates cumulative travel burden for rural patient populations.
- Hematology Centers:Quaternary referral sites consolidating hematopoietic stem cell transplantation programs to align with EMA Advanced Therapy Medicinal Products centralized compliance requirements. German and French reference hospitals are leading this consolidation.
- Research Institutions:Academic centers conducting gene therapy clinical trials under FDA orphan drug exclusivity provisions.
- Diagnostic Laboratories:Next-generation sequencing platforms enabling newborn screening expansion and presymptomatic therapy initiation.
Specialty Clinics capture the highest patient volume; Hematology Centers command premium pricing for cellular interventions.
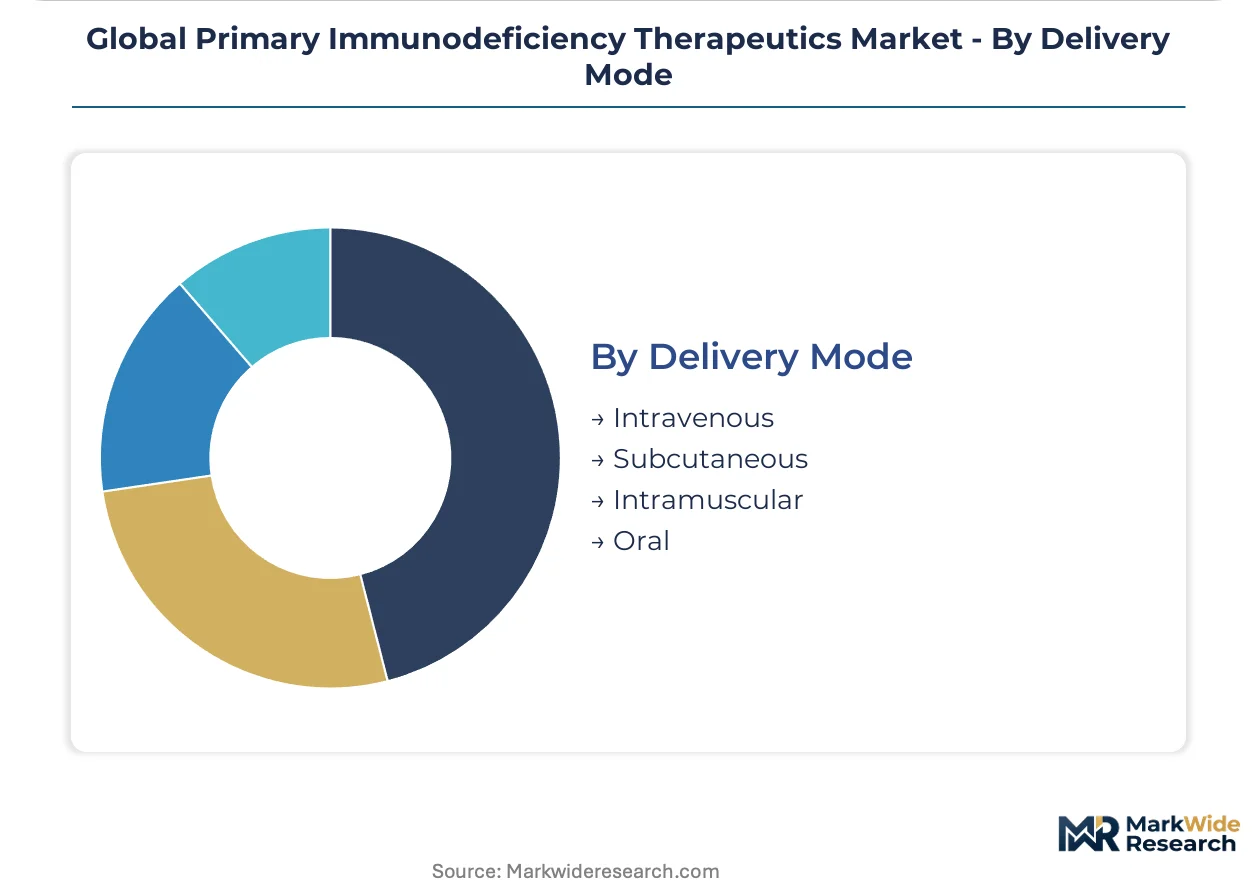
Delivery Mode:
Patient self-administration capability and infusion infrastructure availability drive channel selection and product form preferences.
- Intravenous:Hospital and infusion center administration of immunoglobulin requiring nursing supervision and extended observation periods. Volume concentration in the United States reflects mature commercial payer coverage for site-of-care reimbursement.
- Subcutaneous:Home-based administration enabled by delivery device innovation from Baxter International and competitors, reducing infusion center burden and expanding pediatric and adult eligibility.
- Intramuscular:Limited current use for specific immunoglobulin indications with restricted volume capacity.
- Oral:Emerging formulations for enzyme replacement and supportive therapies with bioavailability challenges in immunodeficiency applications.
Intravenous maintains the largest installed base; Subcutaneous is climbing the fastest as home care infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where plasma fractionation capacity migrates, with cost-of-compliance gaps between the FDA's orphan drug framework and EMA's centralized procedures steering investment toward jurisdictions offering accelerated assessment pathways for rare disease therapies.
United States
Specialty clinics across Texas and Florida are expanding subcutaneous immunoglobulin programs to capture rural patient populations previously dependent on hospital-based infusion centers. FDA orphan drug exclusivity provisions provide seven-year market protection that de-risks clinical development economics for severe combined immunodeficiency gene therapies. Boston and San Francisco anchor the country's gene therapy development clusters, with contract manufacturers deploying automated closed-system bioreactors for lentiviral vector production.
Germany
Reference hospitals in Munich and Heidelberg are consolidating hematopoietic stem cell transplantation programs to align with EMA Advanced Therapy Medicinal Products centralized compliance requirements. The country's plasma collection infrastructure supports CSL Behring's supply security for immunoglobulin therapies across European distribution networks. EMA PRIME eligibility provides enhanced scientific advice that compresses regulatory timelines for novel primary immunodeficiency modalities versus standard centralized procedures.
Japan
PMDA Sakigake designation and reimbursement premiums for pediatric rare diseases are redirecting pipeline focus toward Wiskott-Aldrich syndrome and severe combined immunodeficiency indications. Tokyo and Osaka medical centers are building dedicated cellular therapy units to capture premium pricing for curative interventions. The country's diagnostic referral networks enable newborn screening expansion that supports presymptomatic therapy initiation.
Switzerland
Contract development organizations in Basel and Zurich are deploying automated bioreactor platforms to reduce cleanroom footprint for lentiviral vector manufacturing. Swissmedic harmonizes manufacturing standards with EMA frameworks while offering competitive assessment timelines for gene-modified cellular therapies. The country's viral vector production expertise concentrates at GMP-experienced facilities serving sponsor companies seeking to avoid capital-intensive facility construction.
Brazil
ANVISA's rare disease pathway provides accelerated approval mechanisms for inborn errors of immunity that open Latin America's largest patient population to novel biologic entry. São Paulo and Rio de Janeiro hematology centers are expanding diagnostic capabilities to support newborn screening programs. Cold-chain infrastructure investments are addressing immunoglobulin stability requirements that previously limited distribution reach in regions lacking validated temperature-controlled logistics.
Global Primary Immunodeficiency Therapeutics Market Competitive Landscape
Capacity expansion dominates the current landscape as plasma fractionators scale collection infrastructure to address supply security concerns. The vendor base clusters around three strategic archetypes: integrated plasma collectors with fractionation capabilities, specialized biologics manufacturers focused on delivery device innovation, and emerging gene therapy developers building lentiviral vector production partnerships. Competitive positioning hinges on backward integration into plasma supply, geographic diversification of collection networks, and regulatory pathway expertise for rare disease designations.
Among integrated plasma collectors, CSL Behring and Grifols exemplify the supply-security archetype through North American and European collection infrastructure. Takeda Pharmaceutical Company occupies a position within the rare disease specialization tier, anchoring commercial presence in humoral immunodeficiency portfolios. Baxter International represents the delivery innovation vector, competing on device platforms that enable home-based subcutaneous administration. These three players illustrate how competitive positioning fragments across supply chain control, therapeutic focus, and patient access modalities rather than converging on a single dominant strategy.
| Leading Market Players |
|---|
| Baxter International |
| Takeda Pharmaceutical Company |
| CSL Behring |
| Octapharma |
| Biotest |
| Grifols |
| ADMA Biologics |
| Kedrion Biopharma |
| Bio Products Laboratory |
| Others |
Supply & Pricing Matrix
Quaternary referral centers and specialty infusion clinics concentrate procurement decisions for immunoglobulin therapies, anchoring contract-based long-term offtake agreements that lock in volume commitments against plasma supply volatility. Pricing power accumulates with fractionators controlling North American and European plasma collection networks, while gene therapy developers command premium positioning through outcome guarantees tied to curative durability.
Pricing Analysis
Distributor margins on plasma-derived immunoglobulin products compress as integrated collectors like CSL Behring and Grifols bypass wholesale channels for direct hospital system contracts. Three-tier pricing structure across premium, standard, and economy levels differentiates by viral inactivation protocol sophistication and IgA depletion certification, with cold-chain logistics bundling adding geographic delivery cost variance. Cost compression in standard-grade immunoglobulin is intensifying because Brazilian and Asian buyers qualify lower-specification products for budget-constrained national tender programs. Pediatric specialty clinics demonstrate highest price sensitivity due to lifetime therapy burden calculations, while hematology centers accepting gene therapy show lowest sensitivity given curative intent and bundled outcome pricing.
Supply Chain Analysis
Dual-sourcing requirements for lentiviral vector production mandate sponsor companies qualify both United States and Swiss contract development organizations with GMP viral vector experience, fragmenting manufacturing control. Geographic supply concentration centers on the United States, Germany, and Switzerland for plasma fractionation, with vector production drawing from Swiss and American bioreactor platforms. Raw material dependencies span source plasma, cell culture media, and chromatography resins, with supply chain risk concentrated in single-source vulnerability for specialized filtration membranes. Distribution runs through validated cold-chain logistics networks at two to eight degrees Celsius, limiting reach in regions lacking temperature-controlled infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where FDA orphan drug exclusivity provisions and EMA PRIME eligibility criteria compound development economics for rare disease modalities, with Japan's PMDA Sakigake designation accelerating pediatric indication prioritization.
For Market Incumbents: To counter gene therapy durability uncertainty eroding immunoglobulin replacement benchmarks, plasma fractionators should deepen backward integration into plasma collection infrastructure across Brazil and Eastern Europe while investing in subcutaneous delivery device certification to defend home infusion channel control. Capacity addition in São Paulo and Rio de Janeiro addresses ANVISA rare disease pathway demand growth.
For New Entrants and Emerging Players: Rural patient populations in the United States and Germany underserved by hospital-based infusion centers represent the most penetrable buyer archetype for subcutaneous immunoglobulin programs, with specialty clinic partnership models offering lower customer acquisition cost than quaternary center displacement. Point-of-care diagnostic integration in hematology centers enables newborn screening expansion as a differentiated go-to-market angle.
For Investors and Strategic Acquirers: Large-cap biopharmaceutical companies seeking rare disease portfolio expansion are the most active acquirer in this space, targeting gene therapy developers with lentiviral vector manufacturing partnerships and severe combined immunodeficiency clinical data packages. Long-term viability over a 5-10 year window hinges on payer confidence in curative durability versus chronic replacement economics. The signal to watch is EMA centralized batch release timing for first approved gene-modified cellular therapies.
| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Collection Infrastructure Expansion | CSL Behring and Grifols secure supply security for immunoglobulin therapies across European distribution networks. |
| Automated Bioreactor Platform Deployment | Swiss and American contract manufacturers reduce cleanroom footprint for lentiviral vector production economics. |
| Subcutaneous Delivery Device Certification | Baxter International enables home-based administration reducing infusion center burden for rural populations. |
| Newborn Screening Program Integration | Next-generation sequencing platforms in German and French reference hospitals enable presymptomatic therapy initiation. |
| EMA PRIME Eligibility Pursuit | Gene therapy developers compress regulatory timelines versus standard centralized procedures for severe combined immunodeficiency. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region combined with secondary validation. Primary interviews engaged drug development executives at plasma fractionators and gene therapy sponsors, regulatory affairs leads navigating FDA orphan drug and EMA PRIME pathways, formulary directors at German and Japanese payers, hospital procurement managers at quaternary referral centers, and payer access specialists evaluating gene therapy durability evidence. Secondary sources included FDA orphan drug designation filings, EMA PRIME eligibility assessments, ClinicalTrials.gov protocol registries, and national formulary databases. Bottom-up patient population sizing triangulated against top-down revenue estimates from plasma collector SEC disclosures.
Rate-of-change decomposition separated volume growth from price evolution across the projection horizon. Segmentation dimensions modeled encompassed treatment line, dosage form, administration route, patient population, and regional regulatory cluster. CAGRs derived from spline interpolation between anchor year actuals and terminal year assumptions, with immunoglobulin volume tied to diagnosed prevalent population expansion and gene therapy uptake calibrated to regulatory approval timelines and manufacturing scale-up curves.
Underlying measurement precision varies by segment; immunoglobulin replacement therapies carry tighter precision given mature diagnosis and treatment tracking, while gene therapy forecasts reflect wider confidence intervals pending long-term expression data. Forecasts reflect assumptions about regulatory pathway clarity, payer evidence requirements, and vector manufacturing yield improvements. Deviation in EMA centralized batch release timing or FDA gene therapy durability guidance would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Axial Spondyloarthritis Treatment Market
Specialty Medicine
Global Cancer Immunotherapies Market
Specialty Medicine
Hemifacial Spasm Market
Specialty Medicine
Global Epilepsy Market
Specialty Medicine
US Opioid Use Disorder (OUD) Market
Specialty Medicine
Polyarticular Juvenile Idiopathic Market
Specialty Medicine
Hepatitis C Treatment Market
Specialty Medicine
Endometriosis Market
Specialty Medicine
Toxic Epidermal Neurolysis Market
Specialty Medicine
Vesicoureteral Reflux Market
Specialty Medicine
Global Gastroparesis Treatment Market
Specialty Medicine
Sex Cord-Gonadal Stromal Tumor Market
Specialty Medicine
Global Scleroderma Therapeutics Market
Specialty Medicine
Toxoplasmosis Treatment Market
Specialty Medicine
Strep Throat Treatment Market
Specialty Medicine
Lung Cancer Therapeutics Market