
 Chronic Idiopathic Constipation Treatment Market | 2026-2036
Chronic Idiopathic Constipation Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Idiopathic Constipation Treatment Market Outlook
Asset-light licensing and royalty-based partnership structures is tilting competitive dynamics toward developers with strong patent estates rather than integrated manufacturers. Takeda Pharmaceutical Company leverages its gastrointestinal therapeutic heritage to sustain global distribution reach for linaclotide-based therapies. Ironwood Pharmaceuticals anchors its position through in-house production of guanylate cyclase-C agonists and specialized salesforce deployment in gastroenterology practices. Sanofi competes through broad primary-care channel access and formulary negotiation scale across European reimbursement systems.
Chronic idiopathic constipation treatment encompasses pharmacological interventions targeting persistent, symptom-driven bowel dysfunction unresponsive to dietary modification, including osmotic agents that draw water into the intestinal lumen and guanylate cyclase-C agonists that accelerate colonic transit through cyclic GMP elevation. Guanylate cyclase-C agonists command premium positioning due to prescription-only status and demonstrated efficacy in refractory populations, while bulk-forming agents occupy the over-the-counter entry point with lower per-unit margins but higher volume turnover. Oral delivery dominates prescribing patterns, though homecare settings represent the fastest-expanding end-user channel as telehealth follow-up reduces clinic dependency.
The FDA maintains stringent efficacy endpoints for CIC therapies, requiring twelve-week responder analyses that elevate clinical development costs and extend trial timelines. EMA's centralized pediatric investigation plans and Japan's PMDA gastrointestinal specialty review pathways further fragment market access requirements across developed economies. Stakeholders must monitor how CMS coverage determinations for prescription laxatives interact with Medicare Part D formulary tiering, as these decisions directly shape physician prescribing incentives and patient out-of-pocket exposure.
Market Dynamics
Specialty pharmacy networks and gastroenterology practice consolidation are compressing patient identification timelines while CMS reimbursement tiering for prescription laxatives reshapes physician prescribing economics.
Growth Catalysts
- Telehealth follow-up protocols:Remote monitoring platforms reduce clinic dependency and expand prescriber reach into underserved counties. Homecare settings capture rising patient volumes through virtual stool diary tracking.
- FDA twelve-week responder endpoints:Standardized efficacy thresholds validate premium-tier therapies and accelerate formulary placement in integrated delivery networks.
- Direct-to-consumer advertising:Patient self-identification campaigns in the United States shorten diagnostic delays and drive specialist referral volume.
Market Restraints
- Clinical trial cost inflation:Extended FDA-mandated responder analyses elevate development expenditures for novel guanylate cyclase-C agonists.
- Supply concentration in peptide manufacturing:Active pharmaceutical ingredient production clusters in contract manufacturers with limited gastrointestinal specialty capacity.
- Over-the-counter osmotic substitution:Polyethylene glycol and magnesium hydroxide formulations capture price-sensitive patients before prescription escalation.
Strategic Opportunities
- Pediatric investigation plans:EMA-mandated pediatric studies create first-mover advantage for developers with age-appropriate formulation capabilities.
- Japan PMDA gastrointestinal specialty pathway:Streamlined review timelines for refractory constipation indications reward early regulatory engagement.
- Specialty pharmacy channel expansion:Hub-and-spoke distribution models improve adherence monitoring and prior authorization support.
Industry Challenges
- Gastroenterology workforce scarcity:Fellowship-trained specialists concentrate in metropolitan academic centers, limiting rural prescriber density.
- Prior authorization complexity:Medicare Part D formulary tiering creates administrative burden for practice staff and patient access delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Idiopathic Constipation Treatment Market |
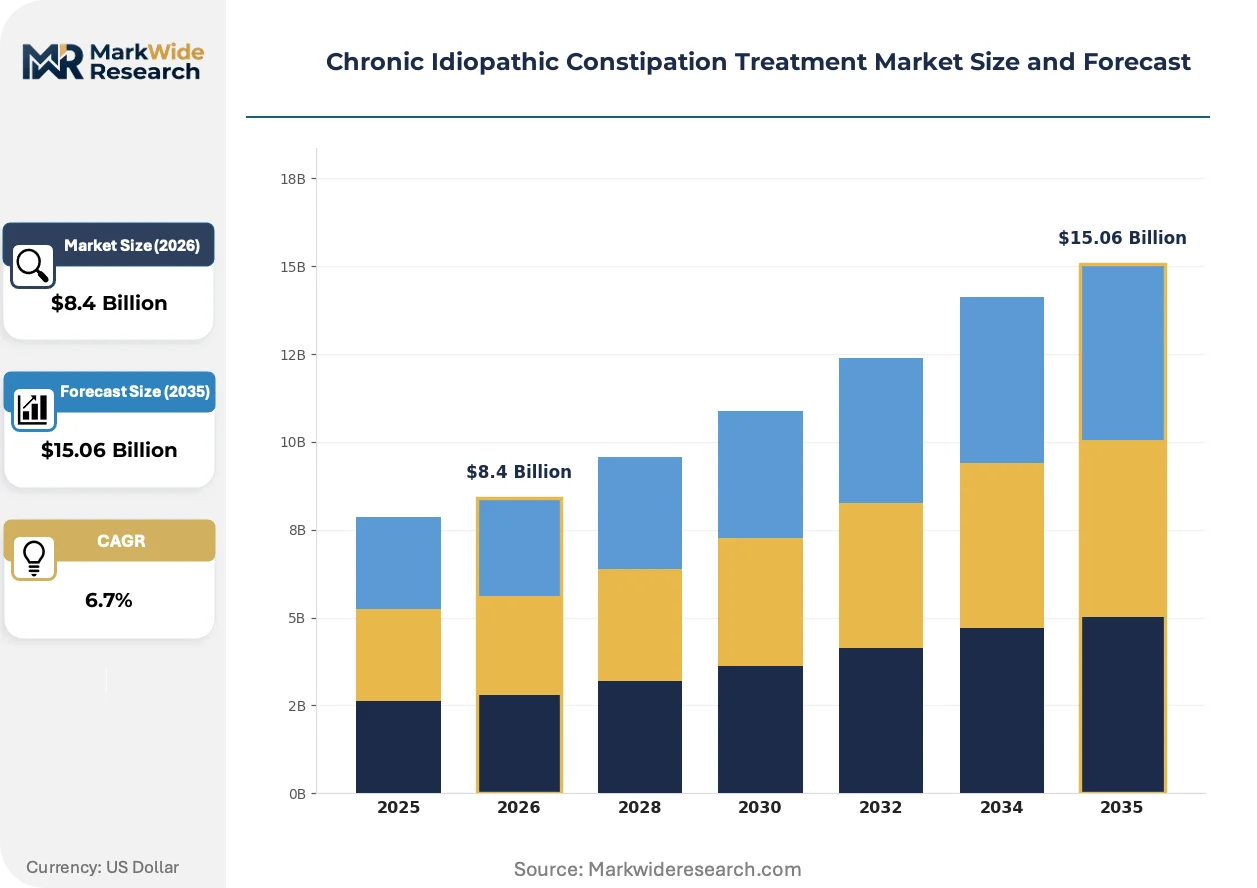
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stimulant Laxatives, Osmotic Agents, Bulk Forming Agents, Guanylate Cyclase-C Agonists Delivery Mode: Oral, Rectal, Injectable, Transdermal End User: Hospitals, Clinics, Homecare Settings, Pharmacies Age Group: Adults, Children, Elderly, Infants |
| Companies Covered | Ironwood Pharmaceuticals, Takeda Pharmaceutical Company, Bausch Health Companies, Allergan, Boehringer Ingelheim International GmbH, Sebela Pharmaceuticals, Sanofi, AstraZeneca, Mallinckrodt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Idiopathic Constipation Treatment Market Strategic Shifts
Digital biomarker integration and cyclic GMP pathway research are compressing traditional diagnostic and therapeutic development cycles across chronic constipation management.
Guanylate cyclase-C agonist mechanism research is virtualizing traditional efficacy measurement by enabling real-time colonic transit monitoring through ingestible sensor platforms. Gastroenterology practices in the United States deploy these tools to validate responder status without repeated clinic visits. The technology is virtualizing the twelve-week endpoint into continuous data streams that reshape payer evidence requirements.
EMA centralized pediatric investigation plans mandate age-stratified efficacy data for all novel CIC therapies seeking European marketing authorization. Developers must commit to pediatric formulation development prior to adult indication approval, extending clinical timelines. Small-molecule programs face the steepest compliance burden due to taste-masking and dosing flexibility requirements.
Patient stool diary apps and connected bathroom scales are fragmenting traditional symptom reporting through direct-to-physician data transmission. Gastroenterology practices integrate these tools into telehealth workflows, replacing retrospective recall with objective frequency metrics. Deployment concentrates in United States integrated delivery networks with existing remote monitoring infrastructure.
Chronic Idiopathic Constipation Treatment Market Segmentation
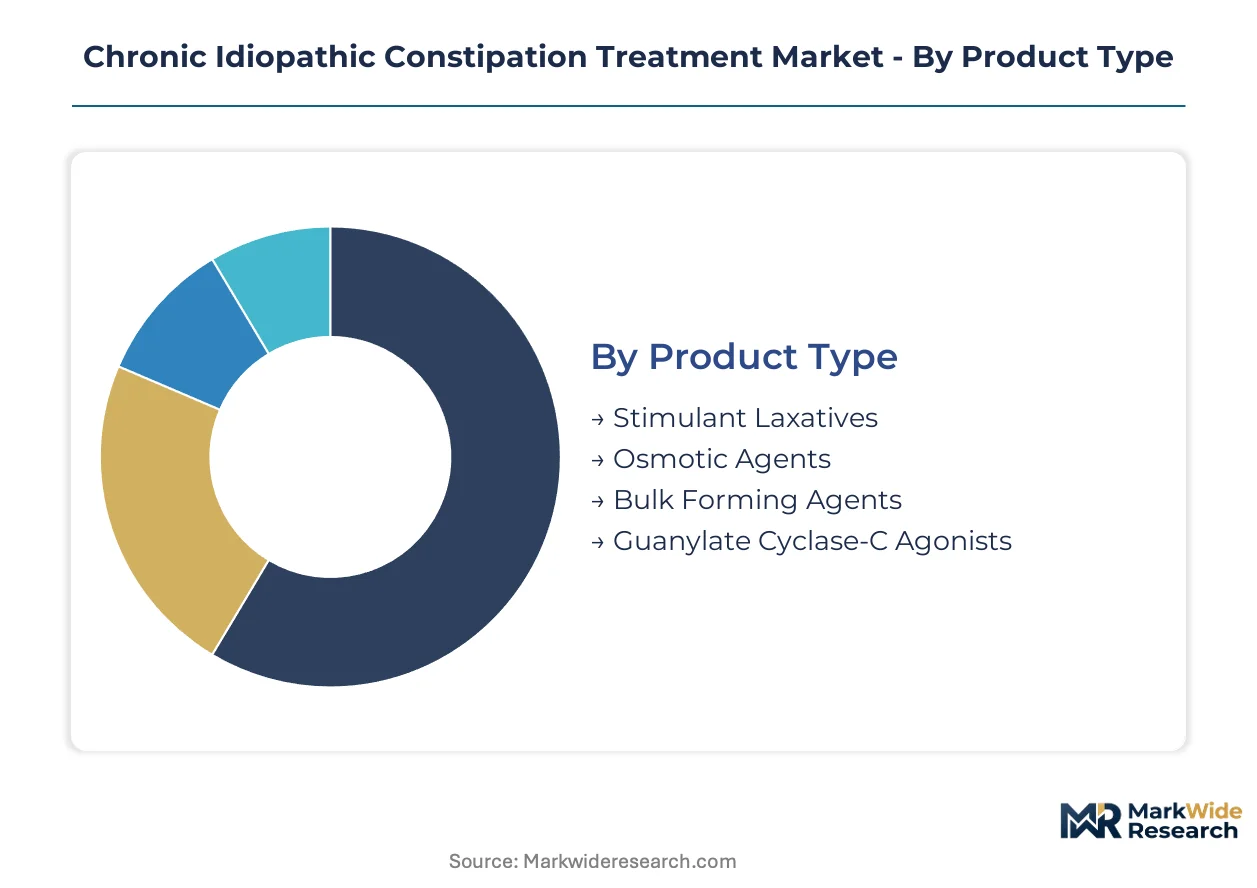
Segmentation in chronic idiopathic constipation treatment reveals how prescribing economics, patient acuity, and reimbursement pathways fragment demand across distinct product tiers and care settings. Understanding these divisions exposes where formulary negotiations concentrate and which channels capture volume versus margin.
Product Type:
Cost tier stratification separates premium prescription mechanisms from commodity over-the-counter alternatives, with reimbursement status determining prescriber behavior and patient access patterns.
- Stimulant Laxatives:These agents trigger intestinal contractions through direct neural stimulation of the myenteric plexus. Demand clusters in primary care practices managing short-term constipation episodes, though prolonged use risks cathartic colon syndrome that limits chronic prescribing.
- Osmotic Agents:Polyethylene glycol and lactulose formulations draw water osmotically into the colonic lumen to soften stool. Hospital formularies favor these for perioperative bowel preparation and elderly populations, with Medicare Part D tiering often placing them at preferred generic co-pay levels.
- Bulk Forming Agents:Psyllium and methylcellulose fiber supplements increase stool mass to stimulate peristalsis. Pharmacy shelf placement drives self-selection among price-sensitive patients prior to physician consultation.
- Guanylate Cyclase-C Agonists:Prescription-only peptides elevate intracellular cyclic GMP to accelerate transit and reduce visceral hypersensitivity. Gastroenterology specialists reserve these for refractory cases failing first-line therapy.
Bulk forming agents command the established base. The steepest expansion runs through guanylate cyclase-C agonists.
Delivery Mode:
Application convenience dictates adherence rates, with route selection reflecting patient functional status, comorbidity burden, and care setting infrastructure.
- Oral:Tablets and capsules dominate outpatient prescribing due to patient familiarity and pharmacy dispensing efficiency. Telehealth protocols reinforce oral preference through remote prescription renewal without procedural training requirements.
- Rectal:Suppositories and enemas achieve rapid onset for acute fecal impaction. Long-term care facilities and home health nurses deploy these when oral intake is compromised or immediate evacuation is clinically necessary.
- Injectable:Subcutaneous formulations address severe opioid-induced constipation refractory to oral therapy. Hospital infusion centers administer these under REMS protocols.
- Transdermal:Patch-based delivery remains investigational for CIC, with development programs targeting pediatric populations and dysphagia patients unable to tolerate oral solids.
Oral formulations anchor volume. Injectable routes are climbing the fastest as specialty pharmacy networks expand self-administration training.
End User:
Customer type determines procurement scale, with institutional buyers negotiating formulary placement while retail channels capture recurring prescription volume.
- Hospitals:Inpatient gastroenterology services standardize care pathways around osmotic agents for surgical bowel preparation and post-operative ileus prevention. Group purchasing organizations leverage volume commitments for contract pricing.
- Clinics:Outpatient gastroenterology practices generate prescription escalation to guanylate cyclase-C agonists after failure of initial therapy. Prior authorization staff manage Medicare Part D tiering appeals.
- Homecare Settings:Remote monitoring platforms and visiting nurse services enable complex regimen management outside institutional walls. Telehealth reimbursement expansion accelerates this channel's share gain.
- Pharmacies:Retail and specialty pharmacy networks handle prescription fulfillment, with hub-and-spoke models providing adherence packaging and refill synchronization for chronic therapy.
Pharmacies process the prescription volume base. Homecare settings are expanding most quickly as virtual follow-up reduces clinic dependency.
Age Group:
Maturity of the patient population shapes dosing formulation requirements, regulatory submission pathways, and caregiver involvement in administration.
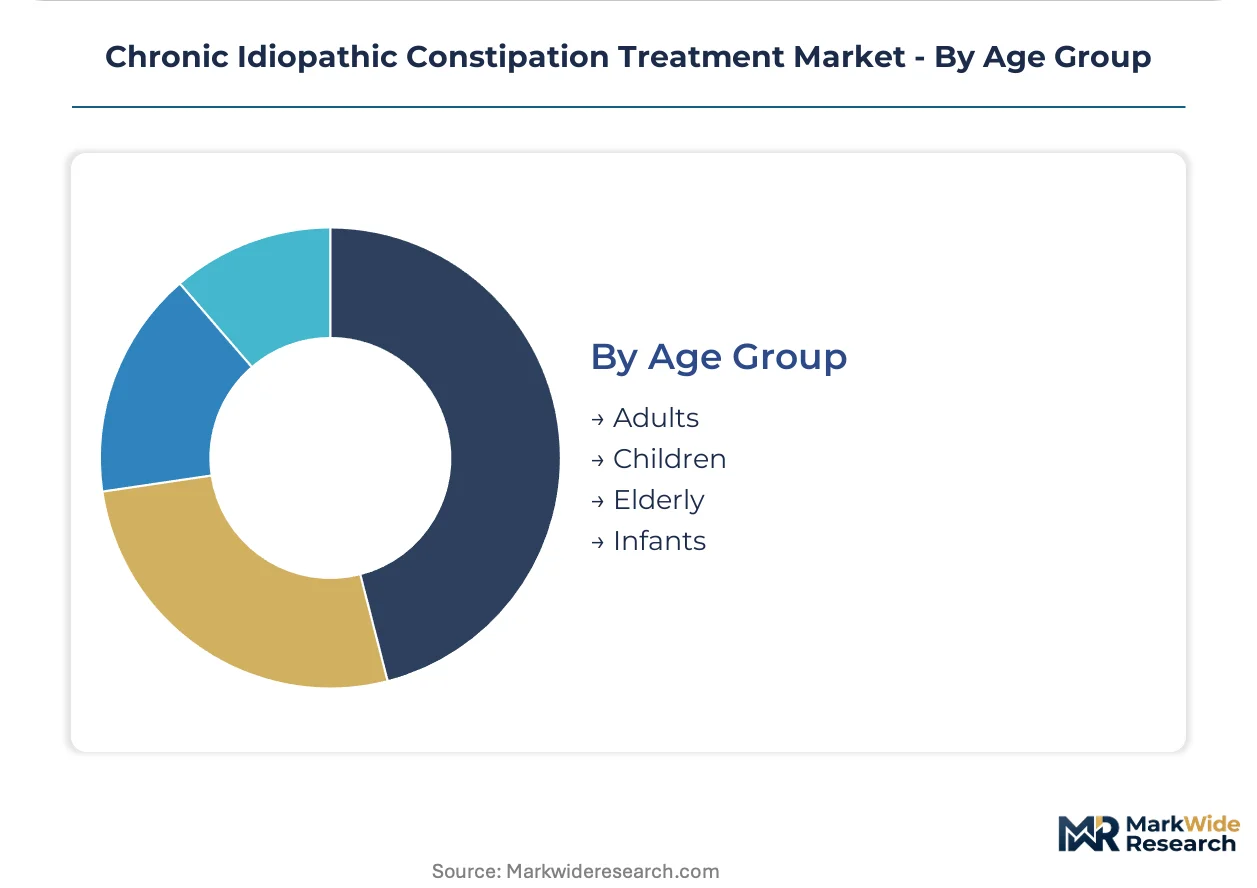
- Adults:Working-age patients between 18 and 64 years drive prescription volume for chronic maintenance therapy. Employer-sponsored insurance coverage determines access to premium-tier agents prior to Medicare eligibility.
- Children:Pediatric CIC requires age-appropriate liquid formulations and taste-masked tablets. EMA pediatric investigation plans mandate dedicated efficacy studies delaying European market entry.
- Elderly:Patients over 65 experience highest prevalence due to medication side effects, reduced mobility, and comorbid conditions. Polypharmacy interactions necessitate careful agent selection in this group.
- Infants:Neonatal and toddler constipation management relies on glycerin suppositories and dietary modification. Prescription pharmacotherapy carries limited labeled indications in this population.
Adults constitute the treated base. The elderly segment is gaining share fastest as population aging expands the addressable pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare Part D formulary tiering and direct-to-consumer advertising drive prescription volume concentration in the United States, while EMA pediatric investigation plans and Japan's PMDA gastrointestinal specialty pathways reshape regulatory timelines across developed economies.
United States
Specialty pharmacy networks and gastroenterology practice consolidation compress patient identification timelines. FDA twelve-week responder endpoints validate premium-tier therapies for integrated delivery networks. Boston and San Francisco biotech clusters host clinical trial infrastructure for guanylate cyclase-C agonist development programs.
Germany
Hospital procurement standardization through group purchasing organizations elevates osmotic agent volume for perioperative bowel preparation. EMA centralized pediatric investigation plans mandate age-stratified efficacy studies prior to marketing authorization. Heidelberg and Munich academic medical centers anchor refractory constipation research consortiums.
Japan
PMDA gastrointestinal specialty review pathways streamline timelines for refractory constipation indications. Aging demographics expand the elderly patient pool eligible for prescription maintenance therapy. Tokyo and Osaka metropolitan areas concentrate gastroenterology specialist density and telehealth infrastructure deployment.
United Kingdom
NICE technology appraisals shape National Health Service formulary placement for prescription laxatives. EMA pediatric investigation plans delay European market entry for developers lacking age-appropriate formulations. London and Manchester integrated care systems pilot remote monitoring platforms for homecare therapy management.
India
CDSCO regulatory pathways for gastrointestinal peptides attract contract manufacturing investment from multinational developers. Price-sensitive patient populations sustain bulk-forming agent demand through retail pharmacy channels. Hyderabad and Bangalore pharmaceutical clusters expand active pharmaceutical ingredient production for peptide-based therapies.
Chronic Idiopathic Constipation Treatment Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented prescription and over-the-counter segments. Market structure tilts toward asset-light licensing arrangements that reward patent estate strength over manufacturing scale. Three archetypes dominate: integrated gastrointestinal specialists with in-house peptide production, primary-care channel giants with formulary negotiation leverage, and royalty-dependent developers with virtual commercialization models. Competitive moves concentrate on specialty pharmacy network expansion and pediatric formulation licensing to satisfy EMA mandates.
Within the integrated specialist tier, Ironwood Pharmaceuticals and Takeda Pharmaceutical Company exemplify archetypes combining manufacturing control with gastroenterology-focused deployment. Sanofi occupies a position representing primary-care channel scale across European reimbursement systems. These three anchors illustrate how competitive positioning splits between prescription-only mechanism ownership and broad formulary access rather than unified vertical control.
| Leading Market Players |
|---|
| Ironwood Pharmaceuticals |
| Takeda Pharmaceutical Company |
| Bausch Health Companies |
| Allergan |
| Boehringer Ingelheim International GmbH |
| Sebela Pharmaceuticals |
| Sanofi |
| AstraZeneca |
| Mallinckrodt |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Indian peptide contract manufacturing is compressing margins for guanylate cyclase-C agonist APIs while simultaneously enabling aggressive pricing postures among finished dose suppliers competing for hospital formulary placement.
Pricing Analysis
Certification level creates the primary spread between premium prescription tiers and commodity alternatives. Three-tier pricing structure across premium, standard, and economy levels dominates: guanylate cyclase-C agonists command prescription-only premiums validated by FDA twelve-week responder data, osmotic agents occupy mid-tier Medicare Part D preferred generic positions, and bulk-forming agents compete on pharmacy shelf price. Price differentiation hinges on regulatory validation status and gastroenterology specialist endorsement. Cost compression in the osmotic tier is intensifying because polyethylene glycol 3350 faces therapeutic substitution pressure from magnesium hydroxide alternatives. Retail self-selectors show highest price sensitivity, while integrated delivery networks purchasing for refractory populations demonstrate lowest sensitivity to per-unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with Lonza, Catalent, and specialized Indian CMOs holding gastrointestinal peptide capacity. Active pharmaceutical ingredient production clusters in India, China, and Switzerland for synthetic peptide precursors. Finished dose formulation and packaging draws from Ireland, Germany, and the United States for regulatory compliance. Supply chain risk centers on single-source vulnerability for cyclic GMP pathway agonist starting materials, where fermentation-derived intermediates face limited qualified suppliers. Distribution runs through specialty pharmacy hub-and-spoke networks that manage cold-chain logistics and prior authorization support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chronic idiopathic constipation treatment represents early-cycle expansion as telehealth reimbursement codes and remote monitoring infrastructure unlock homecare settings previously constrained by clinic-dependent follow-up requirements.
For Market Incumbents: Build regulatory data moats through pediatric investigation plan completion ahead of EMA mandates. Anchor position by securing exclusive supply agreements with Indian peptide API manufacturers facing overcapacity. Defensive consolidation should prioritize backward integration into cyclic GMP agonist starting material production to offset single-source vulnerability. Counter emerging biosimilar threats by embedding digital biomarker tools into prescriber workflows to validate responder status continuously. For New Entrants and Emerging Players: Build out pediatric formulation capabilities to capture EMA-mandated study requirements that delay established competitors. Target Japan's PMDA gastrointestinal specialty pathway for streamlined refractory constipation approval timelines. White-space opportunity concentrates in transdermal delivery systems for dysphagia patients and elderly populations with polypharmacy burden. Go-to-market angle should leverage existing telehealth infrastructure partnerships rather than building de novo prescriber networks. For Investors and Strategic Acquirers: Capital is best deployed toward developers with completed pediatric investigation plans and virtual commercialization models minimizing fixed cost exposure. Long-term viability favors asset-light licensing structures that capture royalty streams without manufacturing capital intensity. Acquisition target archetype: peptide formulation specialists with taste-masking technology and age-appropriate dosing flexibility. Signal to monitor: CMS coverage determinations for prescription laxatives that reshape Medicare Part D tiering and physician prescribing economics.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Investigation Plan Completion | EMA mandates age-stratified data prior to European marketing authorization for all novel therapies. |
| Specialty Pharmacy Network Expansion | Hub-and-spoke distribution improves adherence monitoring and prior authorization support for guanylate cyclase-C agonists. |
| Digital Biomarker Integration | Ingestible sensor platforms virtualize twelve-week responder endpoints into continuous data streams for payer evidence. |
| Peptide API Manufacturing Scale-Up | Indian CMO overcapacity enables competitive sourcing for cyclic GMP pathway agonist production. |
| Telehealth Protocol Development | Remote stool diary tracking reduces clinic dependency and expands prescriber reach into underserved counties. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers; and secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare Part D formulary databases. Bottom-up prescription volume modeling triangulated with top-down market sizing across treatment lines and administration routes.
Forecast inputs incorporated patient population epidemiology, reimbursement pathway evolution, and regulatory timeline probability. Segmentation dimensions modeled included product mechanism class, delivery mode, end-user channel, and age-stratified patient population across regional regulatory clusters. CAGRs were derived from fitted growth curves applied to prescription volume and pricing trajectory assumptions. Industry-specific inputs captured gastroenterology workforce density and specialty pharmacy network expansion rates.
Practitioners should monitor FDA guidance evolution on digital biomarker endpoints and CMS coverage determinations for prescription laxatives as early signals of forecast revision triggers. Forecasts reflect assumptions regarding telehealth reimbursement stability and peptide manufacturing capacity utilization. Quarterly review of formulary tiering decisions and pediatric investigation plan completion timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Sarcopenia Treatment Market
Specialty Medicine
Small Molecule Targeted Cancer Therapy Market
Specialty Medicine
Multiple Sclerosis Market
Specialty Medicine
Global Hereditary Angioedema Therapeutics Market
Specialty Medicine
Pleural Diseases Therapeutics Market
Specialty Medicine
Overt Hepatic Encephalopathy Market
Specialty Medicine
Avascular Necrosis Market
Specialty Medicine
Checkpoint Inhibitor Refractory Cancer Market
Specialty Medicine
Mucous Membrane Pemphigoid Treatment Market
Specialty Medicine
Optic Atrophy Management Market
Specialty Medicine
Postmenopausal Osteoporosis Treatment Market
Specialty Medicine
Gouty Arthritis Market
Specialty Medicine
Acute Lymphoblastic Leukemia Therapeutics Market
Specialty Medicine
Global Endometrial Cancer Market
Specialty Medicine
Americas Gerd and Nerd Treatment Market
Specialty Medicine
Klinefelter Syndrome Treatment Market