
 Omega 3 PUFA Market | 2026-2036
Omega 3 PUFA Market Size, Share, and Industry Trends Forecast 2026-2036
Omega 3 PUFA Market Intelligence
The EU Green Deal's sustainable fisheries quotas is broadening pressure on marine-derived omega-3 supply chains and accelerating investment in algal fermentation platforms. DSM-Firmenich AG leverages its biotechnology portfolio to produce EPA and DHA from Schizochytrium strains at industrial scale. Cargill, Incorporated anchors its position through backward integration into Peruvian anchovy fisheries and refined oil processing. Aker BioMarine competes via Antarctic krill harvesting operations certified by the Marine Stewardship Council.
Omega 3 polyunsaturated fatty acids comprise long-chain carbon molecules with multiple cis-configured double bonds, primarily eicosapentaenoic acid (EPA, 20:5 n-3) and docosahexaenoic acid (DHA, 22:6 n-3), synthesized via cold-pressing or solvent extraction from marine biomass or oilseed feedstock and valued for anti-inflammatory eicosanoid modulation and membrane fluidity enhancement. The source dimension reveals structural tension: fish oil retains volume leadership in pharmaceutical-grade applications demanding high EPA purity, while algal oil captures fastest growth in plant-based nutraceuticals where kosher and allergen-free credentials command margin premiums. Softgel delivery mode dominates healthcare prescribing channels, yet gummy formats in the nutraceutical end-user segment are displacing liquid alternatives among pediatric and geriatric cohorts.
FDA qualified health claims for coronary heart disease risk reduction and EFSA novel food safety assessments shape product formulation standards and market access pathways for new entrants. REACH registration requirements for imported marine oils and California Proposition 65 labeling mandates add compliance layers that favor capital-intensive producers with dedicated regulatory affairs divisions. Stakeholders must monitor algal fermentation yield improvements and krill fishery certification renewals as determinants of long-term input cost trajectories and consumer trust metrics.
Market Dynamics
Algal fermentation technology is decentralizing omega-3 production away from marine fisheries toward controlled bioreactor systems, collapsing traditional geographic dependencies on Peruvian anchovy and Antarctic krill harvesting regions while rewriting capital allocation patterns across the value chain.
Growth Catalysts
- EFSA Novel Food Safety Assessments:Streamlined approval pathways for algal-derived DHA and EPA ingredients accelerate market entry for biotechnology platforms targeting infant formula applications.
- Pediatric Nutraceuticals:Gummy format adoption among parents seeking allergen-free alternatives drives formulation innovation in vegan supplement lines.
- Direct-to-Consumer Subscription Models:Pharmacy retail chains in the United States consolidate volume through recurring delivery platforms, locking in household penetration.
Market Restraints
- Fish Oil Supply Concentration:Peruvian anchovy fishery quotas and El Niño volatility expose pharmaceutical-grade EPA producers to input cost spikes.
- REACH Registration Burden:European chemical compliance requirements for imported marine oils favor capital-intensive producers with dedicated regulatory affairs divisions.
- Plant-Based Omega-3 Competition:Alpha-linolenic acid from flaxseed and chia erodes mid-market positioning for low-concentration fish oil supplements.
Strategic Opportunities
- India Nutraceutical Expansion:FSSAI regulatory modernization and rising middle-class health expenditure create whitespace for algal DHA penetration in maternal nutrition.
- Kosher and Allergen-Free Positioning:Algal fermentation bypasses shellfish and fish allergen concerns, commanding margin premiums in religiously observant and sensitive consumer segments.
- Cellular Agriculture Convergence:Precision fermentation platforms from adjacent biotechnology sectors transfer yield optimization expertise to Schizochytrium strain engineering.
Industry Challenges
- Pharmaceutical-Grade Purification Expertise:EPA isolation at 90%+ purity requires chromatography specialists scarce outside established marine oil processors.
- California Proposition 65 Compliance:Heavy metal and contaminant labeling mandates demand continuous testing infrastructure that strains mid-tier ingredient suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Omega 3 PUFA Market |
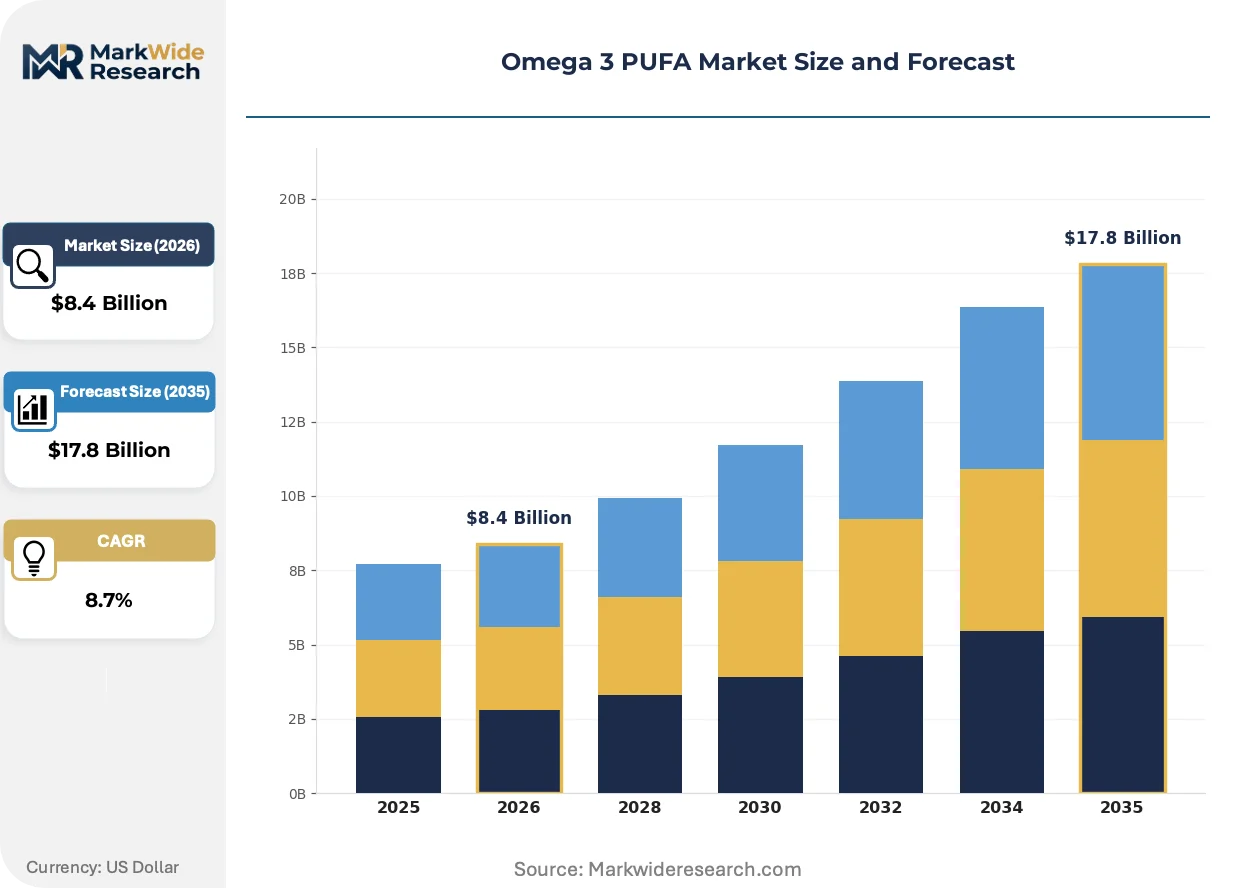
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $17.8 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EPA, DHA, ALA, Others Delivery Mode: Softgels, Liquid, Powders, Gummies End User: Healthcare, Nutraceuticals, Food Industry, Personal Care Source: Fish Oil, Algal Oil, Flaxseed Oil, Krill Oil |
| Companies Covered | BASF SE, Cargill, Incorporated, DSM-Firmenich AG, Aker BioMarine, Croda International Plc, ADM (Archer Daniels Midland Company), Lonza Group, GC Rieber Oils, Corbion N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Omega 3 PUFA Market Strategic Shifts & Innovations
Biotechnology platforms are collapsing the traditional divide between marine extraction and agricultural production, enabling omega-3 manufacturing in land-based facilities independent of ocean ecosystem health. This shift reconfigures supplier geography, regulatory exposure, and sustainability credentialing simultaneously.
Precision fermentation using Schizochytrium and Crypthecodinium strains is decentralizing DHA production from coastal fishing zones to controlled industrial bioreactors. Infant formula manufacturers in North America and Europe adopt these inputs to secure supply continuity and eliminate ocean contaminant risks. The technology compresses lead times from seasonal harvest cycles to continuous batch processing, eroding the volume advantage of traditional fish oil refiners.
EFSA tightened contaminant thresholds for dioxins and polychlorinated biphenyls in marine-derived food supplements, forcing processors to invest in molecular distillation upgrades. Pharmaceutical-grade applications face the steepest compliance costs, while algal alternatives bypass these legacy burdens entirely. German and French regulators now require batch-level testing documentation that smaller Peruvian and Chilean exporters struggle to provision.
Pediatric and geriatric cohorts reject liquid omega-3 formats in favor of gummy and emulsion delivery systems that mask fish odor and improve dosing adherence. Direct-to-consumer brands capture this preference shift through subscription platforms, disintermediating pharmacy retail chains that historically dominated volume. The United States exhibits the most pronounced channel migration, with telehealth-integrated supplement bundles accelerating the transition.
Omega 3 PUFA Market Segmentation
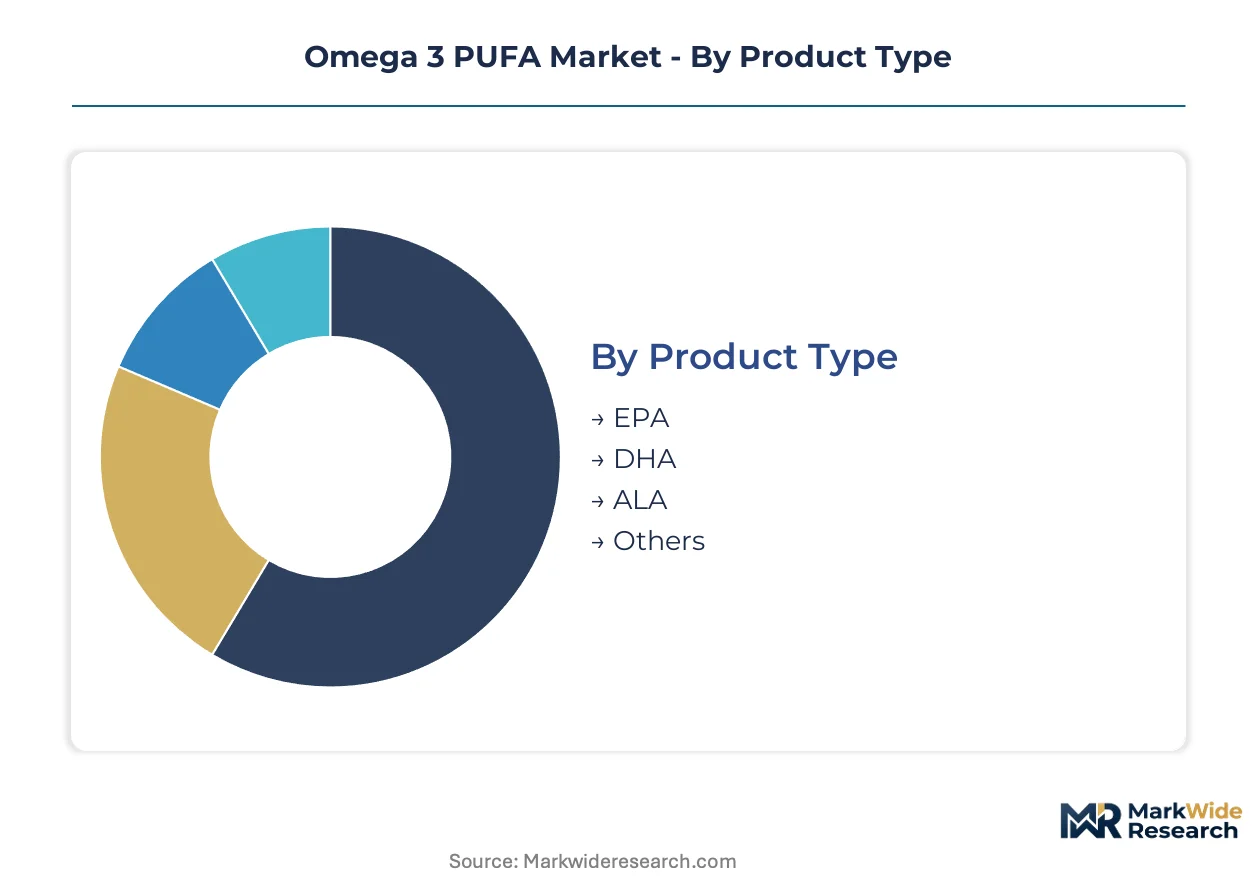
Omega 3 PUFA purchasing decisions hinge on purity thresholds, delivery format preferences, and source sustainability credentials that vary sharply across infant formula manufacturers, pharmacy chains, and direct-to-consumer brands. Segmentation reveals how pharmaceutical-grade EPA specifications diverge from vegan nutraceutical positioning, creating distinct margin architectures within the same molecular category.
Product Type:
Formulation chemists select EPA, DHA, or ALA ratios based on target physiological endpoints and regulatory claim eligibility.
- EPA:Eicosapentaenoic acid at 90%+ purity dominates pharmaceutical applications for cardiovascular risk reduction under FDA qualified health claims. Prescription Lovaza and Vascepa formulations anchor demand in United States healthcare channels where cardiologists specify ethyl ester concentrates.
- DHA:Docosahexaenoic acid concentrates command premium positioning in infant formula and prenatal supplement segments. EFSA novel food approvals for algal-derived DHA accelerate biotechnology platform adoption among European formula manufacturers seeking contaminant-free supply.
- ALA:Alpha-linolenic acid from flaxseed and chia serves mid-market vegan positioning where conversion efficiency to long-chain omega-3s remains a consumer education challenge.
- Others:Stearidonic acid and docosapentaenoic acid occupy emerging research niches in cognitive health and anti-inflammatory protocols.
EPA leads on scale through prescription volume; DHA leads on momentum through algal fermentation capacity expansion.
Delivery Mode:
Patient adherence and pediatric palatability drive format selection, with pharmacy reimbursement favoring softgels while subscription brands chase gummy adoption curves.
- Softgels:Gelatin and plant-based capsule shells dominate hospital and clinic dispensing in the United States. Enteric coating technologies mask fish odor for GERD-sensitive populations.
- Liquid:Emulsion formats serve dysphagia patients and precise pediatric dosing in neonatal intensive care units.
- Powders:Microencapsulated DHA integrates into dry infant formula premixes and functional food fortification.
- Gummies:Pectin-based matrices displace liquids among parents seeking allergen-free pediatric supplementation, with United States direct-to-consumer brands capturing subscription renewals through flavor masking.
Softgels anchor reimbursement channels; gummies gain share fastest in household penetration models.
End User:
Regulatory scrutiny intensity and margin structure vary across pharmaceutical, nutraceutical, and cosmetic applications.
- Healthcare:Prescription omega-3 concentrates require FDA-approved manufacturing facilities and REMS compliance for hypertriglyceridemia indications.
- Nutraceuticals:Dietary supplement brands navigate structure-function claim boundaries while competing on third-party testing certifications.
- Food Industry:Bread, dairy, and beverage fortification faces GRAS self-affirmation or notification pathways depending on EPA/DHA concentration thresholds.
- Personal Care:Topical formulations leverage omega-3 barrier repair claims in prestige skincare, though dermal penetration efficacy remains formulation-dependent.
Healthcare commands highest purity premiums; nutraceuticals show steepest expansion trajectory through subscription channel growth.
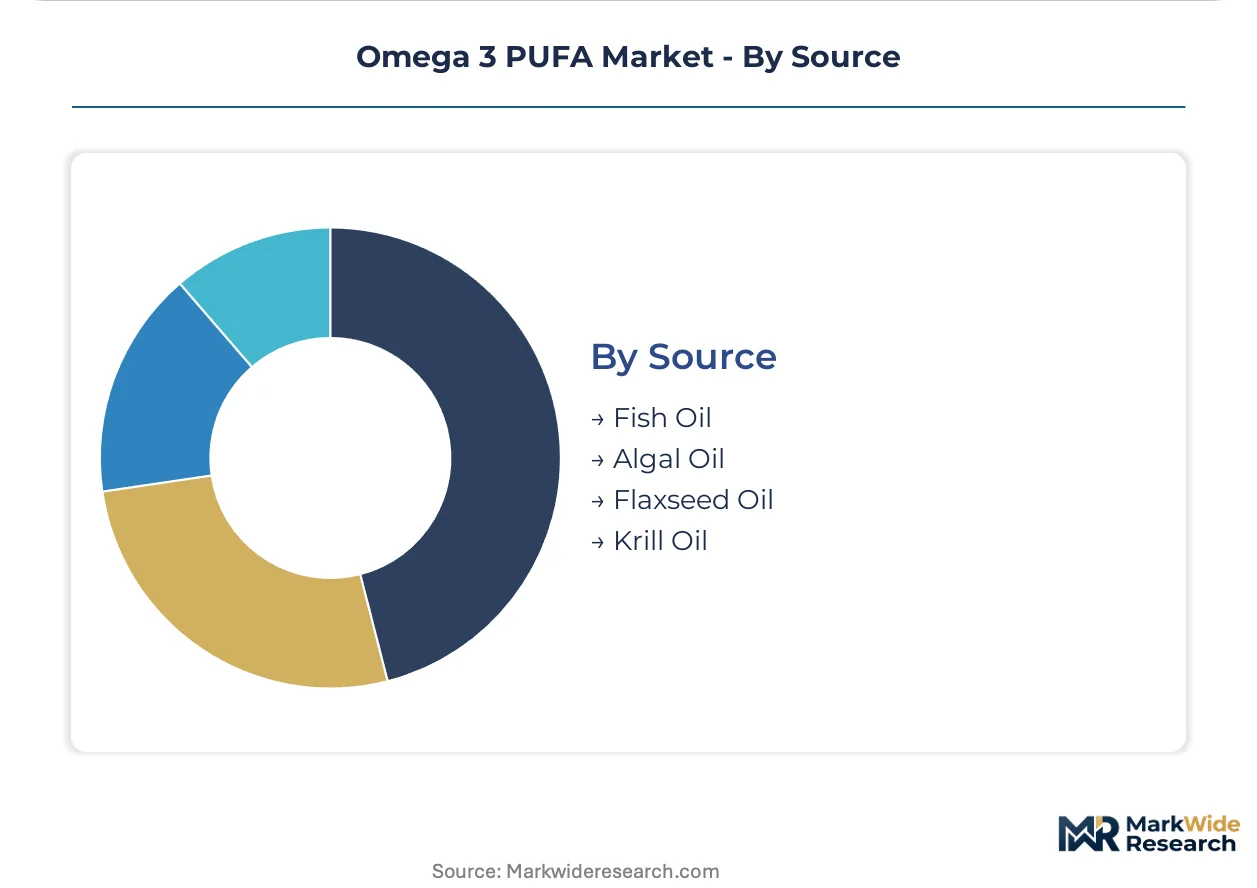
Source:
Supply geography and sustainability certification determine procurement risk profiles for finished goods manufacturers.
- Fish Oil:Peruvian anchovy and North Atlantic cod liver fisheries retain volume leadership for high-EPA pharmaceutical refining. El Niño volatility and EU Green Deal quota pressures concentrate supply risk among coastal processors.
- Algal Oil:Schizochytrium fermentation in land-based bioreactors eliminates ocean contaminant exposure and secures kosher, allergen-free credentials for vegan positioning.
- Flaxseed Oil:Canadian and Ukrainian agricultural output supplies ALA for plant-based omega-3 claims, though metabolic conversion limitations constrain clinical positioning.
- Krill Oil:Antarctic harvesting under Marine Stewardship Council certification competes on phospholipid bioavailability claims in premium supplement segments.
Fish oil retains installed base; algal oil climbs fastest on fermentation yield improvements and EFSA novel food streamlining.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Omega 3 PUFA commercialization traces its industrial roots to Scandinavian cod liver oil processing in the early twentieth century, with Norwegian and Danish fisheries establishing the first extraction infrastructure. Modern production geography now spans fermentation bioreactors, Antarctic harvesting fleets, and South American reduction plants.
United States
Pharmacy retail chains and direct-to-consumer subscription platforms concentrate prescription EPA volume and household nutraceutical penetration. FDA qualified health claims for cardiovascular risk reduction shape formulation standards for Lovaza-equivalent concentrates. The Boston-Cambridge biotechnology corridor hosts algal fermentation startups engineering Schizochytrium strains for infant formula applications.
Germany
EFSA novel food safety assessments and REACH registration requirements filter market entry for imported marine oils and algal ingredients. Molecular distillation specialists in Hamburg and Bremen upgrade Peruvian anchovy crude into pharmaceutical-grade EPA isolates. German regulators now mandate batch-level dioxin testing documentation that strains smaller South American exporters.
China
Domestic infant formula manufacturers accelerate algal DHA sourcing to replace fish oil imports and eliminate ocean contaminant risks. NMPA regulatory pathways for novel food ingredients are streamlining biotechnology platform approvals. The Yangtze River Delta biotech cluster near Shanghai hosts multiple Schizochytrium fermentation facilities serving maternal nutrition brands.
Norway
Antarctic krill harvesting operations certified by the Marine Stewardship Council anchor premium phospholipid positioning in European supplement channels. Aker BioMarine's vertical integration from vessel to capsule commands margin premiums in kosher and allergen-free segments. Tromsø-based research institutes advance lipid extraction technologies for high-purity EPA applications.
India
FSSAI regulatory modernization and rising middle-class health expenditure create whitespace for algal DHA penetration in prenatal and infant nutrition. Import substitution policies favor domestic biotechnology partnerships over Peruvian fish oil sourcing. Mumbai and Hyderabad pharmaceutical formulators are negotiating toll manufacturing agreements with European algal oil suppliers.
Omega 3 PUFA Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the omega-3 value chain. Integrated marine harvesters and fermentation operators control upstream supply, while nutraceutical brands and pharmaceutical formulators capture downstream margin through delivery innovation and channel positioning. Three archetypes dominate: Antarctic krill harvesters with MSC certification, algal biotechnology platforms with EFSA novel food approvals, and Peruvian anchovy processors with backward integration into reduction fisheries. Competitive moves concentrate on fermentation yield patents and pharmacy retail chain exclusivity agreements.
Among European chemical conglomerates, BASF SE and DSM-Firmenich AG exemplify divergent strategic postures. BASF SE occupies a position anchored in industrial-scale chemical processing infrastructure, while DSM-Firmenich AG represents the biotechnology pivot toward controlled fermentation systems. Cargill, Incorporated anchors the agricultural-commodity-to-specialty-ingredient trajectory through Peruvian fisheries integration. These three entities collectively illustrate how capital allocation now splits between ocean-dependent extraction and land-based bioreactor platforms.
| Leading Market Players |
|---|
| BASF SE |
| Cargill, Incorporated |
| DSM-Firmenich AG |
| Aker BioMarine |
| Croda International Plc |
| ADM (Archer Daniels Midland Company) |
| Lonza Group |
| GC Rieber Oils |
| Corbion N.V. |
| Others |
Cost & Logistics Intelligence
Sovereign-backed Norwegian krill harvesters and private-equity-rolled-up Peruvian anchovy processors anchor divergent supply strategies, with the former commanding phospholipid premiums through Marine Stewardship Council certification while the latter face cost compression from El Niño volatility and EU Green Deal quota restrictions.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, nutraceutical-premium, and economy bulk segments governs transaction dynamics. Price differentiation rests on EPA purity thresholds and kosher-allergen-free certification status. Cost compression in economy fish oil tiers is intensifying because flaxseed ALA alternatives erode positioning. Pharmacy chains exhibit lowest price sensitivity; direct-to-consumer subscription brands show highest elasticity.
Supply Chain Analysis
Direct-to-brand ingredient supply handles hyperscale nutraceutical demand while pharmaceutical channels rely on contracted offtake from molecular distillation specialists. Raw material flows draw from Peruvian anchovy fisheries, Antarctic krill harvesting zones, and land-based Schizochytrium fermentation facilities in China and Germany. Single-source vulnerability concentrates in seasonal marine biomass availability. Distribution runs through pharmacy retail chains in the United States and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EFSA novel food safety assessments for algal-derived DHA accelerate biotechnology platform adoption and compress traditional marine oil margins.
For Market Incumbents: Lock in pharmacy retail chain exclusivity agreements for prescription EPA volumes before algal fermentation yields erode cost advantages. Secure backward integration into Peruvian reduction fisheries or captive bioreactor capacity to defend input cost positions against El Niño-driven supply shocks. For New Entrants and Emerging Players: Direct-to-consumer subscription channels offer the lowest barrier to household penetration in pediatric gummy segments. Target maternal nutrition whitespace in India where FSSAI regulatory modernization and import substitution policies favor domestic biotechnology partnerships over established fish oil sourcing. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier algal fermentation operators lacking EFSA novel food approvals but possessing scalable Schizochytrium strain libraries. Watch fermentation yield improvement announcements as the inflection signal distinguishing commodity producers from margin-capturing platform owners.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Approval Pathway | Unlocks European infant formula market access for algal DHA biotechnology platforms. |
| Backward Integration into Fermentation Capacity | Captures margin compression from yield improvements in Schizochytrium strain engineering. |
| Direct-to-Consumer Channel Launch | Disintermediates pharmacy retail chains through subscription-based pediatric gummy formats. |
| Marine Stewardship Council Certification Renewal | Sustains phospholipid premium positioning in Antarctic krill harvesting operations. |
| Pediatric Format Innovation | Addresses adherence barriers through pectin-based gummy matrices masking fish odor. |
Research Approach
Multiple input streams — primary interviews with fermentation platform engineers, regulatory affairs specialists at infant formula manufacturers, pharmacy chain procurement directors, and molecular distillation plant managers; secondary validation through EFSA novel food approval databases, FDA qualified health claim filings, and Marine Stewardship Council certification records; plus customs trade data on Peruvian anchovy meal exports — were reconciled through bottom-up volume modeling and top-down market sizing triangulation.
Historical volume trajectories were cross-referenced against expert panel inputs on fermentation yield improvement timelines and regulatory approval pathway durations. Segmentation dimensions modeled include EPA/DHA/ALA molecular type, softgel/liquid/powder/gummy delivery mode, fish/algal/krill/flaxseed source origin, and healthcare/nutraceutical/food industry end-use application. CAGRs were derived from slope analysis across the projection horizon, with specific weighting applied to algal biotechnology capacity expansion schedules and El Niño frequency patterns in marine biomass availability.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation yield breakthroughs would alter the outlook for marine-derived omega-3 cost competitiveness. Forecasts reflect assumptions regarding EFSA regulatory streamlining continuity and FSSAI modernization momentum in India. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
Asia-Pacific Omega3 PUFA Market
Functional Food & Ingredients
Banana Leaf Extract Market
Functional Food & Ingredients
South America Prebiotic Ingredients Market
Functional Food & Ingredients
APAC Heart Health Functional Food Market
Functional Food & Ingredients
Superfood Powders Market
Functional Food & Ingredients
Prickly Pear Fruit Metabolic Health Ingredients Market
Functional Food & Ingredients
Brazil Flavored and Functional Water Market
Functional Food & Ingredients
Japan Soy Protein Market
Functional Food & Ingredients
South America Omega-3 PUFA Market
Functional Food & Ingredients
Europe Sterol Market
Functional Food & Ingredients
Sacha Inchi Protein Market
Functional Food & Ingredients
Global Medical Foods Market
Functional Food & Ingredients
Mediterranean Cognitive-First Ingredient Systems Market
Functional Food & Ingredients
Brominated Vegetable Oil Market
Functional Food & Ingredients
Functional Ingredients Market
Functional Food & Ingredients
Functional Non-Meat Ingredients Market