
 Asia-Pacific Omega3 PUFA Market | 2026-2036
Asia-Pacific Omega3 PUFA Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Omega3 PUFA Market Outlook
Softgel-to-powder format unbundling is restructuring buyer choice across the Asia-Pacific Omega3 PUFA landscape. Koninklijke DSM N.V. leverages its algal-derived DHA platforms to capture premium positioning in China's maternal nutrition channel. Aker BioMarine anchors Antarctic krill oil supply through its vertically controlled harvesting fleet, while Cargill competes on scale in bulk fish oil concentrates for Southeast Asian feed manufacturers.
Omega3 polyunsaturated fatty acids comprise long-chain EPA and DHA molecules, typically extracted via molecular distillation or supercritical CO2 processing from marine biomass, functioning as structural lipid modulators in cardiovascular, neural, and anti-inflammatory metabolic pathways. Fish oil retains volume leadership across the Asia-Pacific Omega3 PUFA Market due to entrenched supply infrastructure and cost-positioning, yet algal oil demonstrates the steepest trajectory as fermentation technology cuts production costs and eliminates marine contaminant risks. Dietary supplements command the dominant margin pool through direct-to-consumer pricing power, while pharmaceutical-grade applications tighten specification requirements and extend qualification timelines for new entrants.
China's NMPA enforces progressive purity thresholds for imported omega3 concentrates, while India's FSSAI mandates label disclosure of EPA/DHA ratios and oxidation markers for domestic supplement sales. Japan's MHLW maintains pharmaceutical-grade omega3 as a designated quasi-drug category, restricting marketing claims and channel access. Stakeholders must monitor how regulatory divergence between national pharmacopeia standards reshapes formulation strategies and cross-border certification investments.
Market Dynamics
Format unbundling from softgel to powder concentrates is fragmenting buyer decision architecture across the Asia-Pacific Omega3 PUFA landscape, forcing manufacturers to recalibrate production lines and inventory strategies around multiple specification tiers simultaneously.
Growth Catalysts
- FSSAI purity mandates:India's food safety regulator enforces progressive oxidation marker disclosure and EPA/DHA ratio labeling, compelling domestic brands to upgrade analytical capabilities and sourcing standards.
- China's infant nutrition sector:Algal-derived DHA concentrates gain preferential positioning in maternal and early childhood formulations as domestic biotech fermentation capacity scales.
- Japan's quasi-drug designation:MHLW classification of pharmaceutical-grade omega3 restricts marketing claims but creates premium channel access and reimbursement pathways for qualified entrants.
Market Restraints
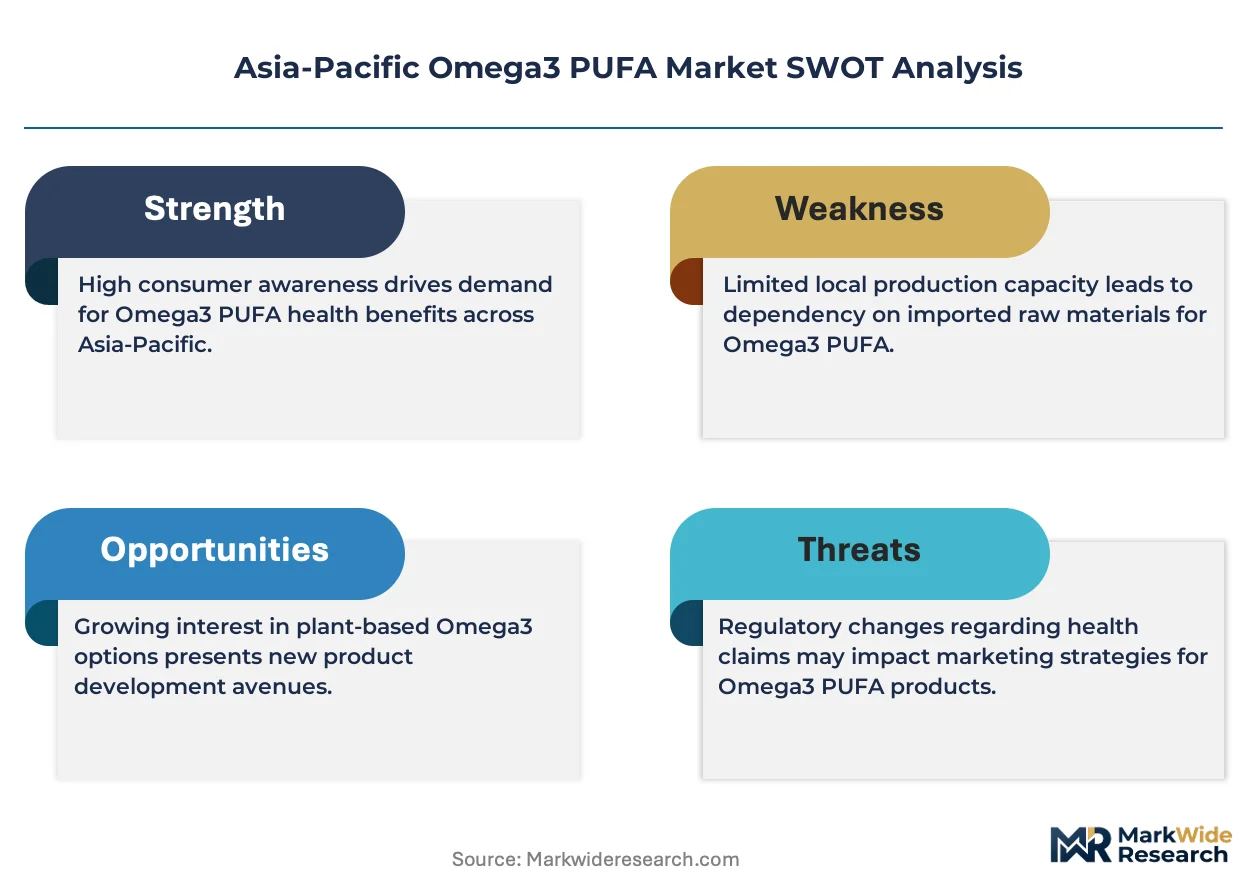
- Antarctic krill supply concentration:Single-fleet harvesting dominance creates bottleneck risk for phospholipid-bound omega3 feedstock, exposing buyers to quota volatility and climate-dependent catch windows.
- Marine biomass input costs:Wild-catch fish oil remains exposed to El Niño-driven anchovy population fluctuations and Peruvian-Chilean quota negotiations.
- NMPA import qualification timelines:China's national pharmaceutical regulator extends certification periods for novel concentrates, freezing product launch schedules and capital deployment.
Strategic Opportunities
- Vietnam and Indonesia underpenetration:Southeast Asian supplement markets lack established omega3 consumption habits, presenting first-mover positioning for powder-format functional foods.
- Supercritical CO2 extraction convergence:Combined with enzymatic interesterification, this processing pairing enables contaminant-free concentrates at temperatures below thermal degradation thresholds.
- South Korea's MFDS functional food pathway:The regulator's expanded health claim recognition for cardiovascular endpoints opens direct-to-consumer positioning beyond generic supplement classification.
Industry Challenges
- Pharmaceutical-grade GMP certification:Quasi-drug qualification in Japan and ICH-aligned manufacturing in China demand 18-24 month facility validation timelines that compress working capital cycles.
- Algal strain IP fragmentation:Proprietary DHA-rich microalgae genetics remain locked behind licensing walls, forcing second-tier producers into royalty-bearing supply agreements.
- Multi-jurisdiction label harmonization:Divergent oxidation marker limits between FSSAI, NMPA, and MFDS specifications necessitate parallel inventory SKUs and analytical batch testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Omega3 PUFA Market |
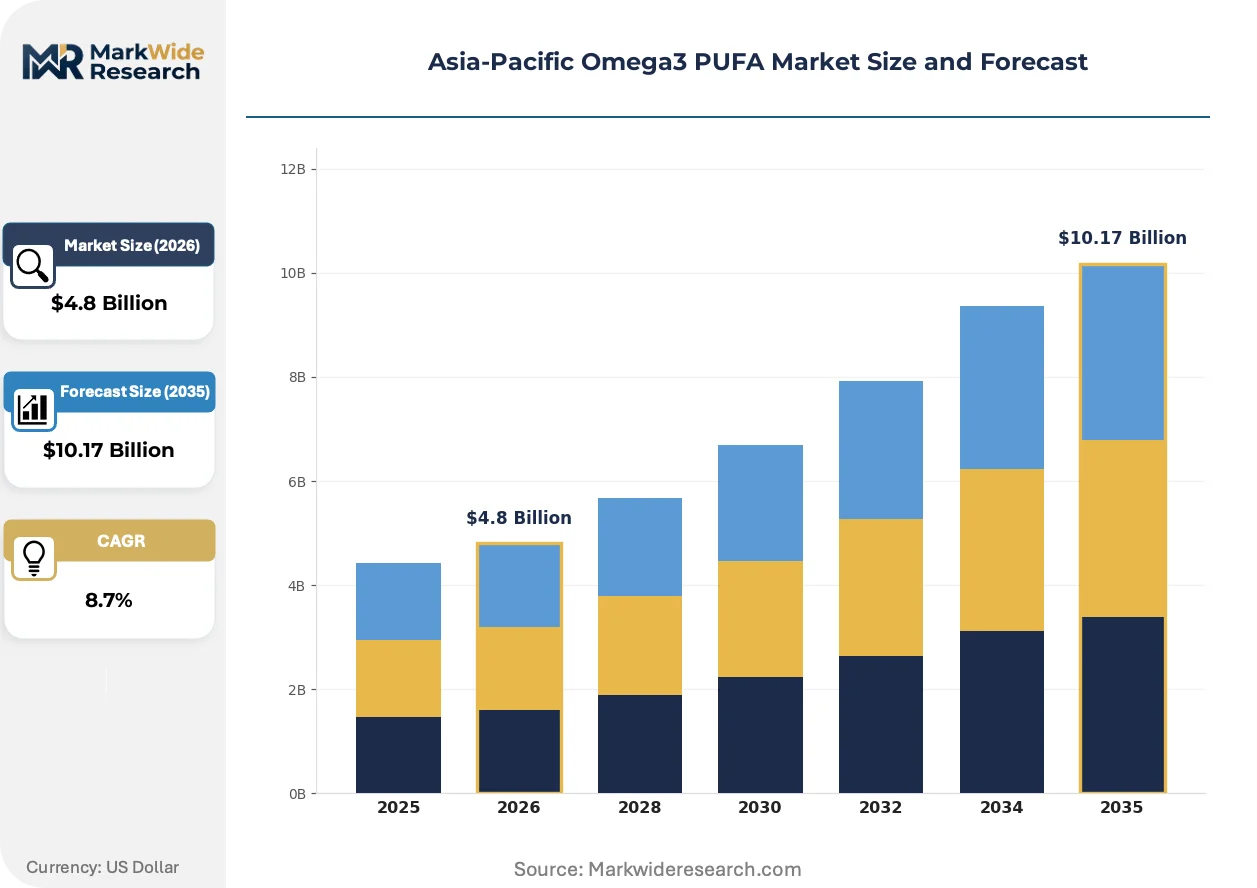
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Oil, Krill Oil, Algal Oil, Cod Liver Oil Application: Dietary Supplements, Food & Beverages, Pharmaceuticals, Animal Nutrition End User: Health Conscious Consumers, Athletes, Pregnant Women, Pets Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | BASF SE, Corbion N.V, Koninklijke DSM N.V., Croda International Plc, KD Pharma Group, Aker BioMarine, Cargill, ADM (Archer Daniels Midland Company), Orkla ASA, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Omega3 PUFA Market Strategic Shifts
Bioprocess engineering advances and regulatory claim pathways are compressing the traditional divide between commodity fish oil and premium-positioned algal alternatives across Asia-Pacific formulation strategies.
Precision fermentation of thraustochytrid microalgae is rewriting cost structures for DHA concentrates. Chinese biotech platforms now achieve cell densities exceeding prior generation photobioreactor yields by an order of magnitude. Infant formula manufacturers in Shanghai and Guangzhou are qualifying these domestic fermentation sources ahead of NMPA novel food ingredient approvals.
NMPA's progressive tightening of imported concentrate purity thresholds is forcing supply chain requalification. The regulator's 2024 draft guidelines on dioxin and PCB limits align with EFSA benchmarks but exceed historical CFDA tolerances. European and South American bulk oil exporters face extended analytical verification periods at designated Chinese port laboratories.
Direct-to-consumer powder sachets displace traditional softgel dominance in South Korean and Japanese retail channels. Younger demographic cohorts favor on-the-go dissolution formats over pill-swallowing regimens. E-commerce platforms in Seoul and Tokyo report concentrate powder velocities outpacing gelatin-capsule SKUs within the omega3 category.
Asia-Pacific Omega3 PUFA Market Segmentation
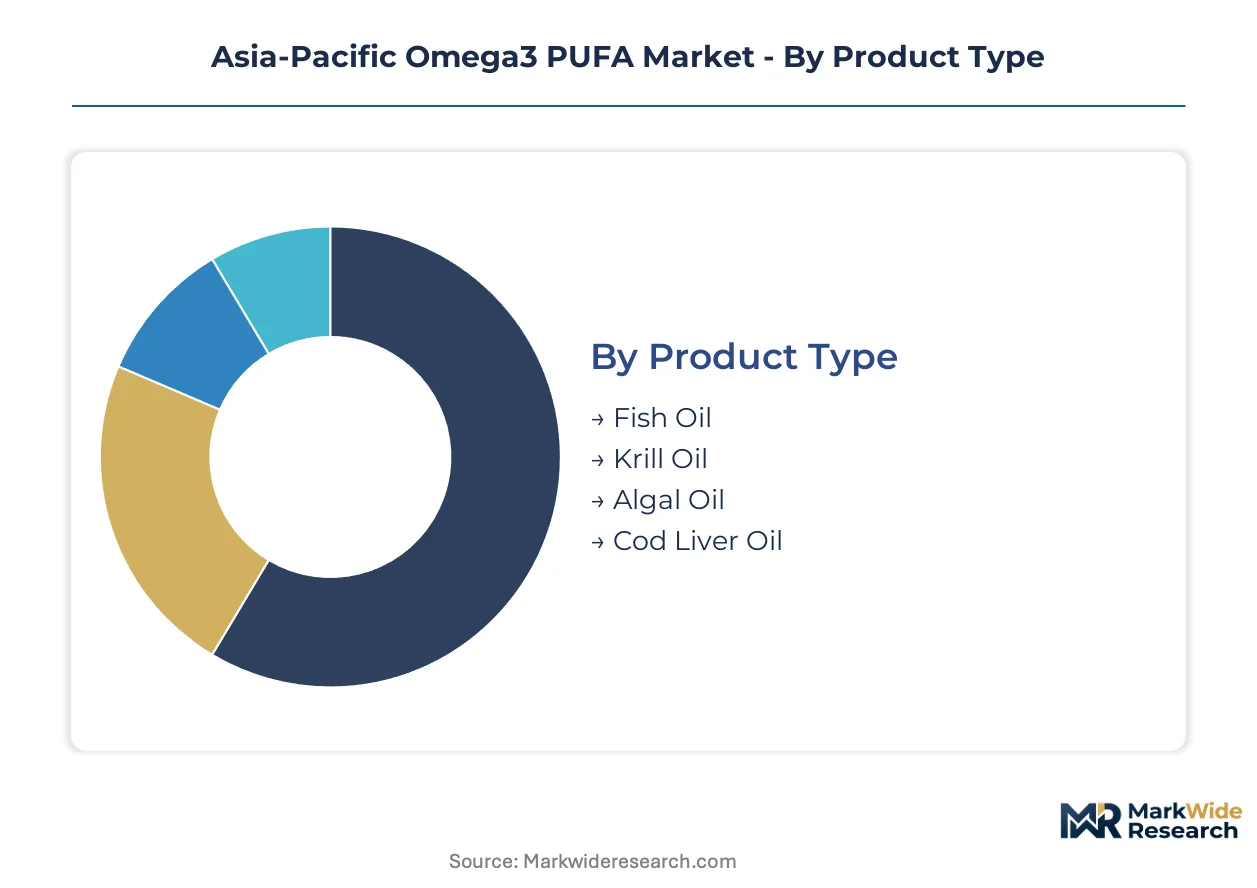
Asia-Pacific Omega3 PUFA procurement decisions fragment across four intersecting dimensions. Product chemistry determines extraction infrastructure requirements, while application context dictates certification tiers and margin structures.
Product Type:
Capital intensity peaks with fermentation-based algal platforms, where bioreactor arrays and strain optimization labs demand the heaviest upfront commitment.
- Fish Oil:Bulk marine concentrates extracted via molecular distillation anchor volume supply across Southeast Asian feed and supplement manufacturing. Chinese and Vietnamese processors dominate toll refining capacity for ethyl ester and triglyceride re-esterified formats.
- Algal Oil:Thraustochytrid fermentation in Shanghai and Guangzhou biotech parks yields DHA concentrates without marine contaminant exposure. Infant formula manufacturers in China qualify these sources ahead of NMPA novel food approvals.
- Krill Oil:Antarctic phospholipid-bound omega3 requires vertically controlled harvesting fleets and at-sea processing vessels.
- Cod Liver Oil:Nordic-sourced retinol-enriched fractions serve legacy supplement positioning in Japan and South Korea.
Most installed capacity flows through Fish Oil. Expansion is steepest in Algal Oil.
Application:
Margin capture stratifies sharply between commoditized feed additives and pharmaceutical-grade concentrates requiring GMP-validated production suites.
- Dietary Supplements:Direct-to-consumer softgels and powder sachets command the widest pricing power across Japanese and South Korean e-commerce channels. FSSAI and MFDS labeling mandates force domestic brands to upgrade analytical capabilities.
- Pharmaceuticals:Japan's MHLW quasi-drug classification restricts marketing claims but opens reimbursement pathways for cardiovascular indications. NMPA import qualification timelines extend to 18-24 months for novel concentrates.
- Food & Beverages:Functional fortification in dairy and bakery applications faces oxidation stability challenges during thermal processing.
- Animal Nutrition:Aquaculture feed in Vietnam and Indonesia drives bulk fish oil offtake with limited specification overhead.
Revenue concentration sits with Dietary Supplements. Regulatory qualification barriers are highest in Pharmaceuticals.
End User:
Purchasing behavior diverges between clinical recommendation channels and self-directed wellness consumption.
- Pregnant Women:Algal-derived DHA concentrates gain preferential positioning in China's maternal nutrition sector as domestic fermentation capacity scales. Shanghai-based infant formula manufacturers qualify novel sources ahead of NMPA approvals.
- Health Conscious Consumers:Powder-format functional foods displace softgel dominance in Seoul and Tokyo retail. Younger demographics favor on-the-go dissolution formats over pill-swallowing regimens.
- Athletes:Anti-inflammatory positioning drives sports nutrition formulations with elevated EPA ratios.
- Pets:Premium companion animal feed in Japan incorporates krill phospholipids for coat quality claims.
Clinical channel access concentrates with Pregnant Women. Self-directed purchasing velocity is fastest among Health Conscious Consumers.
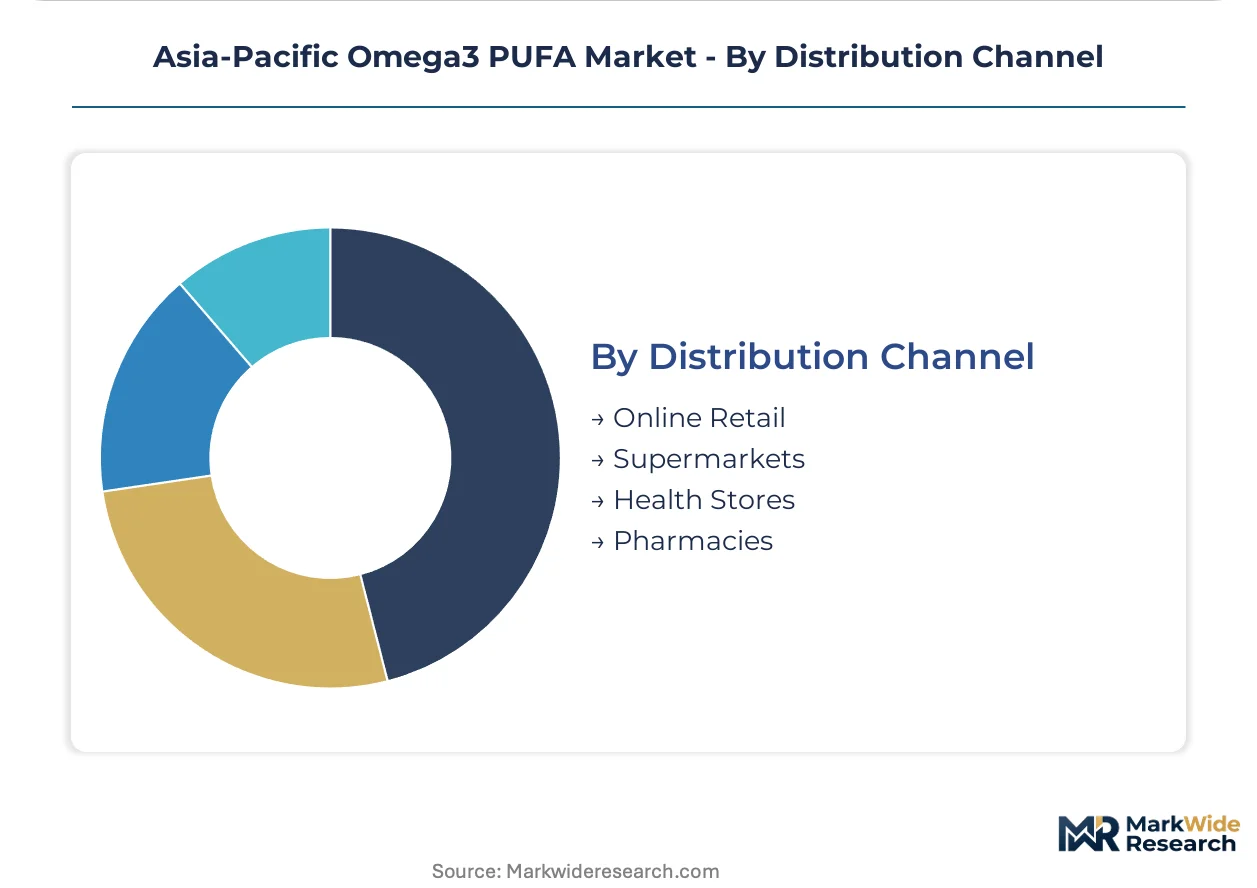
Distribution Channel:
Channel economics separate high-touch consultation environments from algorithm-driven discovery platforms.
- Online Retail:Cross-border e-commerce in China bypasses NMPA registration for gray-market concentrate imports. Seoul and Tokyo platforms report powder sachet velocities outpacing gelatin-capsule SKUs.
- Pharmacies:Japan's MHLW quasi-drug designation restricts pharmaceutical-grade omega3 to licensed dispensing. Trained consultation supports premium pricing for cardiovascular indication products.
- Supermarkets:Mass-market softgel placement in South Korean and Australian grocery chains competes on unit economics.
- Health Stores:Specialty retailers in India navigate FSSAI oxidation marker disclosure requirements with batch-tested inventory.
Customer acquisition costs are lowest through Online Retail. Trust transfer is strongest in Pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marine omega3 extraction infrastructure first scaled in Japan during the 1980s, establishing the region's foundational processing capabilities before Chinese fermentation platforms and Southeast Asian refining clusters emerged as volume centers.
China
Domestic thraustochytrid fermentation in Shanghai and Guangzhou biotech parks now supplies DHA concentrates for infant formula manufacturers ahead of NMPA novel food approvals. The national pharmaceutical regulator progressively tightens imported concentrate purity thresholds, aligning dioxin and PCB limits with EFSA benchmarks. Ningbo and Qingdao host the region's largest toll refining capacity for ethyl ester and triglyceride re-esterified formats.
Japan
MHLW quasi-drug designation restricts pharmaceutical-grade omega3 to licensed pharmacy channels, creating premium reimbursement pathways for cardiovascular indications. Powder-format functional foods displace softgel dominance in Tokyo retail as younger demographics favor on-the-go dissolution. The Kansai corridor maintains legacy cod liver oil supplement positioning through established distribution networks.
India
FSSAI mandates label disclosure of EPA/DHA ratios and oxidation markers, compelling domestic brands to upgrade analytical capabilities and sourcing standards. Health stores in Mumbai and Delhi navigate batch-tested inventory requirements with specialized supply chains. The country's food safety regulator enforces progressive purity thresholds that filter out lower-grade imports.
South Korea
MFDS expanded health claim recognition for cardiovascular endpoints opens direct-to-consumer positioning beyond generic supplement classification. Seoul e-commerce platforms report concentrate powder velocities outpacing gelatin-capsule SKUs within the omega3 category. The regulator's functional food pathway attracts regional brands seeking differentiated positioning.
Vietnam and Indonesia
Southeast Asian supplement markets lack established omega3 consumption habits, presenting first-mover positioning for powder-format functional foods. Aquaculture feed in Ho Chi Minh City and Jakarta drives bulk fish oil offtake with limited specification overhead. Domestic refining infrastructure remains underdeveloped, creating import dependency for concentrate supply.
Asia-Pacific Omega3 PUFA Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification-grade stratification, with pharmaceutical-grade GMP validation separating quasi-drug qualification from mass-market supplement positioning. The vendor base organizes around three strategic archetypes: fermentation-based algal platforms, vertically controlled Antarctic harvesting operations, and bulk marine concentrate refiners. Competitive moves concentrate on supercritical CO2 extraction licensing and backward integration into strain optimization laboratories.
Within the fermentation-platform tier, Koninklijke DSM N.V. and Corbion N.V. exemplify premium positioning through algal-derived DHA supply chains. Aker BioMarine occupies a distinct position as the anchor for phospholipid-bound omega3 feedstock through Antarctic fleet control. Cargill and ADM represent scale-driven commodity supply to Southeast Asian feed manufacturers, with Cargill competing on volume in bulk fish oil concentrates.
| Leading Market Players |
|---|
| BASF SE |
| Corbion N.V |
| Koninklijke DSM N.V. |
| Croda International Plc |
| KD Pharma Group |
| Aker BioMarine |
| Cargill |
| ADM (Archer Daniels Midland Company) |
| Orkla ASA |
| Others |
Value Chain & Pricing Dynamics
NMPA's tightening dioxin and PCB thresholds for imported concentrates are forcing Chinese infant formula manufacturers toward domestic fermentation sources, compressing margins on legacy fish oil supply chains while elevating algal-derived DHA premiums. This specification-driven procurement shift is restructuring supplier pricing power across the Asia-Pacific Omega3 PUFA landscape.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels anchors the Asia-Pacific Omega3 PUFA market. Price differentiation hinges on GMP validation status and NMPA/MFDS import qualification completion, with pharmaceutical-grade concentrates commanding substantial premiums over bulk feed additives. Cost compression in standard-grade fish oil intensifies as Vietnamese and Indonesian toll refiners expand ethyl ester capacity. Feed manufacturers in Southeast Asia exhibit the highest price sensitivity, while Japanese quasi-drug channels tolerate premium positioning for cardiovascular indication products.
Supply Chain Analysis
Refrigerated ocean freight costs from Antarctic harvesting zones to Shanghai and Tokyo processing hubs constitute a material share of landed krill oil concentrate expenses. Supply concentrates in China, Peru, and Chile, with Peruvian anchovy catch fluctuations and El Niño cycles driving raw material volatility. The chain draws from wild-catch marine biomass, thraustochytrid fermentation broth, and Antarctic krill harvest as primary inputs. Single-fleet harvesting dominance for phospholipid-bound omega3 creates pronounced single-source vulnerability. Distribution runs through toll refiners in Ningbo and Qingdao, direct-to-consumer e-commerce platforms in Seoul and Tokyo, and licensed pharmacy channels in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific Omega3 PUFA market functions as a stable compounder, underpinned by regulatory ratcheting of purity standards that perpetually upgrade baseline demand toward premium-certified supply.
For Market Incumbents: To counter algal fermentation cost curves eroding fish oil margins, accelerate backward integration into strain optimization laboratories and secure captive thraustochytrid genetics through exclusive licensing arrangements. Expand GMP-validated capacity in Shanghai biotech parks ahead of NMPA novel food approval waves. For New Entrants and Emerging Players: Launch via direct-to-consumer powder sachet formats on Seoul and Tokyo e-commerce platforms, bypassing pharmaceutical-grade qualification timelines. Vietnam and Indonesia present the most penetrable white-space territories, where aquaculture feed relationships can anchor initial offtake before expanding into human supplement positioning. For Investors and Strategic Acquirers: Asymmetric upside sits with fermentation-platform specialists possessing proprietary DHA-rich microalgae strain libraries and NMPA pre-approval relationships. The five-to-ten year viability window favors targets with demonstrated scale-up from pilot to commercial bioreactor density. Watch for NMPA novel food ingredient approval announcements as the critical inflection signal for domestic algal oil demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Optimization Laboratory Acquisition | Proprietary thraustochytrid genetics lock in royalty-free DHA concentrate production for infant formula manufacturers. |
| GMP Facility Validation in Shanghai | NMPA-aligned manufacturing qualification opens quasi-drug reimbursement pathways for cardiovascular indication products. |
| Powder Format Production Line Conversion | Softgel-to-sachet unbundling captures Seoul and Tokyo demographic shifts toward on-the-go dissolution preferences. |
| Antarctic Fleet Capacity Expansion | Vertically controlled harvesting secures phospholipid-bound omega3 feedstock against quota volatility and climate-dependent catch windows. |
| Cross-Border E-Commerce Platform Partnership | Gray-market concentrate imports bypass NMPA registration timelines while building brand recognition ahead of formal approval. |
Study Parameters
Multiple input streams — regulatory filing analysis, customs trade records, and biotech fermentation capacity databases — were reconciled with primary interviews across fermentation platform executives, infant formula procurement directors, NMPA regulatory consultants, and Southeast Asian aquaculture feed formulators. Secondary validation drew from NMPA draft guideline publications, FSSAI labeling mandate circulars, MFDS functional food claim registers, and toll refiner capacity disclosures. Bottom-up volume modeling and top-down value reconciliation triangulated segment-level outputs.
Data-stream reconciliation across product chemistry, application certification tier, and end-user purchasing behavior generated the analytical framework. Segmentation dimensions modeled include extraction source, grade certification, formulation format, and regional regulatory cluster. CAGRs were derived from fitted growth curves against historical capacity expansion and qualification timeline data. Forecast inputs incorporated NMPA approval probability weightings and El Niño cycle anchovy biomass projections.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt NMPA guideline revisions or Antarctic krill quota suspensions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
Africa Algae Omega-3 Ingredients Market
Functional Food & Ingredients
APAC Heart Health Functional Food Market
Functional Food & Ingredients
South America Omega-3 PUFA Market
Functional Food & Ingredients
Sacha Inchi Protein Market
Functional Food & Ingredients
Mediterranean Pre-Diabetes Ingredient Concepts Market
Functional Food & Ingredients
Europe Omega-3 PUFA Market
Functional Food & Ingredients
Europe Sterol Market
Functional Food & Ingredients
Multifunctional Food Ingredients Market
Functional Food & Ingredients
Functional Ingredients Market
Functional Food & Ingredients
Africa Omega-3 PUFA Market
Functional Food & Ingredients
Banana Leaf Extract Market
Functional Food & Ingredients
Brazil Flavored and Functional Water Market
Functional Food & Ingredients
Europe Prebiotic Ingredient Market
Functional Food & Ingredients
Poultry Probiotic Ingredients Market
Functional Food & Ingredients
Low-Carb Low-Fat Meal Market
Functional Food & Ingredients
Beta Glucan and Fucoidan Market