
 South America Omega-3 PUFA Market | 2026-2036
South America Omega-3 PUFA Market Size, Share, and Industry Trends Forecast 2026-2036
South America Omega-3 PUFA Market Analytics
ANVISA's updated Good Manufacturing Practices for dietary supplements is broadening compliance costs for new entrants while advantaging incumbent operators with established quality systems. Croda International Plc leverages its lipid chemistry expertise to sustain premium positioning across pharmaceutical-grade concentrates. Cargill anchors its South American presence through integrated supply chains linking Peruvian anchovy fisheries to Brazilian processing facilities. DSM differentiates via microencapsulation technologies that extend stability profiles for tropical climate distribution.
South America Omega-3 PUFA denotes long-chain polyunsaturated fatty acids—principally eicosapentaenoic acid and docosahexaenoic acid—extracted from marine biomass or cultivated microalgae, typically standardized to concentrations between 30% and 90% active fatty acids by weight, and deployed for cardiovascular risk modulation, neurodevelopmental support, and anti-inflammatory therapeutic protocols. Fish oil occupies the dominant volume position due to established extraction infrastructure along the Pacific coast, while algal oil captures accelerating interest among vegan-formulation dietary supplement brands seeking to bypass marine resource constraints. Softgel formats lead pharmaceutical dispensing channels, though powder applications in functional food fortification represent the fastest-expanding margin pool as Brazilian processors integrate omega-3 into dairy and bakery matrices.
Brazil's ANVISA, Argentina's national food and drug administration, and MERCOSUR's harmonized technical regulations collectively govern ingredient purity thresholds, label claims substantiation, and cross-border trade facilitation for omega-3 products across the customs union. These frameworks elevate documentation burdens for imported concentrates while creating preferential market access for regional manufacturers meeting bloc-standard specifications. Stakeholders must monitor pending MERCOSUR revisions to maximum permissible oxidation indices, as tighter rancidity standards would force capital redeployment toward cold-chain infrastructure and antioxidant formulation investments.
Market Dynamics
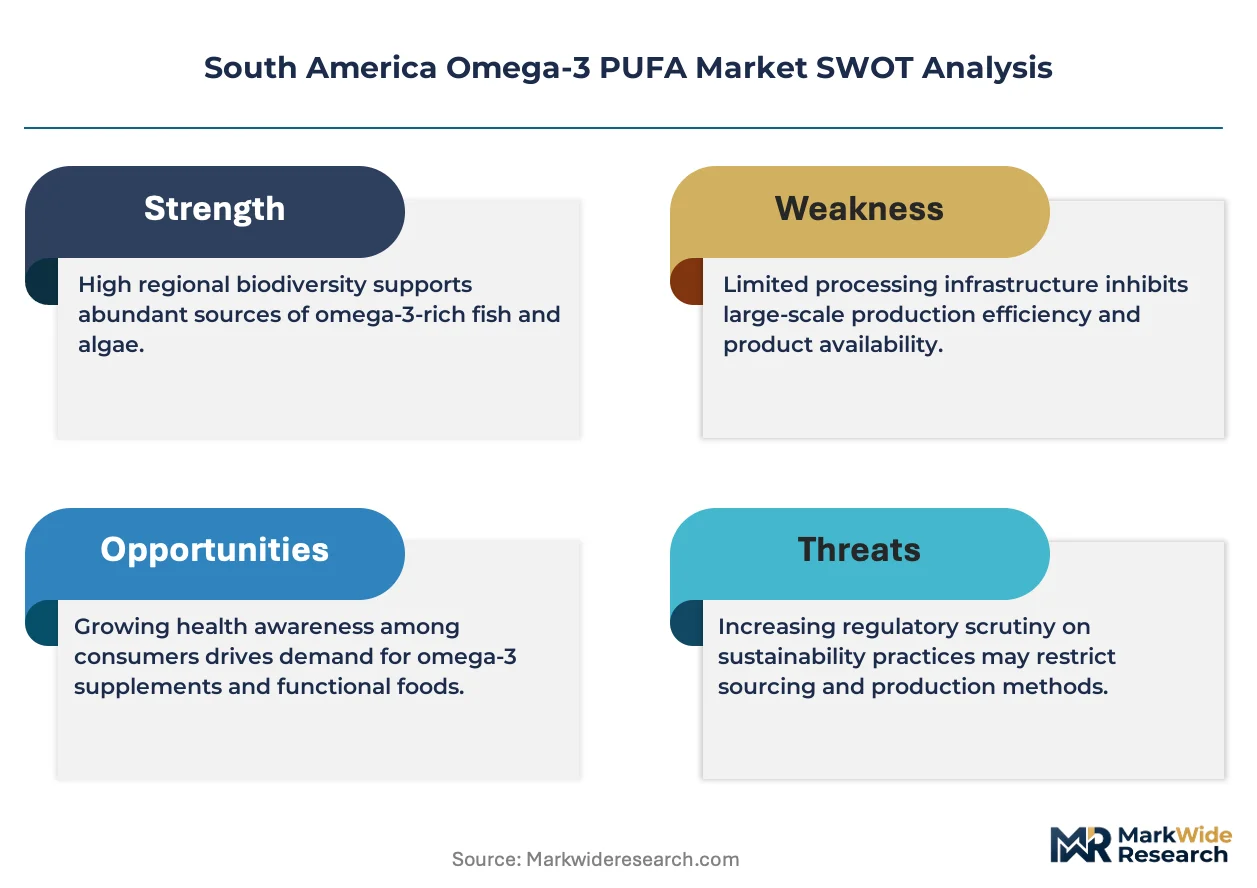
ANVISA's compression of nutraceutical approval timelines is accelerating novel delivery format commercialization, while Peruvian anchovy supply concentration forces Brazilian formulators to build buffer inventory positions against El Niño volatility.
Growth Catalysts
- Cardiovascular protocol integration:Brazilian and Argentine pharmaceutical formulators are embedding EPA and DHA into chronic disease management guidelines, expanding prescriptive dispensing volumes through hospital pharmacy networks.
- MERCOSUR harmonization:The customs union's technical regulations are creating preferential market access for regional manufacturers meeting bloc-standard oxidation index and purity specifications.
- Microencapsulation advances:Tropical climate stability requirements are driving adoption of advanced lipid protection technologies that extend shelf life for powder fortification applications in dairy and bakery matrices.
Market Restraints
- Anchovy biomass volatility:Peruvian fishery yields fluctuate with Pacific temperature oscillations, concentrating input risk in a single geography and forcing price spikes during El Niño events.
- ANVISA compliance escalation:Updated Good Manufacturing Practices for dietary supplements are elevating documentation and quality system investments, disadvantaging smaller importers against incumbent operators with established infrastructure.
- Algal oil cost premium:Microalgae cultivation and extraction processes remain substantially more expensive than marine fish oil refining, limiting vegan-format penetration to premium-positioned supplement brands.
Strategic Opportunities
- Andean export channel expansion:São Paulo's manufacturing base is underutilized for Andean markets, presenting white space for Brazilian processors to capture share in Colombia, Chile, and Ecuador through MERCOSUR trade facilitation.
- Functional food fortification:Powder omega-3 applications in Brazilian dairy and bakery matrices represent an emerging margin pool as processors seek differentiation through nutritional enhancement claims.
- Cold-chain infrastructure investment:Pending MERCOSUR revisions to maximum permissible oxidation indices will reward early movers deploying antioxidant formulation and temperature-controlled logistics capabilities.
Industry Challenges
- Lipid chemistry talent scarcity:Formulation expertise in pharmaceutical-grade concentrate processing is concentrated among a small cohort of specialists, constraining Brazilian and Argentine capacity expansion timelines.
- Cross-border certification complexity:Divergent documentation requirements between ANVISA, Argentina's national food and drug administration, and MERCOSUR technical committees create approval friction for novel delivery formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Omega-3 PUFA Market |
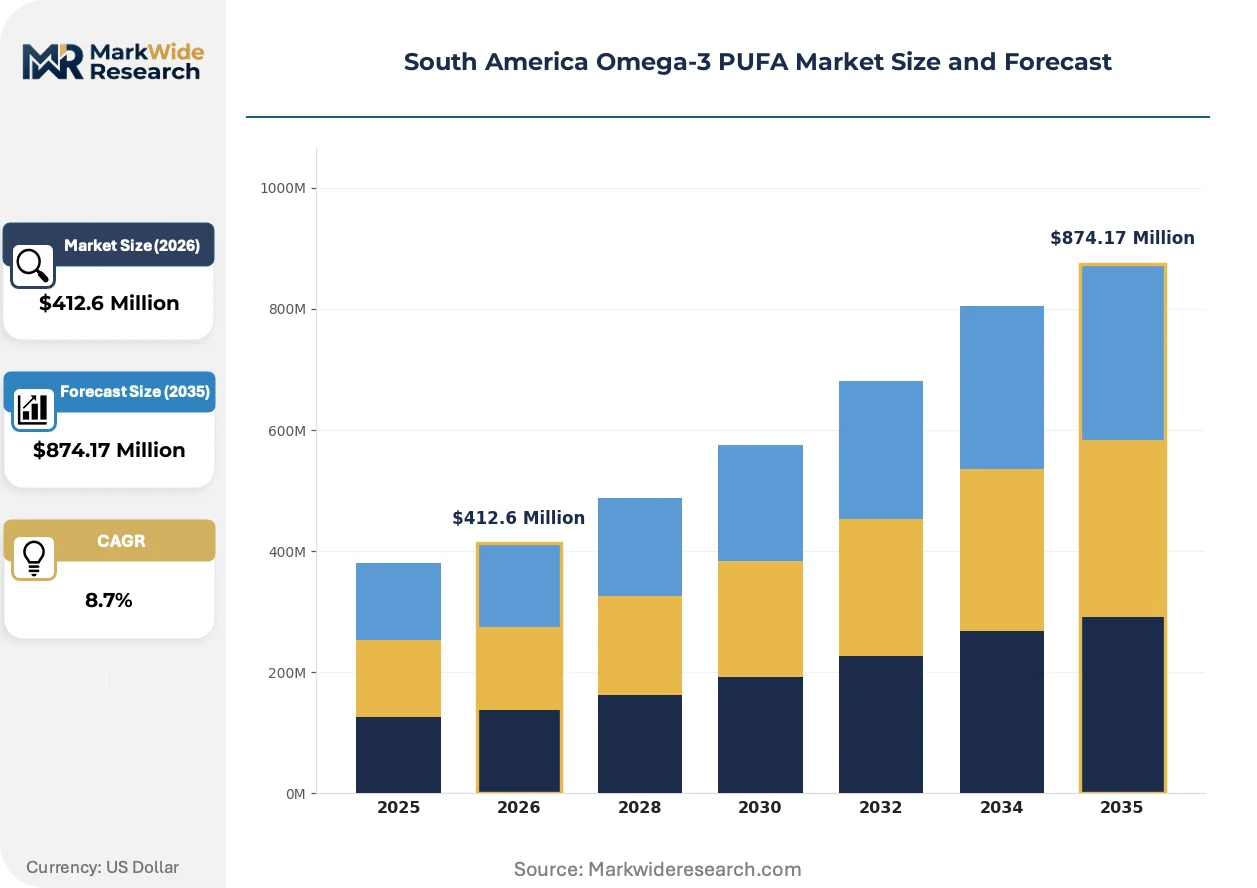
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Oil, Algal Oil, Krill Oil, Omega-3 Concentrates End User: Food & Beverage, Pharmaceuticals, Dietary Supplements, Animal Nutrition Form: Capsules, Powder, Liquid, Softgels Application: Heart Health, Cognitive Function, Joint Health, Skin Health |
| Companies Covered | Croda International Plc, Naturmega, Cargill, Omega Protein Corporation, GC Rieber Oils, DSM, BASF SE, OLVEA Fish Oils, Pharma Marine AS, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Omega-3 PUFA Market Evolving Landscape
Delivery format diversification and climate-adapted stabilization technologies are compressing traditional softgel dominance while reshaping competitive positioning around formulation expertise rather than raw material access alone.
Microencapsulation via complex coacervation and spray-drying is electrifying powder omega-3 production for functional food integration. Brazilian dairy processors are adopting these lipid protection systems at accelerating pace to fortify yogurt and bread matrices. This technological shift is compressing the historical boundary between pharmaceutical and food-grade omega-3 supply chains.
ANVISA's evolving nutraceutical registration pathways are streamlining approval timelines for novel delivery formats while tightening post-market surveillance obligations. The regulatory friction reduction is lowering barriers for imported concentrate entrants, though incumbent operators with established quality systems retain compliance cost advantages. Brazilian pharmaceutical formulators are responding by accelerating dossier preparation for softgel alternatives.
Hospital pharmacy procurement consolidation is displacing fragmented retail supplement purchasing for cardiovascular and neurodevelopmental indications. Argentine and Brazilian public health systems are centralizing omega-3 sourcing through tender mechanisms that favor suppliers with integrated quality documentation. This pattern is most visible in São Paulo's southeast corridor, where manufacturing proximity to institutional buyers shapes contract allocation.
South America Omega-3 PUFA Market Segmentation
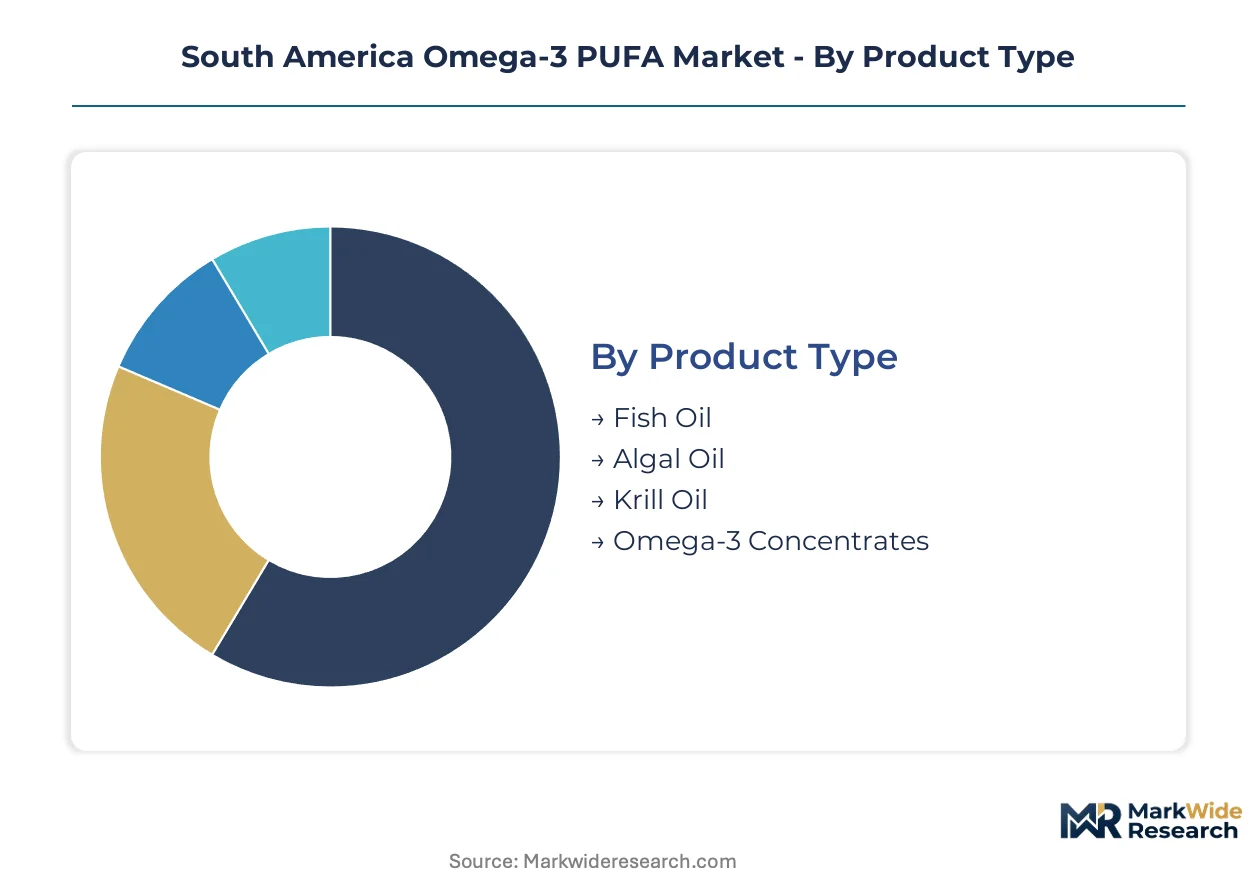
Omega-3 PUFA segmentation in South America reflects divergent supply chain architectures and regulatory pathways. Each dimension captures distinct margin structures, from commodity fish oil refining to pharmaceutical-grade concentrate formulation.
Product Type:
Integration depth varies sharply across source materials, with marine extraction dominating volume and algal cultivation commanding premium positioning for vegan formulations.
- Fish Oil:Extracted from Peruvian anchovy biomass and standardized to 30-60% EPA/DHA concentrations. Brazilian pharmaceutical formulators in São Paulo's southeast corridor absorb the majority of regional supply for cardiovascular protocol integration.
- Algal Oil:Cultivated from Schizochytrium or Crypthecodinium microalgae strains, delivering DHA-dominant profiles without marine resource dependencies. Argentine dietary supplement brands targeting vegan positioning drive uptake despite substantial cost premiums over marine alternatives.
- Krill Oil:Antarctic-derived phospholipid-bound omega-3 with superior bioavailability claims.
- Omega-3 Concentrates:Pharmaceutical-grade distillations exceeding 80% active fatty acids for prescriptive dispensing.
Volume placements concentrate in Fish Oil; the faster expansion belongs to Algal Oil.
End User:
Cost tier stratification separates commodity feed applications from high-margin pharmaceutical formulations, with regulatory intensity escalating across the value chain.
- Pharmaceuticals:ANVISA-registered concentrates for chronic disease management protocols. Brazilian hospital pharmacy networks in São Paulo and Rio de Janeiro centralize procurement through tender mechanisms demanding integrated quality documentation.
- Dietary Supplements:Over-the-counter softgels and capsules for wellness positioning. Argentine retail channels show accelerating preference for algal-derived vegan formats as consumer segmentation sharpens.
- Food & Beverage:Microencapsulated powders for dairy and bakery fortification.
- Animal Nutrition:Feed-grade fish oil for aquaculture and livestock omega-3 enrichment.
Revenue concentration sits with Pharmaceuticals; steepest expansion trajectory emerges in Food & Beverage as Brazilian processors integrate nutritional enhancement claims.
Form:
Supply concentration patterns favor softgel infrastructure investment, though powder applications are gaining share through functional food channel development.
- Softgels:Gelatin-encapsulated liquid fills dominating pharmaceutical dispensing. São Paulo's manufacturing base maintains excess capacity serving both domestic and Andean export channels.
- Powder:Spray-dried or complex coacervation microencapsulates for thermal stability in food matrices. Brazilian dairy processors adopt these systems for yogurt fortification at accelerating pace.
- Capsules:Hard-shell alternatives for vegetarian formulation requirements.
- Liquid:Bulk concentrates for industrial food processing and compounding pharmacies.
Softgels retain volume dominance; powder formats are climbing the fastest as bakery and dairy integration deepens.
Application:
Clinical substantiation intensity varies by therapeutic claim, with cardiovascular indications commanding the most rigorous documentation standards.
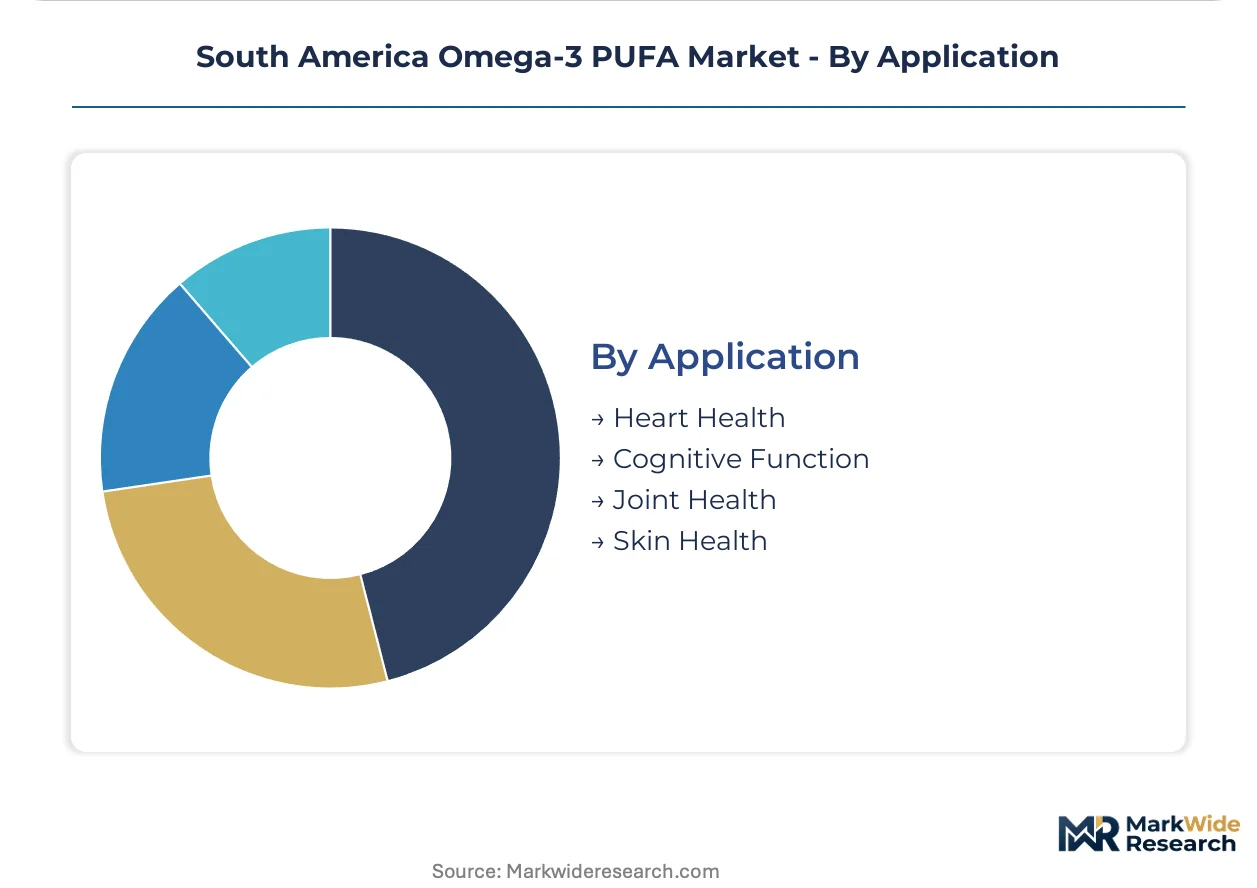
- Heart Health:EPA-dominant protocols for triglyceride reduction and arrhythmia risk modulation. Brazilian public health system formularies increasingly embed these supplements into chronic disease management guidelines.
- Cognitive Function:DHA-focused applications for neurodevelopmental support in prenatal and pediatric populations. Argentine maternal health programs drive institutional purchasing concentration.
- Joint Health:Anti-inflammatory positioning for osteoarthritis symptom management.
- Skin Health:Cosmetic and dermatological applications for barrier function support.
Heart Health maintains the largest revenue base; Cognitive Function applications are gaining share fastest through prenatal health program expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manaus Free Trade Zone incentives concentrate pharmaceutical-grade processing capacity in Brazil's northern corridor, while São Paulo's manufacturing base anchors downstream formulation for domestic and Andean export channels.
Brazil
ANVISA's evolving nutraceutical registration pathways compress approval timelines for novel delivery formats. São Paulo's southeast corridor hosts the densest cluster of softgel manufacturers serving hospital pharmacy networks. Brazilian pharmaceutical formulators embed EPA and DHA into chronic disease management guidelines, expanding prescriptive dispensing volumes.
Argentina
The national food and drug administration governs ingredient purity thresholds alongside MERCOSUR harmonized technical regulations. Buenos Aires and Córdoba concentrate dietary supplement brands targeting vegan positioning with algal-derived formats. Public health system tender mechanisms centralize omega-3 sourcing for cardiovascular protocols.
Chile
Peruvian anchovy supply chains feed Chilean processing facilities for export-grade concentrate production. Santiago's regulatory alignment with MERCOSUR standards facilitates cross-border trade facilitation. Cold-chain infrastructure investments in Valparaíso respond to pending oxidation index revisions.
Colombia
Bogotá's pharmaceutical distributors absorb Brazilian-manufactured omega-3 through MERCOSUR trade preferences. The Andean nation's hospital pharmacy procurement consolidation mirrors Brazilian tender mechanisms. Regional manufacturers leverage bloc-standard specifications for preferential market access.
Peru
Pacific coast extraction infrastructure dominates marine biomass supply for regional omega-3 refining. El Niño temperature oscillations force Brazilian formulators to build buffer inventory positions against yield volatility. Lima-based fishery operations anchor the raw material tier for South American concentrate production.
South America Omega-3 PUFA Market Competitive Landscape
Peruvian fishery operators anchor the raw material tier; European and North American specialists hold premium concentrate and formulation capabilities. Market structure concentrates among integrated multinationals with lipid chemistry expertise and established ANVISA quality systems. Three archetypes dominate: marine biomass extractors, pharmaceutical-grade refiners, and microencapsulation technology providers. Competitive moves center on backward integration into Peruvian supply chains and capacity expansion for powder format production.
Within the pharmaceutical-grade refiner tier, Croda International Plc and GC Rieber Oils exemplify European specialists with premium positioning across concentrate formulations. Cargill represents the integrated multinational archetype with South American presence through supply chain linkages. These three companies occupy positions that reflect divergent strategic emphases: lipid chemistry expertise, integrated biomass-to-refining operations, and global scale logistics respectively.
| Leading Market Players |
|---|
| Croda International Plc |
| Naturmega |
| Cargill |
| Omega Protein Corporation |
| GC Rieber Oils |
| DSM |
| BASF SE |
| OLVEA Fish Oils |
| Pharma Marine AS |
| Others |
Value Network & Pricing Analysis
Pharmaceutical-grade concentrate premiums over commodity fish oil feedstock diverge sharply across the South American Omega-3 PUFA market, with that bifurcation manifesting in both spot-market volatility for Peruvian anchovy-derived inputs and long-term offtake premiums commanded by ANVISA-registered formulators in São Paulo's manufacturing corridor. This tiered cost structure rewards backward-integrated operators with captive supply arrangements while exposing spot-market buyers to El Niño-driven price spikes.
Pricing Analysis
Short lead-time premiums for pharmaceutical-grade concentrates command substantial markups over spot fish oil purchases, while inventory-heavy buyers capture discounts during El Niño supply disruptions. Three-tier pricing structure across pharmaceutical, food-grade, and feed-grade levels separates ANVISA-registered formulators from commodity refiners. Cost compression in commodity fish oil is intensifying because Peruvian fishery yield volatility forces Brazilian processors to carry expensive buffer stocks. Hospital pharmacy networks show least price sensitivity due to tender-based procurement; dietary supplement brands exhibit highest sensitivity to input cost fluctuations.
Supply Chain Analysis
ANVISA's domestic-content preferences for MERCOSUR-registered products are reshaping sourcing patterns toward Brazilian and Argentine processing facilities. Geographic supply concentration centers on Peru for marine biomass extraction, Brazil for pharmaceutical formulation, and Chile for export-grade concentrate refining. Raw material dependencies rest on Peruvian anchovy biomass, Antarctic krill phospholipids, and Schizochytrium microalgae cultivation. Single-source vulnerability in Peruvian fishery yields exposes regional formulators to climate-driven supply interruptions. Distribution runs through São Paulo's manufacturing base serving hospital pharmacy networks and Andean export channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South American Omega-3 PUFA market structure favors consolidation plays as ANVISA compliance escalation forces subscale importers to exit, concentrating share among incumbent operators with established quality systems.
For Market Incumbents: Cement market position through captive supply arrangements with Peruvian fishery operators and accelerated microencapsulation capacity expansion in São Paulo's southeast corridor. Threat substitution from algal-derived vegan formats demands defensive patent positioning around lipid stabilization technologies. Certification investment in MERCOSUR oxidation index compliance represents the critical lever for tender participation in consolidated hospital pharmacy procurement.
For New Entrants and Emerging Players: Capture white space in Colombian and Ecuadorian Andean markets through MERCOSUR trade facilitation, where Brazilian-manufactured omega-3 faces limited local competition. The most penetrable segment lies in microencapsulated powder applications for Brazilian dairy fortification, where technical formulation barriers are lower than pharmaceutical-grade concentrates. Go-to-market execution should emphasize direct technical partnership with yogurt and bakery processors seeking nutritional enhancement differentiation.
For Investors and Strategic Acquirers: Re-rating potential sits with microencapsulation technology specialists given accelerating functional food integration and pending MERCOSUR oxidation index revisions. Long-term viability across the analysis window hinges on backward integration into climate-resilient supply chains. Acquisition targets should display established ANVISA quality systems and active dossier pipelines for novel delivery formats. The signal to watch is hospital pharmacy tender award concentration rates in São Paulo and Rio de Janeiro metropolitan networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Peruvian Fishery Supply | Captive anchovy biomass access insulates Brazilian formulators from El Niño price volatility. |
| Microencapsulation Capacity Expansion | Spray-drying and complex coacervation investments capture powder format growth in dairy fortification. |
| ANVISA Quality System Certification | Registered facility status unlocks hospital pharmacy tender participation against unregistered imports. |
| MERCOSUR Trade Route Development | Preferential bloc access enables São Paulo manufacturers to serve underpenetrated Andean markets. |
| Algal Oil Cultivation Partnership | Schizochytrium supply agreements address vegan-format demand from Argentine dietary supplement brands. |
Research Methodology
Independent corroboration across primary interviews with pharmaceutical formulators, hospital procurement managers, and Peruvian fishery operators underwrites the qualitative findings presented in this study. Secondary validation draws from ANVISA registration databases, MERCOSUR technical regulation filings, and Peruvian production statistics. Bottom-up demand modeling triangulates against top-down supply-side capacity assessments across Brazilian and Chilean processing facilities.
Comparable-period anchoring connects historical reference data to projection assumptions across the analysis window, with segmentation modeling spanning source material tier, end-use application, delivery format, and therapeutic indication. CAGRs derive from regression analysis against cardiovascular protocol adoption rates, functional food integration trajectories, and regulatory approval velocity. Industry-specific inputs include El Niño frequency projections and hospital pharmacy procurement consolidation patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MERCOSUR oxidation index revisions, algal oil cost curve trajectories, and Peruvian fishery yield volatility. Forecasts reflect documented assumptions regarding regulatory pathway timelines and raw material supply stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
APAC Heart Health Functional Food Market
Functional Food & Ingredients
Brazil Flavored and Functional Water Market
Functional Food & Ingredients
Multifunctional Food Ingredients Market
Functional Food & Ingredients
Africa Omega-3 PUFA Market
Functional Food & Ingredients
Sacha Inchi Protein Market
Functional Food & Ingredients
Functional Ingredients Market
Functional Food & Ingredients
Healthy Fats Low Carb Market
Functional Food & Ingredients
Protein Cookie Market
Functional Food & Ingredients
Poultry Probiotic Ingredients Market
Functional Food & Ingredients
South America Prebiotic Ingredients Market
Functional Food & Ingredients
Refined Functional Carbohydrates Market
Functional Food & Ingredients
Brominated Vegetable Oil Market
Functional Food & Ingredients
Europe Omega-3 PUFA Market
Functional Food & Ingredients
Omega 3 PUFA Market
Functional Food & Ingredients
Mediterranean Pre-Diabetes Ingredient Concepts Market
Functional Food & Ingredients
Africa Algae Omega-3 Ingredients Market