
 Europe Sterol Market | 2026-2036
Europe Sterol Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sterol Market Foresight
Plant-based extraction methods are tilting sterol production away from traditional solvent-based processes toward supercritical CO2 and enzymatic refinement. BASF SE leverages its integrated biotechnology platforms to secure feedstock advantages across German manufacturing hubs. Cargill sustains broad sourcing networks that span multiple European oilseed processing corridors. Raisio Oyj anchors its position through specialized stanol production tied to Nordic oat supply chains.
Sterols comprise a class of steroid alcohols including phytosterols, stanols, and ergosterol, typically extracted from vegetable oils and tall oil pitch through crystallization or molecular distillation at purity thresholds exceeding 95%. These compounds function primarily as cholesterol-lowering agents in functional foods and as precursors for vitamin D2 synthesis in pharmaceutical applications. Phytosterols dominate volume flows through food and beverages applications where EFSA-approved health claims support premium positioning. Stanols command higher margin pools in pharmaceutical-grade formulations despite smaller throughput. Powder and liquid forms split demand between industrial-scale food manufacturing and precision-dosing nutraceutical applications.
EFSA health claim regulations under Regulation 1924/2006 shape product formulation standards and label compliance costs across EU member states. REACH and EU Green Deal sustainability criteria are tightening feedstock traceability requirements for tall oil and vegetable oil derivatives. The EU F-Gas Regulation indirectly affects extraction equipment specifications in solvent-based operations. Stakeholders must monitor evolving EFSA opinions on novel sterol delivery mechanisms and pre-empt supply chain audits for bio-based content verification.
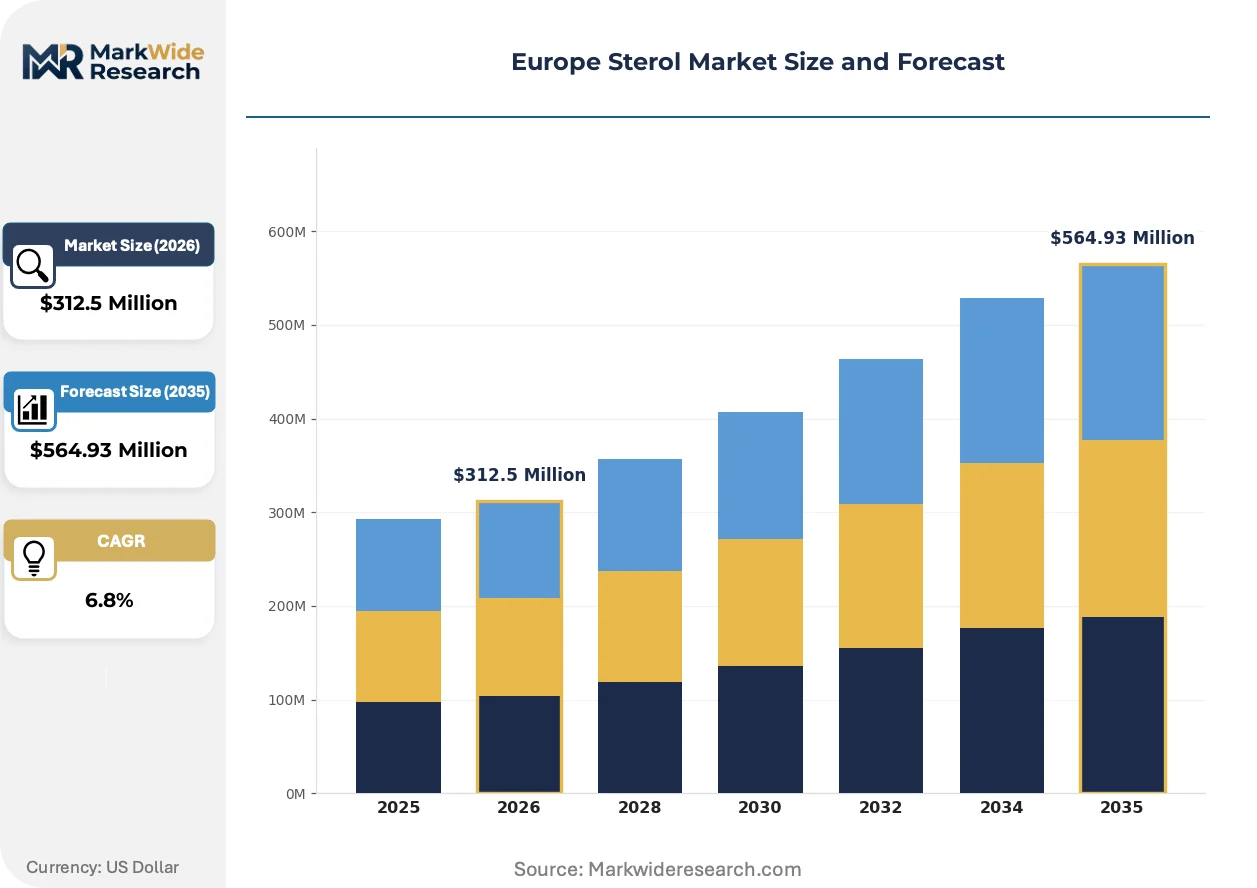
Market Dynamics
EFSA health claim enforcement under Regulation 1924/2006 is compressing formulation timelines and forcing simultaneous reformulation across German, French, and Dutch manufacturing bases. This regulatory pressure is reshaping competitive positioning by privileging vertically integrated sterol suppliers with in-house clinical substantiation capabilities.
Growth Catalysts
- Phytosterol fortification mandates:Functional dairy processors in Germany are expanding sterol dosing in spreads and yogurts to capture EFSA-approved cholesterol-lowering label claims.
- REACH bio-based traceability:EU Green Deal sustainability criteria are accelerating tall oil pitch sourcing audits and certifying supply chains for pharmaceutical-grade stanol production.
- Supercritical CO2 extraction:This solvent-free technology is displacing hexane-based crystallization in Nordic oat processing corridors, reducing residual solvent compliance costs.
Market Restraints
- Vegetable oil feedstock volatility:Rapeseed and sunflower oil price swings in Black Sea sourcing regions compress sterol producer margins during contract renegotiations.
- Tall oil supply concentration:Scandinavian pulp mill integration limits independent sterol refiner access to pitch feedstock, creating bottleneck risk for stanol manufacturers.
- EFSA novel delivery opinion delays:Pending EFSA evaluations of nano-emulsified sterol formats are freezing R&D pipelines and extending time-to-market for encapsulation innovators.
Strategic Opportunities
- Polish and Romanian nutraceutical penetration:Underdeveloped functional food markets in Eastern Europe offer first-mover positioning for phytosterol-fortified bakery and meat applications.
- CSRD sustainability reporting:Mandatory EU corporate sustainability disclosures are creating premium pricing tiers for sterol suppliers with verified carbon-negative extraction credentials.
- Enzymatic refinement convergence:Integration of lipase biocatalysis with membrane filtration is opening pharmaceutical-grade purity thresholds at food-grade cost structures.
Industry Challenges
- Phytochemistry analytical talent scarcity:European universities are producing insufficient sterol stereochemistry specialists to staff quality control laboratories expanding for EFSA compliance.
- Multi-jurisdiction certification timelines:Parallel EFSA novel food and REACH substance evaluation processes are extending product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sterol Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phytosterols, Stanols, Ergosterol, Cholesterol Application: Food & Beverages, Pharmaceuticals, Cosmetics, Animal Feed Form: Powder, Liquid, Granules, Tablets End User: Food Manufacturers, Pharmaceutical Companies, Nutraceutical Firms, Research Institutions |
| Companies Covered | BASF SE, Archer Daniels Midland Company, Cargill, Raisio Oyj, Gustav Parmentier GmbH, DuPont de Nemours, Inc., Arboris, LLC, Kerry Group plc, FMC Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sterol Market Shifts & Advancements
Biotechnology platforms are collapsing traditional extraction economics while regulatory digitization and buyer consolidation are rewiring how sterol specifications propagate through European supply chains.
Supercritical CO2 extraction with integrated online chromatographic monitoring is collapsing the cost gap between food-grade and pharmaceutical-grade sterol purification. Dutch toll manufacturers are adopting these systems to serve both nutraceutical compounders and vitamin D2 precursor buyers from single production campaigns. The technology is collapsing legacy batch crystallization capacity utilization rates as continuous processing enables just-in-time sterol esterification.
EU F-Gas Regulation phase-down schedules are forcing solvent-based extraction equipment retrofits across Spanish and Italian vegetable oil refineries. This policy compression is redirecting capital expenditure toward sealed-loop systems with heat pump integration, particularly affecting mid-scale sterol producers dependent on legacy hexane infrastructure. Southern European processors are responding by consolidating tolling relationships with Northern European supercritical CO2 operators.
Long-term offtake contracting is displacing spot purchasing in German and French functional food manufacturing. Procurement departments at dairy multinationals are locking 3-5 year sterol supply agreements with fixed purity escalators, squeezing trading house intermediaries and forcing direct processor-to-manufacturer relationships. This pattern is most visible in Benelux margarine manufacturing clusters where buyer consolidation has reduced qualified supplier pools.
Europe Sterol Market Segmentation
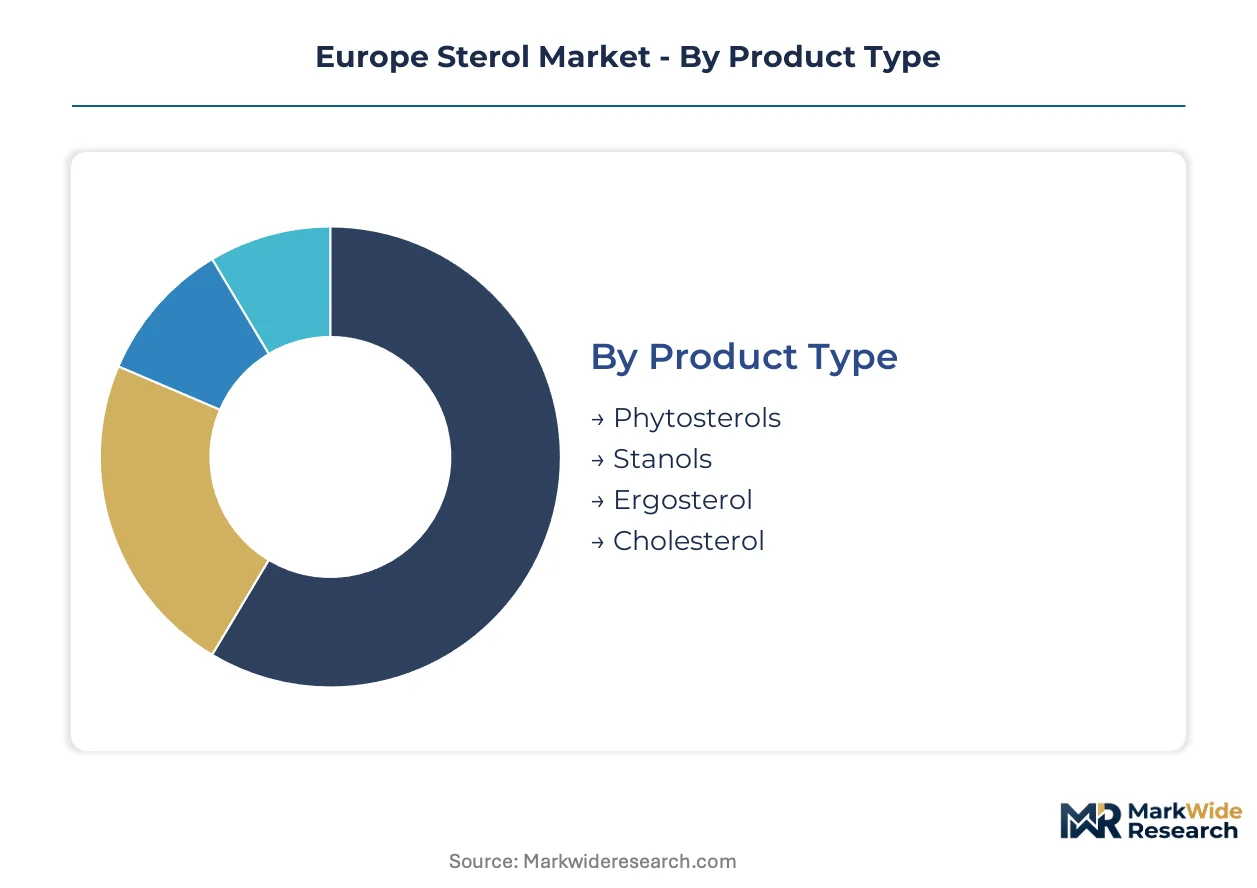
Sterol procurement patterns diverge sharply across European markets based on regulatory claim requirements, extraction purity thresholds, and end-use formulation complexity. Understanding these segment boundaries reveals where margin pools concentrate and which technical specifications command premium positioning.
Product Type:
Cost tier differentiation separates commodity phytosterol flows from pharmaceutical-grade stanol premiums, with extraction method and stereochemical purity driving the price architecture.
- Phytosterols:These plant-derived steroid alcohols, extracted from vegetable oils and tall oil pitch at 95%+ purity, dominate volume flows through German and French functional dairy manufacturing. EFSA-approved cholesterol-lowering health claims under Regulation 1924/2006 anchor premium positioning in spreads and yogurts.
- Stanols:Hydrogenated phytosterol variants command elevated margin pools in pharmaceutical-grade formulations despite smaller throughput, with Nordic oat supply chains providing specialized feedstock for saturated sterol production. REACH bio-based traceability requirements tighten sourcing audits for stanol manufacturers dependent on Scandinavian pulp mill integration.
- Ergosterol:Fungal-derived provitamin D2 serves as the primary precursor for vitamin D2 synthesis in pharmaceutical applications, with Dutch toll manufacturers processing ergosterol for both nutraceutical compounders and synthetic vitamin producers.
- Cholesterol:Animal-derived sterol finds limited pharmaceutical and research applications, constrained by plant-based formulation trends and EFSA novel food evaluation timelines for non-phytosterol cholesterol claims.
Phytosterols hold installed capacity. Stanols is rotating up the share rankings.
Application:
Application focus determines regulatory pathway complexity, with EFSA health claim substantiation creating divergent compliance cost structures across food, pharmaceutical, and cosmetic uses.
- Food & Beverages:Functional dairy processors in Germany and Benelux margarine clusters drive phytosterol esterification demand, with 3-5 year offtake contracts displacing spot purchasing and squeezing trading house intermediaries.
- Pharmaceuticals:Stanol and ergosterol precursors for vitamin D2 synthesis require pharmaceutical-grade purity thresholds, with supercritical CO2 extraction systems collapsing the cost gap between food-grade and pharmaceutical-grade purification campaigns.
- Cosmetics:Emollient and barrier-function applications for phytosterol derivatives serve formulators seeking bio-based alternatives to synthetic emulsifiers, though smaller volumes limit dedicated production line investment.
- Animal Feed:Growth promotion and feed efficiency applications concentrate in Eastern European markets, with Polish and Romanian nutraceutical penetration offering first-mover positioning for sterol-fortified livestock nutrition.
Food & Beverages maintains volume leadership. Pharmaceuticals is climbing the fastest on margin expansion.
Form:
Volume scale and precision-dosing requirements split demand between industrial-scale manufacturing inputs and consumer-facing nutraceutical delivery formats.
- Powder:Free-flowing phytosterol and stanol powders serve industrial-scale food manufacturing, with spray-dried and micronized grades enabling uniform dispersion in spreads and bakery matrices.
- Liquid:Oil-dispersed and esterified liquid forms facilitate precision-dosing in nutraceutical applications and continuous processing in dairy manufacturing lines.
- Granules:Agglomerated formats improve handling characteristics for direct compression tableting and animal feed pelleting operations.
- Tablets:Finished dosage forms concentrate in pharmaceutical and nutraceutical firm procurement, with pending EFSA evaluations of nano-emulsified formats freezing some R&D pipelines.
Powder commands installed capacity. Liquid is gaining share fastest on processing efficiency advantages.
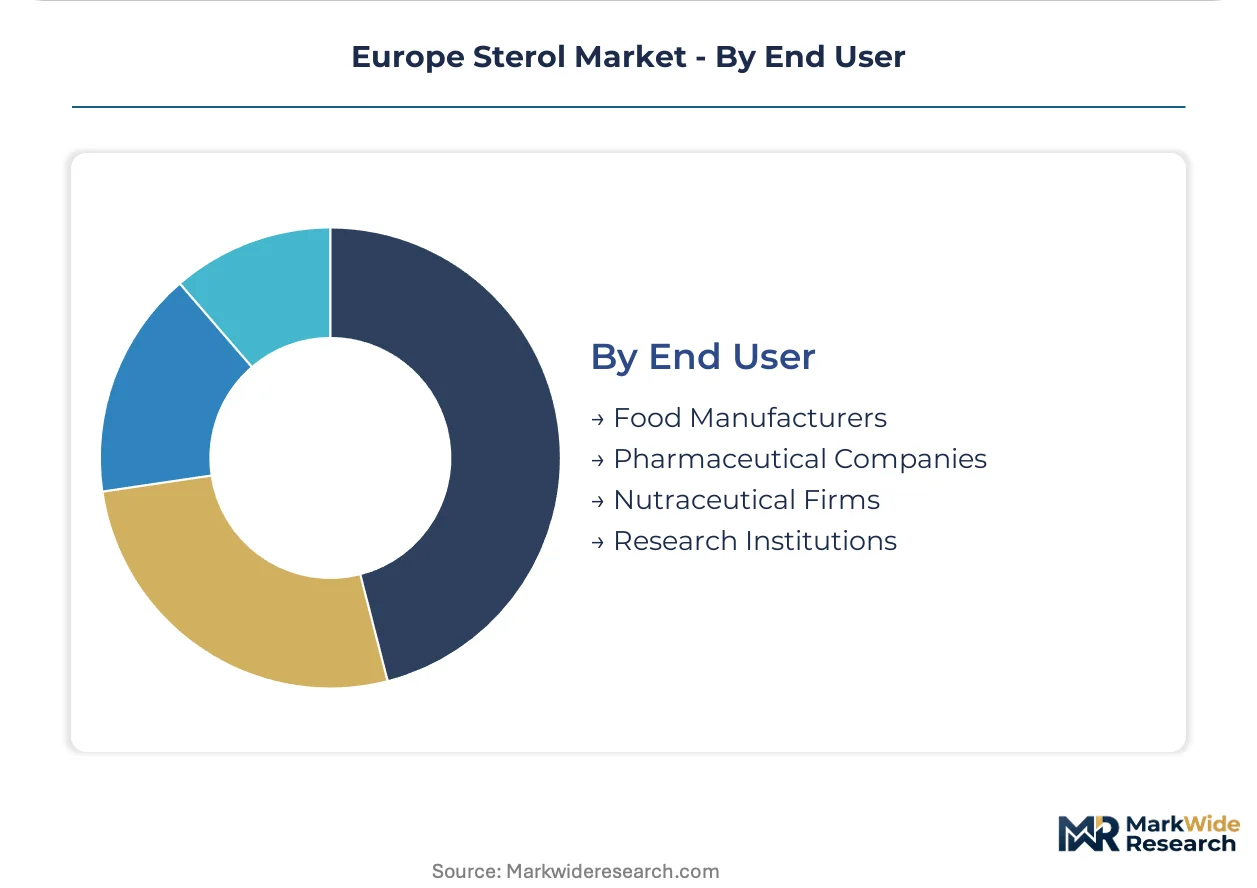
End User:
Customer type dictates contract structure, with procurement centralization at dairy multinationals forcing direct processor-to-manufacturer relationships and squeezing intermediary margins.
- Food Manufacturers:German and French functional dairy processors anchor phytosterol demand, locking long-term supply agreements with fixed purity escalators that privilege vertically integrated suppliers with in-house clinical substantiation capabilities.
- Pharmaceutical Companies:Vitamin D2 precursor buyers and finished dosage formulators require pharmaceutical-grade stanol and ergosterol, with Dutch toll manufacturers adopting supercritical CO2 systems to serve both nutraceutical and pharmaceutical specifications from single campaigns.
- Nutraceutical Firms:Dietary supplement compounders drive demand for tablet and liquid sterol formats, with CSRD sustainability reporting creating premium pricing tiers for suppliers with verified carbon-negative extraction credentials.
- Research Institutions:Academic and clinical research users represent fragmented, small-volume demand for high-purity sterol reference standards and novel delivery mechanism evaluation.
Food Manufacturers hold installed capacity. Pharmaceutical Companies is rotating up the share rankings on margin pool expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German sterol processors export refined phytosterol esters to French and Benelux dairy manufacturers under long-term supply contracts. This trade corridor channels over half of Europe's food-grade sterol volumes.
Germany
Functional dairy processors in Bavaria and North Rhine-Westphalia drive phytosterol demand for cholesterol-lowering spreads and yogurts. EFSA health claim enforcement under Regulation 1924/2006 compresses formulation timelines for manufacturers seeking approved label statements. The Frankfurt-Rhine-Main corridor hosts toll manufacturers adopting supercritical CO2 extraction to serve both food and pharmaceutical specifications.
France
Margarine compounders in the Hauts-de-France region anchor Benelux-facing sterol esterification demand. REACH bio-based traceability requirements accelerate tall oil pitch sourcing audits for stanol producers. The Lyon-Grenoble biotechnology cluster supports enzymatic refinement R&D for pharmaceutical-grade purity thresholds.
Netherlands
Dutch toll manufacturers process ergosterol for vitamin D2 precursor buyers across European pharmaceutical supply chains. EU F-Gas Regulation phase-down schedules force solvent-based extraction equipment retrofits at Rotterdam-area vegetable oil refineries. The Eindhoven-Helmond corridor concentrates supercritical CO2 system adoption for continuous processing campaigns.
Sweden
Nordic oat supply chains in southern Sweden provide specialized feedstock for saturated sterol production. Scandinavian pulp mill integration limits independent refiner access to tall oil pitch, creating sourcing bottlenecks for stanol manufacturers. The Gothenburg biotechnology hub supports integrated biotechnology platforms for feedstock-secure production.
Poland
Underdeveloped functional food markets in Greater Poland and Silesia offer first-mover positioning for phytosterol-fortified bakery applications. CSRD sustainability reporting requirements create premium pricing tiers for suppliers with verified carbon-negative extraction credentials. The Warsaw metropolitan area anchors Eastern European distribution networks for sterol-fortified animal feed.
Europe Sterol Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated chemical conglomerates and specialized Nordic oat processors. The vendor base stratifies across three tiers: multinational chemical majors with integrated biotechnology platforms, regional oilseed processors with toll manufacturing capabilities, and specialized stanol producers tied to captive feedstock supply. Dominant competitive moves include backward integration into vegetable oil crushing assets and technology licensing partnerships for supercritical CO2 extraction systems.
Within the multinational chemical tier, BASF SE and Cargill occupy positions defined by broad sourcing networks spanning multiple European oilseed processing corridors. Among specialized Nordic producers, Raisio Oyj exemplifies the feedstock-captive archetype through its integration with regional oat supply chains. These three companies represent the prevailing strategic models: platform-scale biotechnology deployment, distributed sourcing optimization, and captive raw material control.
| Leading Market Players |
|---|
| BASF SE |
| Archer Daniels Midland Company |
| Cargill |
| Raisio Oyj |
| Gustav Parmentier GmbH |
| DuPont de Nemours, Inc. |
| Arboris, LLC |
| Kerry Group plc |
| FMC Corporation |
| Others |
Supply & Pricing Matrix
Scandinavian pulp mill concentration of tall oil pitch feedstock anchors margin capture at the stanol refining tier, forcing downstream phytosterol processors to compete on extraction efficiency rather than raw material arbitrage. This upstream bottleneck reshapes where value accumulates across European sterol supply chains.
Pricing Analysis
Prior-generation hexane-based crystallization equipment commands depressed valuations against supercritical CO2 extraction systems that collapse pharmaceutical-grade purification premiums. Three-tier pricing structure across pharmaceutical-grade stanols, food-grade phytosterol esters, and feed-grade concentrates reflects EFSA certification status and REACH bio-based traceability tiers. Cost compression in standard-grade phytosterol flows intensifies as Dutch toll manufacturers scale continuous processing campaigns. Nutraceutical compounders exhibit highest price sensitivity; vitamin D2 precursor buyers absorb premium positioning with limited volume elasticity.
Supply Chain Analysis
Tariff exposure between Black Sea sunflower oil sourcing regions and German processing hubs dominates supply chain risk calculus for vegetable oil-derived sterol producers. Feedstock flows concentrate in Germany, Sweden, and the Netherlands, drawing from rapeseed crushing, Nordic oat milling, and tall oil pitch refining respectively. Rapeseed oil, tall oil pitch, and oat lipids constitute the three critical input streams, with each tethered to distinct agricultural and forestry commodity cycles. Single-source vulnerability concentrates at Scandinavian pulp mill integration points for stanol manufacturers. Distribution runs through Rotterdam-area toll manufacturers serving Benelux and French dairy clusters under long-term offtake contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe sterol market tracks a cyclical recovery pattern anchored to EFSA health claim enforcement waves that periodically force formulation refreshes across German and French dairy manufacturing bases.
For Market Incumbents: Harden clinical substantiation capabilities against pending EFSA novel delivery mechanism opinions that threaten to obsolete existing formulation portfolios. Deepen backward integration into Nordic oat supply chains to secure captive stanol feedstock against Scandinavian pulp mill bottleneck risks. Lock 5-year fixed-escalator contracts with Benelux margarine manufacturers before supercritical CO2 tolling capacity expands.
For New Entrants and Emerging Players: Build out enzymatic refinement capabilities targeting pharmaceutical-grade purity thresholds at food-grade cost structures, exploiting the technology gap between incumbent solvent-based infrastructure and next-generation biocatalysis. Polish and Romanian functional bakery applications offer the most penetrable white-space target, with underdeveloped health claim regulatory enforcement reducing compliance barriers versus Western European markets.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized Nordic oat processors with integrated stanol production and verified REACH bio-based traceability credentials, positioning for CSRD sustainability reporting premium tiers. The 5-10 year viability window favors feedstock-captive models over toll manufacturing arbitrage. Watch EFSA publication timelines for nano-emulsified sterol format approvals as the critical inflection signal for encapsulation technology valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Scale-Up | Dutch toll manufacturers collapse pharmaceutical-grade cost premiums through continuous processing campaigns. |
| Backward Integration into Oat Supply | Raisio Oyj secures captive feedstock for saturated sterol production against Scandinavian pulp mill bottlenecks. |
| EFSA Novel Food Submission | Nano-emulsified sterol formats unlock encapsulation premium positioning pending regulatory clearance. |
| CSRD Sustainability Certification | Verified carbon-negative extraction credentials command premium pricing tiers from nutraceutical compounders. |
| Long-Term Supply Agreement | German dairy multinationals lock 3-5 year offtake contracts displacing spot purchasing and trading intermediaries. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EFSA opinion registers, REACH substance evaluation databases, and EU customs trade data for vegetable oil and tall oil derivatives. Primary interviews engaged plant managers at Nordic oat processing facilities, procurement leads at German functional dairy manufacturers, regulatory affairs specialists navigating EFSA health claim pathways, and distribution channel partners serving Benelux margarine clusters. Secondary validation drew from Cefic chemical industry reports, SEC 10-K filings of listed sterol producers, and EU F-Gas Regulation implementation tracking. Bottom-up capacity utilization rates at supercritical CO2 extraction facilities were triangulated against top-down demand estimates from food and pharmaceutical end-use segments.
Forecast inputs span phytosterol versus stanol versus ergosterol product type splits, food and beverage versus pharmaceutical versus cosmetic application tiers, and powder versus liquid versus granule form factors across the projection horizon. Regional regulatory cluster differentiation—Western European EFSA enforcement intensity versus Eastern European penetration potential—shapes geographic allocation modeling. CAGRs derive from segment-level volume growth assumptions calibrated to EFSA health claim adoption curves and supercritical CO2 capacity expansion timelines. Feedstock price volatility in Black Sea sunflower oil markets and Scandinavian tall oil pitch availability constraints inform sensitivity bounds.
Stress conditions across rapeseed oil price bands, EFSA novel food evaluation delays, and supercritical CO2 equipment delivery lead times were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EFSA regulatory trajectory and EU Green Deal sustainability criteria implementation pace. Material shifts in EFSA novel delivery mechanism approval timelines or REACH bio-based traceability enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
Italy Protein Market
Functional Food & Ingredients
Europe Botanical Extract Market
Functional Food & Ingredients
Brominated Vegetable Oil Market
Functional Food & Ingredients
North America Omega-3 PUFA Market
Functional Food & Ingredients
Functional Non-Meat Ingredients Market
Functional Food & Ingredients
Refined Functional Carbohydrates Market
Functional Food & Ingredients
Low-Carb Low-Fat Meal Market
Functional Food & Ingredients
South America Omega-3 PUFA Market
Functional Food & Ingredients
Lovage Extract Market
Functional Food & Ingredients
Multifunctional Food Ingredients Market
Functional Food & Ingredients
Banana Leaf Extract Market
Functional Food & Ingredients
Africa Algae Omega-3 Ingredients Market
Functional Food & Ingredients
North America and Europe Medical Foods Market
Functional Food & Ingredients
Healthy Fats Low Carb Market
Functional Food & Ingredients
North America Pea Protein Ingredients Market
Functional Food & Ingredients
Sacha Inchi Protein Market