
 South America Prebiotic Ingredients Market | 2026-2036
South America Prebiotic Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
South America Prebiotic Ingredients Market Analytics
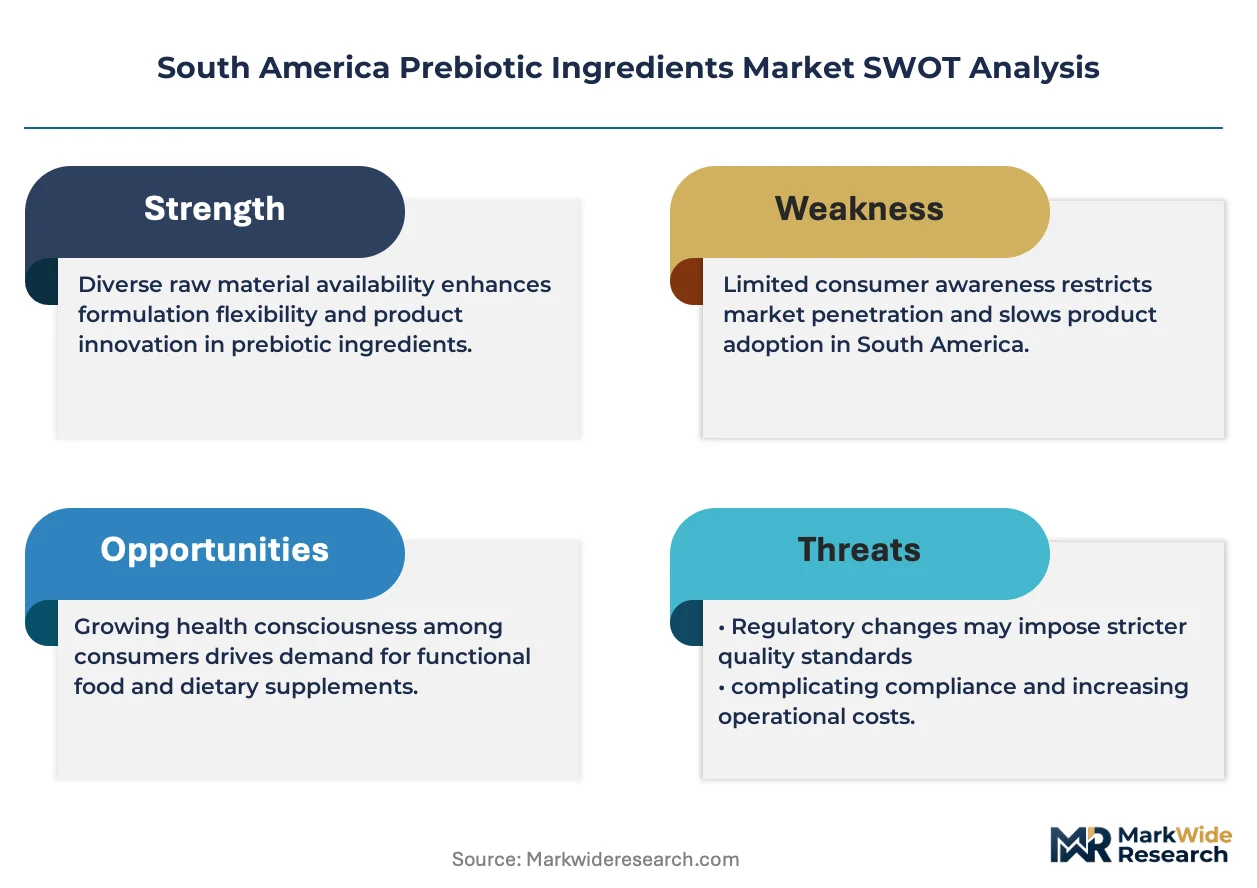
ANVISA's novel food regulation is recalibrating the cost-of-entry calculus for foreign prebiotic suppliers seeking Brazilian market access. BENEO GmbH leverages its European regulatory dossiers to accelerate ANVISA compliance timelines. Ingredion anchors its regional position through backward integration into South American chicory root sourcing. Cargill competes via its existing sweetener distribution infrastructure that extends into prebiotic ingredient channels.
Prebiotic ingredients are non-digestible food components—typically oligosaccharides, inulin, or resistant starch—that selectively stimulate growth of beneficial gut microbiota, with inulin requiring extraction from chicory roots at polymerization degrees ranging from 2 to 60 fructose units. These ingredients serve primarily to enhance digestive health claims in consumer packaged goods while improving mineral absorption profiles. Inulin dominates current volume flows due to established extraction economies and broad formulation compatibility across dairy and bakery matrices. Galacto-oligosaccharides represent the fastest-expanding product category, driven by infant formula fortification mandates and pediatric nutrition R&D pipelines. Dietary supplements command premium margin pools as direct-to-consumer brands emphasize strain-specific microbiome modulation.
ANVISA governs novel food approvals and health claim substantiation in Brazil, while Argentina's national food regulator oversees Mercosur-aligned ingredient standards, and Peru's DIGEMID monitors pharmaceutical-grade prebiotic registrations. These frameworks collectively determine which prebiotic structures qualify for functional claims, directly shaping R&D investment priorities and label positioning strategies. Stakeholders must monitor pending Mercosur harmonization proposals that could unify maximum permitted dosage thresholds across member states.
Market Dynamics
ANVISA's streamlined novel food registration pathway is compressing compliance timelines for oligosaccharide suppliers while concentrating procurement decisions among Brazilian dairy processors with dedicated regulatory affairs teams. This regulatory acceleration is redrawing competitive entry barriers across the continent's functional food supply chain.
Growth Catalysts
- Infant formula fortification mandates:Pediatric nutrition regulations in Brazil and Argentina are embedding prebiotic minimums into early-life nutrition standards, forcing reformulation across dairy processing clusters.
- ANVISA's expedited dossier review:The Brazilian regulator's alignment with EFSA safety assessments is collapsing registration cycles for European-sourced inulin and galacto-oligosaccharides.
- São Paulo-state dairy belt concentration:Functional yogurt processors in southeastern Brazil are anchoring regional demand through dedicated prebiotic supply contracts with chicory root extractors.
Market Restraints
- Chicory root supply concentration:Inulin extraction depends on captive European and Argentine chicory cultivation, exposing processors to weather-driven input volatility and currency mismatch risks.
- Mercosur harmonization delays:Pending unified dosage thresholds across Brazil, Argentina, Paraguay and Uruguay are freezing cross-border formulation standardization investments.
- Resistant starch substitution:Cost-competitive modified starches from South American corn processors are capturing price-sensitive bakery and snack applications.
Strategic Opportunities
- Peruvian pharmaceutical-grade channel:DIGEMID's separate registration track for clinical nutrition applications is opening higher-margin institutional supply contracts for purified prebiotic fractions.
- Direct-to-consumer supplement platforms:Microbiome-testing subscription services are bypassing traditional food ingredient distribution, creating pull-through demand for strain-specific prebiotic blends.
- Amazonian biodiversity screening:Brazilian research institutes are cataloging novel oligosaccharide structures from native tubers and legumes for future novel food dossiers.
Industry Challenges
- Regulatory affairs talent scarcity:Few South American consultancies possess dual expertise in ANVISA novel food procedures and EFSA-style toxicology dossier preparation, extending compliance timelines for new entrants.
- Clinical trial infrastructure gaps:Demonstrating strain-specific microbiome modulation claims requires localized human studies, yet accredited CRO capacity in Brazil and Argentina remains insufficient for pipeline demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Prebiotic Ingredients Market |
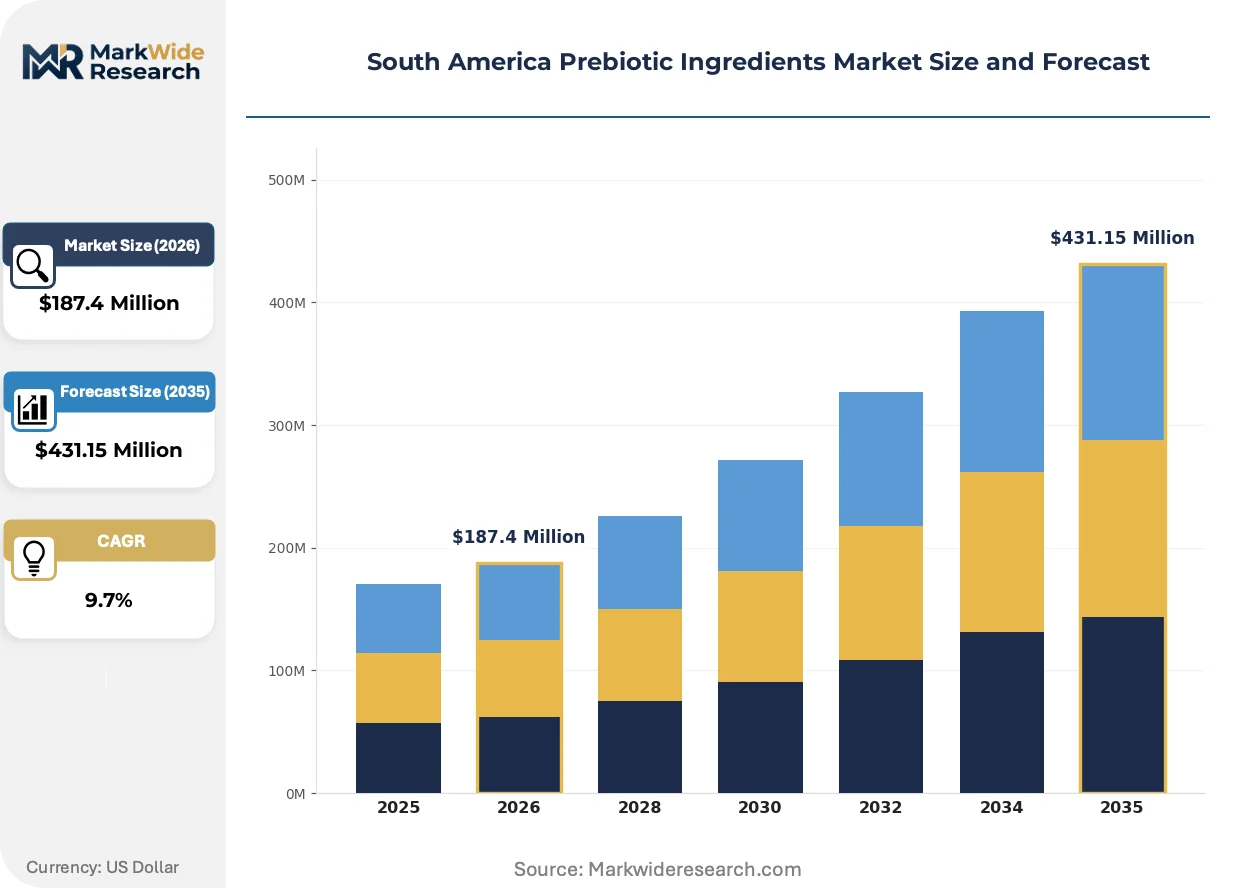
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inulin, Oligofructose, Galacto-Oligosaccharides, Resistance Starch Application: Dairy Products, Beverages, Bakery, Dietary Supplements End User: Food & Beverage Industry, Pharmaceuticals, Nutraceuticals, Cosmetics Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | BENEO GmbH, Fonterra, Ingredion, Cargill, DuPont, Archer Daniels Midland Company, Roquette Frères, COSUCRA, Clasado Limited, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Prebiotic Ingredients Market Evolving Landscape
Enzymatic synthesis pathways and precision fermentation are displacing traditional plant-extraction methods across the continent's prebiotic manufacturing base. These biotechnological shifts are compressing capital requirements while expanding molecular diversity beyond established inulin and galacto-oligosaccharide structures.
Precision fermentation of human milk oligosaccharides is electrifying infant formula innovation pipelines. Argentine biotechnology startups and Brazilian contract manufacturers are scaling pilot facilities to replicate 2'-fucosyllactose and lacto-N-neotetraose structures previously isolated from dairy sources. This microbial production route is collapsing cost curves for premium pediatric nutrition ingredients while enabling structure-specific health claims that plant-derived prebiotics cannot match.
ANVISA's 2024 novel food guideline revision is mandating stepped safety documentation for synthetic biology-derived ingredients. The regulator now requires tiered toxicology packages correlating fermentation strain genealogy with metabolite purity profiles. Brazilian infant formula manufacturers are responding by pre-qualifying suppliers with existing GRAS or EFSA approvals, effectively filtering the vendor base toward established European and North American biotechnology firms.
Buyer concentration among São Paulo-state dairy cooperatives is consolidating procurement decisions into fewer technical sourcing committees. These processors are unbundling ingredient specifications from traditional distribution relationships, instead issuing direct tenders to prebiotic manufacturers with ANVISA-registered dossiers. This disintermediation is compressing margins for regional ingredient traders while rewarding suppliers with in-house regulatory capabilities and Brazilian warehousing infrastructure.
South America Prebiotic Ingredients Market Segmentation
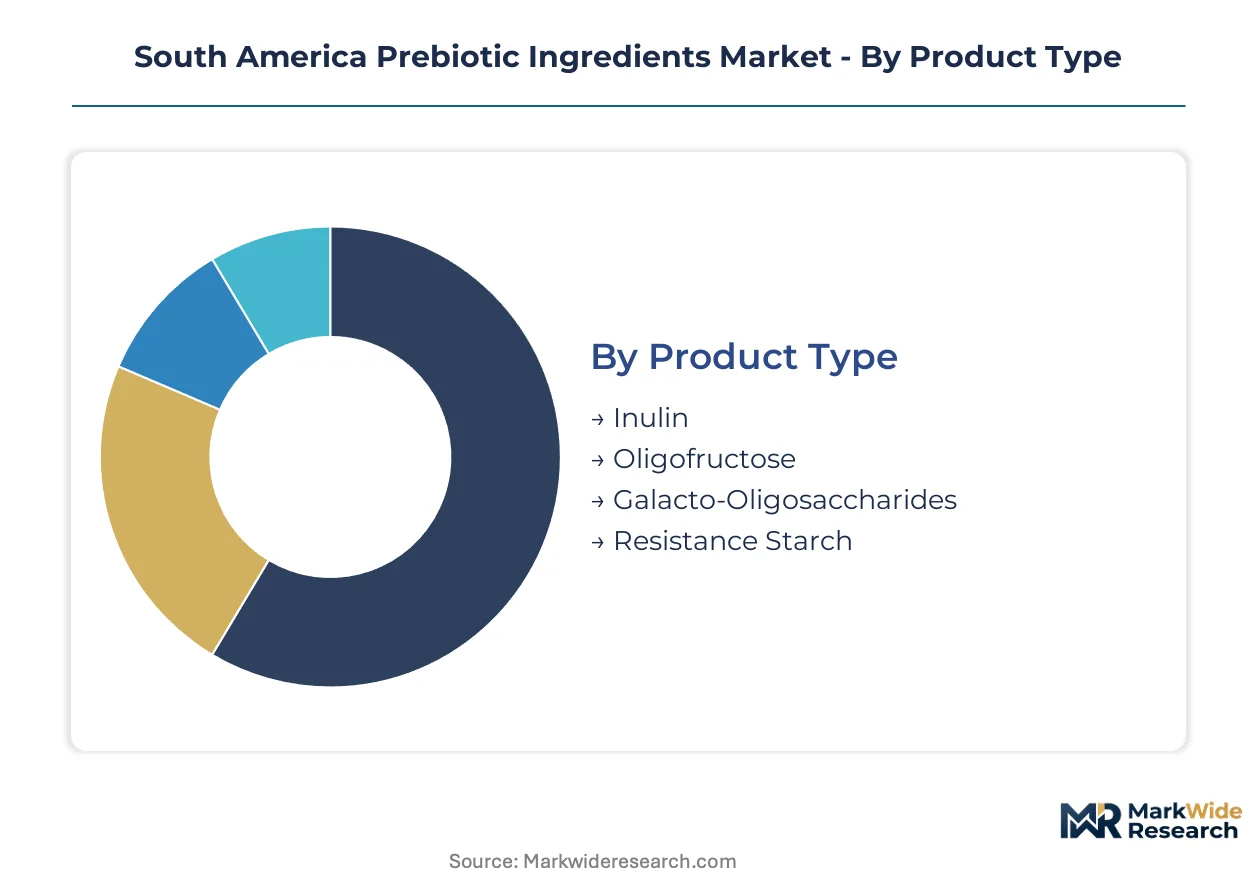
Prebiotic ingredient procurement in South America diverges sharply across product chemistry, application matrix, and channel structure. Buyers prioritize formulation compatibility, regulatory dossier completeness, and supply security when selecting among structurally distinct oligosaccharide categories.
Product Type:
Cost tier determines supplier selection, with extraction economics and biotechnological production routes creating three distinct price-performance bands.
- Inulin:Extracted from chicory roots at polymerization degrees spanning 2 to 60 fructose units, this polysaccharide dominates dairy and bakery applications due to established supply chains from European and Argentine chicory cultivation. São Paulo-state yogurt processors anchor regional offtake through long-term contracts with specialized extractors.
- Galacto-Oligosaccharides:Enzymatically synthesized from lactose feedstock, these short-chain oligosaccharides concentrate in infant formula fortification programs across Brazil and Argentina. Pediatric nutrition regulations embedding prebiotic minimums into early-life standards are accelerating procurement volumes from ANVISA-registered suppliers.
- Oligofructose:Partial enzymatic hydrolysis of inulin yields this lower-molecular-weight fraction with enhanced solubility for beverage applications.
- Resistance Starch:Modified corn-derived starches from South American grain processors compete on cost for price-sensitive bakery and snack formulations.
Volume sits with Inulin; growth tilts toward Galacto-Oligosaccharides.
Application:
Margin structure varies by processing intensity and claim substantiation requirements, with direct-to-consumer formats commanding premium pricing over commodity food manufacturing.
- Dairy Products:Functional yogurt lines in Brazil's southeastern dairy belt represent the dominant consumption node, with processors sourcing galacto-oligosaccharides for digestive health positioning. São Paulo-state cooperatives consolidate procurement through technical sourcing committees that unbundle specifications from traditional distribution relationships.
- Dietary Supplements:Direct-to-consumer microbiome-testing subscription services bypass conventional ingredient distribution, creating pull-through demand for strain-specific prebiotic blends with premium margin profiles.
- Beverages:Enhanced mineral absorption claims drive incorporation into functional drink formulations, particularly in Brazilian urban markets.
- Bakery:Resistant starch substitution pressures prebiotic positioning in price-sensitive bread and snack applications.
Revenue concentrates in Dietary Supplements; volume expansion is steepest in Dairy Products.
End User:
Regulatory pathway complexity segments buyers, with pharmaceutical-grade registrations requiring distinct toxicology dossiers from food-grade approvals.
- Food & Beverage Industry:Brazilian and Argentine dairy processors constitute the core demand base, with ANVISA novel food compliance serving as the critical supplier selection filter.
- Pharmaceuticals:DIGEMID's separate registration track for clinical nutrition applications in Peru opens institutional supply contracts for purified prebiotic fractions.
- Nutraceuticals:Strain-specific microbiome modulation claims require localized human studies, yet accredited CRO capacity in Brazil and Argentina remains insufficient for pipeline demands.
- Cosmetics:Prebiotic incorporation into topical formulations remains nascent, with limited regulatory precedent for cutaneous microbiome claims.
Procurement scale favors Food & Beverage Industry; margin capture is highest in Pharmaceuticals.
Distribution Channel:
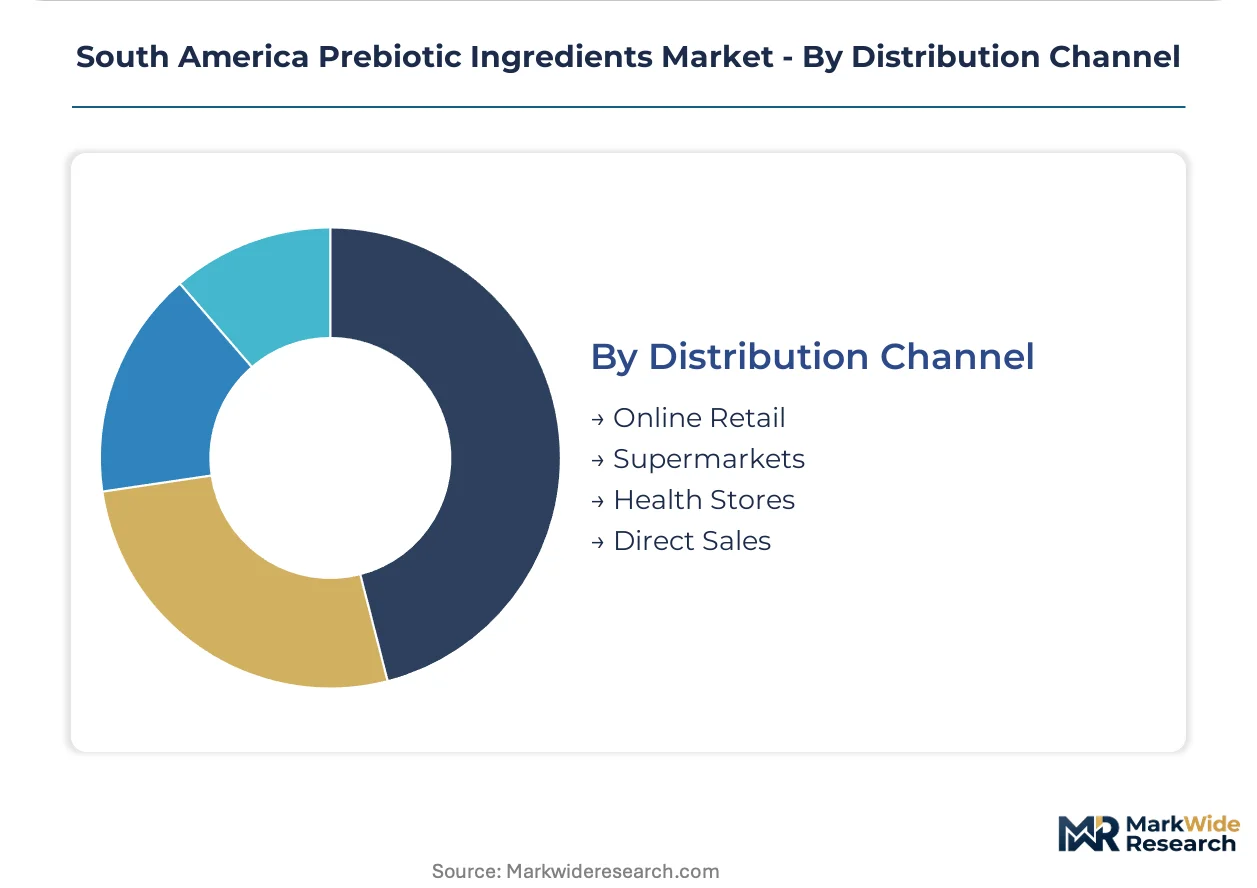
Customer type and order scale determine channel selection, with large manufacturers disintermediating traders while small buyers rely on specialized retail access.
- Direct Sales:São Paulo-state dairy cooperatives issue direct tenders to prebiotic manufacturers with ANVISA-registered dossiers, compressing margins for regional ingredient traders while rewarding suppliers with Brazilian warehousing infrastructure.
- Online Retail:Microbiome-testing subscription platforms and direct-to-consumer supplement brands source strain-specific blends through digital procurement channels.
- Supermarkets:Mass-market prebiotic-fortified foods reach consumers through conventional retail distribution networks.
- Health Stores:Specialized retailers serve the premium supplement segment with curated prebiotic product selections.
Transaction value concentrates in Direct Sales; channel expansion is fastest in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manaus Free Trade Zone tax incentives concentrate pharmaceutical-grade ingredient importation, while São Paulo's industrial policy clusters functional food processing in the southeastern dairy belt. These fiscal architectures redistribute prebiotic supply chain nodes across distinct regulatory and logistics environments.
Brazil
ANVISA's novel food registration pathway accelerates European-sourced inulin approvals, collapsing compliance timelines for foreign suppliers. São Paulo-state dairy cooperatives anchor continental demand through direct procurement tenders to ANVISA-registered manufacturers. Functional yogurt processors in the southeastern dairy belt source galacto-oligosaccharides for digestive health positioning.
Argentina
The national food regulator oversees Mercosur-aligned ingredient standards that govern prebiotic fortification in pediatric nutrition. Buenos Aires-based infant formula manufacturers expand reformulation programs to meet embedded prebiotic minimums in early-life nutrition regulations. Córdoba's dairy processing cluster drives regional procurement of enzymatically synthesized oligosaccharides.
Peru
DIGEMID's separate registration track for pharmaceutical-grade prebiotics opens institutional supply contracts for purified fractions. Lima's clinical nutrition distributors target higher-margin hospital and medical food channels. The capital's warehousing infrastructure supports Andean distribution of imported prebiotic ingredients.
Chile
Santiago's functional food manufacturers leverage the country's advanced logistics infrastructure for Andean cross-border distribution. The national food safety authority maintains stringent novel food documentation requirements that filter supplier eligibility. Valparaíso's port facilities enable efficient importation of European chicory root extracts.
Colombia
Bogotá's dietary supplement brands bypass traditional distribution through direct-to-consumer microbiome-testing platforms. The national food and drug surveillance institute regulates health claim substantiation for prebiotic-fortified products. Medellín's contract manufacturing sector scales encapsulation capacity for premium supplement formulations.
South America Prebiotic Ingredients Market Competitive Landscape
European producers anchor the premium tier through established regulatory dossiers and novel food approvals; North American agribusiness conglomerates hold scale-driven positions through existing sweetener distribution infrastructure. Market structure concentrates procurement decisions among Brazilian dairy processors with dedicated regulatory affairs capabilities. Three archetypes dominate: biotechnology specialists with precision fermentation platforms, agricultural processors with captive chicory root supply, and diversified ingredient traders with regional warehousing networks. Competitive dynamics center on ANVISA compliance acceleration and backward integration into South American raw material sourcing.
Within the European biotechnology tier, BENEO GmbH leverages its regulatory dossiers to compress Brazilian approval timelines. Ingredion anchors regional positioning through upstream control over South American chicory root cultivation. Cargill occupies a scale-driven position by extending existing sweetener distribution channels into prebiotic ingredient markets. These three exemplify distinct competitive vectors: regulatory dossier depth, raw material captive supply, and infrastructure reuse.
| Leading Market Players |
|---|
| BENEO GmbH |
| Fonterra |
| Ingredion |
| Cargill |
| DuPont |
| Archer Daniels Midland Company |
| Roquette Frères |
| COSUCRA |
| Clasado Limited |
| Others |
Value Network & Pricing Analysis
Enzymatic synthesis pathways displacing traditional chicory root extraction are compressing capital requirements for galacto-oligosaccharide production while concentrating manufacturing among biotechnology specialists with precision fermentation platforms. This technological transition simultaneously lowers entry costs for new producers and tightens supply control among incumbent firms with validated ANVISA dossiers, reshaping how São Paulo-state dairy processors negotiate long-term offtake contracts.
Pricing Analysis
Short lead-time premiums command substantial markups as Brazilian yogurt processors facing reformulation deadlines pay above-contract rates for ANVISA-registered galacto-oligosaccharide inventory. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade purified fractions from food-grade inulin and commodity resistant starch alternatives. Cost compression in the economy tier is intensifying as South American corn processors scale modified starch output for price-sensitive bakery applications. Spot buyers in the dietary supplement channel exhibit the highest price sensitivity, while infant formula manufacturers locked into pediatric nutrition compliance mandates absorb premium pricing with limited substitution options.
Supply Chain Analysis
Reverse-logistics flows for fermentation equipment refurbishment and enzyme catalyst recovery are emerging as cost-control nodes for Argentine biotechnology startups scaling human milk oligosaccharide pilot facilities. Geographic supply concentration centers on Belgium and the Netherlands for chicory root extraction, China for enzymatic synthesis catalysts, and Brazil for regional lactose feedstock processing. Raw material dependencies hinge on European chicory cultivation cycles, specialized fermentation strain imports, and pharmaceutical-grade purification resin supplies. Single-source vulnerability from European inulin extractors exposes processors to currency mismatch risks and weather-driven harvest volatility. Distribution runs through São Paulo-state dairy cooperatives issuing direct tenders to ANVISA-registered manufacturers, bypassing traditional ingredient traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints around ANVISA regulatory affairs talent and accredited clinical trial infrastructure are propping pricing power for incumbent prebiotic suppliers with established Brazilian compliance capabilities. Chicory root cultivation bottlenecks and fermentation strain validation backlogs limit rapid capacity expansion, sustaining margin premiums for dossier-complete manufacturers.
For Market Incumbents: Cement ANVISA dossier depth as the primary defensive moat by accelerating toxicology package updates ahead of Mercosur harmonization proposals. Backward integration into Argentine chicory cultivation or Brazilian lactose processing secures feedstock autonomy against European supply volatility. Precision fermentation platform expansion in São Paulo-state industrial zones captures demand from infant formula manufacturers pre-qualifying suppliers with existing GRAS or EFSA approvals. For New Entrants and Emerging Players: Enter via DIGEMID's pharmaceutical-grade registration track in Peru, where institutional supply contracts for purified prebiotic fractions command premium margins with limited incumbent competition. The direct-to-consumer microbiome-testing subscription channel offers the most penetrable entry point, bypassing traditional food ingredient distribution relationships entirely. Partner with Brazilian contract manufacturers possessing existing ANVISA novel food approvals to compress compliance timelines and accelerate market access. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by European biotechnology specialists seeking ANVISA-registered platforms for Latin American expansion. Long-term viability favors precision fermentation capabilities over plant-extraction assets as enzymatic synthesis routes displace traditional manufacturing. Monitor pending Mercosur harmonization proposals for unified dosage thresholds as the critical inflection signal determining whether regional formulation standardization investments accelerate or freeze.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Dossier Acceleration | European suppliers leveraging EFSA alignment collapse Brazilian approval cycles for novel oligosaccharides. |
| Precision Fermentation Scale-Up | Argentine and Brazilian facilities replicating human milk oligosaccharide structures capture infant formula premium tiers. |
| Backward Integration into Chicory | Upstream control over Argentine cultivation reduces European supply volatility exposure for inulin extractors. |
| Direct-to-Consumer Channel Development | Microbiome-testing platforms bypass traditional distribution, creating pull-through demand for strain-specific blends. |
| Peruvian Pharmaceutical-Grade Registration | DIGEMID's separate clinical nutrition track opens higher-margin institutional contracts for purified fractions. |
Research Methodology
Document review covered ANVISA novel food registration filings, EFSA safety assessment databases, and Mercosur harmonization proposal drafts, complemented by interviews with regulatory affairs directors at Brazilian dairy processors, procurement leads at Argentine infant formula manufacturers, and toxicology consultants specializing in Latin American novel food dossiers. Secondary validation drew from customs trade data on chicory root and lactose imports, DIGEMID pharmaceutical registration databases, and industry association reports on pediatric nutrition formulation trends. Bottom-up demand modeling from individual processor procurement volumes was cross-referenced against top-down market sizing from ingredient trade flows.
Historical volume trajectories were cross-referenced against expert panel inputs from supply chain managers and category buyers to anchor projection assumptions. The analytical framework modeled demand across product chemistry segments, application matrices, and regulatory pathway complexity tiers throughout the forecast period. CAGRs were derived from segment-level growth rate distributions reflecting ANVISA approval velocity, infant formula fortification mandate implementation timelines, and precision fermentation cost curve trajectories. Industry-specific forecast inputs included enzymatic synthesis capacity buildout schedules and Mercosur regulatory harmonization probability assessments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged Mercosur harmonization delays or accelerated resistant starch substitution in bakery applications. Practitioners should monitor ANVISA novel food guideline revisions and European chicory harvest yield reports for early signals of supply constraint intensity or pricing pressure direction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
Poultry Probiotic Ingredients Market
Functional Food & Ingredients
Brominated Vegetable Oil Market
Functional Food & Ingredients
Functional Ingredients Market
Functional Food & Ingredients
Lovage Extract Market
Functional Food & Ingredients
APAC Heart Health Functional Food Market
Functional Food & Ingredients
Prickly Pear Fruit Metabolic Health Ingredients Market
Functional Food & Ingredients
Low-Carb Low-Fat Meal Market
Functional Food & Ingredients
Omega 3 PUFA Market
Functional Food & Ingredients
Europe Omega-3 PUFA Market
Functional Food & Ingredients
Europe Prebiotic Ingredient Market
Functional Food & Ingredients
Superfood Powders Market
Functional Food & Ingredients
Asia-Pacific Omega3 PUFA Market
Functional Food & Ingredients
Healthy Fats Low Carb Market
Functional Food & Ingredients
Global Medical Foods Market
Functional Food & Ingredients
Banana Leaf Extract Market
Functional Food & Ingredients
Multifunctional Food Ingredients Market