
 Sacha Inchi Protein Market | 2026-2036
Sacha Inchi Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Sacha Inchi Protein Market Analytics
The EU Green Deal is pivoting procurement criteria for plant-based protein across European food manufacturers. MG Natura Peru S.A.C. anchors its supply chain through direct smallholder partnerships in the Peruvian Amazon. Peruvian Nature differentiates via organic certification and cold-pressed oil co-product streams. Axiom Foods extends its ingredient portfolio by blending sacha inchi with other allergen-free proteins for North American contract manufacturers.
Sacha inchi protein is a complete plant protein extracted from the seeds of Plukenetia volubilis, containing all nine essential amino acids with a PDCAAS score comparable to soy, and it serves primarily as a hypoallergenic alternative in sports nutrition and clean-label food formulations. Protein powder occupies the largest volume share among product types due to its versatility in smoothie and shake applications. The food and beverages application segment leads value generation as beverage brands reformulate with sustainable protein sources. Online retail channels represent the fastest-growing distribution pathway, driven by direct-to-consumer subscription models and influencer-led education.
The FDA governs GRAS self-affirmation pathways for sacha inchi protein entering US interstate commerce, while EFSA evaluates novel food dossiers for EU market authorization, and Peru's national agricultural authority oversees organic export certification for Amazonian producers. These overlapping compliance frameworks create tiered market access costs that favor established players with dedicated regulatory affairs capacity. Stakeholders must monitor evolving protein content labeling standards and carbon footprint disclosure requirements as buyer procurement criteria harden.
Market Dynamics
Smallholder cooperatives in Peru's San Martín region concentrate raw seed supply, creating a bottleneck that forces downstream processors to secure offtake agreements before EFSA Novel Food dossier completion.
Growth Catalysts
- EU Green Deal procurement mandates:European food manufacturers now face binding sustainable protein sourcing targets that favor Amazonian-origin ingredients with verified carbon credentials.
- Cold-pressed oil co-product economics:Mechanical oil extraction generates defatted cake as feedstock for protein isolate, improving unit economics for integrated processors.
- Sports nutrition formulation pipelines:North American brands actively seek hypoallergenic alternatives to soy and whey for clean-label positioning.
Market Restraints
- Amazonian climate volatility:El Niño precipitation patterns disrupt flowering cycles in Peru's Ucayali and San Martín growing zones.
- EFSA Novel Food timeline friction:The 18-24 month safety evaluation window blocks EU revenue recognition until full authorization.
- Whey protein substitution threat:Dairy processors in Wisconsin and New Zealand command established supply contracts with fitness brands.
Strategic Opportunities
- German direct-to-consumer subscription channels:Online retail growth outpaces traditional foodservice distribution for protein powder formats.
- Cosmeceutical peptide applications:Hydrolyzed sacha inchi fractions target dermal collagen support in South Korean skincare formulations.
- USDA Organic plus Regenerative Organic Certified stacking:Dual certification commands shelf placement premiums in Whole Foods Market and Sprouts Farmers Market.
Industry Challenges
- Novel food toxicology study costs:EFSA-mandated 90-day rodent feeding trials require capital outlays that strain mid-tier ingredient suppliers.
- Smallholder traceability infrastructure:Blockchain-enabled provenance systems demand smartphone penetration and cooperative management capacity absent in remote Amazonian collection points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sacha Inchi Protein Market |
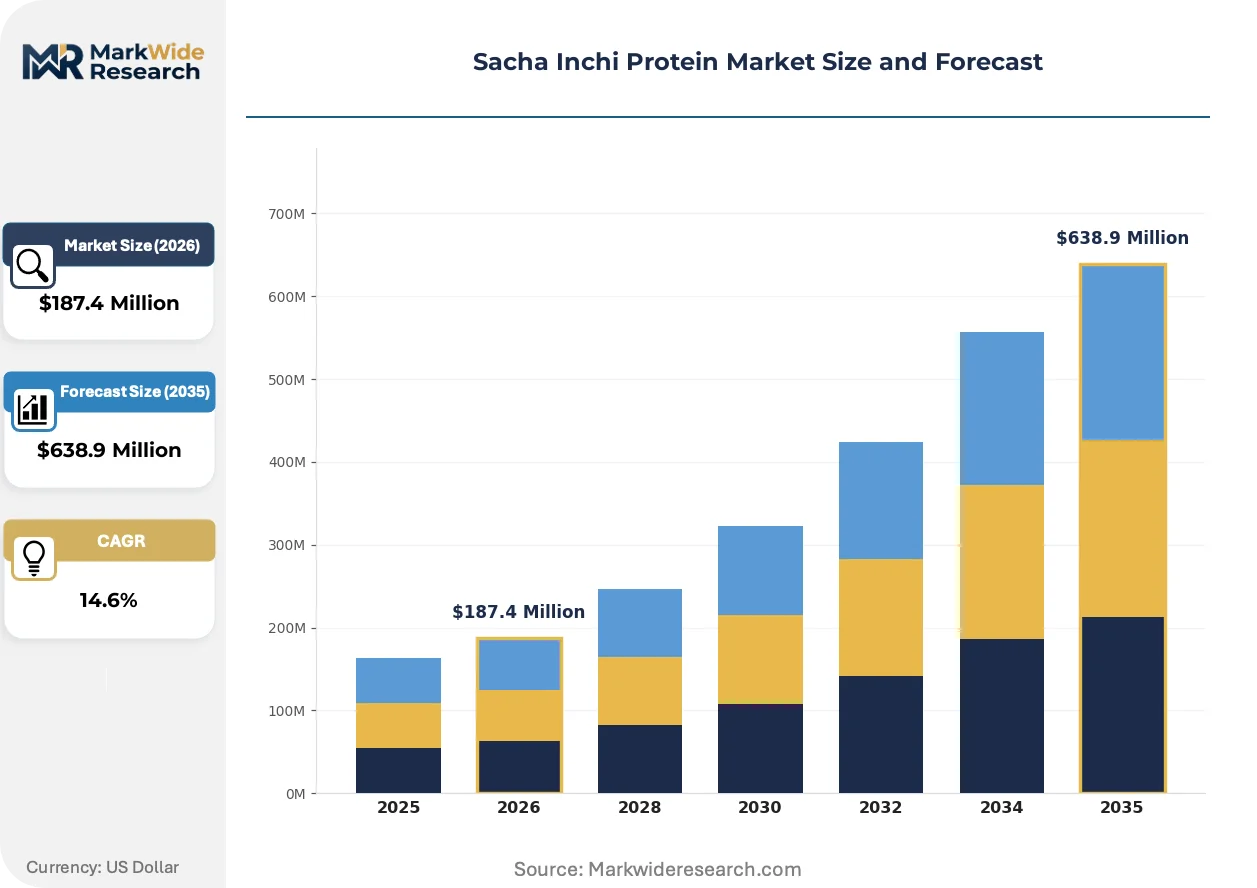
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Powder, Protein Bars, Snack Foods, Supplements End User: Athletes, Health Enthusiasts, Vegan Consumers, Sports Nutrition Application: Dietary Supplements, Food & Beverages, Meal Replacement, Bakery Products Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops |
| Companies Covered | Axiom Foods, Flora Manufacturing & Distributing Ltd., NP Nutra, Imlak’Esh Organics, MG Natura Peru S.A.C., Peruvian Nature, HerboNutra, MaiSavanhLao, Nature's Power Nutraceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sacha Inchi Protein Market Evolving Landscape
Protein extraction technologies and certification protocols are reshaping how Amazonian seed moves from forest to formulation, compressing traditional commodity trading margins while opening premium positioning pathways.
Enzymatic hydrolysis is unifying protein recovery rates with functional property tuning. Sports nutrition contract manufacturers in California and Texas adopt this approach to achieve 90%+ protein concentration while preserving emulsification capacity. The technology is unifying what previously required separate isolation and modification steps into single-unit operations, eroding the margin advantage of legacy solvent-based processors.
EFSA's evolving Novel Food guidance on insect and plant proteins is tightening dossier requirements for allergenicity assessment. The regulation now demands cross-reactivity screening against established legume allergens before market authorization. European ingredient importers are responding by front-loading toxicology budgets and delaying EU launch timelines until US GRAS self-affirmation generates cash flow.
Direct-to-consumer subscription models are displacing brick-and-mortar sports nutrition retail in English-speaking markets. Influencer-led education on PDCAAS scoring and amino acid completeness drives trial conversion for sacha inchi powder. This shift concentrates most visibly in Australian and Canadian urban markets where fitness culture intersects with sustainability-conscious purchasing.
Sacha Inchi Protein Market Segmentation
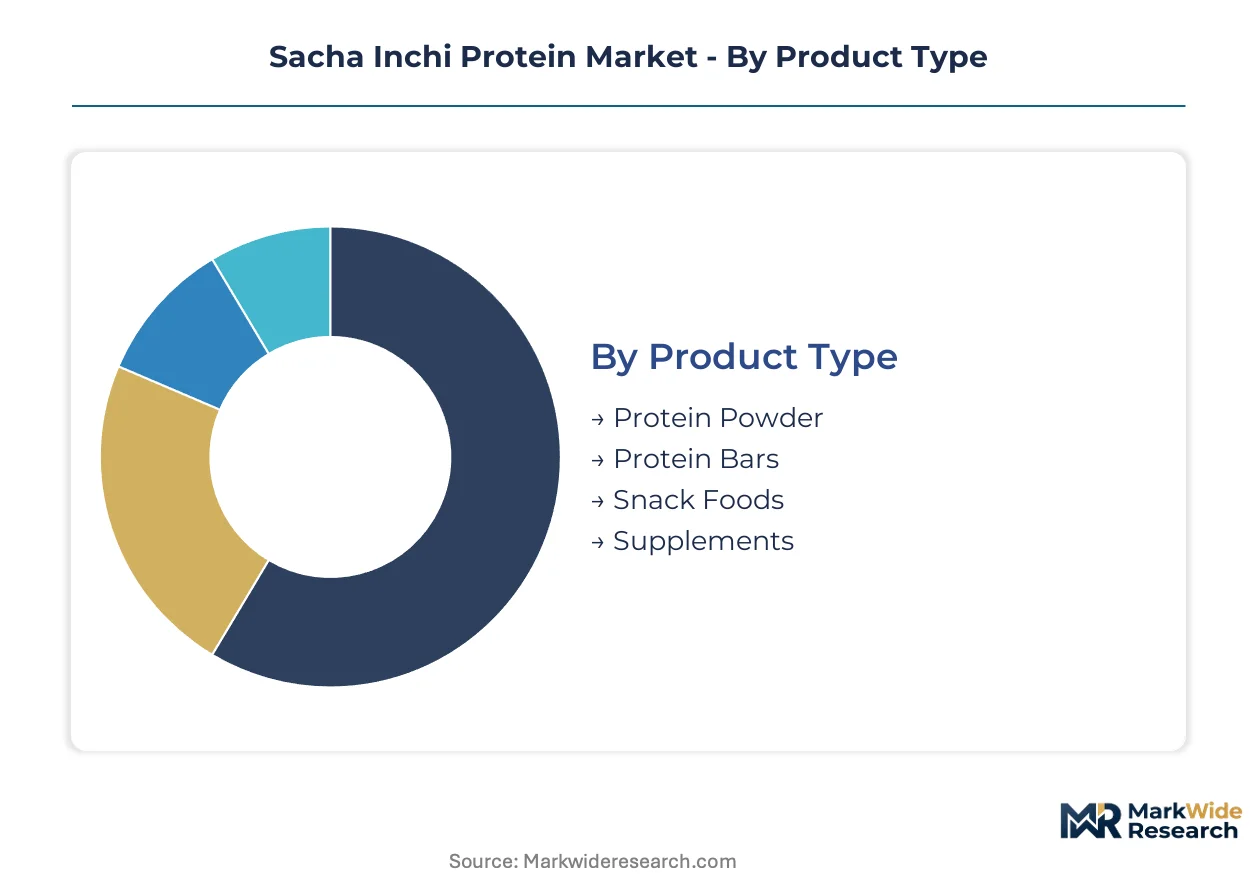
Segmentation in the Sacha Inchi Protein Market reveals how capital deployment and regulatory compliance costs concentrate in powder processing infrastructure while downstream formats capture margin through branding. Understanding these divisions helps processors prioritize capacity investments and identify which customer cohorts justify premium certification spending.
Product Type:
Protein powder production demands the heaviest capital commitment, requiring solvent extraction or enzymatic hydrolysis equipment, spray-drying towers, and cleanroom packaging lines that can exceed seven-figure installation costs.
- Protein Powder:Dry-milled and spray-dried concentrates achieve 50-70% protein content, with enzymatic hydrolysis variants reaching 90%+ for sports nutrition applications. California contract manufacturers absorb the bulk of North American volume as they reformulate away from soy and whey for clean-label positioning. The format's versatility in smoothie bases sustains premium pricing despite commoditization pressure in bulk ingredient trading.
- Protein Bars:Extrusion and cold-press binding equipment requires moderate capital outlay compared to isolate production, with co-manufacturers in Texas and Utah specializing in allergen-free line certification. Demand concentrates in direct-to-consumer subscription channels where Australian and Canadian fitness influencers drive trial conversion through PDCAAS scoring education.
- Snack Foods:Roasted whole seeds and puffed formulations leverage existing nut-processing infrastructure with lower barrier to entry.
- Supplements:Capsule and tablet formats depend on contract manufacturers with NSF Certified for Sport or Informed Sport accreditation.
Most installed capacity flows through protein powder. Expansion is steepest in protein bars.
End User:
Customer acquisition costs and lifetime value calculations vary dramatically across these cohorts, with athletes commanding the highest per-capita spending but vegan consumers offering the most predictable repeat purchase patterns.
- Athletes:Competitive and recreational athletes prioritize leucine content and digestibility speed, with collegiate programs and CrossFit affiliates in Texas and Florida generating concentrated demand for bulk powder procurement. EFSA Novel Food authorization blocks EU revenue recognition from this segment until full market authorization clears.
- Vegan Consumers:Ethical and environmental motivation drives loyalty above price sensitivity, with subscription retention rates exceeding conventional sports nutrition. German direct-to-consumer channels capture disproportionate share of this cohort through influencer-led sustainability messaging and carbon footprint disclosure.
- Health Enthusiasts:Wellness-focused generalists respond to omega-3 co-benefit marketing and adaptogen positioning.
- Sports Nutrition:Institutional buyers including team dietitians and military procurement officers demand batch-tested certification.
Volume concentrates with athletes. Vegan consumers are gaining share fastest.
Application:
Formulation complexity and regulatory pathway costs diverge sharply between supplement and food uses, with the latter demanding GRAS self-affirmation or Novel Food dossier completion before revenue recognition.
- Dietary Supplements:Capsule, tablet, and powder formats operate under DSHEA in the US with self-affirming GRAS status sufficient for interstate commerce, allowing faster cash flow generation than food applications. Amazonian processors front-load toxicology budgets here to fund later EFSA submissions.
- Food & Beverages:Beverage brands in California and Texas reformulate with sustainable protein sources, requiring emulsification-stable isolates that preserve mouthfeel in RTD formats. The segment leads value generation but carries the longest regulatory timelines.
- Meal Replacement:Complete nutrition formulations compete with established soy and pea protein supply chains on cost-per-gram-protein metrics.
- Bakery Products:Gluten-free and paleo-positioned bakeries in Colorado and Oregon trial sacha inchi flour for texture and protein fortification.
Revenue recognition is fastest in dietary supplements. Food and beverages shows the steepest expansion trajectory.
Distribution Channel:
Channel selection determines working capital intensity and margin capture, with direct-to-consumer models requiring inventory risk absorption in exchange for customer data ownership.
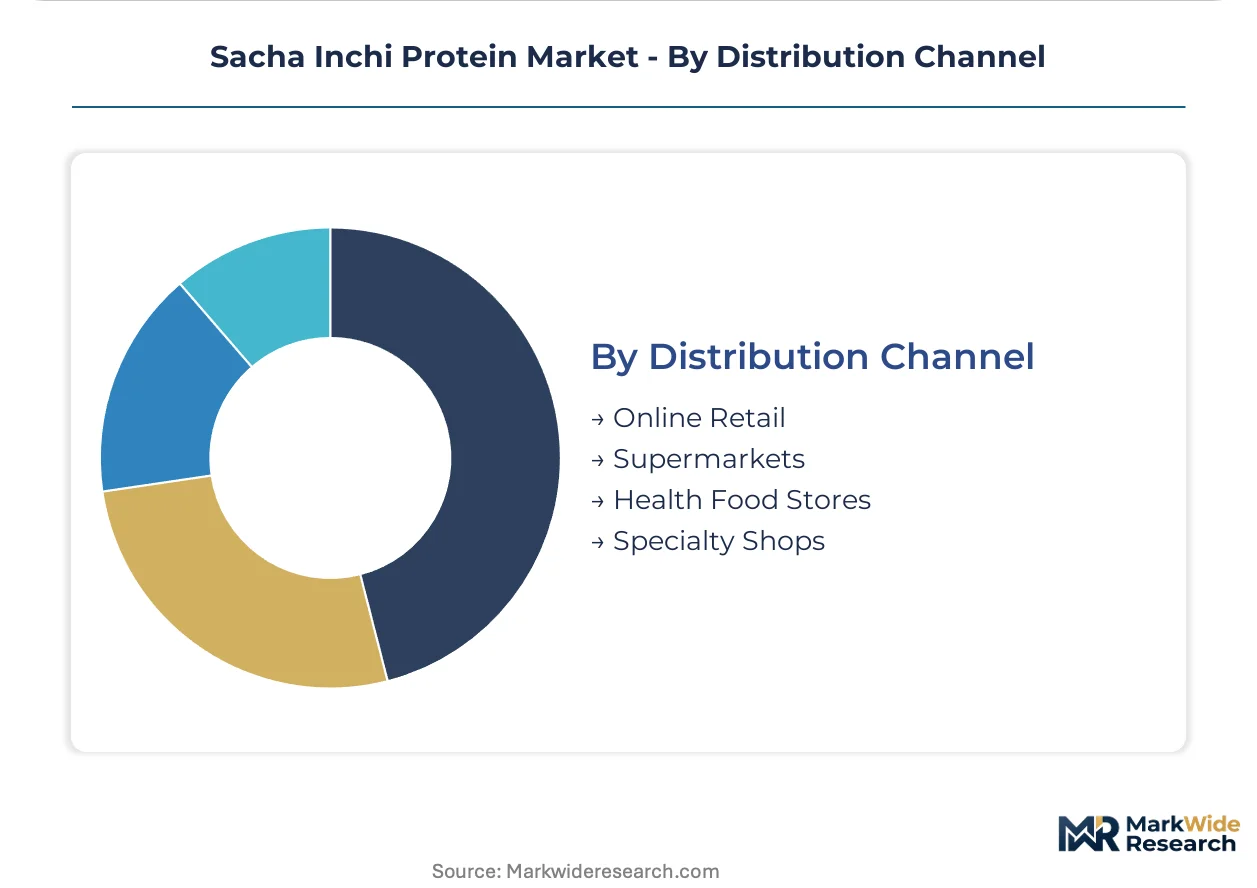
- Online Retail:Subscription models and influencer affiliate structures concentrate in Australian and Canadian urban markets where fitness culture intersects with sustainability-conscious purchasing. Amazonian-origin storytelling and blockchain-enabled provenance claims justify premium pricing against commodity whey.
- Supermarkets:Slotting fees and promotional spend requirements favor established brands with trade marketing budgets, though Sprouts Farmers Market and Whole Foods Market award shelf placement premiums for dual USDA Organic and Regenerative Organic Certified positioning.
- Health Food Stores:Independent retailers in Colorado and Oregon serve as trial channels for novel formats before national rollout.
- Specialty Shops:CrossFit boxes, yoga studios, and climbing gyms capture impulse purchases through point-of-sale placement.
Supermarkets absorb the most volume. Online retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peru's San Martín region pioneered commercial sacha inchi cultivation in the early 2000s, establishing the Amazonian seed as a viable export commodity. Processing infrastructure and formulation demand now span three continents.
United States
California contract manufacturers drive powder formulation demand for sports nutrition brands seeking clean-label alternatives. FDA GRAS self-affirmation pathways allow faster product launches than European authorization timelines. Los Angeles and San Diego clusters specialize in allergen-free protein blending for direct-to-consumer subscription channels.
Germany
EU Green Deal procurement mandates force food manufacturers toward verified sustainable protein sources. EFSA Novel Food dossier requirements create 18-24 month authorization delays that block immediate revenue recognition. Berlin and Hamburg direct-to-consumer brands capture disproportionate vegan consumer share through carbon footprint disclosure and influencer marketing.
Peru
Smallholder cooperatives in San Martín and Ucayali regions concentrate raw seed supply, creating upstream bottlenecks for international processors. The national agricultural authority oversees organic export certification requirements for Amazonian producers. Tarapoto and Pucallpa serve as collection and pre-processing hubs where MG Natura Peru S.A.C. and Peruvian Nature maintain direct farmer partnerships.
Australia
Fitness culture intersects with sustainability-conscious purchasing in Sydney and Melbourne urban markets. TGA regulations govern therapeutic claims for protein supplements, creating compliance complexity distinct from US or EU frameworks. Brisbane contract manufacturers specialize in protein bar extrusion for Asia-Pacific export.
Canada
Health Canada and PMRA oversight applies to natural health product classifications for sacha inchi protein. Toronto and Vancouver direct-to-consumer channels show subscription retention rates exceeding conventional sports nutrition retail. Cross-border e-commerce integration with US fulfillment networks accelerates market access for emerging brands.
Sacha Inchi Protein Market Competitive Landscape
Capital-heavy Amazonian processors compete with asset-light North American formulation specialists in a bifurcated structure. The market fragments vertically: upstream seed collection and oil extraction demand agricultural equipment and cooperative management capacity, while downstream branding and distribution reward digital marketing expertise and regulatory affairs navigation. Three archetypes dominate—integrated Peruvian originators with smallholder networks, US-based ingredient blenders serving contract manufacturers, and direct-to-consumer brands controlling subscription relationships. Competitive moves concentrate in strategic partnerships securing offtake agreements before EFSA authorization and portfolio diversification into cosmeceutical peptide applications.
Within the integrated originator tier, MG Natura Peru S.A.C. and Peruvian Nature exemplify Amazonian supply chain control through direct smallholder partnerships in San Martín. Axiom Foods occupies the North American ingredient blending position, extending allergen-free protein portfolios for California and Texas contract manufacturers. These three anchors demonstrate how geographic specialization and regulatory capacity separate sustainable competitive positions in a market where EFSA timeline friction favors players with diversified revenue streams.
| Leading Market Players |
|---|
| Axiom Foods |
| Flora Manufacturing & Distributing Ltd. |
| NP Nutra |
| Imlak'Esh Organics |
| MG Natura Peru S.A.C. |
| Peruvian Nature |
| HerboNutra |
| MaiSavanhLao |
| Nature's Power Nutraceuticals |
| Others |
Value Network & Pricing Analysis
Enzymatic hydrolysis specialists in California and Texas command wage premiums that widen spreads between commodity-grade powder and functional isolate tiers. Labor-cost differentials between Amazonian collection points and North American processing facilities amplify price stratification across certification levels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates regenerative-certified isolate from conventional organic concentrate and bulk commodity powder. Price differentiation hinges on EFSA Novel Food authorization status and dual USDA Organic plus Regenerative Organic Certified stacking. Cost compression in the economy tier is intensifying because Brazilian and Colombian entrants are expanding raw seed cultivation. Vegan consumers in German direct-to-consumer channels show least price sensitivity, while Texas CrossFit affiliates purchasing bulk powder exhibit highest elasticity.
Supply Chain Analysis
Direct-to-brand channels handle North American sports nutrition demand, while European importers rely on distributor intermediaries pending EFSA clearance. Geographic supply concentration centers on Peru, with emerging volumes from Brazil and Colombia. Raw material dependencies encompass Amazonian seed stock, hexane or enzymatic extraction reagents, and spray-drying energy inputs. Single-source vulnerability in Peru's San Martín cooperatives exposes processors to El Niño precipitation disruption. Distribution runs through Los Angeles contract manufacturers for US formulation, Hamburg direct-to-consumer platforms for EU vegan segments, and Toronto subscription services for Canadian health enthusiasts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal operates as a regulatory compounder, with binding sustainable protein procurement mandates forcing manufacturer reformulation toward verified Amazonian-origin ingredients.
For Market Incumbents: Anticipate whey protein substitution threats from Wisconsin and New Zealand dairy processors by securing multi-year offtake agreements with San Martín cooperatives before competitors lock supply. Invest in cold-pressed oil co-product infrastructure to improve unit economics against mid-tier entrants lacking integrated processing. Certification investment in dual USDA Organic and Regenerative Organic Certified stacking defends shelf placement premiums at Sprouts Farmers Market and Whole Foods Market. For New Entrants and Emerging Players: Enter via Australian and Canadian direct-to-consumer subscription channels where influencer-led PDCAAS education drives trial conversion with lower customer acquisition costs than saturated US markets. Target German vegan consumers through carbon footprint disclosure and sustainability messaging, as this cohort shows highest retention rates and lowest price sensitivity. White-space exists in South Korean cosmeceutical peptide applications for hydrolyzed sacha inchi fractions targeting dermal collagen support. For Investors and Strategic Acquirers: North American sports nutrition brands with established GRAS self-affirmation pathways are the most active acquirer in this space, seeking Amazonian supply security ahead of EU authorization. Long-term viability centers on processors with captive smallholder networks and enzymatic hydrolysis capacity spanning the 5-10 year window. Acquisition target archetype: integrated Peruvian originators with direct farmer partnerships and toxicology study completion for EFSA dossier submission. Monitor EFSA Novel Food authorization timelines as the critical inflection signal for EU revenue recognition acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Dossier Completion | Unlocks EU market access for sports nutrition and food applications, enabling revenue recognition from German and broader European formulation demand. |
| Smallholder Cooperative Partnership Expansion | MG Natura Peru S.A.C. and Peruvian Nature anchor supply security through direct farmer relationships in San Martín and Ucayali regions. |
| Enzymatic Hydrolysis Capacity Addition | California contract manufacturers achieve 90%+ protein concentration while preserving emulsification capacity for beverage applications. |
| Direct-to-Consumer Subscription Launch | Australian and Canadian urban markets concentrate fastest-growing channel with influencer-led education driving trial conversion. |
| Cosmeceutical Peptide Application Development | Hydrolyzed fractions target South Korean skincare formulations for dermal collagen support, diversifying beyond nutrition. |
Research Methodology
Direct dialogue with Amazonian cooperative managers, California contract manufacturing executives, German direct-to-consumer brand founders, and EFSA regulatory consultants grounded qualitative findings in operational reality. Secondary validation drew from FDA GRAS notification databases, EFSA Novel Food approved and pending lists, Peruvian agricultural export statistics, and USDA organic certification registries. Bottom-up seed production estimates from San Martín and Ucayali regions triangulated against top-down sports nutrition formulation demand in North American and European markets.
Bottom-up modeling tracked raw seed volumes through oil extraction and protein isolate yields, while top-down analysis scaled from addressable sports nutrition and plant-based food market penetration assumptions. Segmentation dimensions encompassed product type, end-user cohort, application format, and distribution channel, with regional regulatory pathway status as an industry-specific overlay. CAGRs were derived from trajectory fitting across historical Amazonian export growth and projected European authorization timing. Forecast inputs included El Niño cycle impact on flowering yields and enzymatic hydrolysis adoption curves among North American processors.
Inputs from EFSA dossier tracking, Peruvian agricultural ministry reports, and North American contract manufacturer capacity disclosures were available through the study window; gaps in real-time smallholder yield data and proprietary brand formulation volumes introduce uncertainty bands around production estimates. Forecasts reflect assumptions regarding EU Green Deal enforcement timing and sports nutrition brand reformulation velocity. Periodic stress-testing of base assumptions is recommended, particularly around EFSA authorization delays and Amazonian climate volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
Europe Botanical Extract Market
Functional Food & Ingredients
Global Probiotic Ingredients Market
Functional Food & Ingredients
Poultry Probiotic Ingredients Market
Functional Food & Ingredients
North America Pea Protein Ingredients Market
Functional Food & Ingredients
Functional Ingredients Market
Functional Food & Ingredients
Africa Algae Omega-3 Ingredients Market
Functional Food & Ingredients
Protein Cookie Market
Functional Food & Ingredients
Omega 3 PUFA Market
Functional Food & Ingredients
Vegan DHA Market
Functional Food & Ingredients
Superfood Powders Market
Functional Food & Ingredients
Functional Food Ingredients Market
Functional Food & Ingredients
North America and Europe Medical Foods Market
Functional Food & Ingredients
Prebiotic Ingredients Market
Functional Food & Ingredients
Low-Carb Low-Fat Meal Market
Functional Food & Ingredients
Lovage Extract Market
Functional Food & Ingredients
Beta Glucan and Fucoidan Market