
 Global Medical Foods Market | 2026-2036
Global Medical Foods Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Foods Market Foresight
North America is rewriting capacity expectations as domestic manufacturers expand enteral nutrition production to reduce import dependency. Danone leverages its specialized nutrition infrastructure across multiple therapy areas to sustain premium positioning. Abbott anchors hospital formulary access through clinical validation programs that differentiate its metabolic formulas from commodity alternatives. Nestlé competes via direct-to-patient distribution models that control last-mile delivery to home healthcare providers.
Medical foods constitute formulated products intended for dietary management of diseases with distinctive nutritional requirements, typically administered under physician supervision and processed to precise macronutrient and micronutrient specifications. These products serve primarily to bridge nutritional gaps where conventional diet modification proves insufficient for therapeutic outcomes. Enteral nutrition commands the largest revenue pool due to institutional procurement scale, while metabolic formulas represent the fastest-expanding category as rare disease screening expands newborn diagnostic protocols. Home healthcare providers emerge as the highest-margin end-user channel because reimbursement structures favor outpatient administration over acute care stays.
The FDA maintains distinct regulatory classification for medical foods separate from drugs and dietary supplements, creating specific formulation and labeling compliance obligations that shape manufacturer R&D allocation. EFSA and Health Canada apply parallel but non-identical standards, forcing multinational suppliers to maintain multiple specification tiers across production batches. Stakeholders must monitor evolving reimbursement eligibility criteria as payors recalibrate coverage thresholds between medical foods and standard nutritional supplements.
Market Dynamics
Hospital formulary consolidation is compressing supplier margins as group purchasing organizations centralize enteral nutrition procurement across multi-hospital networks, forcing manufacturers to absorb pricing pressure or sacrifice volume access.
Growth Catalysts
- Medicare reimbursement expansion:US Centers for Medicare & Medicaid Services broadened coverage for home-based nutritional therapy, accelerating patient discharge protocols and shifting administration from acute care to outpatient settings.
- Newborn screening mandates:State-level expansion of metabolic disorder detection protocols in the United States and European Union member states is enlarging the addressable patient base for disease-specific formulas.
- Precision fermentation:Novel protein production methods are reducing input cost volatility for amino acid-based formulations while enabling tighter macronutrient control in metabolic products.
Market Restraints
- Whey protein concentrate volatility:Dairy commodity price swings directly compress gross margins on enteral nutrition products where protein constitutes the dominant input cost.
- Single-source API dependency:China controls the majority of global L-carnitine and specific amino acid production, creating supply vulnerability for metabolic formula manufacturers.
- FDA-EFSA specification divergence:Differing micronutrient labeling thresholds between US and European regulators force dual-batch production or market-specific inventory, elevating working capital requirements.
Strategic Opportunities
- Brazilian rare disease protocols:ANVISA streamlined orphan disease nutritional product registration, opening Latin America's largest healthcare market to specialized metabolic formula entrants.
- Remote patient monitoring integration:Connected feeding pumps and telehealth oversight platforms enable proactive intervention, reducing hospital readmission liability for home healthcare providers.
- Japan's FOSHU functional food pathway:METI's Foods for Specified Health Uses framework offers a regulatory bridge for medical food manufacturers seeking consumer-facing distribution without full pharmaceutical registration.
Industry Challenges
- Clinical dietitian shortage:Specialized nutrition credentialing programs in the United States and Germany are failing to match hospital and home care demand, constraining patient onboarding capacity.
- Legacy ERP integration:Home healthcare distributors struggle to synchronize lot-level traceability data with manufacturer quality management systems, delaying adverse event response protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Foods Market |
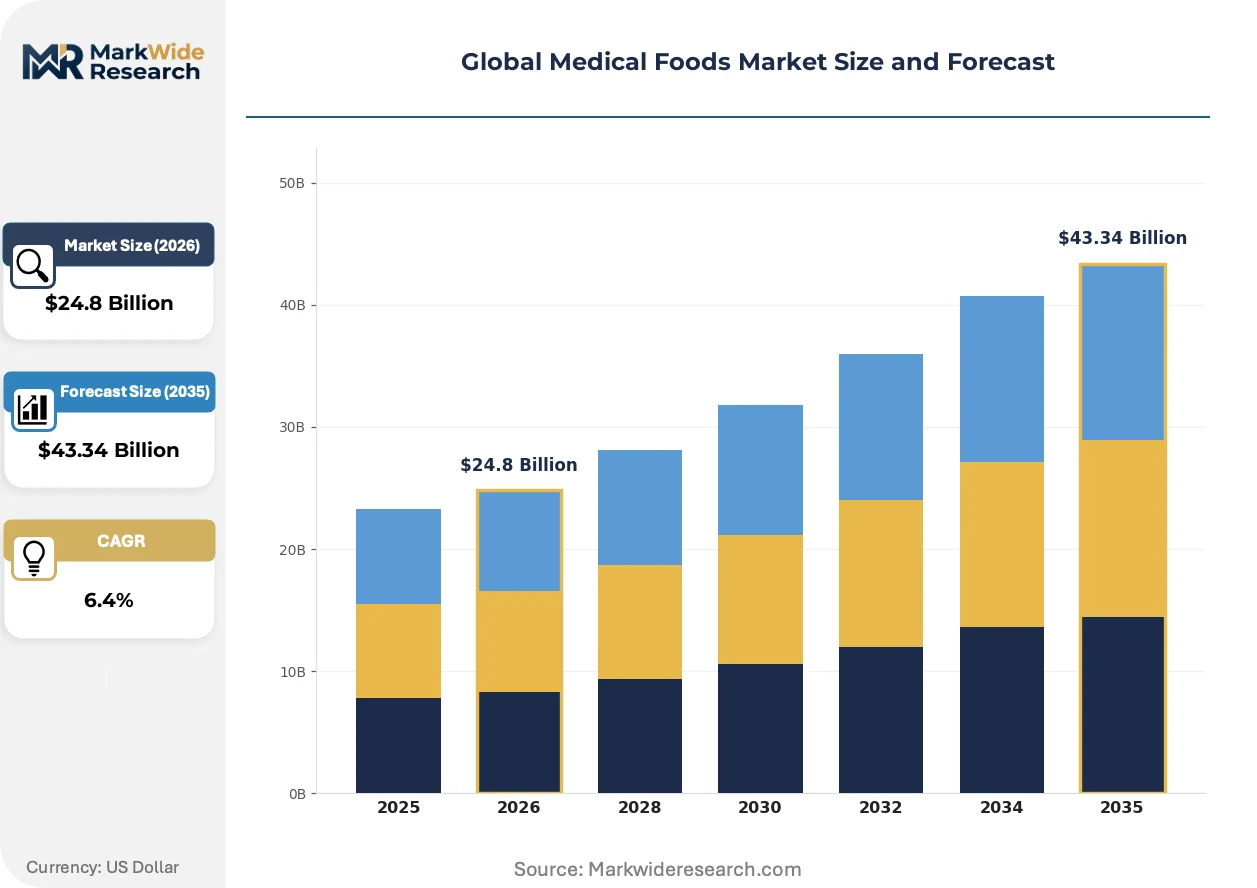
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enteral Nutrition, Metabolic Formulas, Oral Nutritional Supplements, Specialized Nutritional Drinks, Protein Formulas Therapy Area: Neurological Disorders, Metabolic Disorders, Gastrointestinal Conditions, Immunodeficiency Syndrome, Renal Dysfunction End User: Hospitals, Long-Term Care Facilities, Home Healthcare Providers, Outpatient Clinics, Rehabilitation Centers Distribution Channel: Pharmacies, Online Retailers, Medical Supply Distributors, Direct Sales, Specialty Stores |
| Companies Covered | Danone, Nestlé, Abbott, Fresenius Kabi AG, Primus Pharmaceuticals Inc., Mead Johnson & Company LLC, Targeted Medical Pharma Inc., Reckitt Benckiser Group PLC, Medtrition Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Foods Market Shifts & Advancements
Formulation science and delivery mechanisms are converging to enable personalized dosing protocols that adapt to individual metabolic profiles rather than disease-category averages.
Artificial intelligence-driven compounding systems are digitizing the production workflow for patient-specific medical foods. Regional hospital networks in Germany and the Netherlands are piloting these platforms for in-house metabolic formula preparation. The technology is digitizing quality control documentation, compressing batch release timelines from weeks to days while maintaining FDA and EFSA compliance standards.
REACH regulation amendments targeting chemical substance authorization are tightening scrutiny on synthetic vitamin precursors used in enteral nutrition. Manufacturers must now submit extended safety dossiers for retinol and pyridoxine derivatives previously grandfathered under earlier frameworks. Metabolic formula suppliers with European production footprints are responding by accelerating natural-source vitamin qualification programs to preempt authorization delays.
Direct-to-patient subscription models are displacing traditional distributor intermediation in home healthcare channels. Specialized nutrition providers in the United States and Australia are building proprietary logistics networks that bypass wholesale pharmaceutical distributors. This channel compression is most visible in pediatric metabolic disorder management, where parents prioritize continuity of supply over formulary flexibility and respond to automated replenishment systems that eliminate stockout risk.
Global Medical Foods Market Segmentation
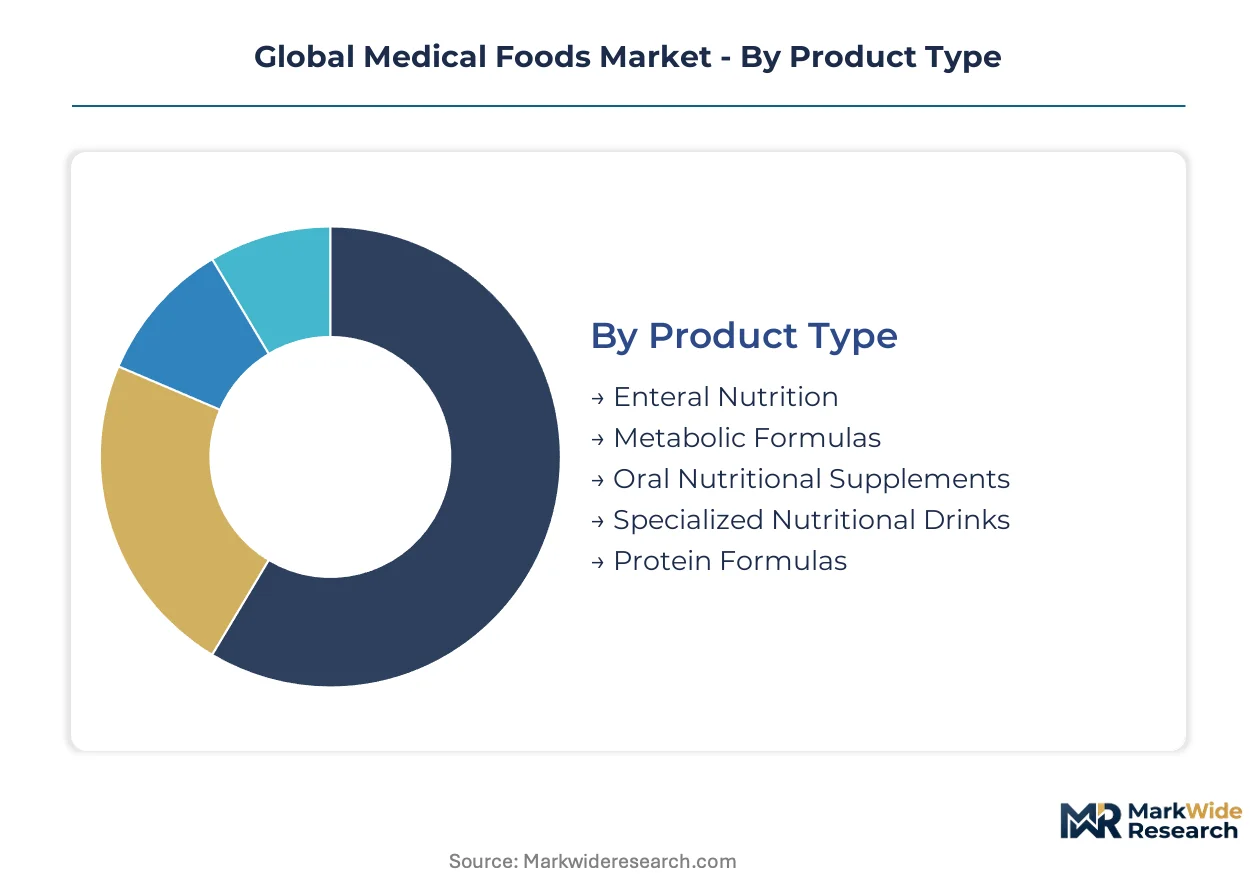
Medical foods segmentation reveals divergent margin profiles across administration settings and disease categories. Hospital procurement cycles operate on annual tenders while home healthcare subscriptions reset monthly, creating fundamentally different working capital dynamics for manufacturers.
Product Type:
Inventory velocity varies dramatically across formulation categories, with enteral nutrition turning over fastest due to institutional procurement scale while metabolic formulas sit in specialized distribution channels with extended shelf-life requirements.
- Enteral Nutrition:Tube-delivered formulations processed to precise osmolality and caloric density specifications for patients unable to tolerate oral intake. Demand concentrates in United States hospital systems where CMS reimbursement protocols favor early enteral feeding initiation to reduce infection risk. Abbott and Danone dominate formulary access through clinical validation programs that demonstrate reduced length-of-stay metrics.
- Metabolic Formulas:Disease-specific amino acid-modified products for inborn errors of metabolism such as phenylketonuria and maple syrup urine disease. Demand is concentrating in Germany and the Netherlands where expanded newborn screening mandates enlarge the diagnosed patient base. Precision fermentation methods are reducing input cost volatility for amino acid precursors.
- Oral Nutritional Supplements:Palatable drinkable formulations targeting malnutrition in ambulatory patients. United States nursing homes and Japanese eldercare facilities drive volume.
- Specialized Nutritional Drinks:Condition-specific beverages for diabetes or renal dysfunction management. Australian and Canadian home healthcare channels show strongest uptake.
- Protein Formulas:Concentrated protein modules for wound healing and sarcopenia intervention. Post-acute rehabilitation centers in France and Spain generate consistent demand.
Enteral nutrition anchors the volume base while metabolic formulas gain share at the steepest rate.
Therapy Area:
Reimbursement complexity stratifies across disease categories, with metabolic disorders commanding premium pricing through orphan drug parallels while gastrointestinal conditions face commoditization pressure from standard nutritional supplements.
- Metabolic Disorders:Phenylketonuria, galactosemia, and homocystinuria require lifelong amino acid-restricted formulas with precise micronutrient fortification. State-level newborn screening expansion in Texas, California, and New York enlarges the United States addressable population. ANVISA's streamlined Brazilian registration pathway opens Latin America's largest market to specialized entrants.
- Neurological Disorders:Ketogenic diet formulations for epilepsy and medium-chain triglyceride products for Alzheimer's cognitive support. Pediatric neurology departments at Boston Children's Hospital and Great Ormond Street Hospital drive protocol adoption through clinical trial networks.
- Gastrointestinal Conditions:Elemental and semi-elemental formulas for Crohn's disease, short bowel syndrome, and eosinophilic esophagitis. United Kingdom and Italian gastroenterology societies publish consensus guidelines that shape prescribing patterns.
- Immunodeficiency Syndrome:Immune-modulating nutritional support for HIV and primary immunodeficiency patients. South African public health programs and Thai hospital networks represent concentrated demand pockets.
- Renal Dysfunction:Phosphate-restricted, protein-modified formulations for chronic kidney disease. Japanese dialysis clinics and German nephrology practices sustain niche volume.
Metabolic disorders command the highest per-patient revenue while gastrointestinal conditions deliver the largest aggregate patient volume.
End User:
Channel economics invert traditional healthcare patterns, with home administration generating superior margins than institutional settings due to reimbursement structures that favor outpatient over acute care stays.
- Home Healthcare Providers:Specialized nursing services managing enteral feeding and metabolic formula administration in residential settings. United States Medicare reimbursement expansion for home-based nutritional therapy accelerates patient discharge protocols. Nestlé's direct-to-patient distribution models control last-mile delivery and capture subscription revenue streams.
- Hospitals:Acute care facilities purchasing enteral nutrition through group purchasing organization contracts. Multi-hospital network consolidation in Germany and the Netherlands compresses supplier margins through centralized procurement.
- Long-Term Care Facilities:Nursing homes and skilled nursing facilities managing chronic malnutrition. Ontario and Quebec provincial health systems in Canada drive standardized formulary adoption.
- Outpatient Clinics:Ambulatory settings prescribing oral nutritional supplements for preventive intervention. Australian primary care networks and Spanish community health centers show expanding utilization.
- Rehabilitation Centers:Post-acute facilities addressing protein-energy malnutrition during recovery. Stroke and orthopedic rehabilitation units in Switzerland and Austria generate specialized demand.
Home healthcare providers deliver the steepest margin expansion trajectory while hospitals retain the largest absolute revenue pool.
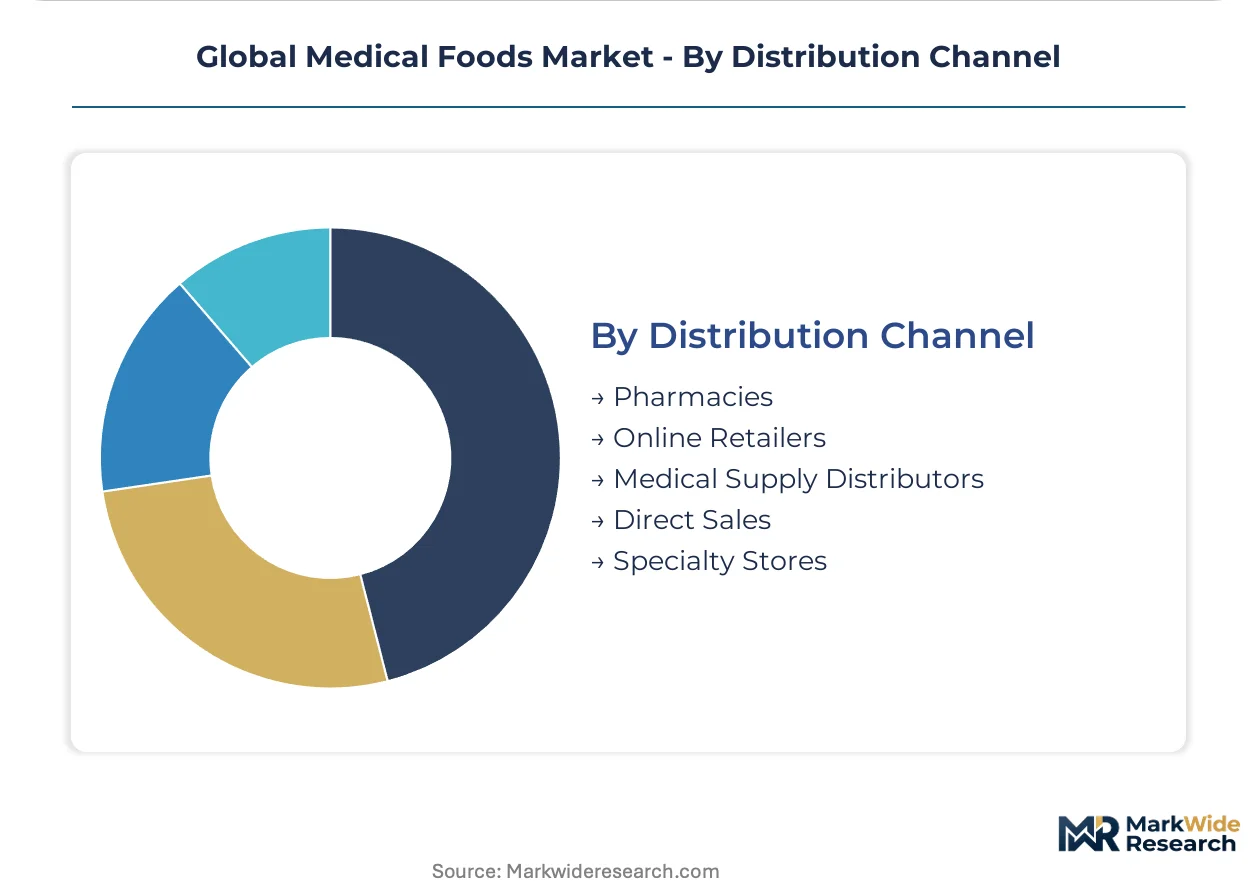
Distribution Channel:
Channel compression is displacing traditional pharmaceutical wholesale intermediation, with manufacturers building proprietary logistics networks that bypass distributors to capture margin and ensure supply continuity for critical therapies.
- Direct Sales:Manufacturer-controlled distribution to hospitals and home healthcare providers. Danone and Abbott deploy specialized nutrition sales forces that maintain direct relationships with clinical dietitians and metabolic specialists. This channel captures the highest margin by eliminating wholesale markups.
- Medical Supply Distributors:Specialized healthcare logistics providers handling temperature-controlled storage and lot-level traceability. United States distributors struggle with legacy ERP integration that delays adverse event response protocols.
- Pharmacies:Community and hospital pharmacy networks dispensing oral nutritional supplements. French and Italian pharmacy chains maintain strong patient counseling relationships that influence brand selection.
- Online Retailers:E-commerce platforms serving consumer-directed purchases of specialized nutritional drinks. Australian and United Kingdom regulatory frameworks permit certain medical food categories in direct-to-consumer channels.
- Specialty Stores:Nutrition-focused retail outlets catering to specific dietary requirements. Japanese FOSHU-certified functional food distribution through convenience and health food channels.
Direct sales channels are expanding most quickly while medical supply distributors retain the largest institutional volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA labeling requirements and CMS reimbursement protocols anchor the United States as the regulatory benchmark shaping formulation standards worldwide. Hospital procurement consolidation and home healthcare expansion are redrawing geographic demand patterns across major economies.
United States
Medicare reimbursement expansion for home-based nutritional therapy accelerates patient discharge protocols from acute care facilities. The FDA's updated labeling requirements for medical foods impose distinct formulation compliance obligations separate from drugs and dietary supplements. Boston Children's Hospital and pediatric metabolic centers in Texas drive clinical validation networks for rare disease formulas.
Germany
Expanded newborn screening mandates for metabolic disorders enlarge the diagnosed patient base requiring lifelong amino acid-modified formulas. EFSA micronutrient labeling thresholds diverge from FDA specifications, forcing dual-batch production strategies for multinational suppliers. The Netherlands-Germany hospital network corridor pilots AI-driven compounding systems for in-house metabolic formula preparation.
Japan
METI's Foods for Specified Health Uses framework offers regulatory pathways for medical food manufacturers seeking consumer-facing distribution. Aging demographics in Kanto and Kansai regions concentrate demand for specialized nutritional drinks in eldercare facilities. Dialysis clinics in Nagoya and Osaka sustain niche volume for phosphate-restricted renal formulations.
Brazil
ANVISA streamlined orphan disease nutritional product registration, opening Latin America's largest healthcare market to specialized metabolic formula entrants. State-level rare disease protocols in São Paulo and Minas Gerais expand diagnostic capacity for phenylketonuria and maple syrup urine disease. Pediatric metabolic centers in Rio de Janeiro anchor clinical trial networks for amino acid-based formulations.
Australia
Primary care networks in New South Wales and Victoria show expanding utilization of oral nutritional supplements for preventive intervention. The TGA permits certain medical food categories in direct-to-consumer e-commerce channels, diverging from prescription-gated distribution models. Home healthcare providers in Queensland build proprietary logistics networks bypassing traditional pharmaceutical wholesale intermediation.
Global Medical Foods Market Competitive Landscape
Capability concentration sits with specialized nutrition manufacturers possessing clinical validation infrastructure; scale advantage sits with diversified food and pharmaceutical conglomerates operating multi-therapy portfolios. The vendor base stratifies across three tiers: global diversified nutrition groups with hospital formulary dominance, mid-cap metabolic specialists with rare disease focus, and regional compounding pharmacies serving patient-specific formulations. Two dominant competitive moves define current positioning: direct-to-patient distribution models that compress channel margins, and precision fermentation investments that reduce amino acid input cost volatility.
Within the diversified nutrition tier, Danone, Nestlé, and Abbott exemplify divergent strategic archetypes. Danone leverages specialized nutrition infrastructure across multiple therapy areas to sustain premium positioning in European and Asian markets. Nestlé competes through direct-to-patient distribution models controlling last-mile delivery to home healthcare providers, particularly in pediatric metabolic disorder management. Abbott anchors hospital formulary access through clinical validation programs that differentiate metabolic formulas from commodity alternatives in United States acute care networks.
| Leading Market Players |
|---|
| Danone |
| Nestlé |
| Abbott |
| Fresenius Kabi AG |
| Primus Pharmaceuticals Inc. |
| Mead Johnson & Company LLC |
| Targeted Medical Pharma Inc. |
| Reckitt Benckiser Group PLC |
| Medtrition Inc. |
| Others |
Supply & Pricing Matrix
The Rotterdam-Antwerp pharmaceutical corridor channels temperature-controlled medical food shipments from European manufacturing hubs to distribution nodes across Germany and the Netherlands, with freight cost volatility directly amplifying margin compression for metabolic formula producers while enabling price differentiation between direct-to-patient subscription tiers and institutional contract volumes.
Pricing Analysis
Price spreads between United States and European metabolic formulas reflect divergent reimbursement frameworks rather than input cost differentials. Three-tier pricing structure across premium, standard, and economy levels segments by clinical validation depth and amino acid sourcing precision, with precision fermentation-derived inputs commanding sustained premiums. Pricing pressure stems from group purchasing organization consolidation across United States hospital networks, forcing absorption or volume sacrifice. Home healthcare providers exhibit lowest price sensitivity due to Medicare reimbursement cushioning, while long-term care facilities face acute budget constraints.
Supply Chain Analysis
Contract manufacturing for amino acid-based metabolic formulas concentrates with Lonza, Catalent, and Patheon facilities across Switzerland, Germany, and Singapore, with these sites handling the majority of FDA and EFSA dual-compliant batch production. Raw material dependencies center on Chinese L-carnitine and lysine precursors, New Zealand whey protein isolates, and Indian vitamin premix concentrates. Single-source API vulnerability from Chinese amino acid dominance creates tariff exposure and geopolitical disruption risk. Distribution runs through manufacturer-direct sales forces for hospital formulary access, bypassing traditional pharmaceutical wholesale markups in the highest-margin home healthcare channel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
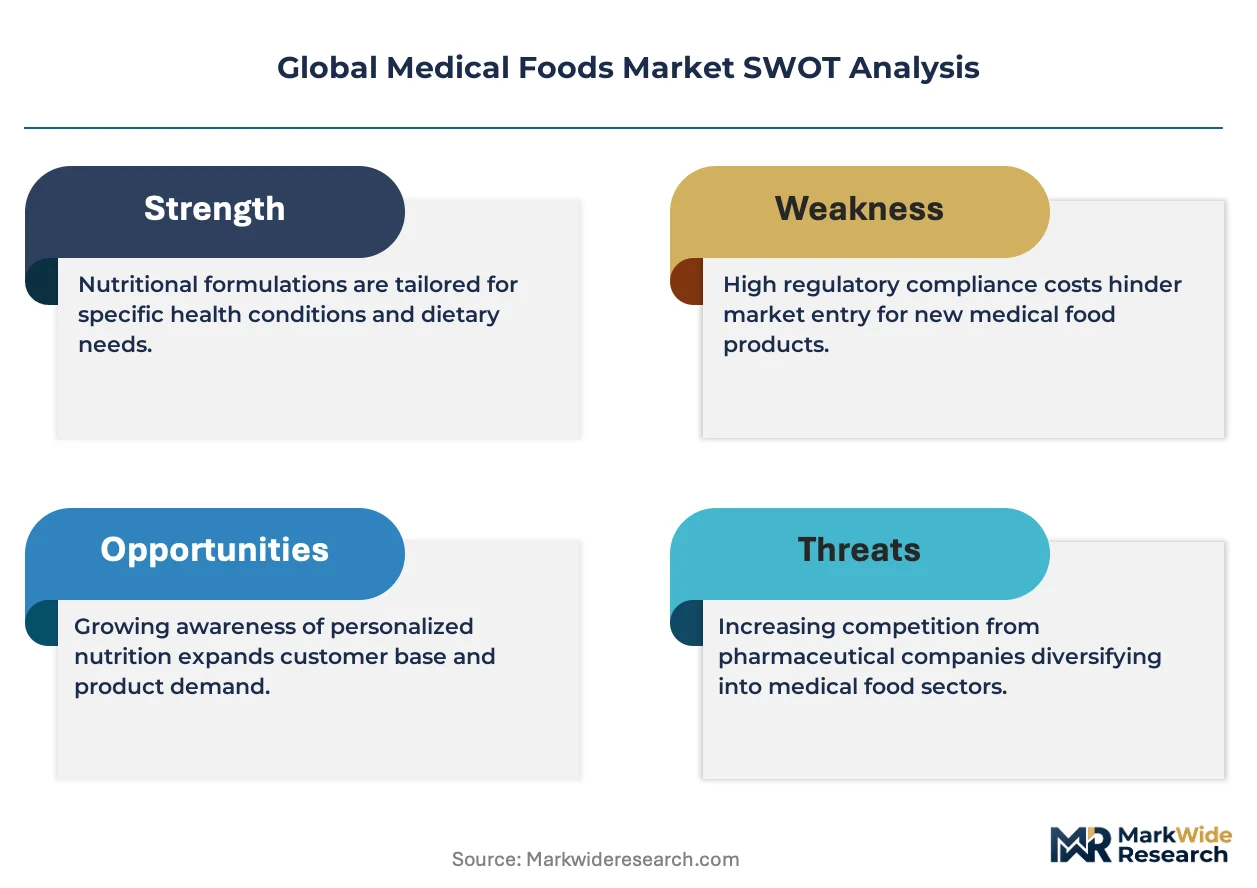
Medical foods represent an early-cycle expansion story as newborn screening mandates across Texas, California, and New York enlarge the diagnosed metabolic disorder patient base, creating durable demand for lifelong amino acid-modified formulas with limited substitution risk.
For Market Incumbents: Build clinical validation moats through hospital formulary access programs that demonstrate reduced length-of-stay metrics against commodity alternatives. Expand precision fermentation capacity in European production footprints to preempt REACH authorization delays on synthetic vitamin precursors. Anchor defensive positioning against direct-to-patient distribution challengers by controlling last-mile logistics partnerships with home healthcare providers. For New Entrants and Emerging Players: Brazilian rare disease protocols under ANVISA represent the most penetrable entry point for specialized metabolic formula manufacturers seeking Latin American expansion. Australian direct-to-consumer regulatory pathways for oral nutritional supplements offer secondary white-space with lower capital requirements. Pursue go-to-market angles through telehealth-integrated feeding pump platforms that enable remote patient monitoring subscriptions. For Investors and Strategic Acquirers: Regional compounding pharmacies with AI-driven patient-specific formulation capabilities represent the highest-conviction acquisition archetype for capability extension into personalized medical foods. Long-term viability hinges on reimbursement policy durability across Medicare and European statutory health insurance frameworks. Monitor ANVISA registration timelines and state-level newborn screening expansion legislation as early inflection signals for addressable market growth.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Reduces input cost volatility for amino acid precursors while enabling tighter macronutrient control in metabolic products. |
| Direct-to-Patient Distribution Buildout | Captures subscription revenue streams and eliminates stockout risk in pediatric metabolic disorder management. |
| AI-Driven Compounding System Deployment | Compresses batch release timelines from weeks to days while maintaining FDA and EFSA compliance standards. |
| Dual-Batch Production Capacity Addition | Addresses FDA-EFSA specification divergence that elevates working capital requirements for multinational suppliers. |
| Telehealth Platform Integration | Enables proactive intervention through connected feeding pumps, reducing hospital readmission liability for providers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with clinical dietitians, hospital procurement managers, metabolic specialists, and home healthcare logistics directors; and secondary validation against FDA medical food labeling databases, CMS Medicare reimbursement filings, EFSA micronutrient threshold specifications, and ANVISA orphan product registration records. Bottom-up patient population estimates by diagnosed metabolic disorder prevalence triangulated against top-down manufacturer revenue disclosures across the analysis window.
Forecast inputs incorporated therapy area segmentation by disease category, product type tiering by administration route and formulation complexity, end-user channel economics distinguishing institutional from home healthcare margins, and geographic regulatory cluster differentiation between FDA, EFSA, and ANVISA jurisdictions. CAGRs derived from regression analysis of historical volume trends adjusted for newborn screening mandate implementation schedules and reimbursement policy expansion trajectories.
Practitioners should monitor whey protein commodity price indices, Chinese amino acid export license modifications, and Medicare coverage determination updates for early signals of forecast revision triggers. Quarterly review of state-level newborn screening legislation, ANVISA registration approval velocities, and REACH authorization timelines for synthetic vitamin precursors is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
Beta Glucan and Fucoidan Market
Functional Food & Ingredients
Superfood Powders Market
Functional Food & Ingredients
Omega 3 PUFA Market
Functional Food & Ingredients
South America Omega-3 PUFA Market
Functional Food & Ingredients
Refined Functional Carbohydrates Market
Functional Food & Ingredients
Poultry Probiotic Ingredients Market
Functional Food & Ingredients
Europe Botanical Extract Market
Functional Food & Ingredients
Protein Cookie Market
Functional Food & Ingredients
Lovage Extract Market
Functional Food & Ingredients
Low-Carb Low-Fat Meal Market
Functional Food & Ingredients
North America Omega-3 PUFA Market
Functional Food & Ingredients
North America and Europe Medical Foods Market
Functional Food & Ingredients
Functional Non-Meat Ingredients Market
Functional Food & Ingredients
Europe Omega-3 PUFA Market
Functional Food & Ingredients
Multifunctional Food Ingredients Market
Functional Food & Ingredients
Mediterranean Cognitive-First Ingredient Systems Market