
 APAC Heart Health Functional Food Market | 2026-2036
APAC Heart Health Functional Food Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Heart Health Functional Food Market Outlook
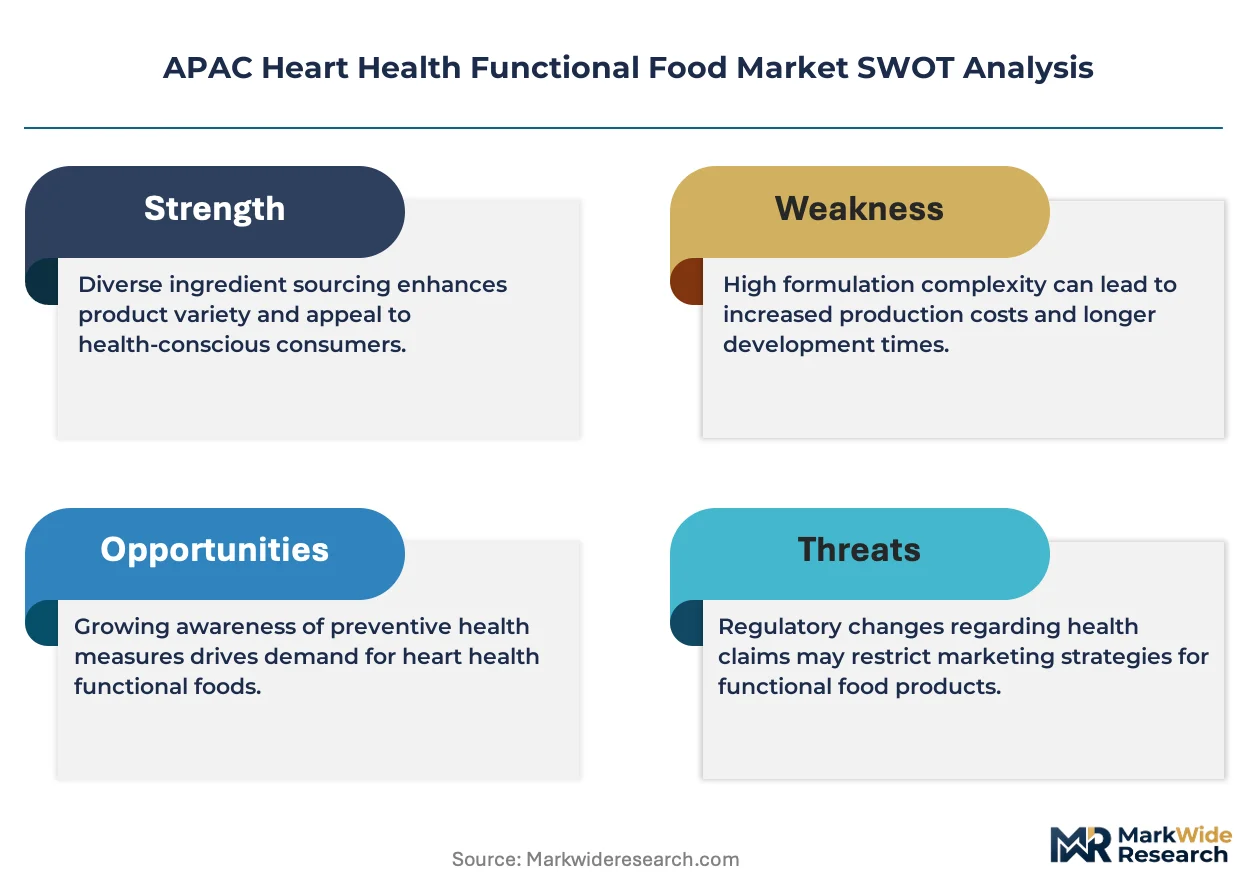
Subscription-based personalized nutrition programs is hardening as a core revenue layer across the APAC heart health functional food sector. Nestlé S.A. leverages its direct-to-consumer digital platforms to lock in recurring purchases of omega-3 fortified offerings. PepsiCo Inc. anchors its regional position through extensive cold-chain distribution networks spanning Southeast Asian pharmacy channels. Marico Ltd. differentiates via Ayurveda-infused heart health formulations targeting Indian households with established brand trust.
APAC heart health functional food comprises edible products engineered with bioactive compounds—omega-3 fatty acids, plant sterols, soluble fibers, and targeted probiotics—formulated to modulate lipid profiles, vascular function, or blood pressure parameters through regular dietary incorporation. Manufacturing employs microencapsulation to preserve thermolabile bioactives during thermal processing, ensuring label claim stability through shelf life. Omega-3 fortified products occupy the dominant value share given established clinical validation and consumer recognition of EPA/DHA efficacy. Probiotics represent the fastest-expanding ingredient class as mechanistic research links specific strains to cholesterol metabolism modulation. Fiber-enriched foods sustain mature volume positions in Japan and Australia where habitual consumption patterns already embed oat beta-glucan and psyllium products.
Japan's Consumer Affairs Agency enforces Foods with Function Claims labeling rules that mandate substantiation dossiers for each heart-related health claim, creating a compliance moat favoring capitalized multinationals. India's FSSAI fortification standards under the Food Safety and Standards Act govern permissible nutrient additions in edible oils and dairy, directly shaping local formulation possibilities. Australia's TGA overlapping jurisdiction with Food Standards Australia New Zealand introduces dual-track assessment complexity for products blurring food-supplement boundaries. Stakeholders must monitor evolving strain-specific probiotic claim acceptance across these frameworks to preempt reformulation costs and market access delays.
Market Dynamics
Japan's Consumer Affairs Agency is tightening evidentiary standards for Foods with Function Claims, forcing manufacturers to build proprietary clinical dossiers rather than rely on generic ingredient studies. This regulatory escalation concentrates competitive advantage among firms with captive research infrastructure.
Growth Catalysts
- India's FSSAI fortification mandate:Edible oil and dairy fortification standards under the Food Safety and Standards Act create guaranteed volume anchors for plant sterol and omega-3 suppliers.
- Preventive cardiology clinic expansion:Metro corridor clinics in Mumbai, Delhi, and Bangalore integrate dietary intervention programs, generating institutional procurement pull for prescription-aligned functional foods.
- Microencapsulation process maturation:Thermolabile bioactive preservation technology enables shelf-stable EPA/DHA claims in ambient retail channels previously restricted to refrigerated formats.
Market Restraints
- Anchovy and krill supply concentration:Omega-3 raw material sourcing clusters in Peruvian and Antarctic fisheries, exposing formulation costs to El Niño-driven catch volatility and quota restrictions.
- Strain-specific probiotic substantiation gaps:Mechanistic research linking Lactobacillus and Bifidobacterium species to cholesterol modulation remains incomplete, blocking claim expansion in Japan's FFC system.
- Dual-track assessment friction:Australia's TGA and Food Standards Australia New Zealand overlapping jurisdiction creates classification ambiguity for products positioned between food and therapeutic boundaries.
Strategic Opportunities
- Indonesia's pharmacy channel formalization:Cold-chain infrastructure investment in Jakarta and Surabaya enables omega-3 fortified distribution through Apotek K-24 and Kimia Farma networks previously inaccessible to perishable functional foods.
- Ayurveda-botanical convergence:Arjuna bark and garlic extract formulations aligned with India's AYUSH Ministry guidelines open differentiated positioning in domestic heart health segments.
- Subscription platform penetration:Direct-to-consumer recurring purchase models bypass traditional retail slotting fees and build longitudinal consumer data for personalized formulation refinement.
Industry Challenges
- Clinical trial design complexity:Demonstrating LDL-C reduction through dietary intervention requires extended study durations and larger cohorts than pharmaceutical equivalence trials, stretching R&D timelines.
- Cross-border strain registration inconsistency:Probiotic identity preservation from manufacturing through shelf life demands harmonized analytical methods not yet standardized between Japan's PMDA and Australia's TGA.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Heart Health Functional Food Market |
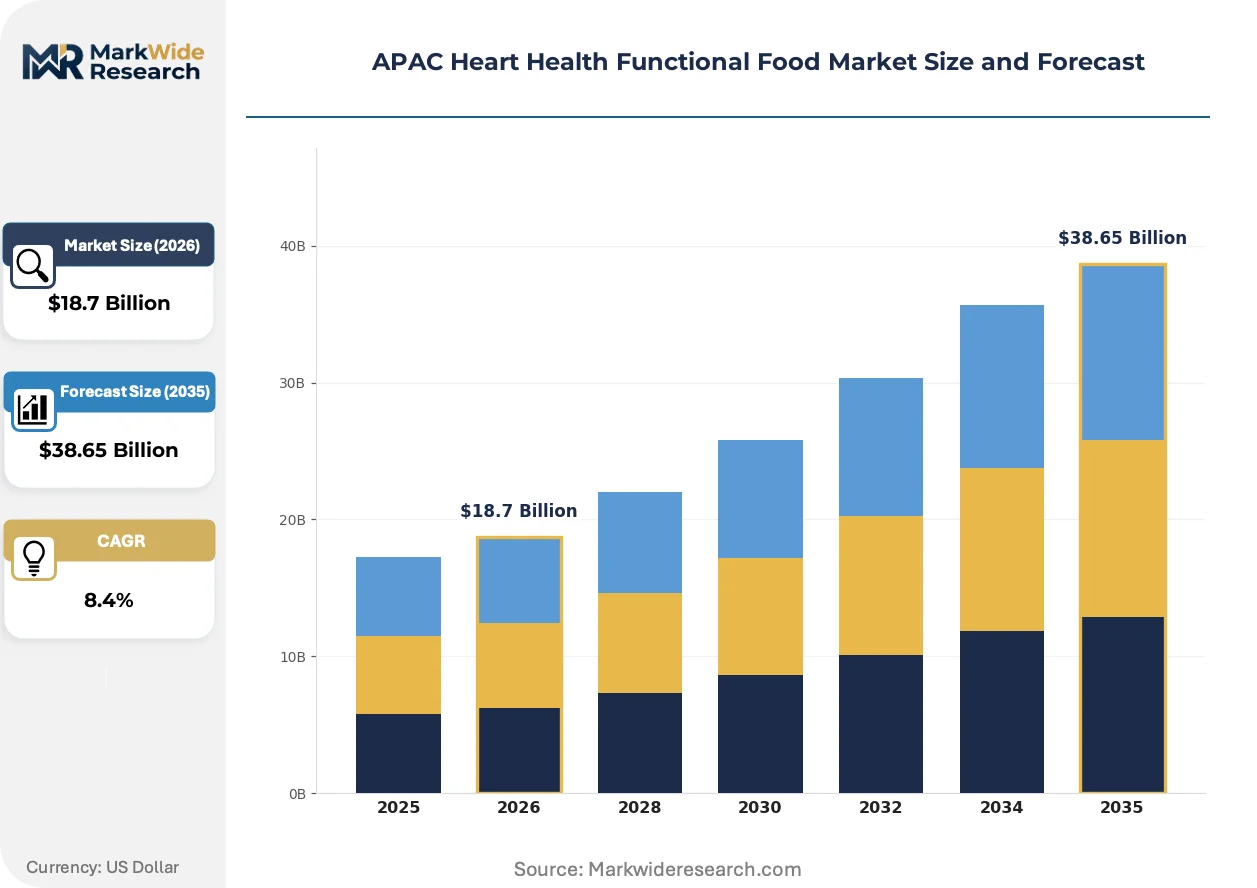
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Omega-3, Plant Sterols, Fiber-Enriched Foods, Probiotics End User: Fitness Enthusiasts, Elderly Consumers, Health-Conscious Individuals, Patients with Cardiovascular Issues Ingredient Source: Natural Ingredients, Fortified Products, Herbal Extracts, Organic Sources Packaging Type: Bottles, Sachets, Boxes, Pouches |
| Companies Covered | Nestlé S.A., Kellogg Company, Marico Ltd., Raisio Plc, Kalbe Farma Tbk, PepsiCo Inc., Ruchi Soya Industries Ltd., Bagrry's India Ltd., Associated British Foods, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Heart Health Functional Food Market Strategic Shifts
Formulation science is pivoting from single-ingredient fortification toward synergistic bioactive combinations that target multiple cardiovascular risk markers simultaneously. This multi-mechanism approach demands more sophisticated manufacturing and substantiation capabilities.
Lipid-based nano-delivery systems are absorbing thermosensitive omega-3 concentrates into ambient-stable food matrices previously incompatible with EPA/DHA incorporation. Bakery and snack manufacturers in Thailand and Vietnam adopt these systems to launch shelf-stable fortified products without cold-chain dependency. The technology is absorbing market share from traditional gelatin-softgel formats in convenience-oriented consumption occasions.
China's NMPA and SAMR are harmonizing functional food claim categories with pharmaceutical-adjacent health outcome language, narrowing the regulatory gap between foods and borderline therapeutic products. This convergence pressures multinationals to rebuild dossiers using China-specific clinical endpoints rather than extrapolated foreign data. Domestic firms with established Traditional Chinese Medicine research infrastructure capture first-mover advantage in the restructured claim landscape.
Hospital discharge protocols in South Korea and Taiwan now embed dietary counseling with specific functional food recommendations, converting acute cardiac events into structured purchasing journeys. Pharmacy chains at these discharge nodes capture prescription-adjacent sales previously lost to unorganized retail. This channel capture concentrates volume in clinically credentialed distribution points rather than mass-market supermarkets.
APAC Heart Health Functional Food Market Segmentation
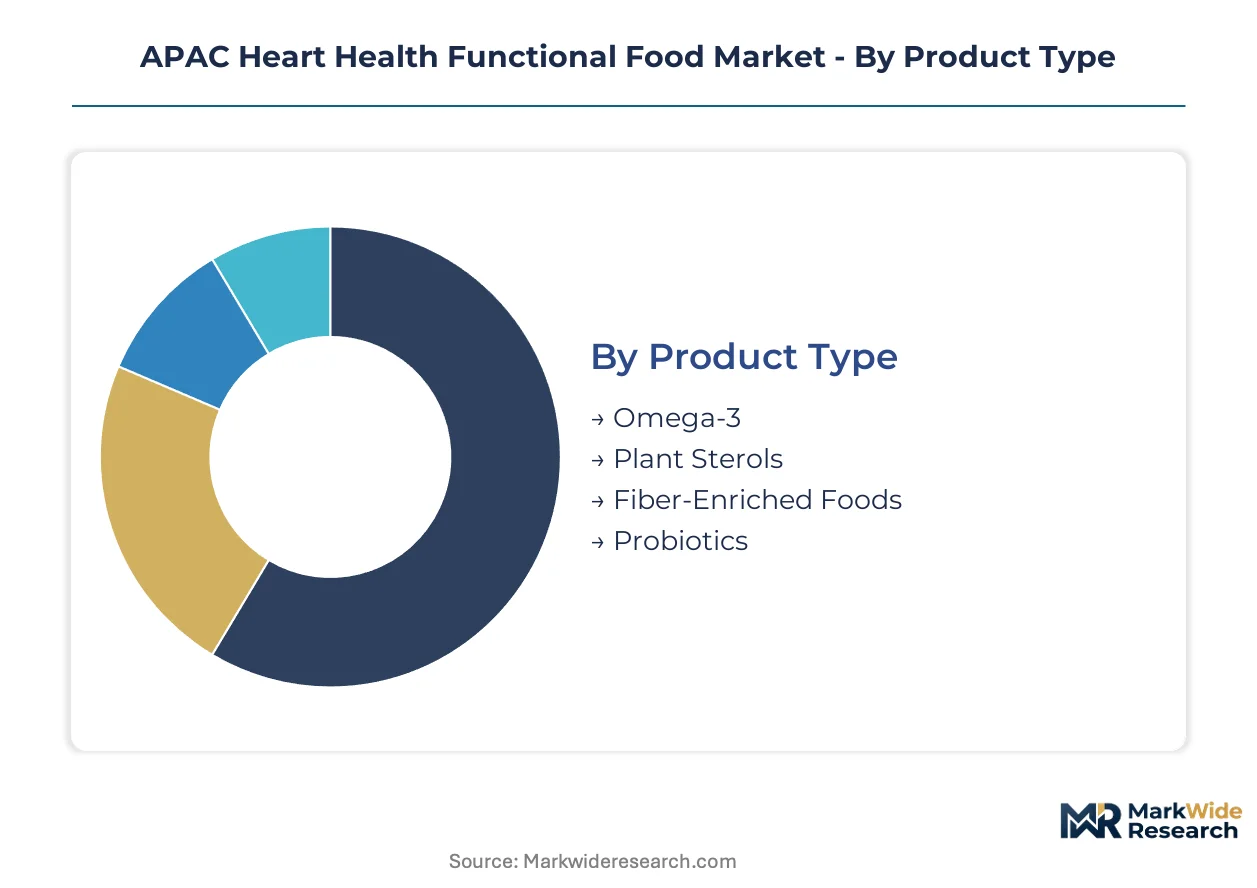
Segmentation in the APAC heart health functional food market reveals distinct technical and commercial boundaries that determine manufacturing investment, regulatory pathway selection, and channel strategy. Each dimension—product chemistry, consumer physiology, raw material provenance, and delivery format—creates separable profit pools with divergent margin structures and growth velocities.
Product Type:
Customization intensity varies sharply across this category, from commodity-scale omega-3 bulk fortification to precision-strain probiotic formulations requiring captive bioprocessing infrastructure.
- Omega-3:EPA and DHA concentrates delivered through fish oil, algal, or krill matrices dominate commercial volumes. Microencapsulation advances now enable ambient-stable incorporation into bakery and snack applications across Thailand and Vietnam, bypassing prior cold-chain constraints. Demand concentrates in urban China's clinician-directed retail channels where cardiologists recommend fortified foods alongside statin regimens.
- Probiotics:Specific Lactobacillus and Bifidobacterium strains selected for cholesterol metabolism modulation represent the most technically demanding segment. Japan's Foods with Function Claims system mandates proprietary clinical dossiers for each strain-health claim pairing, favoring multinationals with dedicated research infrastructure. Expansion is steepest in South Korea's pharmacy channels following hospital discharge protocol integration.
- Plant Sterols:Phytosterol esters for LDL-C reduction operate under established regulatory frameworks with lower substantiation burdens than probiotics.
- Fiber-Enriched Foods:Oat beta-glucan and psyllium products sustain mature positions in Japan and Australia where habitual consumption patterns already embed soluble fiber.
Most installed capacity flows through Omega-3. Expansion is steepest in Probiotics.
End User:
Price elasticity and purchase frequency diverge substantially across physiological risk profiles and self-identified health engagement levels.
- Patients with Cardiovascular Issues:Post-event consumers following myocardial infarction or stroke demonstrate highest compliance and price tolerance. South Korean and Taiwanese hospital discharge protocols now embed specific functional food recommendations, converting acute events into structured purchasing journeys through pharmacy chains at discharge nodes.
- Elderly Consumers:Aging demographics across Japan and urban China drive institutional procurement through preventive cardiology clinics. Mumbai, Delhi, and Bangalore metro corridor clinics integrate dietary intervention programs, generating recurring volume for prescription-aligned formulations.
- Health-Conscious Individuals:Subscription-based personalized nutrition programs capture this segment through direct-to-consumer digital platforms with longitudinal data collection.
- Fitness Enthusiasts:Athletic performance positioning with heart health co-benefits occupies niche premium positioning.
Revenue concentration sits with Patients with Cardiovascular Issues. Subscription model penetration is expanding fastest among Health-Conscious Individuals.
Ingredient Source:
Raw material provenance determines regulatory pathway complexity, supply security exposure, and premium pricing authorization across APAC jurisdictions.
- Natural Ingredients:Wild-caught fish oil and minimally processed botanicals command price premiums in Japan's discerning retail environment. Peruvian anchovy fishery concentration exposes formulation costs to El Niño-driven catch volatility and quota restrictions.
- Herbal Extracts:Arjuna bark and garlic extract formulations aligned with India's AYUSH Ministry guidelines open differentiated domestic positioning. Marico Ltd. leverages established brand trust to capture household penetration in this segment.
- Fortified Products:India's FSSAI edible oil and dairy fortification standards create guaranteed volume anchors for plant sterol and omega-3 suppliers.
- Organic Sources:Certified organic supply chains remain underdeveloped relative to demand in Australian premium channels.
Volume leadership belongs to Fortified Products. Premium positioning is expanding fastest in Herbal Extracts.
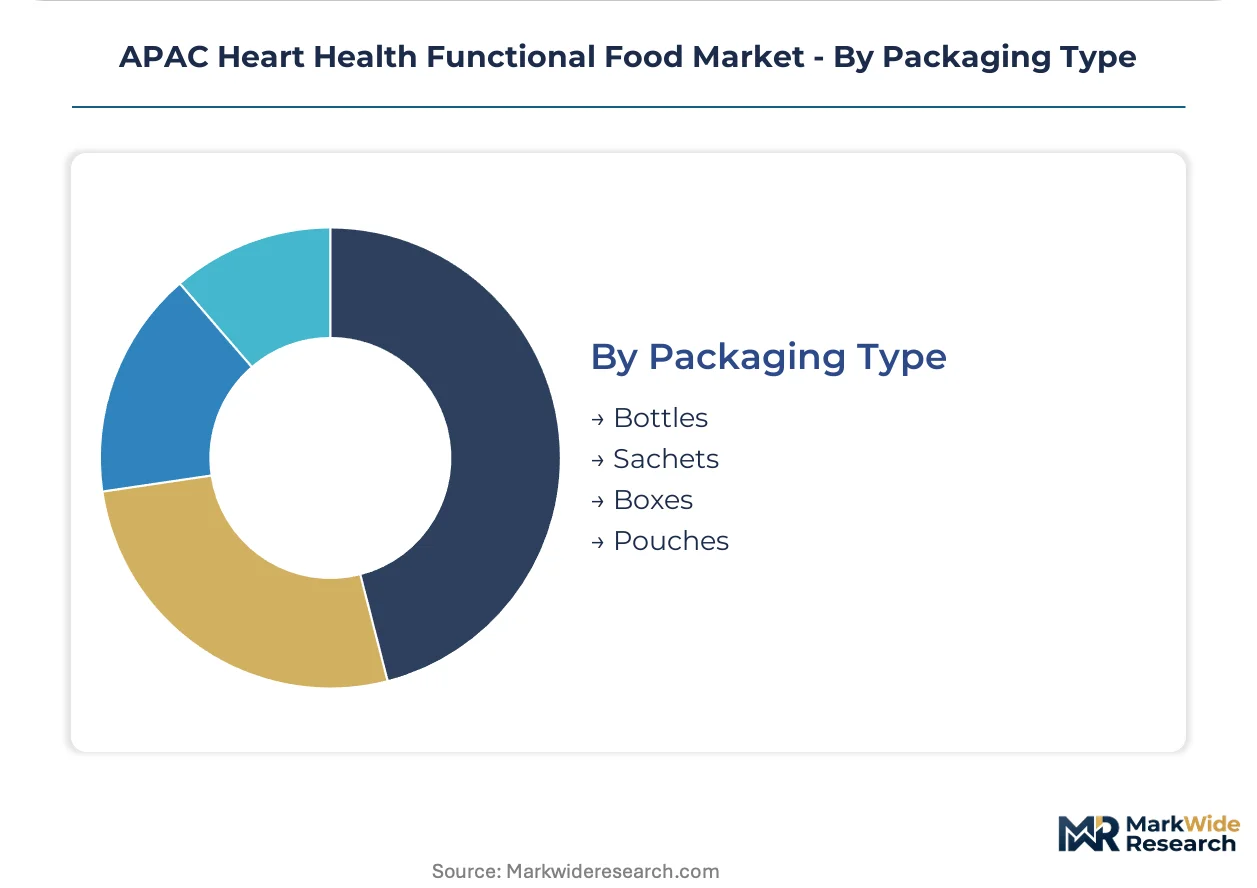
Packaging Type:
Format selection governs shelf-life engineering requirements, distribution economics, and consumption occasion targeting.
- Sachets:Single-serve powder and liquid formats dominate pharmacy channel distribution in Indonesia's emerging formal retail. Cold-chain infrastructure investment in Jakarta and Surabaya enables omega-3 fortified distribution through Apotek K-24 and Kimia Farma networks.
- Bottles:Multi-dose liquid concentrates serve household replenishment patterns in established Japanese and Australian markets.
- Pouches:Flexible packaging absorbs cost-sensitive Southeast Asian mass market volumes.
- Boxes:Carton formats align with traditional retail slotting requirements in Indian organized trade.
Distribution density is highest through Sachets. Format innovation is concentrating in Pouches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's Foods with Function Claims system creates steeper compliance barriers than India's FSSAI fortification mandates, concentrating competitive advantage among firms with captive research infrastructure in Tokyo while guaranteeing volume anchors for plant sterol suppliers in Mumbai.
China
Clinician-directed retail channels in urban centers drive demand as cardiologists recommend fortified foods alongside statin regimens. NMPA and SAMR are harmonizing functional food claim categories with pharmaceutical-adjacent health outcome language. Shanghai and Beijing host the dominant concentration of preventive cardiology clinics integrating dietary intervention programs.
Japan
Aging demographics and habitual soluble fiber consumption sustain mature volume positions for oat beta-glucan products. The Consumer Affairs Agency enforces Foods with Function Claims labeling rules that mandate substantiation dossiers for each heart-related health claim. Tokyo anchors the regional research infrastructure serving proprietary clinical dossier development.
India
Metro corridor clinics in Mumbai, Delhi, and Bangalore generate institutional procurement pull for prescription-aligned functional foods. FSSAI fortification standards under the Food Safety and Standards Act govern permissible nutrient additions in edible oils and dairy. Marico Ltd. leverages established brand trust to capture household penetration with Ayurveda-infused formulations.
South Korea
Hospital discharge protocols now embed dietary counseling with specific functional food recommendations, converting acute cardiac events into structured purchasing journeys. MFDS oversees functional food safety and labeling requirements alongside pharmaceutical-adjacent products. Pharmacy chains at Seoul discharge nodes capture prescription-adjacent sales previously lost to unorganized retail.
Indonesia
Cold-chain infrastructure investment in Jakarta and Surabaya enables omega-3 fortified distribution through Apotek K-24 and Kimia Farma networks. The national pharmaceutical regulator governs products blurring food-supplement boundaries. Urban pharmacy channel formalization is absorbing market share from traditional wet markets for perishable functional foods.
APAC Heart Health Functional Food Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with microencapsulation capability and proprietary clinical dossiers determining tier placement. The market concentrates around three strategic archetypes: multinational nutrition conglomerates with direct-to-consumer platforms, regional Ayurveda-botanical formulators, and cold-chain logistics specialists. Dominant competitive moves include subscription platform penetration to bypass retail slotting fees and backward integration into algal omega-3 cultivation to reduce Peruvian anchovy supply exposure.
Within the multinational conglomerate tier, Nestlé S.A. and PepsiCo Inc. represent divergent channel strategies, with the former leveraging digital platforms for recurring purchase models and the latter anchoring regional position through Southeast Asian pharmacy distribution. Marico Ltd. exemplifies the Ayurveda-botanical convergence archetype, occupying a differentiated position in Indian household penetration. These three entities collectively illustrate how geographic origin and structural format—S.A., Inc., and Ltd. suffixes—correlate with divergent competitive vectors across the regional market.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Kellogg Company |
| Marico Ltd. |
| Raisio Plc |
| Kalbe Farma Tbk |
| PepsiCo Inc. |
| Ruchi Soya Industries Ltd. |
| Bagrry's India Ltd. |
| Associated British Foods |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap Ayurveda formulators in India anchor supply discipline through backward integration into botanical cultivation, while their pricing power rests on AYUSH Ministry certification tiers that command premium positioning in domestic pharmacy channels.
Pricing Analysis
Capacity additions in Vietnam and Thailand are reshaping price floors for ambient-stable omega-3 bakery applications, compressing margins on legacy gelatin-softgel formats. Three-tier pricing structure across premium clinician-directed, standard pharmacy, and economy mass-market levels stratifies by certification grade and cold-chain dependency. Pricing pressure stems from El Niño-driven anchovy catch volatility transferring cost uncertainty downstream. Patients with cardiovascular issues demonstrate lowest price sensitivity due to compliance mandates, while fitness enthusiasts exhibit highest elasticity.
Supply Chain Analysis
Regional distribution centers in Jakarta and Surabaya anchor hub-and-spoke patterns for Indonesia's pharmacy channel formalization. Manufacturing concentrates in Japan, India, and China, with raw material sourcing drawing from Peruvian anchovy fisheries, Antarctic krill zones, and domestic algal cultivation ponds. Single-source vulnerability in omega-3 marine lipids exposes formulation costs to quota restrictions. Distribution runs through clinician-directed retail in urban China, cold-chain pharmacy networks in Southeast Asia, and subscription direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on microencapsulation process maturation collapsing thermolabile bioactive preservation costs, enabling premium ambient-stable claims without cold-chain infrastructure.
For Market Incumbents: Deepen proprietary clinical dossier development under Japan's Foods with Function Claims system to preempt regulatory escalation. Secure captive algal omega-3 cultivation to reduce Peruvian anchovy supply exposure. Anchor channel control through preventive cardiology clinic integration in India's metro corridors. For New Entrants and Emerging Players: Preventive cardiology clinics in Mumbai, Delhi, and Bangalore represent the most penetrable buyer archetype, with institutional procurement pull for prescription-aligned formulations. Target Ayurveda-botanical convergence segments under AYUSH Ministry guidelines. Deploy direct-to-consumer subscription platforms to bypass retail slotting fees. For Investors and Strategic Acquirers: Multinational nutrition conglomerates with direct-to-consumer platforms are the most active acquirer in this space, seeking microencapsulation capability and proprietary strain registrations. Long-term viability favors targets with captive research infrastructure and Japan FFC dossier libraries. Watch strain-specific probiotic claim acceptance across PMDA and TGA frameworks as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Algal Cultivation | Captive EPA/DHA supply reduces exposure to El Niño-driven anchovy quota volatility. |
| Proprietary Clinical Dossier Development | Japan's Consumer Affairs Agency mandates strain-specific substantiation for Foods with Function Claims. |
| Subscription Platform Penetration | Direct-to-consumer models build longitudinal consumer data for personalized formulation refinement. |
| Preventive Cardiology Clinic Partnership | Hospital discharge protocols in South Korea and Taiwan embed specific functional food recommendations. |
| Ayurveda-Botanical Convergence Positioning | Arjuna bark and garlic extract formulations align with India's AYUSH Ministry guidelines. |
Study Parameters
Multiple input streams — regulatory filing analysis, trade flow databases, and channel inventory audits — were reconciled against primary interviews with cardiologists, preventive cardiology clinic procurement heads, FSSAI compliance officers, and pharmacy chain category managers. Secondary validation drew from NMPA claim harmonization notices, FFC substantiation dossier disclosures, and cold-chain logistics provider capacity reports. Bottom-up volume modeling and top-down value reconciliation triangulated segment outputs.
Historical consumption patterns were cross-referenced against panel input from formulation scientists and distribution channel partners. Segmentation dimensions modeled include product chemistry, consumer physiology, ingredient provenance, and delivery format across the projection horizon. CAGRs were derived from trend extrapolation adjusted for regulatory pathway timing and channel penetration curves. Industry-specific inputs incorporated microencapsulation technology adoption rates and clinician-directed retail expansion trajectories.
Underlying measurement precision varies by segment; omega-3 and fiber-enriched categories carry tighter precision than strain-specific probiotics given substantiation gaps. Forecasts reflect documented assumptions around regulatory acceptance timelines and supply security. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
Banana Leaf Extract Market
Functional Food & Ingredients
Japan Soy Protein Market
Functional Food & Ingredients
Europe Prebiotic Ingredient Market
Functional Food & Ingredients
Africa Omega-3 PUFA Market
Functional Food & Ingredients
Africa Algae Omega-3 Ingredients Market
Functional Food & Ingredients
Omega 3 PUFA Market
Functional Food & Ingredients
Sacha Inchi Protein Market
Functional Food & Ingredients
North America Omega-3 PUFA Market
Functional Food & Ingredients
Brazil Flavored and Functional Water Market
Functional Food & Ingredients
South America Omega-3 PUFA Market
Functional Food & Ingredients
Beta Glucan and Fucoidan Market
Functional Food & Ingredients
Asia-Pacific Omega3 PUFA Market
Functional Food & Ingredients
Global Probiotic Ingredients Market
Functional Food & Ingredients
Global Medical Foods Market
Functional Food & Ingredients
Italy Protein Market
Functional Food & Ingredients
Poultry Probiotic Ingredients Market