
 Brazil Flavored and Functional Water Market | 2026-2036
Brazil Flavored and Functional Water Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Flavored and Functional Water Market Outlook
ANVISA's evolving fortification standards is rebalancing formulation priorities across the industry. Coca-Cola Brasil leverages its extensive bottling infrastructure to sustain national distribution density. Ambev S.A. anchors its portfolio through deep channel penetration in the Southeast, while Danone differentiates via specialized nutrient-delivery platforms targeting health-conscious consumers.
Flavored and functional water comprises non-alcoholic beverages enhanced with vitamins, minerals, electrolytes, or botanical extracts, typically maintaining sub-20 calorie profiles per serving through controlled sweetener regimes; these products serve hydration needs while delivering targeted physiological benefits such as electrolyte replenishment or antioxidant support. Vitamin-infused water occupies the dominant volume position as consumers prioritize immune-support positioning, while electrolyte water captures accelerating interest from athletic and post-illness recovery segments where mineral replenishment drives repeat purchase behavior. Tetra packs remain peripheral but gain traction in institutional channels seeking reduced plastic dependency.
ANVISA governs product registration, additive thresholds, and health claim substantiation for all fortified beverages commercialized domestically, while the Ministry of Agriculture (MAPA) oversees mineral water sourcing standards that constrain supply geography for certain functional variants. The PLI scheme's beverage-sector incentives indirectly shape capital allocation toward domestic production capacity. Stakeholders must monitor ANVISA's pending guidelines on probiotic and adaptogenic ingredient classifications, as these rulings will determine which formulation platforms retain market access.
Market Dynamics
ANVISA's tightening fortification guidelines are compressing formulation timelines and forcing manufacturers to rebuild clinical substantiation pipelines before relabeling can proceed. This regulatory pressure is reshaping capital allocation toward in-house R&D capabilities and third-party validation partnerships.
Growth Catalysts
- Post-workout hydration routines:Fitness enthusiasts in São Paulo and Rio de Janeiro are replacing traditional sports drinks with electrolyte-fortified waters, creating repeat purchase velocity in urban gyms and boutique fitness studios.
- ANVISA's beverage-sector clarity:Updated additive thresholds and health claim frameworks, despite their stringency, are reducing regulatory uncertainty for compliant manufacturers and enabling faster product registration cycles.
- Modern retail channel expansion:Premium shelf space concentration in São Paulo state's supermarket chains and convenience networks is accelerating product visibility among health-conscious urban consumers.
Market Restraints
- Sweetener input volatility:Stevia and monk fruit extract prices fluctuate with Brazilian real exchange rates and agricultural harvest cycles, squeezing margin stability for sub-20 calorie formulations.
- Mineral water sourcing constraints:MAPA's geographic restrictions on natural mineral water extraction limit supply base diversification, concentrating production vulnerability in specific aquifer-dependent regions.
- Plastic packaging substitution pressure:Rising consumer and retailer resistance to single-use PET bottles threatens volume growth unless alternative formats achieve cost parity.
Strategic Opportunities
- Northeast Brazil penetration:Recife and Salvador metropolitan areas show underdeveloped functional water penetration relative to Southeast consumption intensity, offering first-mover positioning for fortified hydration brands.
- Institutional channel pivot:Corporate wellness programs and hospital recovery nutrition protocols are creating bulk procurement demand for vitamin-infused water in B2B configurations.
- PLI scheme leverage:Domestic production capacity incentives under Brazil's industrial policy are reducing capital expenditure recovery periods for greenfield bottling investments in underrepresented states.
Industry Challenges
- Clinical substantiation expertise scarcity:ANVISA's demand for peer-reviewed health claim evidence exceeds current local regulatory affairs talent pools, extending product launch timelines.
- Legacy ERP integration friction:Mid-tier manufacturers face complexity connecting new formulation tracking systems to existing production scheduling platforms, delaying compliance readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Flavored and Functional Water Market |
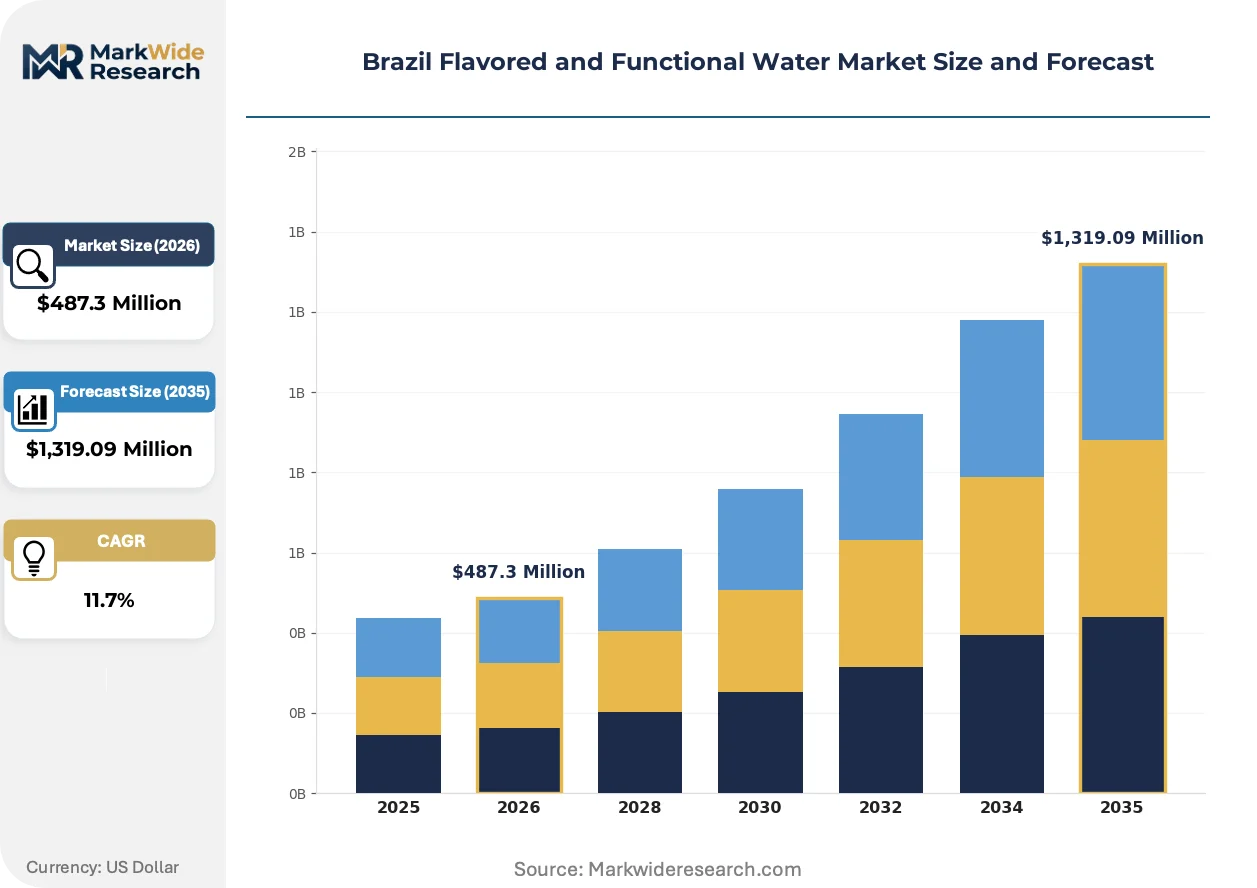
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavored Water, Vitamin-Infused Water, Electrolyte Water, Herbal Water Packaging Type: Bottles, Pouches, Cans, Tetra Packs Distribution Channel: Supermarkets, Health Stores, E-Commerce, Convenience Stores End User: Fitness Enthusiasts, Health Conscious Consumers, Children, Athletes |
| Companies Covered | Nestle, Grupo Petropolis, Coca-Cola Brasil, Monster Beverage Corporation, Red Bull GmbH, Ambev S.A., Danone, Slok, PepsiCo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Flavored and Functional Water Market Strategic Shifts
Reformulation priorities are shifting from simple vitamin fortification toward clinically validated functional ingredients, while packaging formats and channel strategies undergo parallel transformation to match evolving consumption contexts.
Botanical extract infusion technology is rewriting competitive positioning in the premium segment. Electrolyte waters incorporating adaptogenic compounds from Brazilian native plants are gaining traction among marathon runners and CrossFit practitioners in São Paulo's zona sul. This ingredient platform is compressing the differentiation window for basic vitamin-only formulations.
ANVISA's pending probiotic classification guidelines are forcing preemptive formulation adjustments. Manufacturers are conducting stability trials on spore-forming bacterial strains ahead of formal rulings to secure early-mover registration advantages. The functional water segment faces the highest compliance burden, as liquid matrices present unique viability challenges for live culture claims.
Direct-to-gym distribution models are displacing traditional wholesale routes in metropolitan fitness ecosystems. Boutique studio chains in Rio de Janeiro and Brasília are negotiating exclusive refrigerator placements and subscription replenishment programs. This channel fragmentation is most pronounced in high-income urban corridors where consumer loyalty attaches to convenience rather than retail brand recognition.
Brazil Flavored and Functional Water Market Segmentation
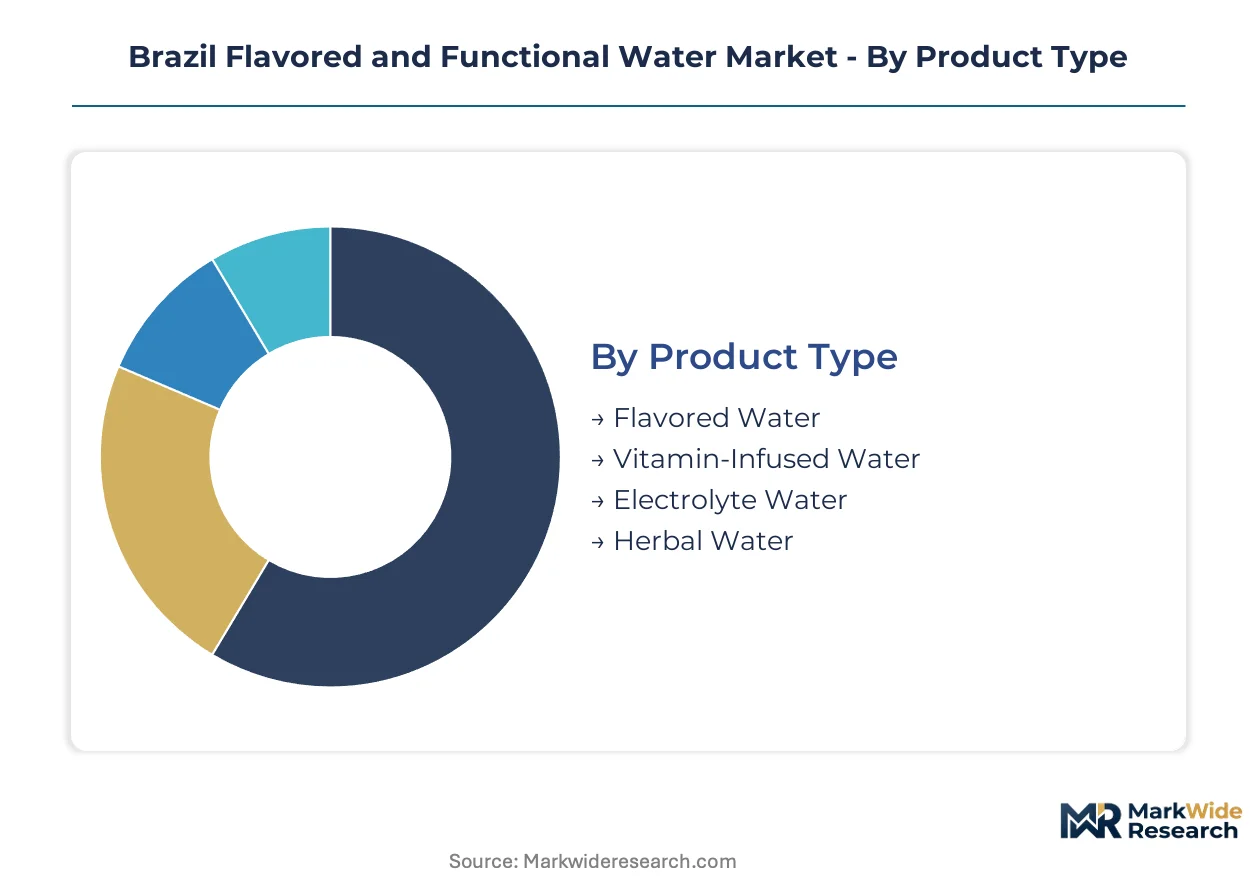
Segmentation in Brazil's functional water market exposes divergent margin profiles across formulation platforms and channel strategies. Manufacturers optimize portfolios by matching fortification intensity to end-use recovery needs while navigating ANVISA's additive thresholds.
Product Type:
Volume concentrates in mainstream hydration, while premium tiers command formulation complexity and clinical substantiation investments.
- Vitamin-Infused Water:Formulations typically deliver vitamins C, B-complex, and zinc through stabilized aqueous suspensions with controlled pH buffering. São Paulo's health-conscious urban consumers drive repeat purchase velocity through supermarket premium shelf placements, prioritizing immune-support positioning. Mature deployment sits with Vitamin-Infused Water. Newer deployment is concentrated in Electrolyte Water.
- Electrolyte Water:Mineral replenishment platforms incorporate sodium, potassium, and magnesium salts at isotonic concentrations optimized for post-exertion absorption. Rio de Janeiro and Brasília fitness ecosystems generate accelerating demand from boutique studio chains and marathon training communities seeking alternatives to traditional sports drinks. This segment gains share fastest among athletic and post-illness recovery cohorts.
- Flavored Water:Sub-20 calorie profiles rely on stevia and monk fruit extract sweetening regimes with natural flavor emulsions.
- Herbal Water:Botanical infusions incorporating Brazilian native plant extracts target adaptogenic benefit claims pending ANVISA classification rulings.
Reformulation pipelines prioritize electrolyte platforms as fitness penetration deepens in Southeast metropolitan corridors.
Packaging Type:
Cost structures diverge sharply between commodity PET and emerging sustainable formats seeking retail acceptance.
- Bottles:PET and rPET configurations dominate production economics through existing Coca-Cola Brasil and Ambev bottling infrastructure. São Paulo state's modern retail channels sustain national distribution density despite rising plastic resistance from institutional procurement policies. Mature deployment sits with Bottles. Newer deployment is concentrated in Tetra Packs.
- Tetra Packs:Aseptic carton technology reduces plastic dependency for corporate wellness and hospital recovery nutrition programs. MAPA's mineral water sourcing constraints limit geographic production flexibility for this format, concentrating supply in specific aquifer-dependent regions.
- Pouches:Flexible film configurations target on-the-go consumption in convenience store channels.
- Cans:Aluminum formats gain traction in gym-exclusive distribution models requiring refrigeration durability.
Sustainability-driven channel shifts are accelerating format diversification despite cost premiums.
Distribution Channel:
Channel selection determines margin capture and consumer loyalty attachment mechanisms.
- Supermarkets:Premium shelf space concentration in São Paulo state chains enables brand visibility among mass-market health seekers. ANVISA's streamlined registration cycles for compliant manufacturers accelerate product listing velocity in this channel.
- Health Stores:Specialized retailers curate clinically substantiated formulations targeting nutrient-delivery sophistication. Urban health-conscious consumers in Southeast Brazil command highest basket values here.
- E-Commerce:Direct-to-consumer platforms enable subscription replenishment programs for fitness enthusiasts.
- Convenience Stores:Impulse-driven purchase occasions favor single-serve formats with immediate consumption positioning.
Channel fragmentation intensifies as direct-to-gym models displace traditional wholesale routes.
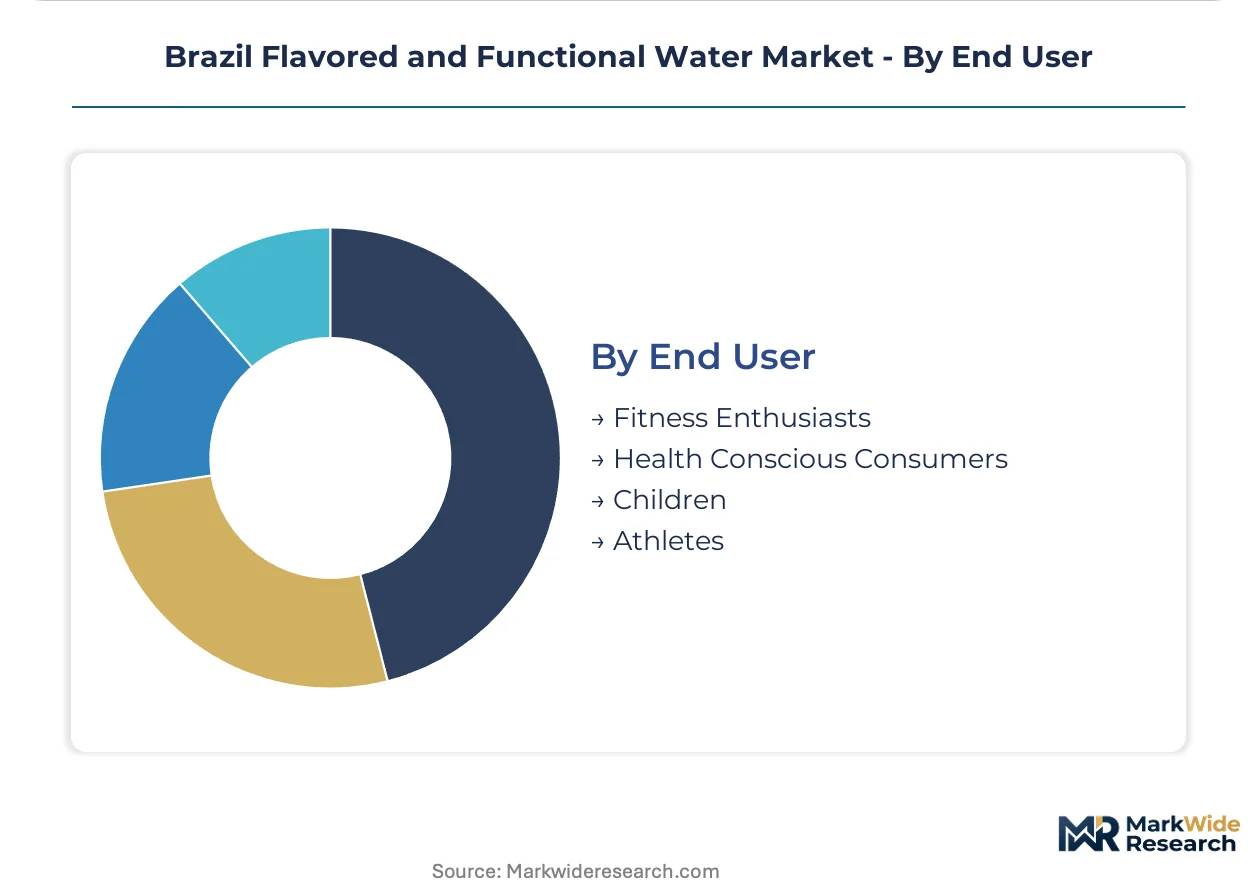
End User:
Recovery context and consumption occasion define formulation specifications and pricing tolerance.
- Fitness Enthusiasts:Post-workout hydration routines in São Paulo and Rio de Janeiro boutique studios drive electrolyte water adoption. CrossFit practitioners and marathon runners exhibit strongest repeat purchase behavior and subscription program enrollment.
- Health Conscious Consumers:Immune-support positioning and clean-label preferences shape vitamin-infused water selection in modern retail environments.
- Athletes:Competitive and endurance training contexts demand precise mineral replenishment protocols with clinical validation.
- Children:Pediatric-appropriate formulations face stricter ANVISA additive thresholds and sugar-content restrictions.
End-use specialization is compressing differentiation windows for undifferentiated mass-market positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Southeast Brazil's mineral-rich aquifer zones, while consumption intensity clusters in São Paulo state's urban corridors. This geographic split shapes logistics networks and channel strategies across the functional water value chain.
São Paulo
São Paulo state commands the dominant share of national functional water consumption through its dense network of boutique fitness studios and premium supermarket chains. ANVISA's streamlined registration protocols accelerate product velocity through modern retail channels headquartered here. The metropolitan region anchors Brazil's highest per-capita spending on electrolyte-fortified hydration products.
Rio de Janeiro
Rio de Janeiro's coastal fitness ecosystems generate concentrated demand for post-workout mineral replenishment formats. MAPA's mineral water extraction standards constrain local sourcing options, forcing manufacturers to transport bulk concentrate from approved aquifer zones. The zona sul district hosts the country's most developed direct-to-gym distribution infrastructure.
Minas Gerais
Minas Gerais holds strategic importance for natural mineral water sourcing under MAPA's geographic certification regime. The state's crystalline aquifers supply raw material for multiple functional water production facilities. Belo Horizonte's emerging health-conscious consumer base is narrowing the consumption gap with Southeast coastal metros.
Bahia
Bahia represents the most significant underpenetrated market for functional water expansion in Northeast Brazil. Salvador's metropolitan consumer base shows rising health awareness without matching product availability in modern retail channels. PLI scheme incentives for domestic production capacity are attracting bottling investment to reduce logistics costs from Southeast supply bases.
Rio Grande do Sul
Rio Grande do Sul maintains distinct consumption patterns favoring herbal and botanical infusion formats. The state's Germanic heritage influences preference for clean-label, minimally processed beverage alternatives. Porto Alegre's retail channels sustain niche demand for adaptogenic plant extracts pending ANVISA classification rulings.
Brazil Flavored and Functional Water Market Competitive Environment
The competitive structure tilts toward multinational beverage conglomerates with established bottling infrastructure and deep modern trade relationships. Three archetypes dominate: global hydration specialists leveraging R&D scale, domestic beverage giants optimizing channel density, and emerging wellness-focused brands pursuing premium positioning through clinical substantiation. Capacity expansion and direct-to-gym channel partnerships constitute the primary competitive vectors reshaping market access.
Among multinational hydration specialists, Nestle and Danone occupy positions exemplifying nutrient-delivery platform sophistication. Coca-Cola Brasil and Ambev S.A. anchor the domestic infrastructure tier, representing archetypes of national distribution density and bottling network leverage. PepsiCo sits within the portfolio diversification tier, illustrating how broader beverage holdings create cross-category replenishment opportunities.
| Leading Market Players |
|---|
| Nestle |
| Grupo Petropolis |
| Coca-Cola Brasil |
| Monster Beverage Corporation |
| Red Bull GmbH |
| Ambev S.A. |
| Danone |
| Slok |
| PepsiCo |
| Others |
Value Chain & Pricing Dynamics
Stevia and monk fruit extract price indices cascade through Brazilian functional water supply chains into three distinct pricing tiers, with exchange rate volatility compressing margins for sub-20 calorie formulations while mineral water sourcing constraints under MAPA certification create geographic cost premiums.
Pricing Analysis
Value-based pricing anchors premium electrolyte waters to post-workout recovery outcomes, while vitamin-infused variants stratify across immune-support efficacy claims. Price differentiation separates clinically substantiated formulations with ANVISA-approved health claims from basic fortification tiers. Pricing pressure stems from sweetener input volatility as Brazilian real fluctuations squeeze mid-tier producers. Health-conscious urban consumers in São Paulo exhibit lowest price sensitivity, while mass-market supermarket buyers drive volume through promotional elasticity.
Supply Chain Analysis
Dual-sourcing requirements for mineral water concentrates mandate MAPA-certified aquifer qualification across multiple Brazilian states, with manufacturers qualifying backup extraction sites to mitigate single-source vulnerability. Raw material dependencies center on stevia extracts from Paraguay and China, electrolyte salts from domestic chemical processors, and aseptic carton packaging from European suppliers. Supply chain risk concentrates in MAPA's geographic restrictions on natural mineral water extraction, which limits production flexibility. Distribution runs through Coca-Cola Brasil and Ambev's bottling infrastructure for national density, with direct-to-gym models fragmenting last-mile logistics in metropolitan fitness corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's functional water sector sits in a formulation technology transition, with botanical extract infusion platforms displacing legacy vitamin-only fortification as ANVISA's pending adaptogenic classification rulings reshape competitive access.
For Market Incumbents: Anchor defensive positioning through preemptive stability trials on spore-forming probiotic strains ahead of ANVISA's formal guidelines, securing registration advantages before compliance windows narrow. Deepen backward integration into MAPA-certified mineral water extraction sites to reduce geographic concentration risk in Southeast aquifers. Channel control through exclusive gym partnerships in Rio de Janeiro's zona sul and São Paulo's boutique studio networks locks in repeat purchase velocity against emerging entrants. For New Entrants and Emerging Players: Electrolyte water with Brazilian native plant adaptogens offers a technology-first wedge into São Paulo's CrossFit and marathon training communities where clinical validation commands premium tolerance. Underpenetrated Northeast Brazil—specifically Recife and Salvador metropolitan areas—presents the most penetrable white space relative to Southeast consumption intensity. Direct-to-gym subscription replenishment programs bypass incumbent retail shelf dominance, attaching consumer loyalty through convenience rather than brand recognition. For Investors and Strategic Acquirers: The window for entry favors wellness-focused brands with proprietary botanical extraction capabilities and pending ANVISA registration dossiers. Long-term viability hinges on formulation platforms that survive regulatory tightening across the projection horizon. Acquisition targets should demonstrate clinical substantiation partnerships with Brazilian research institutions. The signal to watch is ANVISA's final probiotic classification ruling, which will determine which functional water portfolios retain market access and which face reformulation write-downs.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Substantiation Investment | ANVISA's tightened health claim guidelines reward peer-reviewed formulation evidence with faster registration cycles. |
| Direct-to-Gym Channel Expansion | Boutique fitness studio exclusivity in São Paulo and Rio de Janeiro captures subscription-driven repeat purchase velocity. |
| Botanical Extraction Capability Buildout | Adaptogenic ingredient platforms from Brazilian native plants differentiate premium positioning pending regulatory classification. |
| MAPA-Certified Aquifer Diversification | Multi-site mineral water sourcing reduces production vulnerability to geographic extraction restrictions. |
| Sustainable Packaging Transition | Tetra pack adoption for institutional channels addresses rising plastic resistance from corporate wellness procurement policies. |
Study Parameters
Independent corroboration across regulatory affairs directors at functional water manufacturers, category buyers at São Paulo supermarket chains, and procurement leads at corporate wellness programs underwrites the qualitative findings in this study. Primary fieldwork with ANVISA compliance consultants and MAPA certification specialists captured evolving additive threshold interpretations. Secondary validation drew from ANVISA registration databases, MAPA mineral water extraction permits, and modern retail channel expansion disclosures. Bottom-up volume modeling triangulated against top-down category spending estimates.
Comparable-period anchoring aligned the projection framework to historical consumption intensity patterns across Southeast Brazil's metropolitan corridors. Segmentation dimensions modeled include formulation platform, packaging format, distribution channel, and end-use recovery context. CAGRs were derived from growth driver elasticity analysis applied to base-year market sizing. Forecast inputs incorporated ANVISA regulatory timeline assumptions and PLI scheme incentive uptake trajectories for domestic production capacity.
Several conditions sit outside the modeled scope, including abrupt ANVISA probiotic classification reversals, extreme Brazilian real depreciation scenarios, and MAPA aquifer declassification events. Forecasts reflect assumptions about regulatory stability and consumer health-awareness trajectory. Deviation in ANVISA's final adaptogenic ingredient rulings would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
Superfood Powders Market
Functional Food & Ingredients
North America Pea Protein Ingredients Market
Functional Food & Ingredients
North America and Europe Medical Foods Market
Functional Food & Ingredients
Brominated Vegetable Oil Market
Functional Food & Ingredients
Vegan DHA Market
Functional Food & Ingredients
Banana Leaf Extract Market
Functional Food & Ingredients
Poultry Probiotic Ingredients Market
Functional Food & Ingredients
Mediterranean Pre-Diabetes Ingredient Concepts Market
Functional Food & Ingredients
Prickly Pear Fruit Metabolic Health Ingredients Market
Functional Food & Ingredients
Africa Algae Omega-3 Ingredients Market
Functional Food & Ingredients
Functional Food Ingredients Market
Functional Food & Ingredients
Europe Botanical Extract Market
Functional Food & Ingredients
Global Probiotic Ingredients Market
Functional Food & Ingredients
Functional Non-Meat Ingredients Market
Functional Food & Ingredients
Japan Soy Protein Market
Functional Food & Ingredients
Africa Omega-3 PUFA Market