

Mediterranean Cognitive-First Ingredient Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Mediterranean Cognitive-First Ingredient Systems Market Insights
Project finance tied to Mediterranean botanical extraction facilities is rewriting competitive entry requirements for ingredient systems suppliers. DSM-Firmenich leverages its integrated fermentation and extraction footprint across Iberia to sustain supply security for neuroprotective compounds. Indena specializes in standardized botanical derivatives for cognitive health applications, while Euromed anchors its position through captive olive and sage cultivation networks in Spain and Morocco.
Cognitive-first ingredient systems comprise bioactive compounds, standardized plant extracts, and synthetic nootropics formulated to modulate neurotransmitter activity, enhance cerebral blood flow, or protect against oxidative neural stress. These systems typically specify minimum active marker concentrations such as 20% oleuropein for olive-derived neuroprotectives or 50% bacosides for Bacopa monnieri extracts, ensuring batch-to-batch efficacy for downstream formulators. Neuroprotective compounds occupy the largest margin pool due to patent-protected extraction methodologies, while nootropic blends represent the fastest-expanding category as wellness startups seek turnkey premix solutions. Mental performance boosters remain comparatively mature, with price competition intensifying among contract manufacturers serving functional food producers.
EFSA's health claims panel, France's ANSM, and Italy's Ministry of Health enforce divergent substantiation thresholds for memory and alertness claims across Mediterranean jurisdictions. EFSA's 2013 rejection of most botanical health claims continues to constrain on-label positioning for rosemary-derived carnosic acid and sage-based formulations in EU-wide distribution. Stakeholders must monitor pending Novel Food approvals for emerging fungal nootropics and decide whether to pursue national derogation pathways or reformulate around established ingredient dossiers.
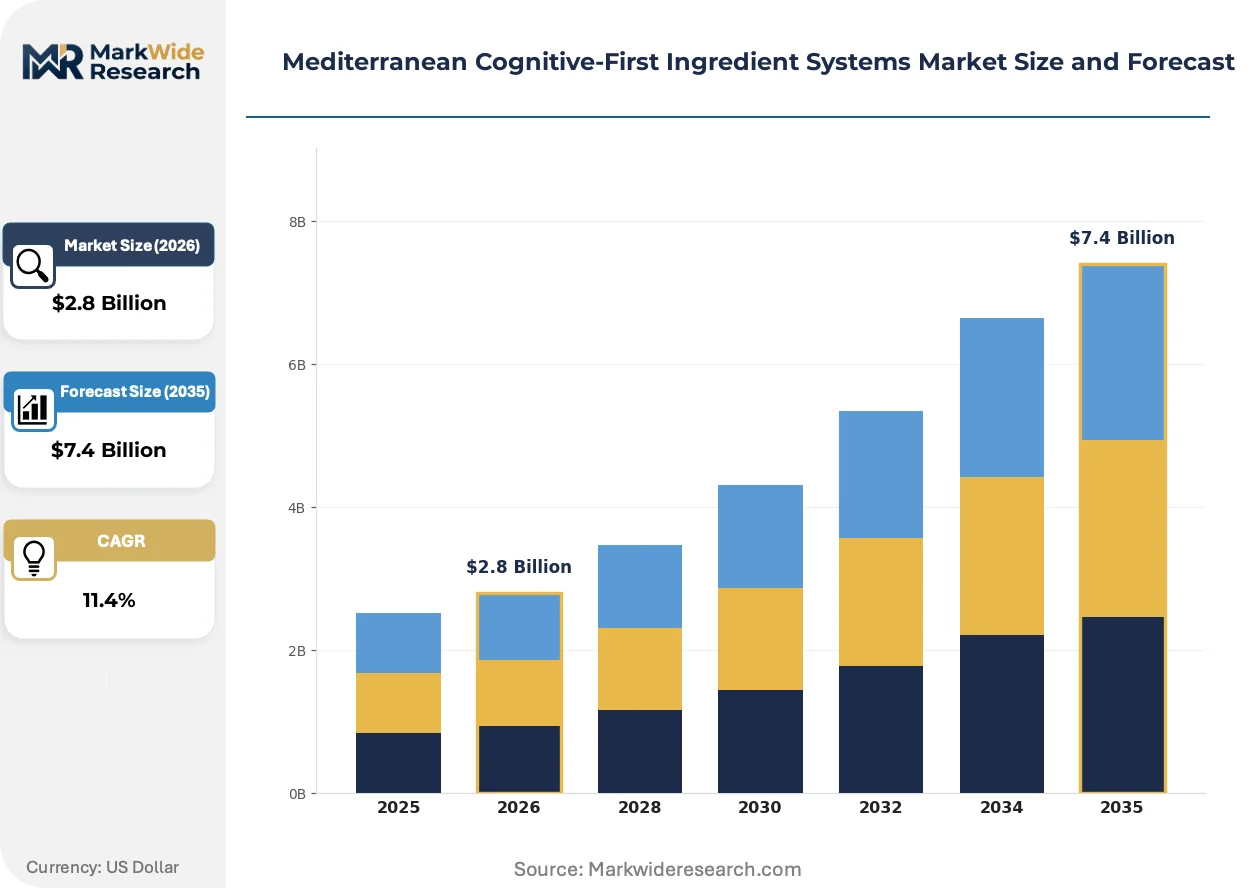
Market Dynamics
EFSA's 2013 botanical health claims rejection continues to compress on-label positioning for Mediterranean neuroactive extracts, forcing suppliers to reformulate around novel food dossiers or pursue fragmented national derogation pathways.
Growth Catalysts
- EU Novel Food Regulation:Accelerated approval timelines for fungal nootropics are opening formulation pathways previously blocked for traditional botanical suppliers.
- Pharmaceutical procurement:Spanish, Italian, and Greek drug innovators are expanding nootropic blend procurement for age-related cognitive decline therapeutics.
- Botanical extraction clustering:Southern France and northern Italy wellness startup density near extraction hubs is concentrating demand-pull for standardized neuroprotective inputs.
Market Restraints
- Oleuropein feedstock volatility:Olive-derived neuroprotective compound costs fluctuate with Iberian and Moroccan harvest yields.
- EFSA substantiation thresholds:The health claims panel's stringent evidence requirements block memory-enhancement labeling for rosemary carnosic acid and sage formulations.
- Synthetic nootropic substitution:Piracetam analogs and racetam derivatives threaten premium positioning of plant-based cognitive ingredients in price-sensitive functional food segments.
Strategic Opportunities
- Greek contract manufacturing:Underdeveloped local extraction capacity creates white space for toll-processing partnerships serving Balkan pharmaceutical formulators.
- Turnkey premix solutions:Wellness startups seek complete nootropic blend systems, shifting value capture from raw extract sales to formulation services.
- France ANSM derogation pathway:National health authority flexibility permits memory claims unavailable under EU-wide EFSA rulings, rewarding localized regulatory strategy.
Industry Challenges
- Marker compound standardization:Batch-to-batch bacoside and oleuropein consistency demands analytical chemistry capabilities scarce among mid-tier Mediterranean suppliers.
- Novel Food dossier timelines:EFSA safety assessment durations of 18-36 months strain working capital for emerging fungal nootropic developers.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mediterranean Cognitive-First Ingredient Systems Market Trends and Innovations
Formulation science and regulatory arbitrage are converging to reshape competitive positioning across Mediterranean cognitive ingredient supply, with digitization of quality systems and procurement models compressing traditional supplier advantages.
Near-infrared spectroscopy coupled with blockchain traceability is digitizing batch certification workflows for olive and sage-derived neuroprotectives. Spanish extraction facilities are adopting these systems fastest, driven by pharmaceutical customer audit requirements. The technology is digitizing documentation burdens that previously favored large integrated suppliers over specialized botanical houses.
France's ANSM maintains divergent substantiation thresholds from EFSA for memory and alertness claims, creating regulatory fragmentation across Mediterranean distribution. This policy divergence forces suppliers to maintain parallel dossier strategies or abandon EU-wide labeling. Rosemary carnosic acid and sage-based formulators are most affected, with many pursuing French national approvals while reformulating for other Mediterranean markets.
Wellness startups in Provence and Lombardy are consolidating supplier relationships around single-source premix partnerships, displacing fragmented multi-ingredient procurement. This behavioral shift concentrates volume with integrated fermentation-extraction houses capable of turnkey neuroactive delivery. The pattern is most visible among venture-backed direct-to-consumer brands targeting cognitive performance positioning.
Mediterranean Cognitive-First Ingredient Systems Market Segmentation
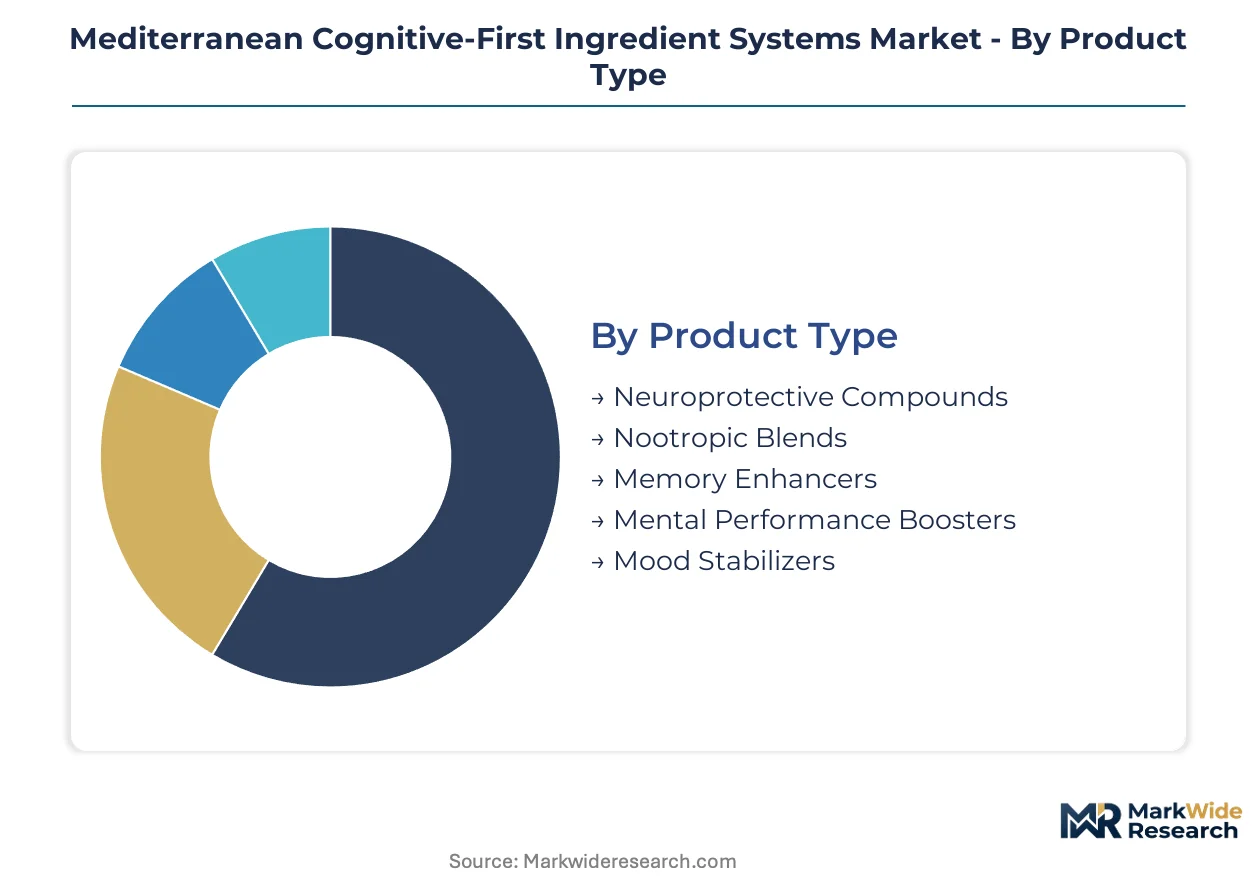
Ingredient system suppliers must align R&D and regulatory dossiers against distinct performance specifications and end-use validation requirements. Segmentation reveals where margin pools concentrate and which customer types drive specification complexity.
Product Type:
Use-case spectrum spans patented extraction methodologies through commodity premix formulations, with neuroprotective applications commanding specification premiums over functional food inputs.
- Neuroprotective Compounds:Standardized oleuropein, carnosic acid, and bacoside extracts with defined active marker thresholds protect neural tissue against oxidative stress. Spanish pharmaceutical innovators in Barcelona and Madrid drive procurement for age-related therapeutic applications, constrained by EFSA substantiation requirements for on-label positioning.
- Nootropic Blends:Turnkey premix systems combine synthetic racetams, fungal-derived compounds, and botanical actives for neurotransmitter modulation. Wellness startups in Provence and Lombardy consolidate supplier relationships around single-source partnerships, shifting value capture from raw extract sales to formulation services.
- Memory Enhancers:Bacopa monnieri and Ginkgo biloba derivatives targeting synaptic plasticity.
- Mental Performance Boosters:Caffeine-theanine combinations and adaptogenic stacks for acute cognitive demands.
- Mood Stabilizers:Saffron crocin extracts and lavender essential oil fractions for anxiolytic applications.
The dominant share belongs to Neuroprotective Compounds, while Nootropic Blends is closing the gap fastest.
Application Area:
Cost tier stratification separates pharmaceutical-grade validation requirements from wellness positioning flexibility, with clinical substantiation costs filtering supplier participation.
- Cognitive Health Supplements:Capsule and tablet formulations for daily neuroprotection regimens.
- Brain Fitness Products:Functional beverages and gummies targeting student and professional demographics.
- Age-Related Cognitive Decline Support:Prescription-adjacent formulations for mild cognitive impairment management. Greek and Italian drug developers in Thessaloniki and Milan expand procurement of standardized nootropic blends, navigating divergent national derogation pathways for memory claims.
- Stress Resilience Formulations:Adaptogenic combinations for cortisol modulation and HPA axis support.
- Mental Alertness Enhancers:Acute-dose products for shift workers and high-performance professionals.
Age-Related Cognitive Decline Support captures the premium pricing tier, whereas Brain Fitness Products are expanding most quickly through direct-to-consumer channels.
End User:
Customer type determines specification stringency, with pharmaceutical audit requirements favoring integrated suppliers over specialized botanical houses.
- Dietary Supplement Manufacturers:Mid-scale formulators sourcing standardized extracts for private-label production.
- Functional Food Producers:Beverage and snack developers integrating nootropic actives at sub-perceptible taste thresholds.
- Pharmaceutical Innovators:Drug developers pursuing novel therapeutic indications for neurodegenerative conditions. Spanish, Italian, and Greek innovators accelerate procurement of nootropic blends, with near-infrared spectroscopy and blockchain traceability digitizing batch certification workflows.
- Wellness Startups:Venture-backed brands in southern France and northern Italy clustering near botanical extraction hubs concentrate demand-pull for turnkey neuroactive delivery systems.
- Nutraceutical Retailers:Pharmacy chains and health food stores curating premium supplement assortments.
Pharmaceutical Innovators command the deepest supplier relationships, while Wellness Startups are gaining share fastest through premix consolidation.
Distribution Channel:
Supply concentration near extraction hubs in Iberia and Morocco shapes channel economics, with proximity advantages compressing logistics costs for temperature-sensitive botanical derivatives.
- Health Food Stores:Independent retailers and regional chains serving aging demographic bases in Provence and Tuscany.
- Online Specialty Retailers:Subscription platforms and marketplace sellers targeting cognitive performance positioning.
- Pharmacies:Licensed dispensaries in France, Italy, and Spain leveraging ANSM and Ministry of Health flexibility for memory claims unavailable under EU-wide EFSA rulings.
- Direct-to-Consumer Platforms:Brand-owned e-commerce and influencer-mediated sales for venture-backed wellness startups.
- Fitness Centers:Gyms and wellness studios distributing acute performance products to member bases.
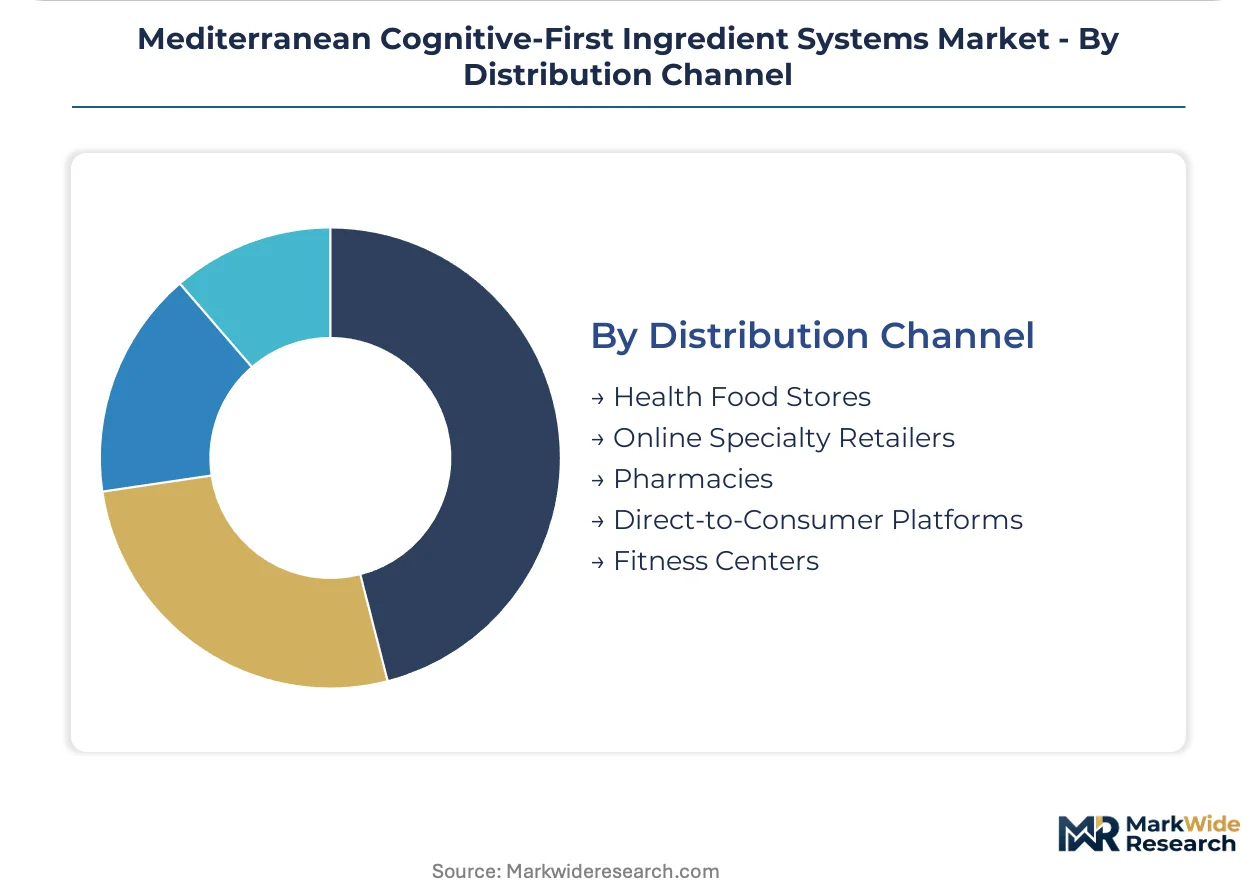
Pharmacies retain the highest trust premium for age-related applications, though Direct-to-Consumer Platforms are climbing the fastest among younger demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian pharmaceutical innovators capture premium pricing for age-related cognitive formulations, while Spanish extraction facilities compete on oleuropein feedstock scale. This asymmetry concentrates margin capture in Milan and Barcelona corridors while compressing returns for Moroccan and Greek suppliers.
Spain
Barcelona and Madrid pharmaceutical clusters drive procurement of standardized nootropic blends for neurodegenerative therapeutics. EFSA's stringent botanical health claims framework constrains on-label positioning for rosemary-derived carnosic acid formulations. Near-infrared spectroscopy adoption accelerates across Andalusian extraction facilities as pharmaceutical audit requirements digitize batch certification workflows.
Italy
Lombardy wellness startups in Milan consolidate supplier relationships around single-source premix partnerships for cognitive performance positioning. Italy's Ministry of Health maintains divergent substantiation thresholds from EFSA, permitting memory claims unavailable under EU-wide rulings. Northern Italian botanical extraction hubs near Provence concentrate demand-pull for turnkey neuroactive delivery systems.
France
Provence-based venture-backed brands target cognitive performance positioning through direct-to-consumer channels. ANSM's regulatory flexibility creates a national derogation pathway for memory and alertness claims blocked by EFSA's 2013 botanical rejections. Southern France wellness startup density clusters near botanical extraction facilities, concentrating specification demand for standardized neuroprotective inputs.
Greece
Thessaloniki drug developers expand procurement of nootropic blends for mild cognitive impairment management. Underdeveloped local extraction capacity creates white space for toll-processing partnerships serving Balkan pharmaceutical formulators. Greek innovators navigate fragmented national derogation pathways while EFSA Novel Food dossiers strain working capital for emerging fungal nootropic developers.
Morocco
Euromed anchors captive olive cultivation networks supplying oleuropein feedstock for neuroprotective compound production. Harvest yield volatility across Iberian and Moroccan growing regions generates oleuropein cost fluctuations that compress margin predictability for downstream formulators. Moroccan extraction infrastructure remains concentrated around established botanical houses with limited mid-tier supplier analytical chemistry capabilities.
Mediterranean Cognitive-First Ingredient Systems Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the margin architecture. The supplier base stratifies between integrated fermentation-extraction houses and specialized botanical derivative houses. Three archetypes dominate: integrated nutrition platforms with captive cultivation networks, contract extraction specialists with standardized marker compound capabilities, and turnkey formulation houses serving wellness startup demand. Competitive moves concentrate on M&A for extraction capacity control and strategic partnerships for Novel Food dossier co-development.
Within the integrated platform tier, DSM-Firmenich and ADM exemplify archetypes combining fermentation scale with botanical extraction footprint. Indena occupies a position representing specialized botanical derivative houses with standardized neuroactive compound focus. These three anchors illustrate how supplier structure maps to customer specification stringency, with pharmaceutical innovators favoring integrated audit-ready platforms while wellness startups consolidate around single-source premix partnerships.
| Leading Market Players |
|---|
| DSM-Firmenich |
| Indena |
| ADM |
| IFF |
| Glanbia Nutritionals |
| Euromed |
| Pharmactive Biotech Products |
| Kerry Group |
| Lonza Group |
| Others |
Pricing and Supply Chain Analysis
Algeciras-Tangier Med freight corridors absorb temperature-controlled logistics premiums that compound with Iberian oleuropein harvest volatility, concentrating pricing power among Spanish extraction houses with captive Moroccan cultivation networks while forcing Greek and Italian buyers into cost-plus contracting.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across pharmaceutical-grade certification, volume scale, and EFSA dossier completeness. Price differentiation hinges on EU Novel Food approval status and batch-to-batch marker compound consistency certified through near-infrared spectroscopy. Cost compression in functional food segments intensifies as synthetic racetam substitutes erode plant-based premium positioning. Wellness startups exhibit highest price sensitivity due to venture capital burn constraints, while pharmaceutical innovators prioritize audit-ready supply security over unit economics.
Supply Chain Analysis
EU dual-use export controls on advanced fermentation bioreactors limit technology transfer to Moroccan and Greek processing facilities, constraining capacity expansion outside Iberian integrated platforms. Feedstock concentration centers on Spain, Morocco, and Italy for olive-derived oleuropein and sage-based carnosic acid, with Bacopa monnieri sourcing tethered to Indian cultivation networks. Single-source vulnerability pervades standardized bacoside supply where analytical chemistry capabilities remain scarce among mid-tier Mediterranean suppliers. Distribution runs through pharmaceutical procurement channels in Barcelona and Milan, wellness startup direct sourcing in Provence, and toll-processing partnerships serving Balkan formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
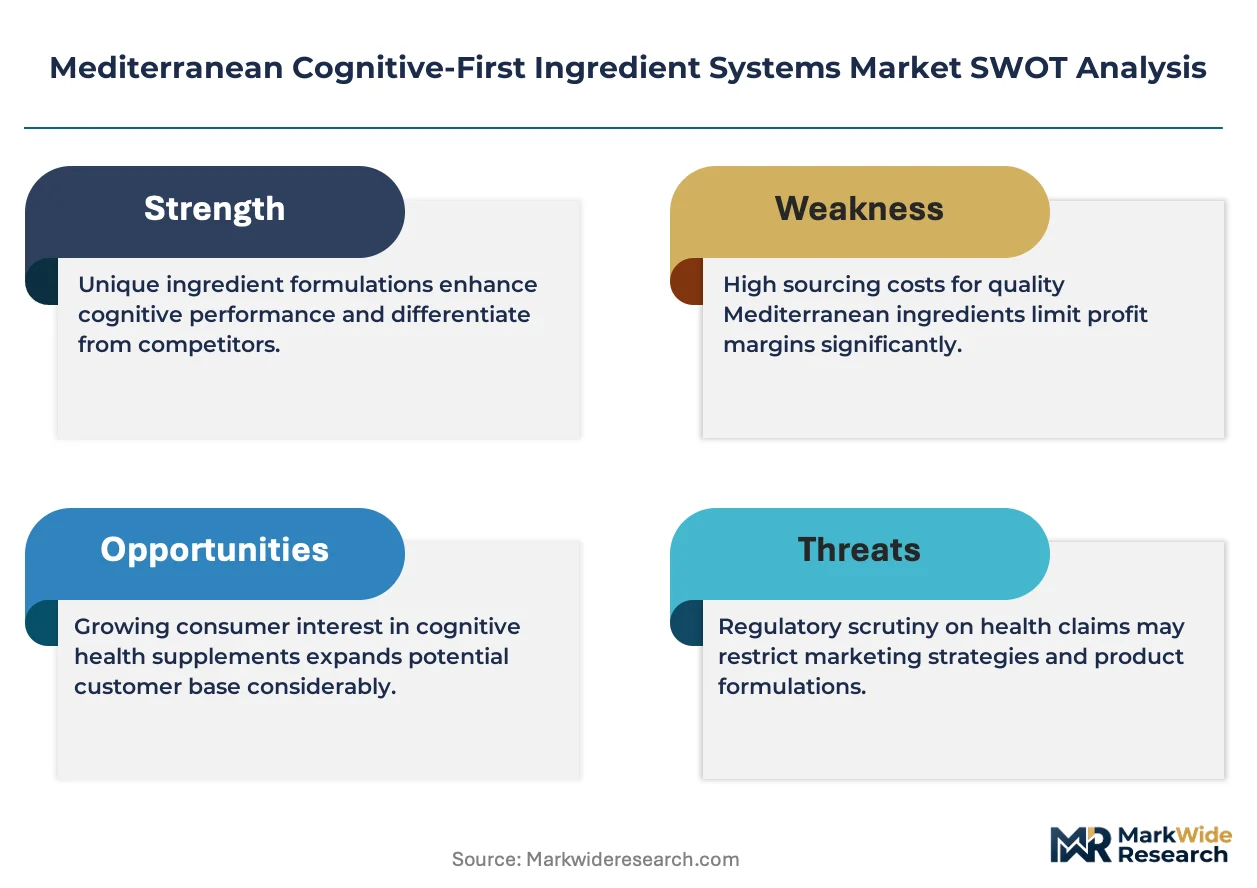
Procurement consolidation among venture-backed wellness startups is shifting buyer power toward single-source premix partnerships, fragmenting multi-ingredient supplier relationships and compressing margins for non-integrated botanical houses.
For Market Incumbents: Build regulatory dossier moats around EU Novel Food approvals for fungal nootropics before accelerated timelines close. Pursue backward integration into captive Moroccan olive cultivation to neutralize oleuropein feedstock volatility threatening margin predictability. Defend against synthetic racetam substitution in functional food tiers through pharmaceutical-grade certification investments that block mid-tier competitors from audit-ready supply relationships. For New Entrants and Emerging Players: Build out toll-processing capacity in Greece where underdeveloped local extraction infrastructure creates white space for Balkan pharmaceutical formulators seeking regional supply security. Target French ANSM derogation pathways for memory claims unavailable under EFSA rulings, exploiting regulatory fragmentation that rewards localized dossier strategies. Pursue turnkey premix partnerships with Provence and Lombardy wellness startups displacing fragmented procurement with single-source neuroactive delivery systems. For Investors and Strategic Acquirers: Specialized botanical derivative houses with standardized neuroactive compound capabilities and pending Novel Food dossiers present asymmetric upside if EFSA timelines compress. Long-term viability hinges on regulatory arbitrage sustainability across Mediterranean jurisdictions and digitization of batch certification workflows. Monitor EFSA health claims panel rulings on emerging fungal nootropics as inflection indicators for category expansion or contraction.| Strategic Initiative | Industry Significance |
|---|---|
| Novel Food Dossier Co-Development | Accelerated EFSA approval timelines for fungal nootropics open formulation pathways previously blocked for traditional botanical suppliers. |
| Captive Cultivation Network Expansion | Moroccan olive and sage cultivation control insulates against Iberian harvest yield volatility compressing oleuropein cost predictability. |
| Turnkey Premix Partnership Consolidation | Single-source relationships with Provence and Lombardy wellness startups shift value capture from raw extract sales to formulation services. |
| Near-Infrared Spectroscopy Adoption | Blockchain-coupled batch certification digitizes documentation burdens that previously favored large integrated suppliers over specialized houses. |
| National Derogation Pathway Pursuit | France ANSM flexibility permits memory claims blocked by EFSA botanical rejections, rewarding localized regulatory strategy investment. |
Research Methodology
Initial hypotheses were tested against primary input from pharmaceutical procurement directors, botanical extraction facility operators, regulatory affairs consultants specializing in EFSA Novel Food submissions, and wellness startup supply chain leads, then refined through secondary validation against EFSA health claims register entries, EU Novel Food approval databases, Mediterranean customs trade flows for oleuropein and bacoside derivatives, and SEC filings of publicly traded nutrition platforms. Bottom-up volume estimates from extraction capacity utilization rates were triangulated against top-down pharmaceutical procurement spend analysis.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by neuroprotective compounds, nootropic blends, and mental performance boosters; application area stratification across age-related cognitive decline support and brain fitness products; and end-user differentiation between pharmaceutical innovators and wellness startups. CAGRs were derived from weighted capacity expansion pipelines, regulatory approval probability assessments, and procurement intention surveys conducted with Milan and Barcelona drug developers. Industry-specific inputs included EFSA dossier timeline distributions and ANSM derogation approval rates.
Practitioners should monitor EFSA Novel Food assessment duration shifts and ANSM regulatory posture changes for early signals of competitive access expansion or constraint. Forecasts reflect assumptions regarding continued botanical health claims rejection consistency and fungal nootropic safety assessment trajectories. Material shifts in EU regulatory harmonization efforts or breakthrough synthetic nootropic efficacy demonstrations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.