
 Functional Non-Meat Ingredients Market | 2026-2036
Functional Non-Meat Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Non-Meat Ingredients Market Analysis
Plant-based meat alternatives is rebalancing demand toward texturizers and binders across European and North American food manufacturers. Kerry Group PLC leverages its hydrocolloid expertise to anchor supply relationships with clean-label processors. Cargill competes through its soy and pea protein verticals, while Ingredion specializes in starch-based texturizers for alternative protein formats.
Functional non-meat ingredients comprise specialized additives—starches, hydrocolloids, proteins, and flavor systems—that replicate or enhance the sensory and structural properties of meat in plant-based and processed foods, typically formulated at concentrations between 0.5% and 5% by weight to achieve target texture, moisture retention, and mouthfeel. Powdered formats dominate current manufacturing throughput due to shelf stability and ease of dry blending, though liquid flavoring agents are gaining traction in high-throughput meat-alternative extrusion lines where uniform dispersion proves critical. Binders and texturizers capture the deepest margin pools as formulation complexity rises, while meat alternatives application growth outpaces legacy processed food segments.
EFSA, FDA, and EMA frameworks govern ingredient safety assessments, allergen labeling, and novel food approvals, with EFSA's 2023 updated guidance on plant protein safety evaluations tightening submission requirements for new texturizer entrants. The EU Green Deal's Farm to Fork strategy accelerates demand for sustainably sourced hydrocolloids and reduced-carbon binders, pressuring suppliers to document supply chain emissions. Stakeholders must monitor evolving novel food consultations across Brussels and Washington to anticipate approval timelines that determine first-mover positioning in emerging protein platforms.
Market Dynamics
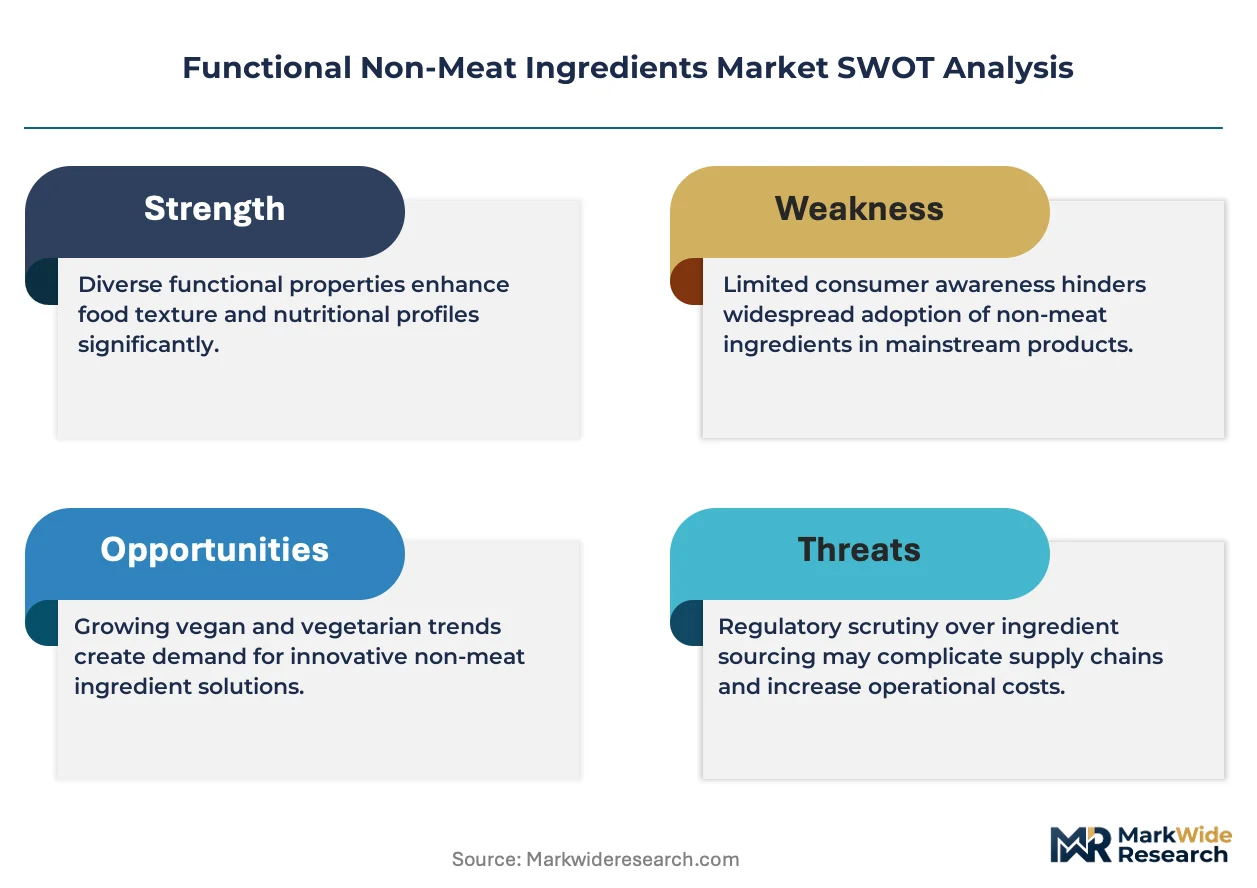
The EU Green Deal and F-Gas Regulation are compressing formulation timelines as food manufacturers scramble to document supply chain emissions for clean-label hydrocolloids and reduced-carbon binders before 2030 compliance deadlines.
Growth Catalysts
- EU Green Deal Farm to Fork strategy:Mandates for sustainably sourced hydrocolloids accelerate procurement of documented low-carbon binders from Cologne and Hamburg innovation clusters.
- Plant-based meat alternatives:Extrusion line throughput demands for uniform dispersion pull liquid flavoring agent adoption ahead of legacy powdered formats.
- Pea protein texturization:Advances in starch-hydrocolloid synergies unlock moisture retention targets that soy isolates previously failed to meet.
Market Restraints
- Pea protein input volatility:Weather-driven crop yields in Canada and France transmit price instability directly to texturizer cost structures.
- EFSA novel food submission requirements:Tightened 2023 guidance on plant protein safety evaluations extends approval timelines for new entrants by 12-18 months.
- Clean-label starch sourcing:Limited certified sustainable tapioca and potato starch supply concentrates procurement risk with Thai and Dutch processors.
Strategic Opportunities
- Fermentation-derived hydrocolloids:Precision fermentation platforms in Denmark and Netherlands bypass agricultural land constraints for binder production.
- Retail foodservice channel:Quick-service chains in Germany pilot custom texturizer blends for proprietary plant-based menu items.
- EU F-Gas Regulation phase-down:Refrigeration-dependent ingredient storage mandates accelerate demand for ambient-stable powdered formats.
Industry Challenges
- Formulation chemist scarcity:Shortage of specialists trained in protein-starch-hydrocolloid interaction modeling delays clean-label product launches.
- Extrusion equipment retrofit costs:Legacy meat processing lines require capital-intensive modifications to handle high-moisture texturizer feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Non-Meat Ingredients Market |
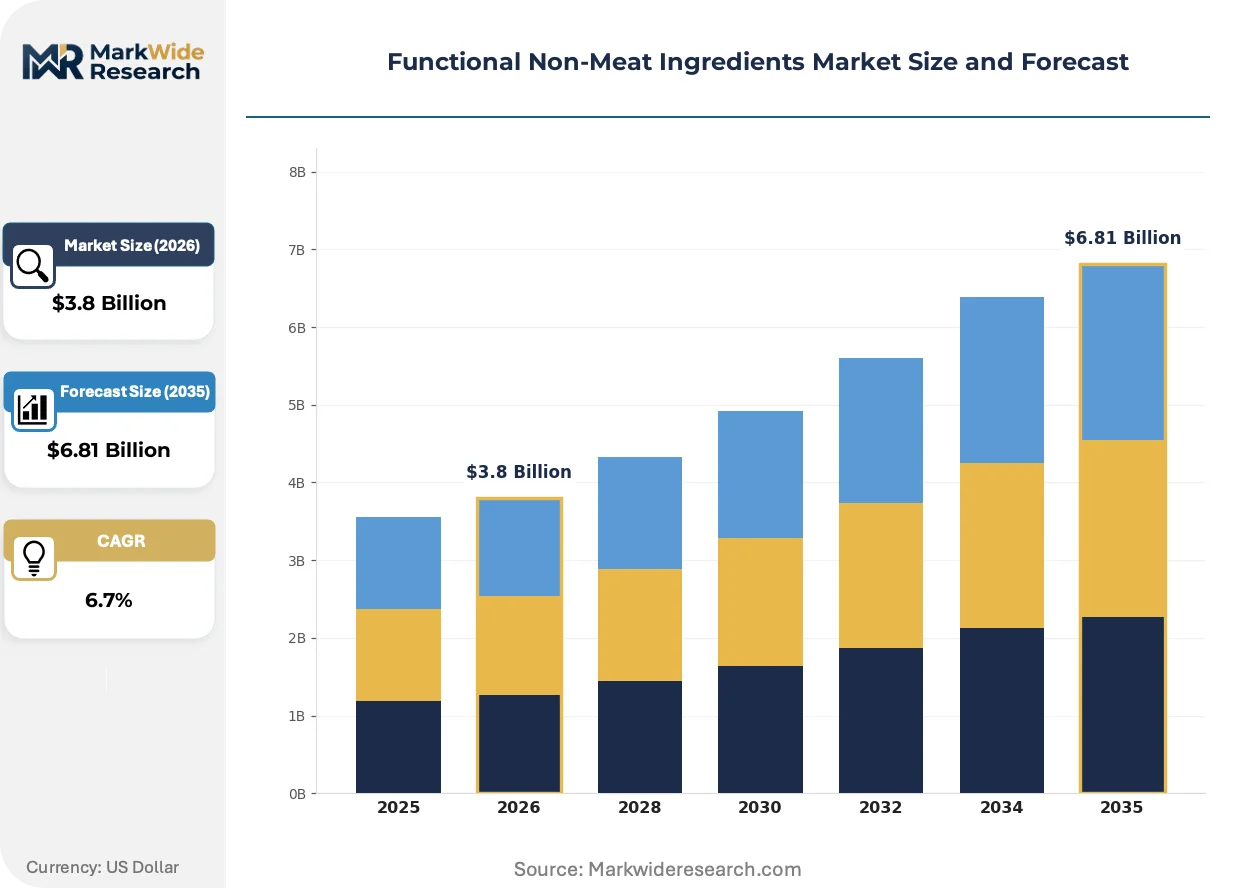
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Binders, Extenders, Flavoring Agents, Texturizers Application: Processed Foods, Snacks, Dairy Alternatives, Meat Alternatives Form: Powder, Liquid, Granule, Paste End User: Food Manufacturers, Restaurants, Retailers, Home Cooks |
| Companies Covered | Kerry Group PLC, Cargill, Archer Daniels Midland Company, DuPont, BASF, Ingredion, Wenda Ingredients, Wiberg GmbH, Ohly GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Non-Meat Ingredients Market Emerging Trajectories
High-moisture extrusion systems are rewriting the technical boundaries of meat analog texture, while regulatory pressure on carbon disclosure and procurement consolidation around specialized ingredient clusters reshape competitive requirements.
High-moisture extrusion (HME) technology is rewriting the structural possibilities for whole-muscle plant-based cuts by enabling fibrous orientation without post-extrusion cooling. German and Dutch food manufacturers are retrofitting HME lines at twice the pace of conventional low-moisture systems. The technology is compressing the performance gap between plant-based and conventional meat to under 15% sensory variance in blind panels.
The EU F-Gas Regulation's hydrofluorocarbon phase-down mandates are forcing cold-chain-dependent ingredient suppliers to accelerate shelf-stable format development. EFSA's parallel tightening of novel food consultation timelines creates dual compliance pressure on hydrocolloid innovators. Suppliers with existing ambient-stable portfolios in Germany and France capture first-mover positioning as refrigerated binder stocks face stranded asset risk.
Direct procurement contracts between meat-alternative brands and hydrocolloid specialists are displacing traditional distributor intermediaries in European supply chains. Cologne-based ingredient clusters now host embedded R&D labs where formulation scientists co-develop custom texturizer systems with CPG buyers. The shift concentrates technical know-how within 200-kilometer radiuses of Hamburg and Rotterdam port infrastructure.
Functional Non-Meat Ingredients Market Segmentation
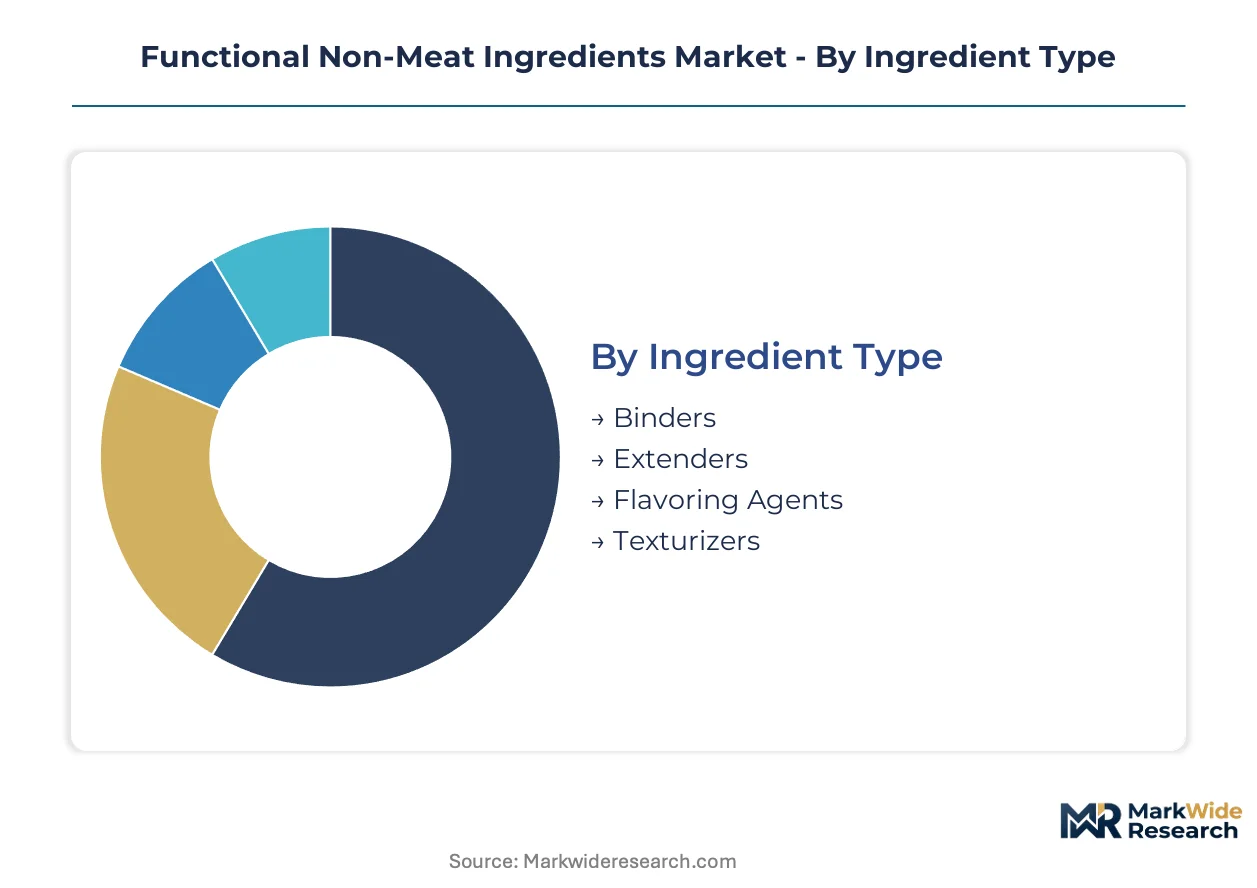
Formulation complexity in plant-based meat alternatives demands precise ingredient matching across functional roles, physical formats, and buyer sophistication levels. Segmentation reveals where margin pools concentrate and which technical specifications command procurement premiums.
Ingredient Type:
Buyers differentiate by the structural challenge their protein base presents—moisture retention, fibrous orientation, or flavor masking—rather than by commodity chemistry alone.
- Binders:Specialized hydrocolloids and starches form cohesive matrices that prevent syneresis in high-moisture extrudates. Demand clusters with German clean-label processors facing EU Green Deal carbon documentation requirements for sustainably sourced tapioca and potato derivatives.
- Texturizers:Protein-starch-hydrocolloid synergies replicate muscle fiber alignment and bite resistance. Cologne-based innovation clusters drive adoption as meat-alternative brands co-develop custom systems for proprietary whole-cut formats.
- Extenders:Cost-efficient carbohydrate and protein fillers stretch formulation yields without sensory degradation. French and Dutch processors favor these for legacy processed food lines where margin pressure exceeds clean-label imperatives.
- Flavoring Agents:Encapsulated and liquid systems mask off-notes from pea and soy isolates while delivering Maillard-reactive precursors. High-throughput extrusion lines in Hamburg favor liquid formats for uniform dispersion.
Volume sits with Extenders; growth tilts toward Texturizers.
Application:
End-use differentiation tracks regulatory exposure and speed-to-market pressure rather than absolute volume scale.
- Meat Alternatives:Whole-muscle cuts, ground formats, and fermented analogs require the most sophisticated texturizer-binder-flavor layering. EFSA novel food consultation timelines stretch 12-18 months for new entrants, advantaging suppliers with existing approvals.
- Processed Foods:Legacy emulsified and restructured meat products use functional ingredients primarily for cost control and shelf stability. Dutch and Belgian manufacturers dominate procurement as they retrofit lines for hybrid flexitarian formulations.
- Dairy Alternatives:Fermented and non-fermented plant milks, cheeses, and yogurts demand distinct hydrocolloid behavior—thixotropy for pourability, meltability for analog cheeses. Danish precision fermentation clusters supply next-generation binders bypassing agricultural land constraints.
- Snacks:Extruded and sheeted products prioritize expansion ratios and oil retention over fibrous structure. German private-label retailers drive specification standardization across their supplier bases.
Processed Foods anchor current procurement volumes; Meat Alternatives show the steepest expansion trajectory.
Form:
Physical state selection reflects cold-chain reliability, blending equipment, and dispersion uniformity requirements.
- Powder:Dominant format for dry blending operations and ambient-stable inventory. Shelf stability advantages intensify under EU F-Gas Regulation phase-down mandates threatening refrigerated storage assets.
- Liquid:Critical for high-throughput extrusion where pre-hydrated hydrocolloids ensure uniform moisture distribution. German quick-service chain pilots favor liquid flavoring systems for proprietary menu development.
- Granule:Intermediate dissolution kinetics suit intermediate-moisture applications where controlled hydration timing matters. Dutch ingredient processors specialize in agglomerated formats for reduced dusting.
- Paste:Pre-activated systems eliminate hydration variability for small-batch artisan producers. Limited adoption outside specialty European meat-alternative startups.
Powder commands installed base; liquid gains share fastest in extrusion-intensive operations.
End User:
Buyer sophistication and formulation control separate commercial segments from household procurement.
- Food Manufacturers:Integrated R&D capabilities enable custom texturizer co-development with hydrocolloid specialists. Direct procurement contracts displace distributor intermediaries around Cologne and Hamburg clusters.
- Restaurants:Quick-service and fast-casual chains pilot proprietary blends for differentiated plant-based menu items. German foodservice operators lead specification complexity.
- Retailers:Private-label consolidation drives standardization requests across multiple supplier tiers. French and Dutch supermarket chains pressure ingredient documentation for shelf-edge sustainability claims.
- Home Cooks:Pre-mixed consumer formats with simplified hydration instructions. Margins compress against commercial segments; growth limited to specialty health-food channels.
Food Manufacturers capture formulation value; Restaurants represent the fastest-climbing demand tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Hamburg and Rotterdam drive ingredient clustering, concentrating hydrocolloid innovation and clean-label processing capacity near North Sea port infrastructure.
Germany
Meat-alternative brands in Cologne and Hamburg co-develop custom texturizer systems with hydrocolloid specialists, pulling procurement from traditional distributors. The EU F-Gas Regulation's hydrofluorocarbon phase-down pressures cold-chain-dependent suppliers toward ambient-stable formats. Hamburg's port-adjacent ingredient clusters now host embedded R&D labs for direct CPG collaboration.
France
French processors favor extenders for legacy processed food lines where margin pressure exceeds clean-label imperatives, though Paris-based startups accelerate novel protein consultations. EFSA's tightened 2023 guidance on plant protein safety evaluations extends approval timelines for new entrants. The Auvergne-Rhône-Alpes region concentrates tapioca starch sourcing relationships with Thai suppliers.
Netherlands
Dutch ingredient processors specialize in agglomerated granule formats for reduced dusting, serving intermediate-moisture applications across European food manufacturers. Rotterdam's port infrastructure anchors hydrocolloid import and distribution networks. Precision fermentation platforms in the Randstad bypass agricultural land constraints for next-generation binder production.
United States
American food manufacturers retrofit high-moisture extrusion lines at twice the pace of conventional systems, compressing the sensory performance gap with conventional meat. FDA frameworks govern allergen labeling and novel food safety assessments for plant protein entrants. Midwest soy processing clusters face margin pressure from pea protein texturization advances.
Denmark
Danish precision fermentation clusters supply fermentation-derived hydrocolloids that bypass agricultural land constraints and carbon documentation requirements. The country's national food regulator aligns with EFSA consultation timelines for novel protein approvals. Copenhagen-area biotech infrastructure attracts venture funding for alternative binder platforms.
Functional Non-Meat Ingredients Market Vendor Landscape
Top-tier vendors anchor hydrocolloid and protein verticals, while mid-tier specialists occupy niche texturizer and flavor system segments. The vendor base organizes around three strategic archetypes: diversified agricultural processors with captive raw material supply, ingredient technology specialists with embedded R&D capabilities, and regional flavor houses with local formulation expertise. Competitive moves concentrate on direct procurement contracting with meat-alternative brands and co-development partnerships for proprietary texturizer systems.
Within the diversified processor tier, Kerry Group PLC and Cargill occupy positions defined by vertical integration into raw material supply and scale-driven manufacturing footprints. Ingredion exemplifies the starch-specialist archetype, anchoring formulation relationships with clean-label processors facing EU Green Deal carbon documentation requirements. These three entities collectively represent the competitive tension between agricultural commodity leverage and specialized ingredient technology development.
| Leading Market Players |
|---|
| Kerry Group PLC |
| Cargill |
| Archer Daniels Midland Company |
| DuPont |
| BASF |
| Ingredion |
| Wenda Ingredients |
| Wiberg GmbH |
| Ohly GmbH |
| Others |
Supply Flow & Price Mechanics
Backward integration into pea protein processing anchors supply positions for European texturizer specialists while compressing margin pools for distributors caught between farm-gate volatility and clean-label processor procurement mandates. The EU Green Deal's carbon documentation requirements concentrate pricing power with suppliers who control certified sustainable tapioca and potato starch sourcing from Thai and Dutch processors.
Pricing Analysis
Short lead-time premiums dominate spot procurement for high-moisture extrusion lines where German manufacturers face compressed formulation timelines. Three-tier pricing structure across premium, standard, and economy levels separates fermentation-derived hydrocolloids from commodity starches and extenders. Cost compression in standard-tier binders is intensifying because Canadian and French pea protein harvest volatility transmits directly to texturizer input costs. Private-label retailers show highest price sensitivity while integrated meat-alternative brands absorb premiums for proprietary co-development partnerships.
Supply Chain Analysis
Hydrocolloid supply rests on Thai tapioca starch processors, Dutch potato starch refiners, and Danish precision fermentation platforms for next-generation binder production. Raw material dependencies center on pea and soy protein isolates, specialty starches, and Maillard-reactive flavor precursors. Single-source vulnerability concentrates in certified sustainable tapioca supply where Thai processors dominate clean-label documentation. Distribution runs through direct procurement contracts displacing traditional intermediaries around Cologne and Hamburg ingredient clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pea protein texturization capacity bottlenecks prop pricing premiums as extrusion line retrofit demand outstocks qualified formulation chemist supply. Supply constraints concentrate procurement leverage with incumbent hydrocolloid specialists holding documented carbon-compliant sourcing.
For Market Incumbents: Hedge against fermentation-derived hydrocolloid disruption by securing long-term tapioca and potato starch offtake agreements with Thai and Dutch processors. Accelerate embedded R&D lab deployments in Cologne and Hamburg to defend against precision fermentation entrants bypassing agricultural land constraints. Certification investment in EU Green Deal carbon documentation anchors clean-label processor relationships against commodity starch competitors. For New Entrants and Emerging Players: Precision fermentation platforms offer a technology-first wedge into binder production where Danish infrastructure and venture funding clusters reduce capital access barriers. White-space targets concentrate in ambient-stable powdered formats demanded by EU F-Gas Regulation compliance and in quick-service chain custom blends for proprietary German menu development. Go-to-market positioning through direct CPG collaboration agreements bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified agricultural processors seeking hydrocolloid technology capabilities. Long-term viability favors precision fermentation specialists with existing novel food approvals and ambient-stable format portfolios over cold-chain-dependent legacy suppliers. Watch EFSA consultation timeline compression as the inflection signal determining first-mover positioning in emerging protein platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Denmark-based platforms bypass Thai tapioca land constraints for carbon-compliant binder supply. |
| Embedded R&D Lab Deployment | Cologne clusters enable direct co-development with meat-alternative brands displacing distributors. |
| High-Moisture Extrusion Retrofit | German manufacturers compress sensory variance gaps through equipment modernization programs. |
| Carbon Documentation Certification | EU Green Deal compliance anchors clean-label processor procurement relationships against commodity competition. |
| Novel Food Approval Acceleration | EFSA consultation navigation determines first-mover positioning in pea and emerging protein texturizers. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with formulation chemists, procurement leads at meat-alternative brands, hydrocolloid R&D directors, and foodservice chain menu developers validated demand assumptions. Bottom-up volume modeling triangulated against top-down spending estimates from food manufacturer capex disclosures and ingredient import trajectories across the analysis window.
Data-stream reconciliation between extrusion equipment shipment records, novel food submission databases, and clean-label processor procurement surveys shaped the analytical framework across ingredient type, application format, and end-user sophistication segments. CAGRs derived from trend extrapolation of high-moisture extrusion adoption curves and carbon documentation compliance timelines. Forecast inputs incorporated EFSA consultation velocity and EU F-Gas Regulation phase-down implementation pacing.
Several conditions sit outside the modeled scope, including speculative novel protein platforms without active safety consultations and pre-commercial fermentation technologies lacking pilot-scale validation. Forecasts reflect documented assumptions about regulatory approval timelines and supply chain decarbonization trajectories. A small set of named triggers warrants ongoing watch: EFSA guidance revisions, Thai tapioca harvest disruption, and precision fermentation platform commercialization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
South America Prebiotic Ingredients Market
Functional Food & Ingredients
Beta Glucan and Fucoidan Market
Functional Food & Ingredients
Omega 3 PUFA Market
Functional Food & Ingredients
Global Whole Grain and High Fiber Food Market
Functional Food & Ingredients
Japan Soy Protein Market
Functional Food & Ingredients
Healthy Fats Low Carb Market
Functional Food & Ingredients
Europe Botanical Extract Market
Functional Food & Ingredients
Europe Prebiotic Ingredient Market
Functional Food & Ingredients
Global Medical Foods Market
Functional Food & Ingredients
Asia-Pacific Omega3 PUFA Market
Functional Food & Ingredients
Protein Cookie Market
Functional Food & Ingredients
Lovage Extract Market
Functional Food & Ingredients
Mediterranean Cognitive-First Ingredient Systems Market
Functional Food & Ingredients
Europe Omega-3 PUFA Market
Functional Food & Ingredients
Functional Food Ingredients Market
Functional Food & Ingredients
Prebiotic Ingredients Market