
 Brominated Vegetable Oil Market | 2026-2036
Brominated Vegetable Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Brominated Vegetable Oil Market Outlook
Soybean oil is decoupling from brominated vegetable oil formulations as beverage manufacturers pursue alternative emulsification chemistries. Penta Manufacturing Company leverages its specialty chemical synthesis capabilities to serve residual industrial demand for brominated esters. Parchem Fine & Specialty Chemicals anchors its position through bulk distribution networks that sustain access to niche food-grade brominated oil channels. Spectrum Chemical Manufacturing Corp differentiates via its analytical-grade product lines that command premium positioning in laboratory and quality-control applications.
Brominated vegetable oil comprises bromine atoms esterified to triglycerides derived from vegetable sources, typically achieving bromine content between 34% and 36% by weight to confer density modification in citrus-flavored beverages. Its primary commercial purpose centers on preventing flavor oil separation in soft drinks by matching the density of aqueous solutions. The soft drinks segment leads volume consumption despite sustained reformulation activity, while the shelf life extension application commands disproportionate margin contribution from preservative-adjacent positioning. Food additives represents the fastest-contracting category as clean-label migration accelerates across North American and European retail channels.
FDA maintains a regulatory framework that permits brominated vegetable oil in specified food applications subject to identity standards and additive tolerance thresholds, while state-level initiatives in California and New York advance prohibitions that fragment compliance geography. The EPA oversees bromine compound environmental release profiles that indirectly constrain manufacturing location decisions. EFSA evaluations of brominated substances in food contact materials create parallel compliance obligations for exporters serving European beverage manufacturers. Stakeholders must monitor the divergence between federal permissibility and sub-national restriction trends to calibrate portfolio exposure across formulation alternatives.
Market Dynamics
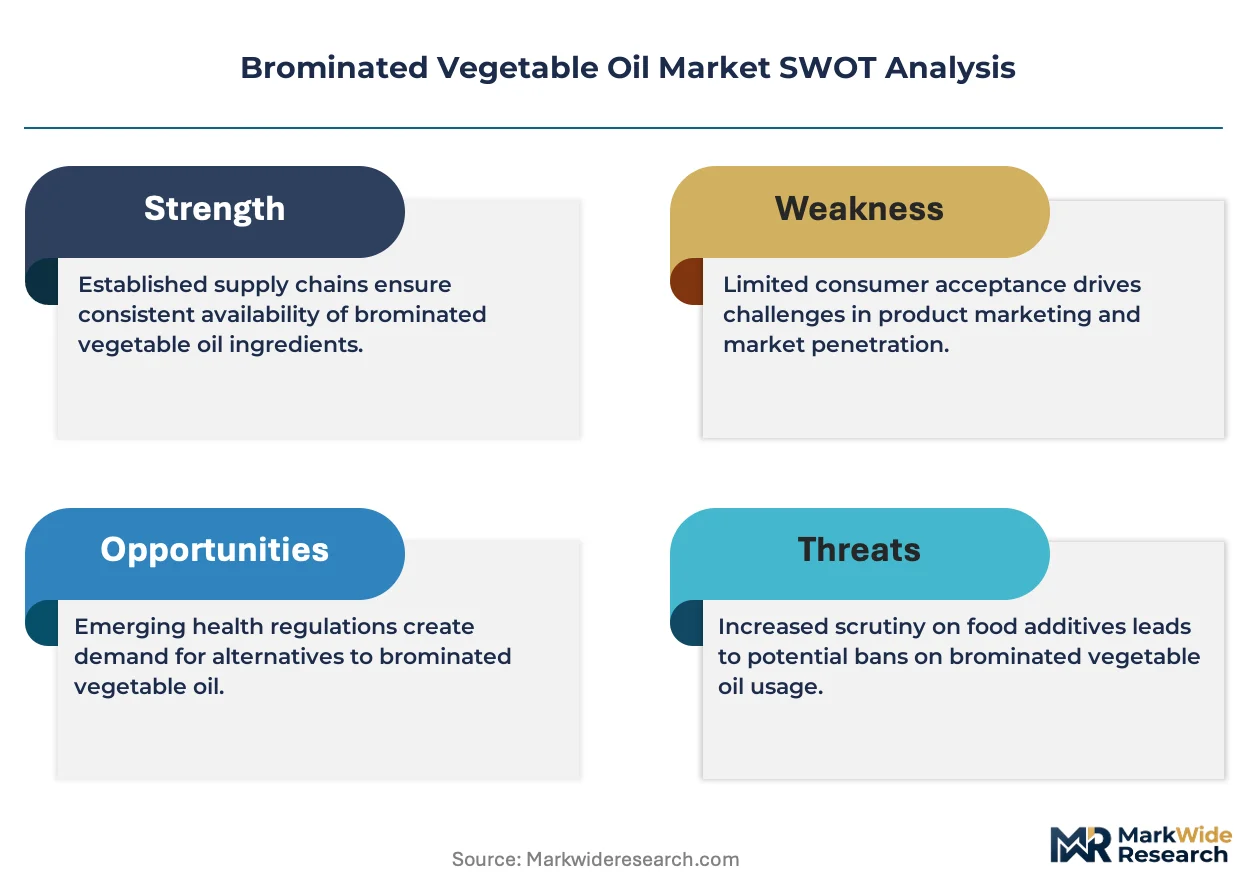
The brominated vegetable oil market is undergoing a fundamental restructuring driven by the collision between legacy beverage formulations and state-level prohibition mandates that are fragmenting compliance geography across the United States.
Growth Catalysts
- Residual soft drink formulation demand:Citrus-flavored beverage manufacturers in the United States continue specifying brominated vegetable oil for density matching of flavor oils, sustaining volume despite reformulation pressures.
- REACH compliance for industrial brominated esters:European chemical manufacturers maintain demand for brominated vegetable oil derivatives in non-food applications, creating a parallel demand channel.
- Analytical-grade laboratory consumption:Quality control laboratories and research institutions procure brominated vegetable oil as reference standards and density calibration materials.
Market Restraints
- California Assembly Bill 418:State-level prohibitions on brominated vegetable oil in food products create compliance fragmentation that complicates national distribution strategies for beverage manufacturers.
- Soybean oil price volatility:Feedstock cost fluctuations for the triglyceride base directly compress margin structures for bromination processors.
- Glycerol ester of wood rosin substitution:Alternative density-modifying emulsifiers achieve comparable performance in citrus beverages without bromine content, accelerating displacement in reformulating product lines.
Strategic Opportunities
- Industrial brominated ester pivot:Specialty chemical manufacturers can redirect bromination capacity toward flame retardant and polymer additive applications as food-grade demand contracts.
- Latin American beverage export channels:Regulatory permissibility in Mexico and Brazil sustains demand for legacy citrus beverage formulations that specify brominated vegetable oil.
- ISO 17025-certified reference material positioning:Analytical-grade producers can capture premium positioning through accredited quality management systems for laboratory supply chains.
Industry Challenges
- Bromination process safety compliance:Facilities handling elemental bromine face intensifying OSHA process safety management requirements that elevate operational overhead.
- Dual-use chemical licensing complexity:Export control frameworks for bromine compounds create documentation burdens that delay international shipment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brominated Vegetable Oil Market |
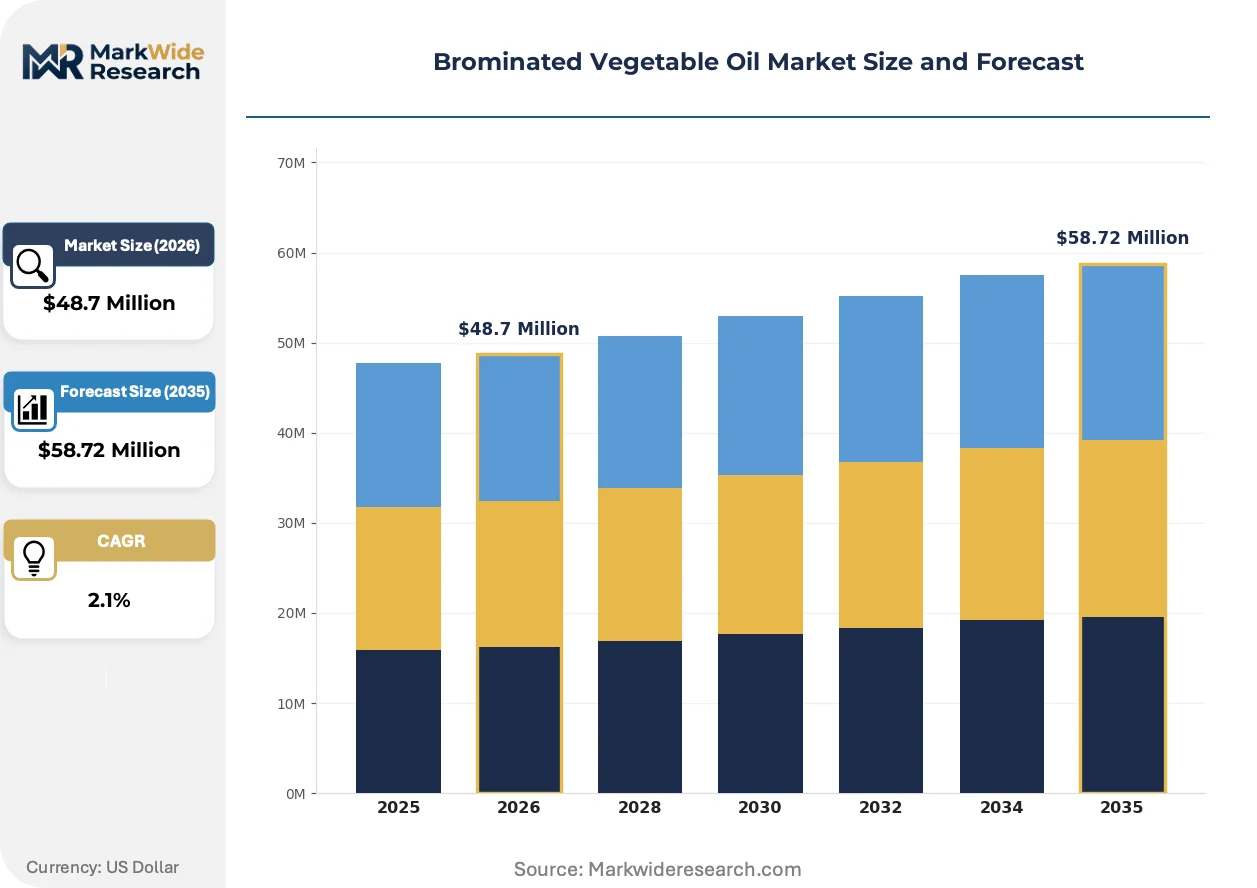
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $58.72 Million |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Drinks, Food Additives, Confectionery, Bakery Products End User: Food Industry, Beverage Industry, Nutraceuticals, Cosmetics Application: Flavor Enhancement, Color Stabilization, Texture Modification, Shelf Life Extension Distribution Channel: Supermarkets, Online Retail, Wholesale Distributors, Specialty Stores |
| Companies Covered | Penta Manufacturing Company, Parchem Fine & Specialty Chemicals, Spectrum Chemical Manufacturing Corp, Synutra International, Kerry Ingredients & Flavours, Abitec Corporation, Watson Inc., Advanced Food Systems Inc., Aarhuskarlshamn AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brominated Vegetable Oil Market Strategic Shifts
Reformulation chemistry is actively displacing legacy emulsification approaches as beverage manufacturers confront divergent regulatory thresholds across state and national boundaries.
Microfluidic emulsification technology is absorbing development attention from alternative density-matching solutions. Beverage formulators at mid-sized citrus drink manufacturers are piloting these systems to achieve stable oil-in-water dispersions without brominated compounds. The technology is absorbing capital that previously supported brominated vegetable oil procurement budgets, compressing the addressable market for traditional emulsifiers.
California's AB 418 prohibition on brominated vegetable oil in food products took effect in 2027, establishing the most restrictive state-level standard in the United States. The regulation forces national beverage brands to maintain dual formulation inventories or abandon brominated vegetable oil entirely. Citrus-flavored soft drink lines distributed across multiple states are most affected, with manufacturers accelerating clean-label transitions ahead of anticipated adoption in New York and Illinois.
Direct procurement relationships between beverage conglomerates and specialty chemical houses are consolidating supply chain tiers. Distributor intermediaries that historically managed brominated vegetable oil logistics are losing position as buyers seek formulation partnership models with bromination specialists. This restructuring is most visible in the southeastern United States, where concentrated soft drink production clusters enable supplier co-location strategies.
Brominated Vegetable Oil Market Segmentation
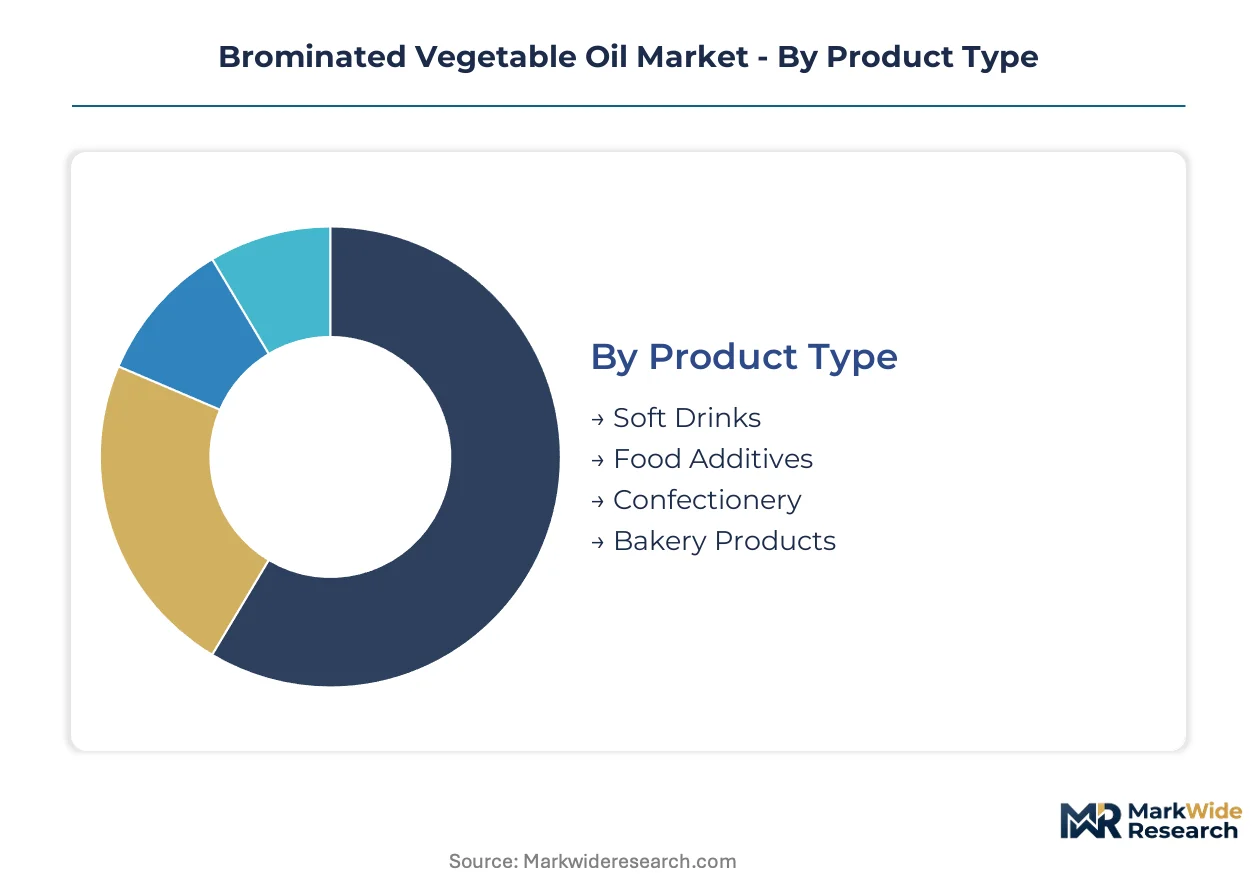
Brominated vegetable oil demand fragments sharply across regulatory tolerance thresholds. FDA-permitted food applications now coexist with state-level prohibitions that force manufacturers to maintain parallel formulation inventories.
Product Type:
Certification burdens concentrate in food-contact segments where FDA identity standards apply, while industrial and analytical grades face separate REACH and ISO compliance tracks.
- Soft Drinks:Citrus-flavored beverage formulations specify brominated vegetable oil at 34-36% bromine content to match aqueous density. California AB 418 prohibition forces national brands to maintain dual inventory or abandon the ingredient entirely.
- Food Additives:Clean-label migration accelerates displacement across North American retail channels. Reformulation toward glycerol ester of wood rosin substitutes compresses this segment's trajectory.
- Confectionery:Limited penetration in panned coatings and oil-based flavor systems where density modification proves secondary to crystallization control.
- Bakery Products:Marginal adoption confined to specialty emulsified shortenings where brominated triglycerides interact with leavening chemistry.
Soft Drinks sits at the top of the volume ranking, with Food Additives climbing the fastest—though downward.
End User:
Customer scale determines procurement modality, with beverage conglomerates pursuing direct bromination partnerships while smaller formulators rely on distributor intermediaries.
- Food Industry:Processed food manufacturers face the steepest reformulation pressure as clean-label commitments cascade from retail channel mandates.
- Beverage Industry:Legacy citrus soft drink producers in the southeastern United States sustain residual demand through concentrated production clusters that enable supplier co-location.
- Nutraceuticals:Minimal penetration; emulsification needs in supplement delivery systems favor non-brominated alternatives due to export market restrictions.
- Cosmetics:Industrial-grade brominated esters find niche application in pigment dispersion systems outside food-contact regulatory scope.
Beverage Industry commands the largest procurement volumes, with Food Industry contracting most rapidly under prohibition mandates.
Application:
Functional performance requirements dictate bromine content specifications and analytical validation protocols across use cases.
- Flavor Enhancement:Density-matching of citrus oils remains the core technical justification, preventing phase separation in aqueous systems. Reformulation to microfluidic emulsification systems is absorbing capital formerly directed to brominated vegetable oil procurement.
- Shelf Life Extension:Preservative-adjacent positioning commands disproportionate margin contribution despite smaller volume, as oxidative stability claims support premium pricing.
- Color Stabilization:Limited adoption in oil-soluble dye systems where brominated carriers interact with light stability requirements.
- Texture Modification:Marginal application in viscoelastic gel systems where triglyceride crystallization behavior affects mouthfeel.
Flavor Enhancement anchors volume demand, with Shelf Life Extension gaining share fastest through premium positioning.
Distribution Channel:
Channel structure reflects customer concentration geography and lot-size requirements for brominated compound handling.
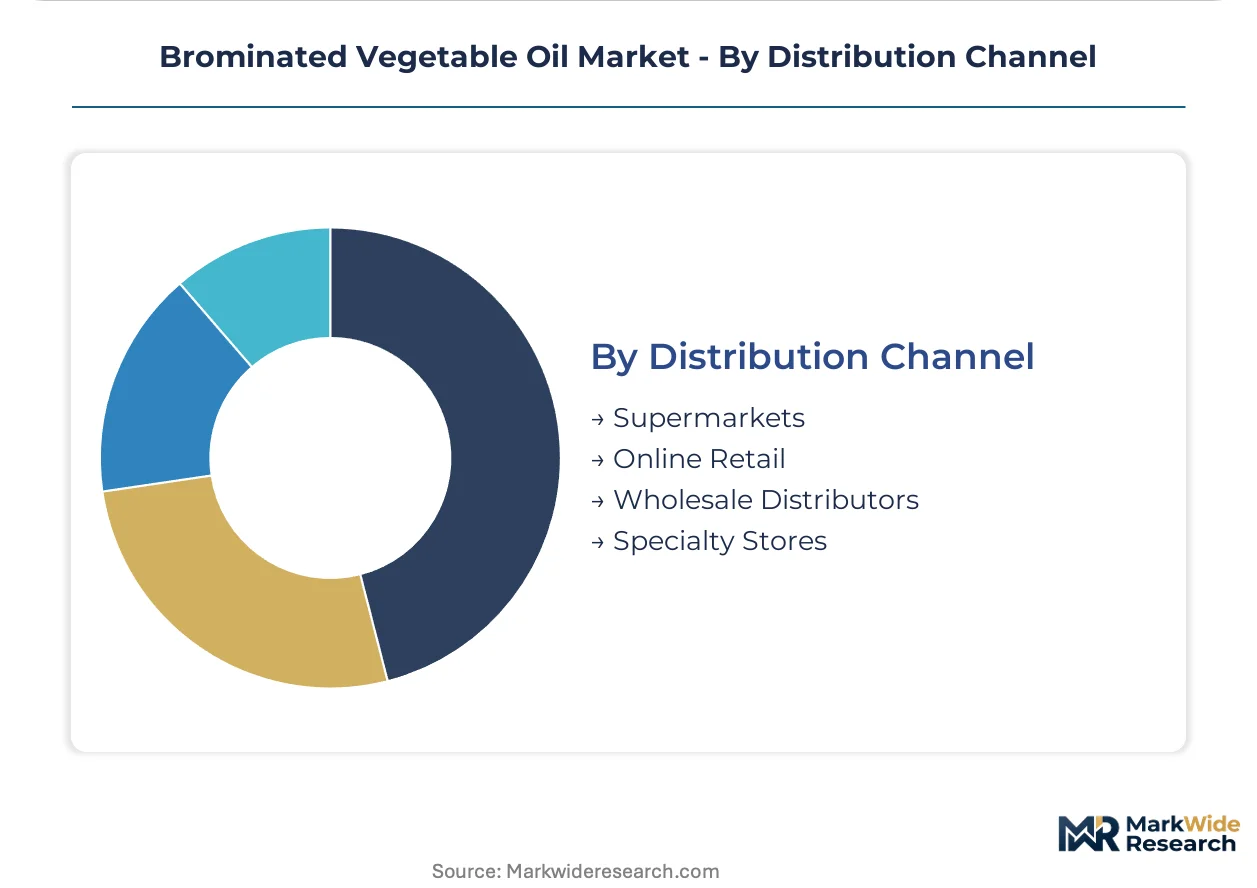
- Wholesale Distributors:Bulk logistics networks sustain access to niche food-grade channels, though direct procurement trends erode intermediary position.
- Online Retail:Analytical-grade and laboratory-scale quantities migrate to digital procurement platforms serving quality control and research institutions.
- Supermarkets:Negligible direct sales; consumer-facing brominated vegetable oil products are effectively nonexistent in retail grocery.
- Specialty Stores:Confined to industrial chemical suppliers serving flame retardant and polymer additive applications outside food contact.
Wholesale Distributors retains volume leadership, with Online Retail expanding most quickly in analytical-grade segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The southeastern United States beverage production corridor sustains the largest concentration of brominated vegetable oil procurement, with legacy citrus soft drink manufacturing clusters anchoring residual demand despite accelerating reformulation mandates.
United States
Legacy citrus beverage manufacturers in Georgia and Florida continue specifying brominated vegetable oil for density matching, though California AB 418 forces national brands toward dual formulation inventories. FDA maintains federal permissibility under 21 CFR standards while state-level prohibitions fragment compliance geography. The Atlanta-Charlotte corridor hosts concentrated supplier co-location strategies as direct procurement relationships consolidate.
Germany
Specialty chemical manufacturers leverage bromination capacity for industrial ester derivatives serving flame retardant and polymer additive channels. REACH compliance frameworks govern non-food applications, creating parallel demand distinct from beverage emulsification. The Rhine-Ruhr industrial basin concentrates bromination processing infrastructure for export-oriented chemical production.
Brazil
Regulatory permissibility sustains demand for legacy citrus beverage formulations among domestic soft drink producers and export-oriented manufacturers. ANVISA frameworks lack equivalent prohibitions to California standards, preserving formulation continuity. The São Paulo state beverage manufacturing cluster imports brominated vegetable oil through distributor networks serving Latin American distribution.
China
Domestic bromination capacity serves industrial applications including polymer additives and analytical-grade reference materials, with minimal food-contact penetration due to export market restrictions. GB standards and SAMR oversight govern chemical safety profiles for domestic distribution. The Yangtze River Delta chemical manufacturing corridor hosts brominated ester production for regional specialty chemical supply chains.
Mexico
Beverage export channels to the United States drive residual brominated vegetable oil specification in legacy formulation lines, though reformulation pressure intensifies with cross-border distribution complexity. COFEPRIS regulatory frameworks permit continued food-grade application absent federal prohibition. The Mexico City metropolitan area concentrates beverage manufacturing procurement decisions affecting northern border state supplier relationships.
Brominated Vegetable Oil Market Competitive Environment
Global majors compete with regional champions across formulation partnership and distribution channel dimensions, producing a tiered structure where direct procurement relationships consolidate at the beverage conglomerate tier while distributor intermediaries serve mid-sized formulators. The vendor base separates into bromination specialists with captive synthesis capabilities, bulk chemical distributors managing logistics complexity, and analytical-grade producers serving laboratory quality-control channels. Dominant competitive moves include geographic co-location near beverage production clusters and portfolio diversification toward industrial brominated ester applications as food-grade demand contracts.
Within the specialty chemical synthesis tier, Penta Manufacturing Company and Parchem Fine & Specialty Chemicals exemplify divergent strategic positioning—Penta anchors residual industrial demand for brominated esters through synthesis capabilities, while Parchem occupies a bulk distribution position sustaining access to niche food-grade channels. Spectrum Chemical Manufacturing Corp represents the analytical-grade archetype, commanding premium positioning in laboratory supply chains through quality management accreditation. These three entities collectively illustrate the market's fragmentation across synthesis, distribution, and certification-based differentiation vectors.
| Leading Market Players |
|---|
| Penta Manufacturing Company |
| Parchem Fine & Specialty Chemicals |
| Spectrum Chemical Manufacturing Corp |
| Synutra International |
| Kerry Ingredients & Flavours |
| Abitec Corporation |
| Watson Inc. |
| Advanced Food Systems Inc. |
| Aarhuskarlshamn AB |
| Others |
Value Chain & Pricing Dynamics
Family-owned specialty chemical mid-caps in the southeastern United States exercise tight pricing discipline through captive bromination capacity and long-standing formulation partnerships with legacy beverage producers. Their ownership structure insulates margin targets from quarterly earnings pressure, allowing selective volume retention even as soybean oil feedstock costs fluctuate and California prohibition mandates fragment addressable demand.
Pricing Analysis
Input-cost pass-through from soybean oil and elemental bromine feedstocks governs contract renegotiation rhythms between bromination processors and beverage manufacturers. Three-tier pricing structure across food-grade certified, industrial-grade, and analytical-grade quality levels separates procurement channels, with ISO 17025-accredited reference materials commanding substantial premia over bulk industrial esters. Cost compression in food-grade tiers is intensifying because glycerol ester of wood rosin substitutes achieve equivalent density-matching performance at lower regulatory compliance burden. Mid-sized citrus beverage formulators exhibit highest price sensitivity as reformulation capital absorbs procurement budgets, while analytical laboratories demonstrate lowest sensitivity due to reference standard requirements.
Supply Chain Analysis
Reverse-logistics flows for brominated vegetable oil are negligible given single-use consumption patterns in beverage applications and hazardous material handling restrictions on returns. Supply concentrates in the United States, Germany, and China, with the Atlanta-Charlotte corridor hosting the densest cluster of bromination capacity serving North American beverage production. Feedstock dependencies draw from soybean oil processors, elemental bromine extractors, and specialty packaging suppliers for food-grade containment. Single-source vulnerability characterizes the supply structure, as qualified bromination facilities face intensifying OSHA process safety management requirements that constrain capacity expansion. Distribution runs through wholesale chemical distributors for bulk industrial quantities, with direct procurement relationships consolidating at beverage conglomerate tier.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in brominated vegetable oil hinges on portfolio pivot toward analytical-grade certification and industrial brominated ester applications, as food-grade volume contracts accelerate clean-label substitution.
For Market Incumbents: Deploy backward integration into elemental bromine sourcing to defend margin position against feedstock volatility and glycerol ester of wood rosin substitution threat. Incumbent bromination specialists should consolidate direct procurement relationships with southeastern United States beverage clusters while redirecting excess capacity toward flame retardant polymer additive channels. ISO 17025 accreditation investment represents critical defensive positioning as laboratory reference material demand proves most resilient to prohibition mandates. For New Entrants and Emerging Players: Microfluidic emulsification technology platforms offer technology-first entry wedge into citrus beverage formulation services, displacing traditional brominated vegetable oil specification entirely. New entrants should target mid-sized Latin American beverage exporters in Mexico and Brazil, where ANVISA and COFEPRIS frameworks preserve regulatory permissibility for legacy formulations. Go-to-market execution should emphasize formulation partnership models rather than commodity chemical distribution, capturing procurement budgets previously directed to brominated vegetable oil. For Investors and Strategic Acquirers: Valuations sit cheapest among analytical-grade producers with captive ISO 17025 quality management systems, as laboratory supply chain positioning commands durable premium multiples. Long-term viability framing centers on industrial brominated ester pivot capacity and geographic exposure to regulatory-permissible markets. Acquisition target archetype encompasses specialty chemical mid-caps with bromination assets in the United States or Germany and established distributor relationships in Latin America. Practitioners should monitor California AB 418 adoption cascades into New York and Illinois state legislatures as inflection indicator for food-grade demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elemental Bromine | Captive feedstock supply insulates Penta Manufacturing Company from commodity price volatility. |
| ISO 17025 Quality Management Accreditation | Spectrum Chemical Manufacturing Corp commands laboratory reference material premia through certified positioning. |
| Latin American Distribution Channel Expansion | Parchem Fine & Specialty Chemicals sustains food-grade volume through Brazil and Mexico regulatory permissibility. |
| Industrial Brominated Ester Capacity Pivot | German specialty chemical manufacturers redirect bromination assets toward REACH-compliant flame retardant applications. |
| Direct Procurement Relationship Consolidation | Beverage conglomerates eliminate distributor intermediaries through supplier co-location in southeastern United States clusters. |
Study Parameters
Coverage spans the United States, Germany, Brazil, China, and Mexico, with primary inputs from each market informing demand segmentation and regulatory trajectory assessment. The analysis combines structured interviews with bromination plant managers, procurement leads at citrus beverage manufacturers, specialty chemical distribution channel partners, and technical R&D directors at emulsifier specialists. Secondary validation draws from FDA 21 CFR filings, ECHA REACH registration databases, ANVISA regulatory bulletins, SAMR GB standards publications, and customs trade flow records. Bottom-up volume modeling triangulates against top-down value estimates derived from chemical industry association reports.
Rate-of-change decomposition separates volume trajectory into price elasticity effects, substitution coefficient shifts, and regulatory prohibition impacts across the projection horizon. The analytical framework models segmentation across product grade tier, end-use industry, application function, and regional regulatory cluster. CAGRs were derived through regression analysis of historical procurement patterns and scenario-weighted regulatory adoption timelines. Industry-specific forecast inputs include bromine content specification requirements, clean-label reformulation capital allocation surveys, and state-level prohibition mandate tracking.
The model holds under stable federal FDA permissibility with state-level prohibition fragmentation; deviation toward federal prohibition or accelerated international adoption would shift trajectory substantially. Forecasts reflect assumptions regarding reformulation technology diffusion rates and industrial brominated ester demand elasticity. Practitioners should monitor OSHA process safety management enforcement intensity and glycerol ester of wood rosin cost curves for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
Global Medical Foods Market
Functional Food & Ingredients
Italy Protein Market
Functional Food & Ingredients
Mediterranean Pre-Diabetes Ingredient Concepts Market
Functional Food & Ingredients
Multifunctional Food Ingredients Market
Functional Food & Ingredients
Asia-Pacific Omega3 PUFA Market
Functional Food & Ingredients
Mediterranean Cognitive-First Ingredient Systems Market
Functional Food & Ingredients
Global Probiotic Ingredients Market
Functional Food & Ingredients
Protein Cookie Market
Functional Food & Ingredients
Omega 3 PUFA Market
Functional Food & Ingredients
North America and Europe Medical Foods Market
Functional Food & Ingredients
Global Whole Grain and High Fiber Food Market
Functional Food & Ingredients
Lovage Extract Market
Functional Food & Ingredients
Functional Food Ingredients Market
Functional Food & Ingredients
Prebiotic Ingredients Market
Functional Food & Ingredients
Prickly Pear Fruit Metabolic Health Ingredients Market
Functional Food & Ingredients
Brazil Flavored and Functional Water Market