
 Superfood Powders Market | 2026-2036
Superfood Powders Market Size, Share, and Industry Trends Forecast 2026-2036
Superfood Powders Market Intelligence
The emphasis on single-origin and scientifically validated nutrient profiles is unwinding the market’s reliance on generic blends. This shift favors suppliers with transparent supply chains and clinical backing for their ingredients. Archer-Daniels-Midland Company leverages its vast ingredient processing scale to supply foundational materials. Navitas Organics specializes in consumer-facing organic products, building strong brand trust, while Kerry Group plc differentiates through its focus on nutrition science in functional food formulations.
Superfood powders are concentrated, dehydrated forms of foods recognized for high nutrient density. Production often involves freeze-drying or cold-milling to preserve heat-sensitive enzymes and vitamins, a key quality differentiator. Demand for berry powders like acai and leafy greens such as spirulina commands a significant share of the product landscape. The organic source category defines the premium tier, with smoothies and nutritional supplements remaining the primary applications for these products.
Regulatory frameworks from the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) scrutinize health claims and labeling accuracy. These standards create high barriers for new entrants unable to provide clinical validation. In China, the State Administration for Market Regulation (SAMR) oversees import registrations, which influences sourcing strategies for multinational brands. Suppliers must navigate the challenge of substantiating health benefits scientifically while ensuring supply chain integrity for premium ingredients.
Market Dynamics
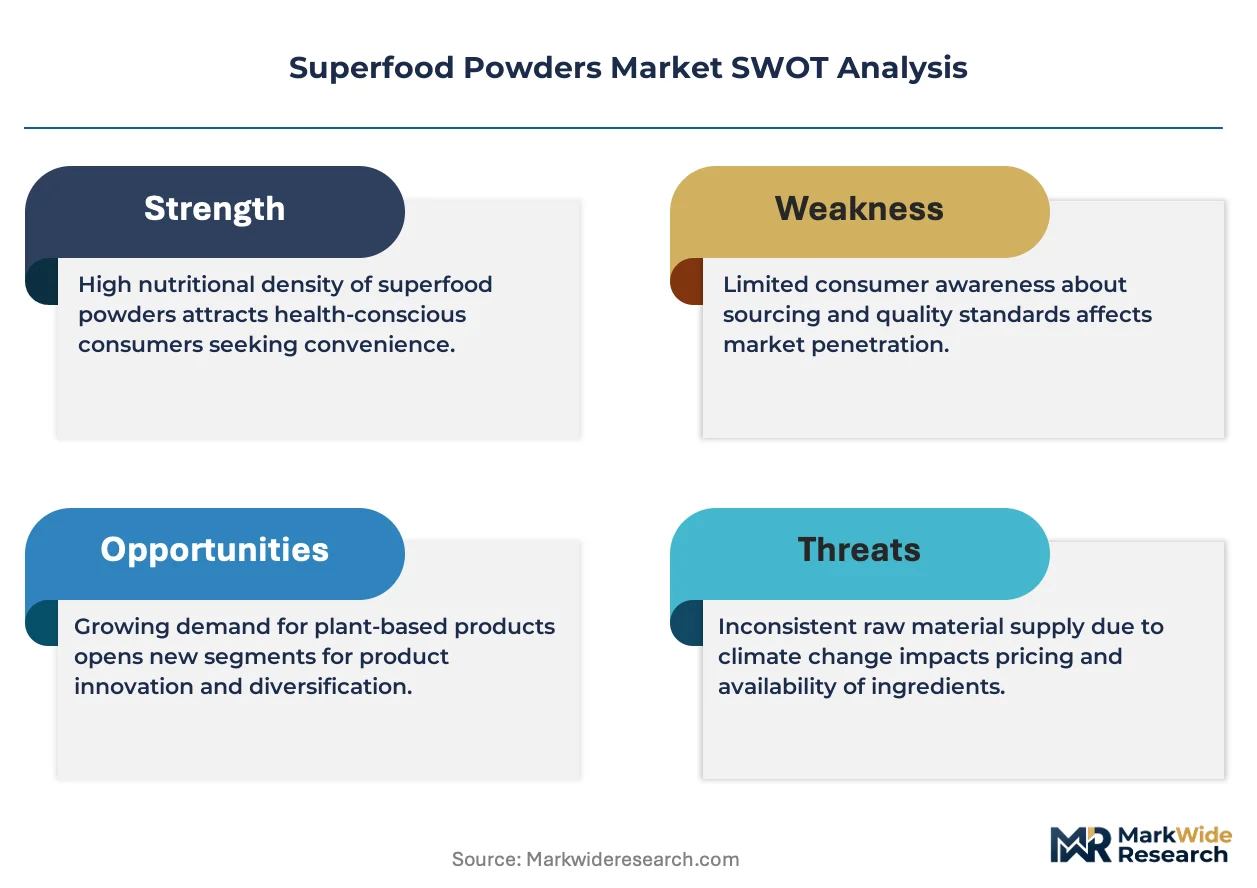
The market's central dynamic is the increasing demand for scientific validation of health benefits, a force that elevates regulatory compliance from a cost center to a key competitive differentiator. This pressure for clinical substantiation is reshaping sourcing, formulation, and marketing strategies across the industry.
Growth Catalysts
- Consumer Health Consciousness:Heightened consumer focus on preventative health and wellness, particularly in the United States and Germany, drives demand for nutrient-dense foods and transparently sourced ingredients for smoothies and home cooking.
- Stringent Organic Standards:The rigorous certification criteria of bodies like the USDA and the EU's organic framework create a distinct premium tier, allowing certified producers to command higher prices and build consumer trust.
- Functional Food Integration:The expansion of the functional food and beverage sector provides a significant catalyst, pulling superfood powders into new product categories like fortified snacks, yogurts, and ready-to-drink beverages.
Market Restraints
- High Production Costs:Premium processing methods such as freeze-drying, essential for preserving nutrient integrity, are capital- and energy-intensive, which elevates final product prices and limits accessibility for mass-market consumers.
- Supply Chain Vulnerability:Reliance on single-origin ingredients, such as acai from the Amazon basin or matcha from specific Japanese prefectures, exposes the market to climate-related disruptions, geopolitical risks, and price volatility.
- Health Claim Substantiation:The stringent requirements for scientific evidence to support health claims, enforced by regulators like the EFSA and FDA, create significant financial and research barriers for new and smaller market entrants.
Strategic Opportunities
- Geographic Expansion:There is a clear opportunity to penetrate markets in Southeast Asia and the Middle East, where rising disposable incomes and a growing wellness culture present a new frontier for growth beyond established North American and European markets.
- Personalized Nutrition Formulations:Development of targeted superfood powder blends for specific consumer needs, such as sports performance, cognitive health, or immune support, offers a path to value-added differentiation beyond generic wellness products.
- Nutraceutical Ingredient Development:Leveraging superfood extracts as active ingredients within scientifically validated nutraceuticals and dietary supplements opens a high-margin opportunity that aligns with the demand for evidence-based wellness solutions.
Industry Challenges
- Navigating Import Regulations:The complex and evolving import registration processes, such as the framework managed by China's SAMR, create significant administrative hurdles and time-to-market delays for brands seeking to enter new international markets.
- Ensuring Ingredient Authenticity:A primary operational challenge is combating adulteration and ensuring the authenticity and potency of premium ingredients throughout a global supply chain, which requires robust testing and traceability systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Superfood Powders Market |
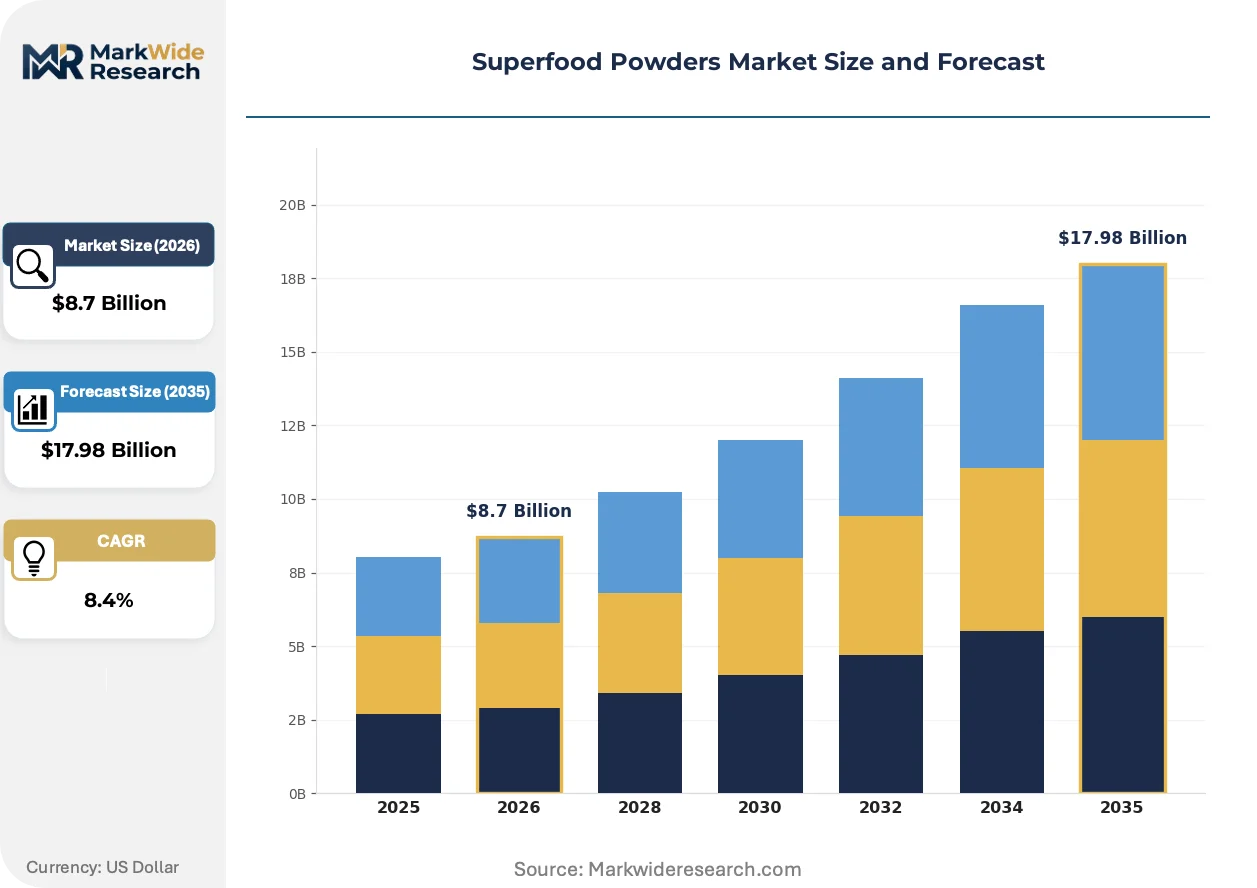
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leafy Greens, Berries, Roots, Protein Powders Source: Plant-Based, Organic, Non-GMO, Conventional Form: Powder, Capsule, Liquid, Extract Application: Smoothies, Baking, Meal Replacement, Nutritional Supplements |
| Companies Covered | Archer-Daniels-Midland Company, Terrasoul Superfoods, Navitas Organics, The Hain Celestial Group, Inc., Kerry Group plc, Glanbia PLC, Orgain, Suncore Foods Inc., Sunfood, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Superfood Powders Market Strategic Shifts & Innovations
The market is maturing from offering generalized wellness blends toward providing application-specific, scientifically validated ingredients. This evolution is driven by more sophisticated consumer expectations and stricter regulatory oversight, favoring suppliers with strong R&D capabilities and transparent supply chains.
Advanced processing technologies like freeze-drying and cold-milling preserve the delicate vitamins, enzymes, and phytonutrients in raw superfoods. Premium consumer brands and functional food formulators are rapidly adopting these methods to ensure maximum nutrient retention. This technological shift is supplanting traditional, high-heat dehydration techniques that often degrade the nutritional value and sensory profile of the final powder.
European Food Safety Authority (EFSA) regulations on health and nutrition claims are forcing manufacturers to provide robust scientific dossiers to substantiate product benefits. This regulatory tightening directly impacts product labeling and marketing, compelling companies to invest heavily in clinical research. The nutritional supplement segment is most affected, now prioritizing ingredients with pre-approved claims or strong clinical backing to mitigate compliance risks.
A distinct behavioral shift sees consumers moving away from complex, proprietary blends toward single-ingredient powders with verifiable origins. This demand for transparency is disrupting legacy brands that rely on opaque formulations, while empowering direct-to-consumer and specialty retail channels. This trend is most prominent in health-conscious markets like the United States and Germany, where ingredient provenance is a primary purchasing criterion.
Superfood Powders Market Segmentation
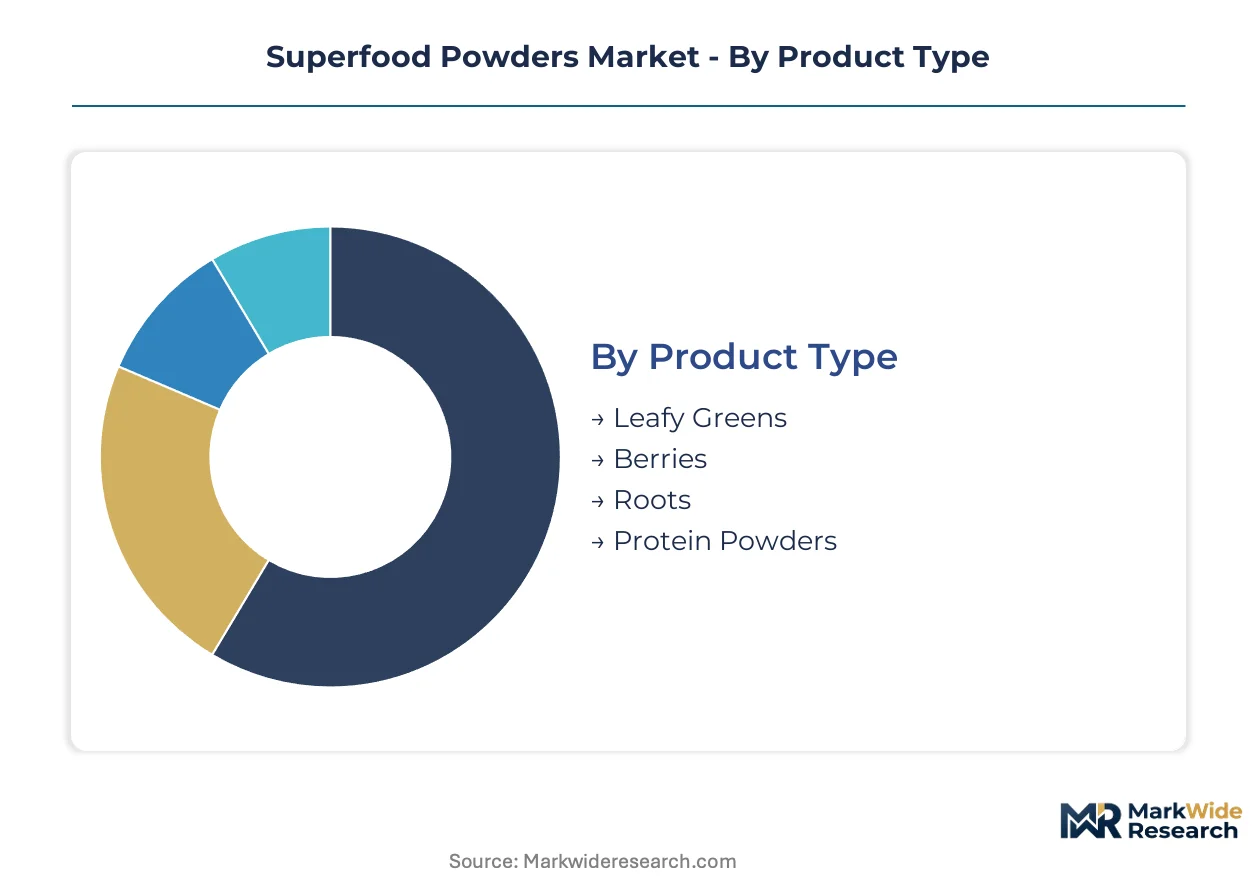
Segmentation within the Superfood Powders Market delineates the varied preferences of health-conscious consumers and the specific applications driving product development. This analysis reveals where innovation concentrates, how regulatory requirements shape product offerings, and which product types and sources garner the most consumer trust and investment.
Product Type:
Margin pools within the product type category are highest for specialized, nutrient-dense ingredients with strong scientific backing and transparent sourcing.
- Leafy Greens:These powders, such as spirulina and chlorella, offer concentrated chlorophyll, vitamins, and minerals, often associated with detoxification and digestive health benefits. Demand for leafy green powders is particularly strong in the United States and Germany, where consumers prioritize foundational wellness and preventative health.
- Berries:Powders derived from berries like acai, blueberry, and cranberry are rich in antioxidants and vitamin C, supporting immune function and cellular health. These ingredients find widespread use in smoothies and nutritional supplements, appealing to consumers seeking natural immune boosters and anti-inflammatory properties.
- Roots:This segment includes powders from ingredients such as turmeric and ginger, valued for their anti-inflammatory and digestive support properties.
- Protein Powders:Plant-based protein powders, often derived from peas, rice, or hemp, serve as alternatives to animal proteins, supporting muscle recovery and satiety.
The dominant share belongs to Berries, while Leafy Greens is closing the gap fastest.
Source:
The cost tier of superfood powders is directly influenced by the sourcing method, with certified options commanding a premium due to stringent quality control and traceability.
- Organic:Organic superfood powders adhere to strict certification standards from bodies like the USDA and the EU, ensuring products are free from synthetic pesticides and fertilizers. This source category defines the premium tier, building significant consumer trust, particularly in health-conscious markets like Germany.
- Plant-Based:This segment encompasses powders derived exclusively from plant sources, catering to vegan and vegetarian consumers seeking nutrient-dense alternatives. The plant-based trend drives significant demand for sustainable and ethical product options, especially in the US and Europe.
- Non-GMO:Non-genetically modified organism (Non-GMO) powders appeal to consumers concerned about ingredient purity and natural cultivation methods.
- Conventional:Conventional sources offer broader accessibility and a lower price point, though they may lack specific certifications found in premium tiers.
The premium segment is driven by Organic certifications, while broader accessibility relies on Conventional sourcing.
Form:
Application versatility dictates the market's form preferences, with powders providing the broadest utility across various consumer uses.
- Powder:Superfood powders represent the most common form, offering high concentration and versatility for integration into smoothies, beverages, and baked goods. Their ease of use makes them a staple for home consumption and functional food formulations.
- Capsule:Capsules provide a convenient, pre-dosed format for superfood consumption, favored by consumers seeking precise nutrient intake without altering taste or texture. This form is prevalent in the nutritional supplements sector, particularly for targeted health benefits.
- Liquid:Liquid forms are often found in ready-to-drink beverages, offering rapid absorption and convenience for on-the-go consumption.
- Extract:Extracts are highly concentrated forms of specific compounds from superfoods, primarily used in functional food formulations and nutraceuticals for targeted benefits.
The market's versatility is best captured by Powder, with Capsule offering targeted convenience.
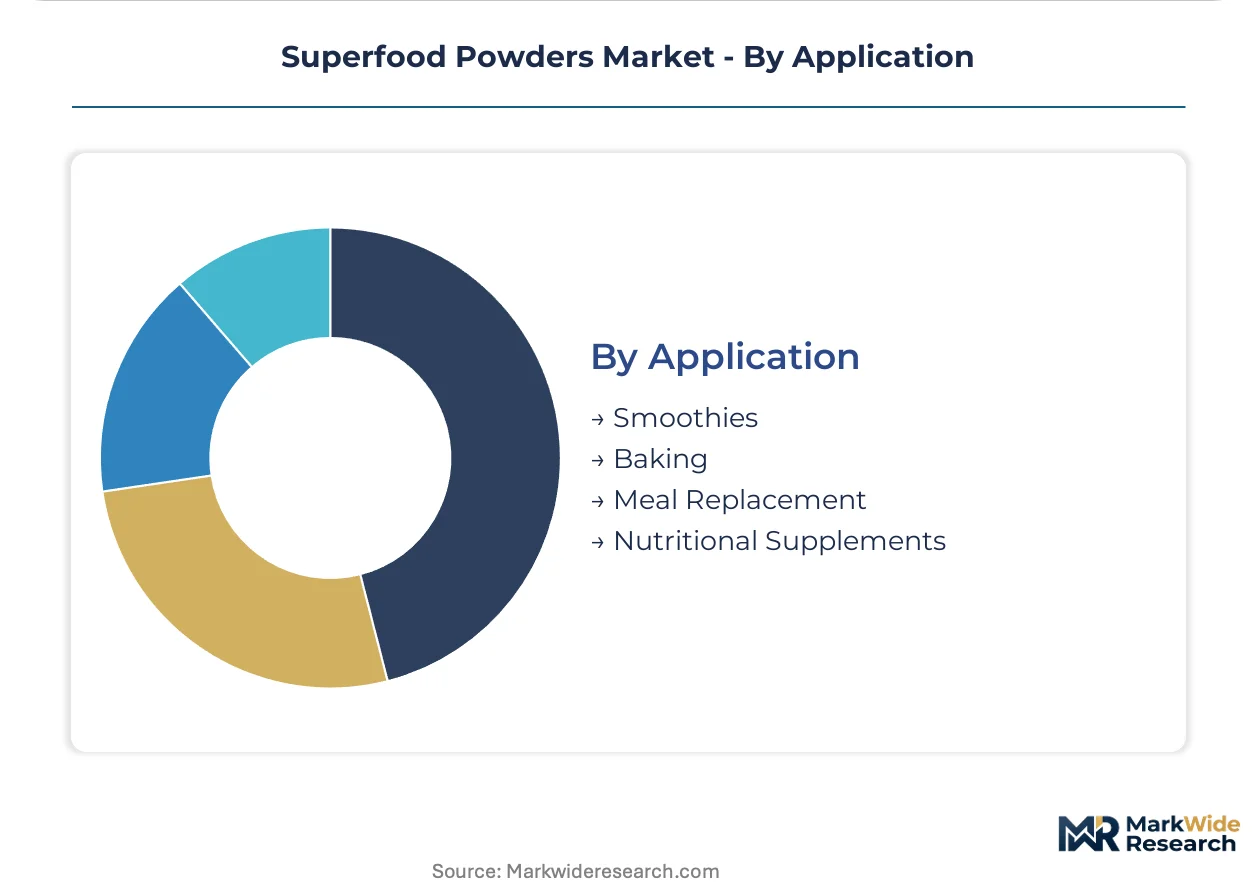
Application:
The maturity of application segments varies, with established uses like smoothies representing foundational demand and nutritional supplements offering significant growth potential due to scientific validation.
- Smoothies:Smoothies remain a primary application for superfood powders, offering an easy and palatable way for consumers to integrate nutrient-dense ingredients into their daily diets. This application is particularly popular among health-conscious individuals in the United States.
- Nutritional Supplements:Superfood powders are increasingly formulated into targeted nutritional supplements, driven by demand for evidence-based health solutions and regulatory scrutiny from bodies like the FDA and EFSA. This high-margin segment requires significant investment in clinical validation.
- Baking:Superfood powders are incorporated into baked goods for functional fortification, enhancing the nutritional profile of everyday foods.
- Meal Replacement:This application utilizes superfood powders in formulations designed to replace full meals, offering convenience and controlled nutrition for weight management or busy lifestyles.
Established applications like Smoothies continue to dominate, but Nutritional Supplements offer significant expansion opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumer price sensitivity for superfood powders varies significantly across regions. Established markets like the United States exhibit lower elasticity for premium, organic offerings due to strong health consciousness. Conversely, emerging economies often prioritize accessibility, driving demand for more conventional or value-tier products.
United States
United States consumers prioritize preventative health and transparently sourced ingredients for smoothies and home cooking. The U.S. Food and Drug Administration (FDA) rigorously scrutinizes health claims, influencing product development. California's health and wellness industry drives innovation in personalized nutrition formulations and direct-to-consumer channels.
Germany
German consumers display high demand for organic superfood powders, emphasizing foundational wellness and preventative health. The European Food Safety Authority (EFSA) enforces stringent health claim regulations, compelling clinical validation. Munich's robust organic food sector concentrates consumer trust in certified premium products.
China
China exhibits a growing wellness culture and rising disposable incomes, fueling demand for functional food integration. The State Administration for Market Regulation (SAMR) manages complex import registrations for superfood ingredients. Shanghai serves as a primary hub for multinational brands entering the Chinese market, adapting sourcing strategies.
India
India's increasing health awareness and a shift towards plant-based diets drive demand for nutrient-dense powders. The Food Safety and Standards Authority of India (FSSAI) regulates food supplements, influencing product formulations. Bengaluru's rapidly expanding nutraceutical industry integrates superfood extracts into innovative health solutions.
United Arab Emirates
Affluent consumers in the United Arab Emirates embrace Western wellness trends and premium ingredient preferences. The Ministry of Health and Prevention (MOHAP) regulates imported health products and health claims. Dubai's cosmopolitan market drives demand for high-end, organic superfood powders, often sourced internationally.
Superfood Powders Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the superfood powders market. The market exhibits a tiered structure, from large-scale ingredient processors to specialized consumer brands. Strategic archetypes include commodity ingredient suppliers, premium organic product specialists, and science-backed functional food formulators. Companies pursue portfolio diversification and geographic expansion to secure market share.
Within the large-scale ingredient processing segment, Archer-Daniels-Midland Company leverages its vast infrastructure to supply foundational materials to the industry. Navitas Organics, a consumer-facing organic product specialist, builds strong brand trust with its certified organic product lines, appealing directly to health-conscious consumers. Kerry Group plc exemplifies a functional food formulator, differentiating through its focus on nutrition science in ingredient development for various applications. These companies anchor different parts of the value chain, from raw material supply to consumer-ready products and specialized formulations. Their varied approaches reflect the market's segmentation by scale, brand focus, and scientific validation requirements, influencing product innovation across the sector.
| Leading Market Players |
|---|
| Archer-Daniels-Midland Company |
| Terrasoul Superfoods |
| Navitas Organics |
| The Hain Celestial Group, Inc. |
| Kerry Group plc |
| Glanbia PLC |
| Orgain |
| Suncore Foods Inc. |
| Sunfood |
| Others |
Cost & Logistics Intelligence
Large-scale ingredient processing, particularly for foundational superfood materials, establishes significant scale economies that shape both supply concentration and market price floors. This efficiency allows major players to offer competitive pricing for high-volume orders.
Pricing Analysis
The European Food Safety Authority (EFSA) regulations dictate the pricing tier structure for superfood powders, particularly for products with health claims. Pricing stratifies across premium, standard, and economy tiers, driven by organic certification levels and scientific backing for nutrient profiles. Pricing pressure stems from the high production costs of advanced processing methods like freeze-drying, which limits accessibility for mass-market consumers. Health-conscious consumers in the United States and Germany exhibit lower price sensitivity for certified organic offerings, while conventional buyers prioritize accessibility.
Supply Chain Analysis
Port congestion in key trade lanes from South America and Asia significantly impacts inbound logistics costs for superfood powders. Geographic supply concentrates in the Amazon basin for acai and specific Japanese prefectures for matcha, while China sources a substantial share of spirulina. The market relies on specific berry harvests and leafy green cultivation, exposing it to climate-related disruptions and geopolitical risks. Supply chain vulnerability also stems from commodity price volatility. Distribution runs through both direct-to-consumer channels for specialty brands and large-scale ingredient processors for foundational materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consumer demand for single-ingredient powders with verifiable origins fragments the buyer base, shifting power towards suppliers with transparent sourcing. This fragmentation necessitates targeted strategies to capture diverse purchasing preferences.
For Market Incumbents: Secure long-term supply agreements with certified organic growers to mitigate supply chain vulnerability. Invest heavily in clinical validation for specific health benefits, countering the threat of new entrants with scientifically backed products. Strengthen R&D into application-specific nutrient profiles, differentiating beyond generic wellness blends. Control over distribution channels through strategic partnerships can also defend market share against emerging direct-to-consumer brands. For New Entrants and Emerging Players: Underserved demand for personalized nutrition formulations creates a significant service-layer gap for new entrants. Target markets in Southeast Asia and the Middle East, where rising disposable incomes present new growth frontiers. Focus on developing nutraceutical ingredients with scientifically validated benefits for specific health needs like cognitive function or immune support. A digital-first direct-to-consumer model emphasizing transparent sourcing and clinical backing offers a compelling go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized organic product brands with strong consumer trust and direct-to-consumer channels. The market presents strong long-term viability over the next decade, driven by sustained consumer health consciousness and demand for evidence-based solutions. Target functional food formulators with robust R&D capabilities or premium organic brands with verifiable origins. The signal to watch is increased M&A activity within the nutraceutical ingredient development segment, indicating consolidation around scientific validation.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Investment | Robust scientific dossiers mitigate regulatory risks from the FDA and EFSA, building consumer trust. |
| Supply Chain Traceability Enhancement | Ensuring ingredient authenticity and potency combats adulteration, particularly for premium ingredients. |
| Geographic Market Entry | Expanding into Southeast Asia and the Middle East taps into rising disposable incomes and wellness culture. |
| Personalized Formulation Development | Targeted blends for specific health needs differentiate products beyond generic wellness offerings. |
| Nutraceutical Ingredient R&D | Leveraging superfood extracts as active ingredients opens high-margin opportunities in evidence-based solutions. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary regulatory filings anchors the qualitative findings of this study. Primary research involved discussions with nutritionists, food scientists, regulatory affairs specialists, and procurement managers at consumer packaged goods companies. Secondary data sources included USDA organic standards, European Food Safety Authority scientific opinions, China's SAMR import regulations, and company annual reports. This approach employed both bottom-up market sizing and top-down validation to ensure data integrity.
Sensitivity analysis evaluated market projections under various scenarios, informing the forecast across the analysis window. The analytical framework modeled segmentation dimensions including product type, source, form, application, and regional regulatory compliance. Compound annual growth rates were derived from historical data and projected growth drivers, accounting for technological advancements. Key industry-specific forecast inputs included consumer health consciousness trends and organic certification penetration rates in established markets.
Underlying assumptions cover stable regulatory environments and consistent consumer purchasing power, with deviation risk concentrated in climate-related disruptions and evolving import regulations. Forecasts reflect these assumptions. Outcomes outside this envelope, such as unforeseen scientific validation costs, would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
Global Probiotic Ingredients Market
Functional Food & Ingredients
Japan Soy Protein Market
Functional Food & Ingredients
Prebiotic Ingredients Market
Functional Food & Ingredients
Mediterranean Cognitive-First Ingredient Systems Market
Functional Food & Ingredients
Refined Functional Carbohydrates Market
Functional Food & Ingredients
Banana Leaf Extract Market
Functional Food & Ingredients
Europe Sterol Market
Functional Food & Ingredients
Prickly Pear Fruit Metabolic Health Ingredients Market
Functional Food & Ingredients
Global Medical Foods Market
Functional Food & Ingredients
Italy Protein Market
Functional Food & Ingredients
Essential Fatty Acids Market
Functional Food & Ingredients
Asia-Pacific Omega3 PUFA Market
Functional Food & Ingredients
Africa Algae Omega-3 Ingredients Market
Functional Food & Ingredients
Europe Botanical Extract Market
Functional Food & Ingredients
Lovage Extract Market
Functional Food & Ingredients
North America Pea Protein Ingredients Market