
 Japan Soy Protein Market | 2026-2036
Japan Soy Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Soy Protein Market Foresight
Subscription-based formulation services is realigning how ingredient suppliers engage Japanese food manufacturers. Fuji Oil Holdings extends its technical service contracts to cover custom isolate blends for meat analog producers. Cargill, Incorporated anchors its position through dedicated application labs in Yokohama. Ajinomoto Co. Inc. differentiates via fermentation-derived protein expertise integrated with soy fractionation.
Soy protein comprises refined or textured fractions of defatted soybean meal, typically containing protein concentrations from fifty percent in flour to over ninety percent in isolate forms, produced through aqueous extraction and precipitation or extrusion cooking for functional texturization. The ingredient serves primarily as a structured emulsion system, gelling agent, or nutritional fortificant across formulated foods and beverages. Isolate commands premium positioning due to superior emulsification capacity in dairy alternatives and medical nutrition. Textured soy protein sustains volume leadership within meat alternatives as Japanese foodservice chains expand plant-based menu lines. Concentrate occupies stable demand from protein enrichment applications in bakery and sports nutrition.
METI oversees industrial biomanufacturing incentives that accelerate domestic soy protein processing capacity expansion. Japan's Consumer Affairs Agency enforces Food Labeling Act standards that constrain marketing claims around protein functionality and allergen disclosure. PMDA guidelines for Foods for Specified Health Uses create a regulated pathway for clinically validated soy protein formulations. Stakeholders must track how FSSC 22000 certification requirements and evolving allergen threshold regulations reshape supplier qualification criteria for national retail distribution.
Market Dynamics
Japan's soy protein sector is restructuring around tighter Food Labeling Act enforcement and the geographic clustering of innovation capacity in Tokyo and Osaka, which concentrates both regulatory compliance burdens and technical development resources in two metropolitan zones.
Growth Catalysts
- Functional food cluster expansion:Tokyo's dense concentration of nutraceutical formulators drives isolate demand for medical nutrition and senior care applications.
- Plant-based menu mandates:Major Japanese foodservice chains are expanding dedicated plant-based lines, pulling textured soy protein into standardized procurement specifications.
- METI biomanufacturing incentives:Domestic processing capacity expansion receives direct subsidy support, reducing reliance on imported intermediate fractions.
Market Restraints
- Input cost volatility:Defatted soybean meal prices fluctuate with Brazilian and US harvest cycles, compressing margin predictability for domestic processors.
- Regulatory friction:Consumer Affairs Agency allergen threshold enforcement requires costly production line segregation and extended labeling compliance timelines.
- Technical limitation:Isolate production requires aqueous extraction infrastructure that few domestic facilities possess, creating supply concentration risk.
Strategic Opportunities
- Elderly nutrition protocols:PMDA's Foods for Specified Health Uses pathway enables clinically validated soy protein formulations targeting sarcopenia prevention.
- Fermentation-convergence:Integration of precision fermentation with traditional soy fractionation opens novel protein texture profiles for meat analog developers.
- Direct-to-manufacturer channels:Subscription-based formulation services bypass traditional distribution layers, capturing margin from technical consultation.
Industry Challenges
- Application science talent scarcity:Protein functionality expertise in extrusion and emulsion systems remains concentrated among senior technicians at legacy suppliers.
- FSSC 22000 certification timelines:National retail distribution access requires extended audit cycles that delay market entry for new processing entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Soy Protein Market |
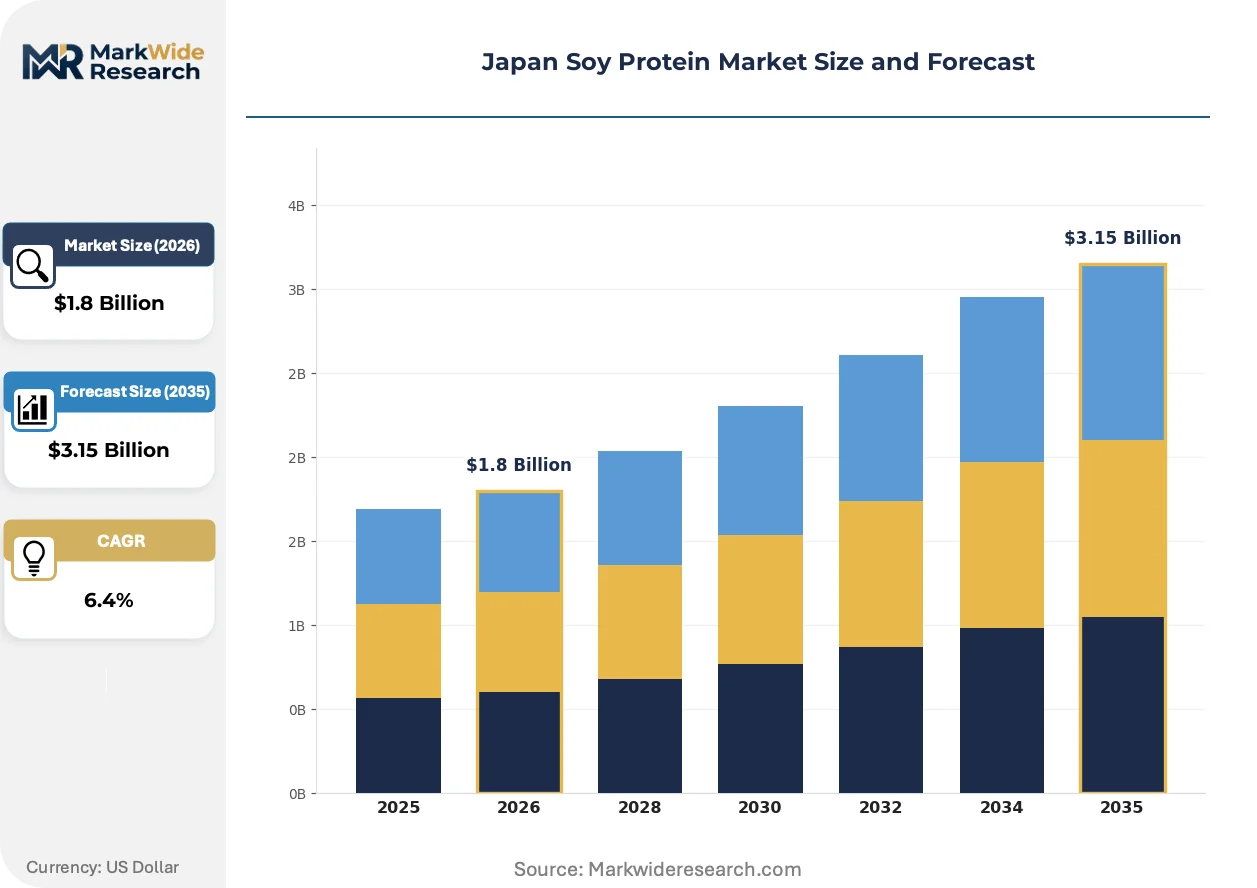
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolate, Concentrate, Textured, Flour Application: Meat Alternatives, Dairy Alternatives, Protein Enrichment, Snacks Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Foodservice End User: Households, Restaurants, Manufacturers, Fitness Centers |
| Companies Covered | Fuji Oil Holdings Inc., Archer Daniels Midland Company, Ajinomoto Co. Inc., Cargill, Incorporated, International Flavors & Fragrances Inc., Kikkoman Corporation, Marusan Co., Ltd., Megmilk Snow Brand, Lacto Japan Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Soy Protein Market Shifts & Advancements
Processing technology convergence and procurement model evolution are redrawing competitive boundaries between ingredient suppliers and finished food manufacturers in Japan's soy protein value chain.
Extrusion-based texturization is expanding into high-moisture meat analog production as equipment suppliers refine shear-cell and long-fiber extrusion systems. Japanese food manufacturers are piloting these systems at pilot-scale facilities in Kanagawa Prefecture. The technology is expanding into applications previously dominated by imported pea and wheat protein isolates, compressing the addressable market for competing plant proteins.
Consumer Affairs Agency enforcement of revised Food Labeling Act standards tightens permissible claims around protein functionality and allergen disclosure. Manufacturers must substantiate any performance claims with clinical or analytical data, raising compliance costs for smaller formulators. Medical nutrition and senior care segments are responding by consolidating supplier relationships around established players with dedicated regulatory affairs capacity.
Buyer concentration among national retail chains and major foodservice operators compresses supplier negotiation leverage and extends payment terms. Technical service contracts are displacing spot purchasing as the dominant procurement mode, locking manufacturers into multi-year formulation partnerships. This pattern is most visible in Osaka's ingredient processing hub, where mid-size suppliers compete primarily on application laboratory capability rather than commodity pricing.
Japan Soy Protein Market Segmentation
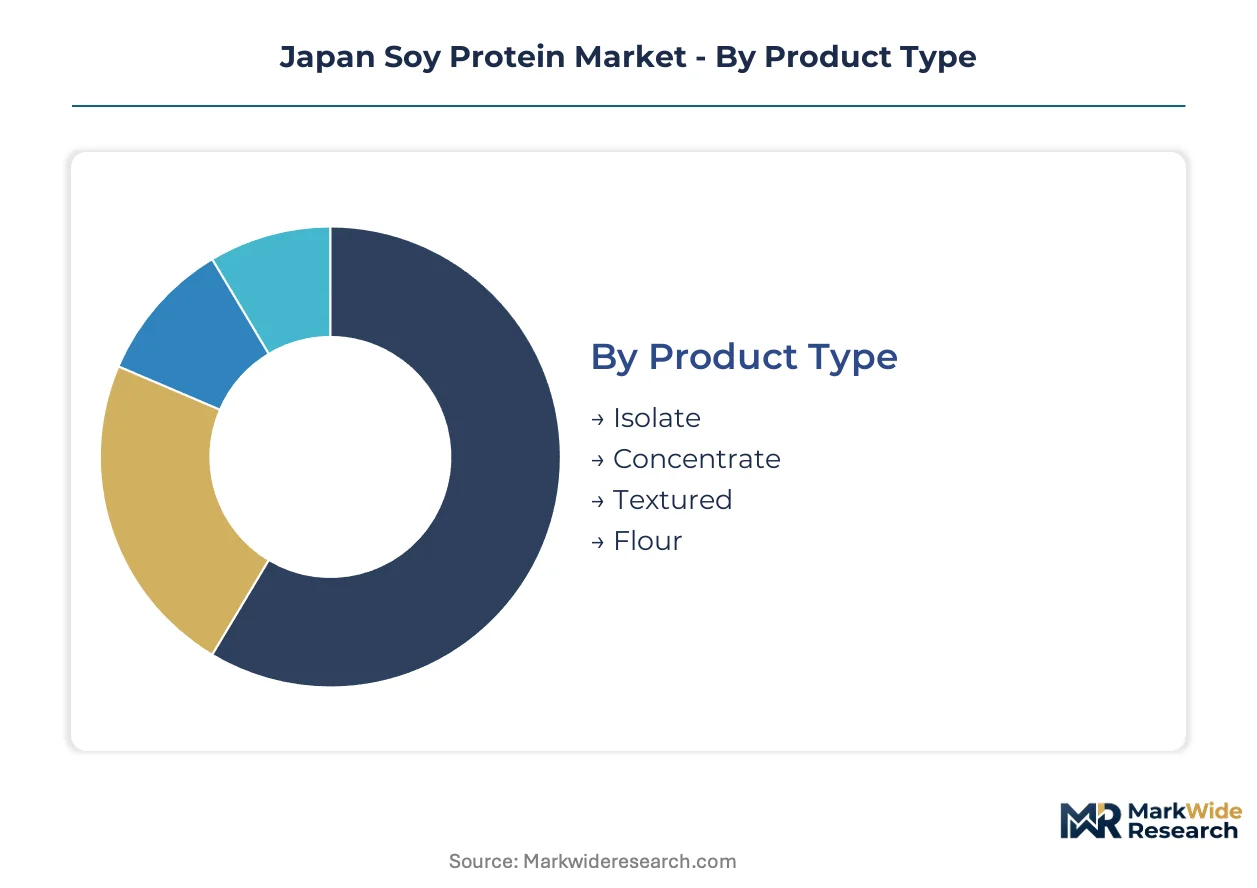
Japan's soy protein market segments around capital-intensive processing tiers and divergent regulatory pathways. Understanding these divisions reveals where technical barriers protect margins and where commoditization pressures concentrate.
Product Type:
Isolate production demands aqueous extraction infrastructure with precipitation and membrane filtration systems, requiring the heaviest capital deployment among all soy protein categories.
- Isolate:Refined protein fractions exceeding ninety percent purity, produced through isoelectric precipitation and ultrafiltration. Tokyo's functional food cluster drives demand for medical nutrition and senior care applications, though METI biomanufacturing incentives are expanding domestic capacity beyond legacy import dependence.
- Textured:Extruded defatted soy flour or concentrate processed through thermomechanical texturization to create fibrous meat-like structures. Osaka's ingredient processing hub concentrates supply for Japanese foodservice chains expanding plant-based menu mandates, with high-moisture extrusion systems absorbing the majority of recent equipment investment.
- Concentrate:Intermediate protein content between flour and isolate, typically sixty-five to ninety percent, produced through aqueous alcohol washing. Sports nutrition and bakery enrichment applications in Kanagawa Prefecture sustain steady procurement volumes.
- Flour:Ground defatted soybean meal with protein content near fifty percent, serving as the foundational input for downstream fractionation. Lowest processing intensity positions this segment as the entry point for new domestic processing entrants seeking FSSC 22000 certification.
Textured soy protein absorbs the bulk of installed capacity; isolate is expanding most quickly as medical nutrition protocols deepen.
Application:
End-use segmentation reflects divergent customer procurement patterns, with food manufacturers demanding technical service integration while retail channels prioritize label compliance.
- Meat Alternatives:Structured soy protein systems replacing or extending animal muscle tissue in processed foods and foodservice offerings. Major Japanese restaurant chains are standardizing textured soy protein specifications, pulling suppliers into multi-year formulation partnerships with dedicated application laboratory support.
- Protein Enrichment:Fortification of conventional foods with concentrated or isolated fractions to achieve nutritional claims. Consumer Affairs Agency enforcement of revised Food Labeling Act standards is consolidating demand around suppliers with established regulatory affairs capacity.
- Dairy Alternatives:Emulsion systems and nutritional fortification for plant-based milk, yogurt, and frozen dessert applications. Superior emulsification capacity of soy isolate supports premium positioning in this segment.
- Snacks:Extruded and baked products incorporating soy flour or concentrate for texture and protein content. Health food stores and online retail channels drive fragmented demand with shorter procurement cycles.
Meat alternatives command the largest revenue pool; protein enrichment is climbing the fastest as clinical validation requirements reshape supplier relationships.
Distribution Channel:
Channel structure determines working capital intensity and technical service depth, with direct manufacturer relationships requiring the most specialized sales infrastructure.
- Foodservice:Direct supply to restaurant chains, institutional catering, and prepared food manufacturers with customized formulation support. National procurement consolidation is extending payment terms and locking suppliers into subscription-based technical service contracts.
- Supermarkets:Mass retail distribution requiring FSSC 22000 certification and extended audit timelines that delay market entry for new processing entrants.
- Health Food Stores:Specialty retail with concentrated demand in Tokyo's functional food cluster, where consumer education around protein functionality drives premium pricing tolerance.
- Online Retail:Direct-to-consumer and small business channels with lower certification barriers but compressed margins and fragmented order patterns.
Foodservice channels absorb the dominant share of technical service investment; online retail is gaining share fastest among emerging plant-based brands.
End User:
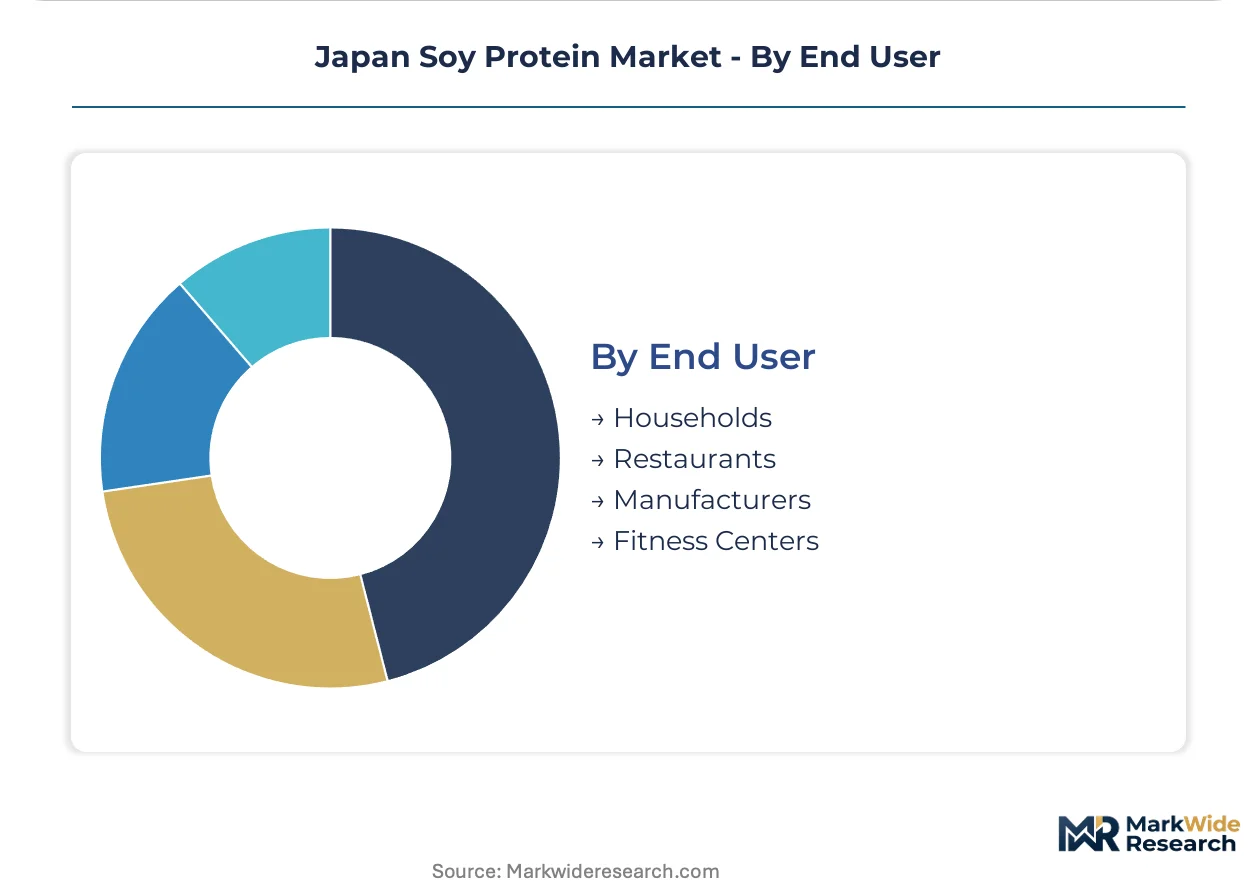
User segmentation maps to distinct protein functionality requirements and procurement sophistication levels across Japan's metropolitan innovation zones.
- Manufacturers:Food and beverage formulators requiring custom isolate blends and application-specific technical consultation. Osaka's ingredient processing hub concentrates this demand, with mid-size suppliers competing primarily on laboratory capability rather than commodity pricing.
- Restaurants:Foodservice operators expanding dedicated plant-based lines with standardized procurement specifications and volume commitments.
- Fitness Centers:Sports nutrition distribution points with concentrated demand for protein enrichment products in urban markets.
- Households:Individual consumers purchasing through retail channels with sensitivity to allergen labeling and price positioning.
Manufacturers represent the most deeply penetrated end user category; restaurants are expanding most quickly as plant-based menu mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's soy protein production capacity concentrates in Kanto and Kansai while consumption spreads across metropolitan foodservice clusters. Domestic processing expansion under METI incentives is narrowing the import dependency gap. Regional specialization is deepening as Tokyo drives medical nutrition demand and Osaka anchors meat analog manufacturing.
Kanto/Tokyo
Tokyo's functional food cluster generates premium isolate demand for senior care and clinical nutrition applications. METI biomanufacturing subsidies support fermentation-integrated processing facilities in Kanagawa Prefecture. Yokohama hosts dedicated application laboratories serving dairy alternative formulators with custom emulsion systems.
Kansai/Osaka
Osaka's ingredient processing hub concentrates textured soy protein supply for national foodservice chains. Consumer Affairs Agency enforcement of revised Food Labeling Act standards is consolidating supplier relationships around established regulatory affairs capacity. High-moisture extrusion systems absorb the majority of recent equipment investment in the prefecture.
Chubu/Nagoya
Nagoya's manufacturing base sustains steady concentrate demand for sports nutrition and bakery enrichment applications. Central Japan's logistics infrastructure enables efficient distribution to protein fortification formulators. Regional processors compete on FSSC 22000 certification timelines to access national retail channels.
Kyushu
Kyushu's emerging food technology corridor attracts pilot-scale fermentation facilities integrating traditional soy fractionation. Prefectural industrial incentives target precision protein texture development for meat analog applications. Fukuoka's startup ecosystem is incubating novel ingredient companies bypassing traditional distribution layers.
Hokkaido
Hokkaido's agricultural base supplies non-GMO soybean feedstock to domestic fractionation plants. Regional dairy alternative manufacturers source local isolate for premium positioning. Sapporo's food science institutes collaborate with processors on allergen threshold compliance protocols.
Japan Soy Protein Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Japan's soy protein value chain. The market structures around three tiers: integrated oilseed processors with captive crushing capacity, specialized ingredient formulators with dedicated application laboratories, and regional distributors with technical service contracts. Strategic moves concentrate on fermentation-convergence partnerships and subscription-based formulation service expansion. Capacity expansion in high-moisture extrusion is absorbing the majority of domestic capital deployment.
Among integrated oilseed processors, Fuji Oil Holdings Inc. and Archer Daniels Midland Company occupy positions spanning crushing through isolate production. Cargill, Incorporated anchors the technical service tier with dedicated application infrastructure in Yokohama. Ajinomoto Co. Inc. exemplifies the fermentation-convergence archetype, integrating precision biomanufacturing with traditional soy fractionation. These three patterns represent how competitive positioning is stratifying across capital intensity and technical specialization vectors.
| Leading Market Players |
|---|
| Fuji Oil Holdings Inc. |
| Archer Daniels Midland Company |
| Ajinomoto Co. Inc. |
| Cargill, Incorporated |
| International Flavors & Fragrances Inc. |
| Kikkoman Corporation |
| Marusan Co., Ltd. |
| Megmilk Snow Brand |
| Lacto Japan Co., Ltd. |
| Others |
Supply & Pricing Matrix
High-moisture extrusion technology adoption across Osaka's ingredient processing hub simultaneously compresses unit production costs and concentrates supply among capital-equipped processors, reshaping how textured soy protein reaches Japanese foodservice chains.
Pricing Analysis
Margin tightening in isolate tiers reflects aqueous extraction infrastructure scarcity that limits domestic supply elasticity. Three-tier pricing structure across premium medical-nutrition, standard food-manufacturing, and economy bakery-enrichment levels stratifies around FSSC 22000 certification status and application laboratory depth. Pricing pressure accelerates in textured segments as national foodservice procurement consolidation extends payment terms. Household consumers through online retail channels exhibit highest price sensitivity; medical nutrition formulators in Tokyo's functional food cluster demonstrate lowest sensitivity due to clinical validation requirements.
Supply Chain Analysis
Application science talent scarcity in Kanagawa Prefecture and Osaka constrains domestic high-moisture extrusion capacity expansion. Supply concentrates in Japan, Brazil, and the United States, with defatted soybean meal feedstock drawing from Brazilian and North American harvest cycles. Raw material dependencies include non-GMO soybean feedstock, membrane filtration systems, and precision fermentation inputs. Single-source vulnerability around aqueous extraction equipment creates bottleneck risk. Distribution runs through direct-to-manufacturer technical service contracts that displace traditional spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's soy protein sector is consolidating around regulatory compliance capacity and application laboratory infrastructure, with Consumer Affairs Agency enforcement of revised Food Labeling Act standards forcing smaller formulators toward acquisition or exit.
For Market Incumbents: Deepen fermentation-convergence capabilities by integrating precision biomanufacturing with traditional soy fractionation to defend against emerging precision-fermentation entrants. Expand captive aqueous extraction capacity in Kanagawa Prefecture under METI biomanufacturing incentives to reduce import dependency for isolate production. Lock national foodservice chains into extended technical service contracts that embed switching costs. For New Entrants and Emerging Players: PMDA's Foods for Specified Health Uses pathway in Japan opens a window for clinically validated sarcopenia-prevention formulations targeting Tokyo's senior care institutions. White-space exists in direct-to-manufacturer subscription services bypassing Osaka's traditional distribution layers. Kyushu's emerging food technology corridor offers lowest regulatory compliance overhead for pilot-scale fermentation facilities. Target online retail channels for emerging plant-based brands with allergen-transparent labeling. For Investors and Strategic Acquirers: Re-rating potential sits with fermentation-integrated ingredient formulators given METI subsidy acceleration and medical nutrition protocol expansion. Long-term viability favors processors with captive crushing capacity and dedicated application laboratories over commodity distributors. Acquisition target archetype: mid-cap suppliers with FSSC 22000 certification and established regulatory affairs capacity. Watch PMDA approval velocity for Foods for Specified Health Uses as inflection indicator for clinical-validation premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| High-Moisture Extrusion Capacity Expansion | Osaka's equipment investments absorb majority of domestic capital deployment for meat analog supply. |
| Fermentation-Convergence Partnership | Ajinomoto's precision biomanufacturing integration opens novel protein texture profiles for developers. |
| Subscription-Based Formulation Service | Fuji Oil's technical contract extension captures margin from custom isolate blend consultation. |
| FSSC 22000 Certification Investment | Cargill's Yokohama application lab infrastructure enables national retail distribution access. |
| Backward Integration into Crushing | Domestic oilseed processing reduces Brazilian and US harvest cycle price volatility exposure. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study. Primary interviews with soy protein plant managers, procurement leads at Japanese food manufacturers, distribution channel partners, and technical R&D directors at ingredient suppliers combined with METI biomanufacturing incentive disclosures, Consumer Affairs Agency enforcement bulletins, and PMDA Foods for Specified Health Uses registration databases. Bottom-up capacity modeling and top-down demand estimation triangulated volume and value outputs.
Granularity-level modeling tracked isolate, textured, concentrate, and flour product types across meat alternatives, protein enrichment, dairy alternatives, and snack applications. End-use segmentation captured manufacturers, restaurants, fitness centers, and households with regional splits across Kanto, Kansai, Chubu, Kyushu, and Hokkaido. CAGRs derived from historical trajectory analysis and forward-looking capacity deployment schedules. Forecast inputs incorporated high-moisture extrusion adoption curves and PMDA clinical validation pipeline velocity.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation integration would alter the outlook. Forecasts reflect assumptions around METI subsidy continuity, Consumer Affairs Agency enforcement intensity, and Brazilian soybean harvest stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
Superfood Powders Market
Functional Food & Ingredients
Africa Omega-3 PUFA Market
Functional Food & Ingredients
Refined Functional Carbohydrates Market
Functional Food & Ingredients
Prickly Pear Fruit Metabolic Health Ingredients Market
Functional Food & Ingredients
Europe Omega-3 PUFA Market
Functional Food & Ingredients
Low-Carb Low-Fat Meal Market
Functional Food & Ingredients
Functional Food Ingredients Market
Functional Food & Ingredients
Functional Non-Meat Ingredients Market
Functional Food & Ingredients
Mediterranean Pre-Diabetes Ingredient Concepts Market
Functional Food & Ingredients
Brominated Vegetable Oil Market
Functional Food & Ingredients
North America Pea Protein Ingredients Market
Functional Food & Ingredients
Global Medical Foods Market
Functional Food & Ingredients
Beta Glucan and Fucoidan Market
Functional Food & Ingredients
Prebiotic Ingredients Market
Functional Food & Ingredients
Healthy Fats Low Carb Market
Functional Food & Ingredients
Sacha Inchi Protein Market