
 Global White Inorganic Pigments Market | 2026-2036
Global White Inorganic Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Global White Inorganic Pigments Market Foresight
Aftermarket service revenue from technical pigment consulting and custom dispersion formulation is narrowing as raw material suppliers consolidate value-added capabilities in-house. BASF SE leverages its integrated pigment and additives portfolio to capture formulation-level margins. Tronox Holdings plc anchors its position through captive titanium feedstock mines in Western Australia and South Africa. KRONOS Worldwide Inc. differentiates via chloride-process capacity that yields higher-purity grades for specialty coatings.
Global white inorganic pigments encompass synthetic mineral compounds—principally titanium dioxide (TiO₂, refractive index 2.7), zinc oxide, and lithopone—engineered to scatter visible light and deliver opacity, brightness, and UV stability across substrates. These materials function as indispensable opacifiers in coatings, plastics, and paper where substrate hiding power and durability determine product performance. Titanium dioxide dominates product type value pools due to its unmatched refractive efficiency, though zinc oxide gains traction in personal care and electronics applications seeking lower photocatalytic activity. Powder form leads volume shipments for coatings and building materials, while dispersion formats command premium positioning in automotive OEM and electronics segments where millbase consistency reduces downstream processing costs.
The EPA enforces TSCA Section 5 premanufacture notification for novel nano-scale pigment variants, while REACH in Europe mandates registration and hazard classification for titanium dioxide under its carcinogen category 2 listing. China's MEE implements emission standards for sulfate-process TiO₂ production that favor chloride-technology upgrades and cleaner manufacturing investments. Stakeholders must monitor regulatory divergence between jurisdictions as classification inconsistencies threaten cross-border formulation standardization and inventory pooling strategies.
Market Dynamics
Chloride-process titanium dioxide capacity is consolidating among feedstock-integrated producers while REACH classification of TiO₂ as a category 2 carcinogen forces reformulation investments across European coatings supply chains.
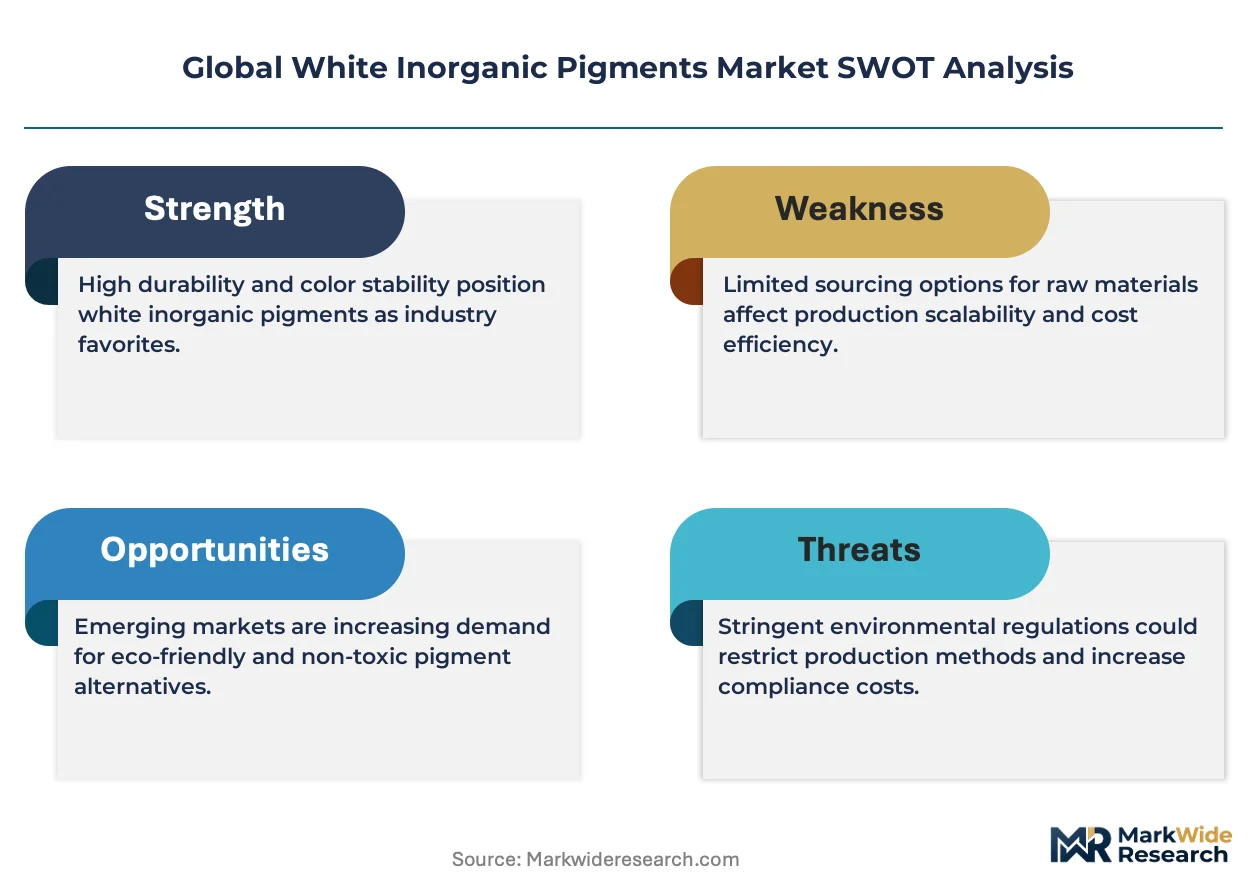
Growth Catalysts
- Automotive OEM coatings procurement:Electric vehicle manufacturers in Germany and China are expanding high-purity TiO₂ volumes for premium exterior finishes requiring enhanced UV durability and color stability.
- REACH-driven substitution:The European Chemicals Agency's hazard classification is accelerating zinc oxide adoption in personal care formulations seeking lower photocatalytic activity alternatives.
- Sulfate-process displacement:China's Ministry of Ecology and Environment emission standards are forcing domestic producers toward chloride-technology upgrades, tightening global supply of lower-carbon pigment grades.
Market Restraints
- Ilmenite and rutile feedstock concentration:Captive titanium ore supplies in Western Australia and South Africa limit independent processor access to cost-competitive raw material streams.
- Chloride-process capex intensity:Chloride technology requires substantially higher capital deployment than sulfate routes, constraining new entrant participation in premium-grade production.
- Nano-scale pigment regulatory friction:EPA TSCA Section 5 premanufacture notification requirements create timeline uncertainty for novel particle-size variants targeting electronics applications.
Strategic Opportunities
- India specialty coatings penetration:BIS certification requirements and domestic manufacturing incentives under the PLI scheme are attracting chloride-process investment for automotive and industrial finishes.
- UV-curable ink dispersion formats:Premixed millbase supply to narrow-web printing operations in Japan and South Korea reduces downstream processing costs and captures formulation-level margins.
- EU Green Deal circularity mandates:Packaging sector requirements for recyclable coatings are driving demand for lithopone and zinc oxide blends compatible with mechanical recycling streams.
Industry Challenges
- Chloride-process engineering talent scarcity:Specialized reactor design and chlorine handling expertise concentrates among retiring cohorts at established producers, constraining technology transfer.
- Cross-jurisdiction inventory pooling complexity:Divergent hazard classifications between REACH, EPA, and China's GB standards fragment formulation standardization and complicate global supply chain optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global White Inorganic Pigments Market |
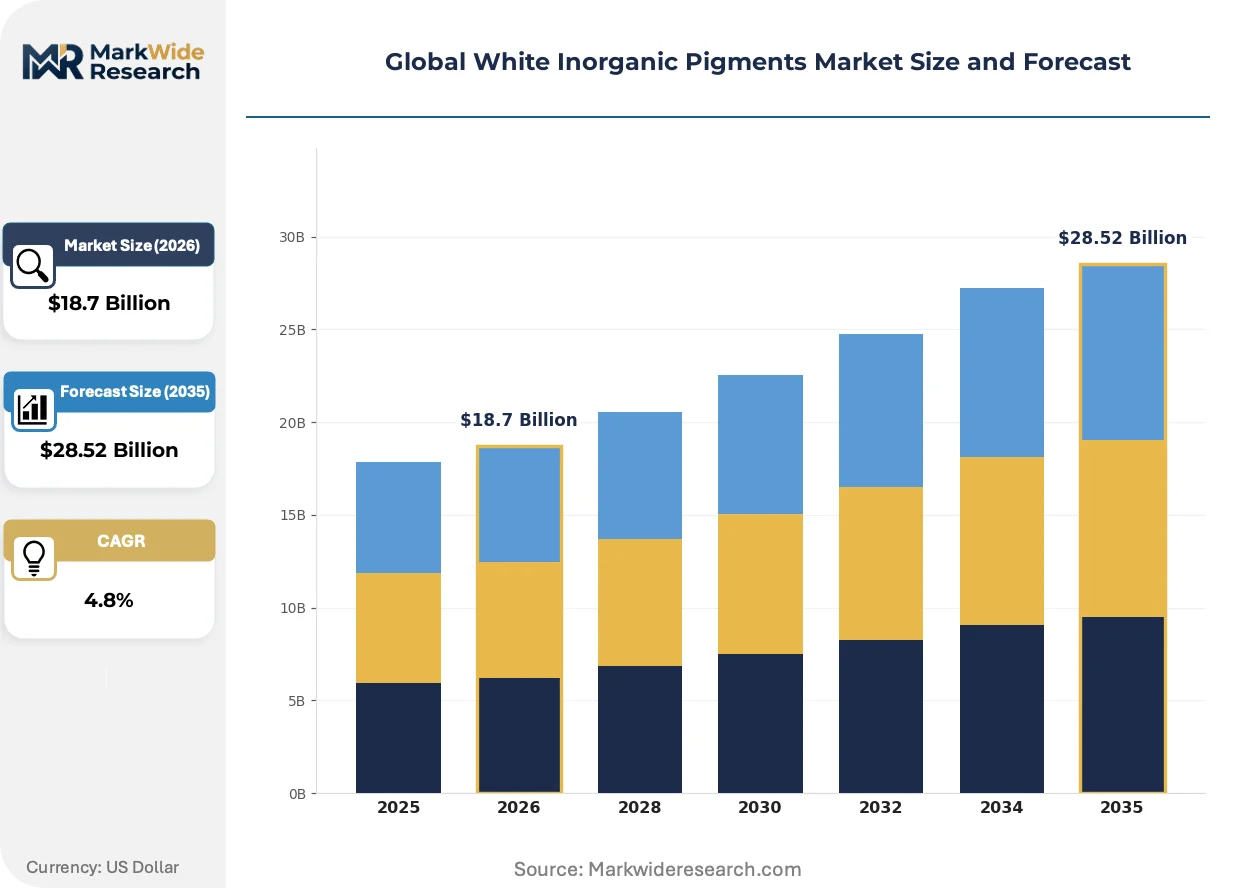
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Titanium Dioxide, Zinc Oxide, Antimony Oxide, Barium Sulfate, Lithopone Form: Powder, Slurry, Paste, Granules, Dispersion Application: Coatings, Plastics, Paper, Building Materials, Textiles End User Industry: Packaging, Consumer Goods, Construction, Electronics, Personal Care |
| Companies Covered | The Chemours Company, BASF SE, Tronox Holdings plc, KRONOS Worldwide Inc., LANXESS AG, Venator Materials PLC, Clariant International AG, Altana AG, Ferro Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global White Inorganic Pigments Market Shifts & Advancements
Surface-treated TiO₂ architectures and dispersion delivery formats are compressing traditional technical service margins while regulatory hazard reclassifications force rapid reformulation cycles across coatings value chains.
Core-shell pigment engineering is hybridizing rutile TiO₂ with alumina and silica surface layers to suppress photocatalytic activity. Personal care and food packaging formulators in Switzerland and the United States are adopting these grades at accelerating rates. The technology is hybridizing supplier value capture away from standalone dispersion services toward integrated particle design.
REACH's carcinogen category 2 listing for titanium dioxide powder forms is compelling downstream notification and labeling investments. Coatings manufacturers serving European architectural and industrial markets are reformulating toward encapsulated or liquid dispersion formats to maintain shelf placement. Specialty coatings segments with premium pricing tolerance are absorbing compliance costs fastest while commodity producers delay transitions.
Automotive OEM procurement teams are consolidating millbase supply contracts to reduce qualification overhead. Tier-1 coatings suppliers in Germany and Japan are displacing multi-source pigment purchasing with single-supplier dispersion partnerships. This consolidation is most visible in metallic and pearl effect finishes where color consistency requirements compress supplier switching flexibility.
Global White Inorganic Pigments Market Segmentation
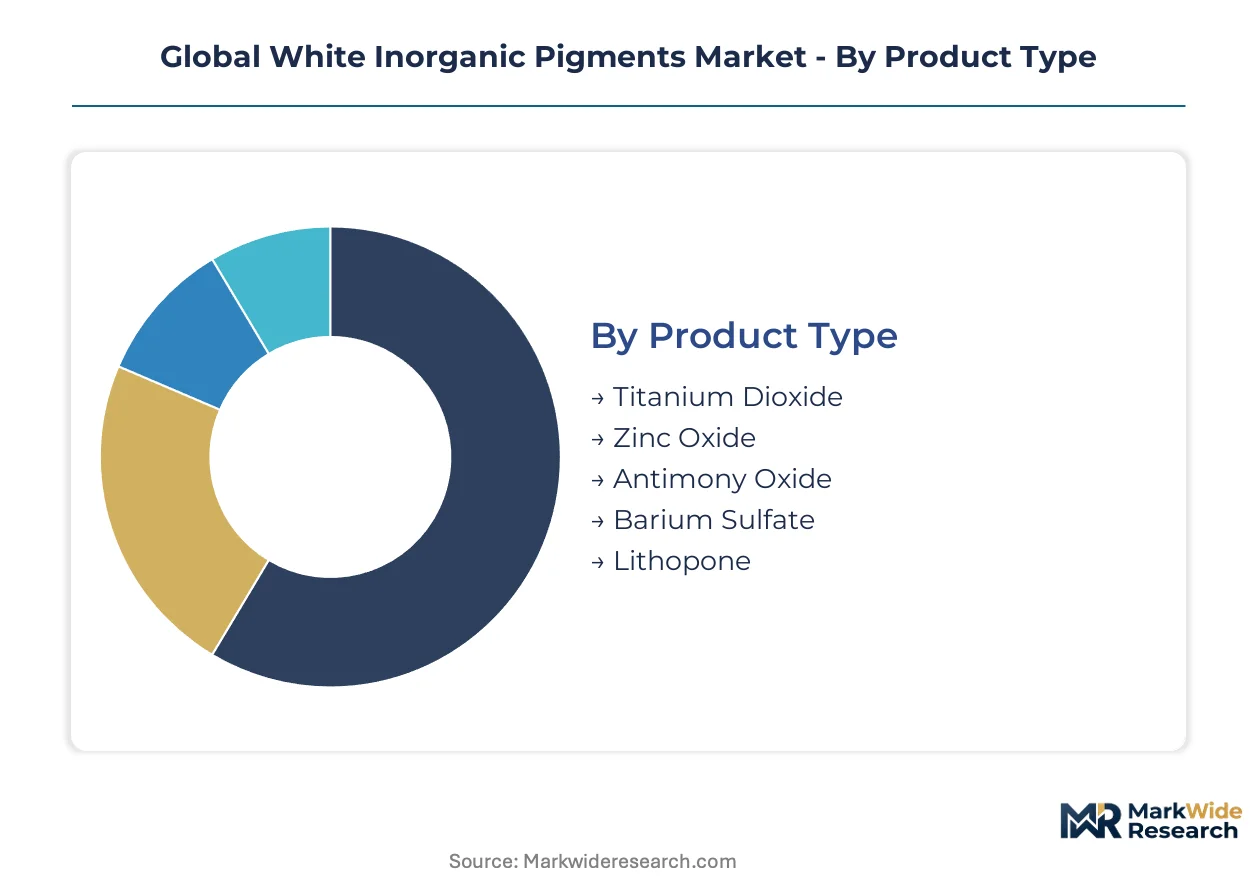
Segmentation in white inorganic pigments reveals divergent margin structures and inventory velocities. Titanium dioxide commands extended contract cycles in automotive coatings, while zinc oxide turns faster in personal care procurement. Understanding these rhythm differences separates working capital efficiency from capital trap.
Product Type:
Cycle times stretch from multi-year TiO₂ supply agreements to spot-market zinc oxide trades. Titanium dioxide locks in twelve-to-eighteen-month procurement horizons, while zinc oxide and specialty oxides clear inventory in quarterly windows.
- Titanium Dioxide:Synthetic rutile and anatase crystal structures deliver refractive index 2.7 for maximum opacity efficiency. German automotive OEMs and Chinese architectural coatings manufacturers anchor demand for chloride-process grades with sub-50ppm heavy metal specifications.
- Zinc Oxide:Lower refractive index (2.0) trades scattering efficiency for reduced photocatalytic activity and antimicrobial surface properties. Swiss and US personal care formulators are accelerating procurement as REACH category 2 classification drives substitution away from TiO₂ powder in cosmetic applications.
- Antimony Oxide:Synergist flame-retardant applications in electronics housings and cable insulation, particularly in South Korean and Taiwanese manufacturing clusters serving consumer electronics brands.
- Barium Sulfate:Extender pigment for cost reduction in industrial primers and powder coatings, with Chinese sulfate-process TiO₂ producers integrating downstream into composite grades.
- Lithopone:Zinc sulfide-barium sulfate coprecipitate for interior architectural paints and paper coatings where lower durability requirements permit cost-optimized formulations.
Titanium Dioxide dominates installed base. Zinc Oxide is where expansion concentrates.
Form:
Cost tier separation runs widest in this dimension. Dispersion formats capture formulation-level margins at three-to-five times powder unit economics, while commodity powder shipments absorb logistics and handling cost pressure.
- Dispersion:Pre-milled pigment concentrates in solvent or water-based carrier systems eliminate downstream milling capital and qualification overhead. Japanese and German automotive OEM coatings suppliers are consolidating single-source dispersion partnerships for metallic and pearl effect finishes.
- Powder:Dry pigment requiring downstream dispersion equipment and technical expertise. Chinese architectural coatings manufacturers and Indian industrial paint producers absorb the processing burden to preserve input cost flexibility.
- Slurry:Aqueous suspensions for paper and paperboard wet-end applications, favored by Scandinavian and North American pulp mills for direct injection without dust handling.
- Paste:High-solids concentrates for UV-curable ink narrow-web printing in South Korean and Japanese packaging operations.
- Granules:Dust-suppressed forms for automated handling in large-volume plastics compounding, particularly German and US automotive interior trim manufacturing.
Powder dominates installed base. Dispersion is where expansion concentrates.
Application:
Volume concentration versus margin extraction splits this category. Coatings and plastics absorb seventy-plus percent of pigment tonnage, while textiles and selected building materials command premium positioning through specification lock-in.
- Coatings:Architectural, automotive OEM, automotive refinish, industrial, and marine formulations requiring weathering resistance and color consistency. German premium automotive manufacturers specify chloride-process TiO₂ with alumina-silica surface treatment for exterior durability exceeding ten years.
- Plastics:Masterbatch and direct compounding applications in polyolefins, PVC, and engineering polymers. Chinese appliance and electronics housing manufacturers are expanding procurement of surface-treated grades for UV stability in outdoor applications.
- Paper:Wet-end filler and coating layer opacification for printing and packaging grades. North American and European publication paper producers face secular decline while Asian packaging paper demand climbs.
- Building Materials:Concrete coloration, stucco, and exterior insulation finish systems where TiO₂ loading affects both aesthetics and surface temperature management.
- Textiles:Synthetic fiber delustering and printing paste applications, concentrated in South Korean and Taiwanese technical textile manufacturing.
Coatings dominates installed base. Plastics is where expansion concentrates.
End User Industry:
Customer type maturity separates this category. Construction and packaging operate on cyclical capital expenditure rhythms, while electronics and personal care demand continuous innovation cycles with shorter product lifespans.
- Packaging:Food contact, beverage, and consumer goods containers requiring migration-compliant pigment grades. EU Green Deal circularity mandates are driving recyclable coatings demand compatible with mechanical recycling streams.
- Personal Care:Sunscreen, cosmetics, and pharmaceutical applications demanding photocatalytic suppression and dermatological safety certification. US FDA and Swissmedic oversight concentrates on nano-scale particle registration.
- Construction:Architectural coatings and building materials tied to residential and commercial construction cycles. Chinese property sector volatility and Indian infrastructure investment create divergent regional demand patterns.
- Electronics:Device housings, displays, and printed circuit board substrates requiring precision color matching and electromagnetic compatibility. South Korean and Japanese consumer electronics brands specify tightly controlled particle size distributions.
- Consumer Goods:Appliances, furniture, and durable goods coatings where cost-positioning determines pigment grade selection.
Construction dominates installed base. Personal Care is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Southeast Asia exhibit acute price sensitivity to sulfate-process titanium dioxide, while German automotive OEMs absorb chloride-grade premiums for color consistency. This demand-elasticity divide shapes procurement patterns across regions.
Germany
Premium automotive exterior coatings drive chloride-process TiO₂ consumption for ten-year durability specifications. ECHA's REACH category 2 carcinogen classification forces reformulation investments across coatings supply chains. The Ruhr industrial corridor hosts BASF SE's integrated pigment and additives operations serving OEMs.
China
Domestic sulfate-process capacity expansion displaces import dependency in architectural coatings. MEE emission standards tighten purity thresholds and favor chloride-technology upgrades among producers. The Yangtze River Delta concentrates TiO₂ manufacturing clusters serving construction and plastics compounding.
United States
EPA TSCA Section 5 oversight creates timeline friction for nano-scale pigment variants targeting electronics. Personal care formulators accelerate zinc oxide procurement amid dermatological safety certification requirements. The Gulf Coast petrochemical corridor anchors dispersion format production for automotive OEM supply.
India
BIS certification requirements and PLI scheme incentives attract chloride-process investment for automotive finishes. Domestic industrial paint producers absorb powder-form processing burdens to preserve input cost flexibility. Gujarat's chemical manufacturing belt expands specialty coatings pigment blending capacity.
Japan
Automotive OEM coatings suppliers consolidate single-source dispersion partnerships for metallic and pearl effect finishes. METI standards govern precision particle size distributions for consumer electronics applications. The Nagoya industrial region concentrates millbase supply contracts reducing qualification overhead.
Global White Inorganic Pigments Market Competitive Landscape
Capability concentration sits with feedstock-integrated producers holding captive titanium ore supplies; scale advantage sits with diversified chemical conglomerates spanning pigment and additive portfolios. The market structure tiers between chloride-process specialists with Western Australian and South African mine access, and sulfate-process operators serving cost-sensitive architectural segments. Three archetypes dominate: integrated miners with captive feedstock, diversified chemical majors with formulation-level capabilities, and regional specialists in dispersion formats. Competitive moves center on backward integration into titanium ore and portfolio diversification into surface-treated architectures.
Within the integrated-mining tier, Tronox Holdings plc and The Chemours Company represent feedstock-anchored positioning. Among diversified chemical majors, BASF SE exemplifies formulation-level margin capture through integrated pigment and additives portfolios. KRONOS Worldwide Inc. occupies a position in the chloride-process specialist archetype.
| Leading Market Players |
|---|
| The Chemours Company |
| BASF SE |
| Tronox Holdings plc |
| KRONOS Worldwide Inc. |
| LANXESS AG |
| Venator Materials PLC |
| Clariant International AG |
| Altana AG |
| Ferro Corporation |
| Others |
Supply & Pricing Matrix
Feedstock concentration in Western Australian and South African titanium ore deposits compresses margin flexibility for non-integrated processors while simultaneously widening pricing spreads between chloride-process premiums and sulfate-process commodity tiers. ECHA's REACH category 2 carcinogen classification on TiO₂ powder adds regulatory compliance costs that concentrate in European architectural coatings procurement, forcing buyers toward dispersion formats that absorb formulation-level premiums.
Pricing Analysis
Aftermarket service revenue from technical pigment consulting and custom dispersion formulation narrows as raw material suppliers consolidate value-added capabilities in-house. Three-tier pricing structure across premium, standard, and economy levels separates chloride-process automotive grades from sulfate-process architectural powders and extender-blended economy tiers. Price differentiation hinges on heavy metal certification thresholds and captive feedstock access. Pricing pressure stems from Chinese domestic sulfate-process capacity expansion displacing import volumes. Indian industrial paint producers exhibit highest price sensitivity, absorbing powder-form processing burdens to preserve input cost flexibility, while German automotive OEMs absorb chloride-grade premiums for ten-year durability specifications.
Supply Chain Analysis
Extended payment terms from Chinese sulfate-process producers to Southeast Asian distributors compress working capital cycles for independent traders. Geographic supply concentration centers on China for sulfate-process TiO₂, Australia and South Africa for chloride-process feedstock integration, and Germany for specialty dispersion formats. Raw material dependencies rest on ilmenite and rutile titanium ores, chlorine gas for chloride-route reactors, and sulfuric acid for sulfate-process digestion. Single-source vulnerability concentrates among non-integrated processors lacking captive mine access. Distribution runs through direct millbase partnerships with automotive OEM coatings suppliers in Germany and Japan, bulk powder shipments to Chinese architectural manufacturers, and regional blending operations in India and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized reactor design and chlorine handling expertise concentrates among retiring cohorts at established producers, constraining technology transfer and creating asymmetric capability gaps between integrated miners and independent processors.
For Market Incumbents: Harden feedstock security through upstream control over Western Australian or South African titanium ore deposits, eliminating single-source vulnerability to ilmenite price volatility. Expand chloride-process capacity in India under BIS certification and PLI scheme incentives to capture automotive finishes demand before regional competitors qualify. Defend formulation-level margins by integrating surface-treated TiO₂ architectures that suppress photocatalytic activity, displacing standalone dispersion service providers. For New Entrants and Emerging Players: India's specialty coatings penetration under domestic manufacturing incentives offers the most penetrable geographic entry point for chloride-process investment. Target UV-curable ink dispersion formats for narrow-web printing operations in Japan and South Korea, where premixed millbase supply reduces downstream processing costs and captures premium positioning. Establish single-source dispersion partnerships with tier-1 coatings suppliers seeking to consolidate procurement overhead for metallic and pearl effect finishes. For Investors and Strategic Acquirers: REACH's carcinogen category 2 classification reshapes the acquisition landscape by compelling reformulation investments and favoring targets with encapsulated or liquid dispersion capabilities. Long-term viability across the analysis window favors feedstock-integrated producers with captive titanium ore supplies and diversified chemical majors spanning pigment and additive portfolios. Monitor ECHA enforcement patterns on TiO₂ powder notification requirements as the signal indicating acceleration in substitution demand toward zinc oxide and surface-treated alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Feedstock | Captive ilmenite and rutile supplies from Western Australia eliminate raw material cost volatility for chloride-process producers. |
| Chloride-Technology Capacity Expansion | MEE emission standards in China force domestic upgrades, tightening global supply of lower-carbon pigment grades. |
| Surface-Treated TiO₂ Architecture Development | Core-shell engineering with alumina-silica layers captures formulation-level margins in Swiss and US personal care applications. |
| Dispersion Format Partnership Consolidation | Single-source millbase contracts with German and Japanese automotive OEMs reduce qualification overhead and lock in premium pricing. |
| Green Manufacturing Transition | EU Green Deal circularity mandates drive recyclable coatings demand compatible with mechanical recycling streams. |
Research Methodology
Desk research of trade flow databases, SEC 10-K filings, and ECHA regulatory submissions preceded structured interviews with plant managers at TiO₂ production facilities, procurement leads at automotive OEM coatings suppliers, distribution channel partners in Asian pigment trading hubs, and technical R&D directors specializing in surface treatment technologies. Primary fieldwork combined with secondary validation from customs records and Cefic industry reports enabled bottom-up and top-down triangulation across volume and value estimates.
The analytical framework held macroeconomic conditions, regulatory enforcement intensity, and technology diffusion rates as fixed assumptions across the modeling period while varying regional demand elasticity, feedstock access tiers, and substitution dynamics between TiO₂ and zinc oxide. Segmentation dimensions modeled include product type, form, application, and end-use industry, with additional granularity on process technology and certification grade. CAGRs derived from regression analysis against historical capacity utilization and forward-looking procurement contract visibility, incorporating chloride-process engineering talent scarcity and cross-jurisdiction inventory pooling complexity as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by diversified chemical majors or accelerated chloride-technology licensing by retiring engineering cohorts would shift outcomes beyond modeled ranges. Macroeconomic deviation, regulatory reclassification in additional jurisdictions, or breakthrough photocatalytic suppression technologies would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
High Performance Organic Pigments Market
Dyes and Pigments
Pearl Pigment Market
Dyes and Pigments
Water-Based Pigments Market
Dyes and Pigments
Acid Dyes Market
Dyes and Pigments
Petroleum-Fuel Dyes and Markers Market
Dyes and Pigments
Ponceau 4R Colors Market
Dyes and Pigments
Pharmaceutical Dyes Market
Dyes and Pigments
Acrylic Colors Market
Dyes and Pigments
Pigment Dispersions Market
Dyes and Pigments
Polymer Colorant Market
Dyes and Pigments
Global Pigments Market
Dyes and Pigments
Pearlescent Pigments Market
Dyes and Pigments
Plastic Pigments Market
Dyes and Pigments
Fluorescent Brightening Agents Market
Dyes and Pigments
Global Organic Pigments Market
Dyes and Pigments
Global Aluminum Anodizing Dyes Market