
 Pivaloyl Chloride Market | 2026-2036
Pivaloyl Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Pivaloyl Chloride Market Outlook
Isobutyryl chloride is expanding its role as a functional substitute in certain acylation protocols, yet pivaloyl chloride retains structural advantages where steric bulk protects reactive centers during multi-step synthesis. BASF SE leverages captive chlorination capacity and backward integration into pivalic acid feedstock to defend cost positions across European pharmaceutical supply chains. CABB Group anchors its competitiveness through dedicated acyl chloride infrastructure at German manufacturing sites, while WeylChem Group differentiates via custom synthesis capabilities for GMP-grade pivaloyl derivatives.
Pivaloyl chloride is an acyl halide with the molecular formula C5H9ClO, prepared industrially through thionyl chloride-mediated chlorination of pivalic acid under controlled temperature profiles to minimize side-chain decomposition. The compound serves primarily as a protecting group reagent and acylating agent in pharmaceutical intermediate manufacturing, where its steric bulk prevents unwanted rearrangements during complex molecule assembly. Pharmaceutical intermediates command the deepest margin pools among application segments, reflecting stringent purity requirements and qualification protocols that lock in supplier relationships. Agricultural chemicals represent the fastest-growing application category, driven by pivaloyl-protected fungicide and herbicide active ingredients gaining registration traction across multiple jurisdictions. Product type segmentation shows pivaloyl chloride itself dominating volume, while pivaloyl esters capture expanding share in flavoring agent formulations where volatility control matters.
REACH registration requirements in Europe mandate comprehensive toxicological dossiers for acyl chloride imports, elevating compliance costs for non-European suppliers seeking market access. The EPA's New Chemicals Program under TSCA Section 5 imposes pre-manufacture notification burdens on novel pivaloyl derivatives intended for U.S. commercialization, shaping R&D investment timelines. India's CDSCO aligns with ICH Q3C guidelines on residual solvent limits, directly impacting purification specifications for pivaloyl chloride supplied to domestic API manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions, as tightening purity standards in one geography create competitive barriers that integrated producers can exploit against traders lacking technical service depth.
Market Dynamics
Pharmaceutical contract manufacturers in India are consolidating procurement volumes around qualified pivaloyl chloride suppliers, creating asymmetric bargaining power that favors integrated producers with captive pivalic acid supply and dedicated chlorination assets.
Growth Catalysts
- Peptide synthesis expansion:CDSCO-aligned contract research organizations in India are scaling pivaloyl-based coupling chemistry for antiviral drug programs, locking in multi-year supply agreements.
- REACH registration completion:European acyl chloride suppliers who filed comprehensive toxicological dossiers with ECHA now command preferential access to API manufacturers requiring documented purity pedigrees.
- Fungicide active ingredient registrations:Pivaloyl-protected agrochemical molecules are gaining multi-jurisdiction approvals, opening formulation chemistry demand beyond traditional pharmaceutical channels.
Market Restraints
- Thionyl chloride input volatility:The chlorinating agent's price swings and supply interruptions directly compress pivaloyl chloride margin structures for non-integrated producers.
- German manufacturing concentration:Dedicated acyl chloride infrastructure at CABB Group and WeylChem sites creates geographic supply risk that buyers must hedge through dual-sourcing.
- Isobutyryl chloride substitution:This functional substitute is capturing share in acylation protocols where steric bulk protection is less critical, narrowing addressable market for pivaloyl variants.
Strategic Opportunities
- Brazilian agrochemical formulation:ANVISA registration pathways for pivaloyl-protected fungicides remain underpenetrated relative to molecule potential, offering first-mover positioning.
- Continuous flow chlorination:Convergence of microreactor engineering with automated temperature profiling promises to de-bottleneck batch production constraints.
- PLI scheme alignment:India's production-linked incentive framework for active pharmaceutical ingredients subsidizes domestic pivaloyl chloride capacity expansion against import dependency.
Industry Challenges
- GMP-grade purification expertise:Contract manufacturers face acute scarcity of chemists qualified to validate residual solvent limits per ICH Q3C guidelines.
- TSCA Section 5 notification timelines:EPA pre-manufacture review periods for novel pivaloyl derivatives extend R&D-to-commercialization cycles beyond investor patience thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pivaloyl Chloride Market |
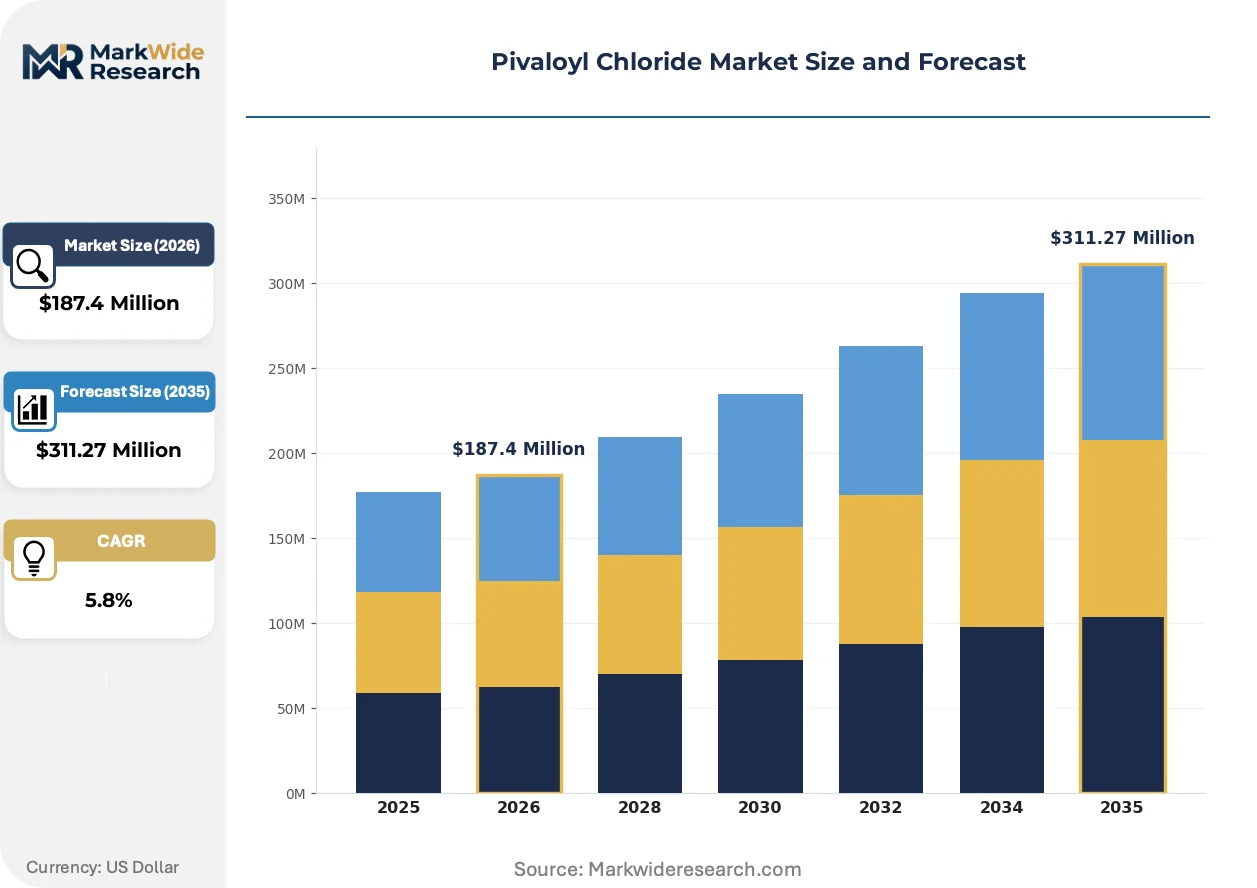
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pivaloyl Chloride, Pivalic Acid, Pivaloyl Esters, 4-Pivaloylphenol Application: Agricultural Chemicals, Pharmaceutical Intermediates, Flavoring Agents, Adhesives End User: Pharmaceutical Companies, Agrochemical Firms, Food Industry, Chemical Manufacturers Delivery Mode: Liquid, Solid, Bulk, Packaged |
| Companies Covered | BASF SE, Merck KGaA, CABB Group, WeylChem Group, Celanese Corporation, Thermo Fisher Scientific, Hebei Fude Chem-Tech, Lubon Chemical, Shandong Jiahong Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pivaloyl Chloride Market Strategic Shifts
Process intensification and regulatory data harmonization are compressing supplier qualification timelines while simultaneously raising technical barriers to market entry.
Continuous flow microreactor systems for thionyl chloride-mediated chlorination are consolidating batch-process capacity in European pharmaceutical supply chains. BASF SE and CABB Group have retrofitted dedicated acyl chloride lines with automated temperature profiling that minimizes side-chain decomposition. This capital-intensive transition is consolidating production among integrated players who can amortize equipment across multiple acyl halide product streams.
REACH registration requirements for acyl chloride imports now mandate toxicological dossiers that elevate compliance costs for non-European suppliers seeking EEA market access. The regulation's industrial consequence is a bifurcation between qualified suppliers with documented purity pedigrees and traders lacking technical service depth. Pharmaceutical intermediate manufacturers are responding by locking in multi-year contracts with registered European producers rather than qualifying new import sources.
Buyer concentration among Indian CDSCO-aligned contract research organizations is compressing supplier negotiation leverage and accelerating volume commitment requirements. Large peptide synthesis houses are displacing spot-market purchasing with framework agreements that bundle pivaloyl chloride with downstream coupling reagents. This procurement consolidation is most visible in Hyderabad and Mumbai pharmaceutical clusters, where CROs are vertically integrating formulation chemistry capabilities.
Pivaloyl Chloride Market Segmentation
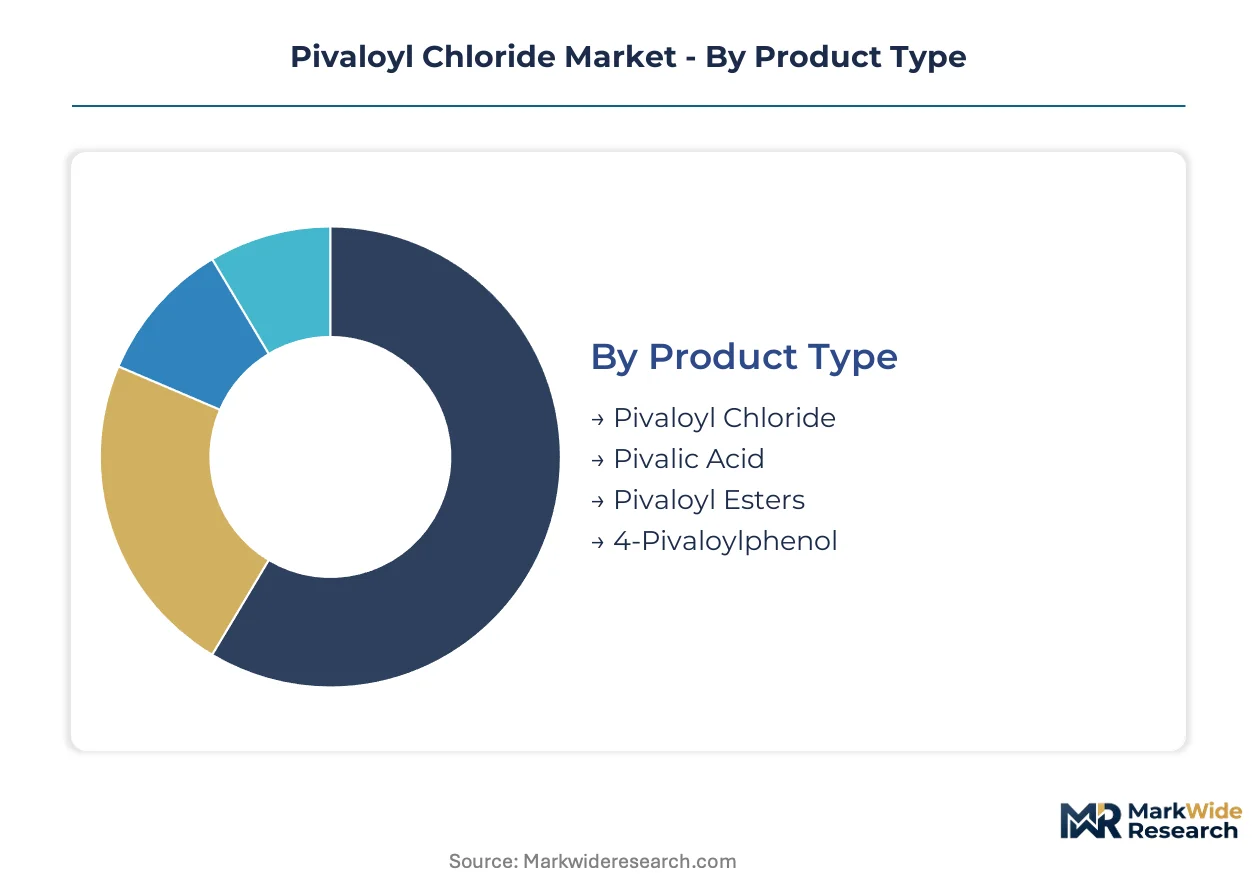
Pivaloyl chloride demand fragments across product variants, end-use applications, and delivery specifications that each impose distinct purity and handling requirements. Supplier positioning depends on matching segment-specific qualification protocols with captive production capabilities.
Product Type:
Supply concentration among integrated chlorination specialists favors producers with backward control over pivalic acid feedstock and dedicated acyl halide infrastructure.
- Pivaloyl Chloride:The acyl halide C5H9ClO serves as the foundational reagent for steric protection in multi-step pharmaceutical synthesis. Demand concentrates at CDSCO-aligned contract research organizations in India, where peptide coupling chemistry for antiviral programs locks in volume commitments.
- Pivalic Acid:This branched C5 carboxylic acid functions as the essential chlorination precursor and finds direct application in specialty ester manufacturing. European REACH-registered suppliers command preferential access as API manufacturers prioritize documented purity pedigrees over spot-market sourcing.
- Pivaloyl Esters:Volatility-controlled formulations for flavoring agent applications.
- 4-Pivaloylphenol:Aromatic derivative used in targeted agrochemical intermediate synthesis.
Pivaloyl chloride absorbs the bulk of installed capacity; pivaloyl esters are expanding most quickly.
Application:
Margin structures diverge sharply between qualification-heavy pharmaceutical channels and volume-driven agricultural chemical segments.
- Pharmaceutical Intermediates:Steric bulk protection during active pharmaceutical ingredient assembly commands the deepest margin pools. ICH Q3C residual solvent limits enforced by India's CDSCO and EMA-aligned European manufacturers create asymmetric barriers that favor integrated producers with GMP-grade purification expertise.
- Agricultural Chemicals:Pivaloyl-protected fungicide and herbicide actives are gaining multi-jurisdiction registrations. Brazil's ANVISA pathway remains underpenetrated relative to molecule potential, offering first-mover positioning for suppliers with formulation chemistry capabilities.
- Flavoring Agents:Controlled volatility requirements in food-grade pivaloyl ester applications.
- Adhesives:Niche industrial bonding applications with specification-driven procurement.
Pharmaceutical intermediates capture the steepest margin premiums; agricultural chemicals show the fastest volume trajectory.
End User:
Customer consolidation patterns determine supplier bargaining power and contract structure flexibility.
- Pharmaceutical Companies:Multi-year framework agreements with bundled reagent sourcing are displacing spot-market purchasing among large peptide synthesis houses. Hyderabad and Mumbai pharmaceutical clusters exhibit the most pronounced procurement consolidation.
- Agrochemical Firms:Registration-dependent demand for pivaloyl-protected actives requires technical service depth that traders cannot replicate.
- Food Industry:Flavoring agent manufacturers with volatility-controlled formulation needs.
- Chemical Manufacturers:Diversified industrial buyers with specification-flexible requirements.
Pharmaceutical companies concentrate the highest-value procurement; agrochemical firms are diversifying supplier relationships fastest.
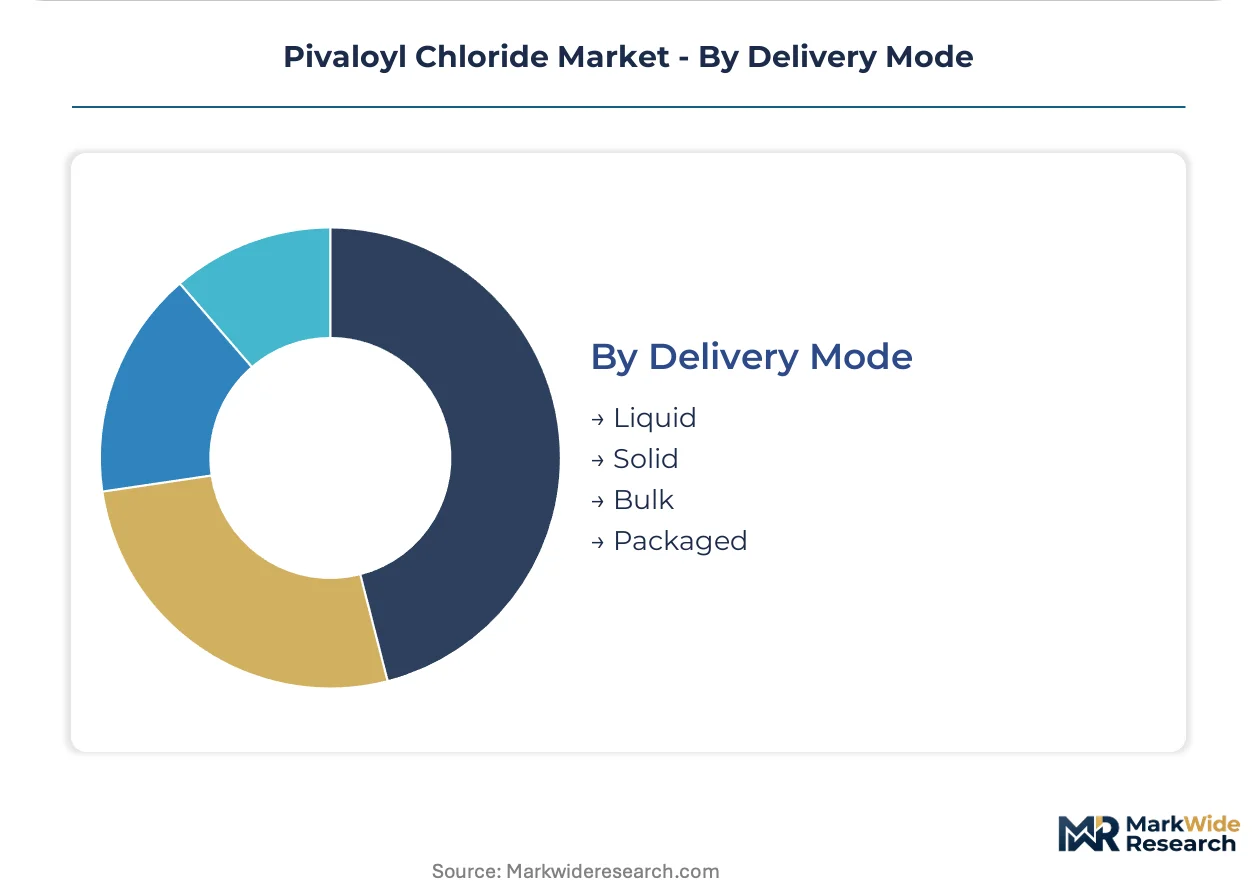
Delivery Mode:
Handling specifications align with end-use purity tiers and geographic supply chain configuration.
- Liquid:Standard bulk delivery for chlorination-derived acyl halides with established cold-chain protocols. German manufacturing sites at CABB Group and WeylChem anchor European liquid supply, creating geographic concentration risk that buyers hedge through dual-sourcing.
- Packaged:GMP-grade containers for pharmaceutical intermediate manufacturers with validated residual solvent limits. India's PLI scheme for active pharmaceutical ingredients subsidizes domestic packaged capacity expansion against import dependency.
- Solid:Specialized handling for derivative forms with stability requirements.
- Bulk:Volume shipments for agricultural chemical formulation with lower purity thresholds.
Liquid delivery dominates current volume; packaged formats are climbing the fastest on pharmaceutical qualification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentration among Indian contract research organizations is redrawing supply chain geography for acyl halide reagents. European REACH-registered producers retain pricing power in qualified pharmaceutical channels. Brazilian agrochemical registration pathways remain underdeveloped relative to molecule potential.
India
CDSCO-aligned contract research organizations in Hyderabad and Mumbai are scaling pivaloyl-based peptide coupling chemistry for antiviral drug programs. The PLI scheme for active pharmaceutical ingredients subsidizes domestic chlorination capacity expansion against import dependency. Gujarat and Maharashtra pharmaceutical clusters are consolidating procurement volumes around qualified suppliers with GMP-grade purification capabilities.
Germany
Dedicated acyl chloride infrastructure at CABB Group and WeylChem sites anchors European pharmaceutical supply chains for steric protection reagents. ECHA REACH registration requirements mandate comprehensive toxicological dossiers that elevate compliance costs for non-European suppliers. The North Rhine-Westphalia and Hesse chemical corridors concentrate backward-integrated pivalic acid production with captive chlorination assets.
United States
EPA TSCA Section 5 pre-manufacture notification timelines extend R&D-to-commercialization cycles for novel pivaloyl derivatives. Generic drug manufacturers in New Jersey and North Carolina pharmaceutical corridors are qualifying multi-year supply agreements with registered European producers. The FDA enforces ICH Q3C residual solvent limits that lock in supplier relationships for API synthesis applications.
Brazil
ANVISA registration pathways for pivaloyl-protected fungicide actives remain underpenetrated relative to molecule potential in agrochemical formulation. São Paulo and Minas Gerais agrochemical clusters are diversifying supplier relationships beyond traditional European sources. The national health surveillance agency's evolving technical standards for crop protection chemistry create first-mover positioning for technical service-capable producers.
China
Shandong and Hebei chemical provinces host thionyl chloride-mediated chlorination capacity serving domestic pharmaceutical intermediate demand. NMPA alignment with ICH guidelines on residual solvent limits shapes purification specifications for export-oriented API manufacturers. The Yangtze River Delta pharmaceutical corridor is consolidating procurement around qualified suppliers with documented purity pedigrees.
Pivaloyl Chloride Market Competitive Environment
Capacity expansion dominates the current landscape as integrated producers retrofit dedicated acyl chloride lines with automated temperature profiling. The vendor base stratifies between multinational chemical conglomerates with captive feedstock supply and regional specialists focused on custom synthesis. Three archetypes define competitive positioning: backward-integrated pivalic acid producers, dedicated acyl halide infrastructure operators, and GMP-grade custom synthesis houses. Geographic expansion and portfolio diversification represent the dominant competitive moves as players seek to amortize equipment across multiple product streams.
Among European-registered chemical conglomerates, BASF SE and CABB Group exemplify the integrated archetype with captive chlorination capacity and pivalic acid feedstock control. WeylChem Group occupies a position within the custom synthesis tier, differentiating through technical service depth for pharmaceutical qualification protocols. Chinese specialists including Hebei Fude Chem-Tech, Lubon Chemical, and Shandong Jiahong Chemical represent the regional manufacturing tier, competing on scale and thionyl chloride input access while navigating REACH registration barriers for EEA market entry.
| Leading Market Players |
|---|
| BASF SE |
| Merck KGaA |
| CABB Group |
| WeylChem Group |
| Celanese Corporation |
| Thermo Fisher Scientific |
| Hebei Fude Chem-Tech |
| Lubon Chemical |
| Shandong Jiahong Chemical |
| Others |
Value Chain & Pricing Dynamics
Thionyl chloride spot-price volatility cascades through pivaloyl chloride manufacturing cost structures, compressing margins for non-integrated producers while amplifying pricing power for backward-integrated specialists with captive chlorination assets. REACH registration compliance costs and GMP-grade purification requirements stratify the market into premium-registered, standard-industrial, and economy-spot tiers that buyers navigate based on end-use qualification protocols.
Pricing Analysis
Volume concentrates in standard-industrial grades serving agrochemical formulation, while margin pools deepen in GMP-certified pharmaceutical channels where ICH Q3C residual solvent documentation commands substantial premiums. Price differentiation hinges on REACH registration status and CDSCO-aligned purification certification, with European-registered producers capturing 40-60% premiums over unregistered Asian imports. Pricing pressure stems from isobutyryl chloride substitution in acylation protocols where steric bulk protection proves non-critical, eroding addressable market for commodity-grade pivaloyl variants. Pharmaceutical contract manufacturers exhibit lowest price sensitivity due to locked-in supplier qualification timelines, while agricultural chemical blenders drive hardest bargaining through volume consolidation and dual-sourcing strategies.
Supply Chain Analysis
Reverse-logistics infrastructure for spent chlorinating agent recovery and pivalic acid reclamation remains underdeveloped across European and Asian production hubs, creating environmental compliance cost exposures that integrated producers mitigate through on-site recycling loops. Supply concentrates in Germany, India, and China, with North Rhine-Westphalia chemical corridors, Gujarat pharmaceutical clusters, and Shandong chlorination provinces anchoring regional capacity. Raw material dependencies center on thionyl chloride feedstock, pivalic acid precursor supply, and specialized corrosion-resistant reactor materials. Single-source vulnerability runs through German acyl chloride infrastructure at CABB and WeylChem sites, prompting buyer hedging through Indian dual-sourcing. Distribution runs through liquid bulk for industrial tiers and validated cold-chain packaged formats for pharmaceutical qualification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pivaloyl chloride supply remains structurally constrained by thionyl chloride input volatility and REACH registration bottlenecks, with qualified European capacity insufficient to meet Indian pharmaceutical procurement consolidation. This supply-constrained dynamic props pricing premiums for registered producers while compressing trader margins.
For Market Incumbents: Anchor market position through dedicated acyl chloride infrastructure retrofits with automated temperature profiling that minimizes side-chain decomposition during chlorination. Prioritize multi-year framework agreements with CDSCO-aligned contract research organizations in Hyderabad and Mumbai to lock in volume commitments before PLI-subsidized domestic Indian capacity reaches scale. Defend against isobutyryl chloride substitution by emphasizing steric bulk protection advantages in peptide coupling applications where rearrangement prevention justifies premium positioning.
For New Entrants and Emerging Players: Enter via Brazilian agrochemical formulation channels where ANVISA registration pathways for pivaloyl-protected fungicides remain underpenetrated relative to molecule potential. Target São Paulo and Minas Gerais agrochemical clusters with technical service capabilities that traders cannot replicate, leveraging first-mover positioning before European incumbents extend registration dossiers. Pursue continuous flow microreactor engineering partnerships to de-bottleneck batch production constraints and amortize capital across multiple acyl halide product streams.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale Indian chlorination specialists with CDSCO-aligned GMP capabilities and PLI scheme qualification in Gujarat and Maharashtra corridors. Long-term viability across a 5-10 year window rests on consolidation of fragmented domestic capacity against import dependency. Monitor thionyl chloride price normalization and REACH registration completion timelines as inflection indicators for margin expansion in qualified pharmaceutical channels.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pivalic Acid | BASF SE and CABB Group defend cost positions through captive feedstock control across European pharmaceutical supply chains. |
| Continuous Flow Chlorination Retrofit | Microreactor engineering convergence promises to de-bottleneck batch constraints and minimize side-chain decomposition losses. |
| REACH Registration Dossier Completion | ECHA-compliant toxicological documentation elevates compliance barriers against non-European traders lacking technical service depth. |
| PLI-Aligned Domestic Capacity Expansion | India's production-linked incentive framework subsidizes Gujarat and Maharashtra chlorination assets against import dependency. |
| ANVISA Registration Pathway Development | First-mover positioning in São Paulo agrochemical clusters opens formulation chemistry demand beyond traditional pharmaceutical channels. |
Study Parameters
Independent corroboration across plant managers at chlorination facilities, procurement leads at Indian CDSCO-aligned contract research organizations, distribution channel partners in European acyl halide supply chains, and technical R&D directors at agrochemical formulation houses underwrites the qualitative findings. Secondary validation draws from ECHA REACH registration databases, CDSCO regulatory filings, customs and trade data for thionyl chloride and acyl halide flows, and SEC 10-K disclosures from listed chemical conglomerates. Bottom-up triangulation across segmented demand models and top-down reconciliation against macroeconomic chemical production indices ensures methodological robustness.
Comparable-period anchoring to historical pharmaceutical intermediate demand cycles and agrochemical active ingredient registration waves shapes the forecast window construction across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use industry application, packaging and delivery format, and regional production hub classification. CAGRs derive from slope-intercept extrapolation of qualified demand growth rates, cross-referenced against capacity expansion announcements and regulatory approval timelines. Industry-specific inputs incorporate peptide synthesis program scaling at Indian CROs and fungicide registration momentum across Brazilian ANVISA pathways.
Forecast precision tightens around the base case; tail outcomes carry wider variance under thionyl chloride supply disruption scenarios or accelerated isobutyryl chloride substitution in non-critical acylation protocols. Practitioners should monitor REACH registration completion rates, PLI scheme disbursement timelines, and continuous flow chlorination technology adoption curves for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Sodium Selenite Market
Bulk Chemicals
North America Vinyl Chloride Monomer Market
Bulk Chemicals
Titanium Dioxide Market
Bulk Chemicals
Propionic Acid Market
Bulk Chemicals
Aniline Market
Bulk Chemicals
Guanidine Nitrate Market
Bulk Chemicals
Magnesium Acetate Market
Bulk Chemicals
Magnesium Nitrate Hexahydrate Market
Bulk Chemicals
M, P-Cresol Market
Bulk Chemicals
United States Iodine Market
Bulk Chemicals
Sodium Hydroxide Market
Bulk Chemicals
South America Carbon Black Market
Bulk Chemicals
Bio-Succinic Acid Market
Bulk Chemicals
Global Fermentation Chemicals Market
Bulk Chemicals
4-Diisopropylbenzene Market
Bulk Chemicals
Nahcolite Market