
 Global Capric Acid Market | 2026-2036
Global Capric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Capric Acid Market Foresight
Multi-source procurement for fatty acid feedstocks is restructuring supply relationships across the capric acid value chain. KLK Oleo leverages integrated palm oil refining complexes in Malaysia to sustain cost advantages in crude capric acid output. IOI Oleo GmbH competes through specialized oleochemical derivatives serving European pharmaceutical customers. Wilmar International controls extensive distribution networks that anchor its position in Asian bulk chemical supply.
Capric acid, a saturated medium-chain fatty acid with ten carbon atoms, typically derives from coconut oil or palm kernel oil through fractional distillation and hydrolysis processes, functioning primarily as an antimicrobial agent, emulsifier, and precursor in ester manufacturing. Refined capric acid dominates pharmaceutical applications where purity thresholds exceed industrial grades, while crude variants occupy lubricant and animal feed formulations where cost sensitivity outweighs specification stringency. Synthetic capric acid remains nascent but attracts investment from chemical manufacturers seeking supply independence from tropical oil volatility.
EMA guidelines govern pharmaceutical-grade capric acid purity standards across Europe, while FDA regulations shape food additive and excipient qualifications in the United States. BIS certification requirements in India create compliance barriers for imported oleochemicals serving domestic personal care manufacturers. Stakeholders must monitor feedstock price volatility in palm and coconut oil markets alongside evolving purity mandates that could fragment procurement strategies between regional regulatory zones.
Market Dynamics
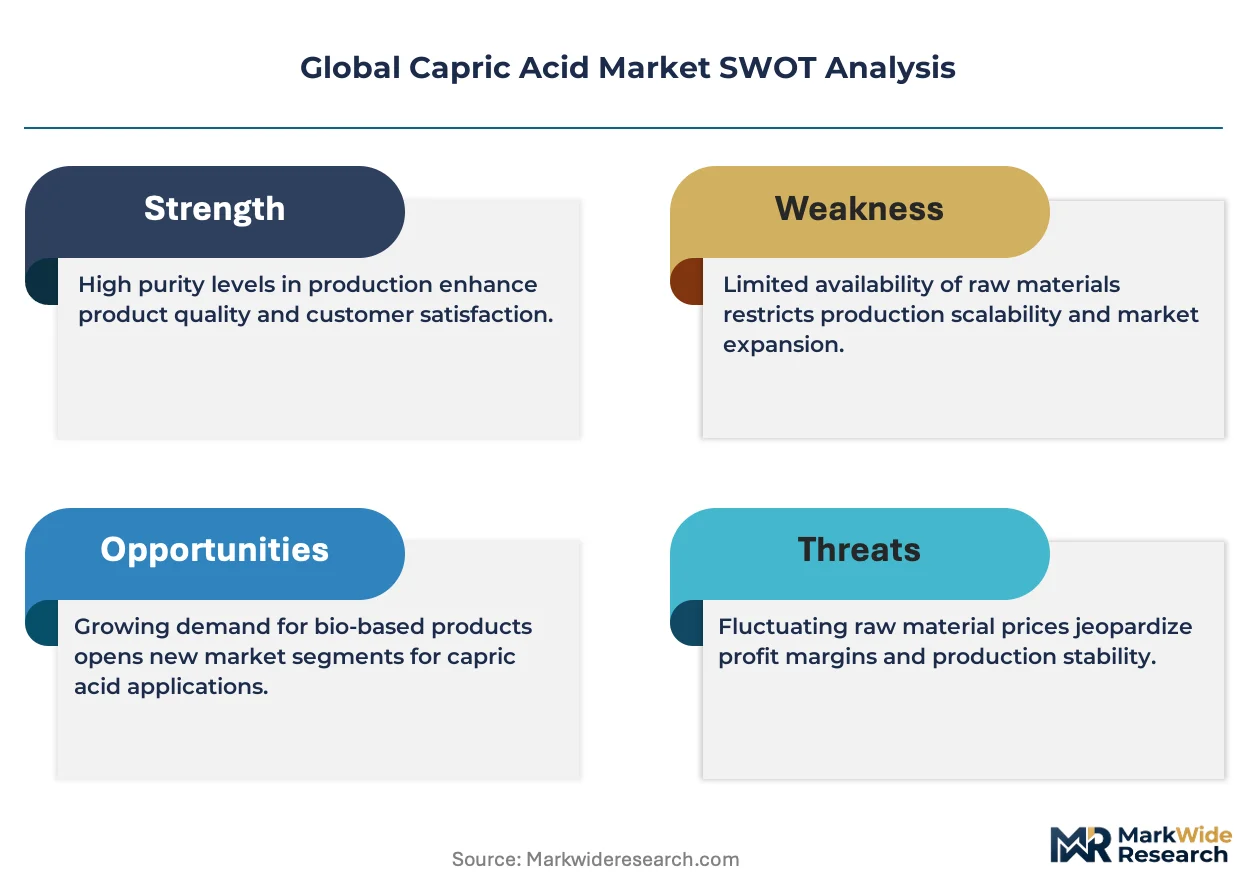
Feedstock concentration in Southeast Asian palm kernel oil clusters is restructuring procurement relationships across the capric acid value chain, forcing buyers to diversify sourcing strategies amid tropical oil price volatility.
Growth Catalysts
- REACH compliance mandates:ECHA purity requirements for cosmetic-grade imports are filtering out substandard suppliers and consolidating demand around certified European pharmaceutical customers.
- Malaysian oleochemical cluster expansion:Integrated refining complexes in Port Klang and Pasir Gudang are compressing production costs for crude capric acid serving lubricant formulators.
- Ester manufacturing demand:Personal care manufacturers in Germany and France are expanding emollient formulations requiring refined capric acid as antimicrobial precursors.
Market Restraints
- Palm kernel oil volatility:Malaysian and Indonesian crude palm oil price swings transmit directly to capric acid feedstock costs, squeezing margin stability for non-integrated processors.
- Synthetic route economics:Petrochemical-based capric acid production remains cost-prohibitive against natural fatty acid distillation, limiting supply diversification.
- BIS certification barriers:India's domestic personal care manufacturers face extended compliance timelines for imported oleochemicals, constraining market access for foreign suppliers.
Strategic Opportunities
- Brazilian pharmaceutical excipient demand:ANVISA's evolving purity standards for generic drug manufacturing are opening specification-grade opportunities for certified exporters.
- Synthetic biology investment:Microbial fermentation platforms using engineered yeast strains are attracting capital from chemical manufacturers seeking supply independence from tropical agriculture.
- Direct-to-compounder distribution:Specialty chemical distributors are bypassing traditional bulk traders to serve mid-sized personal care formulators in Poland and Czechia.
Industry Challenges
- Fractional distillation expertise scarcity:Qualified process engineers capable of operating high-purity separation equipment are concentrated among legacy Malaysian and German operators.
- Multi-jurisdiction certification timelines:Simultaneous FDA food additive, EMA pharmaceutical-grade, and BIS cosmetic compliance requires 18-24 month validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Capric Acid Market |
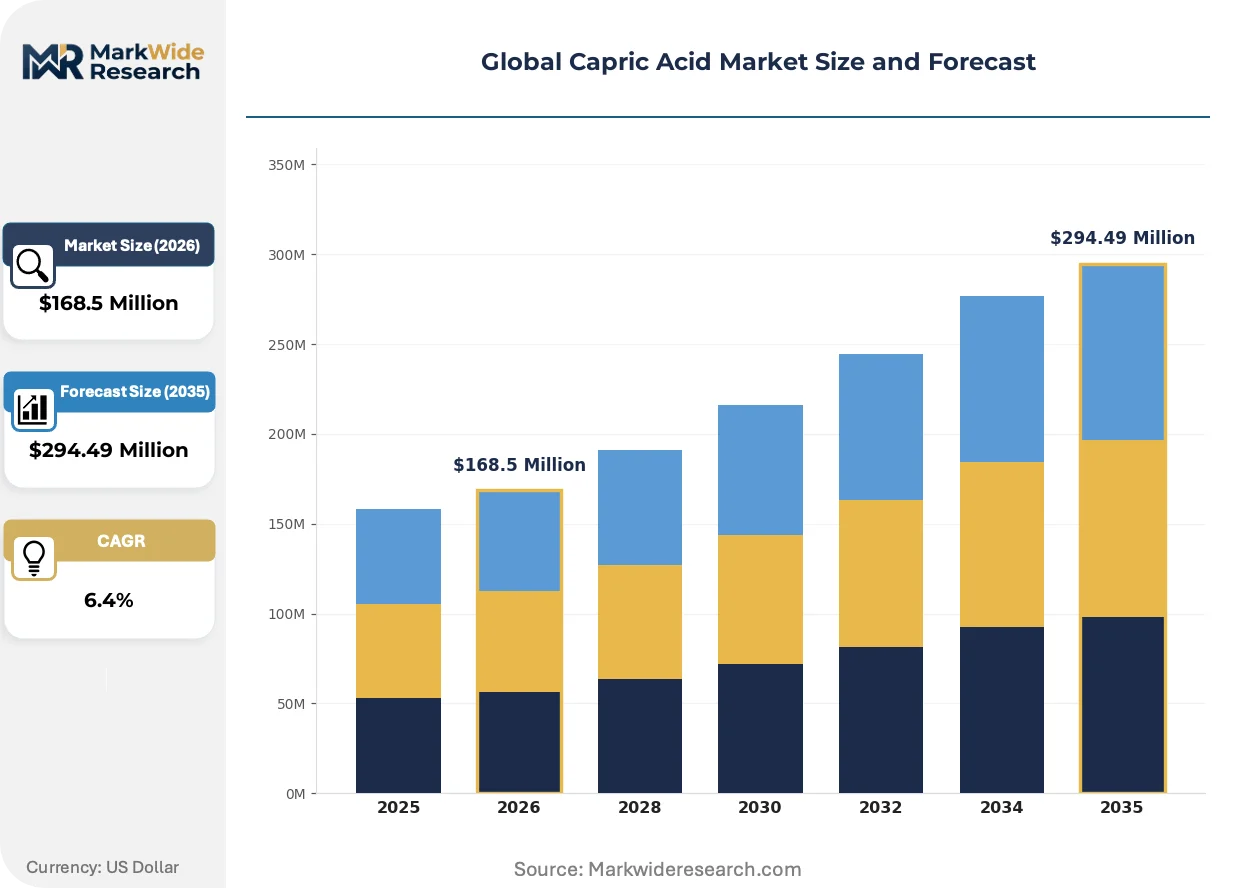
| Market Size in 2026 | $168.5 Million |
| Market Size in 2035 | $294.49 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Capric Acid, Crude Capric Acid, Purified Capric Acid, Synthetic Capric Acid Application: Food Additives, Animal Feed, Cosmetics, Lubricants, Pharmaceuticals End User: Personal Care Manufacturers, Feed Producers, Pharmaceutical Companies, Chemical Manufacturers Packaging Type: Drums, Bulk Bags, Intermediate Bulk Containers, Barrels |
| Companies Covered | P&G Chemicals, Temix Oleo, KLK Oleo, Permata Group, Acme-Hardesty Co., Univar Solutions, IOI Oleo GmbH, Muslim Mas Group, Wilmar International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Capric Acid Market Shifts & Advancements
Process intensification and regulatory digitization are compressing the gap between laboratory-grade and industrial-scale capric acid production, enabling faster specification transitions across pharmaceutical and personal care applications.
Continuous hydrolysis reactor technology is unifying fractional distillation and enzymatic splitting into single-unit operations. German specialty chemical producers are retrofitting existing plants with these systems to reduce solvent use. This convergence is unifying cost structures across pharmaceutical and industrial grade boundaries, pressuring traditional batch processors.
REACH's 2024 updated substance evaluation criteria are tightening impurity thresholds for cosmetic-grade capric acid imports into Europe. ECHA's SCIP database requirements are forcing supply chain transparency disclosures from Southeast Asian exporters. Personal care formulators in France and Italy are responding by consolidating procurement around pre-registered suppliers with established IUCLID dossiers.
Specification-driven procurement is displacing spot-market purchasing among European pharmaceutical excipient buyers. Compounders in Switzerland and Germany are locking annual contracts with fixed purity bands rather than accepting variable-grade shipments. This behavioral shift is most visible in Basel and Frankfurt, where generic drug manufacturers face EMA audit pressures requiring batch-to-batch consistency documentation.
Global Capric Acid Market Segmentation
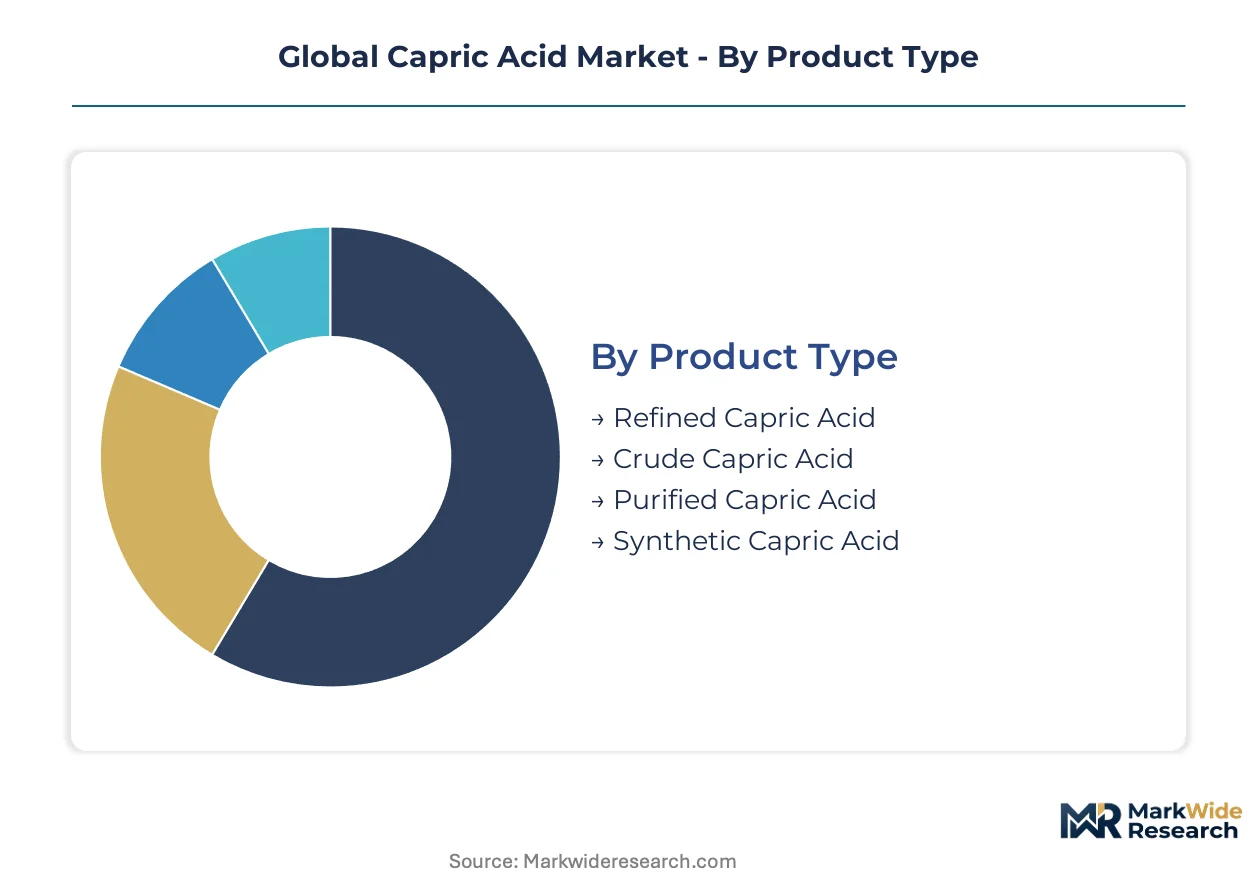
Capric acid specifications fragment across purity tiers and synthetic alternatives, each commanding distinct procurement relationships and margin structures. Understanding these divisions reveals where integrated oleochemical producers defend position against specialty chemical competitors and where regulatory thresholds create specification premiums.
Product Type:
Refined grades operate as standalone antimicrobial agents in pharmaceutical formulations, while crude and synthetic variants embed into broader chemical manufacturing processes with lower purity tolerance.
- Refined Capric Acid:Pharmaceutical-grade material exceeding purity thresholds for excipient use in generic drug manufacturing. Swiss and German compounders lock annual contracts with fixed purity bands to satisfy EMA audit documentation requirements.
- Crude Capric Acid:Lower-purity output from fractional distillation serving lubricant formulators and animal feed producers where cost sensitivity dominates. Malaysian integrated refiners in Port Klang compress production costs through captive palm kernel oil supply.
- Purified Capric Acid:Intermediate grade bridging cosmetic and pharmaceutical applications. Personal care manufacturers in France specify this tier for emollient formulations requiring REACH-registered supply chains.
- Synthetic Capric Acid:Petrochemical-derived material attracting investment from manufacturers seeking independence from tropical oil volatility. Current economics remain unfavorable against natural fatty acid distillation routes.
Volume placements concentrate in crude grades serving industrial lubricant markets; the faster expansion belongs to refined grades driven by pharmaceutical excipient standardization.
Application:
Demand intensity varies sharply across end-uses, with pharmaceutical and cosmetic applications commanding specification premiums while feed and lubricant markets compete on delivered cost.
- Food Additives:Antimicrobial preservative applications in processed foods. FDA food additive qualification timelines stretch 18-24 months, consolidating procurement around established suppliers with prior approvals.
- Cosmetics:Ester precursors for emollient formulations in skin and hair care products. REACH compliance mandates are filtering out substandard suppliers and consolidating demand around ECHA-registered European pharmaceutical customers.
- Animal Feed:Antimicrobial growth promoter in livestock nutrition. Formulators accept variable-grade shipments where cost sensitivity outweighs specification stringency.
- Lubricants:Base stock and additive component for industrial metalworking fluids. Malaysian oleochemical clusters supply this segment through integrated refining complexes.
- Pharmaceuticals:Excipient and active pharmaceutical ingredient precursor. EMA guidelines govern purity standards across Europe, with Swissmedic and German regulators enforcing batch-to-batch consistency documentation.
Margin concentration sits with pharmaceutical applications; cosmetics applications are climbing fastest on personal care manufacturer expansion.
End User:
Procurement sophistication diverges between multinational pharmaceutical compounders with locked annual contracts and mid-sized personal care formulators seeking flexible supply arrangements.
- Personal Care Manufacturers:German and French formulators expand emollient portfolios requiring refined capric acid as ester precursors. REACH SCIP database disclosures force supply chain transparency from Southeast Asian exporters.
- Pharmaceutical Companies:Generic drug manufacturers in Basel and Frankfurt face EMA audit pressures requiring fixed purity bands and batch documentation. Specification-driven procurement is displacing spot-market purchasing.
- Feed Producers:Livestock nutrition compounders prioritize delivered cost over specification grades. Procurement concentrates around Malaysian and Indonesian supply clusters.
- Chemical Manufacturers:Broad industrial users spanning lubricant, solvent, and intermediate applications. This segment shows highest price elasticity and supplier switching frequency.
Contract sophistication concentrates with pharmaceutical companies; personal care manufacturers are expanding procurement volume most rapidly.
Packaging Type:
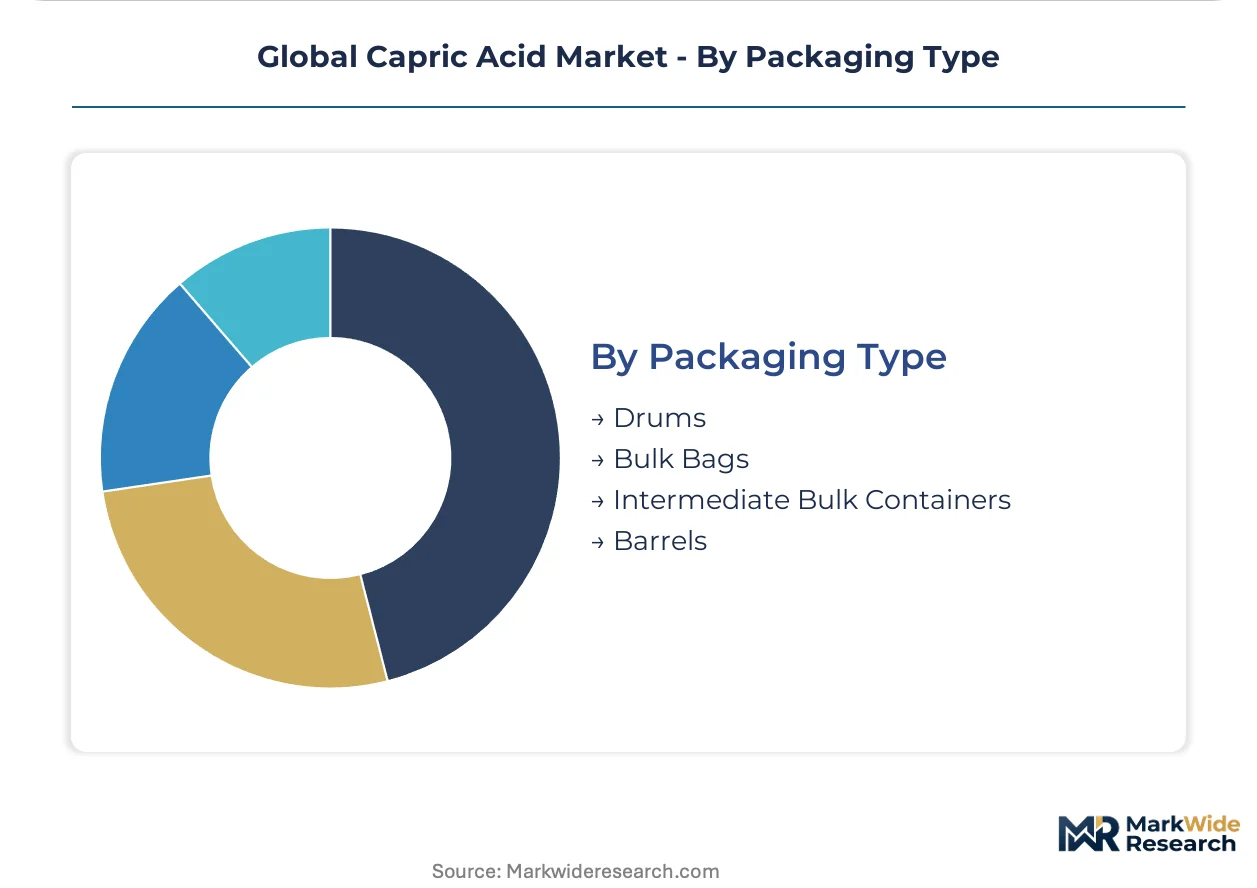
Logistics configuration tracks end-user scale and handling infrastructure, with bulk formats dominating integrated chemical manufacturing and unitized packaging serving dispersed formulators.
- Drums:Standard 200-liter steel containers for mid-volume pharmaceutical and cosmetic compounders. German and Swiss generic drug manufacturers specify this format for excipient deliveries.
- Bulk Bags:Flexible intermediate bulk containers for high-volume lubricant and feed applications. Malaysian export logistics favor this format for regional Asian distribution.
- Intermediate Bulk Containers:Reusable rigid totes for chemical manufacturers with integrated handling systems. Cost-per-use economics improve with shipment frequency.
- Barrels:Traditional wooden or fiber containers for specialty chemical distributors serving Poland and Czechia personal care formulators through direct-to-compounder channels.
Shipment volume concentrates in bulk bags; intermediate bulk containers are gaining share fastest on chemical manufacturer investment in handling automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical excipient demand concentrates in German and Swiss manufacturing clusters, while oleochemical production gravitates toward Malaysian and Indonesian palm kernel oil refining complexes. Personal care formulators in France and Italy are consolidating procurement around REACH-registered suppliers.
Germany
EMA audit pressures are forcing generic drug manufacturers in Frankfurt and Basel-adjacent facilities to lock annual contracts with fixed purity bands. The German regulator enforces batch-to-batch consistency documentation for pharmaceutical-grade capric acid. Port Klang exporters serve this market through specialized oleochemical distributors with established IUCLID dossiers.
Malaysia
Integrated palm oil refining complexes in Port Klang and Pasir Gudang compress production costs for crude capric acid serving lubricant formulators. The Malaysian Investment Development Authority supports oleochemical cluster expansion through tax incentives for downstream processing. KLK Oleo leverages captive feedstock supply to sustain cost advantages in regional bulk chemical distribution.
France
Personal care manufacturers in Lyon and Paris expand emollient portfolios requiring refined capric acid as ester precursors. REACH SCIP database mandates force supply chain transparency disclosures from Southeast Asian exporters. French formulators are consolidating procurement around pre-registered suppliers with established ECHA compliance records.
India
Domestic personal care manufacturers in Maharashtra and Gujarat face extended BIS certification timelines for imported oleochemicals. The Bureau of Indian Standards creates compliance barriers that constrain market access for foreign suppliers. Mumbai-based compounders are developing alternative sourcing relationships with Malaysian exporters to circumvent validation delays.
Indonesia
Oleochemical production clusters in Medan and Surabaya are expanding fractional distillation capacity to serve Asian lubricant markets. The Indonesian government promotes downstream palm oil processing through export duty differentials. Wilmar International controls distribution networks anchoring its position in regional bulk chemical supply from these manufacturing hubs.
Global Capric Acid Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated Southeast Asian refiners scale fractional distillation output to capture pharmaceutical-grade premiums. The vendor base organizes around three strategic archetypes: palm oil conglomerates with captive feedstock supply, European specialty chemical distributors with regulatory expertise, and regional trading houses facilitating spot-market liquidity. M&A activity concentrates among Malaysian producers seeking backward integration into palm kernel crushing, while technology licensing agreements proliferate between German engineering firms and Asian processors.
Within the integrated refining tier, KLK Oleo and Wilmar International exemplify the captive-feedstock archetype, leveraging Malaysian and Indonesian palm oil complexes to compress production costs. IOI Oleo GmbH occupies a position among European specialty distributors, serving pharmaceutical customers through regulatory-compliant supply chains. Temix Oleo and Acme-Hardesty Co. sit within the mid-market distributor segment, facilitating specification-grade procurement for personal care compounders lacking direct refinery relationships.
| Leading Market Players |
|---|
| P&G Chemicals |
| Temix Oleo |
| KLK Oleo |
| Permata Group |
| Acme-Hardesty Co. |
| Univar Solutions |
| IOI Oleo GmbH |
| Muslim Mas Group |
| Wilmar International |
| Others |
Supply & Pricing Matrix
Pharmaceutical-grade certification premiums diverge sharply from commodity lubricant grades, embedding purity thresholds as the primary pricing axis while concentrating supply relationships around EMA-registered European distributors and Malaysian integrated refiners. This bifurcation forces buyers to maintain dual procurement channels: locked annual contracts with fixed purity bands for excipient use, and spot-market flexibility for industrial applications where Port Klang cost compression dominates.
Pricing Analysis
Volume placements cluster in crude grades serving lubricant formulators, while margin capture concentrates with refined pharmaceutical grades commanding certification premiums. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial levels reflects EMA audit documentation requirements, REACH SCIP database compliance, and feedstock cost pass-through respectively. Cost compression in crude tiers is intensifying because Malaysian integrated refiners leverage captive palm kernel oil supply. Feed producers exhibit highest price sensitivity, accepting variable-grade shipments, whereas Swiss generic drug manufacturers lock fixed purity bands regardless of spot volatility.
Supply Chain Analysis
Single-source vulnerability sits with Southeast Asian palm kernel oil clusters, where Malaysian and Indonesian production hubs anchor global fatty acid distillation capacity. Raw material dependencies draw from coconut oil, palm kernel oil, and nascent microbial fermentation feedstocks. Regulatory restriction risk manifests through REACH substance evaluation updates and BIS certification barriers constraining Indian market access. Distribution runs through specialized oleochemical distributors with established IUCLID dossiers serving European pharmaceutical customers, bypassing traditional bulk traders for specification-grade procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive feedstock supply and downstream certification capabilities determine competitive position. Players are pursuing backward integration into palm kernel crushing to compress production costs and secure volume commitments.
For Market Incumbents: To counter synthetic biology investment from chemical manufacturers seeking supply independence, KLK Oleo and Wilmar International should deepen captive supply of palm kernel oil through Malaysian plantation expansion while securing EMA pre-registration for pharmaceutical-grade output. Certification investment in IUCLID dossiers and SCIP database compliance anchors European customer retention against emerging microbial fermentation platforms. For New Entrants and Emerging Players: Synthetic biology platforms using engineered yeast strains offer the most penetrable wedge for supply-independent positioning, targeting pharmaceutical excipient buyers in Basel and Frankfurt frustrated by tropical oil volatility. Direct-to-compounder distribution channels in Poland and Czechia present white-space opportunities bypassing established bulk traders. A technology-first go-to-market emphasizing batch-to-batch consistency documentation aligns with EMA audit pressures reshaping procurement behavior. For Investors and Strategic Acquirers: Re-rating potential sits with Malaysian integrated refiners possessing captive feedstock and ECHA-registered supply chains given REACH compliance consolidation filtering substandard suppliers. Long-term viability over the next decade hinges on specification-grade margin capture rather than commodity volume placement. The signal to watch is synthetic route economics breaching cost parity with natural fatty acid distillation, which would trigger feedstock diversification mandates from risk-averse pharmaceutical compounders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palm Kernel Crushing | Captive feedstock supply compresses production costs for Malaysian refiners serving lubricant markets. |
| REACH Pre-Registration Investment | ECHA IUCLID dossiers enable European pharmaceutical customer retention against unregistered competitors. |
| Synthetic Biology Platform Development | Engineered yeast fermentation attracts capital from manufacturers seeking independence from tropical agriculture volatility. |
| Direct-to-Compounder Distribution | Specialty chemical distributors bypass bulk traders to serve mid-sized personal care formulators in Central Europe. |
| Continuous Hydrolysis Reactor Retrofit | German specialty chemical producers reduce solvent use while unifying cost structures across grade boundaries. |
Research Methodology
Independent corroboration across primary interviews with oleochemical plant managers, pharmaceutical procurement leads, and specialty chemical distributors, alongside secondary validation through customs trade data, ECHA registration databases, and SEC filings from listed palm oil conglomerates, underwrites the qualitative findings. Bottom-up triangulation against top-down market sizing reconciles fractional distillation capacity estimates with downstream demand segmentation across pharmaceutical, cosmetic, and industrial applications.
Comparable-period anchoring to historical palm kernel oil price volatility and oleochemical capacity utilization rates structured the forecast window across the analysis window. Segmentation dimensions modeled include purity grade tier, end-use industry application, packaging format, and regional regulatory cluster. CAGRs were derived through demand elasticity analysis against feedstock cost pass-through patterns, incorporating pharmaceutical excipient standardization timelines and personal care manufacturer expansion trajectories as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen biotechnology breakthroughs achieving synthetic route cost parity, abrupt shifts in EMA or FDA purity thresholds, and geopolitical disruptions to Southeast Asian palm oil supply chains. Forecasts reflect documented assumptions about regulatory stability and tropical oil price mean reversion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
GCC Calcium Chloride Market
Bulk Chemicals
Sheet Molding and Bulk Molding Compounds Market
Bulk Chemicals
Heavy Alkyl Benzenes Market
Bulk Chemicals
Fine Hydrate Market
Bulk Chemicals
US Hydrochloric Acid Market
Bulk Chemicals
Europic Chloride Market
Bulk Chemicals
US Magnesium Stearate Market
Bulk Chemicals
Bistrifluoromethanesulfonimide Lithium Market
Bulk Chemicals
North America Copper Sulphate Market
Bulk Chemicals
Dithiocarbamates Market
Bulk Chemicals
Sodium Hydrosulfide Market
Bulk Chemicals
Zinc Gluconate Granules Market
Bulk Chemicals
Global Hexamethylenediamine Market
Bulk Chemicals
Caustic Potash Market
Bulk Chemicals
Paraxylene(PX) Market
Bulk Chemicals
Asia-Pacific Formic Acid Market