
 Global Laboratory Gas Generators Market | 2026-2036
Global Laboratory Gas Generators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Laboratory Gas Generators Market Foresight
Contract research organizations is unwinding the historical dominance of academic laboratories in laboratory gas generator procurement. Peak Scientific Instruments leverages its installed base across European pharma hubs to sustain recurring service revenue. Parker Hannifin Corporation anchors North American demand through its chromatography gas solutions division. Linde plc competes on cryogenic-derived generator architectures for high-purity nitrogen segments.
Laboratory gas generators are self-contained systems that produce purified gases on-demand through pressure swing adsorption, membrane separation, or electrolytic dissociation, typically delivering hydrogen at 99.9999% purity or nitrogen at 99.999% purity for analytical instrumentation feedstock. Their primary purpose is to eliminate cylinder logistics while ensuring continuous, specification-grade gas supply for chromatography, mass spectrometry, and elemental analysis workflows. Nitrogen generators occupy the largest product category due to universal deployment in liquid chromatography-mass spectrometry systems across pharmaceutical quality control labs. Pressure swing adsorption technology dominates unit economics for mid-capacity installations, while membrane separation systems are gaining share in food and beverage testing environments where lower purity thresholds suffice. Hydrogen generators represent the fastest-growing product segment as labs transition from helium carrier gas to hydrogen for gas chromatography applications amid helium supply constraints.
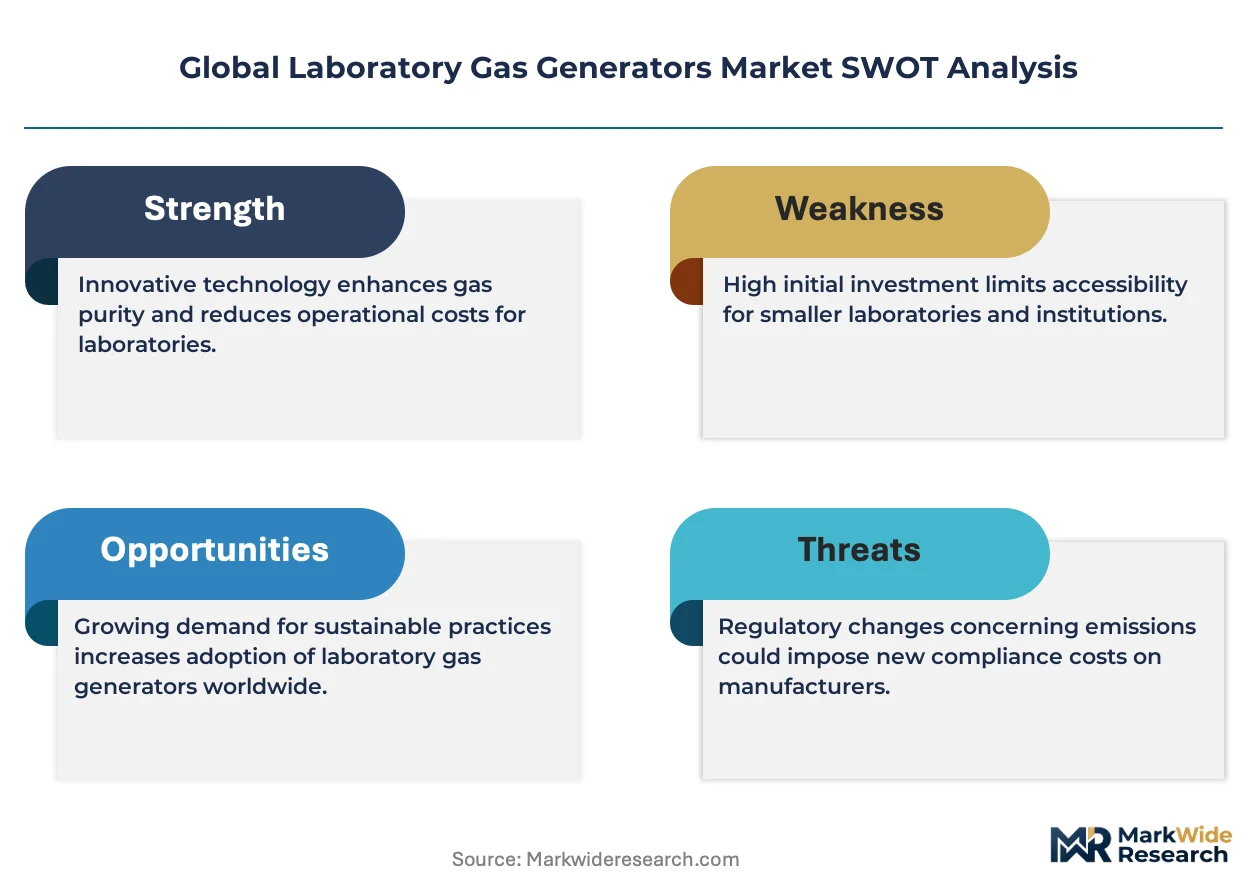
FDA Good Manufacturing Practice guidelines and EPA Method validation protocols collectively shape gas purity documentation requirements and instrument qualification standards in the United States. EMA's analytical procedure validation framework and REACH chemical safety obligations in Europe drive comparable compliance investments among generator manufacturers seeking CE-marked product placement. ISO 8573 purity classes for compressed air quality provide the foundational technical reference that buyers invoke in procurement specifications across jurisdictions. Stakeholders must monitor helium substitution timelines and hydrogen safety code revisions to calibrate product development priorities and regional sales deployment.
Market Dynamics
The laboratory gas generator market is experiencing a structural compression driven by helium supply constraints, which is forcing chromatography labs to accelerate hydrogen carrier gas adoption and triggering cascading investments in on-site hydrogen generation infrastructure.
Growth Catalysts
- EMA Analytical Procedure Validation Framework:European pharmaceutical quality control labs must document gas purity traceability, creating mandatory upgrade cycles for generator installations.
- Contract Research Organization Clustering:Dense CRO concentrations near Frankfurt and Munich are standardizing nitrogen generator specifications, generating procurement momentum.
- Pressure Swing Adsorption:This technology platform delivers superior unit economics for mid-capacity installations, expanding addressable market share in routine analytical workflows.
Market Restraints
- Platinum Catalyst Cost Volatility:Hydrogen generator electrolytic cells depend on platinum group metal electrodes, exposing manufacturers to raw material price swings.
- German Equipment Supply Concentration:Critical membrane separation components source predominantly from specialized Bavarian suppliers, creating single-point vulnerability.
- Helium Reserve Liquidation:US Bureau of Land Management helium auctions are temporarily depressing helium prices, slowing some hydrogen substitution decisions.
Strategic Opportunities
- India CDSCO Inspection Regime:Strengthened domestic pharmaceutical manufacturing compliance is opening demand for specification-grade nitrogen generators in quality control labs.
- Food and Beverage Testing:Membrane separation systems are penetrating this segment where lower purity thresholds reduce capital barriers.
- Internet-of-Things Remote Monitoring:Predictive maintenance platforms are enabling service revenue unbundling from equipment sales.
Industry Challenges
- Electrolytic Stack Technician Scarcity:Hydrogen generator maintenance requires specialized proton exchange membrane expertise that training pipelines have not scaled.
- ISO 8573 Certification Timeline:Third-party purity validation for compressed air quality classes extends sales cycles by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Laboratory Gas Generators Market |
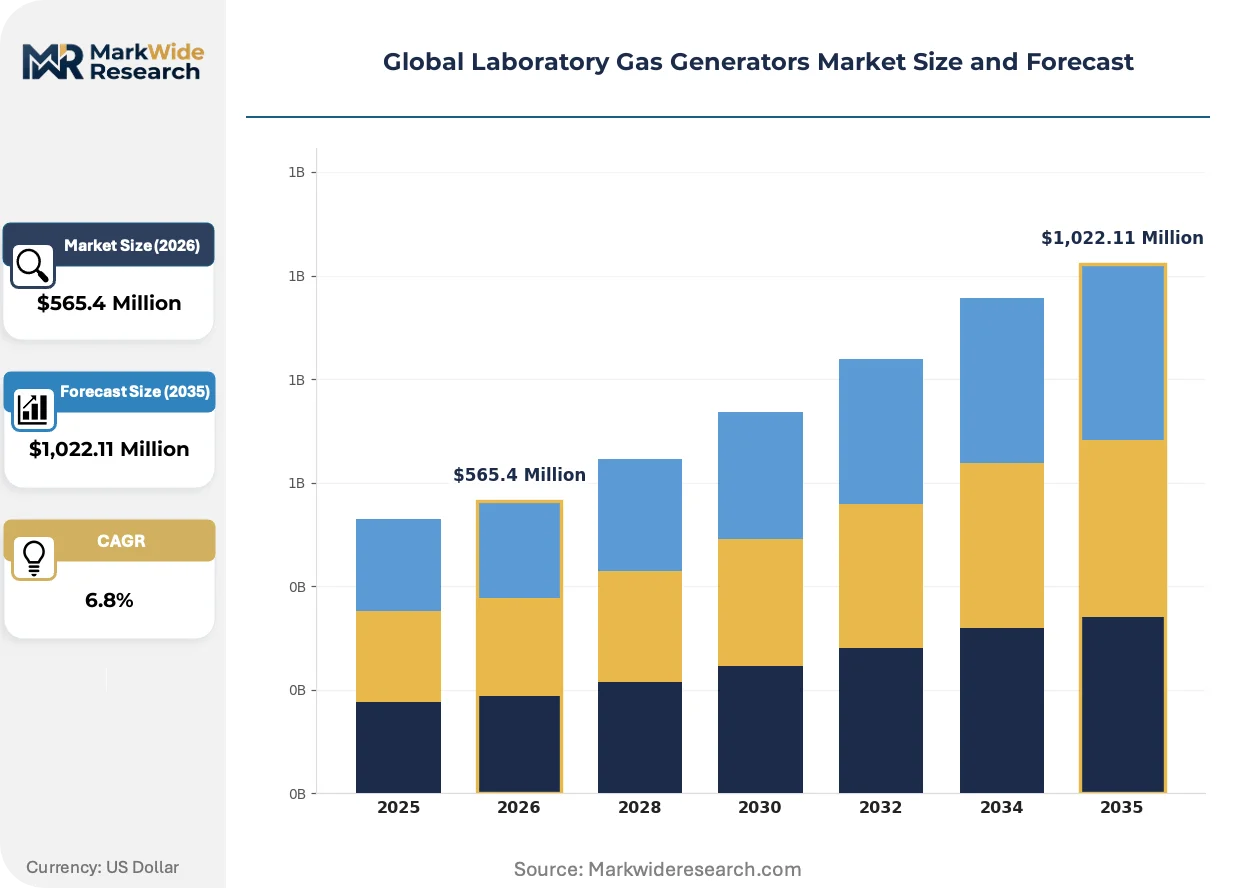
| Market Size in 2026 | $565.4 Million |
| Market Size in 2035 | $1,022.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogen Generators, Nitrogen Generators, Zero Air Generators, Specialty Gas Generators Technology: Pressure Swing Adsorption, Membrane Separation, Cryogenic Distillation, Catalytic Reforming Application: Pharmaceutical Analysis, Food & Beverage Testing, Environmental Monitoring, Petrochemical Analysis End User: Research Institutes, Quality Control Labs, Chemical Testing Facilities, Academic Laboratories |
| Companies Covered | Parker Hannifin Corporation, Peak Scientific Instruments, Linde plc, PerkinElmer Inc., Claind S.r.l., VICI DBS, Atlas Copco, LNI Swissgas, ErreDue S.p.a, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Laboratory Gas Generators Market Shifts & Advancements
Electrolytic dissociation architectures are undergoing rapid footprint reduction, compressing generator dimensions while maintaining purity specifications. This physical transformation is unlocking installation possibilities in space-constrained laboratory environments.
Membrane separation technology is miniaturizing through advanced polymer hollow-fiber configurations. Portable food safety testing labs are adopting these compact nitrogen generators for field-deployable chromatography. The technology is miniaturizing equipment footprints from cabinet-scale to benchtop dimensions, eroding the historical advantage of pressure swing adsorption in small-capacity segments.
EPA Method validation protocols are tightening documentation requirements for gas purity in environmental testing laboratories. Instrument qualification standards now mandate continuous purity verification rather than periodic calibration. Gas chromatography-mass spectrometry workflows in US contract labs are responding by specifying generators with integrated purity sensors and automated audit trails.
Service contract unbundling is separating generator hardware from maintenance and consumables in procurement negotiations. Large pharmaceutical quality control departments are negotiating direct technical service agreements independent of original equipment manufacturers. This pattern is most visible in German CRO clusters where standardization enables multi-site service consolidation.
Global Laboratory Gas Generators Market Segmentation
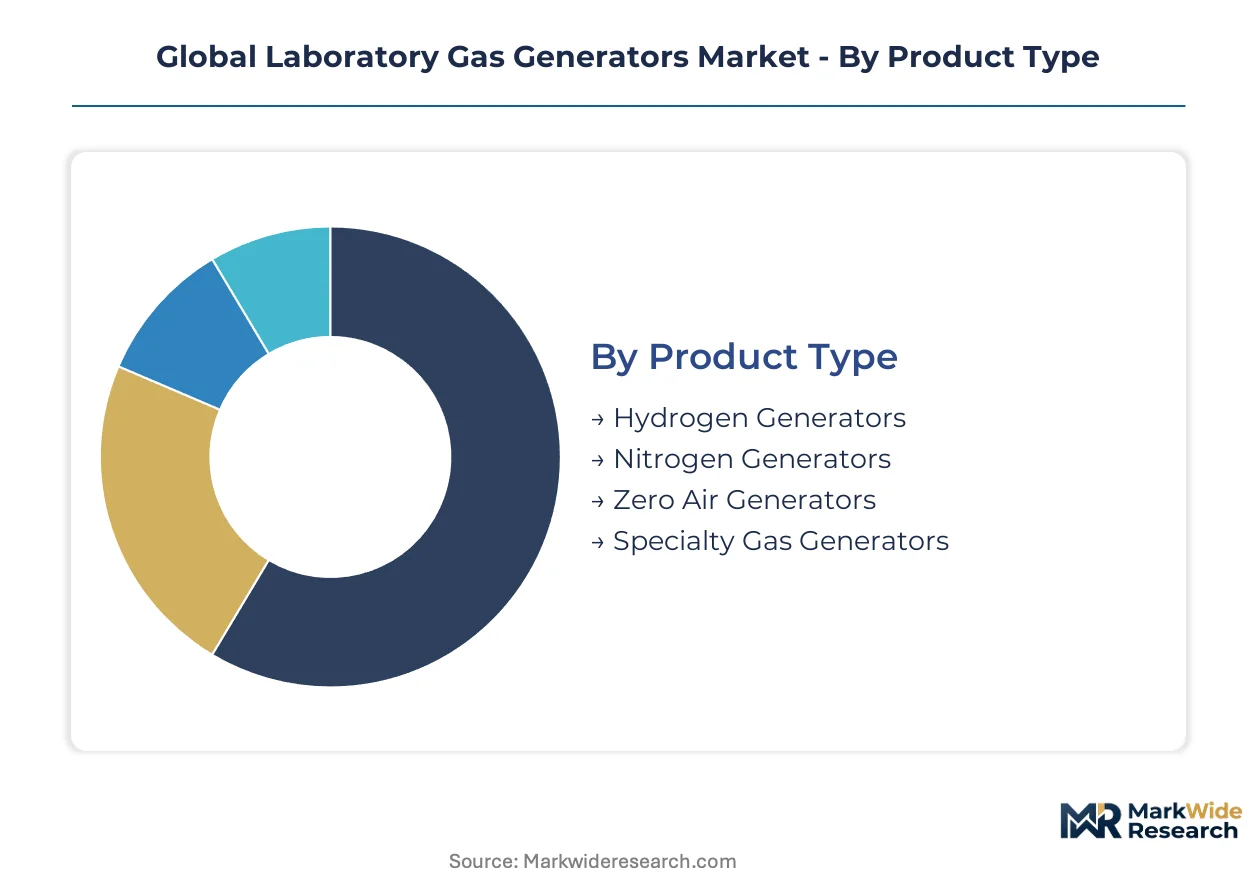
Laboratory gas generator procurement patterns diverge sharply across product types and end-use contexts. Channel strategy must account for whether buyers prioritize capital efficiency, regulatory documentation, or operational continuity.
Product Type:
Direct sales teams capture high-value hydrogen and nitrogen generator contracts, while distributors handle smaller zero air and specialty gas units where specification complexity is lower.
- Nitrogen Generators:Pressure swing adsorption and membrane architectures deliver 99.999% purity for liquid chromatography-mass spectrometry feedstock. Demand concentrates in German pharmaceutical quality control labs near Frankfurt and Munich, where FDA and EMA documentation requirements mandate continuous purity verification.
- Hydrogen Generators:Proton exchange membrane electrolytic cells produce 99.9999% purity hydrogen carrier gas. US chromatography labs are accelerating adoption as helium supply constraints from Bureau of Land Management auction volatility force carrier gas transitions.
- Zero Air Generators:Catalytic hydrocarbon removal systems supply flame ionization detector support gas.
- Specialty Gas Generators:Custom-configured systems address rare noble gas and calibration mixture requirements.
Nitrogen generators dominate installed base. Hydrogen generators are where expansion concentrates.
Technology:
Cost tier stratification separates premium cryogenic systems from mid-range pressure swing adsorption and economy membrane alternatives.
- Pressure Swing Adsorption:Carbon molecular sieve beds separate nitrogen from compressed air through cyclic pressure modulation. Mid-capacity pharmaceutical installations in India and Germany favor this technology for its balance of capital cost and purity specification.
- Membrane Separation:Hollow-fiber polymer configurations exploit differential gas permeation rates. Food and beverage testing environments in Europe adopt these systems where 95-99% purity thresholds reduce capital barriers.
- Cryogenic Distillation:Ultra-low temperature fractional condensation achieves highest purity nitrogen for semiconductor and research applications.
- Catalytic Reforming:Hydrocarbon steam reforming with pressure swing adsorption purification produces hydrogen from natural gas feedstock.
Pressure swing adsorption anchors routine analytical workflows. Membrane separation is climbing the fastest in portable and field-deployable segments.
Application:
Customer type determines procurement velocity — pharmaceutical quality control demands fastest qualification timelines while academic laboratories extend evaluation cycles.
- Pharmaceutical Analysis:Good Manufacturing Practice compliance drives nitrogen generator standardization across quality control and stability testing workflows. CDSCO inspection regime strengthening in India is opening specification-grade demand in domestic manufacturing facilities.
- Environmental Monitoring:EPA Method validation protocols mandate continuous gas purity documentation. US contract laboratories specify generators with integrated sensors and automated audit trails for chromatography-mass spectrometry workflows.
- Food & Beverage Testing:Membrane nitrogen systems support modified atmosphere packaging analysis and contaminant screening.
- Petrochemical Analysis:Hydrogen generators supply refinery laboratory process control and product certification testing.
Pharmaceutical analysis commands premium pricing. Environmental monitoring is where regulatory compliance investments are accelerating most quickly.
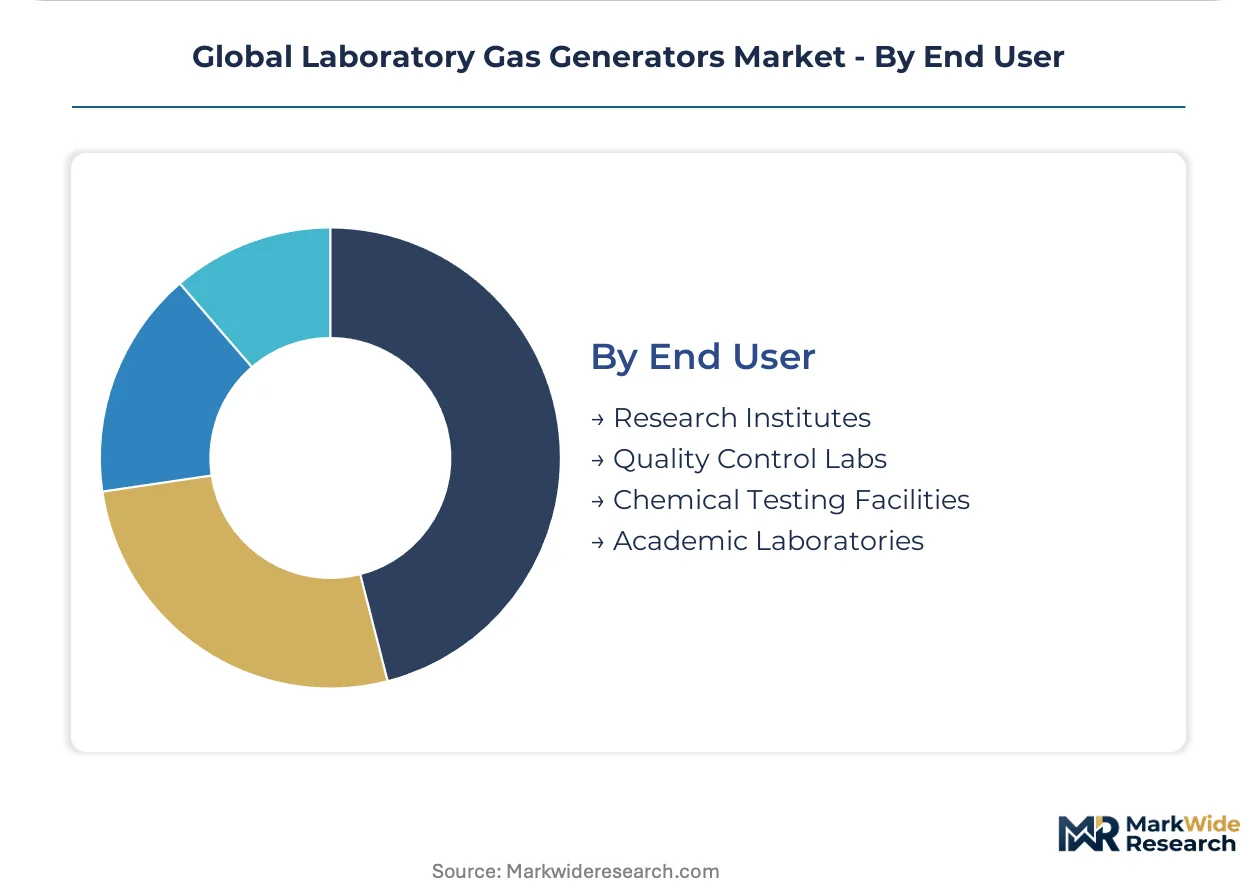
End User:
Volume concentration varies — quality control labs standardize across sites while research institutes customize per principal investigator requirements.
- Quality Control Labs:Centralized procurement functions negotiate multi-site service agreements independent of original equipment manufacturers. German CRO clusters near Frankfurt and Munich demonstrate this pattern through consolidated nitrogen generator specifications.
- Research Institutes:Decentralized purchasing accommodates diverse analytical workflows across departmental boundaries. Helium-to-hydrogen transition timelines vary by research group based on instrument vintage and grant funding cycles.
- Chemical Testing Facilities:Industrial contract laboratories prioritize uptime guarantees and rapid technician response.
- Academic Laboratories:Budget constraints favor lower-capacity units with extended service intervals.
Quality control labs dominate replacement demand. Research institutes are where helium substitution decisions are concentrating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export pressure swing adsorption systems to pharmaceutical quality control labs across India and the United States, establishing the primary trade corridor for specification-grade nitrogen generators.
United States
Chromatography laboratories accelerate hydrogen generator procurement as helium supply constraints from Bureau of Land Management auction volatility force carrier gas transitions. EPA Method validation protocols mandate continuous gas purity documentation with automated audit trails. Houston and Boston pharmaceutical corridors concentrate demand for integrated purity sensor systems.
Germany
Contract research organization clusters near Frankfurt and Munich standardize nitrogen generator specifications across multi-site installations. EMA analytical procedure validation framework tightens gas purity traceability requirements for pharmaceutical quality control. Bavarian membrane component suppliers anchor the regional equipment supply chain.
India
Domestic pharmaceutical manufacturing facilities expand specification-grade nitrogen generator installations following CDSCO inspection regime strengthening. BIS certification requirements align procurement specifications with international purity standards. Maharashtra and Gujarat pharmaceutical corridors drive quality control lab infrastructure investment.
China
Environmental monitoring laboratories deploy nitrogen generators for chromatography-mass spectrometry workflows under tightening MEE pollutant detection mandates. NMPA pharmaceutical manufacturing guidelines elevate analytical instrument qualification standards. Yangtze River Delta contract research facilities concentrate procurement decisions.
Japan
Research institutes manage helium-to-hydrogen transition timelines based on instrument vintage and grant funding cycles. METI industrial standards shape proton exchange membrane electrolytic cell specifications for analytical applications. Kanto region pharmaceutical quality control labs standardize service contract structures.
Global Laboratory Gas Generators Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with chromatography gas divisions and specialized laboratory equipment manufacturers. Market structure exhibits moderate consolidation with tiered competition across premium specification-grade and economy membrane separation segments. Strategic archetypes include cryogenic-derived system specialists, proton exchange membrane electrolytic cell developers, and pressure swing adsorption platform providers. Competitive moves concentrate on geographic expansion through distributor networks and technology licensing agreements for membrane separation miniaturization.
Within the diversified industrial tier, Parker Hannifin Corporation anchors North American demand through its chromatography gas solutions division. Peak Scientific Instruments leverages its installed base across European pharmaceutical hubs to sustain recurring service revenue. Linde plc competes on cryogenic-derived generator architectures for high-purity nitrogen segments.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Peak Scientific Instruments |
| Linde plc |
| PerkinElmer Inc. |
| Claind S.r.l. |
| VICI DBS |
| Atlas Copco |
| LNI Swissgas |
| ErreDue S.p.a |
| Others |
Supply & Pricing Matrix
Fourteen-to-eighteen week lead times for proton exchange membrane electrolytic cells concentrate pricing power with Bavarian component suppliers while compressing margins for hydrogen generator assemblers facing platinum catalyst cost volatility. This inventory constraint shapes procurement negotiations across pharmaceutical quality control labs in Germany and the United States.
Pricing Analysis
The technology-generation pricing gap separates legacy pressure swing adsorption systems from compact membrane separation units and emerging cryogenic-derived architectures. Three-tier pricing structure across premium, standard, and economy levels stratifies by purity certification grade and after-sales service bundling. Pricing pressure stems from helium reserve liquidation temporarily depressing hydrogen substitution urgency. Academic laboratories exhibit highest price sensitivity while quality control labs prioritize specification compliance over capital cost.
Supply Chain Analysis
Inventory concentration for hollow-fiber polymer membranes centers on Bavarian suppliers, with pressure swing adsorption carbon molecular sieves drawing from German and Indian sources, and platinum group metal electrodes resting on South African and Russian mining outputs. Critical dependencies include proton exchange membrane stacks, catalytic hydrocarbon removal substrates, and precision pressure modulation valves. Single-source vulnerability in German membrane component supply creates disruption exposure. Distribution runs through direct sales teams for high-value pharmaceutical contracts and specialized laboratory equipment distributors for smaller academic installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service contract unbundling is expanding faster than hardware sales as German CRO clusters negotiate multi-site technical service agreements independent of original equipment manufacturers. This recurring-revenue layer offers superior margin stability.
For Market Incumbents: Fortify installed base retention by embedding predictive maintenance platforms with remote purity monitoring, countering emerging IoT-native entrants. Deepen backward integration into proton exchange membrane stack production to offset platinum catalyst cost volatility. Prioritize ISO 8573 certification investment to extend qualification timelines as a competitive moat. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships unlocks German pharmaceutical quality control labs where EMA analytical procedure validation framework mandates documented gas purity traceability. Target food and beverage testing segments where membrane separation purity thresholds reduce capital barriers. Pursue field-deployable miniaturization for portable chromatography applications. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because service attach rates and consumables replacement cycles decouple from capital expenditure cyclicality. Acquisition targets should display concentrated installed bases in pharmaceutical corridors with underpenetrated service contracts. Monitor helium auction price trajectories as the signal for hydrogen substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Remote Monitoring Platform Launch | Enables predictive maintenance revenue unbundling from hardware sales in German CRO clusters. |
| Proton Exchange Membrane Backward Integration | Captures platinum catalyst cost volatility margin through in-house electrolytic stack production. |
| CE Marking Fast-Track Certification | Accelerates EMA compliance documentation for pharmaceutical quality control lab procurement cycles. |
| Membrane Separation Miniaturization Partnership | Unlocks portable food safety testing applications through advanced polymer hollow-fiber configurations. |
| Multi-Site Service Consolidation Agreement | Standardizes nitrogen generator specifications across Frankfurt and Munich CRO installations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA warning letters, EMA inspection databases, and ISO certification registries across laboratory equipment manufacturers. Interviews with pharmaceutical quality control managers, chromatography instrument specialists, aftermarket service directors, and procurement leads at contract research organizations informed demand-side validation. Customs trade data, SEC equipment manufacturer filings, and national pharmaceutical regulator inspection reports provided supply-side triangulation through bottom-up installation tracking and top-down market sizing.
Segmentation dimensions modeled include product type, technology platform, application workflow, and end-user procurement structure across the projection horizon. CAGRs derive from unit shipment trajectories weighted by average selling price evolution and service revenue attachment rates. Hydrogen carrier gas substitution timelines and CDSCO inspection regime strengthening in India constitute industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained helium supply constraint and stable EMA analytical procedure validation enforcement; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Global Argon Market
Industrial Gases
Noble Gas Market
Industrial Gases
North America Industrial Gases Market
Industrial Gases
Nitrogen Generator Market
Industrial Gases
Europe Syngas Market
Industrial Gases
Neon Gas for Laser Market
Industrial Gases
CNG, RNG, and Hydrogen Tanks Market
Industrial Gases
High Purity Methane Gas Market
Industrial Gases
High Purity Gas/Ultra-High Purity Gas/Pure Gas Market
Industrial Gases
Global Sulfur Dioxide Market
Industrial Gases
Commercial Hydrogen Market
Industrial Gases
Global Specialty Gas Market
Industrial Gases
LAMEA Industrial Nitrogen Market
Industrial Gases
Syngas Market
Industrial Gases
Industrial Gases for Metals and Metal Fabrication Market
Industrial Gases
Carbon Monoxide Market