
 Tallow Market | 2026-2036
Tallow Market Size, Share, and Industry Trends Forecast 2026-2036
Tallow Market Analytics
Traditional wholesale procurement channels for rendered animal fats is fragmenting as biofuel blenders and specialty chemical firms build direct relationships with integrated renderers. Darling Ingredients Inc. leverages its North American rendering network to secure long-term supply contracts with renewable diesel producers. Tyson Foods Inc. competes by anchoring captive tallow output to its protein processing footprint across Midwestern states. SARIA SE & Co. KG differentiates through European rendering assets that supply oleochemical refineries with ISCC-certified feedstock.
Tallow denotes the rendered fat derived primarily from bovine adipose tissue, with a typical fatty acid profile containing 40-50% oleic acid, 25-30% palmitic acid, and 20-25% stearic acid, obtained through wet or dry rendering at temperatures between 115°C and 140°C. This lipid serves as a foundational oleochemical feedstock for surfactants, lubricity additives, and saponification bases where petrochemical substitutes face carbon intensity penalties. Rendered Tallow occupies the largest volume share owing to its standardized quality grades and compatibility with both food-grade and technical applications. Biodiesel Production represents the fastest-expanding application segment as renewable diesel hydrotreaters commission dedicated tallow pretreatment units to meet low-carbon fuel standards.
The EPA Renewable Fuel Standard, EU Renewable Energy Directive, and California LCFS collectively determine tallow eligibility for renewable fuel credits and carbon intensity scoring. These frameworks incentivize segregated supply chains with mass-balance certification, pressuring unverified renderers to invest in traceability systems. Stakeholders must monitor evolving lifecycle assessment methodologies and regional book-and-claim accounting rules that will determine which tallow streams command premium offtake terms.
Market Dynamics
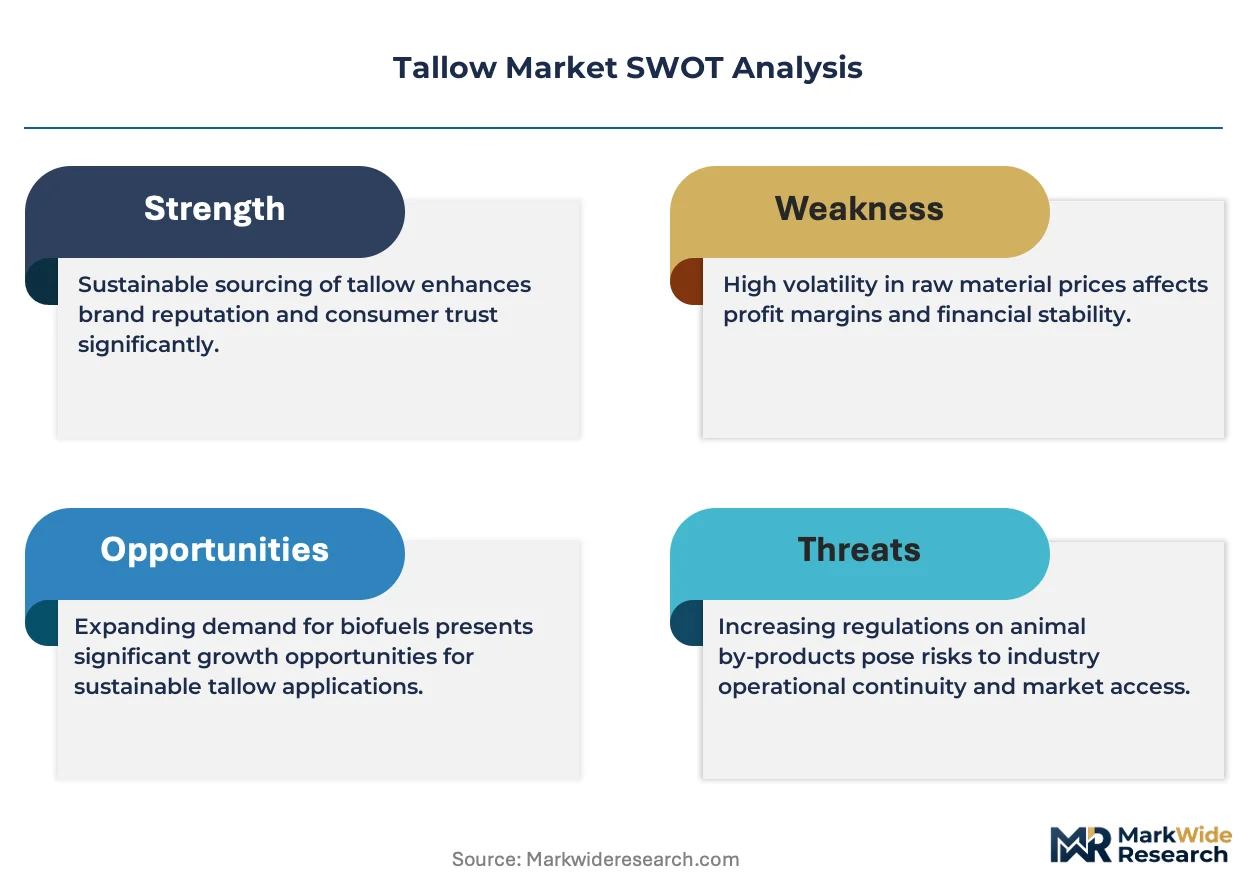
Renewable diesel hydrotreaters are reconfiguring tallow procurement economics by demanding ISCC-certified feedstock with verified carbon intensity scores, compressing spot market liquidity and forcing renderers to invest in segregated supply chains.
Growth Catalysts
- California LCFS:Low-carbon fuel standards award carbon credits to tallow-based renewable diesel, pulling Midwest rendering output toward West Coast refiners.
- Oleochemical surfactants:Personal care formulators substitute petrochemical feedstock with tallow fatty acids to meet Scope 3 reduction targets.
- Midwest meatpacking corridors:Concentrated rendering infrastructure around Nebraska and Iowa reduces logistics costs for biodiesel producers.
Market Restraints
- Feedstock competition:Used cooking oil and distillers corn oil command lower carbon intensity scores in California LCFS calculations, displacing tallow in credit-maximizing blends.
- Rendering concentration:Four integrated processors control approximately 70% of North American edible and inedible tallow output, creating bottleneck risk.
- F-Gas Regulation:EU restrictions on fluorinated gases redirect industrial lubricant demand toward synthetic esters with superior cold-flow properties.
Strategic Opportunities
- Southeast Asia oleochemical expansion:Indonesian and Malaysian palm oil sustainability controversies create opening for certified tallow imports into Asian surfactant plants.
- EU Green Deal:Carbon border adjustment mechanisms penalize petrochemical-derived fatty acids, advantaging EU-sourced tallow with verified lifecycle data.
- Pretreatment technology convergence:Membrane filtration and enzymatic degumming integration enables direct tallow feeding into renewable diesel units without standalone refining.
Industry Challenges
- ISCC certification timeline:Mass-balance documentation requirements demand 12-18 month system implementations for mid-size renderers lacking traceability infrastructure.
- Hydrotreater feedstock flexibility:Co-processing tallow with soybean oil requires precise moisture and phosphorus control, straining legacy rendering quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tallow Market |
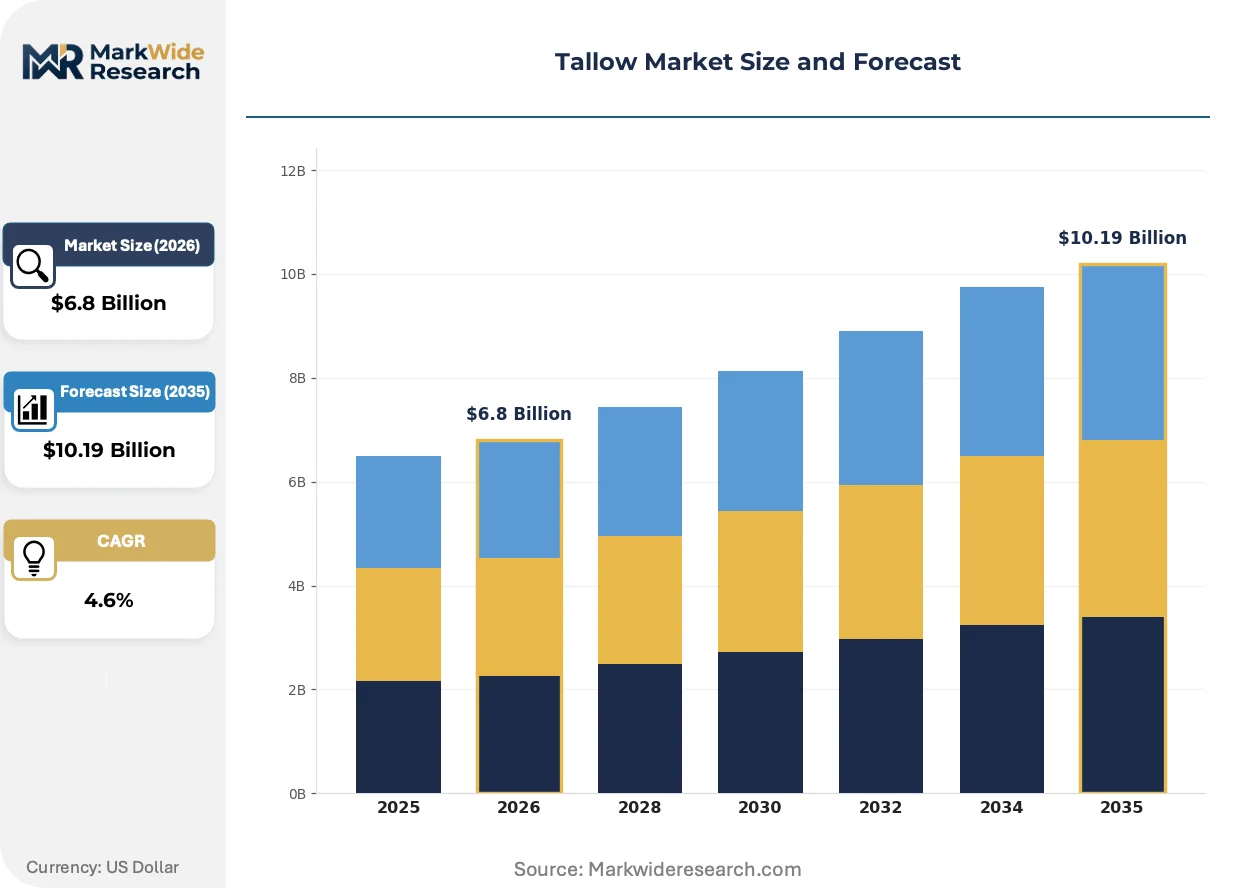
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rendered Tallow, Beef Tallow, Mutton Tallow, Spectrum Tallow Application: Industrial Lubricants, Soap Manufacturing, Biodiesel Production, Animal Feed End User: Food Industry, Cosmetics, Pharmaceuticals, Biofuels Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | Tyson Foods Inc., Wilmar International Limited, Darling Ingredients Inc., Vantage Specialty Chemicals, Inc., BASF SE, Cargill, Incorporated, JBS S.A., Australian Tallow Producers, SARIA SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tallow Market Evolving Landscape
Digital traceability platforms and advanced pretreatment chemistry are collapsing the traditional separation between rendering and renewable fuel production, enabling real-time carbon intensity tracking from abattoir to hydrotreater.
Enzymatic interesterification is migrating from niche cosmetic applications to technical-grade tallow modification, allowing oleochemical producers to custom-tailor fatty acid profiles without fractional crystallization. Specialty lubricant blenders in Germany and the Netherlands are adopting enzymatically modified tallow esters for biodegradable metalworking fluids. This technology is migrating from high-margin personal care into industrial volumes, compressing capital requirements for mid-scale processors.
The EU F-Gas Regulation and delegated acts under the Renewable Energy Directive III are tightening feedstock sustainability verification requirements, mandating satellite-linked geolocation data for cattle sourcing. Renderers must now document chain-of-custody from slaughterhouse to final product. European biodiesel producers are responding by consolidating supply relationships with integrated meatpackers possessing captive rendering and veterinary traceability systems.
Direct offtake contracting is displacing merchant spot purchases as renewable diesel producers seek 5-7 year supply commitments with fixed carbon intensity baselines. Large biofuel refiners in Texas and Louisiana are negotiating directly with Tyson Foods and JBS rendering divisions, bypassing traditional fat brokers. This pattern is most visible in the US Gulf Coast, where new hydrotreater capacity is concentrating and tallow represents the lowest-cost qualifying feedstock with domestic supply security.
Tallow Market Segmentation
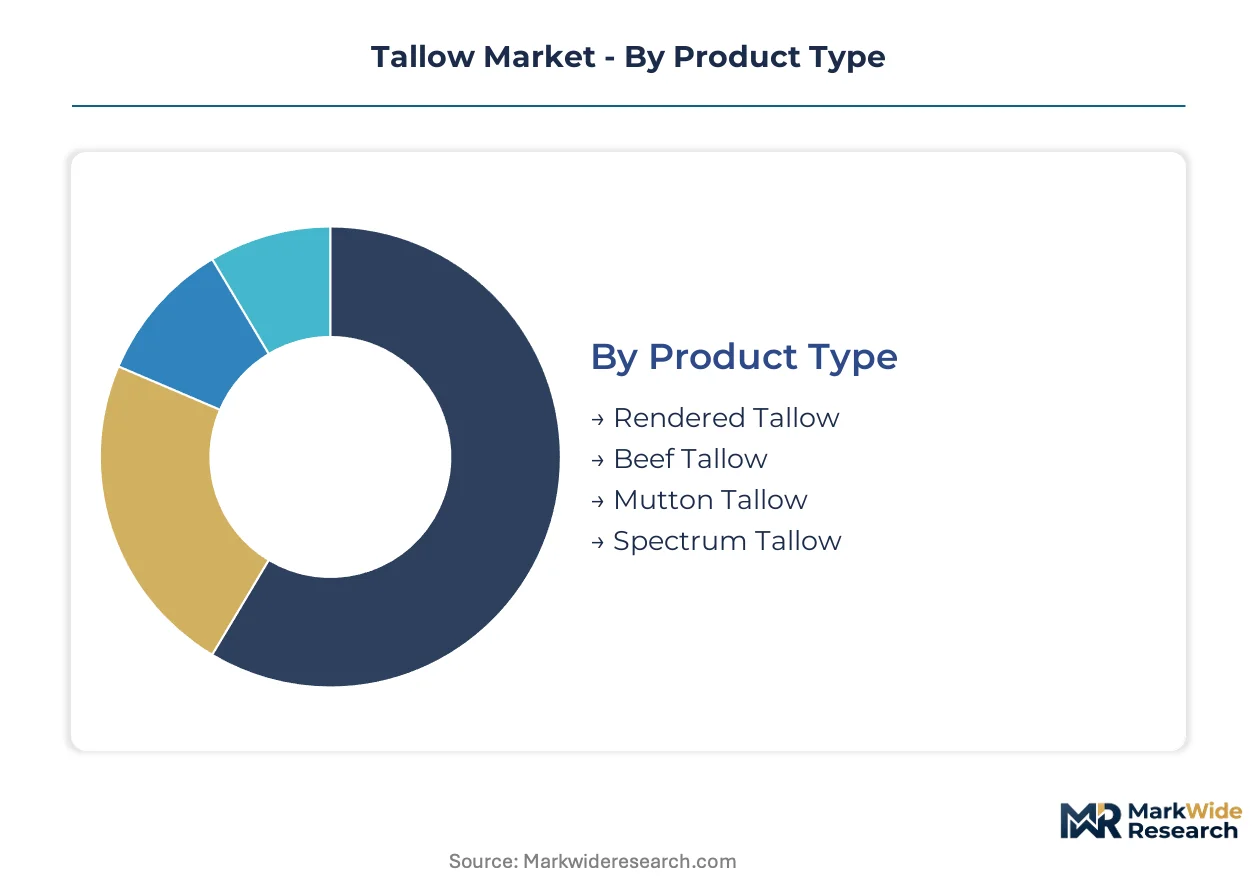
Tallow segmentation tracks how rendering chemistry, carbon intensity scoring, and supply chain certification reshape procurement economics across distinct product grades and end-use specifications. Each dimension reveals divergent margin structures and compliance burdens that determine competitive positioning.
Product Type:
Product differentiation centers on rendering method, fatty acid saturation, and contaminant thresholds that dictate downstream compatibility.
- Rendered Tallow:Standardized output from wet or dry rendering at 115°C to 140°C containing 40-50% oleic acid, 25-30% palmitic acid, and 20-25% stearic acid. Demand concentrates in North American biodiesel hydrotreaters seeking ISCC-certified feedstock with verified carbon intensity baselines for California LCFS compliance.
- Beef Tallow:Derived specifically from bovine adipose tissue with higher stearic acid content than mixed-species render. European oleochemical refineries in Germany and the Netherlands source this grade for surfactant production where EU Green Deal carbon border adjustments penalize petrochemical alternatives.
- Mutton Tallow:Rendered sheep fat with distinct fatty acid profile favoring shorter-chain saturates. Specialty lubricant blenders in Australia utilize this grade for biodegradable metalworking fluids.
- Spectrum Tallow:Blended multi-species product optimized for consistent technical specifications. Industrial soap manufacturers in Southeast Asia import this grade to offset palm oil sustainability controversies.
Rendered Tallow commands the established base. The steepest expansion runs through Beef Tallow.
Application:
Application segmentation reveals how regulatory frameworks redirect tallow flows toward credit-eligible uses versus traditional commodity markets.
- Biodiesel Production:Hydrotreated renewable diesel production requires pretreated tallow with precise moisture and phosphorus control. US Gulf Coast refiners negotiate direct offtake agreements with Midwest renderers to secure 5-7 year supply commitments under EPA Renewable Fuel Standard and California LCFS.
- Soap Manufacturing:Saponification bases for personal care and industrial cleaning products. Formulators substitute petrochemical feedstock with tallow fatty acids to meet Scope 3 reduction targets in European and North American markets.
- Industrial Lubricants:Lubricity additives and base stocks for metalworking and textile applications. EU F-Gas Regulation redirects demand toward synthetic esters with superior cold-flow properties, compressing tallow share in this segment.
- Animal Feed:Energy-dense ingredient for livestock and pet nutrition rations. Rendering networks supply this grade through traditional merchant channels with lower certification requirements.
Soap Manufacturing retains the volume foundation. Biodiesel Production is climbing the fastest.
End User:
End user categories reflect divergent purity standards, traceability demands, and price sensitivity across consumer-facing and industrial buyers.
- Biofuels:Renewable diesel and biodiesel producers requiring mass-balance certification and satellite-linked geolocation data for cattle sourcing under EU Renewable Energy Directive III. These buyers command the longest contract tenors and pay premiums for verified low-carbon intensity.
- Cosmetics:Personal care formulators utilizing enzymatically interesterified tallow esters for emollient applications. German and Dutch specialty chemical firms drive adoption of modified tallow with custom fatty acid profiles.
- Food Industry:Edible-grade applications including shortening and frying fats. FDA and USDA inspection requirements constrain supply to integrated meatpackers with captive rendering operations.
- Pharmaceuticals:Excipient and active ingredient applications demanding highest purity grades. Limited volume segment with stringent documentation requirements.
Food Industry holds the incumbent position. Biofuels is gaining share fastest.
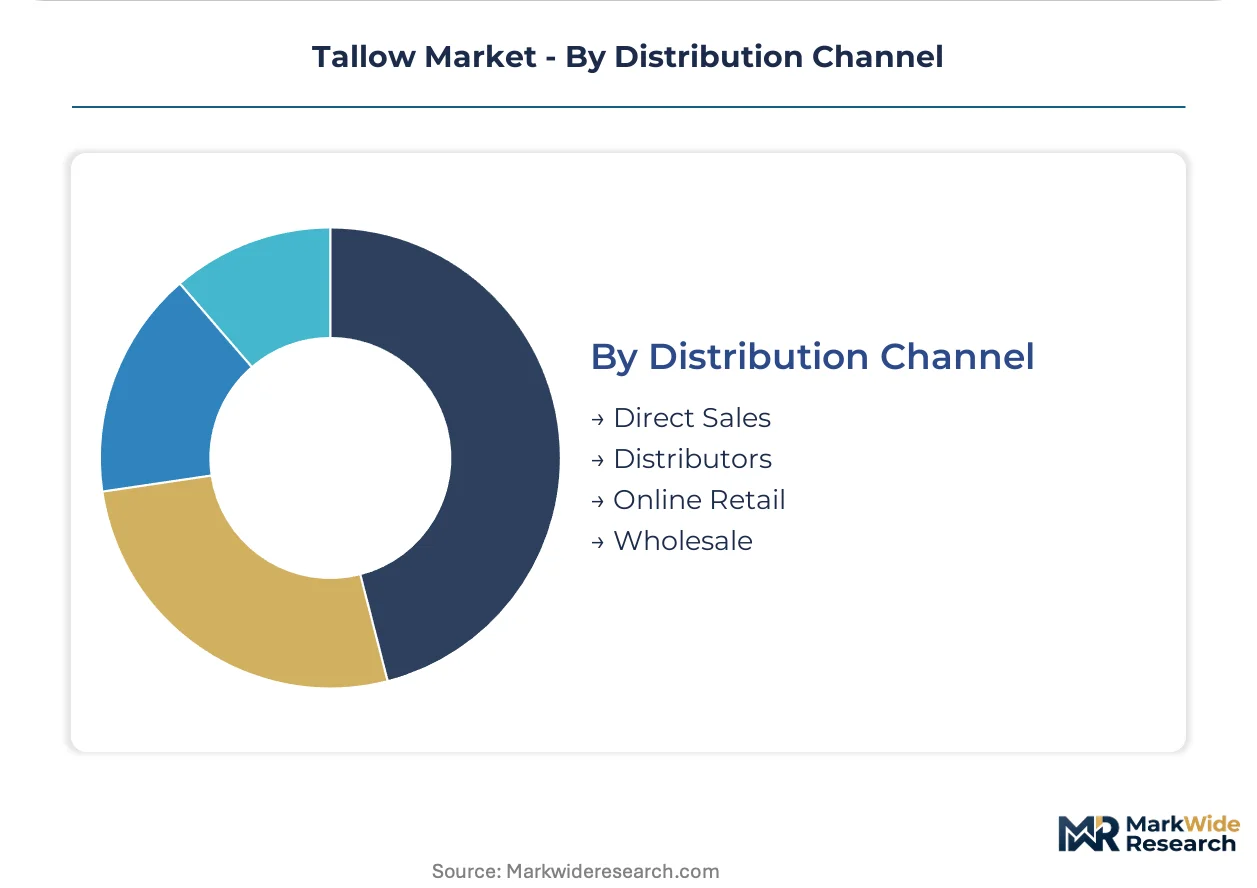
Distribution Channel:
Channel structure tracks the collapse of traditional fat broker intermediation as large buyers pursue supply security through direct relationships.
- Direct Sales:Long-term offtake contracts between integrated renderers and renewable diesel producers. This channel captures the majority of North American biodiesel feedstock procurement.
- Distributors:Regional fat brokers serving smaller oleochemical processors and animal feed compounders. Spot market liquidity is compressing as certified supply concentrates in direct channels.
- Wholesale:Bulk commodity trading for technical-grade applications with lower traceability requirements. Traditional merchant pricing still governs this channel.
- Online Retail:Niche channel for specialty cosmetic and artisanal soap-making ingredients. Limited volume but expanding access for small-scale buyers.
Wholesale maintains the broadest reach. Direct Sales is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Union Pacific rail network links Nebraska and Iowa meatpacking corridors to Gulf Coast renewable diesel refineries, underwriting United States tallow procurement dominance. Port infrastructure at Rotterdam and Hamburg channels European feedstock flows toward oleochemical refineries.
United States
EPA Renewable Fuel Standard credits and California LCFS carbon intensity scoring pull Midwest rendering output toward West Coast and Gulf Coast hydrotreaters. Tyson Foods and JBS rendering divisions negotiate direct 5-7 year offtake agreements with renewable diesel producers. Nebraska and Iowa meatpacking clusters concentrate wet rendering capacity within 200 miles of major feedstock sources.
Germany
EU Green Deal carbon border adjustments penalize petrochemical-derived fatty acids, redirecting surfactant demand toward ISCC-certified tallow. ECHA REACH compliance and F-Gas Regulation restrictions on fluorinated gases compress industrial lubricant applications. The Ruhr industrial corridor hosts specialty chemical firms adopting enzymatically modified tallow esters for biodegradable metalworking fluids.
Netherlands
Rotterdam port infrastructure enables bulk tallow imports for European oleochemical refineries seeking mass-balance certified feedstock. EU Renewable Energy Directive III mandates satellite-linked geolocation data for cattle sourcing, pressuring traceability system investments. Amsterdam specialty chemical clusters drive enzymatic interesterification adoption for custom fatty acid profiles.
Australia
Queensland and New South Wales sheep processing generates mutton tallow for specialty lubricant applications. Australian Tallow Producers supply biodegradable metalworking fluid manufacturers in Germany and the Netherlands. Melbourne rendering facilities export technical-grade product to Southeast Asian soap manufacturers offsetting palm oil sustainability concerns.
Brazil
JBS S.A. integrated meatpacking and rendering operations supply domestic biodiesel blenders and export markets. Brazilian national biofuel policies create demand for low-carbon intensity feedstocks with verified chain-of-custody documentation. São Paulo state industrial corridors concentrate fatty acid refining infrastructure serving Latin American surfactant plants.
Tallow Market Competitive Landscape
On the supply side, the industry is consolidating around integrated meatpackers with captive rendering operations and independent renderers with ISCC certification infrastructure. Four processors control approximately 70% of North American edible and inedible output, creating tiered supply access. Strategic archetypes include protein-integrated renderers, independent specialty chemical suppliers, and regional merchant renderers. Dominant competitive moves encompass backward integration into slaughterhouse operations and 5-7 year direct offtake contracting with renewable diesel producers.
Within the protein-integrated tier, Tyson Foods Inc. and JBS S.A. exemplify archetypes leveraging captive slaughterhouse supply to secure long-term biodiesel feedstock contracts. Darling Ingredients Inc. occupies a distinct position as an independent renderer with North American network scale. SARIA SE & Co. KG represents the European specialist archetype, supplying ISCC-certified feedstock to oleochemical refineries under EU Green Deal compliance frameworks.
| Leading Market Players |
|---|
| Tyson Foods Inc. |
| Wilmar International Limited |
| Darling Ingredients Inc. |
| Vantage Specialty Chemicals, Inc. |
| BASF SE |
| Cargill, Incorporated |
| JBS S.A. |
| Australian Tallow Producers |
| SARIA SE & Co. KG |
| Others |
Value Network & Pricing Analysis
Regulatory chokepoint exposure through EU Renewable Energy Directive III traceability mandates determines both ISCC certification premium spreads and supply chain consolidation toward integrated meatpackers with captive veterinary documentation systems.
Pricing Analysis
Volume-discount tiering separates long-term offtake contracts from spot market transactions. Pricing stratifies across ISCC-certified premium grades, standard technical-grade, and economy feedstock tiers based on carbon intensity verification and chain-of-custody documentation. Cost compression in the certified premium tier is intensifying as renewable diesel producers consolidate procurement relationships with four dominant processors. Merchant spot buyers in animal feed applications exhibit highest price sensitivity, while Gulf Coast hydrotreaters demonstrate lowest sensitivity due to LCFS credit economics.
Supply Chain Analysis
Export-control regime limitations on rendering technology transfers constrain capacity expansion in Southeast Asian markets. Supply concentrates in the United States, Germany, and Brazil, with raw material flows drawing from Nebraska-Iowa meatpacking corridors, Ruhr industrial rendering clusters, and São Paulo protein processing zones. Single-source vulnerability runs through Union Pacific rail links connecting Midwest rendering output to Gulf Coast refineries. Distribution runs through direct sales channels for certified biodiesel feedstock and regional distributors for technical-grade applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against used cooking oil and distillers corn oil feedstocks commanding superior California LCFS carbon intensity scores.
For Market Incumbents: Entrench supply security through backward integration into slaughterhouse operations and ISCC certification infrastructure investment. Defend against UCO displacement by anchoring long-term offtake agreements with fixed carbon intensity baselines. Priority lever: traceability system deployment capturing satellite-linked geolocation data. For New Entrants and Emerging Players: Southeast Asian surfactant plants present the most penetrable white-space opportunity as palm oil sustainability controversies redirect procurement. Target Indonesian and Malaysian oleochemical refineries seeking certified tallow imports. Go-to-market angle: mass-balance certified feedstock with EU Green Deal compliance documentation. For Investors and Strategic Acquirers: Independent mid-scale renderers lacking certification infrastructure represent the acquisition target archetype. Long-term viability hinges on regulatory compliance capex conversion into premium offtake contract access. Signal to watch: California LCFS methodology revisions altering carbon intensity benchmarking for competing feedstocks.| Strategic Initiative | Industry Significance |
|---|---|
| ISCC Certification Investment | Mass-balance documentation systems unlock premium renewable diesel offtake terms under EPA and California frameworks. |
| Backward Integration into Rendering | Captive slaughterhouse supply secures long-term biodiesel feedstock contracts with verified chain-of-custody. |
| Enzymatic Interesterification Scale-Up | Custom fatty acid profile capability penetrates German and Dutch specialty lubricant and surfactant markets. |
| Direct Offtake Contracting | Five-to-seven year supply commitments with fixed carbon intensity baselines displace spot market merchant channels. |
| Southeast Asia Export Expansion | Certified tallow shipments to Indonesian and Malaysian refineries capitalize on palm oil sustainability displacement. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with rendering plant managers, renewable diesel procurement leads, oleochemical refinery technical directors, and EU regulatory compliance officers; and secondary validation through EPA Renewable Fuel Standard filings, California Air Resources Board LCFS data, EU ISCC certification registries, and SEC disclosures from integrated protein processors. Bottom-up volume triangulation across wet and dry rendering capacity combined with top-down demand segmentation across biodiesel, surfactant, and lubricant applications.
Forecast inputs considered product type segmentation by rendering method and fatty acid profile, application segmentation across biodiesel production and oleochemical manufacturing, end-user segmentation between biofuels and personal care formulators, and distribution channel evolution from merchant spot to direct offtake contracting. CAGRs were derived through regression analysis against regulatory credit pricing and feedstock carbon intensity scoring methodologies across the projection horizon. Industry-specific inputs included EPA RIN price trajectories and EU carbon border adjustment mechanism implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by protein-integrated processors would shift outcomes. Material shifts in California LCFS carbon intensity benchmarking methodologies or EU Renewable Energy Directive verification requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Benzotrifluoride Market
Bulk Chemicals
Mancozeb Market
Bulk Chemicals
Global Lithium Fluoride Market
Bulk Chemicals
United States Calcium Chloride Market
Bulk Chemicals
Bromacil Market
Bulk Chemicals
Bio Based Paraxylene Market
Bulk Chemicals
Global Lithium Derivatives Market
Bulk Chemicals
Barium Nitrate Market
Bulk Chemicals
Asia-Pacific Choline Chloride Market
Bulk Chemicals
Global Chlorinated Paraffin Wax Market
Bulk Chemicals
Soda Ash Market
Bulk Chemicals
Sodium Gluconate Market
Bulk Chemicals
Putty Powder Market
Bulk Chemicals
North America Lime Market
Bulk Chemicals
Titanium Dioxide Market
Bulk Chemicals
Copper (II) Carbonate Basic Market