
 Oman Major Home Appliances Market | 2026-2036
Oman Major Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Major Home Appliances Market Analytics
Young professional households migrating to apartment complexes in Muscat is bifurcating demand away from extended-family villa buyers. LG Electronics anchors its position through direct showroom investments along the Sultan Qaboos Highway corridor. Samsung Electronics differentiates via smart kitchen ecosystems that integrate with regional IoT platforms. Haier Group Corporation competes aggressively on washing machine capacity tiers tailored to Omani household sizes.
Major home appliances encompass electrically powered durable goods designed for residential domestic functions, typically operating on 230V/50Hz single-phase supply with rated capacities from 100L compact refrigerators to 16kg front-load washers, fabricated from cold-rolled steel, ABS plastics, and copper-wound compressor motors. Their primary purpose is to automate food preservation, garment cleaning, thermal comfort, and meal preparation within household settings. Refrigerators occupy the largest revenue pool due to replacement cycles shortened by coastal humidity corrosion, while air conditioners represent the fastest-expanding category as summer peak loads intensify across Oman's interior governorates. Smart appliances still trail traditional units in volume but command disproportionate margin attention from distributors.
The Authority for Electricity Regulation enforces minimum energy performance standards that filter out low-efficiency imports, while Oman's Consumer Protection Authority monitors warranty compliance and after-sales service obligations. The Ministry of Commerce, Industry and Investment Promotion oversees product safety certifications aligned with GCC standardization requirements. Stakeholders must track how upcoming building code revisions for new developments mandate pre-installed appliance specifications before committing procurement contracts.
Market Dynamics
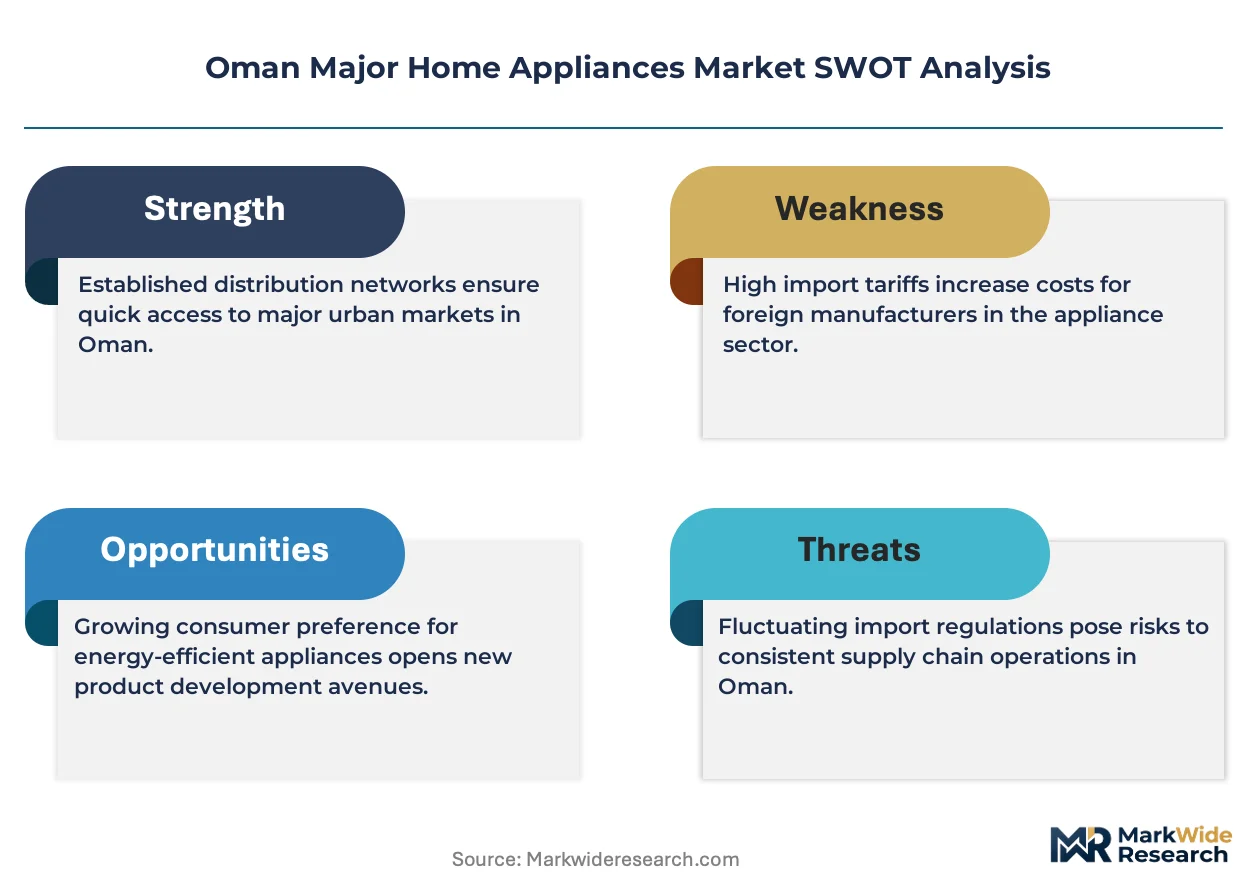
Oman's Authority for Electricity Regulation is compressing the import window for low-efficiency appliances, forcing distributors to requalify entire supplier portfolios around inverter compressor technology and A+++ certification thresholds.
Growth Catalysts
- Building code pre-installation mandates:New residential compounds in Muscat Governorate now require developer-fitted kitchen and cooling packages before occupancy permits issue.
- Inverter air conditioner uptake:Peak load intensity across interior governorates is accelerating replacement cycles for fixed-speed units with variable refrigerant flow systems.
- Coastal humidity corrosion:Shortened refrigerator lifespans in Salalah and Sur are generating above-trend replacement demand for corrosion-resistant cabinet designs.
Market Restraints
- Copper and cold-rolled steel input volatility:Compressor motor fabrication costs fluctuate with commodity exchange pricing, squeezing assembler margins on entry-tier units.
- Single-port logistics concentration:Port Salalah and Sohar handle over ninety percent of appliance imports, creating bottleneck exposure during monsoon disruption windows.
- Smart appliance interoperability gaps:Fragmented regional IoT protocols limit ecosystem integration, suppressing premium-tier volume expansion.
Strategic Opportunities
- Dhofar Governorate penetration:Salalah's apartment construction pipeline remains undersupplied relative to Muscat, offering first-mover positioning for showroom networks.
- After-sales service unbundling:Independent repair certification programs can capture warranty expiration work currently defaulted to manufacturer channels.
- Energy efficiency incentive alignment:The Authority for Electricity Regulation's rebate framework for A+++ rated cold appliances creates margin-accretive upgrade pathways.
Industry Challenges
- Inverter compressor technician scarcity:Variable-speed refrigeration systems require specialized diagnostic training absent from standard vocational curricula.
- GCC certification timeline compression:Product safety testing at approved laboratories creates six-to-eight week launch delays for new model introductions.
- Legacy voltage stabilization integration:Grid fluctuation protection hardware adds cost and installation complexity in interior governorates with weaker infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Major Home Appliances Market |
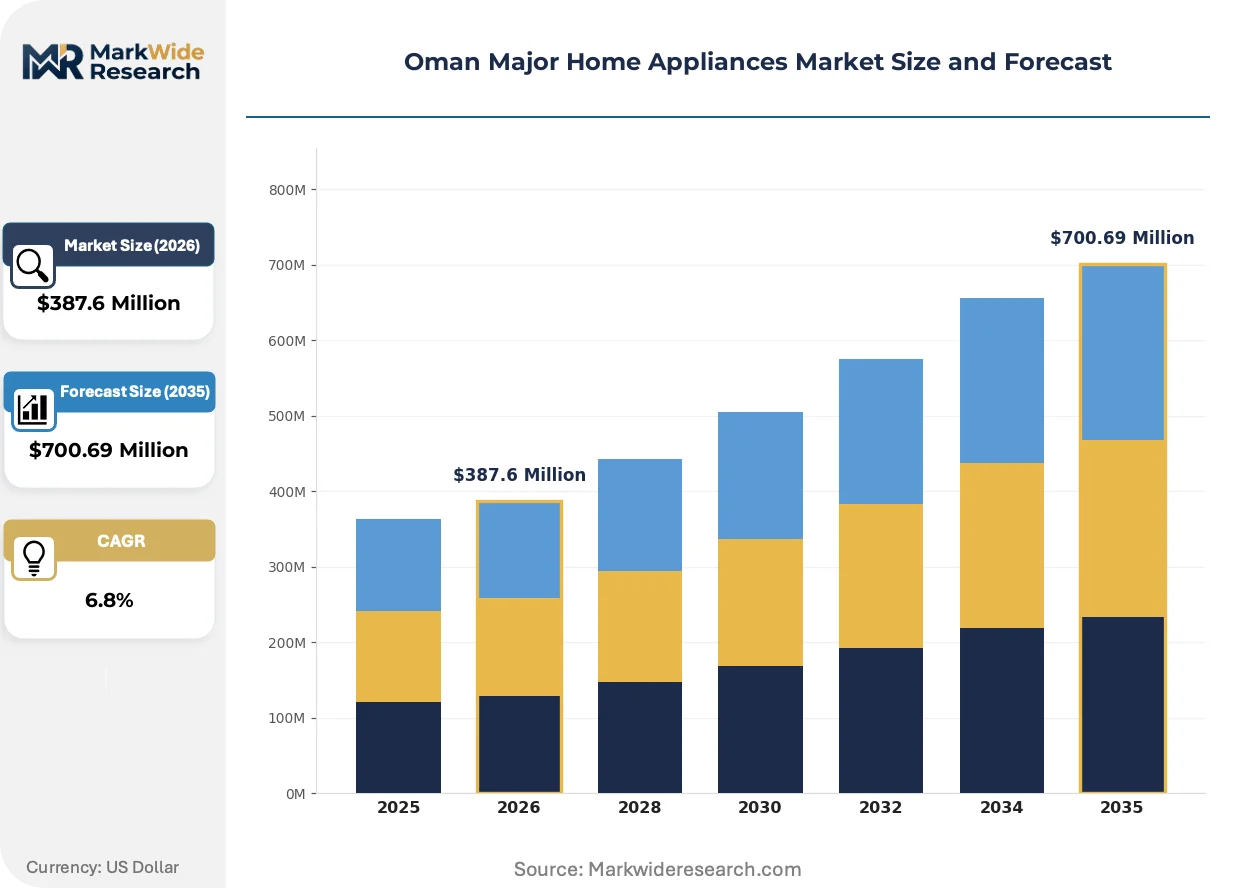
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Air Conditioners, Ovens Technology: Smart Appliances, Energy-Efficient, IoT-Enabled, Traditional End User: Residential Users, Commercial Establishments, Retailers, Property Developers Sales Channel: Direct Sales, Online Retail, Showrooms, Distributors |
| Companies Covered | Bosch, Haier Group Corporation, LG Electronics, Hitachi, Electrolux AB, Samsung Electronics, Panasonic Corporation, Midea Group, Whirlpool Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Major Home Appliances Market Evolving Landscape
Appliance functionality is splitting along household structure lines, with technology portfolios diverging between compact nuclear-family units and extended-family capacity configurations. Three forces are actively restructuring competitive positioning.
Inverter-driven variable refrigerant flow technology is bifurcating the air conditioner category. Young professional households in Muscat's apartment towers are specifying compact wall-mounted units with smartphone-linked climate scheduling. Extended-family villa buyers in Seeb and Al Amerat continue procuring high-tonnage ducted systems. This split is compressing mid-range fixed-speed inventory at distributor warehouses.
The Authority for Electricity Regulation's minimum energy performance standards are filtering import flows at Omani customs checkpoints. Non-compliant stock is being redirected to neighboring markets with weaker enforcement. Refrigerator and air conditioner categories face the steepest compliance curves, with local distributors accelerating supplier transitions ahead of phase-in deadlines.
Young professional household formation patterns are fragmenting traditional extended-family procurement channels. Apartment complex developers in Ghubrah and Bausher now specify built-in appliance packages as standard fit-outs. Independent retail showrooms along Sultan Qaboos Highway are losing volume to project-direct contracts, forcing margin compression on residual walk-in trade.
Oman Major Home Appliances Market Segmentation
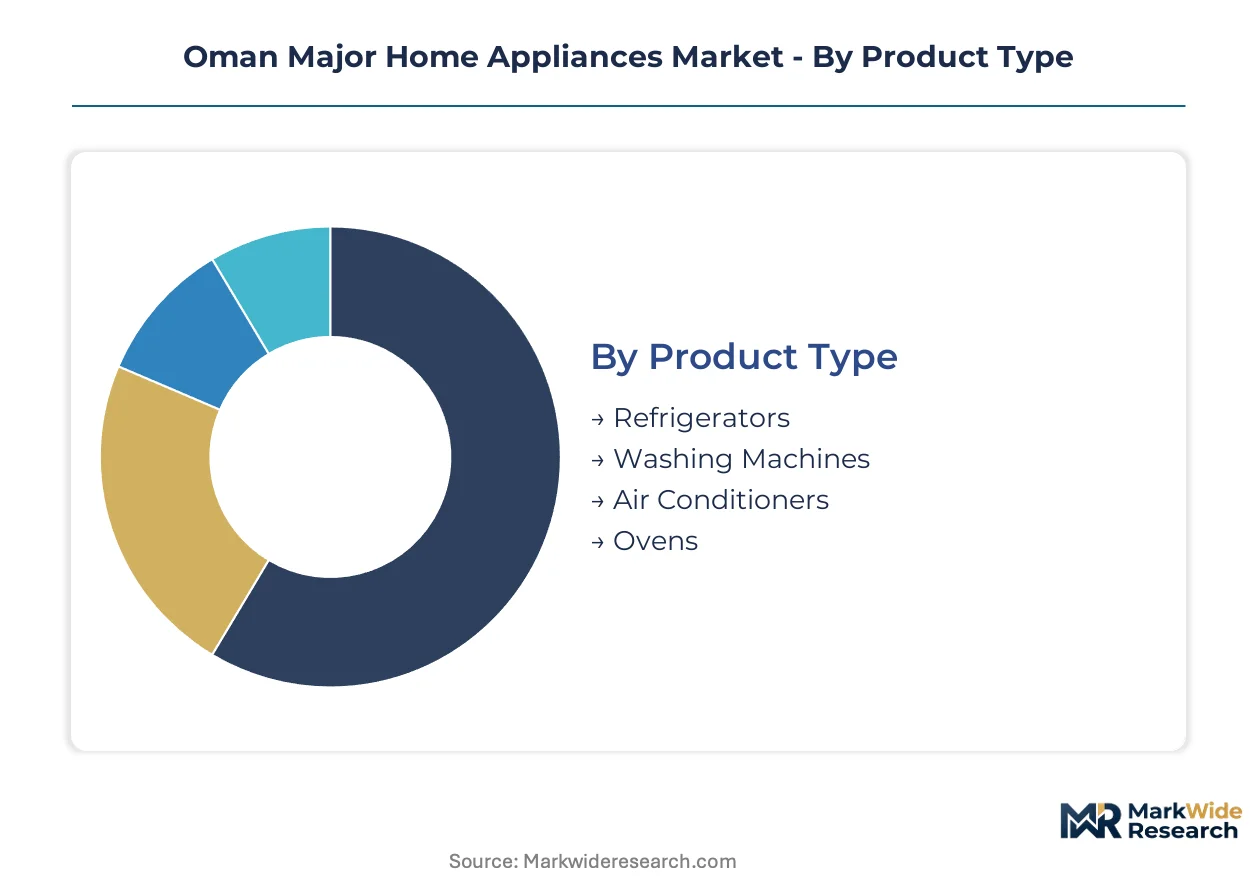
Segmentation in the Oman market tracks how Authority for Electricity Regulation mandates reshape procurement patterns across product tiers and buyer categories. Channel flows diverge sharply between project-direct developer contracts and residual retail walk-in trade.
Product Type:
Channel-mix varies by cooling load intensity and replacement cycle urgency, with coastal corrosion shortening refrigerator lifespans and interior heat spikes accelerating air conditioner turnover.
- Refrigerators:Cold-rolled steel cabinets with copper-wound compressor motors dominate, though coastal humidity in Salalah and Sur drives demand for corrosion-resistant finishes. Property developers in Muscat Governorate specify built-in units as standard fit-outs for new apartment compounds.
- Air Conditioners:Inverter-driven variable refrigerant flow systems are displacing fixed-speed inventory at distributor warehouses. Peak load intensity across interior governorates accelerates replacement cycles, with young professional households in Muscat's apartment towers specifying compact wall-mounted units with smartphone-linked climate scheduling.
- Washing Machines:Capacity tiers align with Omani household size patterns, with front-load designs gaining preference in nuclear-family apartments.
- Ovens:Built-in electric models flow through developer-direct channels for new residential compounds.
By volume, refrigerators lead. By growth pace, air conditioners are climbing the fastest.
Technology:
Cost tier stratification separates premium-certified units from entry-tier imports, with compliance thresholds filtering non-conforming stock at customs checkpoints.
- Energy-Efficient:A+++ rated cold appliances and inverter compressor systems qualify for Authority for Electricity Regulation rebate frameworks, creating margin-accretive upgrade pathways for distributors. These units concentrate in Muscat Governorate's premium residential developments.
- Smart Appliances:Smartphone-linked climate scheduling and kitchen ecosystem integration command disproportionate margin attention despite trailing traditional units in volume. Fragmented regional IoT protocols limit ecosystem penetration.
- IoT-Enabled:Remote diagnostic capability appeals to property developers seeking reduced maintenance overhead for rental portfolios.
- Traditional:Fixed-speed refrigeration and non-inverter cooling units face compressed import windows as minimum energy performance standards phase in.
By installed base, traditional units dominate. By margin expansion, energy-efficient models are gaining share fastest.
End User:
Customer type determines contract structure, with bulk procurement from property developers displacing fragmented extended-family purchasing patterns.
- Property Developers:Building code pre-installation mandates for new residential compounds in Muscat and Salalah require developer-fitted kitchen and cooling packages before occupancy permits issue. This channel captures volume at compressed margins.
- Residential Users:Young professional households migrating to apartment complexes in Ghubrah and Bausher drive specification shifts toward compact, technology-integrated units.
- Commercial Establishments:Hotels and hospitality operators in Dhofar Governorate source high-tonnage ducted cooling systems.
- Retailers:Independent showrooms along Sultan Qaboos Highway face volume erosion as project-direct contracts capture bulk demand.
By transaction count, residential users lead. By contract value, property developers show the steepest expansion trajectory.
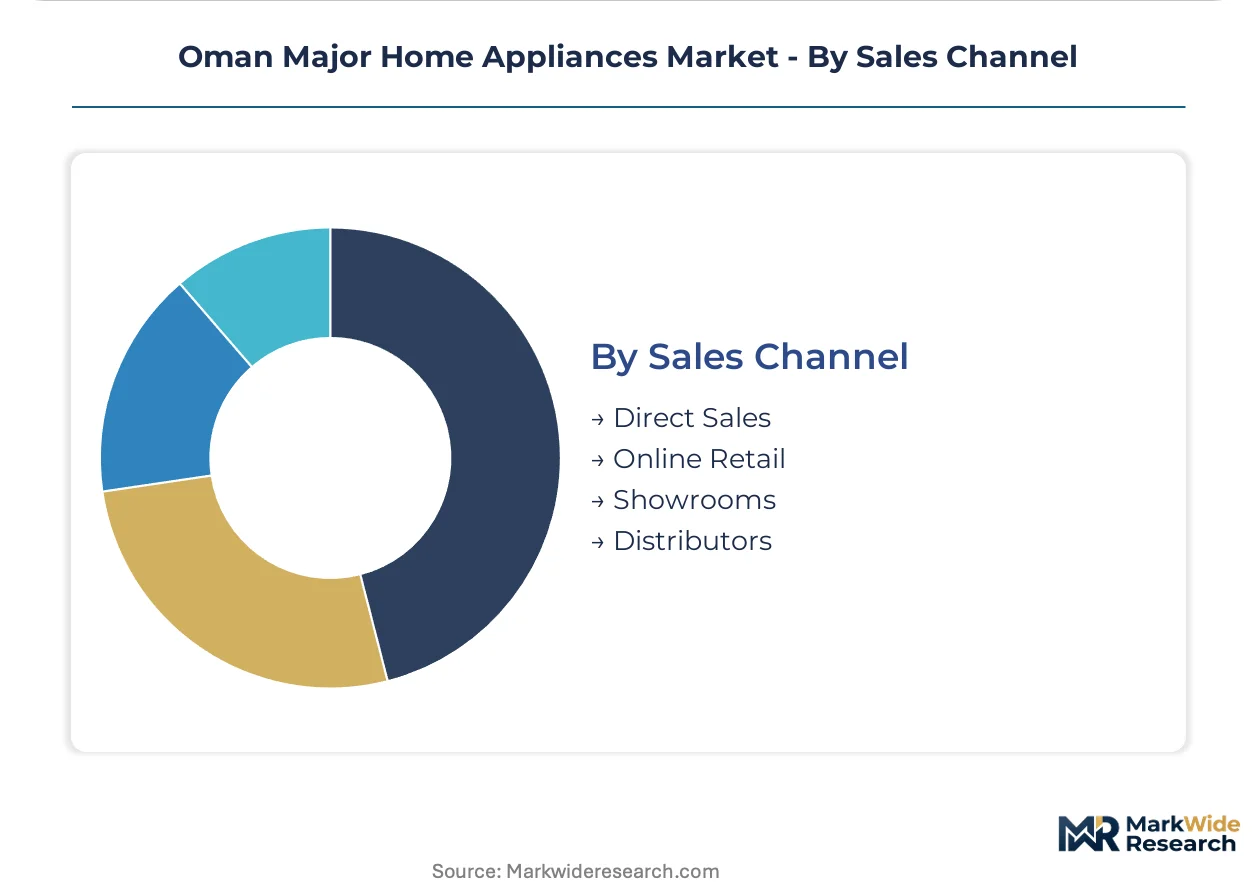
Sales Channel:
Geographic concentration shapes channel viability, with showroom networks undersupplied in Dhofar Governorate relative to Muscat.
- Direct Sales:Manufacturer-direct contracts with property developers eliminate distributor margins for bulk new-construction procurement. LG Electronics anchors this channel through investments along the Sultan Qaboos Highway corridor.
- Showrooms:Premium positioning targets extended-family villa buyers in Seeb and Al Amerat with high-tonnage ducted systems and built-in kitchen packages.
- Distributors:Handle inventory for residual walk-in trade and after-sales service fulfillment, though monsoon disruptions at Port Salalah and Sohar create bottleneck exposure.
- Online Retail:Compact appliance categories with standardized specifications see modest traction among young professional households.
By revenue contribution, direct sales lead. By network expansion urgency, showrooms in undersupplied governorates are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import flows concentrate through Port Salalah and Sohar, with over ninety percent of appliance volumes clearing through these two maritime gateways. Monsoon disruptions at these ports create seasonal bottleneck exposure that reshapes inventory positioning across interior governorates.
Muscat Governorate
Young professional households in Ghubrah and Bausher apartment complexes drive specification shifts toward compact, technology-integrated units. The Authority for Electricity Regulation enforces minimum energy performance standards that filter non-compliant imports at customs checkpoints. Direct sales channels from manufacturer showrooms along Sultan Qaboos Highway corridor capture bulk procurement from property developers fitting built-in kitchen and cooling packages.
Dhofar Governorate
Salalah's apartment construction pipeline remains undersupplied relative to Muscat, generating first-mover opportunities for showroom network expansion. Coastal humidity corrosion shortens refrigerator lifespans, accelerating replacement demand for corrosion-resistant cabinet designs. Hotels and hospitality operators in this southern region source high-tonnage ducted cooling systems for commercial establishments.
Al Batinah Governorate
Extended-family villa buyers in Seeb and Al Amerat continue procuring high-capacity appliances suited to larger household structures. Building code pre-installation mandates for new residential compounds require developer-fitted packages before occupancy permits issue. Distributor warehouses in this northern coastal zone face compressed mid-range fixed-speed inventory as inverter-driven systems displace legacy stock.
Ad Dakhiliyah Governorate
Peak load intensity across interior summer conditions accelerates air conditioner replacement cycles for fixed-speed units. Grid fluctuation protection hardware adds installation complexity in zones with weaker infrastructure stability. Independent repair certification programs target warranty expiration work currently defaulted to manufacturer channels.
Ash Sharqiyah Governorate
Sur's coastal exposure generates above-trend refrigerator replacement demand due to salt-air corrosion degradation. Port Sohar's logistics concentration creates vulnerability during seasonal disruption windows that affect inventory replenishment timing. Young household formation patterns in emerging residential zones fragment traditional extended-family procurement channels.
Oman Major Home Appliances Market Competitive Landscape
Concentration sits with diversified electronics conglomerates that leverage integrated supply chains and brand equity across multiple appliance categories. The vendor base spans three distinct tiers: premium-positioned innovators, scale-driven volume players, and regional specialists targeting price-sensitive segments. Strategic moves center on showroom network expansion along high-traffic corridors and direct developer contract capture for new construction fit-outs. Technology licensing partnerships and after-sales service unbundling represent the dominant competitive vectors.
Among the diversified electronics conglomerates, LG Electronics and Samsung Electronics anchor premium positioning through investments in direct retail presence and smart ecosystem integration. Haier Group Corporation occupies a scale-driven position emphasizing washing machine capacity tier differentiation. Bosch and Electrolux AB exemplify European-engineered positioning targeting corrosion-resistant specifications for coastal governorates. Midea Group and Whirlpool Corporation represent volume-accessible alternatives for replacement cycles in interior regions. Panasonic Corporation and Hitachi sit within the technology-licensing tier, supplying compressor and control systems to regional assemblers.
| Leading Market Players |
|---|
| Bosch |
| Haier Group Corporation |
| LG Electronics |
| Hitachi |
| Electrolux AB |
| Samsung Electronics |
| Panasonic Corporation |
| Midea Group |
| Whirlpool Corporation |
| Others |
Value Network & Pricing Analysis
Six-to-eight week GCC certification timelines at approved laboratories compress inventory positioning cycles, concentrating pricing power with distributors holding pre-qualified A+++ rated stock while squeezing margins on entry-tier units awaiting customs clearance.
Pricing Analysis
The Authority for Electricity Regulation's minimum energy performance standards dictate the pricing tier structure across the Oman Major Home Appliances Market. Three-tier pricing separates A+++ certified inverter systems from mid-efficiency fixed-speed units and non-compliant imports facing customs rejection. Price differentiation centers on energy certification grade and after-sales service bundling, with corrosion-resistant cabinet specifications commanding coastal premiums. Pricing pressure stems from copper and cold-rolled steel input volatility, compressing assembler margins on entry-tier washing machines and refrigerators. Property developers in Muscat Governorate show least price sensitivity due to bulk contract scale, while independent retail walk-in trade in interior governorates exhibits highest sensitivity to sticker-price fluctuations.
Supply Chain Analysis
Container availability constraints on Asia-Middle East trade lanes amplify inbound logistics costs during monsoon disruption windows at Port Salalah and Sohar. Manufacturing concentration rests on China, South Korea, and Thailand for compressor motors, control systems, and finished cabinet assembly. Raw material dependencies draw from copper-wound motor components, cold-rolled steel sheet, and ABS plastic resins. Single-port logistics concentration creates structural bottleneck exposure when seasonal weather patterns interrupt vessel scheduling. Distribution runs through manufacturer-direct contracts with property developers, bypassing traditional distributor markups for bulk new-construction procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Oman Major Home Appliances Market functions as a service-attach opportunity where independent repair certification programs and warranty expiration work expand faster than hardware unit sales. After-sales revenue layers now outpace appliance shipment growth in margin contribution.
For Market Incumbents: Secure technician training partnerships for inverter compressor diagnostics before vocational curriculum gaps widen. Lock corrosion-resistant cabinet supply agreements with cold-rolled steel mills facing commodity volatility. These moves defend against emerging regional assemblers and certification-timeline compression threatening first-mover positioning. For New Entrants and Emerging Players: After-sales service unbundling in Dhofar Governorate offers white-space penetration where manufacturer channels default warranty expiration work. Target Salalah's undersupplied showroom network for compact apartment-fit appliances. Pursue direct contracts with apartment developers specifying built-in packages as standard fit-outs. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates seeking to monetize non-core regional distribution assets. Long-term viability hinges on energy efficiency mandate alignment and service-network density rather than pure manufacturing scale. Watch Authority for Electricity Regulation rebate framework expansion as inflection signal for A+++ rated cold appliance demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Showroom Network Expansion | Captures first-mover positioning in Salalah's undersupplied Dhofar Governorate corridor. |
| Technician Certification Programs | Addresses inverter compressor diagnostic scarcity before vocational curriculum updates. |
| Corrosion-Resistant Product Line | Aligns cabinet specifications with coastal humidity degradation patterns in Sur and Salalah. |
| Developer Direct Contracting | Bypasses distributor margins through bulk procurement for Muscat residential compounds. |
| Energy Efficiency Rebate Alignment | Positions A+++ rated inventory for Authority for Electricity Regulation incentive frameworks. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with appliance distributor procurement heads, property developer fit-out managers, and Authority for Electricity Regulation compliance officers; and secondary validation through GCC Standardization Organization certification records, Oman Customs import manifests, and Port Salalah throughput statistics. Bottom-up triangulation cross-checked distributor inventory positioning against top-down energy efficiency mandate phase-in schedules.
Across the modeling period, the analytical framework segmented volume and value outputs by product type, technology tier, end-user contract structure, and sales channel concentration. CAGRs were derived from replacement cycle intensity patterns, coastal corrosion degradation rates, and building code pre-installation mandate adoption curves. Inverter air conditioner uptake velocity and smart appliance interoperability gaps served as category-specific forecast inputs.
Forecasts assume regulatory continuity in Authority for Electricity Regulation minimum energy performance standards and GCC certification timelines; material policy shifts accelerating phase-in deadlines or restricting import windows would require re-modeling. Commodity price volatility for copper and cold-rolled steel, monsoon disruption severity at concentrated ports, and smart appliance protocol standardization represent specific risk factors that could revise trajectory assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
North America Home Appliances Market
Home Appliances
Australia Washing Machine Market
Home Appliances
Saudi Arabia Major Home Appliances Market
Home Appliances
Europe Personal Care Appliances Market
Home Appliances
Europe Washing Machine Market
Home Appliances
White Goods Market
Home Appliances
US Household Appliances Market
Home Appliances
India Refrigerator Market
Home Appliances
Egypt Home Appliances Market
Home Appliances
Brazil Laundry Appliances Market
Home Appliances
Mexico Home Appliances Market
Home Appliances
France Household Appliances Market
Home Appliances
Japan Household Appliance Market
Home Appliances
Qatar Home Appliances Market
Home Appliances
Built-In Hobs Market
Home Appliances
Germany Major Home Appliance Market