
 White Goods Market | 2026-2036
White Goods Market Size, Share, and Industry Trends Forecast 2026-2036
White Goods Market Intelligence
The capital-intensity divergence between mass-market producers and specialized component suppliers is unwinding the industry’s established value chain. Large-scale manufacturers like Haier Smart Home and Midea Group achieve significant economies of scale through massive production volumes. Conversely, Robert Bosch GmbH sustains a strong position by supplying high-performance motors and control units to multiple brands. Whirlpool Corporation navigates this by balancing its global brand portfolio with localized product features.
White goods are major household appliances used for routine domestic tasks such as refrigeration, laundering, and cooking. Functionally, these products are defined by long service lives and specific energy efficiency ratings, such as the standards required for Energy Star certification. The refrigerators product category continues to dominate market value, but smart technology integration is driving rapid growth in washing machines and dishwashers. Sales through Online Retailers are expanding quickly, challenging the traditional dominance of Specialty Stores for these high-consideration appliance purchases.
Product design and market access are governed by stringent energy performance standards set by bodies like the U.S. Department of Energy and the European Commission under its Green Deal framework. In China, national GB standards for energy consumption and MEE regulations on refrigerant use further shape manufacturing specifications. Manufacturers must now decide whether to engineer products for a single global standard or customize them to meet diverging regional energy and connectivity protocols.
Market Dynamics
The primary structural force shaping the white goods market is the tension between achieving global economies of scale and meeting divergent regional regulations. Manufacturers face a critical choice: design a single global product platform or customize appliances for disparate energy, safety, and connectivity standards.
Growth Catalysts
- Urbanization in Emerging Economies:Rapid urbanization and an expanding middle class in countries like India and Brazil are creating new households, which require first-time purchases of essential appliances like refrigerators and washing machines.
- Energy Efficiency Mandates:Regulatory frameworks such as the EU Green Deal and its updated energy labeling requirements compel consumers to replace older, less efficient appliances, accelerating the replacement cycle.
- Property Developer Segment:Large-scale residential and commercial construction projects require bulk procurement of appliances, providing a consistent volume-driven demand channel for manufacturers.
Market Restraints
- High Capital Intensity:The substantial capital investment required for large-scale, automated manufacturing facilities creates a high barrier to entry for new players attempting to compete on volume with established producers.
- Component Supplier Dependency:A reliance on a concentrated pool of specialized suppliers for critical components like high-performance motors and advanced control units creates supply chain vulnerabilities and pricing pressure.
- Diverging Regulatory Standards:Navigating a complex web of differing energy performance standards from the U.S. Department of Energy, the European Commission, and China's GB standards increases design and compliance costs.
Strategic Opportunities
- Smart Technology Integration:Extending smart features and IoT connectivity beyond refrigerators to other categories like washing machines and dishwashers creates new value propositions based on convenience, remote monitoring, and energy management.
- Direct-to-Consumer Channels:The expansion of online retail platforms offers manufacturers an opportunity to bypass traditional specialty store intermediaries, enabling direct engagement with consumers and capturing higher margins.
- Circular Economy Models:Designing products for repairability, modularity, and remanufacturing aligns with emerging regulations like the EU's 'Right to Repair' and appeals to environmentally conscious consumer segments.
Industry Challenges
- Supply Chain Localization:Manufacturers face the operational challenge of balancing globally scaled production with the need to customize product features and components to meet specific regional tastes and regulatory requirements.
- Connectivity Protocol Fragmentation:The absence of a universal standard for smart home connectivity forces appliance makers to support multiple, often incompatible, protocols, complicating product development and user experience.
- Long-Term Service Obligations:The extended service life of white goods requires manufacturers to maintain extensive and costly service networks and spare part inventories for many years, impacting long-term profitability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | White Goods Market |
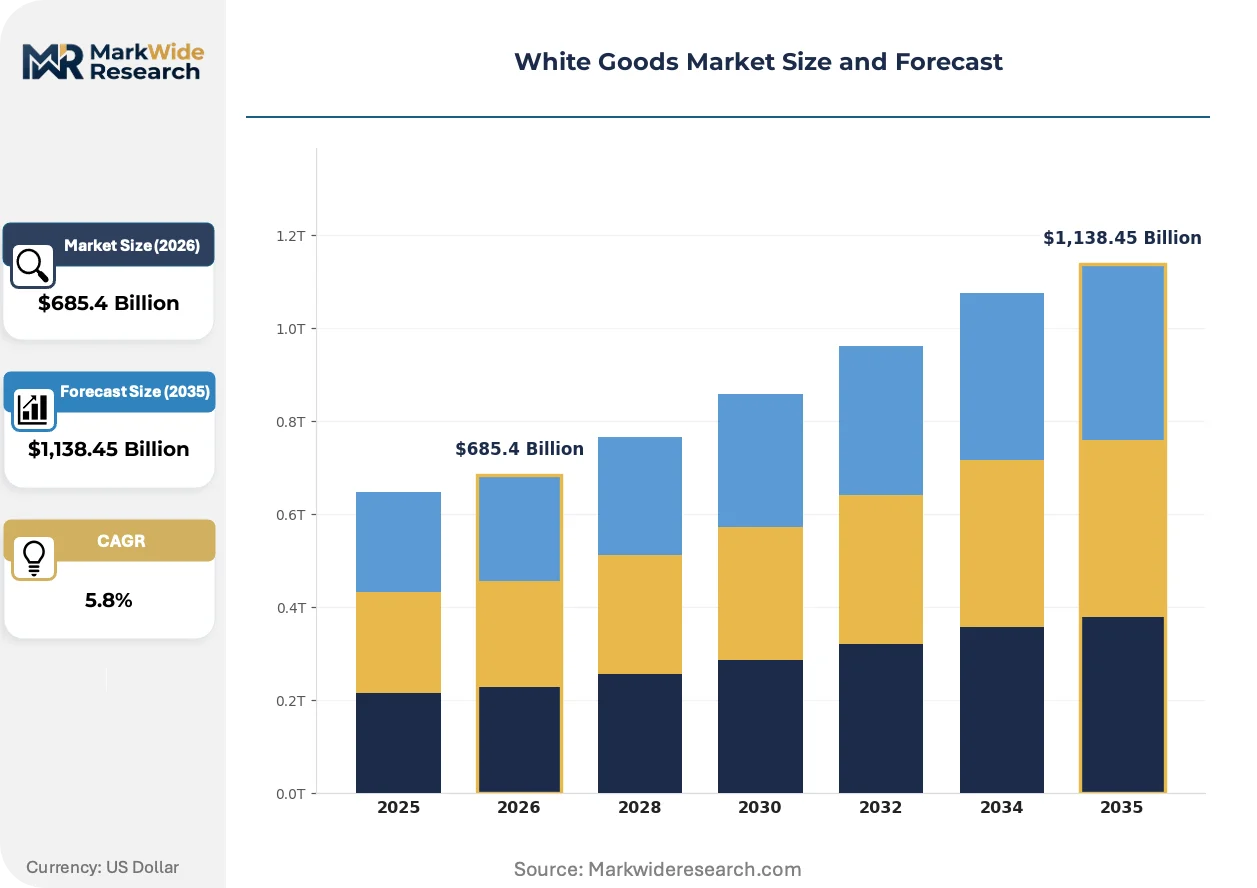
| Market Size in 2026 | $685.4 Billion |
| Market Size in 2035 | $1,138.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
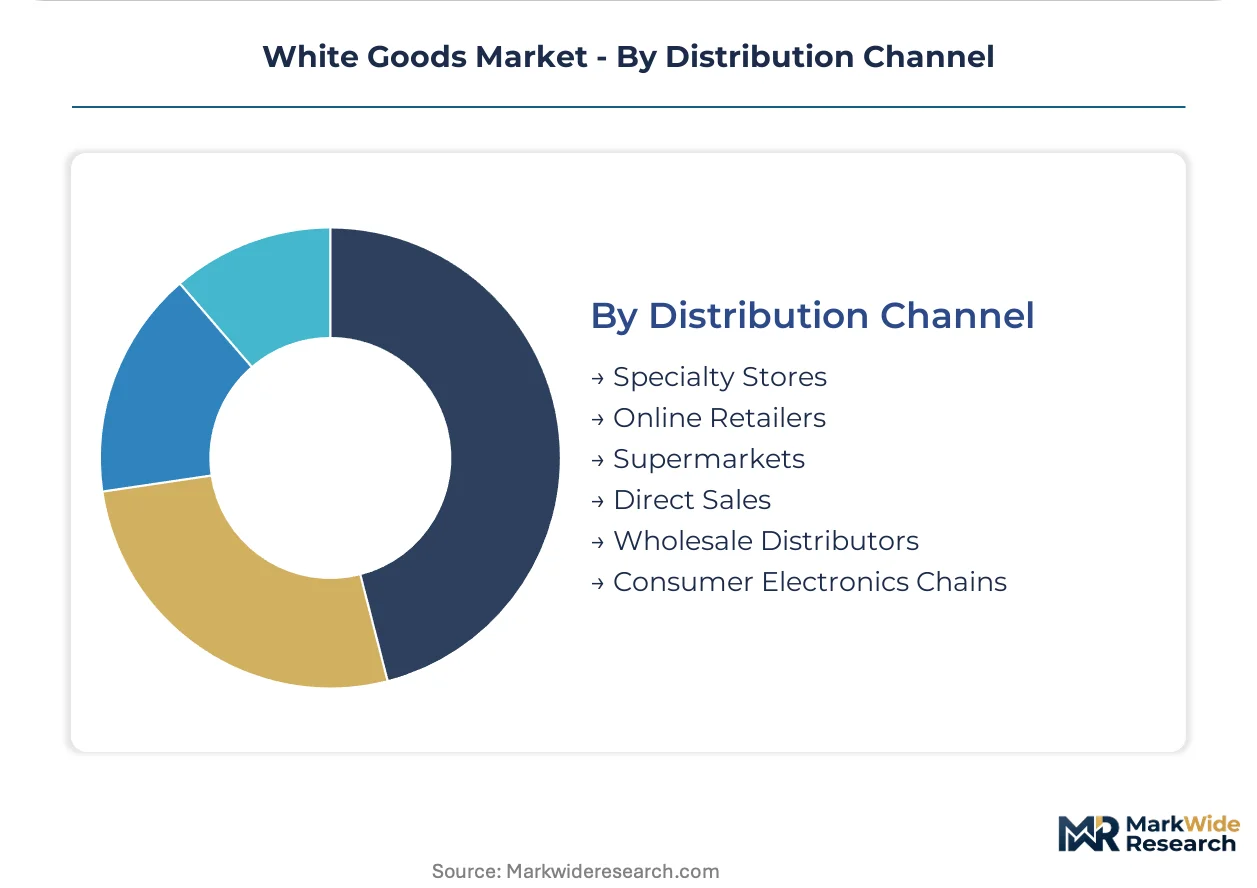
| Segmentation | Product Type: Refrigerators, Washing Machines, Dishwashers, Electric Cookers, Air Conditioners, Water Heaters Technology: Inverter, Smart, Energy Star, Wi-Fi Enabled, Touch Control, Sensor Driven End User: Households, Property Developers, Hospitality, Rental Services, Institutional Facilities, Commercial Complexes Distribution Channel: Specialty Stores, Online Retailers, Supermarkets, Direct Sales, Wholesale Distributors, Consumer Electronics Chains |
| Companies Covered | Whirlpool Corporation, Samsung Electronics Co., Ltd., LG Electronics Inc., Haier Smart Home Co., Ltd., Electrolux AB, Midea Group, Robert Bosch GmbH, GE Appliances, BSH Home Appliances, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
White Goods Market Strategic Shifts & Innovations
The market's evolution is defined by the transformation of standalone mechanical devices into connected, software-enabled assets within a broader home ecosystem. This shift is driven by a dual focus on enhanced energy efficiency and integrated user convenience, fundamentally altering product design and value.
Technology and Product Evolution
Inverter technology for compressors and motors delivers variable speed control, dramatically improving the energy efficiency of modern refrigerators and washing machines. Appliance manufacturers are rapidly adopting this technology across mid-range and premium product lines to meet stricter energy labels. This innovation is miniaturizing core mechanical components, which frees up valuable internal appliance space and enables more flexible, user-centric product designs.
Regulatory and Policy Shifts
The European Commission’s Green Deal framework, particularly its Ecodesign directive, mandates improved product repairability and longevity. This policy forces manufacturers to engineer appliances with modular components and guarantee the availability of spare parts for an extended period after sale. The refrigerator and washing machine categories are most impacted, requiring significant redesigns to ensure compliance and avoid market access restrictions.
Demand and Behavioral Shifts
Consumer purchasing behavior is moving decisively toward online channels for high-consideration appliances, extending beyond initial research to final transaction. This shift disrupts the business model of traditional specialty retailers who have historically relied on showroom consultations and bundled services. The trend is most advanced in North American and European markets, where robust e-commerce logistics and consumer trust in online purchasing are well-established.
White Goods Market Segmentation

Understanding the white goods market through segmentation clarifies the diverse forces shaping demand and supply. This analysis highlights how product innovation, technological integration, and evolving consumer preferences drive distinct growth trajectories across various categories. Each segment offers unique commercial implications for manufacturers and distributors navigating a complex global landscape.
Product Type:
The product type segmentation reveals how core appliances serve both established domestic markets and expanding international demand.
- Refrigerators:These essential cooling appliances feature advanced insulation and compressor technologies, maintaining food preservation standards. Demand concentrates in emerging economies like India, where first-time purchases for new households drive significant volume.
- Washing Machines:Modern washing machines integrate smart technology and efficient water usage, improving convenience and reducing environmental impact. Growth is particularly strong in urban centers of Brazil, as consumers upgrade to connected and energy-efficient models.
- Dishwashers:These appliances offer automated cleaning solutions for kitchenware, often incorporating sensor-driven cycles and water-saving features. Adoption rates are steadily climbing in European markets, supported by evolving lifestyle preferences.
- Electric Cookers:Electric cookers provide versatile cooking options, ranging from induction hobs to built-in ovens. Sales remain consistent across developed markets due to appliance replacement cycles.
- Air Conditioners:Air conditioners manage indoor climate control through various cooling and heating technologies. Demand surges in regions with extreme temperatures, such as Southeast Asia, driven by climate change and urbanization.
- Water Heaters:Water heaters supply hot water for domestic use, utilizing electric or gas heating elements. Regulatory pressures in China for energy efficiency influence product development and consumer choices.
Refrigerators holds the largest share; momentum sits with Washing Machines.
Technology:
Technology segmentation differentiates products based on their functional sophistication and market maturity, influencing competitive strategies.
- Smart:Smart appliances incorporate internet connectivity and AI-driven features, allowing remote control and predictive maintenance. Consumer adoption in North America is accelerating, driven by the desire for integrated home ecosystems.
- Inverter:Inverter technology provides variable motor and compressor speeds, significantly enhancing energy efficiency and reducing operational noise. This technology is becoming standard across premium and mid-range products in the EU, responding to Ecodesign directives.
- Energy Star:Energy Star certified products meet strict energy efficiency guidelines set by the U.S. Department of Energy. Manufacturers target this standard to appeal to environmentally conscious consumers and secure market access in the United States.
- Wi-Fi Enabled:Wi-Fi enabled appliances offer basic connectivity for remote monitoring and control via smartphone applications. This feature is a common upgrade in new product lines, enhancing user convenience.
- Touch Control:Touch control interfaces provide a sleek, modern aesthetic and intuitive operation for various appliance functions. These designs are popular in high-end kitchens, offering a premium user experience.
- Sensor Driven:Sensor-driven technologies automate appliance functions, such as detecting laundry soil levels or dish cleanliness. This enhances performance and efficiency, appealing to busy households seeking convenience.
Smart technology products demonstrate high market penetration, while Inverter technology continues to increase its market presence.
End User:
The end-user segmentation highlights distinct procurement patterns and demand drivers across different customer types, shaping sales strategies.
- Households:Individual consumers purchasing white goods for personal use in residential settings represent the foundational demand segment. Replacement cycles and first-time purchases in growing urban areas drive this segment.
- Property Developers:Large-scale residential and commercial construction firms procure appliances in bulk for new projects. This segment provides consistent, high-volume demand, particularly in rapidly urbanizing regions like India and Brazil.
- Hospitality:Hotels, resorts, and restaurants require durable, high-capacity appliances for commercial-grade operations. Product specifications emphasize longevity and energy efficiency for continuous use.
- Rental Services:Companies offering appliance rentals to consumers or businesses constitute a specialized end-user category. Their procurement focuses on robust, easily maintainable models with long service lives.
- Institutional Facilities:Schools, hospitals, and government buildings purchase appliances to meet specific operational requirements. Durability and compliance with safety standards are paramount for these buyers.
- Commercial Complexes:Office buildings and shopping centers require various white goods for staff facilities and tenant amenities. Energy efficiency and low maintenance are key considerations for these large-scale installations.
Households represent the largest volume segment, with Property Developers exhibiting significant strategic importance due to bulk procurement.
Distribution Channel:
Distribution channel segmentation illustrates the evolving landscape of how white goods reach consumers, influencing pricing and market access strategies.
- Online Retailers:E-commerce platforms facilitate direct consumer purchases, offering extensive product catalogs and home delivery services. This channel is rapidly expanding in North American and European markets, disrupting traditional retail models.
- Specialty Stores:Dedicated appliance showrooms provide expert consultation, product demonstrations, and installation services. These stores maintain a strong presence for high-consideration purchases, emphasizing customer service.
- Supermarkets:Large retail chains offer a limited selection of basic white goods, often as part of broader household product offerings. This channel caters to convenience-driven purchases and budget-conscious consumers.
- Direct Sales:Manufacturers engage directly with consumers through their own brand stores or online portals, bypassing intermediaries. This channel allows for greater brand control and direct customer feedback.
- Wholesale Distributors:These intermediaries supply appliances in bulk to smaller retailers, contractors, and institutional buyers. Their role is critical in logistics and inventory management for diverse market segments.
- Consumer Electronics Chains:Retailers specializing in electronics also carry a range of white goods, leveraging their existing customer base and store footprint. They often feature smart and connected appliances.
Online Retailers are rapidly gaining market share, while Specialty Stores continue to command a significant portion of high-value transactions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
White goods consumption patterns exhibit distinct regional variations, with emerging economies focusing on first-time purchases and developed markets prioritizing energy efficiency and smart technology upgrades. This consumption-mix differential influences product development and market penetration strategies across different geographies. Manufacturers must align their offerings with local demand characteristics and regulatory landscapes.
India
Urbanization and a rapidly expanding middle class drive significant first-time purchases of essential white goods like refrigerators and washing machines. The Indian government's Production Linked Incentive (PLI) scheme encourages domestic manufacturing and technological advancement. Major metropolitan areas like Delhi-NCR and Mumbai serve as critical distribution hubs and consumer markets for appliance sales.
Germany
Appliance demand in Germany centers on replacement cycles and premium, energy-efficient models, driven by strong consumer environmental awareness. The EU Green Deal and its Ecodesign directive compel manufacturers to offer highly efficient and repairable products. Bavaria hosts significant research and development centers for white goods components, influencing European product innovation.
United States
The United States market emphasizes smart home integration and appliance upgrades, with consumers seeking convenience and connectivity features. Energy Star certification, mandated by the U.S. Department of Energy, remains a critical standard for market access and consumer appeal. California leads in adopting advanced, connected appliances, reflecting a trend towards integrated home ecosystems.
China
Expanding middle-class households and rapid urbanization fuel demand for both basic and technologically advanced white goods in China. National GB standards for energy consumption and MEE regulations on refrigerant use significantly shape product specifications. The Yangtze River Delta region is a major manufacturing and innovation hub, producing a vast array of white goods for domestic and export markets.
Brazil
Brazil's white goods market benefits from ongoing urbanization and a growing middle class, leading to increased household formation and first-time appliance acquisitions. Government initiatives to improve energy infrastructure and consumer purchasing power support market expansion. São Paulo functions as a key commercial center, concentrating both consumer demand and major distribution networks for appliances.
White Goods Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the white goods market's competitive structure. This tiered landscape features global conglomerates competing on scale and brand recognition, alongside specialized component suppliers offering high-performance solutions. Strategic archetypes include diversified consumer electronics giants, dedicated appliance manufacturers, and niche technology providers. Capacity expansion and portfolio diversification are dominant competitive moves among market participants.
At the scale-driven end, Whirlpool Corporation exemplifies a global appliance manufacturer leveraging an extensive brand portfolio and localized product features. Haier Smart Home Co., Ltd. represents an integrated player focusing on smart home ecosystems and global market penetration. Robert Bosch GmbH, a German engineering and technology company, anchors the specialized component supplier segment, providing high-performance motors and control units to multiple appliance brands across the industry.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| Samsung Electronics Co., Ltd. |
| LG Electronics Inc. |
| Haier Smart Home Co., Ltd. |
| Electrolux AB |
| Midea Group |
| Robert Bosch GmbH |
| GE Appliances |
| BSH Home Appliances |
| Others |
Cost & Logistics Intelligence
Project-based contracts for bulk installations, particularly with property developers, lock in both supply access and price visibility for large-scale appliance manufacturers. This structure influences how production volumes are committed and pricing tiers are established across the market.
Pricing Analysis
Project-based pricing dominates the property developer segment, driven by volume scale and installation service bundling for new constructions. Price differentiation stems from energy efficiency certifications like Energy Star and brand premium associated with integrated smart features. Pricing softness reflects intense competition from large-scale manufacturers in mass-market segments. Households exhibit the highest price sensitivity, while hospitality buyers prioritize durability and long-term operational cost.
Supply Chain Analysis
Container availability and shipping costs on key trade lanes from Asia significantly influence the inbound logistics for white goods components. Geographic supply concentration centers on China and Southeast Asia for core manufacturing, alongside Germany for high-performance components like motors and control units. Raw material dependencies include specialized plastics, steel, and semiconductors. Single-source vulnerability for advanced control units presents a structural risk. Distribution runs through a hybrid model, balancing online retailers with traditional specialty stores for final delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market necessitates a substitution defense, as incumbents must navigate the increasing integration of smart home ecosystems that challenge standalone appliance value propositions.
For Market Incumbents: Fortify core market share by investing in modular product designs that meet EU Ecodesign directives, enhancing repairability and longevity. Expand vertical integration into critical component manufacturing to mitigate supply chain vulnerabilities, particularly for advanced control units. This strategy counters margin erosion from intense competition and strengthens market access against regulatory shifts.
For New Entrants and Emerging Players: Lead with specialized smart technology integration, targeting the rapidly expanding online retail channel for direct consumer engagement. Focus on underpenetrated categories like dishwashers in European markets, offering sensor-driven models with advanced water-saving features. This approach leverages agility to capture niche demand by emphasizing convenience and sustainability, bypassing traditional distribution barriers.
For Investors and Strategic Acquirers: Specialized component manufacturers offering high-performance motors and advanced control units present attractive acquisition targets for long-term value creation. The market's viability across the next decade rests on manufacturers' ability to integrate seamlessly into broader smart home ecosystems. A signal to watch for inflection is the widespread adoption of a universal connectivity protocol across major appliance brands.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Inverter Technology R&D | Manufacturers enhance energy efficiency and reduce operational noise, meeting stricter regulatory standards in the EU. |
| Expand Direct-to-Consumer Channels | Appliance brands gain higher margins and direct customer feedback, bypassing traditional specialty store intermediaries. |
| Develop Modular Appliance Platforms | Manufacturers improve product repairability and longevity, aligning with the EU's Ecodesign directive for market access. |
| Form Smart Home Ecosystem Partnerships | Companies extend appliance functionality and user convenience by integrating with broader connected home platforms. |
| Localize Manufacturing in Emerging Economies | Manufacturers reduce logistics costs and adapt products to specific regional tastes and regulatory requirements in India. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews with appliance engineers, retail buyers, property developers, and regulatory advisors. This primary intelligence was triangulated with extensive secondary research, drawing from national energy agency reports, trade association statistics, and customs data. A rigorous bottom-up and top-down approach ensured comprehensive market sizing and validation across all segments.
The analytical framework extends across the modeling period, segmenting the market by product type, technology, end-user, distribution channel, and regional regulatory compliance. Compound Annual Growth Rates were derived through a comprehensive analysis of historical trends and projected market dynamics. Key forecast inputs included urbanization rates in emerging economies and the stringency of energy efficiency mandates.
Underlying assumptions cover stable geopolitical trade conditions and consistent raw material supply, with deviation risk concentrated in rapid shifts in energy policy or unforeseen technological disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Household Refrigerators and Freezers Market
Home Appliances
Household Appliance Market
Home Appliances
France Home Appliances Market
Home Appliances
Sweden Laundry Appliances Market
Home Appliances
Washing Machine Market
Home Appliances
Asia-Pacific Home Appliances Market
Home Appliances
United States Major Home Appliances Market
Home Appliances
Russia Laundry Appliances Market
Home Appliances
UAE Home Appliances Market
Home Appliances
Middle East and Africa Laundry Appliances Market
Home Appliances
Qatar Major Home Appliances Market
Home Appliances
China Laundry Appliances Market
Home Appliances
Electrical Appliances Market
Home Appliances
Electric Household Appliances Market
Home Appliances
Smart Small Home Appliances Market
Home Appliances
Egypt Home Appliances Market