
 Germany Major Home Appliance Market | 2026-2036
Germany Major Home Appliance Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Major Home Appliance Market Foresight
Steel-reinforced polymer composites is pivoting from premium niches into mainstream refrigerator and dishwasher chassis production, cutting unit weight while preserving structural integrity. BSH Hausgeräte GmbH leverages its Swabian manufacturing footprint to sustain vertical control over compressor assembly lines. Miele & Cie KG anchors its position through captive testing facilities that certify cycles exceeding industry durability norms. Robert Bosch GmbH competes on sensor-integration depth, embedding moisture and load-detection arrays across its washing machine portfolio.
Germany Major Home Appliance encompasses electrically powered domestic equipment with rated capacities typically between 100 and 3,000 watts, engineered for repetitive food preservation, textile cleaning, culinary preparation, or ambient climate management within enclosed residential spaces. Refrigerators incorporating inverter compressors now dominate replacement demand as households retire units predating the EU Ecodesign Directive's 2021 rescaled efficiency tiers. Smart connectivity modules represent the fastest-expanding technology segment, though margin pools remain thicker in sensor-based load optimization systems that reduce water and electricity draw without cloud dependency. The residential housing application commands the largest volume share, while rental apartments generate steadier replacement cadences due to landlord-mandated maintenance schedules.
The KBA enforces energy-labeling accuracy for imported appliances, while the EU F-Gas Regulation phases down hydrofluorocarbon refrigerants in cooling equipment, compelling manufacturers to retool compressor architectures. Germany's Federal Ministry for Economic Affairs and Climate Action coordinates with BSI to align national efficiency benchmarks with Brussels-mandated minimum performance standards. Stakeholders must monitor how the EU's forthcoming right-to-repair obligations reshape warranty structures and spare-part availability timelines.
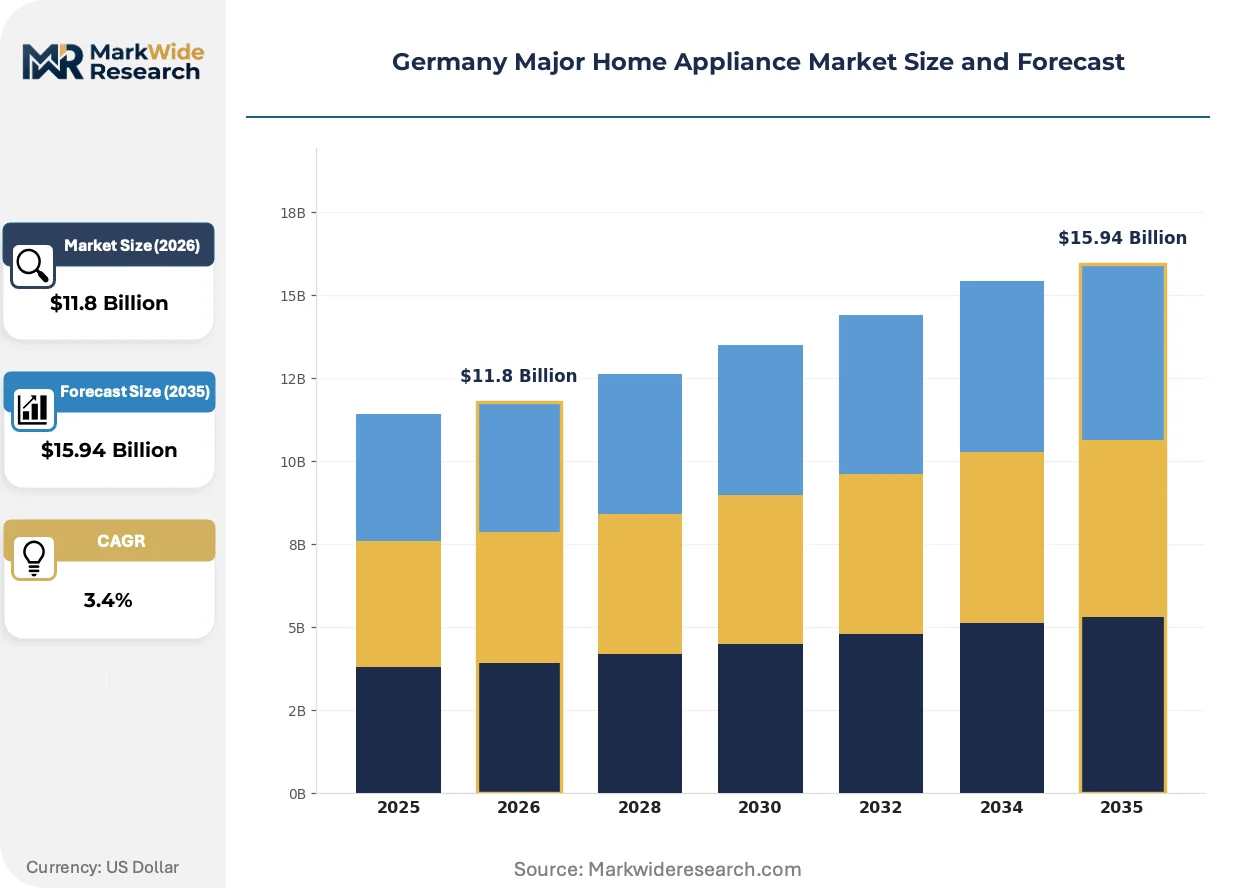
Market Dynamics
Steel-reinforced polymer composites are compressing chassis manufacturing costs while the EU F-Gas Regulation forces compressor architecture retooling across German production lines.
Growth Catalysts
- EU Ecodesign Directive:Rescaled efficiency tiers from 2021 are accelerating replacement cycles for pre-2021 refrigerator and washing machine stock in residential housing.
- Baden-Württemberg construction corridors:Metropolitan renovation activity in Stuttgart and Karlsruhe sustains elevated demand for built-in appliance configurations.
- Inverter compressor technology:Variable-speed refrigeration systems reduce electricity draw below legacy fixed-speed thresholds, aligning with Germany's Building Energy Act mandates.
Market Restraints
- Steel and copper input volatility:Compressor motor laminations and refrigerant tubing face commodity price swings that compress margin pools on mid-tier product lines.
- KBA energy-labeling enforcement:Import certification delays for non-EU manufacturers create inventory friction at German distribution hubs.
- Heat pump dryer substitution:Condensation-based drying systems lose share to heat pump alternatives that halve energy consumption in textile care.
Strategic Opportunities
- Bavaria rental housing stock:Munich and Nuremberg landlord-tenant regulations mandate scheduled appliance replacement, creating predictable refresh demand.
- Right-to-repair obligations:Forthcoming EU warranty restructuring will expand spare-part availability windows and service revenue streams.
- Sensor-cloud convergence:Moisture-detection arrays paired with local edge computing enable load optimization without full cloud dependency, reducing latency for washing machine cycles.
Industry Challenges
- Refrigerant chemistry retooling:Hydrofluorocarbon phase-down timelines compress R&D cycles for compressor seal compatibility with natural refrigerants.
- Smart module integration complexity:Legacy chassis designs require structural modification to accommodate connectivity hardware without compromising insulation performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Major Home Appliance Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $15.94 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Ovens, Dishwashers, Air Conditioners Technology: Inverter, Smart Connectivity, Energy Efficient, Sensor Based, Touch Control Application: Residential Housing, Rental Apartments, Student Housing, Vacation Homes, Serviced Apartments Distribution Channel: Online Retailers, Specialty Stores, Department Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Liebherr International Deutschland GmbH, Whirlpool Corporation, BSH Hausgeräte GmbH, Robert Bosch GmbH, LG Electronics, Miele & Cie KG, Samsung Electronics, Haier Group, Electrolux AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Major Home Appliance Market Shifts & Advancements
Material substitution and regulatory chemistry mandates are restructuring how German manufacturers configure refrigerator and dishwasher platforms.
Steel-reinforced polymer composites are electrifying chassis production by replacing stamped metal in refrigerator cabinets and dishwasher tubs. Appliance assemblers in Swabian manufacturing clusters are adopting these materials at accelerating rates to reduce unit shipping weight. This substitution is electrifying logistics cost structures while preserving structural integrity for heavy-load washing machine drums.
Germany's transposition of the EU F-Gas Regulation is mandating hydrofluorocarbon refrigerant phase-downs in cooling equipment. Compressor manufacturers must redesign seal architectures and lubrication systems to accommodate propane and isobutane alternatives. Refrigeration product lines predating 2021 face accelerated obsolescence as KBA import certification tightens around retooled efficiency benchmarks.
Landlord-mandated maintenance schedules in Bavarian and Baden-Württemberg rental housing are compressing replacement cadences for washing machines and refrigerators. Property management firms are consolidating procurement through direct manufacturer relationships, bypassing traditional retail channels. This concentration is most visible in Munich's dense apartment stock, where standardized appliance specifications reduce maintenance variance across housing portfolios.
Germany Major Home Appliance Market Segmentation
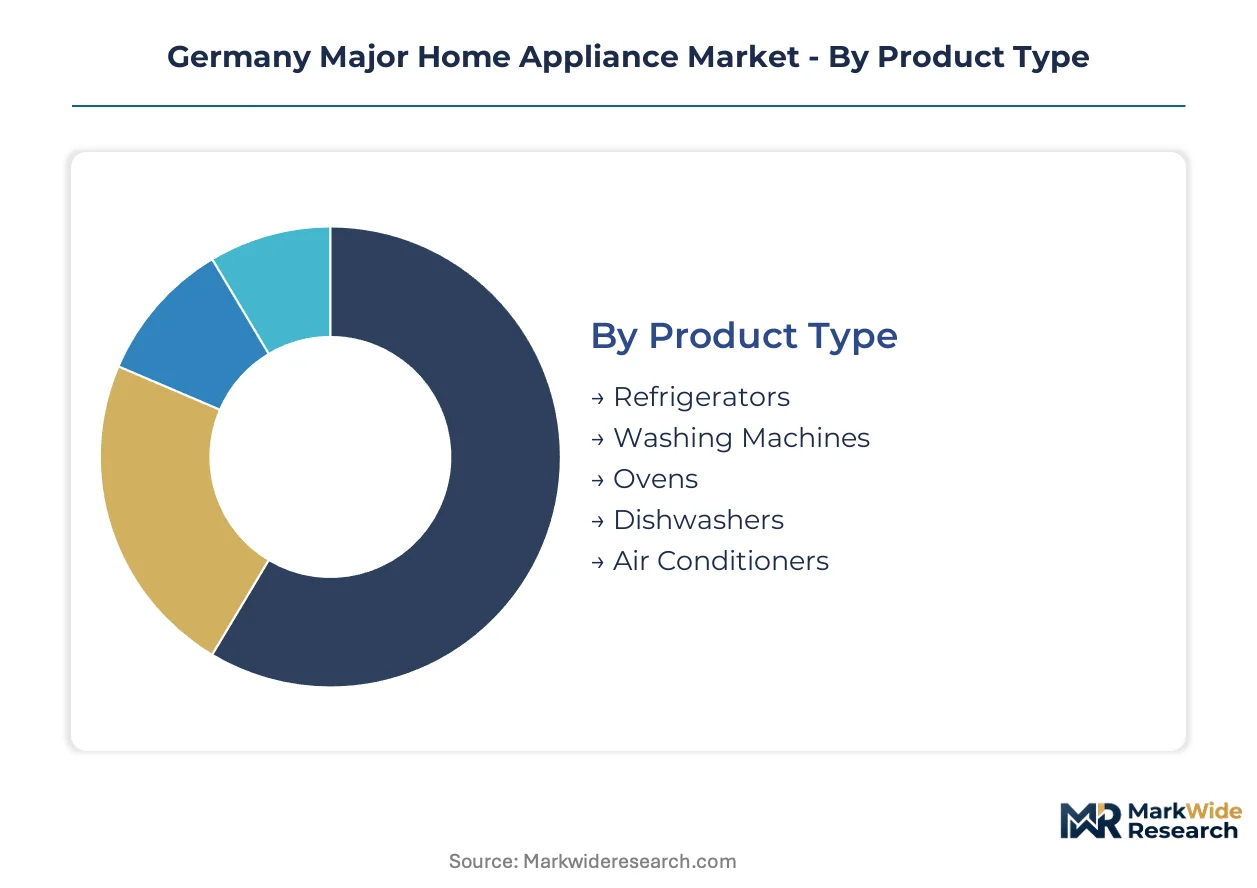
Segmentation in the Germany Major Home Appliance Market reveals how regulatory pressure, housing tenure patterns, and channel consolidation reshape procurement flows. Manufacturers configure product portfolios differently across these dimensions, with efficiency mandates and landlord-tenant frameworks acting as the primary sorting mechanisms.
Product Type:
Buyers in this category differentiate by replacement urgency driven by regulatory efficiency deadlines and housing construction cycles.
- Refrigerators:Inverter compressor systems now dominate replacement demand as households retire units predating rescaled EU Ecodesign tiers. Bavarian and Baden-Württemberg residential developments sustain elevated procurement of built-in configurations that integrate with kitchen cabinetry.
- Washing Machines:Front-loading drum systems with sensor-based load detection command premium positioning in metropolitan rental housing. Stuttgart and Munich property management firms standardize on these units to reduce water and electricity variance across apartment portfolios.
- Ovens:Pyrolytic self-cleaning variants anchor mid-tier positioning in renovation-driven southern Germany markets.
- Dishwashers:Steel-reinforced polymer composite tubs reduce unit weight for logistics efficiency while maintaining structural integrity under thermal cycling.
- Air Conditioners:Split-system configurations face compressed demand windows due to Germany's temperate climate and stringent building energy codes.
Refrigerators lead volumes today; washing machines are gaining share fastest.
Technology:
Technology choices track buyer willingness to absorb upfront cost premiums against operating expenditure reductions mandated by national efficiency frameworks.
- Inverter:Variable-speed compressor and motor architectures reduce electricity draw below fixed-speed thresholds. KBA certification requirements accelerate displacement of legacy equipment in replacement cycles.
- Smart Connectivity:Wi-Fi and Bluetooth modules enable remote diagnostics and cycle management. Rental housing operators in Munich leverage these capabilities for centralized maintenance scheduling across distributed property portfolios.
- Energy Efficient:EU Ecodesign Directive alignment drives baseline specification for all new residential installations.
- Sensor Based:Moisture and load-detection arrays optimize resource consumption without cloud dependency, reducing latency for time-sensitive cycles.
- Touch Control:Capacitive interface panels differentiate premium tiers while adding manufacturing complexity for Swabian production clusters.
Inverter technology anchors current procurement volumes; smart connectivity is expanding most quickly.
Application:
Application segmentation reflects tenure structure and maintenance responsibility allocation across Germany's heterogeneous housing stock.
- Residential Housing:Owner-occupied single-family and multi-family units drive replacement demand aligned with renovation financing cycles. Baden-Württemberg construction corridors sustain elevated demand for integrated appliance configurations.
- Rental Apartments:Landlord-mandated maintenance schedules in Bavaria compress replacement cadences into predictable refresh windows. Property management firms consolidate procurement through direct manufacturer relationships, bypassing retail intermediaries.
- Student Housing:Durability-focused specifications prioritize resistance to intensive use patterns over efficiency optimization.
- Vacation Homes:Seasonal occupancy patterns favor compact capacity units with frost-protection features.
- Serviced Apartments:Hospitality-grade reliability requirements align procurement with commercial rather than residential warranty structures.
Residential housing commands volume leadership; rental apartments show the steepest expansion trajectory.
Distribution Channel:
Channel selection tracks buyer scale, technical support requirements, and price transparency preferences across consumer and institutional segments.
- Online Retailers:Price comparison platforms and direct-to-consumer logistics reduce friction for replacement purchases in metropolitan markets. Energy label transparency requirements enable informed selection without physical inspection.
- Specialty Stores:Consultative selling environments support complex built-in configurations and kitchen system integration. Southern Germany's dense retail networks sustain this channel's relevance for renovation-driven demand.
- Department Stores:Mid-tier positioning captures occasional replacement demand with limited technical consultation.
- Wholesale Distributors:Bulk procurement channels serve property management consolidation and multi-unit installation projects.
- Direct Sales:Manufacturer-owned channels capture institutional relationships with rental housing operators and construction firms.
Specialty stores retain volume primacy; online retailers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swabian manufacturing clusters anchor German appliance production, with vertical integration extending from compressor assembly through finished goods distribution across southern metropolitan corridors.
Bavaria
Munich and Nuremberg rental housing markets sustain predictable replacement cycles through landlord-mandated maintenance schedules. The Building Energy Act drives specification of inverter compressor systems in new residential developments. Munich's dense apartment stock concentrates procurement through direct manufacturer relationships, bypassing traditional retail intermediaries.
Baden-Württemberg
Stuttgart and Karlsruhe renovation corridors elevate demand for built-in appliance configurations integrated with kitchen cabinetry. EU Ecodesign Directive rescaled efficiency tiers accelerate displacement of pre-2021 refrigerator stock. The Swabian manufacturing belt retains captive control over compressor assembly and polymer composite chassis production.
North Rhine-Westphalia
Ruhr metropolitan logistics hubs facilitate distribution to Benelux export markets. KBA energy-labeling enforcement creates certification friction for non-EU imports entering through Cologne-Bonn cargo corridors. Dortmund-based wholesale distributors consolidate bulk procurement for multi-unit housing projects across the Rhine-Ruhr conurbation.
Lower Saxony
Hanover industrial zones support component supply chains for northern German assembly operations. The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants, compelling retooling of compressor seal architectures. Wolfsburg automotive supplier networks spill over into appliance motor and sensor component fabrication.
Hesse
Frankfurt-Rhine-Main finance and logistics infrastructure enables working capital optimization for manufacturer inventory positioning. Federal Ministry for Economic Affairs coordination with BSI aligns national efficiency benchmarks with Brussels-mandated standards. Darmstadt testing and certification facilities service KBA import compliance requirements for Asian-manufactured components.
Germany Major Home Appliance Market Competitive Landscape
Global majors compete with regional champions across technology integration and distribution channel control, producing a tiered structure where scale-driven conglomerates anchor volume leadership alongside specialized domestic fabricators. The vendor base stratifies across three archetypes: diversified industrial conglomerates with captive appliance divisions, independent premium specialists emphasizing durability certification, and Asian scale exporters leveraging cost-optimized manufacturing platforms. Dominant competitive moves include backward integration into compressor and sensor component supply, plus direct-to-institutional sales channel development bypassing retail intermediaries.
Among German-based fabricators, BSH Hausgeräte GmbH and Miele & Cie KG exemplify contrasting strategic positions within the premium tier. BSH occupies a scale-integrated position spanning mass-market through luxury segments, while Miele anchors ultra-premium positioning through captive durability testing protocols. Robert Bosch GmbH represents the diversified conglomerate archetype, leveraging sensor technology cross-flow from automotive and industrial automation divisions into appliance product lines. These three entities collectively illustrate how German manufacturing heritage, regulatory compliance depth, and channel relationship control constitute sustainable competitive moats against Asian scale competitors.
| Leading Market Players |
|---|
| Liebherr International Deutschland GmbH |
| Whirlpool Corporation |
| BSH Hausgeräte GmbH |
| Robert Bosch GmbH |
| LG Electronics |
| Miele & Cie KG |
| Samsung Electronics |
| Haier Group |
| Electrolux AB |
| Others |
Supply & Pricing Matrix
Swabian compressor assembly specialists concentrate manufacturing expertise in a tight corridor between Stuttgart and Ulm, compressing labor-cost differentials into pricing-tier spreads that separate premium sensor-integrated systems from economy fixed-speed alternatives.
Pricing Analysis
Input-cost pass-through from steel and copper commodity volatility compresses margin pools most severely on mid-tier washing machine and refrigerator lines. Three-tier pricing structure across premium, standard, and economy levels stratifies by inverter technology adoption and KBA certification grade. Pricing pressure stems from heat pump dryer substitution eroding condensation-system volumes. Rental housing operators in Munich show lowest price sensitivity due to landlord-mandated maintenance budgets, while individual replacement buyers in North Rhine-Westphalia exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare-earth magnet suppliers feeding compressor motor laminations into Swabian assembly plants. Component sourcing draws from China, South Korea, and domestic German polymer composite fabricators. Steel-reinforced polymer chassis and copper refrigerant tubing constitute critical input dependencies. Tariff exposure on Asian-manufactured smart modules creates inventory friction at Hamburg-Bremerhaven entry points. Distribution runs through wholesale distributors consolidating bulk procurement for Bavarian property management portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's major home appliance market reads as a late-cycle quality story, with replacement demand shifting toward inverter compressor systems and sensor-based load optimization that command durable premium pricing.
For Market Incumbents: Deploy backward integration into polymer composite chassis production to defend margin position against steel input volatility. Compressor seal retooling for natural refrigerant compatibility represents critical R&D priority given EU F-Gas Regulation phase-down timelines. Consolidate direct sales relationships with Munich and Stuttgart rental housing operators to lock out retail-channel competitors. For New Entrants and Emerging Players: Student housing operators represent an underserved buyer archetype prioritizing durability over efficiency optimization. White-space concentration sits in Hanover industrial zones supplying northern German assembly operations with motor and sensor components. Channel entry through wholesale distributors serving multi-unit housing projects offers lowest friction path to volume. For Investors and Strategic Acquirers: Valuations sit cheapest among component suppliers with captive testing certification and KBA compliance infrastructure. Long-term viability centers on regulatory compliance depth rather than manufacturing scale alone. Watch for right-to-repair obligation implementation timelines as inflection signal for spare-part availability revenue expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Assembly | Swabian manufacturers secure margin control over variable-speed refrigeration systems. |
| Sensor-Cloud Convergence Development | Edge computing reduces latency for moisture-detection arrays in washing machine cycles. |
| Direct-to-Institutional Channel Expansion | Bypassing retail intermediaries captures Munich rental housing procurement consolidation. |
| Natural Refrigerant Seal Retooling | Propane and isobutane compatibility ensures KBA certification continuity post-F-Gas phase-down. |
| Steel-Reinforced Polymer Chassis Adoption | Unit weight reduction electrifies logistics cost structures for dishwasher and refrigerator platforms. |
Research Methodology
Multiple input streams — appliance manufacturer procurement directors, property management firm operations heads, KBA certification specialists, and Swabian plant engineers — were reconciled against customs records, EU Ecodesign Directive filings, and BSI efficiency benchmark publications. Bottom-up shipment data triangulated against top-down housing construction permits and renovation financing volumes.
Data-stream reconciliation anchored volume and value outputs across product type, technology tier, application tenure structure, and distribution channel dimensions. CAGRs derived from replacement cycle modeling tied to EU regulatory deadline phasing and Building Energy Act compliance windows. Compressor technology adoption curves and landlord-tenant regulatory frameworks constituted industry-specific forecast inputs.
Underlying measurement precision varies by segment; rental apartment procurement flows carry tighter precision than vacation home seasonal demand. Forecasts reflect assumptions around refrigerant chemistry transition timelines and right-to-repair obligation implementation scope. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
United Kingdom Home Appliances Market
Home Appliances
Germany Small Home Appliance Market
Home Appliances
Household Fridge Market
Home Appliances
Europe Washing Machine Market
Home Appliances
Colombia Home Appliances Market
Home Appliances
India Home Appliances Market
Home Appliances
Russia Home Appliances Market
Home Appliances
Side-By-Side Smart Refrigerator Market
Home Appliances
GCC Major Home Appliances Market
Home Appliances
Qatar Home Appliances Market
Home Appliances
Home Appliances Glass Market
Home Appliances
White Goods Market
Home Appliances
Asia-Pacific Small Home Appliances Market
Home Appliances
Green Smart Household Appliances Market
Home Appliances
South Africa Home Appliances Market
Home Appliances
United States Laundry Appliances Market