
 North America Home Appliances Market | 2026-2036
North America Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
North America Home Appliances Market Analytics
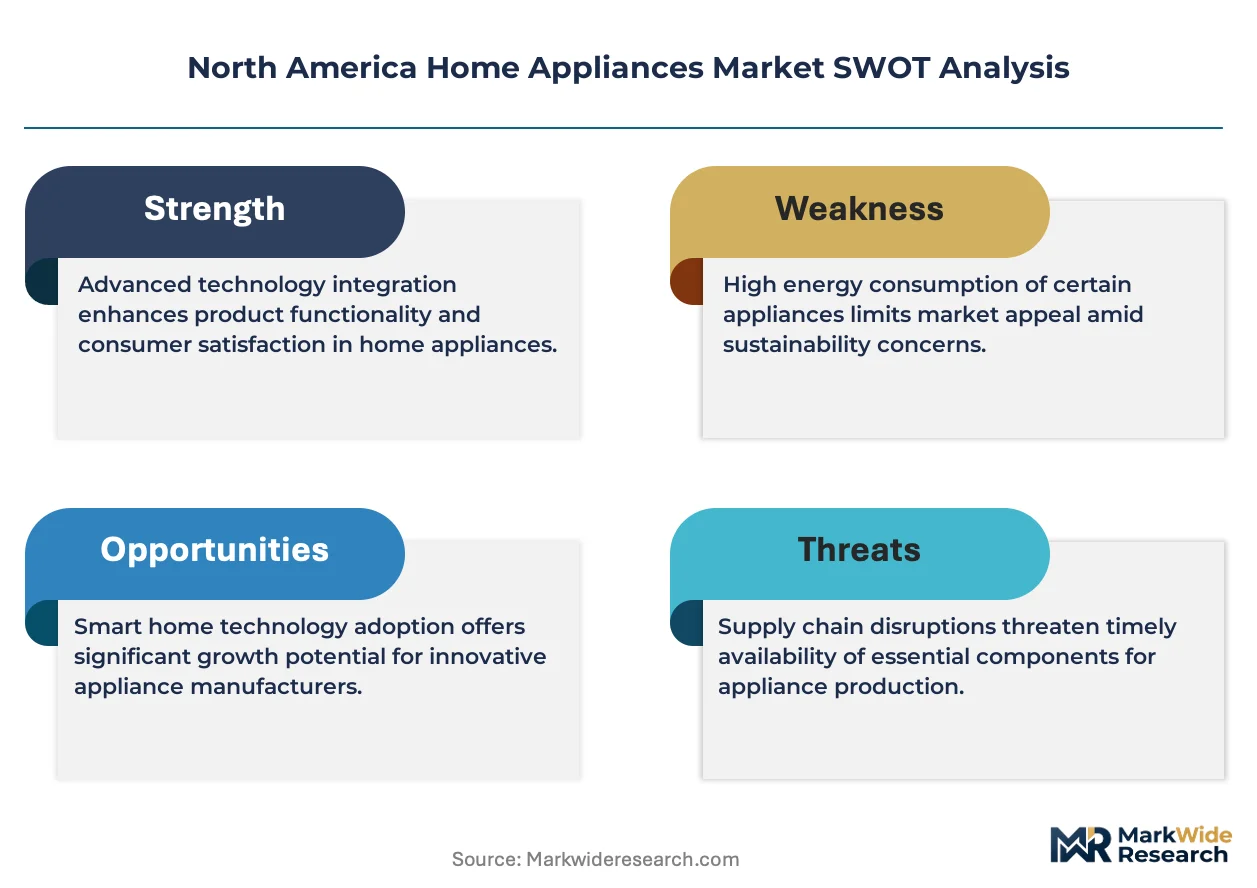
Subscription-based filter replacement and predictive maintenance software is rebalancing revenue streams beyond the initial hardware sale. Whirlpool Corporation leverages its extensive service network to sustain recurring revenue from connected appliance ecosystems. Samsung Electronics anchors its North American position through smart home integration platforms that extend software-defined functionality across kitchen and laundry portfolios. LG Electronics differentiates through proprietary compressor technology and in-house production of core refrigeration components.
North America home appliances comprise electrically powered mechanical devices designed for domestic tasks, typically operating on 120V single-phase residential power with energy consumption ratings measured under standardized test procedures. These systems incorporate thermal management circuits, induction heating elements, or brushless drive motors to perform food preservation, garment cleaning, or meal preparation functions. Refrigerators and washing machines occupy the largest installed base across residential end users, though smart appliances and IoT-enabled devices are expanding fastest as connectivity modules become standard equipment. Energy-efficient systems command margin premiums where utility rebate programs and ENERGY STAR certification requirements create procurement incentives.
The US Department of Energy administers appliance efficiency standards under the National Appliance Energy Conservation Act, while the Environmental Protection Agency operates the ENERGY STAR voluntary labeling program that shapes retailer assortment decisions. Canada's Natural Resources Office of Energy Efficiency maintains parallel regulatory requirements through the Energy Efficiency Act, creating cross-border harmonization pressure for manufacturers. Industry participants must monitor how pending amendments to federal test procedures and state-level building electrification mandates reshape product development priorities and channel inventory requirements.
Market Dynamics
The US Department of Energy's tightening minimum efficiency thresholds for refrigerators and washing machines are forcing manufacturers to redesign thermal management systems and motor architectures ahead of compliance deadlines.
Growth Catalysts
- Building electrification mandates:State-level mandates in California and New York are accelerating replacement cycles for fossil-fuel-dependent appliances. Residential developers in Sun Belt corridors are specifying all-electric kitchens to preempt code changes.
- Smart home integration:IoT-enabled connectivity modules are becoming standard equipment across refrigerator and laundry portfolios. Platform ecosystems are locking in recurring service revenue through predictive maintenance algorithms.
- Texas and Florida housing expansion:Suburban developments in Dallas-Fort Worth and Tampa metropolitan areas are outpacing national construction rates. New household formation is driving first-purchase demand for full appliance suites.
Market Restraints
- Copper and rare-earth magnet volatility:Compressor motors and induction heating elements depend on concentrated supply chains. Price swings in these inputs compress margin visibility for manufacturers with annual contract pricing.
- Test procedure uncertainty:Pending amendments to federal appliance test procedures create inventory risk. Manufacturers face stranded product if efficiency certifications shift mid-production cycle.
- Gas appliance substitution ceiling:Existing natural gas infrastructure in Northeast and Midwest housing stock slows full electrification transitions. Hybrid product strategies dilute R&D focus.
Strategic Opportunities
- Filter subscription services:Water and air filtration cartridges offer recurring revenue attachment to hardware sales. Connected diagnostics enable just-in-time replenishment before performance degradation.
- Canadian regulatory harmonization:Natural Resources Canada's Energy Efficiency Act amendments create cross-border product standardization incentives. Unified SKUs reduce compliance fragmentation for US-based manufacturers.
- Heat pump dryer convergence:Condensation-based drying technology eliminates venting requirements. Apartment and condominium installations in dense urban cores expand addressable market for ventless configurations.
Industry Challenges
- Field service technician scarcity:Connected appliance diagnostics require software troubleshooting skills alongside mechanical repair capabilities. Training pipelines have not kept pace with product complexity.
- Legacy platform integration:Smart appliance ecosystems must interoperate with existing home automation standards. Fragmented protocol landscapes force redundant engineering investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Home Appliances Market |
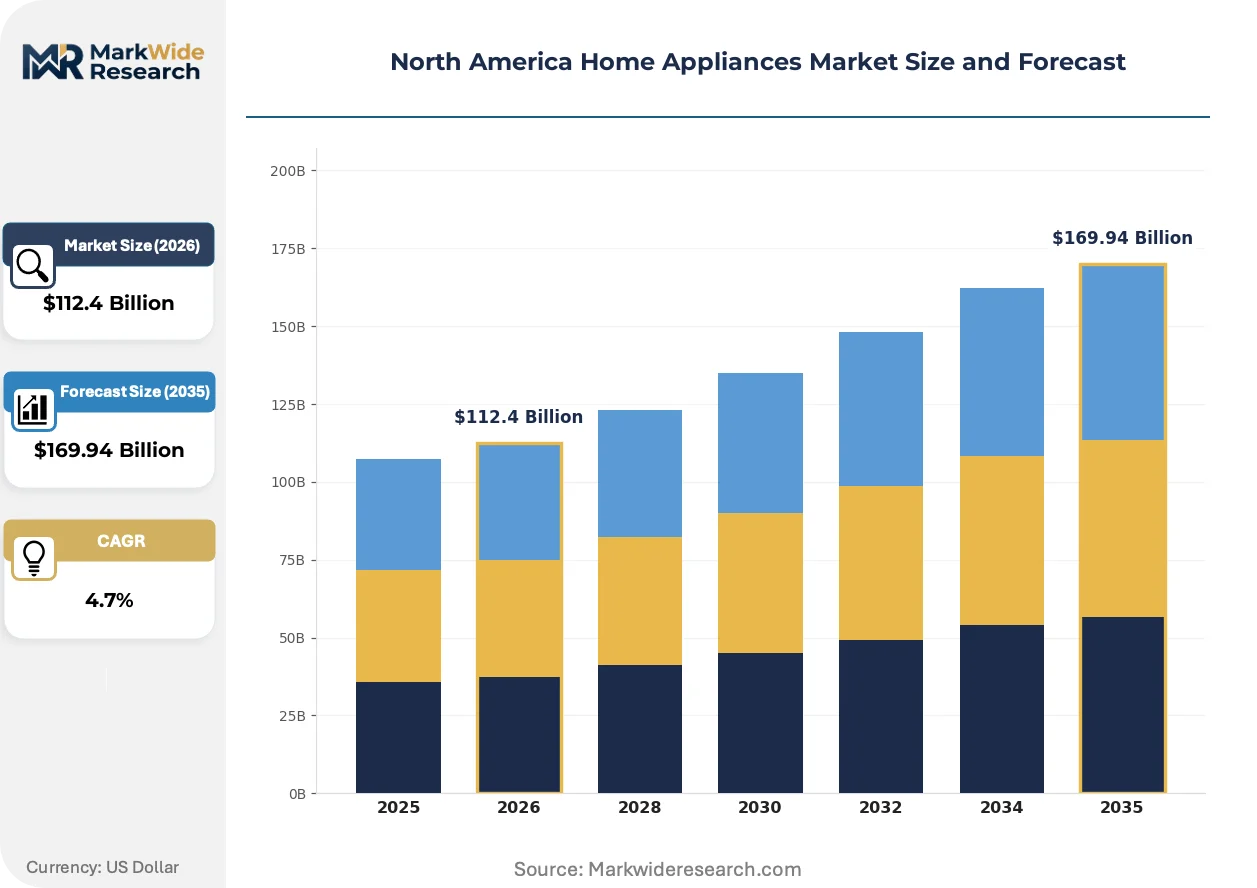
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $169.94 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Ovens, Washing Machines, Dishwashers End User: Residential Consumers, Hospitality, Restaurants, Retail Chains Technology: Smart Appliances, Energy-Efficient Systems, Conventional Devices, IoT Enabled Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Whirlpool Corporation, Samsung Electronics, LG Electronics, Electrolux AB, Robert Bosch GmbH, Haier Smart Home Co., Ltd., Panasonic Corporation, GE Appliances, Midea Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Home Appliances Market Evolving Landscape
Refrigeration and cooking systems are converging around software-defined functionality that extends hardware lifecycles through over-the-air capability updates rather than physical replacement.
Variable-speed inverter compressors are overtaking fixed-speed reciprocating designs in residential refrigeration. Sun Belt builders are specifying inverter platforms for their humidity-load responsiveness. This transition is compressing the service interval advantage that legacy compressor architectures once held.
The US Department of Energy's amended refrigerator test procedure is reshaping insulation and door-seal engineering priorities. Manufacturers are accelerating vacuum-insulated panel adoption to maintain capacity ratings under stricter measurement protocols. Top-mount freezer configurations face disproportionate redesign pressure relative to French-door platforms.
Builders and property managers are bundling appliance suites into single-vendor procurement agreements. Traditional retail channel volume is fragmenting as multifamily developers negotiate direct manufacturer relationships. This concentration is most visible in Texas and Florida metropolitan construction corridors where national builders standardize across regional portfolios.
North America Home Appliances Market Segmentation
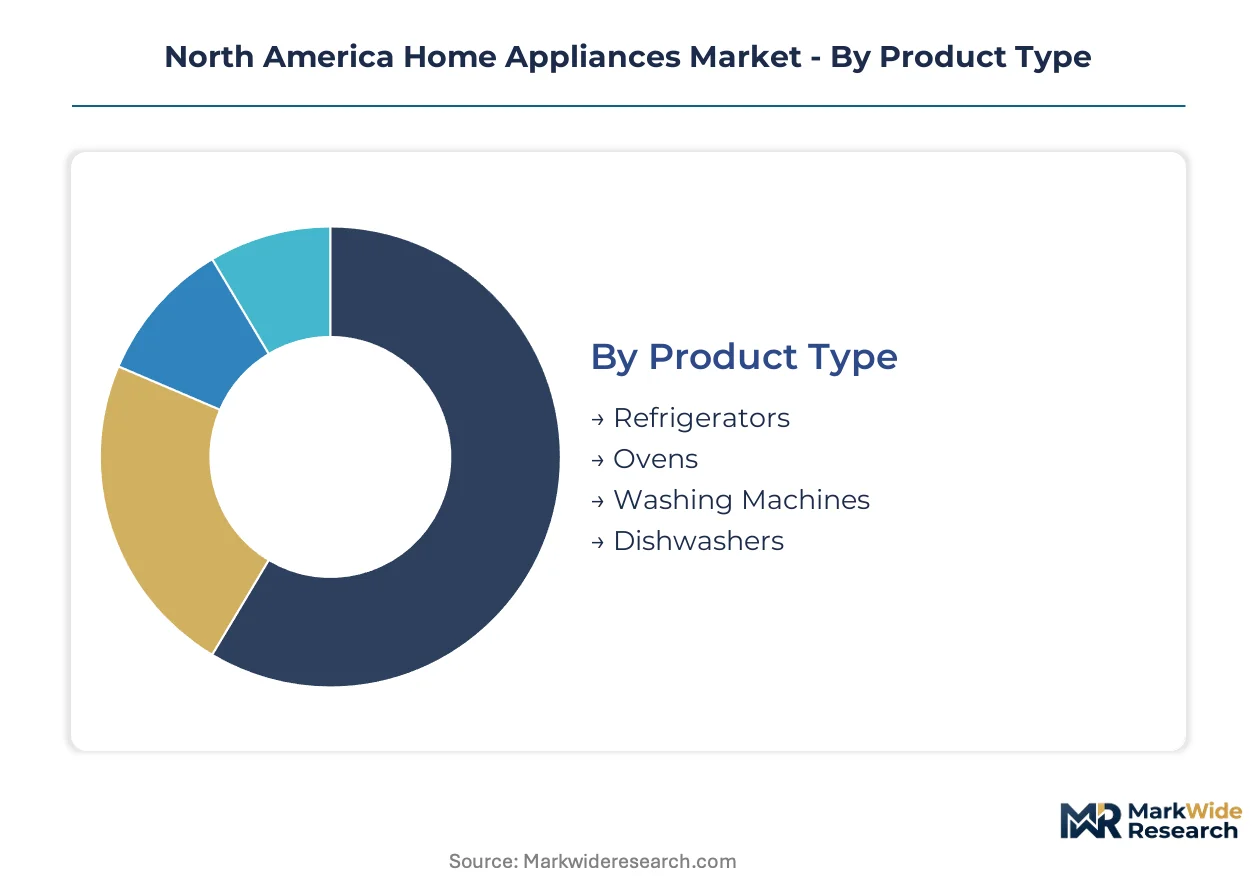
Segmentation in North American home appliances reveals divergent margin structures across product categories and channel strategies. Manufacturers optimize portfolio mix based on replacement cycle timing, electrification compliance costs, and recurring revenue attachment potential from connected ecosystems.
Product Type:
Volume concentration sits in refrigeration and laundry, while cooking platforms command premium positioning through electrification mandates.
- Refrigerators:Variable-speed inverter compressors are displacing fixed-speed reciprocating architectures across top-mount and French-door configurations. Sun Belt residential developers in Dallas-Fort Worth and Tampa corridors specify inverter platforms for humidity-load responsiveness, though vacuum-insulated panel adoption accelerates under amended DOE test procedures.
- Washing Machines:Front-load drum designs with brushless direct-drive motors dominate efficiency-compliant portfolios, capturing utility rebate flows in California and New York. ENERGY STAR certification thresholds are forcing motor architecture redesigns ahead of federal compliance deadlines.
- Ovens:Induction heating elements and convection fan systems define electrification-ready portfolios.
- Dishwashers:Condensation drying and soil-sensing algorithms differentiate efficiency tiers.
Mature deployment sits with refrigerators. Newer deployment is concentrated in washing machines.
End User:
Residential replacement cycles anchor volume, while commercial segments concentrate procurement through bundled suite negotiations.
- Residential Consumers:Suburban household formation in Texas and Florida metropolitan corridors drives first-purchase demand for full appliance suites. Connected kitchen ecosystems with predictive maintenance software are rebalancing revenue streams beyond initial hardware transactions.
- Restaurants:Commercial kitchen electrification mandates in California and New York accelerate replacement of fossil-fuel-dependent cooking platforms. High-duty-cycle refrigeration and convection systems command premium service contracts.
- Hospitality:Property managers negotiate direct manufacturer relationships for standardized suite deployment across regional portfolios.
- Retail Chains:Appliance showroom footprints consolidate as online channels capture specification research.
Residential deployment holds the deepest installed base. Hospitality deployment is expanding most quickly through bundled procurement agreements.
Technology:
Connectivity modules and efficiency certifications are bifurcating product architectures between compliance-driven refresh and premium smart home integration.
- Smart Appliances:Over-the-air capability updates extend hardware lifecycles through software-defined functionality. Platform ecosystems lock in recurring service revenue via predictive maintenance algorithms and filter subscription services.
- Energy-Efficient Systems:ENERGY STAR certification and utility rebate programs shape retailer assortment decisions. DOE-administered efficiency standards under the National Appliance Energy Conservation Act force thermal management and motor redesigns.
- IoT Enabled:Connectivity modules are becoming standard equipment across refrigerator and laundry portfolios.
- Conventional Devices:Non-connected platforms serve price-sensitive replacement demand in legacy housing stock.
Conventional deployment retains volume share in Midwest and Northeast gas infrastructure corridors. Smart deployment shows the steepest expansion trajectory through Sun Belt new construction.
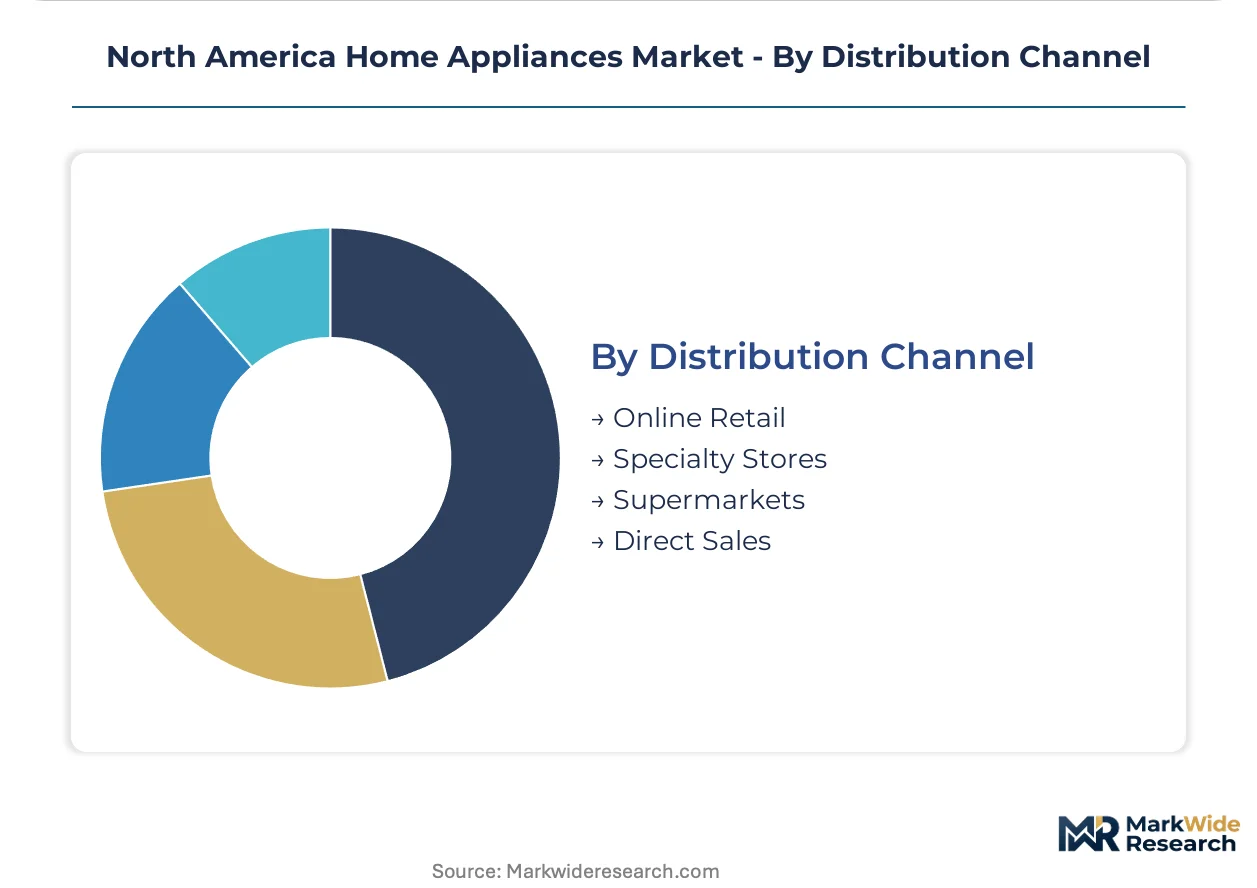
Distribution Channel:
Channel concentration is fragmenting as multifamily developers bypass traditional retail through direct manufacturer relationships.
- Direct Sales:National builders in Texas and Florida metropolitan construction corridors standardize appliance suites across regional portfolios. Single-vendor procurement agreements compress channel margin extraction.
- Online Retail:Specification research and filter subscription replenishment migrate to digital platforms. Connected diagnostics enable just-in-time consumable replacement before performance degradation.
- Specialty Stores:Showroom experience supports premium smart home ecosystem demonstrations.
- Supermarkets:Mass-market volume concentrates in replacement-driven categories with shorter decision cycles.
Specialty store deployment anchors premium positioning. Direct sales deployment is gaining share fastest through builder consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North American appliance production concentrates in midwestern US manufacturing corridors while consumption gravitates toward Sun Belt metropolitan expansion zones. Canada maintains parallel regulatory frameworks that create cross-border harmonization pressure. Mexico serves as a component assembly hub with growing finished goods capacity.
United States
Sun Belt metropolitan corridors in Texas and Florida are outpacing national construction rates, driving first-purchase demand for full appliance suites in Dallas-Fort Worth and Tampa. The US Department of Energy administers appliance efficiency standards under the National Appliance Energy Conservation Act, tightening minimum thresholds for refrigerators and washing machines. Midwestern manufacturing clusters in Ohio and Michigan retain compressor motor and thermal management component production.
Canada
Natural Resources Canada's Office of Energy Efficiency maintains regulatory requirements through the Energy Efficiency Act, creating cross-border standardization incentives for unified SKUs. ENERGY STAR certification shapes retailer assortment decisions in Ontario and Quebec urban markets. Appliance distribution concentrates in the Golden Horseshoe corridor connecting Toronto to Buffalo-Niagara.
Mexico
Appliance component assembly clusters in Nuevo León and Baja California supply compressors and motor assemblies to North American finished goods plants. The country's manufacturing integration deepens under USMCA trade provisions. Guadalajara metropolitan area hosts growing refrigerator and washing machine final assembly capacity serving export markets.
California
State-level building electrification mandates accelerate replacement cycles for fossil-fuel-dependent appliances in residential and commercial segments. California Energy Commission appliance standards exceed federal minimums, forcing early compliance redesigns. Los Angeles and San Francisco metropolitan areas concentrate utility rebate program administration and ENERGY STAR retail penetration.
New York
Climate Leadership and Community Protection Act targets drive all-electric new construction mandates in New York City and downstate corridors. Existing natural gas infrastructure in upstate and legacy housing stock slows full electrification transitions. Buffalo-Rochester manufacturing heritage retains specialized component suppliers for compressor systems.
North America Home Appliances Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across integrated versus modular platform strategies. The market structure consolidates around full-line manufacturers with captive component production and service networks. Three archetypes dominate: diversified conglomerates with smart home ecosystems, specialized refrigeration technology owners, and contract manufacturers with scale-driven cost positions. Competitive moves center on direct builder procurement relationships and predictive maintenance software subscriptions that extend hardware revenue cycles.
Among diversified appliance conglomerates, Whirlpool Corporation and Samsung Electronics exemplify platform ecosystem strategies that lock in recurring service revenue through connected diagnostics and filter replenishment. LG Electronics occupies a position as a refrigeration technology specialist with proprietary compressor manufacturing. These three anchors represent distinct competitive vectors: service network depth, smart home integration breadth, and core component vertical control.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| Samsung Electronics |
| LG Electronics |
| Electrolux AB |
| Robert Bosch GmbH |
| Haier Smart Home Co., Ltd. |
| Panasonic Corporation |
| GE Appliances |
| Midea Group |
| Others |
Value Network & Pricing Analysis
Compressor motor technician scarcity in Ohio and Michigan manufacturing corridors widens labor-cost differentials between premium inverter platforms and conventional fixed-speed architectures. These workforce concentrations anchor pricing-tier spreads as Sun Belt builders absorb premium positioning for humidity-responsive systems while Midwest replacement cycles favor economy-tier procurement.
Pricing Analysis
Margin tightening in economy-tier refrigeration traces to copper and rare-earth magnet input volatility compressing contract visibility. Three-tier pricing structure across premium smart-home-integrated, standard ENERGY STAR-certified, and economy conventional levels separates buyers by connected-service attachment and certification grade. Cost-down pressure on standard-tier laundry accelerates as front-load drum redesigns for federal compliance deadlines stack engineering expenses. Residential replacement buyers in legacy gas-infrastructure corridors exhibit highest price sensitivity; multifamily developers in Texas and Florida corridors demonstrate lowest sensitivity through bundled suite procurement.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare-earth magnet processing for compressor motor assemblies. Component manufacturing concentrates in Mexico's Nuevo León and Baja California assembly clusters, South Korean inverter control module production, and domestic Ohio-Michigan thermal management fabrication. Raw material dependencies span copper winding stock, neodymium-iron-boron magnets, and vacuum-insulated panel cores. Tariff exposure on Chinese-processed rare earths threatens margin stability for motor architecture transitions. Distribution runs through direct builder procurement agreements fragmenting traditional retail channel concentration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America home appliances market occupies a technology-transition phase as variable-speed inverter compressors displace fixed-speed reciprocating designs across residential refrigeration portfolios.
For Market Incumbents: To counter field service technician scarcity threatening connected appliance deployment, incumbents should expand captive training pipelines for software diagnostics competency and secure direct procurement relationships with national builders in Dallas-Fort Worth and Tampa corridors. Backward integration into compressor motor manufacturing preserves margin control against rare-earth magnet supply volatility. For New Entrants and Emerging Players: Launch via filter subscription and predictive maintenance software platforms targeting apartment and condominium segments in dense urban cores where ventless heat pump dryer configurations eliminate infrastructure barriers. White-space concentration sits with condominium property managers seeking standardized suite deployment without venting requirements. For Investors and Strategic Acquirers: Re-rating potential sits with refrigeration technology specialists possessing proprietary compressor manufacturing given electrification mandate acceleration across California and New York. Long-term viability favors asset-light platform ecosystem designers over capital-heavy component producers. Monitor state-level building electrification mandate passage as inflection signal for replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Locks recurring revenue from Whirlpool and Samsung connected ecosystems through filter replenishment algorithms. |
| Inverter Compressor Manufacturing Scale-Up | Captures Sun Belt builder specifications for humidity-load responsiveness in Dallas-Fort Worth corridors. |
| Direct Builder Procurement Partnership | Bypasses retail margin extraction through national developer relationships in Tampa metropolitan expansion zones. |
| Heat Pump Dryer Technology Licensing | Expands addressable market into ventless condominium installations across dense urban cores. |
| Field Service Technician Training Program | Addresses capability scarcity for connected appliance diagnostics alongside mechanical repair skills. |
Research Methodology
Trade association filings, customs import records, and EPA ENERGY STAR certification databases formed the secondary backbone, cross-referenced with primary interviews across appliance manufacturing executives, multifamily developer procurement directors, field service technician training administrators, and utility rebate program administrators. Bottom-up unit shipment estimates by product category and state-level construction permit data were triangulated against top-down manufacturer revenue disclosures.
Historical trendline analysis of replacement cycle timing, new construction appliance penetration rates, and efficiency standard compliance cost trajectories informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user category, technology tier, and distribution channel, with regional regulatory cluster variations for California, New York, and Canadian harmonization pathways. CAGRs were derived from installed base turnover rates and electrification mandate implementation schedules, incorporating compressor motor cost curves and connectivity module adoption slopes as industry-specific inputs.
Regulatory amendment delays, rare-earth supply disruption, and housing construction volatility are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding federal test procedure implementation timing and state electrification mandate enforcement. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
United States Household Refrigerators Market
Home Appliances
Sweden Home Appliances Market
Home Appliances
Household Induction Cooktops Market
Home Appliances
Mexico Small Home Appliances Market
Home Appliances
Europe Residential Water Heaters Market
Home Appliances
US Household Appliances Market
Home Appliances
South Africa Home Appliances Market
Home Appliances
Russia Home Appliances Market
Home Appliances
Home Laundry Appliances Market
Home Appliances
Bahrain Home Appliances Market
Home Appliances
North America Electric Fireplace Market
Home Appliances
Canada Home Appliances Market
Home Appliances
White Goods Market
Home Appliances
Israel Home Appliances Market
Home Appliances
Japan Small Home Appliances Market
Home Appliances
Green Smart Household Appliances Market