
 France Household Appliances Market | 2026-2036
France Household Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
France Household Appliances Market Insights
The France household appliances market is consolidating around a widening gap between premium connected kitchens and basic replacement units. Robert Bosch GmbH leverages its German engineering heritage to dominate the high-efficiency segment with integrated cooking systems. GROUPE BRANDT, as a domestic manufacturer, anchors its position through localized production and reparability compliance. Samsung Electronics differentiates via smart appliance ecosystems that sync with home energy management platforms.
France household appliances encompass electromechanical devices designed for domestic tasks, typically operating at 220-240V/50Hz with energy efficiency ratings from A to G under EU labeling frameworks. These units incorporate compressors, heating elements, or motor-driven mechanisms to perform refrigeration, cleaning, cooking, or food preservation functions for residential and light commercial settings. Refrigerators command the largest product type share due to mandatory replacement of fluorinated refrigerants under F-Gas Regulation phase-down schedules. Energy-efficient technology leads volume growth as French households respond to electricity tariff pressures and carbon footprint tracking tools. Smart appliances remain concentrated in urban centers where broadband infrastructure and smartphone penetration enable remote diagnostics and usage optimization.
France's national market operates under ANSM product safety oversight, EU Ecodesign requirements, and the national reparability index mandated by AGEC anti-waste law. These frameworks compel manufacturers to extend spare parts availability and standardize disassembly protocols, directly reshaping R&D budgets and bill-of-materials decisions. Stakeholders must monitor how upcoming EU right-to-repair amendments will redefine warranty obligations and aftermarket service revenue models.
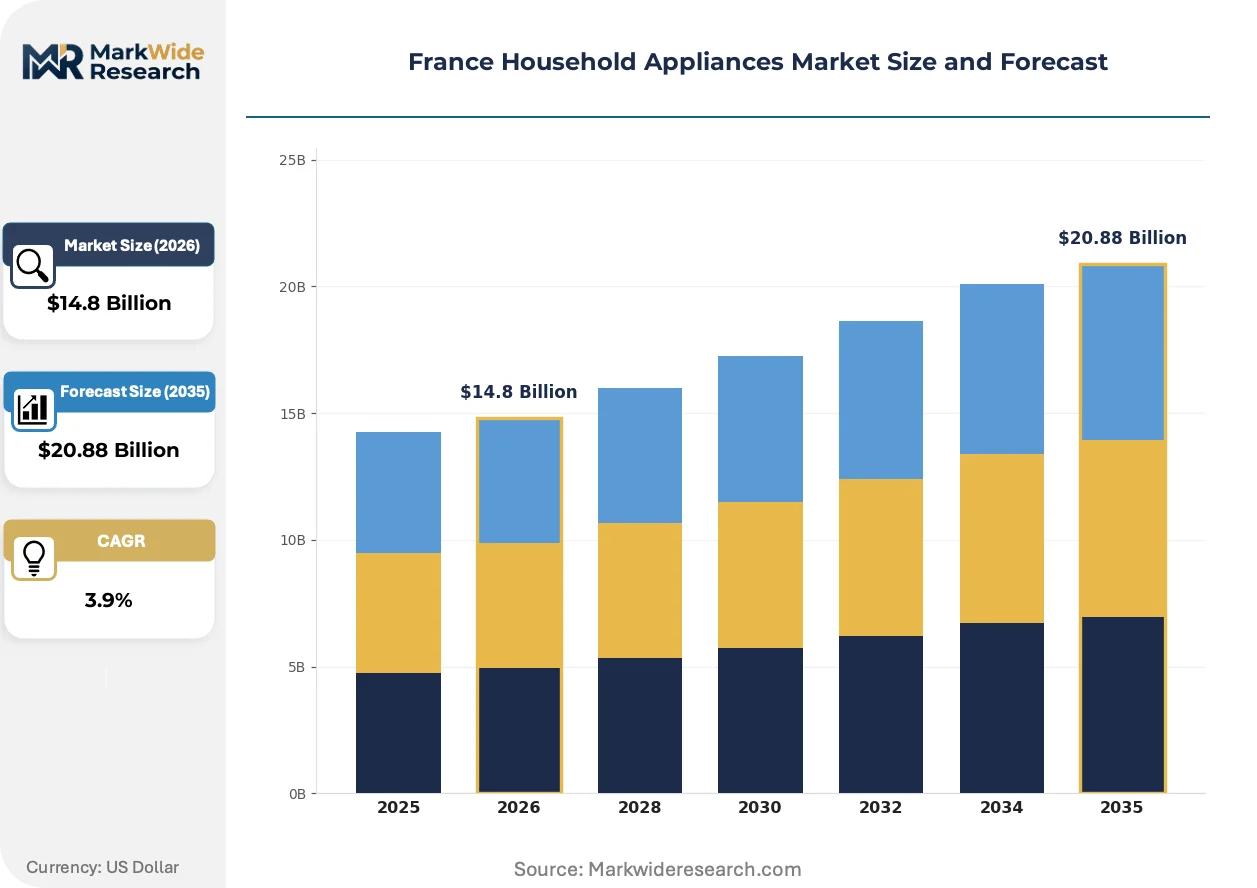
Market Dynamics
The France household appliances market is pivoting around the AGEC anti-waste law's reparability index, which compels manufacturers to redesign for disassembly and spare parts availability. This regulatory pressure is compressing product development cycles while elevating domestic producers with localized supply chains.
Growth Catalysts
- Reparability Index Compliance:ANSM enforcement of AGEC law mandates spare parts availability for ten years, creating pull for modular appliance architectures and standardized component interfaces.
- Île-de-France Renovation Cycles:Paris metropolitan area replacement rates exceed national averages as apartment dwellers upgrade kitchens during property renovations.
- Heat Pump Integration:Electrification of residential heating under France's national energy transition plan is driving demand for hybrid cooking and climate-control appliances.
Market Restraints
- Copper and Rare Earth Volatility:Motor and compressor manufacturing faces input cost pressure from concentrated Chilean copper and Chinese rare earth processing.
- OEM Consolidation in Compressors:Three Asian suppliers control over seventy percent of variable-speed compressor output, creating supply vulnerability for French refrigeration assembly.
- F-Gas Phase-Down Timeline:EU F-Gas Regulation acceleration is forcing premature R-134a and R-410A obsolescence before alternative refrigerant supply scales.
Strategic Opportunities
- Occitanie Secondary Cities:Toulouse and Montpellier renovation rates lag Paris by four years, creating replacement cycle expansion potential as broadband infrastructure enables smart appliance adoption.
- Energy Management Convergence:Linkage between appliance load scheduling and home battery systems opens subscription-based optimization services.
- Refurbishment Channel Development:AGEC law's repair fund incentives enable certified pre-owned appliance networks with warranty backing.
Industry Challenges
- Field Service Technician Shortage:Reparability index enforcement requires trained diagnostics personnel for connected appliance repair, but vocational pipeline output trails demand in Lyon and Marseille metropolitan zones.
- Legacy System Integration:Smart appliance ecosystems must interface with twenty-year-old residential electrical panels and circuit breakers common in pre-2005 Paris housing stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Household Appliances Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $20.88 Billion |
| CAGR (2026 – 2036) | 3.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Microwaves, Dishwashers End User: Residential, Commercial, Institutional, Retail Technology: Smart Appliances, Energy-Efficient, Traditional, Automated Distribution Channel: Online Retail, Brick-and-Mortar, Wholesale, Direct Sales |
| Companies Covered | LG Electronics, Haier Group, Robert Bosch GmbH, GROUPE BRANDT, Panasonic Corporation, Electrolux AB, Samsung Electronics, Arcelik A.S., Whirlpool Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Household Appliances Market Trends and Innovations
Connected kitchen ecosystems are reshaping how French households interact with domestic equipment. Manufacturers are racing to integrate energy optimization, predictive maintenance, and seamless mobile control into core product lines.
Induction cooking technology is overtaking gas and traditional electric resistance in new kitchen installations. Urban apartment renovators in Paris and Lyon specify induction hobs for energy efficiency and space constraints. This shift is compressing gas appliance aftermarket service revenue while expanding demand for compatible cookware and electrical panel upgrades.
France's national reparability index under AGEC law is forcing redesign of appliance architectures for component accessibility. Manufacturers must now document disassembly sequences and guarantee spare parts availability for a decade. Refrigeration and washing machine segments face the steepest compliance costs as sealed systems and drum assemblies require modular re-engineering.
Subscription-based appliance access is displacing outright ownership among younger urban households. Lyon and Bordeaux rental markets see property managers bundling maintained appliance packages into lease agreements. This model concentrates procurement decisions with institutional buyers and extends manufacturer responsibility through full lifecycle service contracts.
France Household Appliances Market Segmentation
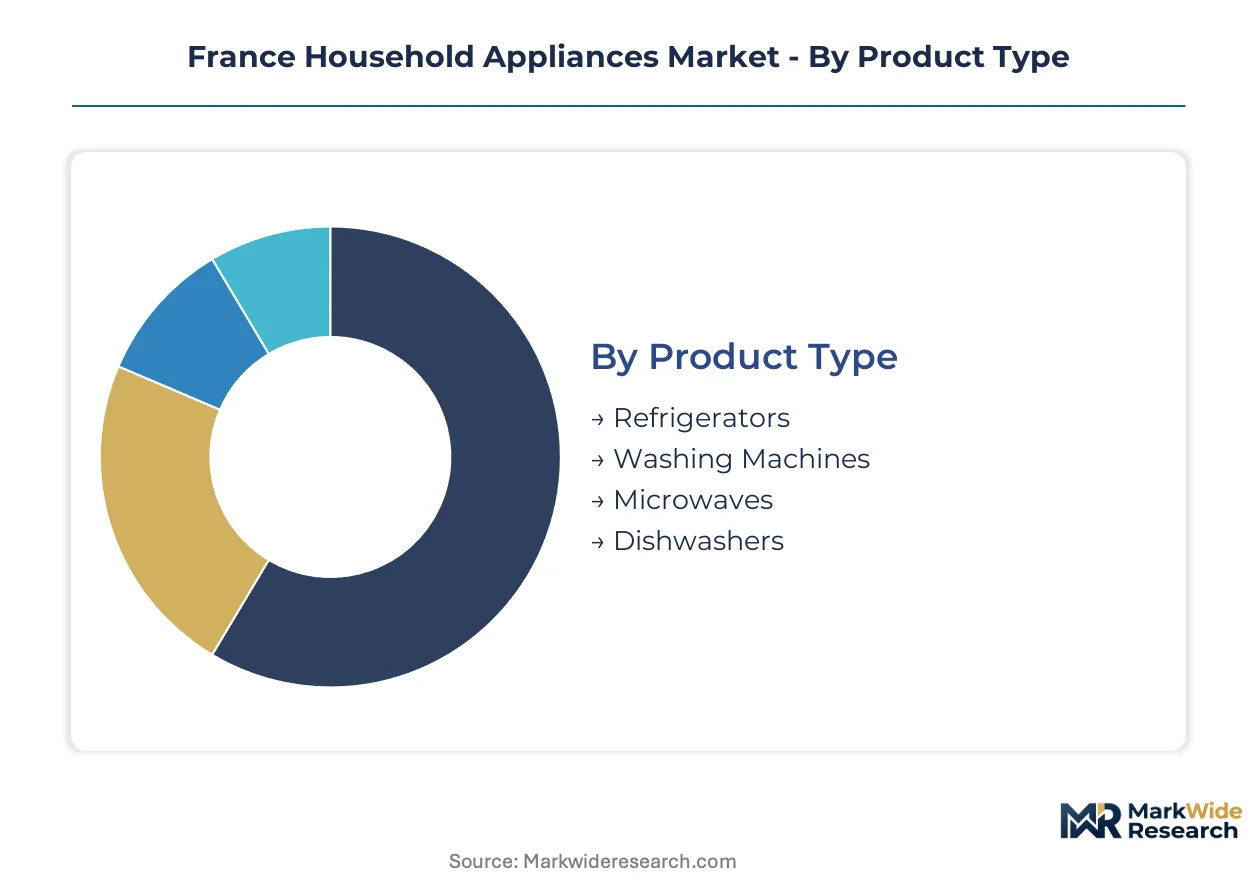
France's household appliances market fragments along four critical axes that determine procurement patterns and margin structures. Product type and technology choices dominate Parisian renovation decisions, while distribution channel selection varies sharply between urban apartment clusters and rural replacement cycles.
Product Type:
Replacement urgency and kitchen renovation timelines drive purchasing priority across French households.
- Refrigerators:Compressor-based cooling systems operating on 220-240V with A-G energy ratings under EU labeling. Demand concentrates in Île-de-France apartment renovations where F-Gas Regulation phase-down accelerates fluorinated refrigerant replacement. ANSM safety oversight and AGEC reparability mandates elevate total cost of ownership calculations.
- Washing Machines:Motor-driven drum assemblies with variable-speed drives and water consumption metrics. Paris and Lyon urban dwellers prioritize front-loading units for space efficiency during bathroom renovations, though drum bearing accessibility for repair compliance adds manufacturing cost.
- Microwaves:Magnetron-based heating elements with inverter technology options. Replacement cycles run shorter than major appliances, with demand clustering in student housing and secondary city rental markets.
- Dishwashers:Pump and heating element systems with water softener integration. Île-de-France installation rates exceed national averages as kitchen renovations incorporate built-in units.
Refrigerators lead on scale; washing machines lead on momentum as reparability redesign penetrates this segment fastest.
End User:
Volume concentration and service contract complexity separate institutional buyers from dispersed residential purchasers.
- Residential:Individual households purchasing single units or matched kitchen suites. Paris metropolitan area drives premium specification as property values justify integrated appliance investments.
- Commercial:Restaurants, hotels, and catering operations requiring heavy-duty cycles and rapid service response. Lyon hospitality sector demands commercial refrigeration with localized technician networks.
- Institutional:Schools, hospitals, and government facilities with centralized procurement and extended warranty requirements. AGEC repair fund eligibility shapes vendor selection.
- Retail:Appliance rental and subscription providers bundling maintenance into monthly fees. Bordeaux and Lyon property managers pilot this model for furnished rental stock.
Residential captures volume dominance; institutional procurement expands most quickly as repair-fund incentives reshape public sector tendering.
Technology:
Energy cost exposure and broadband availability determine technology tier selection across French regions.
- Smart Appliances:WiFi-connected units with remote diagnostics and energy management platform integration. Urban centers with fiber infrastructure enable adoption; rural zones lag on connectivity prerequisites.
- Energy-Efficient:Compressors, motors, and heating elements optimized for A+++ ratings under EU frameworks. Electricity tariff pressures in France accelerate specification of these units across all buyer types.
- Traditional:Electromechanical controls without connectivity or variable-speed drives. Price-sensitive replacement demand in peripheral regions sustains this tier.
- Automated:Sensor-driven operation with load detection and cycle optimization. Dishwasher and washing machine segments incorporate these features for water conservation compliance.
Energy-efficient technology holds installed base dominance; smart appliances gain share fastest where broadband infrastructure enables ecosystem functionality.
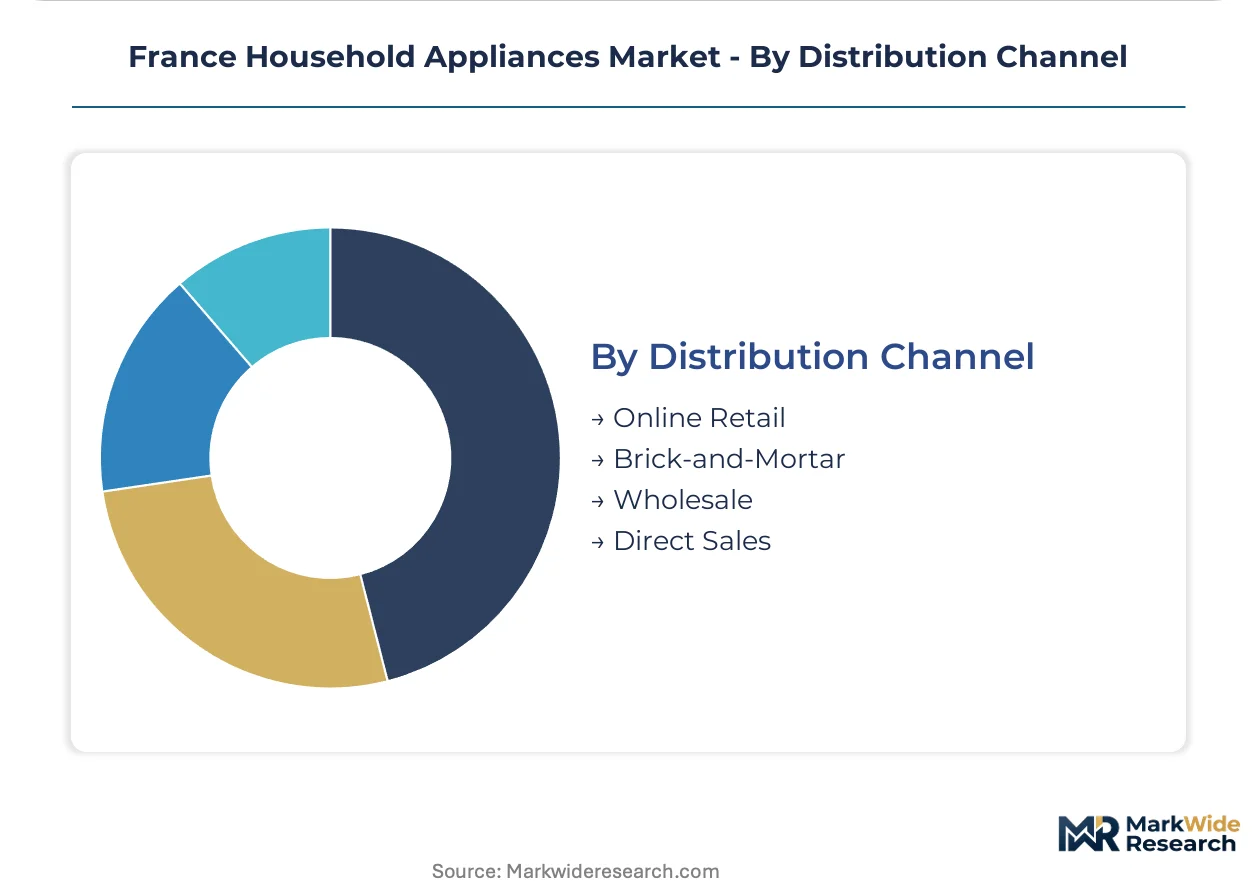
Distribution Channel:
Buyer touchpoint preference splits along geography, urgency, and installation service requirements.
- Online Retail:E-commerce platforms with delivery scheduling and installation coordination. Younger urban households in Paris and Lyon favor this channel for price transparency.
- Brick-and-Mortar:Physical showrooms with product demonstration and immediate takeaway options. Older demographics and rural buyers rely on tactile evaluation before purchase.
- Wholesale:Bulk procurement for property developers, retailers, and institutional buyers. Renovation contractors in Île-de-France source kitchen suites through this channel.
- Direct Sales:Manufacturer-owned stores and subscription service providers. Full lifecycle contracts with maintenance inclusion attract institutional and rental market buyers.
Brick-and-mortar retains transaction volume leadership; online retail climbs fastest as delivery logistics mature for large appliance handling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled appliance technicians and factory workers cluster in France's industrial belts, anchoring regional production capacity and aftermarket service networks across distinct metropolitan zones.
Île-de-France
Paris metropolitan renovation cycles drive premium appliance replacement at rates exceeding national averages. ANSM safety oversight and AGEC reparability mandates shape procurement specifications for apartment kitchen upgrades. Connected appliance adoption concentrates in central arrondissements where fiber infrastructure enables smart ecosystem integration.
Auvergne-Rhône-Alpes
Lyon's hospitality sector generates commercial refrigeration demand from restaurants and hotels requiring rapid service response. EU F-Gas Regulation phase-down accelerates fluorinated refrigerant replacement in existing installed bases. Saint-Étienne retains manufacturing heritage with localized compressor assembly operations serving domestic OEMs.
Provence-Alpes-Côte d'Azur
Marseille's dense rental housing stock sustains shorter replacement cycles for basic washing machines and refrigerators. The national reparability index creates technician demand that outpaces vocational training pipeline output. Toulon and Nice property managers pilot subscription-based appliance bundles for furnished rental units.
Occitanie
Toulouse and Montpellier renovation rates lag Paris by approximately four years, creating deferred replacement cycle expansion potential. Broadband infrastructure rollout enables smart appliance adoption in secondary city centers. The region's repair fund incentives under AGEC law attract certified pre-owned appliance network development.
Hauts-de-France
Lille's cross-border proximity to Belgian and Dutch distribution hubs positions the region for wholesale appliance logistics. Industrial heritage in mechanical engineering supports component supply for modular appliance architectures. Energy-efficient technology adoption accelerates here as electricity tariff pressures affect household budgets directly.
France Household Appliances Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across France's household appliances sector, creating a tiered structure where integrated manufacturers with captive component supply face specialized assemblers sourcing from concentrated compressor and motor suppliers. The vendor base splits between domestic heritage brands with localized production footprints and Asian conglomerates leveraging scale economies for cost-positioned entries. Three strategic archetypes dominate: engineering-driven premium specialists, volume-focused diversified electronics groups, and regional champions exploiting reparability compliance proximity. Competitive moves center on backward integration into compressor manufacturing and strategic partnerships with home energy management platform providers.
Among diversified Korean electronics groups, LG Electronics and Samsung Electronics exemplify ecosystem-centric positioning, while Robert Bosch GmbH anchors the German engineering heritage archetype. GROUPE BRANDT occupies a position as the domestic manufacturer leveraging French production sites for regulatory compliance responsiveness.
| Leading Market Players |
|---|
| LG Electronics |
| Haier Group |
| Robert Bosch GmbH |
| GROUPE BRANDT |
| Panasonic Corporation |
| Electrolux AB |
| Samsung Electronics |
| Arcelik A.S. |
| Whirlpool Corporation |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists with multi-generational French manufacturing heritage anchor pricing discipline through captive component production and localized service networks. Their ownership structure enables long-term reparability investments under AGEC law without quarterly earnings pressure, compressing margin volatility while elevating total cost of ownership transparency for institutional buyers.
Pricing Analysis
Bundled full-lifecycle service contracts separate from unbundled transactional unit sales across French distribution channels. Three-tier pricing structure across premium connected, standard efficient, and economy replacement levels stratifies by energy rating tier and after-sales service inclusion. Pricing pressure stems from copper and rare earth input volatility transmitted through Asian compressor supplier concentration. Property managers in Lyon and Bordeaux exhibit highest price sensitivity due to bulk procurement scale, while Paris apartment renovators show lowest sensitivity when kitchen investments align with property value appreciation.
Supply Chain Analysis
Skilled technician availability constraints in Lyon and Marseille metropolitan zones compress aftermarket service capacity expansion timelines. Component manufacturing concentrates in China for rare earth processing, Chile for copper mining, and Germany for precision compressor assembly. Motor and heating element production draws from concentrated Asian suppliers with single-source vulnerability for variable-speed drives. Distribution runs through Île-de-France wholesale hubs serving renovation contractors, cross-border Belgian logistics platforms, and direct-to-installer channels in secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's household appliances market functions as a stable compounder where regulatory-driven replacement cycles under F-Gas and AGEC frameworks generate predictable demand visibility. Renovation activity in Paris and secondary city catch-up patterns provide secular expansion anchors.
For Market Incumbents: Deepen backward integration into compressor module assembly to offset Asian supplier concentration risk. Expand certified technician training pipelines in Marseille and Toulouse to capture AGEC-mandated repair service revenue. Defend against subscription-based entrants by bundling predictive maintenance into premium product tiers.
For New Entrants and Emerging Players: Furnished rental property managers in Bordeaux and Montpellier represent an underserved buyer archetype seeking lifecycle-inclusive appliance packages. Occitanie's lagging renovation cycle offers geographic white space with less incumbent saturation. Direct sales partnerships with regional property developers bypass established retail channel barriers.
For Investors and Strategic Acquirers: European home energy management platform providers are the most active acquirer in this space, seeking appliance connectivity integration capabilities. Five-to-ten year viability hinges on reparability compliance infrastructure and localized production footprints. Monitor F-Gas Regulation amendment timing as inflection signal for refrigerant technology transition investment windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Reparability Index Compliance Investment | AGEC law mandates ten-year spare parts availability, forcing modular redesign of sealed refrigeration systems. |
| Smart Appliance Platform Integration | WiFi-connected units sync with home energy management systems in Paris fiber-enabled arrondissements. |
| Certified Pre-Owned Network Development | AGEC repair fund incentives enable warranty-backed refurbishment channels in Toulouse and Montpellier. |
| Technician Training Pipeline Expansion | Vocational output trails demand in Lyon and Marseille, creating captive service network advantages. |
| Hybrid Cooking-Climate System Launch | Heat pump integration aligns with France's national energy transition electrification targets. |
Research Methodology
Multiple input streams — executive interviews with appliance manufacturer product strategists, procurement directors at Île-de-France property developers, and aftermarket service network managers — were reconciled against customs trade records, ANSM safety filing databases, and EU Ecodesign regulatory disclosures. Secondary validation drew from AGEC implementation guidance documents, F-Gas Regulation amendment tracking, and regional renovation permit data. Bottom-up unit shipment modeling and top-down household penetration analysis were triangulated to establish market sizing.
Data-stream reconciliation across product type, technology tier, end-user category, and regional adoption pattern dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from replacement cycle velocity analysis and renovation rate projections. Compressor supplier concentration indices and electricity tariff trajectory assumptions informed input cost sensitivity testing.
Underlying measurement precision varies by segment; refrigerators and washing machines carry tighter precision than emerging subscription service categories due to established shipment reporting. Forecasts reflect assumptions on regulatory timeline adherence and broadband infrastructure rollout pace. Material deviation in F-Gas phase-down acceleration or AGEC enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Major Home Appliances Market
Home Appliances
Refrigerator Market
Home Appliances
United Kingdom Small Home Appliances Market
Home Appliances
US Household Appliances Market
Home Appliances
Chile Home Appliances Market
Home Appliances
United States Small Home Appliances Market
Home Appliances
United States Major Home Appliances Market
Home Appliances
Latin America Home Appliances Market
Home Appliances
France Home Appliances Market
Home Appliances
UAE Home Appliances Market
Home Appliances
Qatar Small Home Appliances Market
Home Appliances
Australia Washing Machine Market
Home Appliances
United States Laundry Appliances Market
Home Appliances
Global Residential Microwave Oven Market
Home Appliances
Egypt Small Home Appliances Market
Home Appliances
Merchandizing Refrigerators Market