
 Brazil Laundry Appliances Market | 2026-2036
Brazil Laundry Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Laundry Appliances Market Outlook
Smart connectivity and inverter motor technology is reshaping how laundry appliances are engineered for Brazilian consumers. Samsung Electronics leverages its IoT ecosystem to differentiate connected washers through app-based cycle control and remote diagnostics. Brastemp anchors its position with deep manufacturing roots in Rio Claro and a product range calibrated to local voltage and water pressure conditions. Whirlpool SA competes through extensive service networks that sustain brand loyalty across secondary cities.
Brazil laundry appliances comprise electromechanical systems designed for fabric cleaning and drying, typically operating on 127V or 220V single-phase supply with drum capacities from 8 kg to 16 kg for residential units. These machines employ either agitator or impeller wash action, with spin speeds reaching 1,400 RPM in premium configurations, serving the essential household function of automated garment maintenance. Washing machines dominate volume shipments, though energy efficient technology commands disproportionate margin contribution as electricity tariffs pressure operating cost sensitivity. Smart appliances represent the fastest-expanding technology segment, while commercial laundries drive institutional demand for heavy-duty cycle durability and load capacity above 20 kg.
ANVISA and INMETRO jointly govern appliance safety and efficiency compliance, with INMETRO's Conformity Assessment Program mandating minimum performance thresholds that filter lower-tier imports from formal channels. The country's national energy regulator, ANEEL, indirectly shapes demand through tiered residential electricity pricing that amplifies the total cost of ownership gap between conventional and inverter-driven machines. Stakeholders must monitor how municipal water rationing protocols in drought-prone states could accelerate specification requirements for low-consumption rinse cycles.
Market Dynamics
Urban electrification gaps and INMETRO efficiency mandates are compressing the viable product set for Brazilian manufacturers, forcing portfolio rationalization toward inverter-motor platforms that satisfy both voltage fluctuation tolerance and A-label consumption thresholds.
Growth Catalysts
- INMETRO Conformity Assessment Program:Mandatory efficiency labeling filters low-performance imports from formal distribution channels, clearing shelf space for certified domestic producers in Southeast retail networks.
- Apartment densification in São Paulo:Middle-class vertical housing stock is expanding at triple the rate of single-family construction, concentrating demand for compact 8-10 kg front-load configurations with stackable dryer pairing.
- Inverter motor adoption:Brushless DC drive systems cut energy draw by 40% versus conventional universal motors, aligning household purchasing decisions with ANEEL tiered tariff structures that penalize consumption spikes.
Market Restraints
- Copper and steel input volatility:Drum assemblies and motor windings depend on commodity-priced metals whose exchange-rate amplification squeezes margin on entry-tier SKUs priced below BRL 2,000.
- Southeast manufacturing concentration:Rio Claro and Curitiba industrial corridors host over 70% of domestic assembly capacity, exposing supply continuity to localized logistics disruptions or labor actions.
- Semi-automatic residual demand:Informal settlements and rural Northeast municipalities sustain parallel markets for low-cost twin-tub units that undercut fully automatic upgrade cycles.
Strategic Opportunities
- North and Northeast underpenetration:Ceará and Pernambuco states exhibit sub-45% automatic washer household penetration versus 78% in São Paulo, creating whitespace for regional distribution partnerships.
- Commercial laundry services:Shared-facility models in university dormitories and co-living developments require 20+ kg industrial units with payment-system integration, a segment distinct from residential procurement.
- ANEEL demand-response incentives:Grid-stabilization programs reward appliance-level load flexibility, enabling manufacturers to bundle smart-cycle scheduling as a utility-bill reduction feature.
Industry Challenges
- Inverter drive firmware certification:ANATEL radio-frequency approvals for WiFi-enabled machines add 90-120 days to product launch timelines, compressing competitive response windows.
- Service technician specialization:Diagnostic and repair of electronically commutated motors requires training investment that legacy electromechanical repair networks have not completed.
- Water pressure adaptation:Municipal distribution variance between 0.5 and 4.0 bar across Brazilian cities forces SKU proliferation or compromise on rinse performance consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Laundry Appliances Market |
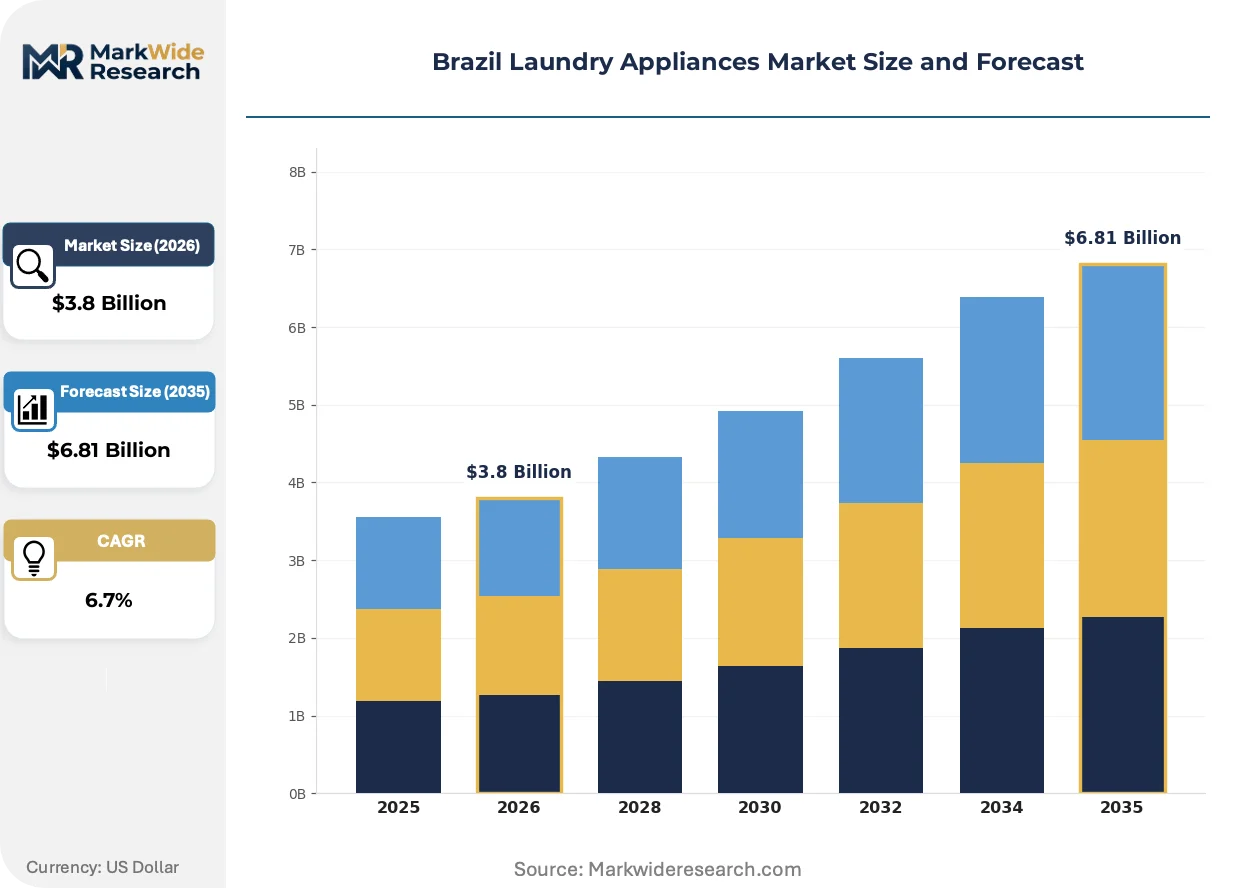
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Washing Machines, Dryers, Washer-Dryer Combos, Spin Dryers Technology: Smart Appliances, Conventional Machines, Energy Efficient, Top Load End User: Households, Commercial Laundries, Hotels, Dry Cleaning Services Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Samsung Electronics, Brastemp, Whirlpool SA, Toshiba Brasil, Colormaq, Electrolux, Midea Carrier, Robert Bosch Ltda., LG Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Laundry Appliances Market Strategic Shifts
Connected appliance ecosystems and precision motor control are redefining how Brazilian households interact with laundry equipment, shifting competitive advantage from mechanical durability to software-enabled service differentiation.
Direct-drive inverter technology eliminates belt-and-pulley transmission systems, replacing them with rotor-stator configurations that adjust torque in real-time based on load imbalance sensors. São Paulo apartment dwellers are adopting these platforms fastest, prioritizing vibration reduction in high-rise installations. This architecture is digitizing maintenance scheduling through embedded current-draw monitoring that predicts bearing wear before failure.
INMETRO's 2024 revision to Ordinance 371 tightened maximum allowable water consumption per kilogram of rated capacity, eliminating several legacy agitator designs from the approved product list. Manufacturers must now submit third-party test reports for every drum size variant, adding documentation burden but creating regulatory moats against gray-market competitors. The Southeast retail channel is responding by consolidating shelf space behind A-label certified inventory and delisting non-compliant SKUs.
Retailer financing penetration has crossed 60% of transactions in major metropolitan areas, displacing upfront cash purchase as the dominant acquisition mode. Magazine Luiza and Casas Bahia are bundling extended warranty and installation into 24-month payment plans, capturing customer lifetime value through service attachment rather than hardware margin alone. This behavioral shift is most pronounced among first-time automatic washer buyers aged 25-34 in Rio de Janeiro and Belo Horizonte.
Brazil Laundry Appliances Market Segmentation
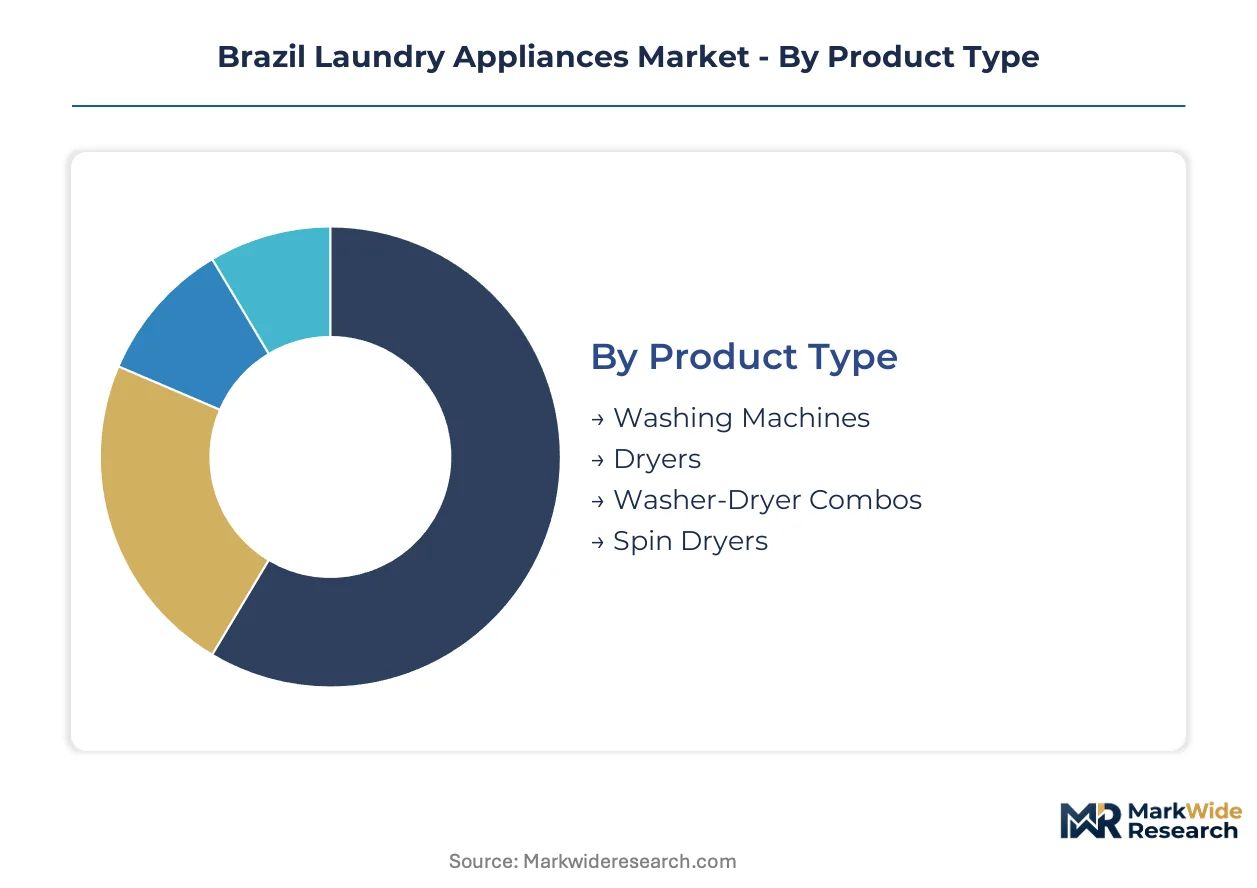
Brazil's laundry appliance market fragments across product architecture, digital capability, and procurement context. Each dimension shapes margin structure, certification burden, and service network requirements differently across Southeast manufacturing clusters and Northeast distribution frontiers.
Product Type:
Cost tier determines installation complexity, water infrastructure requirements, and financing penetration across Brazilian household segments.
- Washing Machines:Fully automatic front-load and top-load configurations with 8-16 kg drum capacity anchor residential demand. São Paulo apartment dwellers prioritize compact 8-10 kg units with stackable dryer pairing as vertical housing stock expands.
- Dryers:Vented and condenser units address humidity challenges in coastal municipalities. Rio de Janeiro's high-rise installations favor heat-pump models with lower ventilation retrofit costs despite premium positioning.
- Washer-Dryer Combos:Single-unit solutions serve space-constrained middle-class households with 10-12 kg wash capacity and 6-8 kg dry ratings. Curitiba's colder climate sustains higher adoption than tropical northern states.
- Spin Dryers:Semi-automatic extraction units persist in informal settlements and rural Northeast municipalities where electricity access limits fully automatic upgrade cycles.
Washing machines hold installed capacity. Dryers are rotating up the share rankings.
Technology:
Application context separates premium connected platforms from baseline electromechanical workhorses across voltage-fluctuation tolerance requirements.
- Smart Appliances:WiFi-enabled machines with app-based cycle control and remote diagnostics require ANATEL radio-frequency certification adding 90-120 days to launch timelines. São Paulo and Rio de Janeiro early adopters prioritize IoT ecosystem integration.
- Conventional Machines:Electromechanical control platforms with analog interfaces serve price-sensitive segments in secondary cities. These units avoid firmware certification burden but face INMETRO efficiency threshold pressure.
- Energy Efficient:Inverter-driven brushless DC motors cut consumption by 40% versus universal motor designs. ANEEL tiered tariffs amplify total cost of ownership advantage in high-consumption households.
- Top Load:Agitator and impeller configurations dominate legacy installed base. INMETRO's 2024 water consumption revisions eliminated several high-volume rinse designs from approved product lists.
Conventional machines hold installed capacity. Smart appliances are climbing the fastest.
End User:
Customer type dictates duty cycle intensity, payment system integration, and service response time requirements.
- Households:Residential procurement centers on 8-16 kg units with 5-15 cycle loads weekly. Magazine Luiza and Casas Bahia financing penetration crossed 60% in metropolitan areas, displacing upfront cash purchase.
- Commercial Laundries:Shared-facility models in university dormitories and co-living developments require 20+ kg industrial capacity with payment-system integration and heavy-duty cycle durability.
- Hotels:Hospitality procurement prioritizes continuous operation reliability and linen-specific programmability. Service network proximity outweighs initial hardware cost in purchase decisions.
- Dry Cleaning Services:Professional garment care operations combine wet cleaning and finishing equipment with specialized solvent handling requirements distinct from residential specifications.
Households hold installed capacity. Commercial laundries are gaining share fastest.
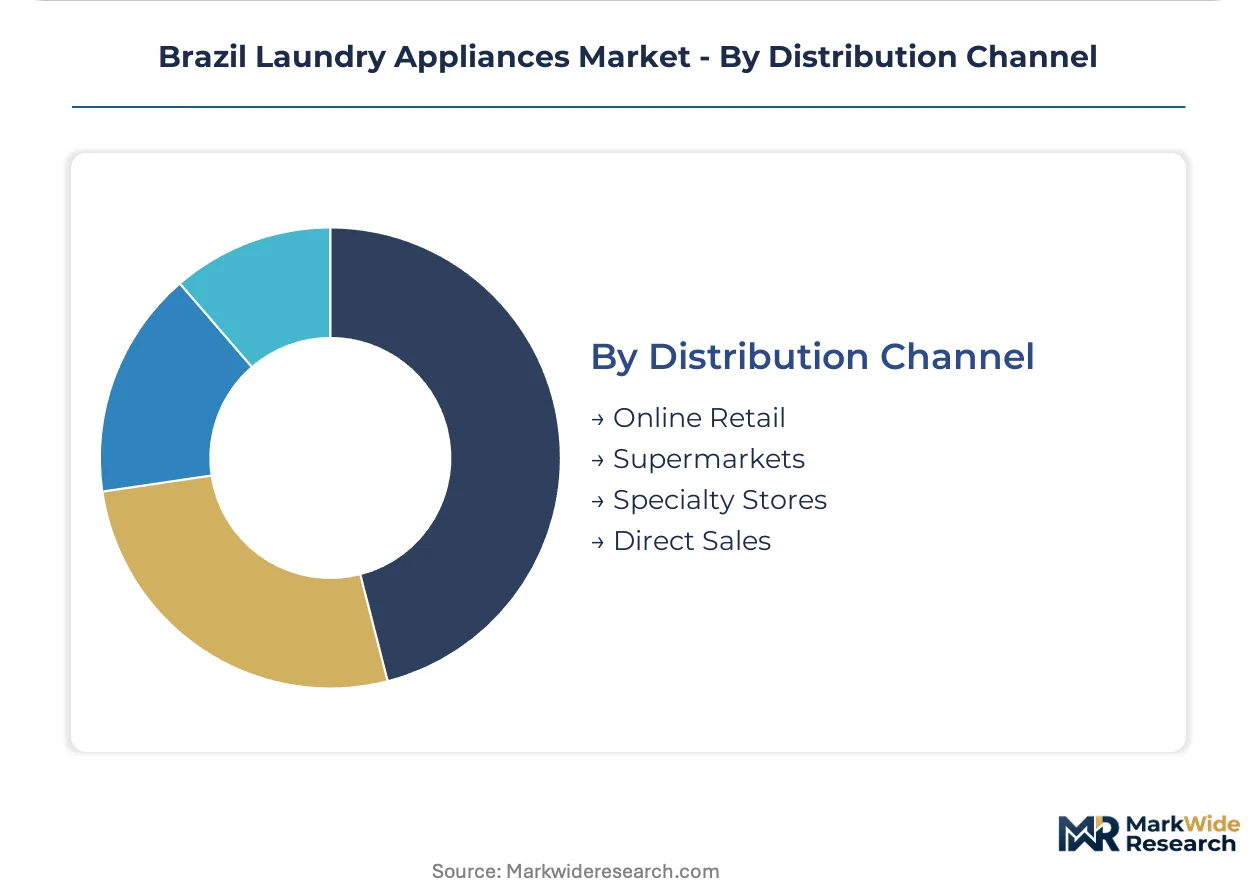
Distribution Channel:
Geography and margin capture separate digital-first acquisition from assisted selling environments requiring installation coordination.
- Online Retail:Digital platforms capture financing-integrated transactions among 25-34 year old first-time automatic washer buyers. Delivery and installation scheduling complexity limits penetration in Northeast logistics-constrained municipalities.
- Supermarkets:Hypermarket chains leverage foot traffic for entry-tier SKU impulse conversion. These channels concentrate in Southeast urban corridors with established appliance sections.
- Specialty Stores:Dedicated appliance retailers provide specification consultation and extended warranty attachment. Rio Claro manufacturing proximity supports inventory depth and service technician density.
- Direct Sales:Manufacturer-controlled channels serve commercial accounts and builder-installed specifications in new vertical housing developments.
Specialty stores hold installed capacity. Online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil exports washing machine components and sub-assemblies to Argentina and Chile, while importing inverter drive systems and smart modules from China and South Korea to feed Southeast assembly lines.
São Paulo
Vertical housing expansion in Guarulhos and Osasco concentrates demand for compact 8-10 kg front-load units with stackable configurations. INMETRO's Conformity Assessment Program filters non-compliant imports from formal retail channels in the metropolitan area. Brastemp maintains manufacturing roots in Rio Claro, supplying certified A-label inventory to Magazine Luiza and Casas Bahia networks.
Rio de Janeiro
High-rise installations in Barra da Tijuca and Centro prioritize heat-pump dryers with lower ventilation retrofit costs despite premium positioning. ANEEL tiered electricity tariffs amplify total cost of ownership advantages for inverter-driven machines in high-consumption coastal households. Samsung Electronics leverages its IoT ecosystem to differentiate connected washers through app-based cycle control in early adopter segments.
Minas Gerais
Belo Horizonte's middle-class apartment stock sustains financing penetration above 60% for first-time automatic washer buyers aged 25-34. Municipal water rationing protocols in drought-prone municipalities accelerate specification requirements for low-consumption rinse cycles. Whirlpool SA competes through extensive service networks that sustain brand loyalty across secondary cities in the state.
Rio Grande do Sul
Curitiba's colder climate sustains higher washer-dryer combo adoption than tropical northern states, with 10-12 kg wash capacity units preferred. ANATEL radio-frequency approvals for WiFi-enabled machines add 90-120 days to product launch timelines, compressing competitive response windows. The industrial corridor hosts assembly capacity serving the South region's replacement demand cycles.
Bahia
Salvador and northeastern municipalities exhibit sub-45% automatic washer household penetration versus 78% in São Paulo, creating whitespace for regional distribution partnerships. Semi-automatic twin-tub units persist in informal settlements, undercutting fully automatic upgrade cycles. Electrolux and Colormaq target this underpenetrated frontier through financing-integrated channel expansion.
Brazil Laundry Appliances Market Competitive Environment
On the supply side, the industry is consolidating around three strategic archetypes: multinational electronics conglomerates with IoT ecosystems, domestic manufacturers with deep manufacturing roots and local voltage calibration, and diversified appliance groups with extensive service networks. Competitive intensity centers on inverter motor platform differentiation and ANATEL certification speed. M&A activity targets regional distribution capabilities, while portfolio rationalization eliminates legacy agitator designs failing INMETRO's 2024 water consumption revisions.
Among multinational electronics conglomerates, Samsung Electronics and LG Electronics exemplify the connected appliance archetype, anchoring premium positioning through smart ecosystem integration. Brastemp and Whirlpool SA represent the domestic manufacturing and service network archetypes respectively. Robert Bosch Ltda. occupies a position bridging European engineering positioning with Brazilian assembly presence. Toshiba Brasil and Midea Carrier sit within the Asia-Pacific-origin diversified industrial group tier, leveraging scale advantages in component sourcing.
| Leading Market Players |
|---|
| Samsung Electronics |
| Brastemp |
| Whirlpool SA |
| Toshiba Brasil |
| Colormaq |
| Electrolux |
| Midea Carrier |
| Robert Bosch Ltda. |
| LG Electronics |
| Others |
Value Chain & Pricing Dynamics
Chinese inverter drive module suppliers anchor upstream concentration, feeding Southeast Brazilian assembly lines where margin pools concentrate in certified A-label inventory and extended warranty bundles rather than bare hardware.
Pricing Analysis
Current-gen inverter-motor platforms command 35-50% premiums over prior-gen universal motor designs, while next-gen connected units with ANATEL-certified WiFi modules stratify pricing further. Three-tier pricing structure across premium connected, standard inverter, and economy electromechanical levels dominates residential procurement. Certification grade under INMETRO's Conformity Assessment Program and after-sales service attachment drive price differentiation. Cost compression in entry-tier SKUs is intensifying because copper and steel input volatility amplifies exchange-rate exposure. First-time automatic washer buyers aged 25-34 in metropolitan Southeast exhibit highest price sensitivity, while hospitality procurement in coastal cities shows lowest.
Supply Chain Analysis
Extended payment terms from 90 to 120 days characterize supplier financing arrangements for Southeast Brazilian manufacturers sourcing inverter modules and smart control boards. China, South Korea, and domestic Rio Claro facilities concentrate component supply, with drum assemblies and motor windings drawing from commodity-priced metals. Raw material dependencies center on copper, cold-rolled steel, and electronic control modules. Single-source vulnerability in WiFi chipset supply creates ANATEL certification bottlenecks. Distribution runs through Magazine Luiza and Casas Bahia retail networks with integrated financing and installation scheduling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's laundry appliance market functions as a service-attach opportunity where extended warranty and installation bundling expand faster than hardware margin capture, particularly among first-time automatic washer buyers seeking payment plan integration.
For Market Incumbents: Build regulatory certification moats through accelerated ANATEL radio-frequency approval pipelines that compress competitive response windows against emerging Asian electronics entrants. Deepen backward integration into inverter motor winding capacity at Rio Claro to offset copper price volatility exposure. Consolidate shelf space behind A-label certified inventory as INMETRO's 2024 water consumption revisions eliminate legacy agitator designs. For New Entrants and Emerging Players: Build out regional distribution partnerships in Ceará and Pernambuco where automatic washer household penetration sits 30 points below São Paulo levels. Target commercial laundry services in university dormitories and co-living developments requiring 20+ kg industrial capacity with payment-system integration. Pursue financing-integrated channel expansion through Casas Bahia's existing credit infrastructure rather than greenfield retail buildout. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional distribution specialists holding Northeast logistics networks and municipal installer relationships. Long-term viability hinges on service network density rather than manufacturing scale given technician specialization requirements for electronically commutated motor repair. Monitor ANEEL demand-response incentive program expansion as inflection indicator for smart-cycle scheduling value capture.| Strategic Initiative | Industry Significance |
|---|---|
| INMETRO Certification Acceleration | Fast-tracked A-label approval clears shelf space ahead of competitors facing 90-120 day ANATEL delays. |
| Extended Warranty Bundling | Service attachment through Magazine Luiza financing plans captures customer lifetime value beyond hardware margin. |
| Northeast Distribution Partnership | Regional alliances in Bahia and Pernambuco access underpenetrated markets below 45% automatic washer penetration. |
| Inverter Motor Platform Standardization | Consolidated brushless DC architectures reduce SKU proliferation while satisfying ANEEL tiered tariff structures. |
| Commercial Laundry Vertical Entry | 20+ kg industrial units with payment integration serve shared-facility models in university and co-living segments. |
Study Parameters
Operator-level perspectives from appliance manufacturing plant managers, retail category buyers at Magazine Luiza and Casas Bahia, aftermarket service technicians, and INMETRO certification specialists anchored the qualitative base. These interviews combined with secondary validation from ANVISA regulatory filings, ANEEL electricity tariff disclosures, INMETRO approved product registry data, and Southeast Brazilian customs import records. Bottom-up shipment data triangulated against top-down household penetration estimates across São Paulo, Rio de Janeiro, and Northeast state capitals.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling demand trajectories under varying electrification expansion and municipal water rationing protocol intensities. Segmentation dimensions included product architecture, digital capability tier, end-user procurement context, and regional distribution channel structure. CAGRs derived from installed base replacement cycles, first-time buyer financing penetration curves, and commercial laundry service expansion rates. Voltage fluctuation tolerance requirements and water pressure adaptation variance across Brazilian cities informed unit specification modeling.
Stress conditions across copper and steel commodity price bands, exchange rate volatility corridors, and ANATEL certification timeline delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding INMETRO regulatory stability and ANEEL tariff structure continuity. Macroeconomic contraction, regulatory timeline extension, or connected appliance technology disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Europe Laundry Appliances Market
Home Appliances
Canada Laundry Appliances Market
Home Appliances
Europe Portable Washing Machine Market
Home Appliances
UAE Laundry Appliances Market
Home Appliances
White Goods Market
Home Appliances
Kuwait Major Home Appliances Market
Home Appliances
Portable Dehumidifier Market
Home Appliances
Bahrain Small Home Appliances Market
Home Appliances
UK Household Appliances Market
Home Appliances
China Major Home Appliances Market
Home Appliances
High-End French Door Refrigerator Market
Home Appliances
Egypt Home Appliances Market
Home Appliances
Household Electric Steamer Cooker Market
Home Appliances
India Small Home Appliances Market
Home Appliances
United Kingdom Major Home Appliances Market
Home Appliances
Europe Washing Machine Market