
 Egypt Home Appliances Market | 2026-2036
Egypt Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Home Appliances Market Analysis
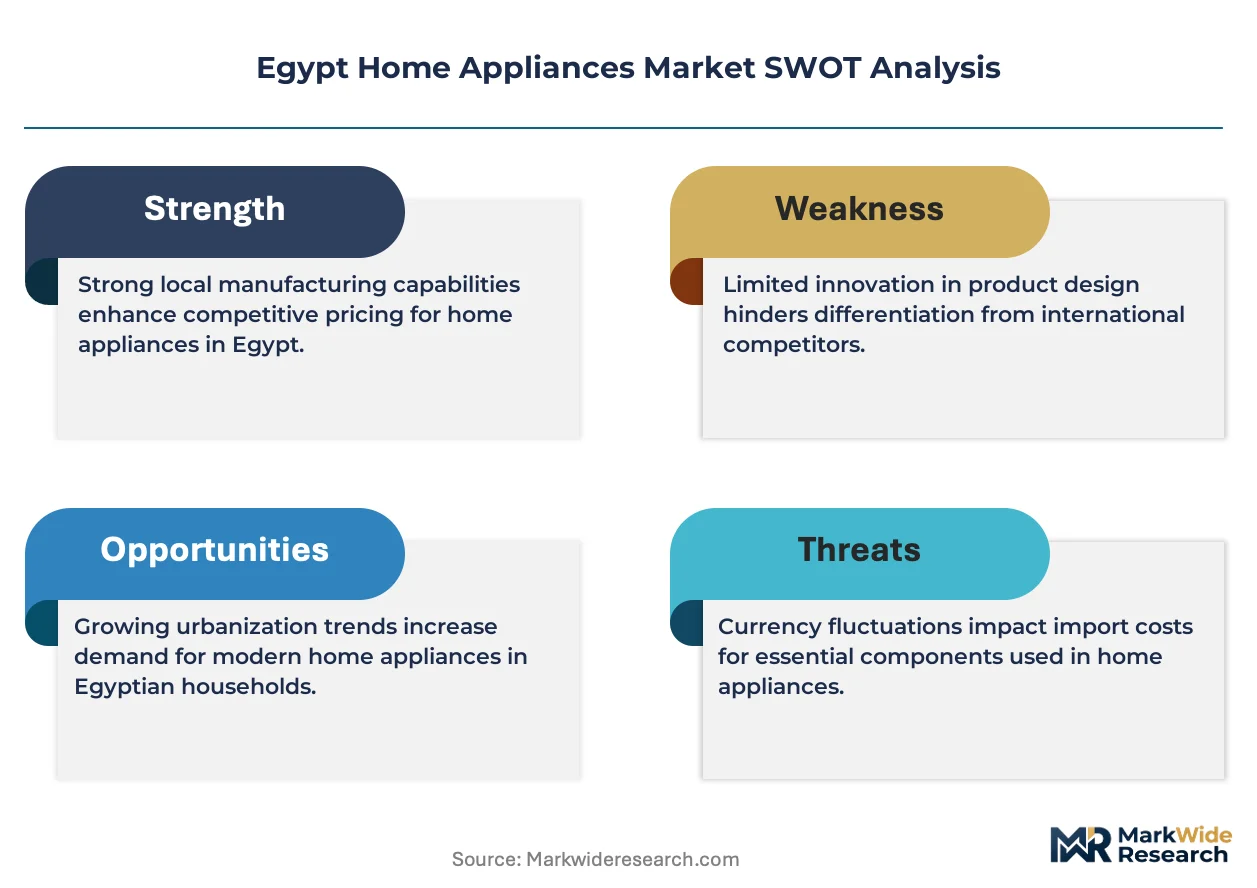
Egypt's mandatory energy efficiency labeling program is pivoting manufacturer priorities toward inverter-driven compressors and low-GWP refrigerants. ELARABY Group leverages its vertically integrated manufacturing complex in 10th of Ramadan City to dominate local refrigerator assembly. Samsung Electronics anchors premium positioning through smart connectivity features in its Cairo-serviced product lines. Fresh Electric competes aggressively on washing machine affordability for first-time buyers in Upper Egypt governorates.
Home appliances encompass electromechanical devices designed for domestic tasks, typically operating on 220V/50Hz Egyptian grid standards with insulation classes rated for ambient temperatures exceeding 40°C, primarily serving food preservation, garment care, thermal comfort, and meal preparation functions. Refrigerators and air conditioners occupy the largest margin pools given compressor technology barriers and seasonal replacement cycles tied to peak summer loads. Smart Appliances within the Technology dimension are attracting disproportionate R&D allocation as manufacturers integrate IoT modules for remote diagnostics and demand-response grid compatibility. The Residential end-user segment sustains volume leadership through government-subsidized housing programs and informal settlement upgrading initiatives.
EOSQ enforcement of efficiency tiers, combined with GOEIC import inspection protocols and EEA environmental compliance requirements, creates a multi-layered gatekeeping structure that favors locally certified production over grey-market imports. The country's central quality regulator periodically tightens testing protocols, forcing distributors to maintain updated conformity documentation or face customs detention. Stakeholders must monitor how forthcoming amendments to appliance safety standards reshape sourcing strategies for imported components and finished goods.
Market Dynamics
EOSQ efficiency labeling mandates are compressing margins for manufacturers while accelerating inverter compressor adoption across Nile Delta assembly lines. This regulatory pressure is reshaping procurement patterns for refrigeration and cooling equipment.
Growth Catalysts
- Urban housing expansion:Government-subsidized residential complexes in Greater Cairo and Alexandria are driving bulk procurement of energy-efficient cooling units for new household formation.
- EEA environmental compliance:Low-GWP refrigerant requirements are creating upgrade cycles for pre-2020 air conditioning stock ahead of enforcement deadlines.
- Electrification corridors:The Nile Delta corridor sustains above-national-average appliance penetration due to grid reliability and income concentration.
Market Restraints
- Compressor technology concentration:Inverter-driven compressor supply depends on a narrow base of specialized component suppliers, creating input bottlenecks for local assemblers.
- Import inspection friction:GOEIC customs protocols generate detention risk for grey-market finished goods, constraining price-competitive alternatives.
- Ambient temperature derating:Insulation class requirements for 40°C+ operating conditions add material cost burden versus temperate-climate imports.
Strategic Opportunities
- Upper Egypt governorates:First-time buyer penetration in garment care appliances remains underdeveloped relative to Delta household equipment rates.
- IoT-enabled demand response:Smart appliance connectivity aligns with EEA grid compatibility mandates for peak-load management programs.
- Informal settlement upgrading:Government infrastructure programs are creating addressable demand for durable cooling and food preservation equipment.
Industry Challenges
- Conformity documentation maintenance:Distributors face recurring compliance costs as EOSQ tightens testing protocols for imported components.
- Retooling capex cycles:Assembly lines require capital redeployment to handle low-GWP refrigerant handling and inverter electronics integration.
- Technician certification gaps:Inverter compressor diagnostics and smart module servicing outpace vocational training program output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Home Appliances Market |
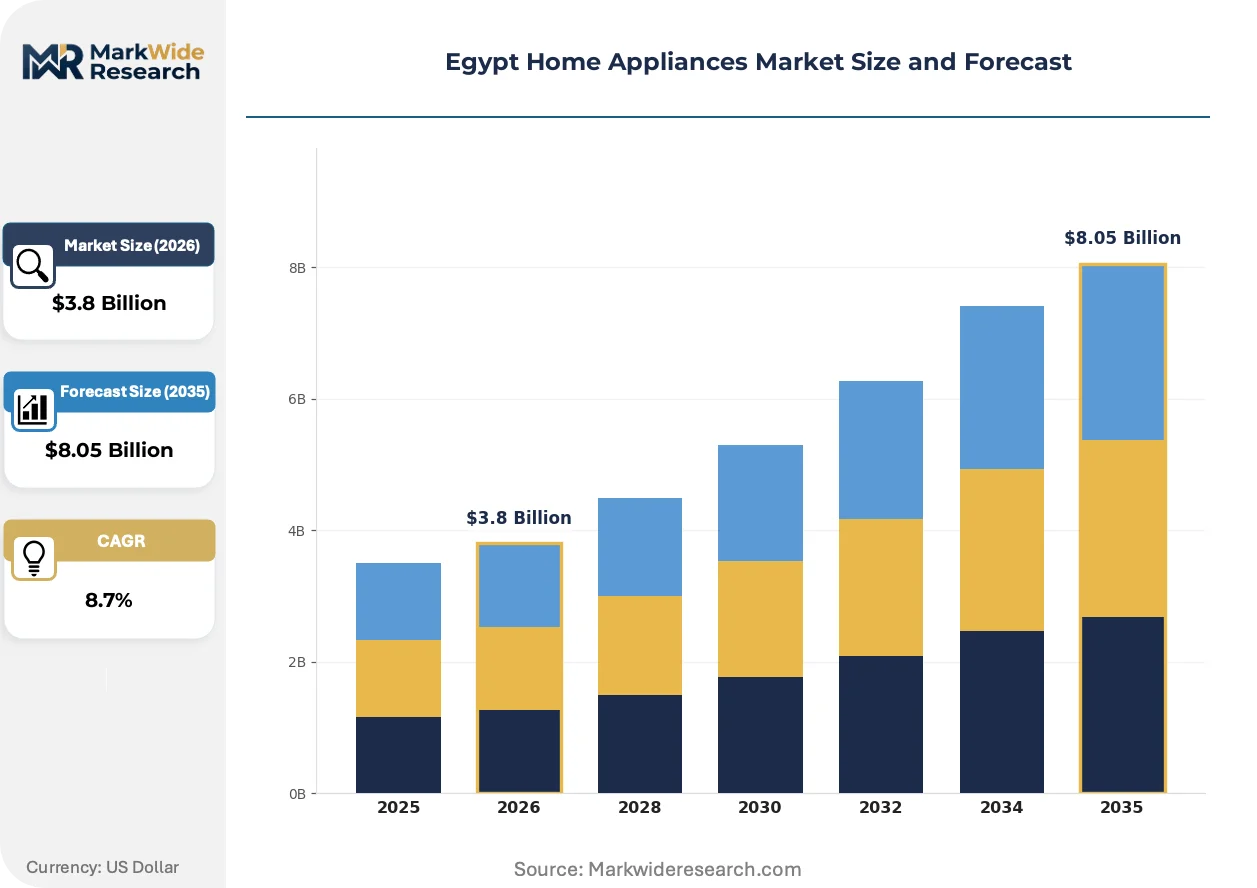
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Microwaves, Air Conditioners End User: Residential, Commercial, Retail, Institutional Technology: Smart Appliances, Energy-Efficient, Conventional, Hybrid Models Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | ELARABY Group, Electrolux Egypt, Fresh Electric, Unionaire Group Technology, Kiriazi Group, Bahgat Group, LG Electronics, Samsung Electronics, BSH Home Appliances, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Home Appliances Market Emerging Trajectories
Inverter compressor technology is compressing replacement cycles while smart connectivity modules are creating new service revenue streams. These shifts are altering how manufacturers and distributors capture value across the equipment lifecycle.
Variable-speed compressor architecture is decentralizing cooling load management across Egyptian residential installations. Upper Egypt first-time buyers are adopting inverter-driven units faster than projected as electricity tariff structures penalize peak-hour consumption. This technology is decentralizing demand patterns away from synchronized summer peak loads toward distributed, efficiency-optimized operation.
EOSQ appliance safety standard amendments are forcing distributors to pre-validate conformity documentation before customs clearance. The multi-layered gatekeeping structure favors locally certified production over import-dependent supply models. Refrigeration assemblers in 10th of Ramadan City industrial zones are responding by deepening backward integration into compressor housing and control module fabrication.
After-sales service unbundling is emerging as buyers separate equipment purchase from installation and maintenance contracts. Traditional dealer networks in Alexandria and Port Said are losing attach-rate revenue to independent service aggregators. This pattern concentrates in urban residential complexes where facility management companies negotiate bulk maintenance agreements separate from procurement decisions.
Egypt Home Appliances Market Segmentation
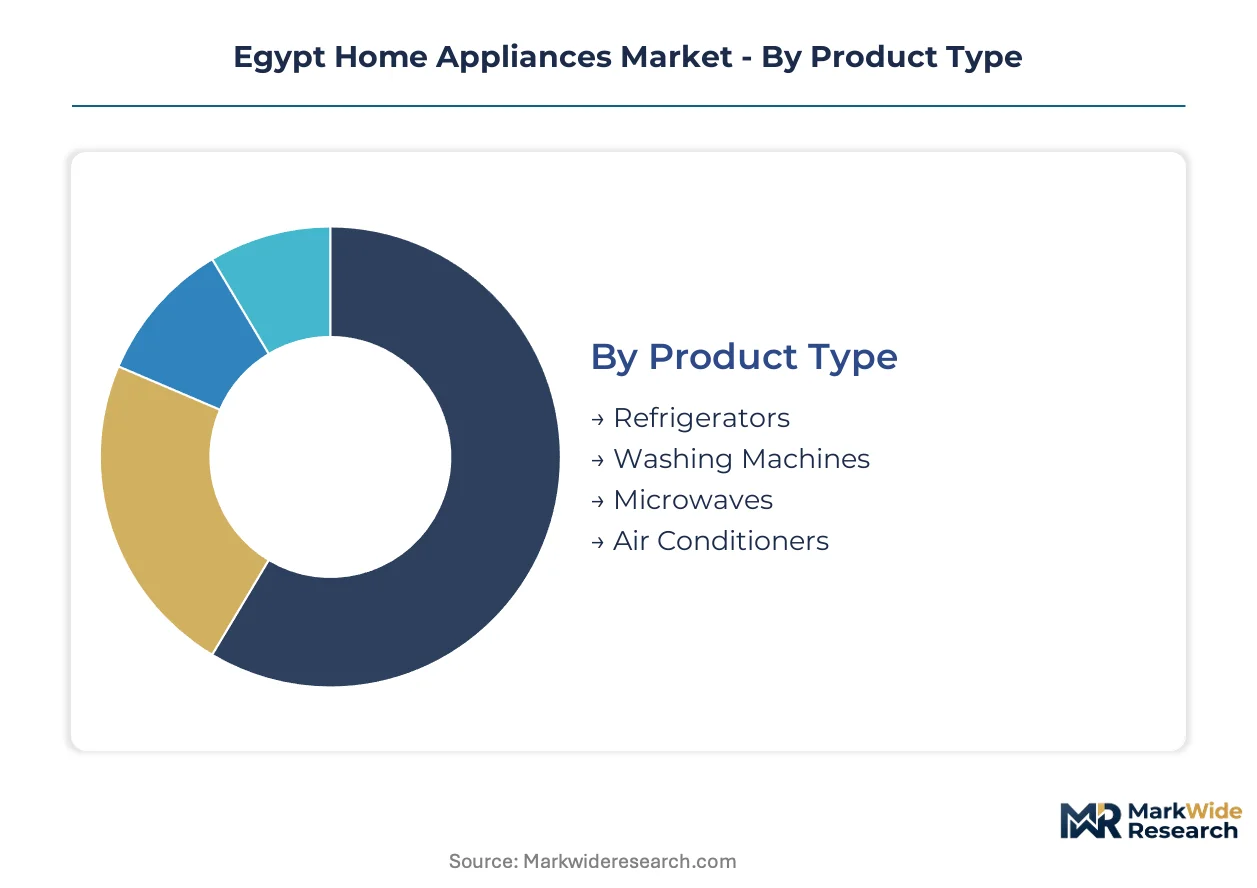
Segmentation in Egypt's home appliances market reveals how regulatory pressure, income stratification, and infrastructure gaps fragment demand across distinct buyer profiles and channel preferences. Understanding these fault lines clarifies where manufacturers must adapt specifications versus where standardization suffices.
Product Type:
Cost tiers separate replacement-driven buyers seeking compressor durability from first-time purchasers prioritizing entry-level affordability.
- Refrigerators:Units rated for 40°C+ ambient operation dominate procurement for Greater Cairo residential complexes, where EOSQ efficiency mandates have accelerated inverter compressor adoption. Nile Delta assemblers capture margin from backward integration into control module fabrication.
- Air Conditioners:Low-GWP refrigerant compatibility requirements are compressing replacement cycles ahead of EEA enforcement deadlines, with seasonal demand peaking ahead of summer grid loads. Alexandria's coastal humidity drives corrosion-resistant coil specifications distinct from Upper Egypt's dust-filtering priorities.
- Washing Machines:Garment care units for first-time buyers in Upper Egypt governorates compete aggressively on price-point accessibility.
- Microwaves:Meal preparation appliances concentrate in urban residential upgrades and informal settlement electrification programs.
Volume sits with refrigerators; growth tilts toward air conditioners.
End User:
Application context determines whether buyers prioritize smart connectivity, bulk procurement terms, or technician service availability.
- Residential:Government-subsidized housing programs in Greater Cairo sustain volume leadership, with household formation rates in the Delta corridor outpacing national averages. Facility management companies increasingly unbundle maintenance contracts from equipment procurement in new urban complexes.
- Commercial:Retail and hospitality installations demand peak-load compatibility for EEA grid demand-response programs.
- Retail:Appliance showroom operators face inventory financing constraints from GOEIC customs detention risks on grey-market imports.
- Institutional:School and hospital procurement runs through centralized tender processes with extended conformity documentation requirements.
Residential captures installed base dominance; commercial applications are climbing the fastest on efficiency-upgrade mandates.
Technology:
Margin structure varies sharply between certified efficiency tiers and uncertified conventional alternatives subject to customs friction.
- Smart Appliances:IoT-enabled modules for remote diagnostics align with EEA grid compatibility requirements, creating service revenue streams separate from hardware margins. Cairo-serviced premium lines anchor connectivity features as differentiation against Delta-assembled competitors.
- Energy-Efficient:Inverter-driven compressor architecture decentralizes cooling load management, with electricity tariff structures penalizing peak-hour consumption. EOSQ labeling mandates compress margins while accelerating technology adoption.
- Conventional:Fixed-speed units retain price-competitive positioning where import inspection protocols constrain grey-market alternatives.
- Hybrid Models:Dual-technology configurations target transitional buyers upgrading from conventional to connected systems.
Energy-efficient holds volume leadership; smart appliances show steepest expansion trajectory on R&D allocation shifts.
Distribution Channel:
Customer type and geography determine whether buyers value physical inspection, credit terms, or installation bundling.
- Offline Retail:Dealer networks in Alexandria and Port Said face attach-rate erosion as independent service aggregators capture maintenance contracts. Traditional showrooms retain strength where buyer education demands product demonstration.
- Online Retail:E-commerce platforms are gaining share in urban residential complexes where facility managers coordinate bulk procurement digitally.
- Direct Sales:Manufacturer-owned channels concentrate in premium smart appliance segments with extended warranty terms.
- Distributors:Wholesalers bear recurring compliance costs as EOSQ tightens testing protocols for imported component shipments.
Offline retail maintains transaction volume dominance; online channels are gaining share fastest among urban bulk buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egypt's appliance production clusters concentrate in industrial zones east of Cairo while consumption spreads unevenly across the Nile corridor. Local assemblers dominate refrigerator and washing machine output for Delta households. Import-dependent supply channels serve Upper Egypt and coastal markets where grey-market penetration historically ran higher.
Greater Cairo
Government-subsidized residential complexes in New Cairo and 6th of October City are driving bulk procurement of inverter-driven cooling units. EOSQ efficiency labeling mandates are compressing margins for distributors serving these developments. The 10th of Ramadan City industrial zone anchors refrigerator assembly with backward integration into control module fabrication.
Alexandria and the North Coast
Coastal humidity specifications distinguish air conditioner demand from interior governorates, with corrosion-resistant coil requirements adding material cost. The Port Said corridor faces attach-rate erosion as independent service aggregators capture maintenance contracts from traditional dealer networks. EEA environmental compliance deadlines are accelerating replacement cycles for pre-2020 refrigerant stock.
Nile Delta Governorates
Electrification rates and household formation in Sharqia, Dakahlia, and Gharbia outpace national averages, sustaining volume leadership in first-time appliance purchases. Grid reliability supports higher penetration of energy-efficient models with inverter compressors. Local assemblers leverage proximity to Cairo component suppliers for just-in-time refrigeration assembly.
Upper Egypt
First-time buyer penetration in garment care appliances remains underdeveloped relative to Delta equipment rates, creating price-point competition among washing machine suppliers. Electricity tariff structures penalizing peak-hour consumption are accelerating inverter adoption faster than projected. Informal settlement upgrading programs are creating addressable demand for durable cooling equipment in Asyut and Sohag.
Sinai and Red Sea Zones
Tourism-dependent hospitality installations demand peak-load compatibility for EEA grid demand-response programs in resort corridors. Seasonal demand concentration complicates inventory financing for distributors serving Sharm El-Sheikh and Hurghada. GOEIC customs detention risks constrain grey-market alternatives in these lower-volume markets.
Egypt Home Appliances Market Vendor Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive manufacturing infrastructure. Local assembly groups dominate mid-market refrigeration through vertically integrated production complexes. Multinational electronics brands anchor premium positioning through smart connectivity features and extended warranty networks. Strategic moves concentrate on backward integration into compressor housing fabrication and technician certification partnerships for inverter servicing.
Among locally integrated manufacturers, ELARABY Group and Kiriazi Group exemplify the conglomerate archetype with industrial park presence in Greater Cairo satellite zones. Fresh Electric occupies a position within the price-competitive tier targeting first-time buyers in underserved governorates. Samsung Electronics and LG Electronics represent the multinational premium vector, leveraging Cairo-serviced distribution for connected appliance rollouts.
| Leading Market Players |
|---|
| ELARABY Group |
| Electrolux Egypt |
| Fresh Electric |
| Unionaire Group Technology |
| Kiriazi Group |
| Bahgat Group |
| LG Electronics |
| Samsung Electronics |
| BSH Home Appliances |
| Others |
Supply Flow & Price Mechanics
Family-owned industrial conglomerates with captive manufacturing infrastructure in Greater Cairo satellite zones anchor both supply discipline and pricing power across Egypt's appliance sector. Their control over compressor housing fabrication and control module production insulates margin structures from import-dependent competitors facing GOEIC customs friction.
Pricing Analysis
Margin tightening in the mid-market tier reflects EOSQ efficiency labeling mandates compressing returns on conventional fixed-speed units. Three-tier pricing structure across premium, standard, and economy levels separates Cairo-serviced smart appliance lines from Delta-assembled efficiency-certified models and grey-market conventional alternatives. Price differentiation traces to certification grade and after-sales service bundling, with first-time buyers in Upper Egypt governorates exhibiting highest sensitivity to unbundled equipment pricing.
Supply Chain Analysis
Dual-sourcing requirements for inverter compressor electronics are forcing assemblers to qualify secondary suppliers beyond dominant East Asian component houses. Manufacturing inputs draw from China for control modules, South Korea for compressor technology, and domestic 10th of Ramadan City facilities for housing fabrication. Single-source vulnerability concentrates in specialized inverter electronics, while distribution runs through Alexandria and Port Said dealer networks facing attach-rate erosion from independent service aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's home appliances sector sits in a technology-transition phase where inverter-driven compressor architecture is systematically displacing fixed-speed legacy stock across residential cooling and refrigeration segments.
For Market Incumbents: Deploy backward integration into compressor housing fabrication to defend margin position against import-dependent distributors facing GOEIC detention risks. Deepen technician certification partnerships for inverter diagnostics to capture service revenue streams as after-sales contracts unbundle from equipment procurement. EOSQ safety standard amendments threaten non-compliant inventory positions. For New Entrants and Emerging Players: Begin with price-point accessible washing machine lines targeting first-time buyers in Asyut and Sohag where garment care penetration lags Delta household equipment rates. IoT-enabled demand-response compatibility offers differentiation for EEA grid compatibility mandates in commercial hospitality installations. For Investors and Strategic Acquirers: Distressed-cycle entries favor locally certified assemblers with EOSQ conformity documentation and 10th of Ramadan City industrial zone presence over import-dependent grey-market distributors. Long-term viability hinges on capturing inverter compressor service capabilities ahead of vocational training program output. Watch EEA environmental compliance enforcement deadlines as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Components | ELARABY Group's captive housing fabrication insulates margins from GOEIC import friction. |
| Technician Certification Partnerships | Inverter diagnostics training addresses servicing gaps outpacing vocational program output. |
| IoT Module Integration for Grid Compatibility | Smart connectivity aligns with EEA peak-load management mandates in commercial segments. |
| Low-GWP Refrigerant Retooling | Assembly line adaptation captures replacement cycles ahead of EEA enforcement deadlines. |
| Upper Egypt Distribution Expansion | First-time buyer penetration in garment care lags Delta rates, creating white-space opportunity. |
Methodological Framework
Trade customs records, EOSQ regulatory filings, and EEA environmental compliance databases formed the secondary backbone for this analysis. Primary interviews with appliance manufacturing executives, compressor component procurement leads, Alexandria dealer network operators, and facility management companies serving Greater Cairo residential complexes validated demand patterns. Bottom-up assembly volume estimates triangulated against top-down household formation and electrification rate projections.
Bottom-up modeling of unit shipments by product category, technology tier, and regional demand cluster anchored the analytical framework across the projection horizon. Segmentation dimensions included product type, end-user application, technology certification level, and distribution channel structure. CAGRs derived from fitted growth curves incorporating income elasticity estimates, replacement cycle assumptions, and regulatory compliance deadlines. Industry-specific inputs encompassed seasonal demand patterns tied to summer peak loads and informal settlement upgrading program timelines.
Underlying measurement precision varies by segment; inverter compressor adoption rates and smart appliance connectivity penetration carry tighter precision than conventional fixed-speed volume estimates. Forecasts reflect assumptions regarding EOSQ enforcement consistency, grid reliability improvements, and electricity tariff structures. Deviation in EEA environmental compliance timeline acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Americas Range Hood Market
Home Appliances
Egypt Major Home Appliances Market
Home Appliances
Russia Laundry Appliances Market
Home Appliances
India Major Home Appliances Market
Home Appliances
North America Small Home Appliances Market
Home Appliances
Slovakia Home Appliances Market
Home Appliances
North America Luxury Appliance Market
Home Appliances
Australia Washing Machine Market
Home Appliances
Asia-Pacific Home Appliances Market
Home Appliances
Household Induction Cooktops Market
Home Appliances
United States Small Home Appliances Market
Home Appliances
Japan Small Home Appliances Market
Home Appliances
Germany Major Home Appliance Market
Home Appliances
Australia Home Appliances Market
Home Appliances
Europe Small Home Appliances Market
Home Appliances
Kuwait Small Home Appliances Market