
 Europe Personal Care Appliances Market | 2026-2036
Europe Personal Care Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Personal Care Appliances Market Foresight
Professional end users are collapsing the historical dominance of household buyers in Europe's personal care appliances channel. Koninklijke Philips N.V. sustains its salon-grade cordless portfolio through intensive R&D spending on lithium-ion motor systems. Groupe SEB anchors its position via backward integration into ceramic heating element manufacturing for hair styling tools. Beurer GmbH differentiates through medical-grade certification pathways that open pharmacy distribution across German-speaking markets.
Europe personal care appliances comprise electrically powered devices for hair management, depilation, and skin grooming, typically integrating brushless DC motors, ceramic or tourmaline heating substrates, and lithium-polymer battery packs operating between 20V and 240V depending on application. These products serve consumer grooming routines and professional beauty services by reducing styling time and improving finish consistency through controlled thermal and mechanical energy delivery. Electric razors and hair dryers together occupy the largest revenue share, though epilators register the fastest expansion as at-home depilation displaces professional waxing services. The power rating segmentation reveals a structural migration toward medium and high power tiers, where manufacturers capture superior margins through ionic conditioning and precision temperature control features that command price premiums in specialty retail.
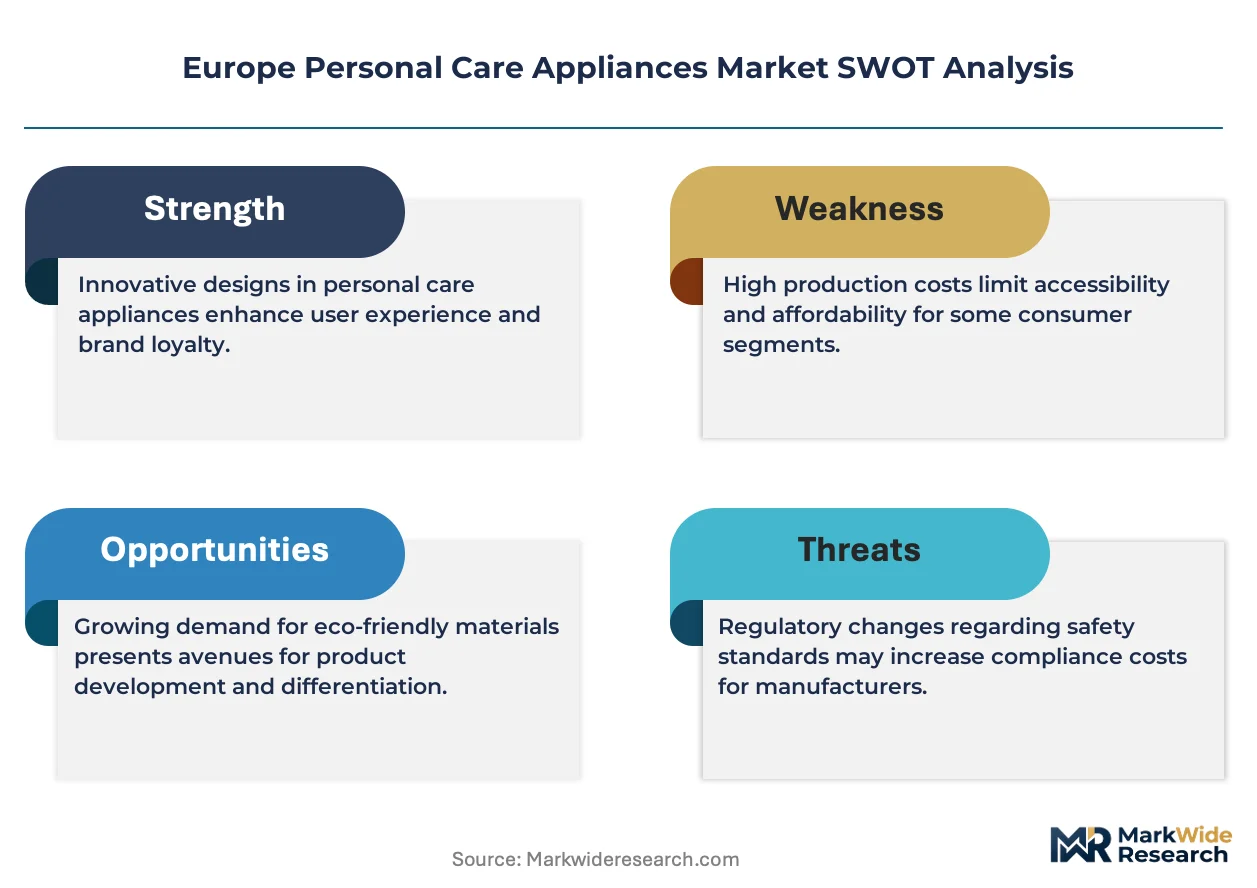
The EU Ecodesign Regulation and CE marking framework mandate minimum energy efficiency thresholds and electromagnetic compatibility standards for all mains-connected personal care appliances sold within the single market. ECHA oversight of substance restrictions under REACH compliance limits certain polymer formulations in device housings, compelling reformulation of grip materials and cord insulation. Germany's national implementation of EU energy labeling directives adds country-specific registration requirements that delay market entry for non-EU manufacturers. Stakeholders must monitor the EU's forthcoming right-to-repair legislation for small domestic appliances, which will mandate spare parts availability periods and disassembly instructions that reshape product architecture decisions during current development cycles.
Market Dynamics
The EU Ecodesign Regulation is compressing motor efficiency tolerances for hair dryers and electric razors, forcing manufacturers to redesign thermal management systems and electromagnetic architectures ahead of 2027 compliance deadlines.
Growth Catalysts
- Professional salon channel expansion:Battery energy density improvements in lithium-polymer cells enable cordless operation at salon-grade power outputs, pulling demand from household buyers toward commercial end users.
- REACH compliance reformulation:ECHA substance restrictions on polymer formulations in device housings accelerate adoption of bio-based grip materials that differentiate premium positioning.
- German metropolitan premium penetration:Households in Berlin, Munich and Hamburg demonstrate faster upgrade cycles for ionic conditioning and precision temperature control features than neighboring markets.
Market Restraints
- Lithium supply concentration:Battery cell manufacturing for cordless styling tools depends on cathode material supply chains concentrated outside the single market, exposing margin volatility to input cost swings.
- Motor efficiency physics:Brushless DC motor systems face thermal dissipation limits that constrain simultaneous achievement of high power output and EU Ecodesign efficiency thresholds.
- CE marking electromagnetic compatibility:Stricter EMC testing protocols for mains-connected appliances extend certification timelines and raise barrier to entry for new market entrants.
Strategic Opportunities
- Pharmacy distribution in German-speaking markets:Medical-grade certification pathways for dermatological appliances open shelf space in Apotheke channels underserved by conventional electronics retailers.
- Right-to-repair spare parts mandate:Forthcoming EU legislation mandating disassembly instructions and parts availability creates aftermarket service revenue streams for established manufacturers with captive technical documentation.
- Ceramic-tourmaline hybrid heating convergence:Integration of infrared-emitting mineral substrates with traditional resistive elements enables faster heat-up times that command price premiums in specialty retail.
Industry Challenges
- Electromechanical engineering talent scarcity:Shortage of specialists combining thermal management expertise with battery system integration slows product development cycles for cordless high-power appliances.
- REACH substance database navigation:Continuous updates to restricted chemical listings require dedicated regulatory affairs capacity to monitor SVHC candidate list expansions and reformulate housings accordingly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Personal Care Appliances Market |
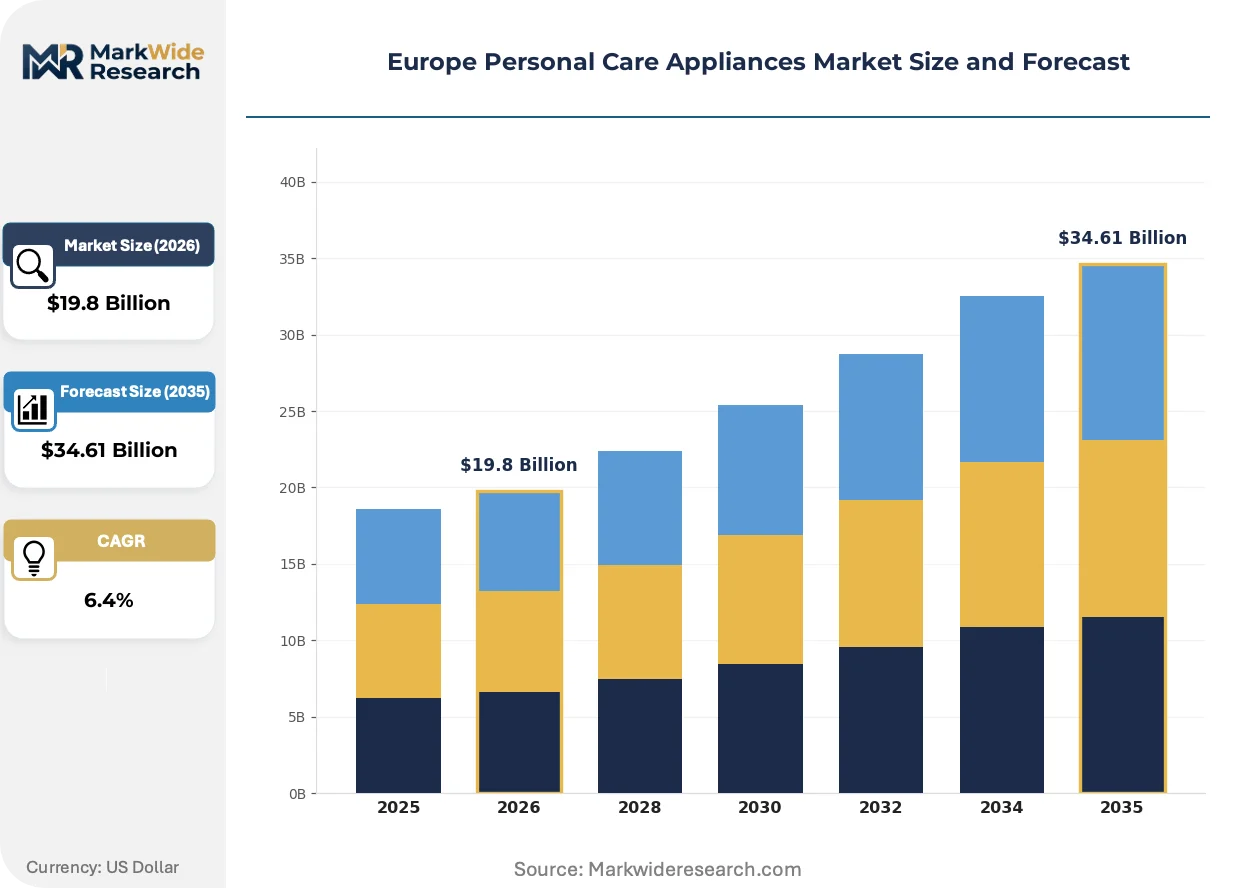
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $34.61 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hair Dryers, Electric Razors, Hair Straighteners, Epilators End User: Women, Men, Children, Professionals Power Rating: Low Power, Medium Power, High Power, Ultra High Power Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | Groupe SEB, Conair Corporation, Koninklijke Philips N.V., Beurer GmbH, Spectrum Brands Inc, Procter & Gamble Company, Panasonic Corporation, Braun GmbH, Dyson Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Personal Care Appliances Market Shifts & Advancements
Power delivery architectures and distribution channels are undergoing parallel transformation as professional end users reshape procurement patterns and regulatory pressure accelerates hardware redesign cycles.
Brushless DC motor systems with integrated gallium nitride power electronics are bifurcating the efficiency-performance tradeoff that previously forced compromise between thermal output and energy consumption. Salon operators in metropolitan France and the Netherlands are adopting these systems at replacement-cycle pace despite 40% price premiums over conventional motors. The technology is bifurcating manufacturer R&D roadmaps into high-efficiency compliance-focused lines and maximum-output professional-grade lines with divergent thermal architectures.
REACH substance restrictions under ECHA oversight are compelling reformulation of polymer formulations in device housings and cord insulation, with particular pressure on halogenated flame retardants and certain phthalate plasticizers. Industrial consequence includes accelerated qualification of bio-based thermoplastics and mineral-filled composites that maintain UL94 flame ratings while satisfying SVHC screening requirements. Hair dryer manufacturers targeting German and Austrian markets are responding fastest due to national implementation of stricter substance notification thresholds.
Pharmacy channel preference is displacing conventional electronics retail for dermatologically positioned appliances in German-speaking markets, where medical-grade certification functions as quality signal. Apotheke buyers seek devices with clinical validation documentation that specialty beauty retailers cannot supply, compressing distribution through Douglas and Sephora for certain product categories. This pattern concentrates in Bavaria and Baden-Württemberg where pharmacy density and consumer trust in Apotheke counsel remain highest.
Europe Personal Care Appliances Market Segmentation
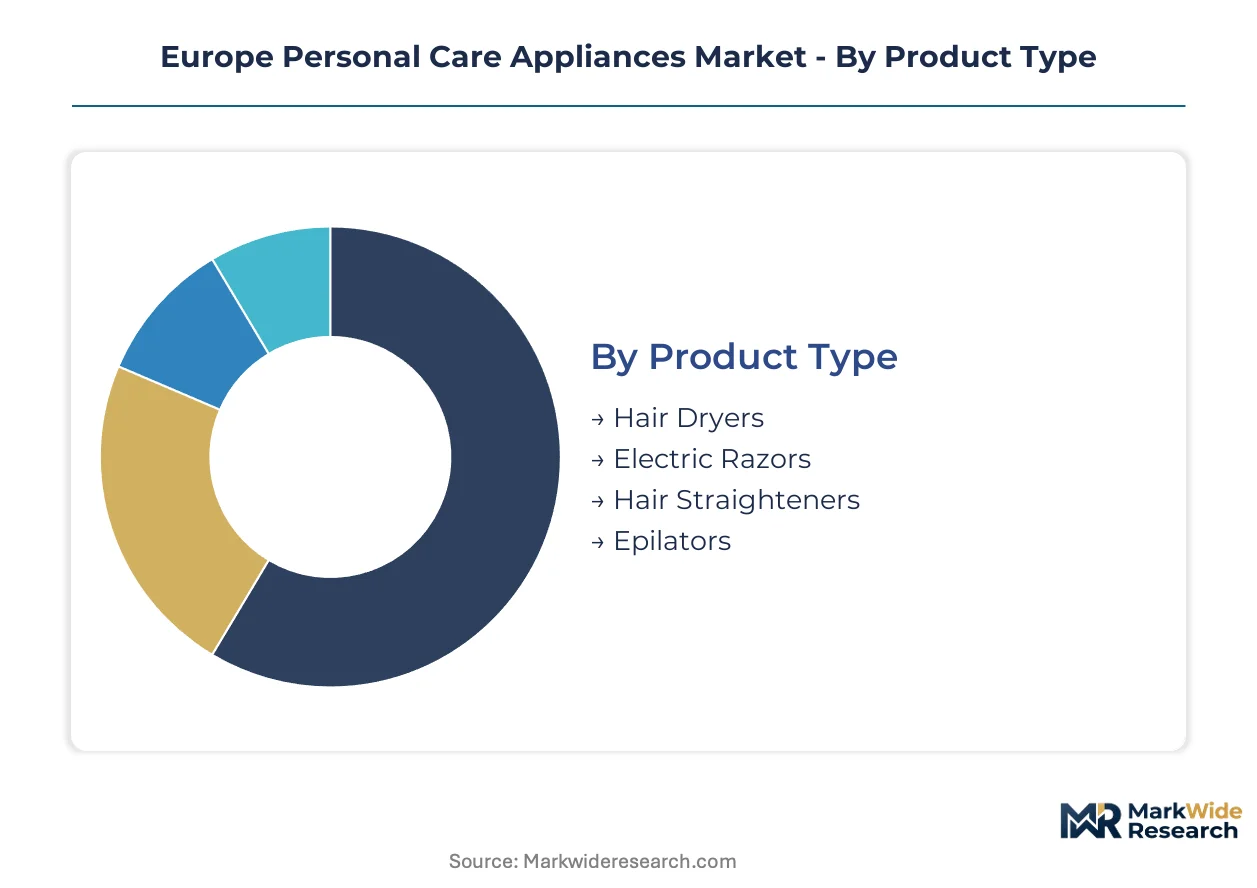
Segmentation in Europe's personal care appliances market reveals distinct procurement patterns across channels. Professional buyers and household consumers diverge sharply in power requirements and certification priorities, reshaping how manufacturers configure product portfolios.
Product Type:
Specialty electronics retailers carry the full product spectrum, while pharmacy channels concentrate on dermatologically tested variants and professional distributors stock salon-grade cordless systems.
- Hair Dryers:Ceramic and tourmaline heating substrates dominate premium positioning, with ionic conditioning features commanding shelf space in German metropolitan specialty stores. Berlin and Munich households upgrade these appliances faster than neighboring markets due to higher disposable income concentration.
- Electric Razors:Rotary and foil cutting systems integrate brushless DC motors with gallium nitride power electronics, bifurcating efficiency-performance tradeoffs. CE marking electromagnetic compatibility requirements extend certification timelines for new rotary head designs entering the single market.
- Hair Straighteners:Cordless lithium-polymer variants are displacing mains-connected units in professional salon procurement.
- Epilators:At-home depilation devices with precision tweezing discs are climbing the fastest as waxing service displacement accelerates in France and the Netherlands.
Hair dryers dominate installed base. Epilators are where expansion concentrates.
End User:
Customer type determines margin structure, with professional buyers accepting 40% price premiums for cordless salon-grade specifications while household purchasers remain price-sensitive.
- Women:Primary demand drivers span hair management and depilation categories, with pharmacy channel preference strongest in German-speaking markets where Apotheke certification signals quality.
- Men:Electric razor and grooming tool purchases concentrate in specialty electronics retail, though beard trimmer demand is pulling some volume toward online channels.
- Children:Safety-certified low-power appliances with rounded tip designs and automatic shutoff features occupy niche positioning.
- Professionals:Salon operators in metropolitan France and the Netherlands are adopting gallium nitride motor systems at replacement-cycle pace, prioritizing cordless operation over energy efficiency compliance.
Women constitute the largest addressable base. Professionals are where manufacturer R&D investment concentrates.
Power Rating:
Energy efficiency regulations and thermal output requirements create tiered performance ceilings that segment pricing architecture.
- Low Power:Travel-sized appliances and battery-operated trimmers serve portability needs, with lithium supply concentration outside the single market exposing margin volatility.
- Medium Power:Household hair dryers and epilators balance EU Ecodesign compliance with consumer performance expectations, capturing volume share in supermarket and online channels.
- High Power:Salon-grade cordless styling tools with 20V to 240V architectures enable professional thermal output, though brushless DC motor systems face thermal dissipation limits constraining simultaneous efficiency achievement.
- Ultra High Power:Industrial-duty appliances for high-throughput salon environments remain limited by battery energy density physics and REACH-compliant housing material availability.
Medium power captures household volume. High power is where premium positioning and margin expansion align.
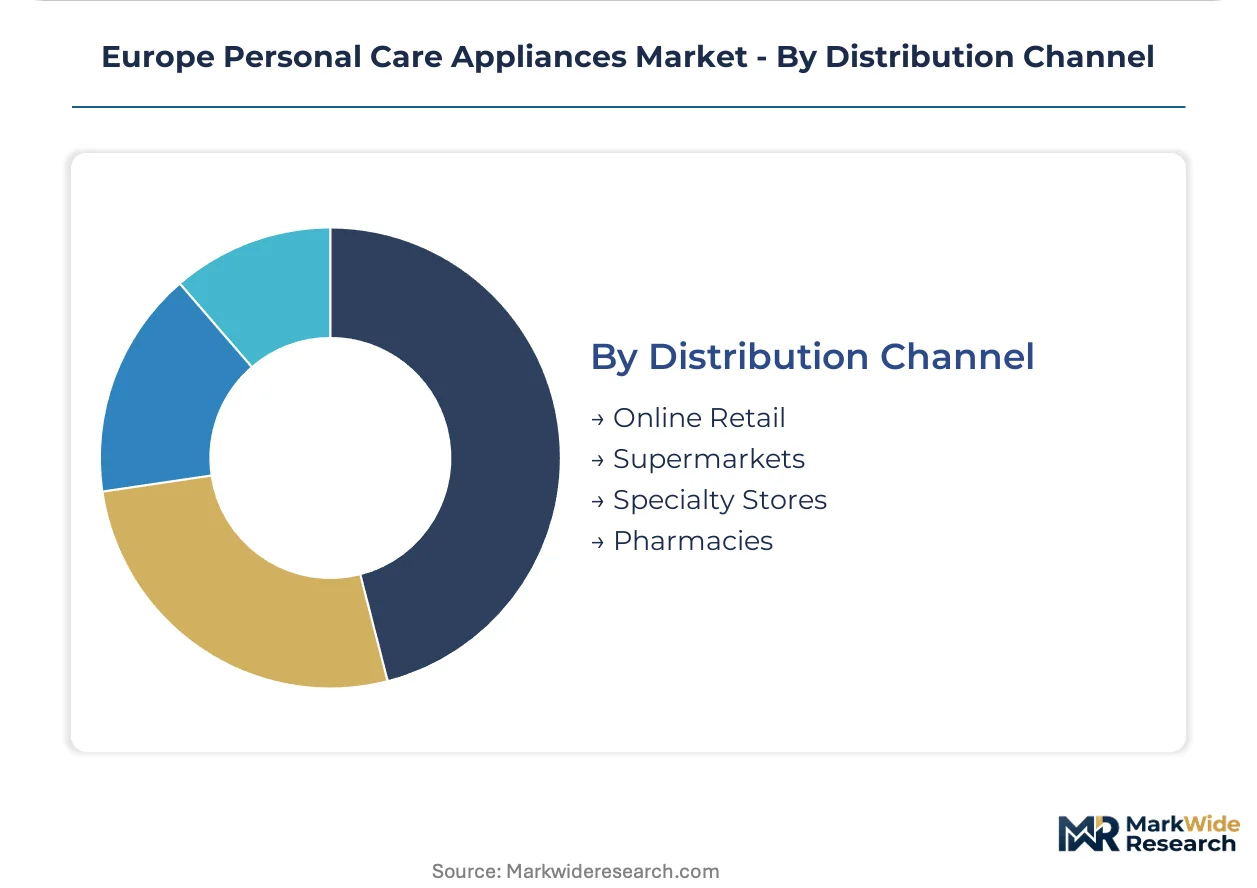
Distribution Channel:
Channel selection increasingly correlates with certification grade rather than price tier, fragmenting traditional retail hierarchies.
- Online Retail:E-commerce platforms aggregate comparison shopping for technical specifications, with German consumers showing highest propensity for direct-to-manufacturer purchasing.
- Supermarkets:Mass-market hair dryers and entry-level electric razors compete on promotional pricing, though shelf space is compressing as pharmacy channels expand.
- Specialty Stores:Douglas and Sephora retain positioning for beauty-oriented appliances, though medical-grade certification is pulling dermatological devices toward Apotheke channels in Bavaria and Baden-Württemberg.
- Pharmacies:Medical-grade certification pathways for dermatological appliances open shelf space underserved by conventional electronics retailers, with Beurer GmbH differentiation strategies exemplifying this channel shift.
Specialty stores retain premium beauty positioning. Pharmacies are where channel expansion for certified devices concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of personal care appliances concentrates in German-speaking industrial corridors, with component supply chains clustering around precision motor and ceramic substrate specialists in southern Germany and adjacent Austrian regions.
Germany
Metropolitan households in Berlin, Munich and Hamburg drive premium appliance replacement cycles faster than neighboring markets, with ionic conditioning features commanding particular shelf space. The country's national implementation of EU energy labeling directives adds registration requirements that delay market entry for non-EU manufacturers. Baden-Württemberg's industrial corridor hosts concentrated ceramic heating element production serving hair styling tool fabricators.
France
Salon operators in metropolitan France adopt gallium nitride motor systems at replacement-cycle pace, prioritizing cordless operation over energy efficiency compliance. ANSM oversight of dermatological device claims shapes marketing authorization pathways for pharmacy-channel appliances. The Île-de-France region concentrates professional beauty service demand that pulls manufacturer R&D investment toward salon-grade specifications.
Netherlands
Professional end users in Amsterdam and Rotterdam procurement channels demonstrate strongest preference for cordless lithium-polymer styling tools among Benelux markets. CE marking electromagnetic compatibility testing protocols extend certification timelines for new rotary head designs entering through Dutch distribution hubs. The Eindhoven region's electronics manufacturing heritage supports brushless DC motor system integration capabilities.
United Kingdom
Post-Brexit regulatory divergence creates parallel compliance tracks for appliances entering UK versus EU channels, doubling certification burden for manufacturers serving both markets. The country's national standards body maintains voluntary alignment with Ecodesign efficiency thresholds despite non-binding status. Greater London concentrates specialty retail demand for premium grooming appliances through department store channels.
Italy
Household purchasers in northern Italian markets show price sensitivity that compresses margin structures for mass-market hair dryer and epilator categories. The country's implementation of REACH substance restrictions through national chemical agency oversight accelerates housing material reformulation timelines. Lombardy's manufacturing base supplies precision mechanical components for electric razor cutting systems.
Europe Personal Care Appliances Market Competitive Landscape
Concentration sits with diversified appliance conglomerates and specialized personal care manufacturers competing across tiered price positioning. The vendor base splits between scale-driven mass-market suppliers and premium-positioned specialists commanding 40% price premiums for salon-grade cordless specifications. Two strategic archetypes dominate: vertically integrated producers controlling ceramic heating element supply, and medical-grade certification specialists accessing pharmacy distribution. Competitive moves center on backward integration into critical components and regulatory pathway diversification across CE marking and medical device frameworks.
Among diversified European appliance conglomerates, Groupe SEB and Koninklijke Philips N.V. exemplify scale-driven archetypes with broad personal care portfolios spanning household and professional channels. Beurer GmbH represents the medical-grade certification specialist archetype, with German GmbH structure signaling concentrated presence in German-speaking pharmacy distribution networks. These three companies occupy positions that reflect divergent strategic bets on channel access versus manufacturing control.
| Leading Market Players |
|---|
| Groupe SEB |
| Conair Corporation |
| Koninklijke Philips N.V. |
| Beurer GmbH |
| Spectrum Brands Inc |
| Procter & Gamble Company |
| Panasonic Corporation |
| Braun GmbH |
| Dyson Ltd. |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts with lithium-polymer cell manufacturers lock in cathode material access and stabilize input cost visibility for cordless styling tool producers navigating EU Ecodesign compliance timelines. These arrangements concentrate pricing power among buyers with balance sheet depth, while smaller fabricators face spot market volatility in battery-grade lithium carbonate sourcing.
Pricing Analysis
EU Ecodesign Regulation dictates the pricing tier structure across personal care appliances, separating salon-grade cordless systems with gallium nitride motor architectures from mass-market mains-connected units. Three-tier pricing structure across premium, standard, and economy levels aligns with certification grade—CE marking plus medical-grade pathways command 40% shelf price premiums in German pharmacy channels. Cost compression in entry-tier hair dryers is intensifying because supermarket buyers prioritize promotional pricing over feature differentiation. Household purchasers in Italian and Spanish markets exhibit highest price sensitivity, while professional salon operators in France and the Netherlands accept premium positioning for cordless operation.
Supply Chain Analysis
Inventory cycles for ceramic heating substrates and brushless DC motor systems stretch 12-16 weeks, constraining rapid product line pivots ahead of regulatory deadlines. Manufacturing concentrates in Germany, China, and Vietnam, with Baden-Württemberg hosting precision ceramic element fabrication and Guangdong province dominating lithium-polymer cell assembly. Raw material flows draw from Chilean lithium brine operations, Malaysian rare earth processing, and Ukrainian neon gas reserves for semiconductor-grade power electronics. Single-source vulnerability in cathode precursor chemicals exposes margin volatility to geopolitical disruption. Distribution runs through Dutch logistics hubs serving Benelux professional channels and direct-to-manufacturer platforms capturing German online retail volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interoperability between cordless styling tools and salon management software platforms is creating ecosystem lock-in dynamics that reshape procurement patterns across European metropolitan markets.
For Market Incumbents: Shield salon-grade market share by accelerating backward integration into gallium nitride power electronics manufacturing, eliminating dependency on Taiwanese semiconductor foundries. Capture captive technical documentation for forthcoming EU right-to-repair spare parts mandates, creating aftermarket service revenue barriers against emerging entrants. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in the Netherlands compresses electromagnetic compatibility certification timelines, opening household channel access ahead of compliance-heavy rivals. Target underpenetrated pharmacy distribution in Austrian and Swiss German-speaking markets where Apotheke certification signals quality differentiation. Lead with dermatological validation documentation that Douglas and Sephora cannot replicate. For Investors and Strategic Acquirers: Capital is best deployed toward medical-grade certification specialists with established pharmacy channel relationships and captive ceramic heating element production. Long-term viability hinges on regulatory pathway diversification across CE marking and medical device frameworks. Watch for lithium supply contract renegotiation announcements as inflection indicators for margin compression risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into GaN Power Electronics | Captive semiconductor supply eliminates Taiwanese foundry dependency for salon-grade motor systems. |
| Medical-Grade Certification Investment | ANSM and BfArM pathways unlock Apotheke shelf space in German-speaking metropolitan markets. |
| Right-to-Repair Documentation Buildout | Spare parts availability mandates create aftermarket revenue streams protected from new entrant competition. |
| Pharmacy Channel Partnership Expansion | Baden-Württemberg and Bavaria Apotheke networks concentrate highest consumer trust in dermatological positioning. |
| Lithium Supply Contract Restructuring | Long-term offtake agreements with Chilean brine operators hedge cathode material cost volatility. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with salon procurement managers, appliance brand managers, ceramic heating element plant engineers, and ECHA regulatory affairs specialists. Secondary validation drew from EU Ecodesign implementing measure drafts, REACH SVHC candidate list updates, German Federal Network Agency registration databases, and Benelux customs import records. Bottom-up unit shipment estimates triangulated against top-down manufacturer revenue disclosures.
Across the analysis window, forecasts model power rating tier migration, end-user channel shift from household to professional, and distribution fragmentation between pharmacy and specialty retail. CAGRs derive from segment-level growth rate blending weighted by base-year revenue contribution. Brushless DC motor adoption curves and lithium-polymer energy density improvement trajectories inform cordless product line penetration assumptions.
Underlying assumptions cover stable EU regulatory implementation timelines, with deviation risk concentrated in REACH substance restriction acceleration and lithium supply chain disruption. Forecasts reflect these conditions without claiming predictive certainty. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
South Africa Home Appliances Market
Home Appliances
Slovakia Home Appliances Market
Home Appliances
North America Home Appliances Market
Home Appliances
France Home Appliances Market
Home Appliances
Oman Small Home Appliances Market
Home Appliances
UK Household Appliances Market
Home Appliances
UAE Home Appliances Market
Home Appliances
Built-In Appliance Market
Home Appliances
Germany Small Home Appliance Market
Home Appliances
Steam Clothing Care System Market
Home Appliances
Saudi Arabia Major Home Appliances Market
Home Appliances
Colombia Home Appliances Market
Home Appliances
Kuwait Major Home Appliances Market
Home Appliances
China Small Home Appliances Market
Home Appliances
United Kingdom Major Home Appliances Market
Home Appliances
Qatar Small Home Appliances Market