
 Japan Household Appliance Market | 2026-2036
Japan Household Appliance Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Household Appliance Market Insights
Domestic production capacity around Osaka and Nagoya is hardening as yen volatility raises import costs for key components. Mitsubishi Electric Corporation leverages its in-house semiconductor fabrication to control inverter module supply for air conditioners. Panasonic Holdings Corporation anchors the refrigeration segment through proprietary nanoeX purification technology. Daikin Industries, Ltd. dominates heat-pump applications with vertically integrated compressor manufacturing in Sakai.
Japan household appliances encompass electrically powered devices designed for domestic tasks, typically operating at 100V/50-60Hz with stringent standby power limits below 1W under METI Top Runner standards. Refrigerators and washing machines represent mature, high-volume categories where margin pools have shifted toward after-service and consumable ecosystems. Smart appliances and IoT connectivity segments attract disproportionate R&D allocation as manufacturers embed AI-driven predictive maintenance and voice-control interoperability.
METI enforces Top Runner program efficiency benchmarks that tighten every three to five years, compelling redesigns of compressor and motor systems. JIS standards and PSE certification requirements create compliance barriers for non-domestic suppliers seeking retail placement. Stakeholders must monitor METI's next efficiency tier revisions and the interoperability standards emerging from Japan's Smart House initiative to anticipate platform consolidation risks.
Market Dynamics
Heat-pump technology and inverter-driven motor systems are compressing energy consumption benchmarks across refrigeration and climate-control categories, forcing wholesale redesigns of compressor architectures and thermal management subsystems.
Growth Catalysts
- METI Top Runner efficiency mandates:Three-to-five-year tightening cycles compel manufacturers to redesign motor and compressor systems, creating continuous refresh demand for high-efficiency replacements.
- Tokyo-Osaka urban condominium development:Premium residential towers specify connected kitchen ecosystems and integrated HVAC, concentrating appliance upgrade cycles in high-density Kanto and Kans corridors.
- Semiconductor integration:Inverter module costs are falling as domestic fabrication scales, enabling variable-speed drives in mid-tier washing machines and refrigerators previously limited to premium lines.
Market Restraints
- Yen-denominated component imports:Compressor valves and rare-earth magnets priced in dollars and yuan create margin volatility for Osaka and Nagoya assembly plants.
- Sakai-based compressor concentration:Heat-pump dryer manufacturing depends on a narrow geographic cluster for vertically integrated rotary compressor supply.
- JIS certification timelines:Refrigerant transition testing for next-generation heat pumps extends product launch windows by 8-14 months versus conventional models.
Strategic Opportunities
- Tohoku and Hokkaido rural electrification:Grid stabilization investments enable all-electric home conversion, expanding addressable market for induction cooking and heat-pump water heaters.
- AI-driven predictive maintenance:Sensor-embedded appliances generate recurring software revenue streams through subscription-based failure prediction and consumable replenishment.
- Smart House interoperability standards:Platform consolidation around ECHONET Lite and Matter protocols creates first-mover advantage for ecosystem-integrated appliance suites.
Industry Challenges
- Power electronics engineering scarcity:Inverter firmware and motor control algorithm expertise concentrates in legacy industrial drive manufacturers, constraining appliance OEM hiring pipelines.
- Refrigerant IP licensing complexity:Next-generation low-GWP formulations require cross-licensing between chemical suppliers and compressor OEMs, fragmenting supply negotiations.
- Legacy 100V/50-60Hz infrastructure:Dual-frequency grid requirements complicate platform standardization versus 230V single-frequency markets, limiting export scale economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Household Appliance Market |
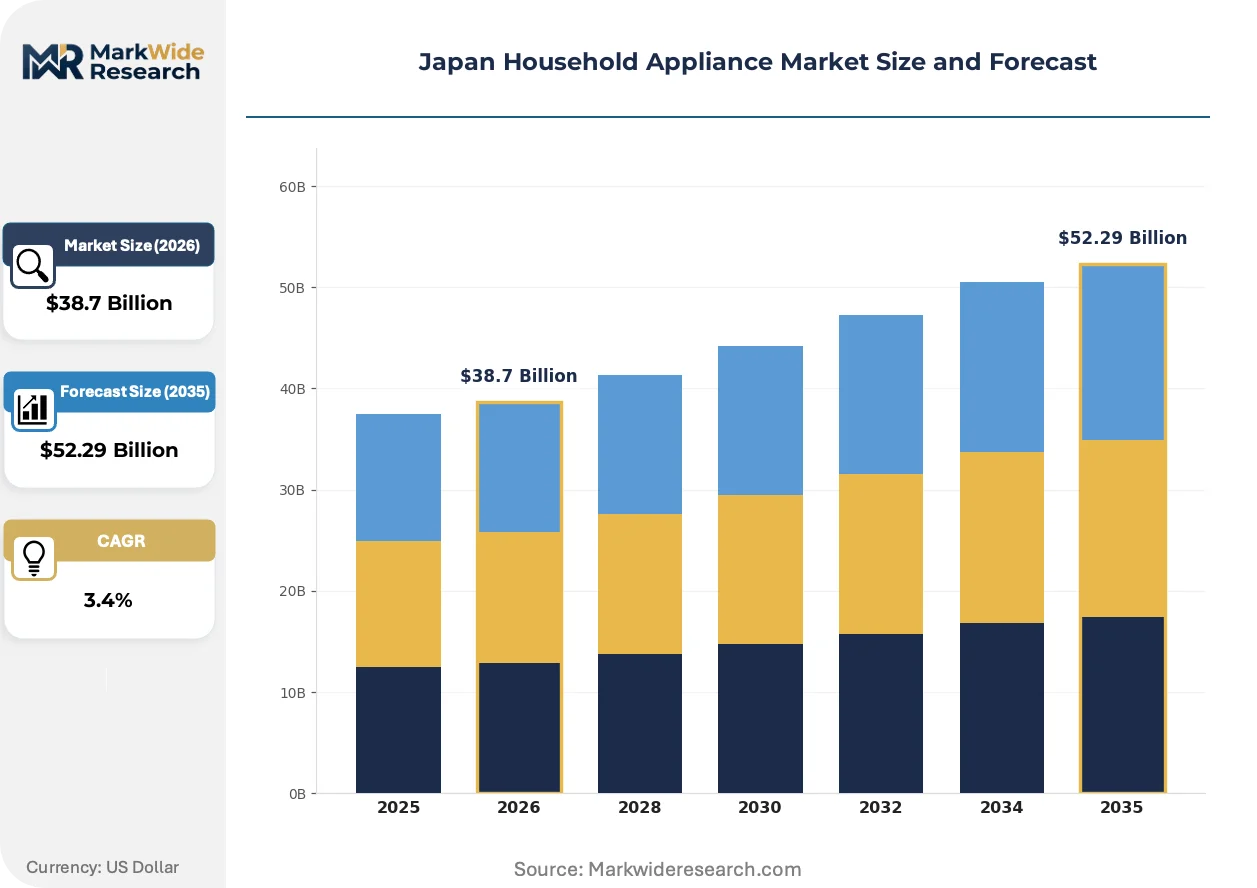
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $52.29 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
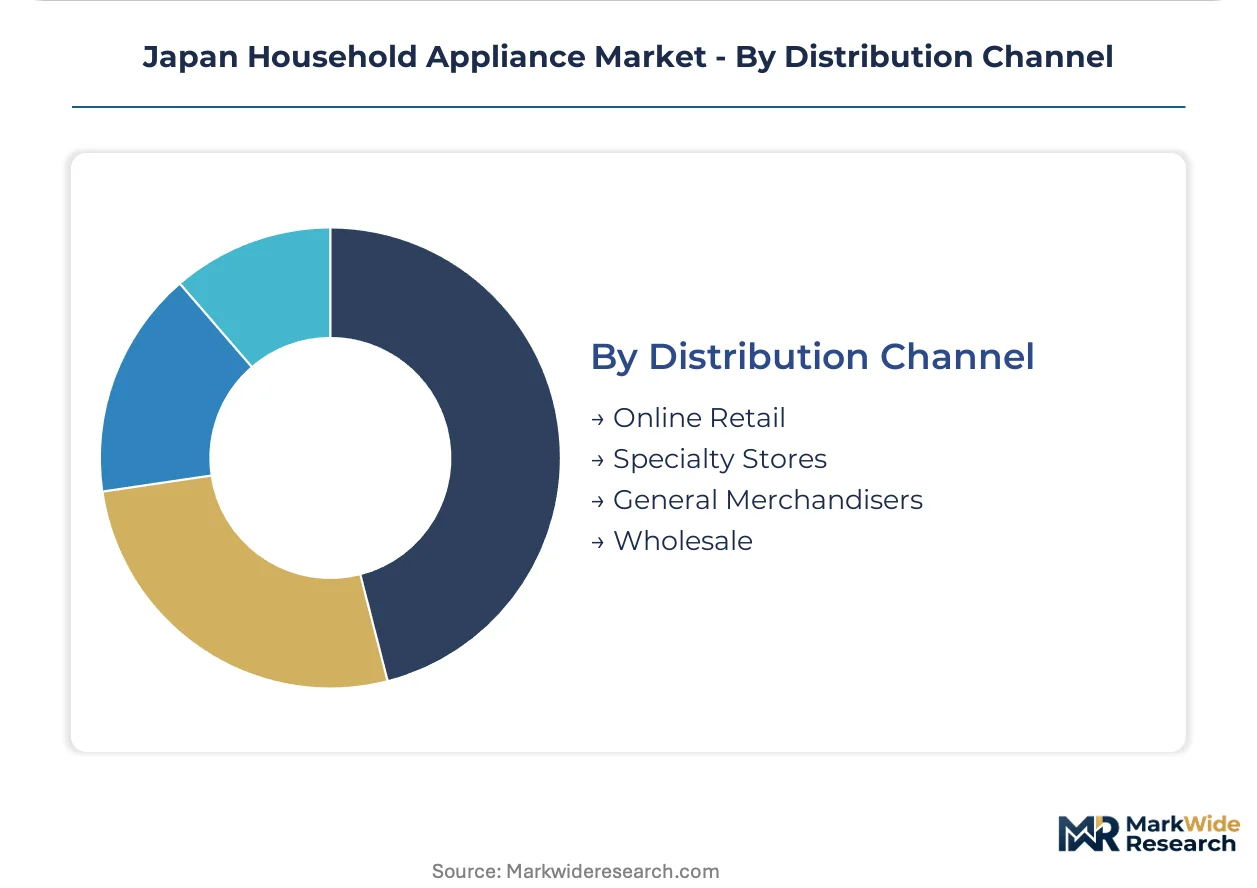
| Segmentation | Product Type: Refrigerators, Washing Machines, Microwaves, Vacuum Cleaners Technology: Smart Appliances, Energy-Efficient Devices, IoT Connectivity, Automated Systems End User: Households, Rental Properties, Hotels, Businesses Distribution Channel: Online Retail, Specialty Stores, General Merchandisers, Wholesale |
| Companies Covered | Mitsubishi Electric Corporation, Daikin Industries, Ltd., Panasonic Holdings Corporation, Samsung Electronics, LG Electronics, Hitachi Global Life Solutions, Toshiba Corporation, Sony Group Corporation, Sharp Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Household Appliance Market Trends and Innovations
Appliance architectures are fragmenting into connected subsystems that interoperate through standardized protocols, compressing the traditional monolithic product lifecycle into iterative software and hardware refresh cycles.
Heat-pump dryer technology is modularizing around separable compressor, heat exchanger, and control modules. Premium condominium developers in Tokyo's Minato and Chiyoda wards specify these as standard fitments, accelerating platform standardization. Component modularity is enabling field-upgradeable capacity scaling and reducing replacement part lead times from weeks to days.
METI's standby power regulations now enforce sub-1W limits across all appliance categories, including network-connected devices in sleep mode. Manufacturers must redesign power supply architectures and embedded controller sleep states, disproportionately affecting smart appliance lines with always-on connectivity. The refrigeration segment faces the steepest redesign burden due to continuous compressor cycling requirements.
Subscription-based consumable and filter replenishment is displacing transactional aftermarket sales. Premium buyers in Osaka's central wards now expect automated detergent and water-filter delivery triggered by usage telemetry. This model concentrates in high-rise developments with centralized logistics access, compressing traditional retail parts margins while securing recurring revenue streams for OEMs.
Japan Household Appliance Market Segmentation
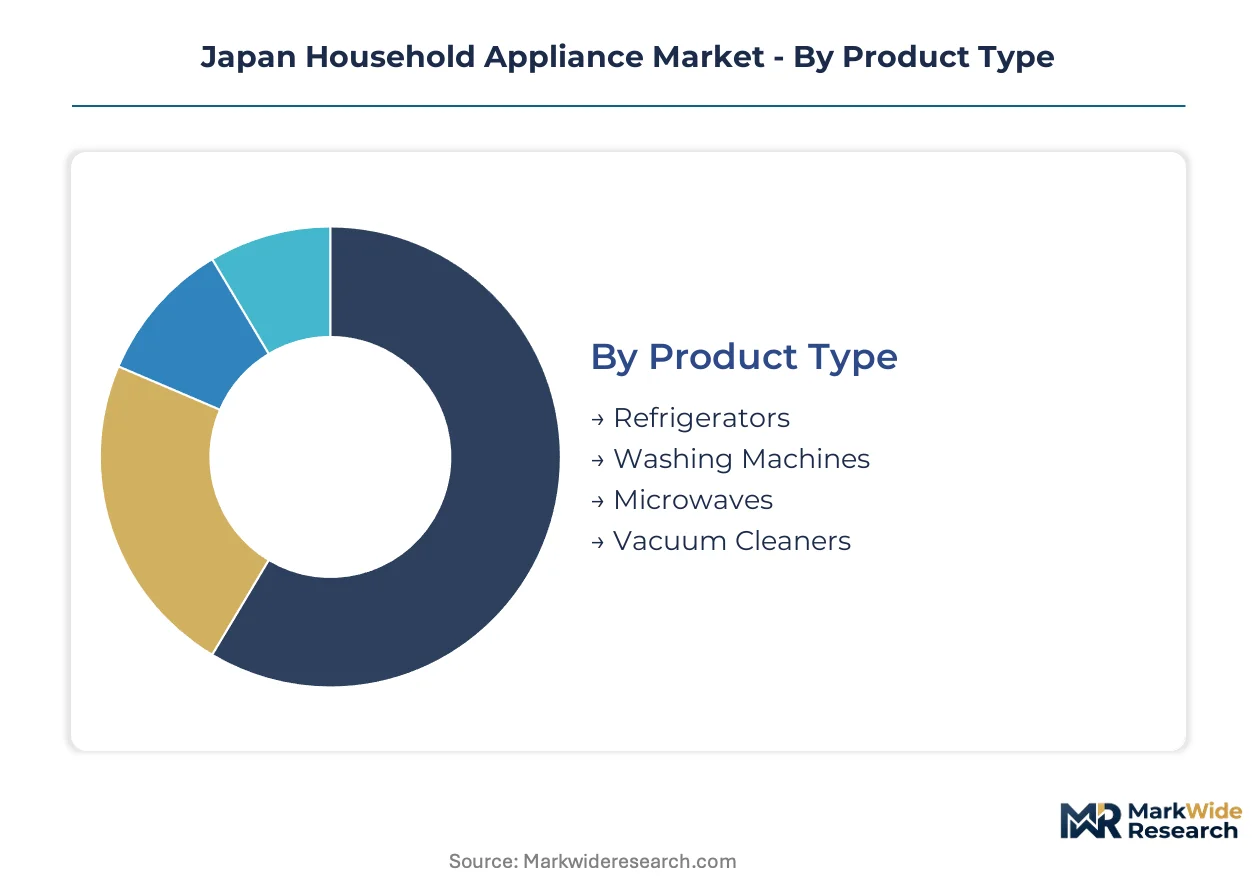
Segmentation in the Japan household appliance market tracks how METI efficiency mandates, condominium development patterns, and semiconductor integration reshape procurement across buyer categories. Understanding these divides clarifies where inverter modules, heat-pump systems, and connected platforms concentrate investment.
Product Type:
Buyer decisions here pivot on replacement cycle timing and energy-benchmark compliance pressure from METI Top Runner revisions.
- Refrigerators:Continuous compressor cycling requirements impose the steepest standby power redesign burden under sub-1W METI limits. Demand clusters in premium Minato and Chiyoda ward condominiums where nanoeX purification and variable-speed inverter drives justify price premiums.
- Washing Machines:Falling inverter module costs now enable variable-speed drives in mid-tier units previously limited to premium lines. Osaka and Nagoya assembly plants harden domestic capacity as yen volatility raises import costs for compressor valves and rare-earth magnets.
- Microwaves:Magnetron supply concentrates in legacy industrial corridors with limited semiconductor integration potential.
- Vacuum Cleaners:Battery-powered cordless formats gain traction in Tokyo high-rise units where storage constraints favor compact form factors.
Volume sits with refrigerators; growth tilts toward washing machines.
Technology:
Cost tier separation determines access to inverter-driven and connected platforms, with semiconductor fabrication scale as the gating factor.
- Smart Appliances:Always-on connectivity triggers disproportionate power supply redesign to meet METI sleep-mode regulations. Premium condominium developers in Kanto specify these as standard fitments, compressing traditional product lifecycles into iterative software refresh cycles.
- Energy-Efficient Devices:Heat-pump compressors and inverter motors dominate METI compliance strategies. Sakai-based vertical integration of rotary compressor manufacturing anchors supply for heat-pump dryers.
- IoT Connectivity:ECHONET Lite and Matter protocol adoption concentrates R&D allocation toward predictive maintenance subscriptions.
- Automated Systems:Sensor-embedded platforms generate recurring revenue through consumable replenishment logistics in high-rise developments.
Revenue concentrates in energy-efficient devices; expansion tilts most sharply toward smart appliances.
End User:
Application context shapes specification standards, with rental and hospitality channels driving standardization around durability and service response.
- Households:Urban Tokyo-Osaka corridors drive connected kitchen ecosystem adoption with concentrated upgrade cycles in premium residential towers.
- Rental Properties:Property management firms prioritize standardized SKUs with rapid replacement part availability from modular heat-pump architectures.
- Hotels:Centralized procurement favors units with field-upgradeable capacity scaling and reduced lead times.
- Businesses:Corporate cafeterias and facility managers specify induction cooking and heat-pump water heaters under Tohoku and Hokkaido rural electrification programs.
Households anchor unit volume; rental properties show the steepest adoption curve for connected platforms.
Distribution Channel:
Customer type and geography determine channel preference, with urban density enabling direct-to-installer models that bypass traditional retail.
- Online Retail:Subscription-based filter and detergent replenishment displaces transactional aftermarket sales in Osaka central wards with centralized logistics access.
- Specialty Stores:JIS certification complexity and PSE requirements create compliance barriers that concentrate high-value transactions in channels with technical consultation capacity.
- General Merchandisers:Mid-tier inverter-enabled washing machines and refrigerators flow through volume channels serving replacement demand in prefectural cities.
- Wholesale:Developer-specified connected kitchen ecosystems and integrated HVAC move through project channels serving Kanto and Kansai condominium construction.
General merchandisers hold volume; online retail gains share fastest on recurring revenue attachment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare-earth magnet deposits in the Kyushu region anchor Japan's compressor motor supply chain. Domestic fabrication of inverter modules concentrates in the Osaka-Nagoya industrial corridor. METI efficiency mandates cascade through prefectural procurement standards.
Kanto/Tokyo
Premium condominium developments in Minato and Chiyoda wards specify connected kitchen ecosystems and integrated HVAC systems. METI Top Runner standards tighten replacement cycles for high-efficiency appliances. Semiconductor fabrication for inverter modules clusters in Tokyo's western suburbs.
Kansai/Osaka
Domestic washing machine assembly hardens capacity as yen volatility raises import costs for compressor valves. Osaka central wards drive subscription-based filter replenishment through centralized logistics access. Sakai anchors vertically integrated rotary compressor manufacturing for heat-pump applications.
Chubu/Nagoya
Industrial motor control expertise concentrates in legacy automation corridors, constraining appliance OEM hiring pipelines. JIS certification timelines extend product launch windows for next-generation refrigerant transitions. Nagoya assembly plants face margin pressure from dollar-denominated rare-earth magnet imports.
Hokkaido
Grid stabilization investments enable all-electric home conversion across rural municipalities. Heat-pump water heater demand accelerates under Tohoku-Hokkaido electrification programs. Sapporo's cold-climate housing stock prioritizes high-COP heating appliances.
Kyushu
Raw material processing for permanent magnet motors concentrates in Fukuoka industrial zones. Local supply chains reduce transport costs for compressor manufacturers. Fukuoka Prefecture hosts testing facilities for low-GWP refrigerant compatibility.
Japan Household Appliance Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue smart connectivity and subscription service models. The vendor base organizes around three archetypes: diversified electronics conglomerates with captive semiconductor fabrication, specialized climate-control manufacturers with compressor integration, and Korean challengers leveraging scale economies. Competitive moves concentrate on backward integration into power electronics and strategic partnerships around interoperability protocols.
Among Japan-based diversified manufacturers, Mitsubishi Electric Corporation, Panasonic Holdings Corporation, and Daikin Industries, Ltd. exemplify distinct strategic positions. Mitsubishi Electric represents the captive semiconductor fabrication archetype, controlling inverter module supply through in-house production. Panasonic Holdings anchors refrigeration specialization with proprietary purification technology positioning. Daikin Industries occupies the climate-control vertical integration tier, with compressor manufacturing concentrated in the Sakai industrial cluster. Korean challengers Samsung Electronics and LG Electronics sit within the scale-driven import segment, competing on cost positioning against domestic JIS-certified suppliers.
| Leading Market Players |
|---|
| Mitsubishi Electric Corporation |
| Daikin Industries, Ltd. |
| Panasonic Holdings Corporation |
| Samsung Electronics |
| LG Electronics |
| Hitachi Global Life Solutions |
| Toshiba Corporation |
| Sony Group Corporation |
| Sharp Corporation |
| Others |
Pricing and Supply Chain Analysis
Rare-earth magnet pricing indices cascade through Osaka-Nagoya assembly corridors into three distinct appliance tiers, compressing margins at the mid-market junction where inverter module costs determine competitive positioning. METI efficiency mandates amplify cost pass-through urgency, forcing OEMs to absorb component volatility or accelerate premium-tier migration.
Pricing Analysis
Warranty and predictive-maintenance bundling separates premium appliance tiers from transactional economy sales, with extended service contracts now standard in Minato and Chiyoda ward condominium specifications. Three-tier pricing structure across premium, standard, and economy levels reflects JIS certification grade and inverter drive capability, with brand premium widening between captive-fabrication and import-dependent OEMs. Pricing pressure stems from yen-denominated rare-earth magnet imports, eroding mid-tier assembler margins fastest. Rental property procurement teams exhibit highest price sensitivity; premium condominium developers show lowest.
Supply Chain Analysis
Direct-to-installer channels handle developer-specified connected kitchen ecosystems, bypassing traditional retail for Kanto and Kansai high-rise projects. Manufacturing concentrates in Japan, South Korea, and China, with domestic fabrication of inverter modules anchoring Osaka-Nagoya capacity. Supply chains rest on rare-earth magnets, compressor valves, and semiconductor wafers as critical inputs. Single-source vulnerability concentrates in Sakai-based rotary compressor production for heat-pump applications. Distribution runs through wholesale project channels serving metropolitan construction pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's household appliance sector sits in a technology-transition phase where heat-pump architectures displace conventional resistive heating, rewiring competitive advantage around compressor integration depth and refrigerant IP positioning.
For Market Incumbents: Lock in captive semiconductor fabrication capacity to defend inverter module supply against Korean scale challengers. Deepen backward integration into rare-earth magnet processing through Kyushu supplier partnerships, insulating margin structures from yen volatility. Prioritize ECHONET Lite certification investment to secure Smart House interoperability gatekeeper status before platform consolidation hardens.
For New Entrants and Emerging Players: AI-driven predictive maintenance algorithms offer a technology-first wedge into premium condominium service contracts, where software subscription attach rates remain underpenetrated. Target Tohoku and Hokkaido rural electrification corridors for heat-pump water heater penetration, leveraging METI efficiency rebates as market entry accelerant. Pursue direct-to-installer distribution partnerships bypassing JIS-certified retail gatekeeping.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier inverter module specialists in the Chubu industrial corridor, where power electronics engineering scarcity constrains OEM hiring pipelines. Long-term viability hinges on refrigerant transition readiness and low-GWP formulation licensing positions. Watch METI's next Top Runner tier revision timing as inflection signal for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Inverter Module Fabrication | Captive semiconductor production insulates Mitsubishi Electric against yen-denominated import volatility. |
| ECHONET Lite Protocol Certification | Smart House interoperability standards create platform gatekeeper advantages for early certifiers. |
| Heat-Pump Dryer Modularization | Field-upgradeable compressor architectures reduce rental property replacement part lead times. |
| Predictive Maintenance Subscription Launch | Sensor-embedded appliances generate recurring revenue through automated detergent and filter replenishment. |
| Kyushu Rare-Earth Magnet Partnership | Local permanent motor supply chains reduce transport costs and tariff exposure for Nagoya assembly. |
Research Methodology
Document review covered METI regulatory filings, JIS standard revision records, and customs trade data, complemented by interviews with appliance OEM product strategists, inverter module procurement leads, and condominium developer specification engineers. Primary fieldwork included discussions with power electronics firmware specialists and heat-pump compressor manufacturing heads. Secondary validation drew from semiconductor fabrication capacity disclosures, rare-earth magnet import statistics, and Smart House initiative protocol documentation. Bottom-up unit shipment modeling triangulated against top-down efficiency mandate compliance projections.
Historical shipment trajectories cross-referenced against expert panel input on refrigerant transition timelines and METI revision cycles. Segmentation modeling tracked product type, technology tier, end-user category, and distribution channel across the projection horizon. CAGRs derived from replacement cycle compression rates and semiconductor cost elasticity assumptions. Industry-specific inputs incorporated Top Runner tier adoption curves and ECHONET Lite penetration scenarios.
Forecast precision tightens around the base case; tail outcomes carry wider variance under yen volatility spikes or accelerated low-GWP refrigerant mandates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Built-In Hobs Market
Home Appliances
Steam Clothing Care System Market
Home Appliances
Saudi Arabia Home Appliances Market
Home Appliances
Europe Portable Washing Machine Market
Home Appliances
UAE Laundry Appliances Market
Home Appliances
Egypt Major Home Appliances Market
Home Appliances
United States Major Home Appliances Market
Home Appliances
Connected Home Appliances Market
Home Appliances
Major Home Appliances Market
Home Appliances
Home Appliances Glass Market
Home Appliances
Kuwait Small Home Appliances Market
Home Appliances
Household Appliance Market
Home Appliances
Slovakia Home Appliances Market
Home Appliances
Europe Personal Care Appliances Market
Home Appliances
Home Laundry Appliances Market
Home Appliances
Kuwait Major Home Appliances Market