
 India Refrigerator Market | 2026-2036
India Refrigerator Market Size, Share, and Industry Trends Forecast 2026-2036
India Refrigerator Market Outlook
E-commerce platforms and direct-to-consumer channels are rewriting how refrigerator makers reach Indian households. Samsung Electronics leverages its extensive service network to sustain brand loyalty in metro and tier-2 markets. LG Electronics anchors its position through inverter compressor technology leadership and deep offline retail presence. Haier India competes aggressively on price while extending its portfolio into bottom-freezer and side-by-side formats.
A refrigerator is an electrically powered thermal insulation appliance that maintains temperatures between zero and four degrees Celsius for fresh compartments and minus eighteen degrees Celsius for freezer sections, using vapor-compression refrigeration cycles with refrigerants, insulation foam, and precision temperature controllers to preserve food safety and extend shelf life in domestic and commercial settings. Top freezer configurations still occupy the largest volume share due to affordability, though side-by-side and French door formats are gaining traction among premium urban buyers seeking larger capacities and aesthetic integration. Direct cool technology dominates rural penetration for its low energy draw, while frost-free and inverter segments capture margin pools in cities where BIS higher star ratings influence purchasing decisions.
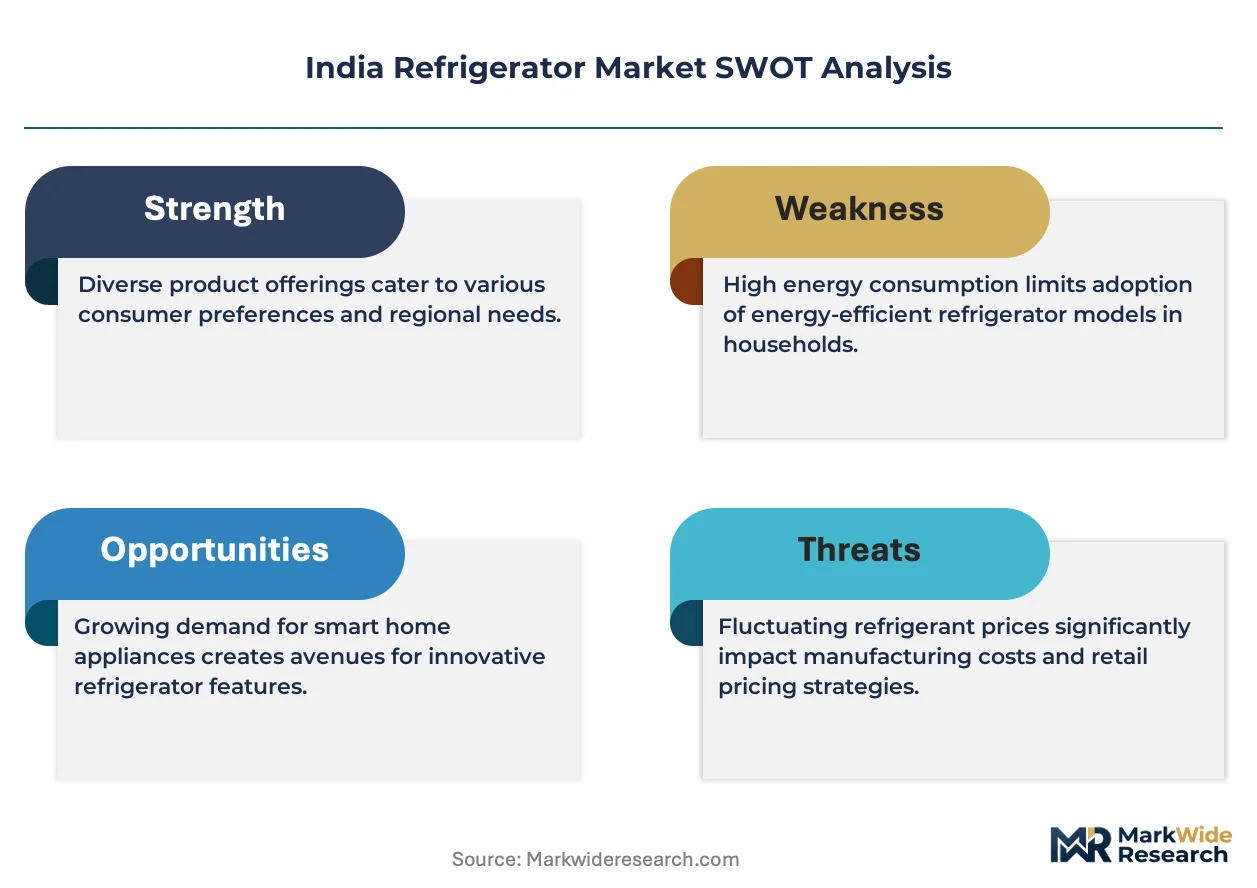
BIS mandatory energy labelling and the Bureau of Energy Efficiency's standards are tightening efficiency thresholds, pushing manufacturers toward inverter compressors and improved insulation chemistries. The Central Pollution Control Board's oversight of refrigerant phase-down under India's Kigali Amendment obligations is accelerating transitions from HFCs to hydrocarbon alternatives. Stakeholders must monitor how state-level electricity tariff structures and municipal building codes for commercial kitchens reshape product specifications across residential, hospitality, and healthcare end-use categories.
Market Dynamics
BIS energy labelling mandates and the Kigali Amendment refrigerant phase-down are compressing manufacturer margins while forcing portfolio reconfiguration toward inverter compressors and hydrocarbon refrigerants across India's organized and unorganized appliance sectors.
Growth Catalysts
- R-600a refrigerant transition:India's Central Pollution Control Board enforcement of Kigali Amendment obligations accelerates manufacturer investment in hydrocarbon-based cooling systems, creating first-mover advantages for compliant producers.
- Tier-2 urban housing expansion:Residential construction growth in cities like Pune, Ahmedabad, and Coimbatore generates replacement demand from direct-cool to frost-free configurations as apartment stock modernizes.
- PLI scheme for white goods:The government's production-linked incentive scheme for air conditioners and refrigerators subsidizes domestic manufacturing scale-up, reducing import dependency for compressor and electronic controller components.
Market Restraints
- Copper and steel input volatility:Refrigerator coil and cabinet manufacturing faces margin compression from fluctuating base metal prices, with hedging costs passed through to price-sensitive rural segments.
- Compressor supply concentration:Domestic production of inverter compressors remains concentrated among three integrated manufacturers, creating bottleneck risks for mid-tier assemblers lacking backward integration.
- Rural electrification gaps:Unreliable grid supply in Bihar, Uttar Pradesh, and Odisha limits addressable market expansion despite rising disposable incomes, as voltage fluctuation damage erodes product trust.
Strategic Opportunities
- Commercial kitchen refrigeration:India's hospitality sector expansion into tier-2 cities creates demand for under-counter and reach-in units, a segment currently dominated by fragmented local fabricators.
- Direct-to-consumer channel maturation:E-commerce platforms enable bypass of multi-tier distributor margins, allowing manufacturers to capture value previously lost to state-level stockists in Maharashtra and Tamil Nadu.
- Healthcare cold chain:Vaccine storage protocols and diagnostic reagent preservation requirements drive institutional demand for medical-grade refrigerators with temperature logging capabilities.
Industry Challenges
- Inverter compressor calibration expertise:The shift from fixed-speed to variable-speed refrigeration systems requires field service networks to retrain technicians on electronic control board diagnostics and refrigerant charge optimization.
- BIS certification timelines:New model approvals face extended testing queues at BIS laboratories, delaying product launches during critical pre-summer inventory build periods.
- Legacy direct-cool inventory liquidation:Manufacturers must manage channel transitions as star-rating revisions render existing stock non-compliant, forcing discounting that cannibalizes frost-free upgrade momentum.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Refrigerator Market |
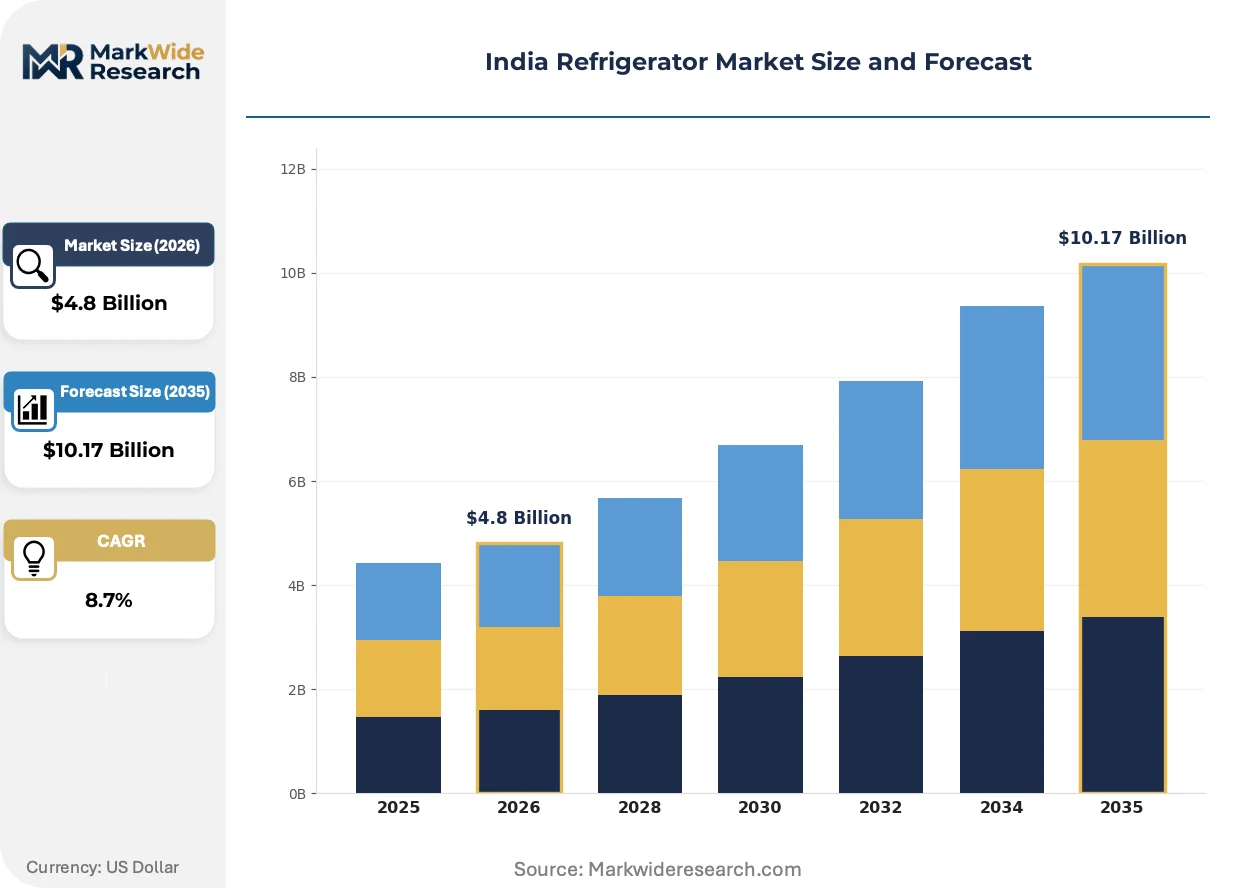
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Top Freezer, Bottom Freezer, Side-by-Side, French Door End User: Residential, Commercial, Hospitality, Healthcare Technology: Frost Free, Direct Cool, Inverter, Conventional Feature: Smart Technology, Energy Efficiency, Temperature Control, Space Saver |
| Companies Covered | Godrej Appliances, Panasonic Corporation, Samsung Electronics, Hitachi Global Life Solutions, Voltas Beko, LG Electronics, Haier India, Blue Star, Whirlpool Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Refrigerator Market Strategic Shifts
Smart connectivity and variable-speed compression are redefining refrigerator architecture in India, with energy efficiency and remote monitoring emerging as the primary axes of product differentiation beyond capacity and configuration.
IoT-enabled refrigerator platforms are digitizing household food management through inventory tracking, expiry alerts, and energy consumption dashboards. Premium urban buyers in Mumbai and Bangalore adopt these features at accelerating rates, compressing the upgrade cycle from ten-year replacement norms toward seven-year intervals as software functionality depreciates hardware value.
BIS mandatory star-labelling revisions under Bureau of Energy Efficiency oversight tighten efficiency thresholds every two years, forcing continuous insulation foam and compressor redesign. Frost-free models above 250 liters face the steepest compliance burdens, with manufacturers responding through vacuum-insulated panel trials and brushless DC motor adoption.
Buyer preferences are fragmenting across channel types, with metro consumers researching online before purchasing offline for touch-and-feel validation, while tier-2 buyers complete transactions entirely through e-commerce platforms offering installation and exchange schemes. This bifurcation forces parallel go-to-market investments, most visible in Gujarat where Flipkart and Amazon now operate dedicated appliance fulfillment centers.
India Refrigerator Market Segmentation
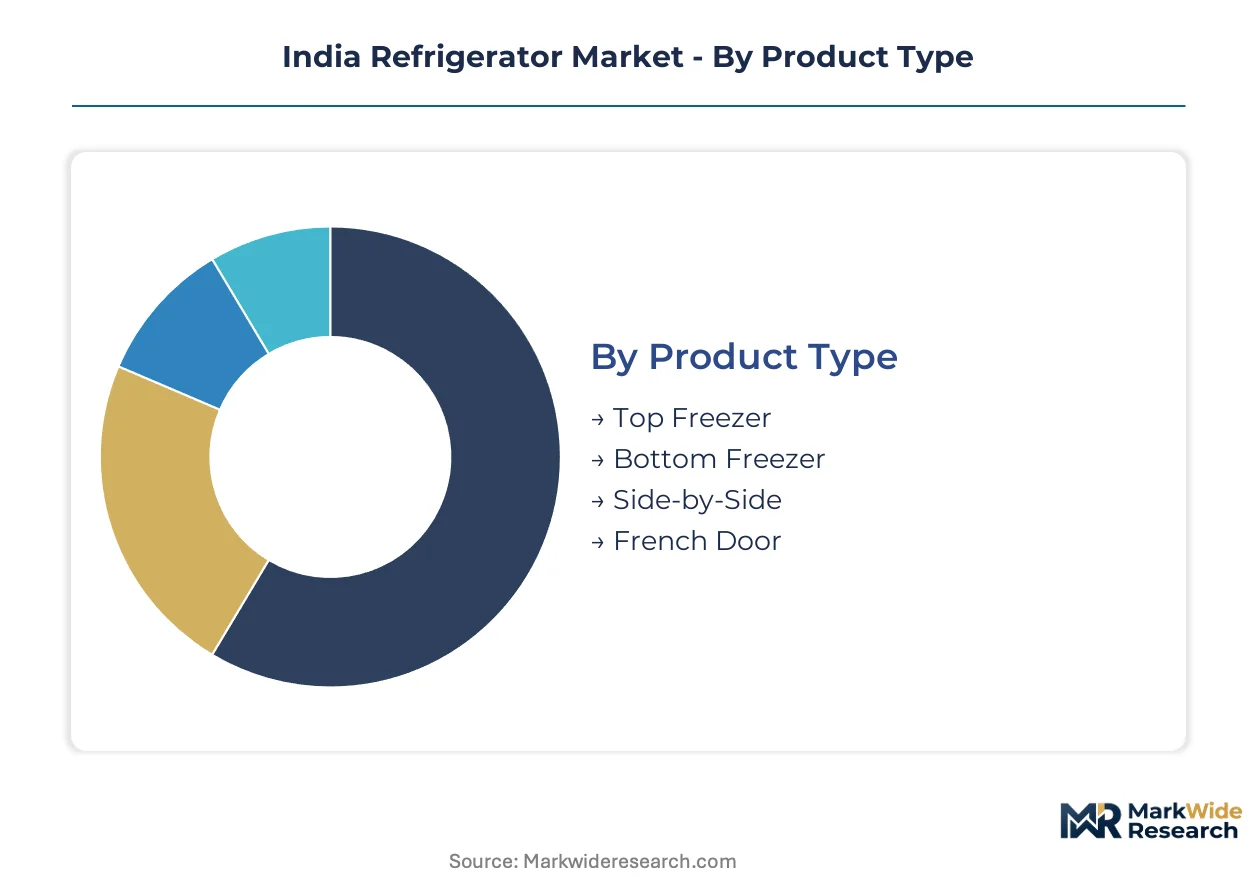
Segmentation in the India refrigerator market reveals distinct replacement cycles and margin pools. Product configuration and technology tier determine upgrade velocity, while end-use category shapes channel access and service requirements across tier-1 and tier-2 city networks.
Product Type:
Replacement cycles vary sharply by configuration, with compact formats turning over every 7-9 years versus premium formats at 5-7 years as feature obsolescence accelerates.
- Top Freezer:This configuration positions the freezing compartment above the refrigeration section, minimizing cold air loss during door openings. Demand concentrates in Maharashtra and Gujarat apartment stock where ceiling height constraints limit vertical clearance, with BIS 3-star ratings serving as the baseline purchase threshold for urban first-time buyers.
- Side-by-Side:Vertical split-door designs allocate equal cabinet width to fresh and frozen compartments, enabling wider storage trays. Premium residential complexes in Bangalore and Hyderabad drive adoption, with integrated water dispensers and ice makers justifying 40-60% price premiums over top-freezer equivalents.
- Bottom Freezer:Eye-level fresh food access reduces bending frequency for daily-use items. Pune and Ahmedabad housing developments favor this format for senior-occupied units, though compressor placement complexity elevates service costs.
- French Door:Dual fresh-food doors above a pull-out freezer drawer maximize interior volume utilization. Mumbai and Delhi NCR luxury developments specify these units for modular kitchen integration, with 500+ liter capacities addressing joint-family storage needs.
Top Freezer anchors the volume base while Side-by-Side gains share at the steepest rate.
End User:
Application context determines specification stringency, with institutional buyers imposing temperature logging and redundancy requirements absent in household procurement.
- Residential:Individual household units dominate absolute volume, with tier-2 city upgraders from direct-cool to frost-free systems driving replacement demand. Maharashtra and Tamil Nadu housing completions correlate with 250-350 liter capacity preferences.
- Commercial:Restaurants, retail grocers, and food processing operations require under-counter and reach-in configurations with stainless steel interiors. Gujarat's organized food retail expansion creates demand for display cases with glass door merchandising.
- Hospitality:Hotels and banquet facilities specify silent compressor operation and integrated aesthetic panels. Star-rated properties in Rajasthan and Kerala tourism corridors prioritize energy efficiency certifications for sustainability reporting.
- Healthcare:Vaccine storage and diagnostic reagent preservation mandate precise temperature maintenance with continuous data logging. CDSCO guidelines for cold chain compliance drive institutional procurement of medical-grade units with alarm systems and backup power compatibility.
Residential absorbs the highest absolute volume while Healthcare exhibits the most rigid specification escalation.
Technology:
Cost tier alignment separates mass-market penetration from premium capture, with efficiency certification thresholds forcing portfolio repositioning every 24 months under BIS revisions.
- Frost Free:Forced-air circulation prevents ice accumulation through automatic defrost cycles, eliminating manual clearing requirements. Urban tier-1 and tier-2 buyers treat this as the default technology for new purchases, with BIS 4-star and 5-star variants commanding disproportionate margin.
- Inverter:Variable-speed compressors modulate cooling output against thermal load rather than cycling on-off, reducing energy consumption and compressor wear. Maharashtra and Gujarat electricity tariff structures accelerate payback calculations for high-usage households.
- Direct Cool:Natural convection cooling with manual defrost requirements maintains the lowest entry price point. Rural electrification gaps in Bihar and Uttar Pradesh sustain demand despite efficiency disadvantages, though voltage stabilizer bundling erodes manufacturer margin.
- Conventional:Fixed-speed compressor systems without inverter modulation occupy the entry tier. Inventory liquidation pressures intensify as BIS star-rating revisions render existing stock non-compliant ahead of summer selling seasons.
Direct Cool retains rural penetration depth while Inverter technology climbs the fastest in urban replacement cycles.
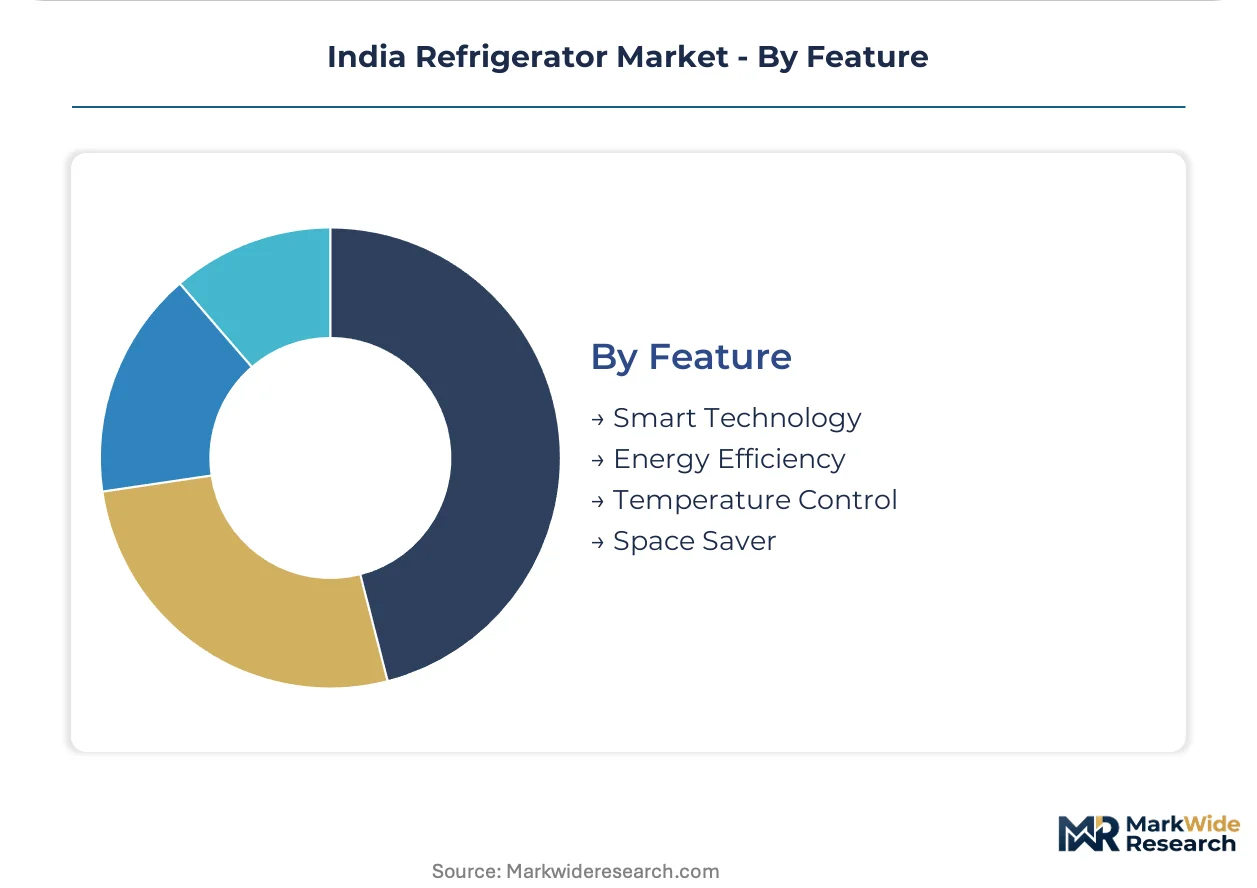
Feature:
Customer type fragmentation separates specification-driven institutional buyers from convenience-seeking residential upgraders, with channel strategy diverging accordingly.
- Smart Technology:WiFi-enabled inventory tracking, expiry alerts, and remote temperature monitoring via mobile applications. Bangalore and Mumbai early adopters compress replacement intervals as software functionality depreciates hardware value faster than mechanical failure.
- Energy Efficiency:BIS star-label compliance and Bureau of Energy Efficiency threshold adherence determine eligibility for utility rebate programs and green building certifications. Tamil Nadu commercial real estate developers specify 5-star units for LEED scoring.
- Temperature Control:Precision thermostats with multiple zone calibration for specialized storage requirements. Healthcare and hospitality end-users prioritize this feature for regulatory compliance and food safety protocols.
- Space Saver:Slim-depth cabinets and reversible door configurations for compact kitchen layouts. Pune and Coimbatore apartment construction trends favor 550-600mm depth units over standard 650-700mm formats.
Energy Efficiency anchors procurement criteria for institutional buyers while Smart Technology expands most quickly among premium residential segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Western Dedicated Freight Corridor underwrites Gujarat's logistics supremacy for appliance distribution, connecting Mundra Port to Delhi-NCR manufacturing clusters with electrified double-stack container service.
Maharashtra
Mumbai-Pune housing completions drive frost-free replacement cycles as apartment stock modernizes. BIS energy labelling mandates accelerate inverter compressor adoption in Thane and Navi Mumbai retail networks. The Chakan-Talegaon industrial belt hosts compressor component fabrication for tier-1 assemblers.
Gujarat
Ahmedabad and Surat residential construction generates demand for bottom-freezer configurations in senior-occupied units. The state's PLI scheme for white goods subsidizes domestic manufacturing scale-up at Sanand and Changodar industrial parks. Gandhinagar-based testing laboratories process BIS certification queues for summer inventory builds.
Tamil Nadu
Chennai-Coimbatore housing corridors concentrate 250-350 liter capacity preferences among upgraders from direct-cool systems. CDSCO cold chain guidelines for vaccine storage drive institutional procurement of medical-grade units in Hosur pharmaceutical clusters. Sriperumbudur electronics manufacturing zones supply electronic controller components.
Karnataka
Bangalore's premium residential complexes compress replacement intervals for smart-connected refrigerators through software functionality depreciation. The state's electricity tariff structures accelerate inverter payback calculations for high-usage households in Whitefield and Electronic City. Mysuru component suppliers feed compressor motor winding demand.
Telangana
Hyderabad's hospitality sector expansion into Gachibowli and HITEC City corridors creates demand for under-counter commercial units. BIS star-rating revisions force inventory liquidation at Secunderabad wholesale markets ahead of compliance deadlines. The Medchal industrial area hosts insulation foam suppliers for organized manufacturers.
India Refrigerator Market Competitive Environment
On the supply side, the industry is tiered between integrated multinationals with captive compressor production and domestic assemblers dependent on outsourced component supply. Three strategic archetypes dominate: Korean-Japanese electronics conglomerates with inverter technology leadership, Indian diversified industrials with deep distribution reach, and Chinese price competitors with aggressive format expansion. Consolidation pressures intensify through backward integration into electronic controllers and strategic partnerships for hydrocarbon refrigerant transition.
Among Korea-based electronics manufacturers, Samsung Electronics and LG Electronics exemplify the technology-integrated archetype, anchoring premium positioning through service network density and inverter compressor R&D. Haier India occupies the Chinese-origin expansionist tier, representing aggressive portfolio diversification into bottom-freezer and side-by-side formats. Godrej Appliances exemplifies the domestic diversified archetype, leveraging century-old distribution infrastructure across Maharashtra and Gujarat trade channels.
| Leading Market Players |
|---|
| Godrej Appliances |
| Panasonic Corporation |
| Samsung Electronics |
| Hitachi Global Life Solutions |
| Voltas Beko |
| LG Electronics |
| Haier India |
| Blue Star |
| Whirlpool Corporation |
| Others |
Value Chain & Pricing Dynamics
Sanand's industrial parks anchor compressor and controller manufacturing capacity, concentrating supply-side leverage among three integrated producers who dictate pricing terms to mid-tier assemblers lacking backward integration into critical components. This geographic concentration amplifies margin pressure when copper coil and steel cabinet input costs fluctuate, forcing tiered pricing adjustments downstream.
Pricing Analysis
Volume-discount tiering structures separate inverter-equipped frost-free models from direct-cool entry units, with BIS star-rating compliance costs driving 15-20% price spreads between adjacent certification levels. Brand premiums for Korean-Japanese electronics conglomerates sustain 25-35% markups over Chinese-origin competitors, while rural electrification gaps in Bihar and Uttar Pradesh sustain demand for stabilizer-bundled economy configurations despite thinner manufacturer margins. Price differentiation intensifies as channel partners demand promotional support for summer inventory builds, compressing net realized prices in Maharashtra and Tamil Nadu wholesale networks.
Supply Chain Analysis
Export-control regimes on semiconductor manufacturing equipment indirectly constrain electronic controller availability for inverter compressor systems, though India sources compressor motors from China, South Korea, and domestic Sriperumbudur electronics zones. Hydrocarbon refrigerant R-600a draws from petrochemical feedstock chains centered on Gujarat's Dahej and Hazira complexes, with insulation foam chemicals resting on MDI and polyol imports from Germany and Belgium. Single-source vulnerability concentrates in inverter compressor supply, where three integrated manufacturers control 80% of domestic availability. Distribution runs through state-level stockist networks in Maharashtra and Tamil Nadu before reaching organized retail and e-commerce fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities multiply as tier-2 housing expansion splinters demand across format preferences and channel types, creating niche capture possibilities beyond the metro-centric strategies of established Korean-Japanese players.
For Market Incumbents: Entrench service network density as the primary defensive moat against Chinese-origin price competitors, particularly in tier-2 cities where installation reliability determines repeat purchase probability. Backward integration into electronic controller production reduces exposure to semiconductor supply bottlenecks that currently constrain inverter model rollout timelines. Compressor calibration expertise represents the critical capability gap that mid-tier assemblers cannot replicate without multi-year technician retraining investments. For New Entrants and Emerging Players: Establish a beachhead in commercial kitchen refrigeration for India's hospitality sector expansion into tier-2 cities, where fragmented local fabricators currently dominate with limited brand recognition. Target under-counter and reach-in configurations for Gujarat's organized food retail growth, leveraging direct-to-consumer e-commerce channels to bypass multi-tier distributor margins that inflate landed costs for traditional stockist-dependent competitors. CDSCO cold chain compliance requirements for vaccine storage create institutional procurement entry points with higher specification barriers and longer contract durations than residential segments. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified Indian industrials with century-old distribution infrastructure but lagging inverter technology portfolios, where production-linked incentive scheme subsidies could fund manufacturing scale-up post-acquisition. Long-term viability hinges on hydrocarbon refrigerant transition completion and captive compressor supply development within a 5-10 year capability-building window. The signal to watch is BIS star-rating revision timing, which forces inventory liquidation cycles that strain working capital for non-compliant stockholders.| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Compressor R&D Investment | Variable-speed technology leadership secures BIS 5-star certification premiums in Maharashtra and Gujarat urban markets. |
| Hydrocarbon Refrigerant Transition | R-600a compliance under Kigali Amendment obligations creates first-mover positioning ahead of CPCB enforcement timelines. |
| Direct-to-Consumer Channel Buildout | E-commerce fulfillment center investments in Ahmedabad and Coimbatore bypass state-level stockist margin capture. |
| Commercial Kitchen Portfolio Expansion | Under-counter and reach-in configurations address hospitality sector growth in Hyderabad and Bangalore corridors. |
| Healthcare Cold Chain Certification | CDSCO-compliant medical-grade units with temperature logging capture institutional procurement in Hosur pharmaceutical clusters. |
Study Parameters
A spread of perspectives from appliance manufacturing executives, state-level distribution channel partners, BIS certification laboratory directors, and hospitality sector procurement managers converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with compressor component suppliers in the Chakan-Talegaon industrial belt and aftermarket service network operators across tier-2 cities. Secondary validation drew from Bureau of Energy Efficiency star-rating databases, CDSCO cold chain compliance guidelines, PLI scheme white goods disbursement records, and customs trade data on refrigerant chemical imports. Bottom-up capacity estimates from Sanand and Changodar manufacturing parks were triangulated against top-down housing completion projections in Pune, Ahmedabad, and Coimbatore.
Demand-supply balance modeling across the projection horizon integrated product configuration preferences, technology tier adoption curves, and end-use category specifications. Segmentation dimensions included format type, cooling technology, capacity band, and geographic housing corridor. CAGRs were derived from replacement cycle compression analysis and efficiency upgrade payback calculations under state-level electricity tariff structures. Industry-specific forecast inputs encompassed BIS star-rating revision schedules, hydrocarbon refrigerant transition timelines, and tier-2 urban housing permit issuance trends.
Stress conditions across copper and steel input volatility, compressor supply concentration bottlenecks, and rural electrification reliability gaps were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding PLI scheme continuity, Kigali Amendment enforcement intensity, and organized retail penetration trajectories. Material shifts in BIS energy labelling thresholds, CPCB refrigerant phase-down acceleration, or state-level electricity tariff restructuring would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Australia Home Appliances Market
Home Appliances
Global Electric Motors Household Appliances Market
Home Appliances
France Home Appliances Market
Home Appliances
UAE Small Home Appliances Market
Home Appliances
Argentina Home Appliances Market
Home Appliances
UAE Major Home Appliances Market
Home Appliances
Household Refrigerators and Freezers Market
Home Appliances
Germany Home Appliances Market
Home Appliances
Latin America Washing Machine Market
Home Appliances
United Kingdom Major Home Appliances Market
Home Appliances
Oman Small Home Appliances Market
Home Appliances
Smart Home Appliances Market
Home Appliances
Steam Clothing Care System Market
Home Appliances
North America Small Home Appliances Market
Home Appliances
Germany Small Home Appliance Market
Home Appliances
Russia Laundry Appliances Market