
 Saudi Arabia Major Home Appliances Market | 2026-2036
Saudi Arabia Major Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Major Home Appliances Market Analytics
Saudi manufacturing clusters near Jubail and Jeddah is restructuring assembly footprints to serve Gulf demand. Whirlpool Corporation leverages its regional distribution network to anchor premium refrigerator supply. Hisense competes aggressively on connected-device pricing across mid-tier segments. Haier sustains inverter-compressor R&D intensity that differentiates its air conditioner portfolio.
Saudi Arabia major home appliances encompass electrically powered durable goods—refrigeration units rated from 200L to 600L capacity, washing machines with variable drum speeds, and split-system air conditioners using R32 refrigerant—designed for residential climate control, food preservation, and textile cleaning in high-ambient-temperature environments. Smart appliances lead technology segment growth as Wi-Fi-enabled diagnostics and remote scheduling reshape household energy management, while energy-efficient models command margin pools due to SASO seasonal energy efficiency ratio requirements. Air conditioners dominate product-type volume given ambient temperatures exceeding 45°C across six months annually, whereas connected devices within the technology segment show the steepest adoption curve among urban households.
SASO mandates minimum energy performance standards and refrigerant-phase-down schedules that manufacturers must satisfy for market access. SFDA oversees material safety in appliance interiors contacting food or water, while the Saudi Building Code specifies electrical load calculations that shape residential circuit design and appliance sizing. Stakeholders must monitor regulatory tightening on cooling-load standards and refrigerant transitions to align procurement and product development cycles.
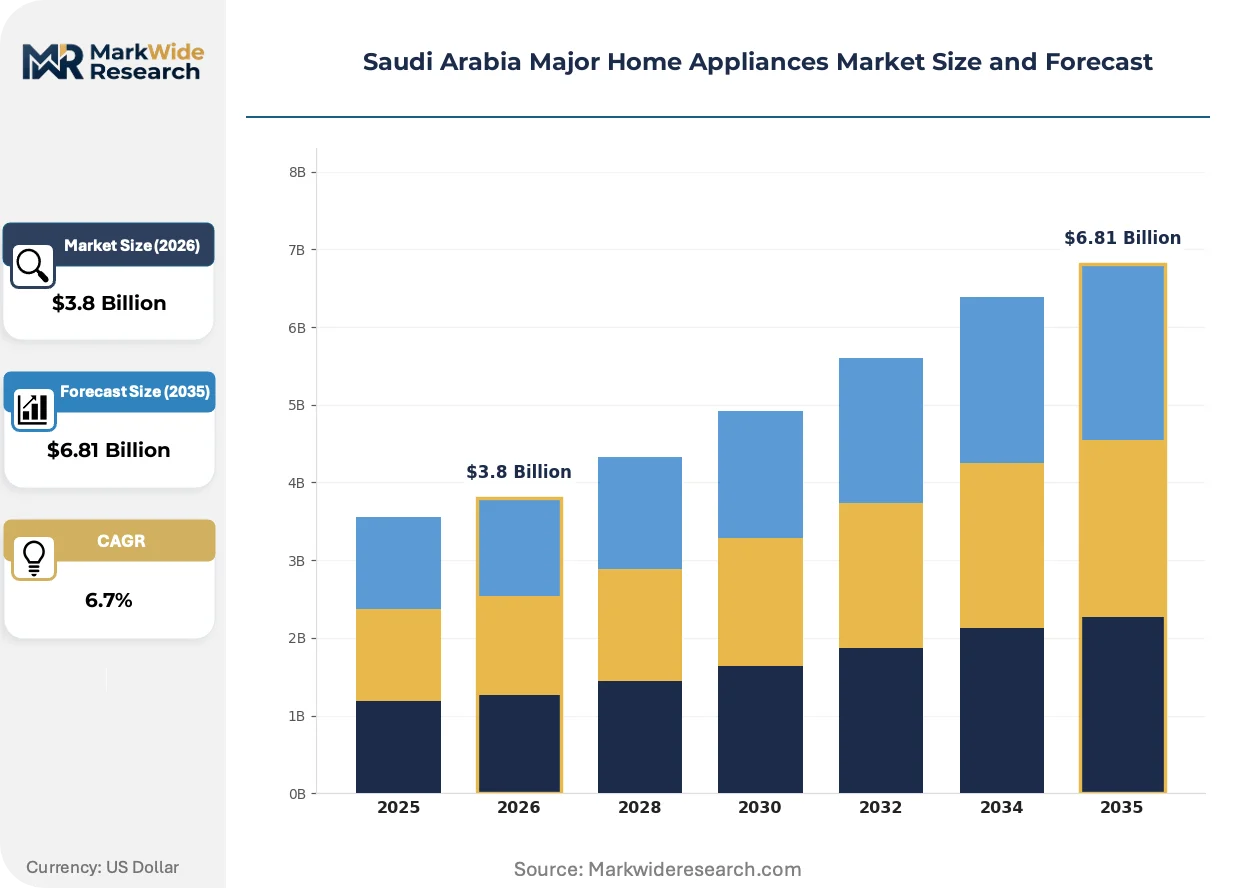
Market Dynamics
SASO energy-efficiency mandates are compressing legacy appliance margins while accelerating inverter-compressor and R32 refrigerant transitions across Saudi manufacturing clusters near Jubail and Jeddah.
Growth Catalysts
- Urban household formation:Riyadh and Jeddah corridors absorb population inflows that expand installed-base replacement cycles for cooling and refrigeration equipment.
- SASO seasonal energy efficiency ratio requirements:Mandated performance thresholds redirect procurement toward inverter-driven air conditioners and variable-speed washing machines.
- Connected-device ecosystems:Wi-Fi-enabled diagnostics and remote scheduling capabilities penetrate mid-tier segments as standard configuration rather than premium add-on.
Market Restraints
- Copper and steel input volatility:Compressor housings and heat exchanger coils expose assemblers to commodity price swings that compress working capital buffers.
- Single-source refrigerant dependency:R32 supply concentrates among Chinese chemical producers, creating import-risk exposure for Saudi-based assembly operations.
- SFDA material safety certification timelines:Extended approval cycles for food-contact surfaces and water-line polymers delay product launches by two to four quarters.
Strategic Opportunities
- Eastern Province housing stock:Dammam and Khobar corridors show underpenetrated smart-appliance adoption relative to Riyadh benchmarks.
- Solar-thermal hybrid cooling:Convergence of photovoltaic generation with absorption-chiller technology opens off-grid residential applications in remote settlements.
- Direct-to-developer channel:Bulk procurement contracts with Saudi Real Estate Refinance Company-financed projects bypass traditional retail markup structures.
Industry Challenges
- Inverter-control firmware specialization:Scarce embedded-systems talent in the Eastern Province forces reliance on overseas design houses for motor-drive algorithms.
- SASO-SFDA dual-track compliance:Parallel energy-performance and material-safety testing creates documentation bottlenecks that extend time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Major Home Appliances Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Dishwashers, Air Conditioners Technology: Smart Appliances, Energy Efficient, Connected Devices, Standalone Appliances End User: Households, Hotels, Restaurants, Retail Outlets Distribution Channel: Online Retail, Specialty Stores, Hypermarkets, Direct Sales |
| Companies Covered | Whirlpool Corporation, Hisense, Haier, Midea, TCL, LG Electronics, Panasonic Corporation, Gree Electric Appliances, Samsung Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Major Home Appliances Market Evolving Landscape
Smart appliance ecosystems are compressing traditional service models while refrigerant-phase-down schedules and channel restructuring reshape competitive positioning across Saudi Arabia's major home appliances landscape.
Inverter-compressor technology paired with R32 refrigerant is automating load-matching across split-system air conditioners. Urban households in Jeddah and Riyadh are specifying variable-speed units as baseline configuration rather than premium upgrade. This automation of cooling-output modulation is compressing energy consumption curves and displacing fixed-speed legacy inventory from distributor warehouses.
SASO refrigerant-phase-down mandates align with Kigali Amendment schedules that restrict high-global-warming-potential alternatives. Manufacturers serving the Saudi market must retool assembly lines to handle mildly flammable R32 charge protocols. Air conditioner portfolios face the steepest compliance gradient, with product development cycles compressing to meet 2025-2027 checkpoint deadlines.
Developer-direct procurement is consolidating purchase authority away from traditional retail channels. Large-scale residential projects in Riyadh's Diriyah Gate and Jeddah's Red Sea coastline are specifying appliance packages at construction phase rather than post-occupancy retail selection. This channel rotation is visible most acutely in premium refrigerator and built-in cooking equipment categories where finish matching drives bundled specification.
Saudi Arabia Major Home Appliances Market Segmentation
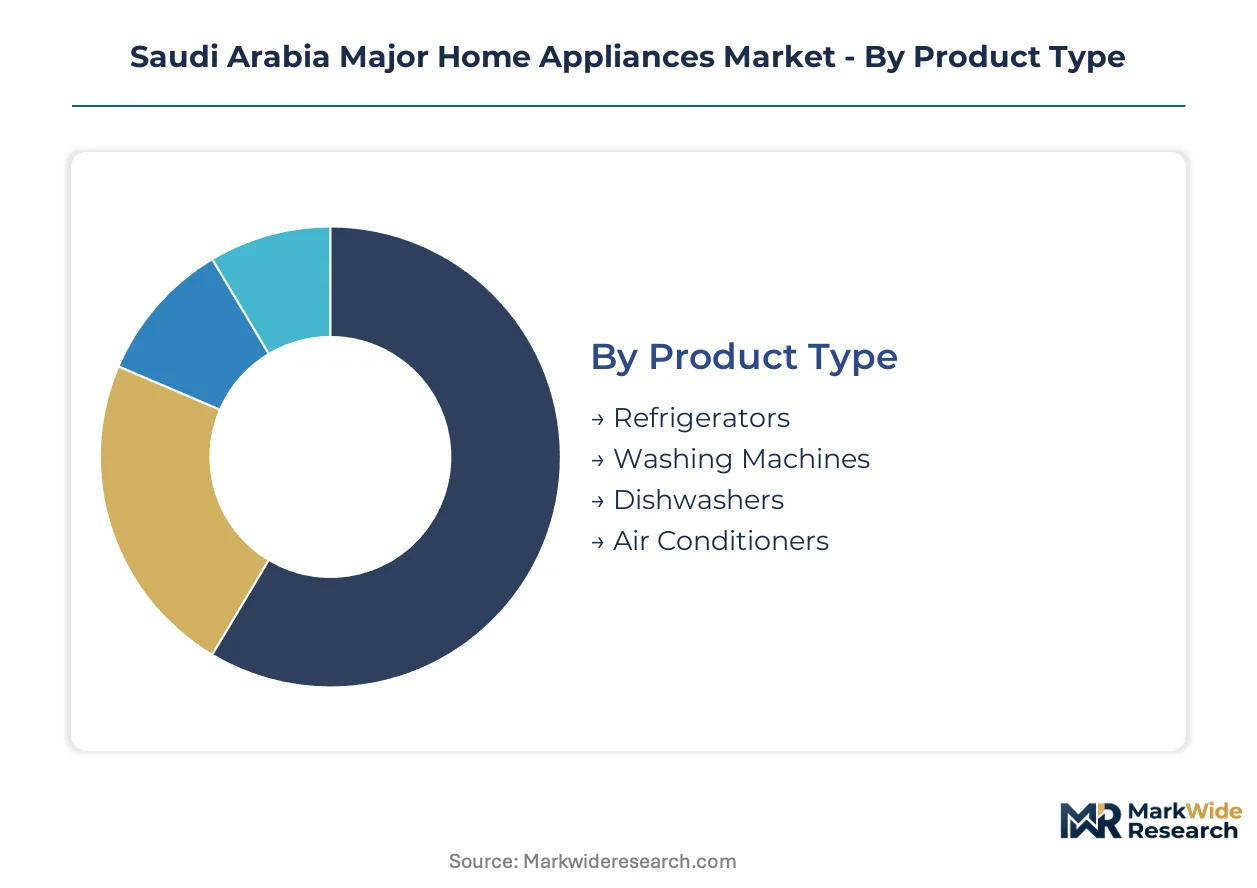
Segmentation in the Saudi Arabia major home appliances market reveals distinct procurement patterns across residential and commercial buyers. SASO energy-efficiency tiers and refrigerant-phase-down schedules create divergent upgrade cycles that manufacturers must navigate through targeted product positioning.
Product Type:
Buyers differentiate primarily by climate-driven replacement urgency and household formation timing rather than discretionary upgrade appetite.
- Air Conditioners:Split-system units rated for 45°C+ ambient operation dominate residential procurement in Riyadh and Jeddah corridors. Inverter-driven R32 refrigerant models absorb SASO seasonal energy efficiency ratio compliance pressure as fixed-speed inventory clears from distributor warehouses.
- Refrigerators:Units spanning 200L to 600L capacity serve extended-family households common in Saudi residential structures. Developer-direct procurement in Diriyah Gate and Red Sea coastline projects bundles finish-matched refrigeration with built-in cooking equipment.
- Washing Machines:Variable drum-speed configurations align with textile-care preferences in urban households. Front-loading designs gain share in new-build apartments where space constraints favor stacked installations.
- Dishwashers:Built-in and freestanding units penetrate affluent Riyadh districts and hospitality retrofit projects. Water-line polymer certifications under SFDA material safety protocols extend approval timelines for new entrants.
Volume sits with air conditioners; growth tilts toward connected refrigeration as smart-home integration penetrates premium household segments.
Technology:
Margin pools concentrate where SASO mandates intersect with buyer willingness to pay for operational cost reduction over appliance lifecycle.
- Smart Appliances:Wi-Fi-enabled diagnostics and remote scheduling capabilities compress traditional service models. Urban households in Jeddah and Riyadh specify these as baseline configuration rather than premium add-on.
- Energy Efficient:Inverter-compressor and variable-speed motor technologies satisfy SASO seasonal energy efficiency ratio minimums. These models command price premiums that recover through reduced electricity consumption in high-usage cooling applications.
- Connected Devices:Ecosystem integration with home automation platforms reshapes mid-tier procurement patterns. Voice control and energy-usage analytics drive specification in Eastern Province housing stock previously underpenetrated versus Riyadh benchmarks.
- Standalone Appliances:Non-connected, fixed-speed units serve price-sensitive replacement demand in secondary cities and rental housing. Legacy inventory clearance accelerates as SASO refrigerant-phase-down deadlines approach.
Revenue concentrates in energy-efficient models; connected-device configurations expand most quickly as ecosystem interoperability standardizes.
End User:
Procurement authority shifts between post-occupancy retail selection and construction-phase bundled specification depending on asset ownership structure.
- Households:Extended-family residences drive large-capacity refrigeration and multi-split air conditioning demand. Urban household formation in Riyadh and Jeddah corridors absorbs population inflows that expand installed-base replacement cycles.
- Hotels:Hospitality operators in Makkah and Madinah corridors prioritize rapid-cycle durability and standardized maintenance protocols. Bulk procurement contracts bypass traditional retail markup structures through direct manufacturer relationships.
- Restaurants:Commercial kitchen equipment specifications emphasize food-contact surface compliance under SFDA oversight. Stainless-steel finishes and rapid-cool refrigeration serve high-turnover food service operations.
- Retail Outlets:Appliance showroom and electronics retail chains require climate-controlled display environments. Split-system cooling maintains product integrity in high-traffic commercial spaces across shopping mall concentrations.
Households anchor absolute volume; hospitality procurement shows steepest specification upgrade as Saudi Real Estate Refinance Company-financed projects expand.
Distribution Channel:
Channel power consolidates where developer-direct procurement and platform-scale online retail displace traditional specialty store relationships.
- Direct Sales:Bulk contracts with large-scale residential developers specify appliance packages at construction phase. This channel rotation is most visible in premium refrigerator and built-in cooking equipment categories.
- Online Retail:Platform aggregators aggregate comparison shopping for replacement-cycle purchases in connected urban households. Logistics networks serving Riyadh and Jeddah enable next-day delivery for standard-size appliances.
- Specialty Stores:Dedicated appliance retailers maintain service relationships and installation capabilities. These outlets retain preference for complex configurations requiring technical consultation.
- Hypermarkets:Big-box retail chains capture impulse replacement demand and entry-level segment volume. Seasonal promotional cycles align with pilgrimage-period household spending patterns.
Transaction volume flows through online and hypermarket channels; value capture tilts toward direct sales as developer procurement scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper and steel feedstock corridors near Jubail anchor Saudi Arabia's appliance assembly footprint. Manufacturing clusters in the Eastern Province and Jeddah restructure to serve Gulf demand.
Riyadh
Urban household formation absorbs population inflows that expand replacement cycles for cooling equipment. SASO seasonal energy efficiency ratio mandates redirect procurement toward inverter-driven air conditioners. Diriyah Gate development projects specify bundled appliance packages at construction phase.
Eastern Province
Dammam and Khobar corridors show underpenetrated smart-appliance adoption relative to capital benchmarks. SFDA material safety certification timelines for food-contact surfaces delay product launches. Manufacturing clusters near Jubail retool assembly lines for R32 refrigerant charge protocols.
Western Region
Jeddah's Red Sea coastline projects drive developer-direct procurement for premium refrigeration and built-in cooking equipment. Ambient temperatures exceeding 45°C across six months accelerate fixed-speed inventory clearance. Logistics networks enable next-day delivery for standard-size appliances.
NEOM Northwest
Remote settlement applications open for solar-thermal hybrid cooling convergence. Saudi Real Estate Refinance Company-financed projects bypass traditional retail markup structures. Photovoltaic generation with absorption-chiller technology targets off-grid residential deployment.
Saudi Arabia Major Home Appliances Market Competitive Landscape
Global majors compete with regional champions across distribution network depth and refrigerant-transition readiness. The vendor base stratifies between scale-driven conglomerates and mid-tier connected-device specialists. Three archetypes dominate: inverter-technology leaders, ecosystem-platform builders, and developer-direct contractors. Competitive moves concentrate on backward integration into compressor manufacturing and strategic partnerships with Saudi-based assembly operations.
Among US-based conglomerates, Whirlpool Corporation anchors premium refrigerator supply through regional distribution networks. Chinese manufacturers Hisense and Haier occupy positions across mid-tier and technology-differentiated segments respectively. Hisense exemplifies aggressive connected-device pricing strategies, while Haier represents sustained R&D intensity in inverter-compressor portfolios.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| Hisense |
| Haier |
| Midea |
| TCL |
| LG Electronics |
| Panasonic Corporation |
| Gree Electric Appliances |
| Samsung Electronics |
| Others |
Value Network & Pricing Analysis
Developer-direct procurement programs in Riyadh's Diriyah Gate and Jeddah's Red Sea coastline anchor a contract-based pricing model that bundles premium refrigeration with installation services. This buyer archetype concentration compresses retail markups while elevating after-sales service bundling as the primary price differentiation mechanism across Saudi Arabia's major home appliances landscape.
Pricing Analysis
Warranty and installation service bundling separates premium inverter-compressor models from unbundled economy-tier fixed-speed inventory. Price differentiation rests on SASO seasonal energy efficiency ratio certification tiers and developer-volume contract scale. Cost compression in the mid-tier segment is intensifying as Chinese manufacturers compete on connected-device pricing. Budget-conscious replacement buyers in secondary cities exhibit highest price sensitivity; affluent urban households in Riyadh show lowest sensitivity to upfront premiums for lifecycle energy savings.
Supply Chain Analysis
Copper cathode supply rests on Chilean and Peruvian mining operations, while R32 refrigerant production concentrates among Chinese chemical manufacturers. Compressor motors draw from Japanese and South Korean precision manufacturing, and cold-rolled steel feeds from Chinese and Indian mills. Single-source dependency on Chinese R32 output creates import-risk exposure for Jubail and Jeddah assembly clusters. Distribution runs through developer-direct bulk contracts and platform-scale online retail, bypassing traditional specialty store networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SASO energy-efficiency mandates and refrigerant-phase-down schedules construct a cost-of-compliance barrier that favors incumbents with established certification infrastructure and penalizes undercapitalized challengers.
For Market Incumbents: Cement market position by deepening backward integration into inverter-control firmware development and securing captive R32 refrigerant supply agreements with Chinese producers. The threat of aggressive connected-device pricing from Hisense demands accelerated smart-home ecosystem partnerships. Certification investment in dual SASO-SFDA compliance infrastructure represents the critical defensive lever. For New Entrants and Emerging Players: Capture white-space opportunity in Eastern Province smart-appliance penetration gaps, specifically Dammam and Khobar corridors where connected-device adoption lags Riyadh benchmarks. The developer-direct channel offers the most penetrable entry vector through Saudi Real Estate Refinance Company-financed projects. A go-to-market angle emphasizing solar-thermal hybrid cooling for NEOM remote settlements bypasses incumbent retail dominance. For Investors and Strategic Acquirers: The window for entry favors inverter-technology specialists with proven SASO compliance track records and established relationships with Saudi-based assembly operations. Long-term viability hinges on regulatory moat sustainability through successive refrigerant transitions. Watch R32 supply contract renegotiation patterns as the inflection signal for margin compression risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | In-house inverter-motor production reduces dependency on Japanese and South Korean component suppliers. |
| R32 Refrigerant Supply Agreement | Long-term offtake contracts with Chinese chemical producers mitigate single-source import-risk exposure. |
| Smart-Home Ecosystem Partnership | Platform integration with Saudi telecom operators accelerates connected-device penetration in underpenetrated Eastern Province corridors. |
| Developer-Direct Channel Expansion | Bulk procurement relationships with Diriyah Gate and Red Sea coastline projects bypass traditional retail markup structures. |
| Solar-Thermal Hybrid Cooling Development | Photovoltaic-absorption chiller convergence targets off-grid residential applications in NEOM remote settlements. |
Research Methodology
SASO regulatory filings, customs import records, and SEC 10-K disclosures from listed appliance manufacturers formed the secondary backbone for market sizing. Primary interviews with product development executives at compressor manufacturers, regulatory affairs leads navigating SASO-SFDA dual-track compliance, procurement directors at Saudi Real Estate Refinance Company-financed developers, and channel sales heads at platform aggregators combined with secondary validation through bottom-up and top-down triangulation.
Historical trendline analysis of installed-base replacement cycles and refrigerant-transition timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user category, and distribution channel structure. CAGRs derived from volume trajectory analysis incorporating urban household formation rates and SASO mandate compliance deadlines. Industry-specific forecast inputs encompassed copper and steel commodity price sensitivity and R32 refrigerant supply availability assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to refrigerant-phase-down schedule acceleration and geopolitical disruption of Chinese chemical supply chains. Forecasts reflect documented assumptions regarding SASO enforcement consistency and population inflow projections for Riyadh and Jeddah corridors. A small set of named triggers—SASO seasonal energy efficiency ratio threshold revisions, R32 supply contract disruptions, and Eastern Province smart-appliance adoption inflections—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Latin America Home Appliances Market
Home Appliances
United States Household Refrigerators Market
Home Appliances
Slovakia Home Appliances Market
Home Appliances
Kuwait Home Appliances Market
Home Appliances
India Home Appliances Market
Home Appliances
Europe Laundry Appliances Market
Home Appliances
Australia Washing Machine Market
Home Appliances
North America Major Home Appliances Market
Home Appliances
Household Refrigerator Market
Home Appliances
Chile Home Appliances Market
Home Appliances
United Kingdom Small Home Appliances Market
Home Appliances
Germany Small Home Appliance Market
Home Appliances
UAE Laundry Appliances Market
Home Appliances
Europe Small Home Appliances Market
Home Appliances
Middle East and Africa Home Appliances Market
Home Appliances
Canada Home Appliances Market