
 Oman Directional Drilling Market | 2026-2036
Oman Directional Drilling Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Directional Drilling Market Analytics
Upstream operator spending is shifting toward extended-reach horizontal programs in Oman's mature carbonate fields. Petroleum Development Oman leverages integrated asset management to sustain drilling efficiency across its Block 6 concessions. Schlumberger Limited dominates directional drilling technology deployment through its in-country engineering centers. Baker Hughes Company competes on rotary steerable system reliability in high-temperature downhole conditions.
Directional drilling encompasses the intentional deviation of a wellbore from vertical to target specific reservoir zones, typically achieving build rates of 1-15 degrees per 100 feet using steerable mud motors or rotary systems. The technique enables multilateral completions and sidetracking from existing wellbores to maximize reservoir contact in fractured carbonate formations. Rotary Steerable Systems command premium service margins due to real-time geosteering capabilities and reduced non-productive time compared to conventional positive displacement mud motors. Measurement While Drilling adoption accelerates as operators demand continuous inclination and azimuth data without pipe tripping. Onshore Drilling applications anchor volume demand, though Offshore Drilling in the Arabian Sea Block 41 generates higher per-well service intensity.
Oman's Ministry of Energy and Minerals enforces local content requirements through In-Country Value certification, directly influencing contractor selection for directional drilling packages. The Sultanate's national oil company procurement standards align with ISO 14001 environmental management and API Q2 quality specifications for service companies. PDO's technical standards mandate wellbore placement accuracy within three meters of target depth for optimal sweep efficiency in EOR projects. Stakeholders must monitor PDO's drilling activity forecasts and localization threshold adjustments to align capacity investments with operator sourcing priorities.
Market Dynamics
PDO's enhanced oil recovery mandates and Ministry of Energy and Minerals localization requirements are forcing contractors to restructure service delivery models around In-Country Value certification thresholds.
Growth Catalysts
- Rotary Steerable Systems:Upstream operators deploy these tools to navigate complex carbonate formations with real-time geosteering precision. The technology reduces non-productive time in extended-reach horizontal wells.
- North Al Sharqiyah tight gas developments:Heavy oil projects in this governorate generate sustained demand for directional drilling packages. Extended-reach capabilities unlock previously inaccessible reservoir zones.
- In-Country Value certification:The Ministry of Energy and Minerals mandates local content thresholds in procurement criteria. Contractors must demonstrate Omani workforce participation and local supplier integration.
Market Restraints
- High-temperature downhole limitations:Rotary steerable electronics face reliability degradation above 175°C in deep carbonate reservoirs. Service companies absorb warranty costs for thermal failures.
- Specialized drilling fluid chemistry:Calcium chloride and formate brine systems for carbonate formations command 40-60% price premiums over standard water-based muds. Operators bear elevated consumables costs.
- Measurement While Drilling tool concentration:Three international service companies control 85% of directional drilling telemetry capacity in the Sultanate. Limited vendor pool constrains pricing negotiation leverage.
Strategic Opportunities
- Block 41 offshore Arabian Sea:Higher per-well service intensity in deepwater environments creates premium pricing potential. Directional complexity exceeds onshore carbonate applications.
- Artificial lift integration:Directional drilling contractors partner with ESP and gas lift providers for combined artificial lift and wellbore placement packages. Integrated offerings differentiate commodity directional services.
- API Q2 quality specification alignment:Early certification to petroleum industry service quality standards positions contractors for PDO technical standard compliance. Quality management documentation accelerates bid qualification.
Industry Challenges
- Geosteering petrophysicist scarcity:Real-time wellbore placement decisions require specialists fluent in carbonate fracture network interpretation. PDO's three-meter accuracy mandates demand experienced personnel.
- Legacy positive displacement motor integration:Contractors maintain hybrid fleets combining rotary steerable systems with conventional mud motors for cost-sensitive appraisal wells. Dual capability training burdens field engineering teams.
- ISO 14001 environmental audit timelines:Certification to environmental management standards requires 12-18 month implementation cycles. Smaller contractors face working capital pressure during pre-qualification periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Directional Drilling Market |
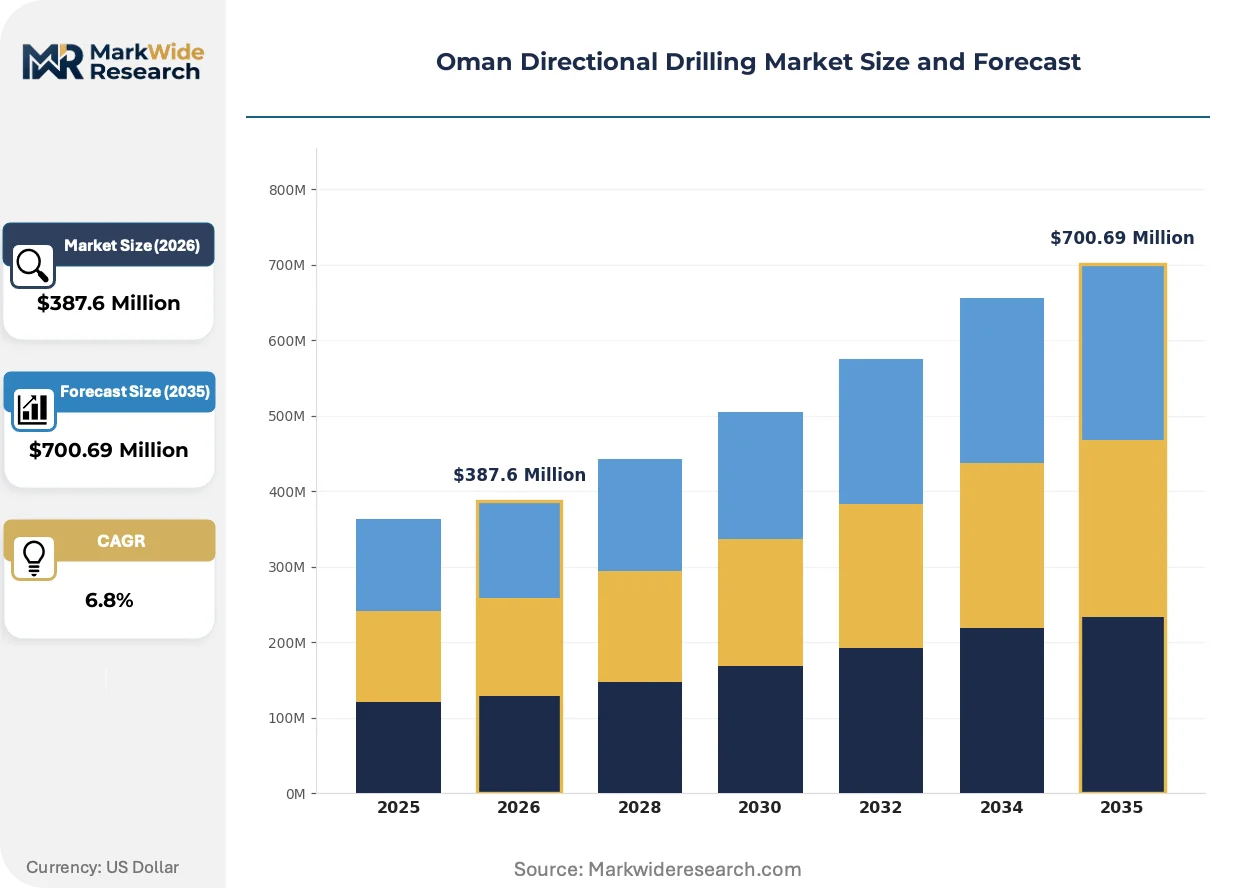
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Rotary Steerable Systems, Mud Motors, Measurement While Drilling, Conventional Drilling End User: Oil & Gas Companies, Independent Operators, Service Providers, Utility Providers Application: Onshore Drilling, Offshore Drilling, Wells Diversion, Reservoir Exploration Service Type: Directional Drilling Services, Well Planning, Engineering Services, Project Management |
| Companies Covered | Baker Hughes Company, Occidental Petroleum Corporation, Petroleum Development Oman, Royal Dutch Shell PLC, Oman Oil Company SAOC, TotalEnergies SE, Halliburton Company, Nabors Industries Ltd, Schlumberger Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Directional Drilling Market Evolving Landscape
Digital telemetry and automated steering algorithms are compressing the skill gap between experienced directional drillers and automated systems. Three distinct developments reshape competitive positioning.
Automated geosteering software is converging with resistivity-at-bit sensors to enable autonomous wellbore trajectory adjustments without surface intervention. PDO deploys these systems in Block 6 EOR projects where reservoir sweep efficiency depends on precise horizontal section placement. The convergence reduces reliance on 24/7 directional drilling engineer presence at rigsite.
In-Country Value certification requirements now mandate 30% minimum Omani workforce participation in directional drilling crews. The Ministry of Energy and Minerals audits contractor compliance through quarterly documentation submissions. Service companies respond by establishing dedicated training centers in Muscat and Sohar to accelerate national technician certification.
Integrated asset management contracts bundle directional drilling with well completion and artificial lift services. PDO's technical standards favor single-point accountability across drilling-to-production workflows. Contractors with captive supply of downhole equipment capture larger share of total well expenditure in mature field redevelopment programs.
Oman Directional Drilling Market Segmentation
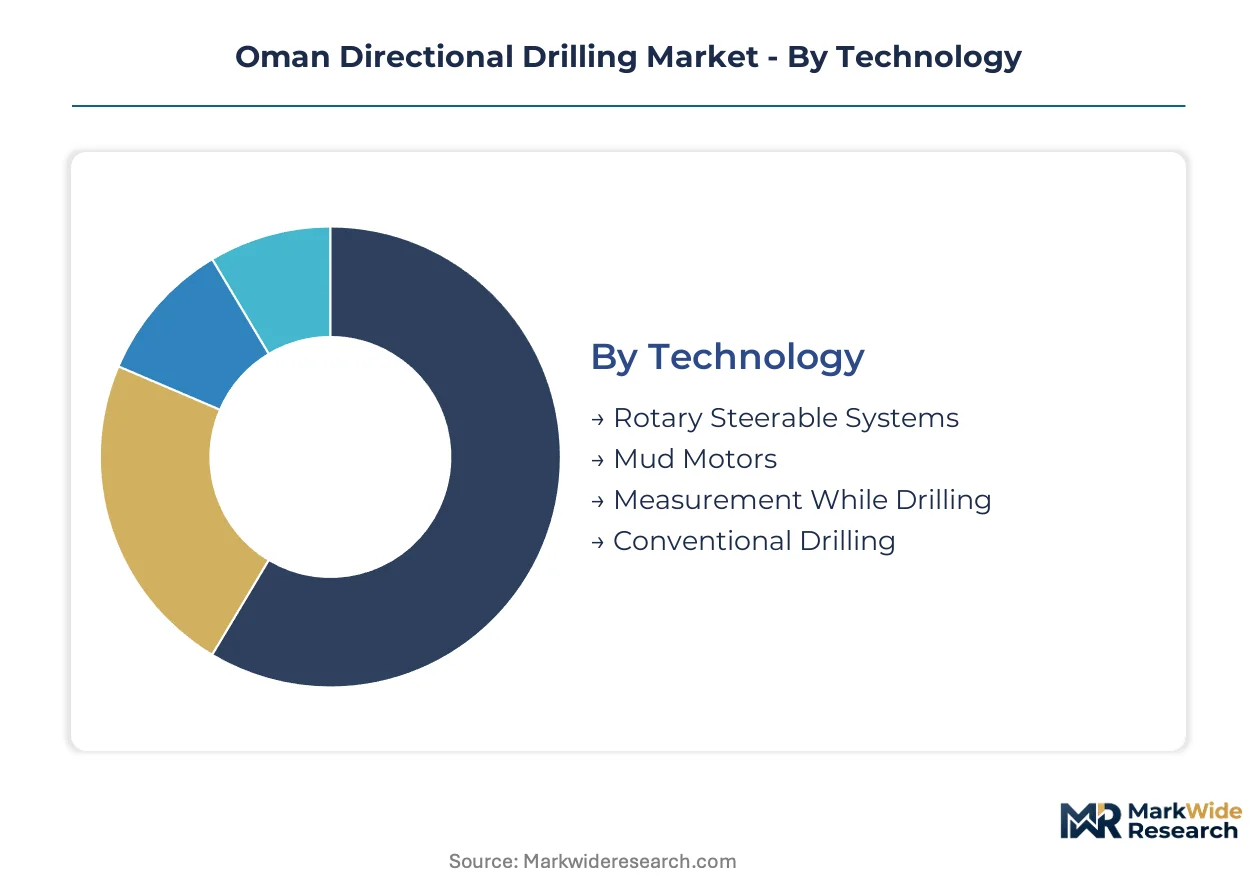
Segmentation in Oman's directional drilling market reveals how technology tiers, service bundling, and operator scale create distinct procurement corridors. Each dimension shapes contract value, localization compliance burden, and vendor qualification pathways differently.
Technology:
Supply concentration in rotary steerable telemetry creates a bifurcated procurement landscape between premium automated systems and conventional motor-based approaches.
- Rotary Steerable Systems:Real-time geosteering tools with continuous rotation eliminate sliding intervals during directional changes. PDO's Block 6 EOR mandates deploy these systems to hit three-meter wellbore placement accuracy in fractured carbonate formations.
- Measurement While Drilling:Telemetry packages transmit inclination, azimuth, and formation evaluation data without pipe tripping. North Al Sharqiyah tight gas projects demand continuous downhole data streams for extended-reach horizontal sections.
- Mud Motors:Positive displacement motors with bent-housing adjustable kickoff points serve cost-sensitive appraisal wells. Operators absorb higher non-productive time from sliding intervals.
- Conventional Drilling:Vertical wellbore techniques with minimal deviation capability anchor shallow exploration programs. Legacy fleet deployment in mature field infill drilling.
Rotary Steerable Systems absorb the bulk of installed capacity; Measurement While Drilling is expanding most quickly.
End User:
Operator scale determines contract structure, with national oil company procurement standards imposing certification tiers that filter vendor participation.
- Oil & Gas Companies:PDO and international joint venture operators dominate drilling expenditure. In-Country Value certification thresholds mandate 30% Omani workforce participation in awarded contracts.
- Independent Operators:Smaller exploration companies in Block 41 and frontier concessions. These operators prioritize cost efficiency over integrated service bundling.
- Service Providers:Drilling contractors subcontracting directional specialists for specific well sections. Fragmented demand across multiple rig operators.
- Utility Providers:Occasional geothermal and water injection well directional requirements. Peripheral volume in the overall market.
Oil & Gas Companies command the deepest contract backlogs; Independent Operators are climbing the fastest as frontier exploration accelerates.
Application:
Geographic application splits the market between mature onshore redevelopment and frontier offshore complexity.
- Onshore Drilling:Extended-reach horizontal wells in North Al Sharqiyah heavy oil and tight gas developments. Mature carbonate fields require multilateral completions to sustain production.
- Offshore Drilling:Block 41 Arabian Sea deepwater exploration with higher per-well service intensity. Directional complexity exceeds onshore applications through salt tectonics and narrow pressure windows.
- Wells Diversion:Sidetracking from existing wellbores to access bypassed pay zones. PDO's mature field redevelopment programs generate steady demand.
- Reservoir Exploration:Appraisal drilling in frontier blocks with limited subsurface data. Higher uncertainty drives conservative directional approaches.
Onshore Drilling anchors volume demand; Offshore Drilling shows the steepest expansion trajectory as Block 41 matures.
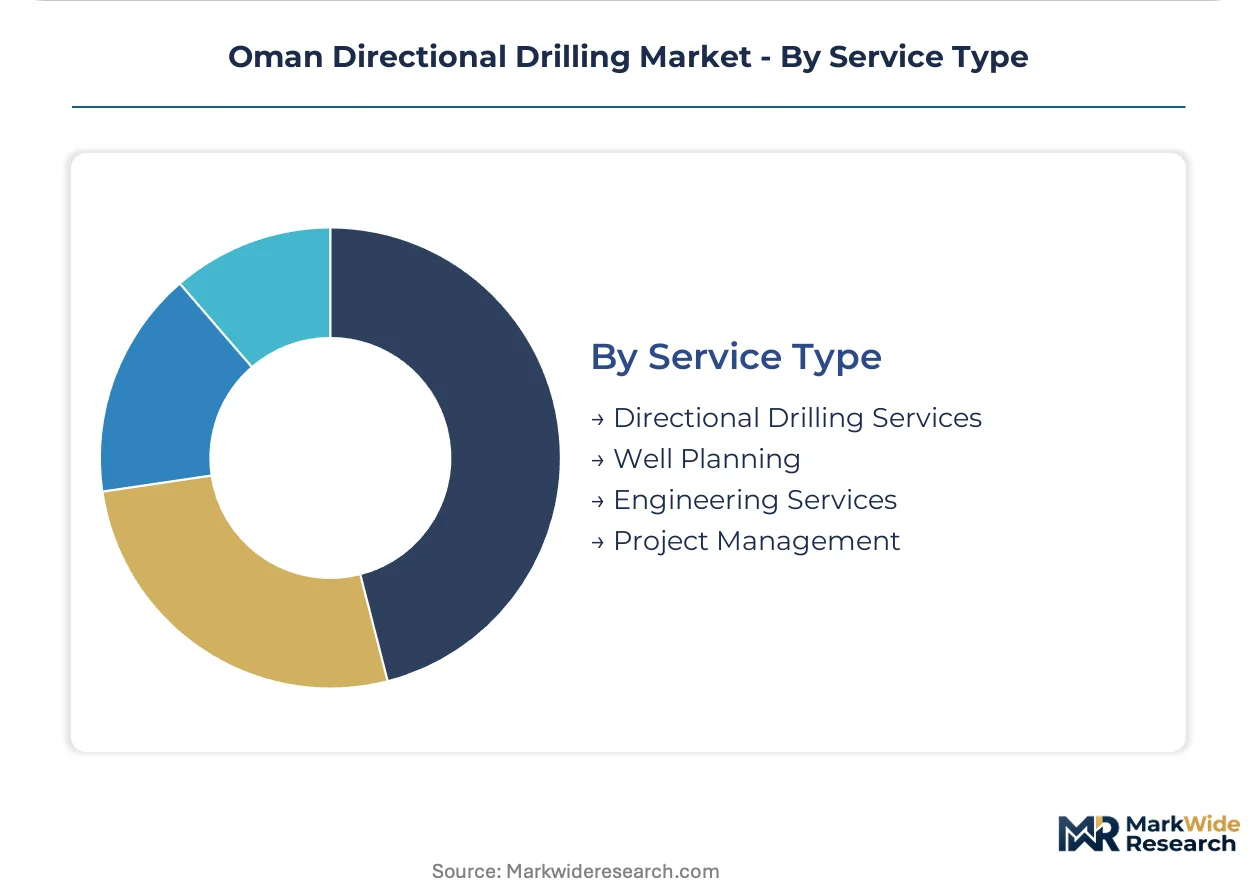
Service Type:
Service bundling intensity creates margin differentiation between standalone directional contracts and integrated asset management arrangements.
- Directional Drilling Services:Tool deployment, bottomhole assembly configuration, and real-time trajectory management. Standalone contracts face commodity pricing pressure.
- Well Planning:Pre-drill subsurface modeling, anti-collision analysis, and torque-drag simulation. PDO's technical standards mandate detailed planning documentation for EOR wellbores.
- Engineering Services:Custom bottomhole assembly design for high-temperature carbonate conditions. Specialized electronics packaging above 175°C commands premium pricing.
- Project Management:Single-point accountability across drilling-to-production workflows. Integrated offerings capture larger share of total well expenditure.
Directional Drilling Services retains the largest installed base; Project Management is gaining share fastest as PDO favors bundled accountability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Duqm Special Economic Zone concentrates directional drilling procurement for offshore frontier developments. Tax incentives and customs exemptions attract international service companies to establish logistics hubs. This SEZ infrastructure underpins exploration access to Block 41 and mature field redevelopment across the Sultanate.
North Al Sharqiyah Governorate
Heavy oil developments and tight gas projects drive extended-reach horizontal drilling demand. The Ministry of Energy and Minerals mandates In-Country Value certification thresholds for all awarded contracts. Sohar industrial city hosts service company training centers accelerating Omani technician certification for directional drilling crews.
Dhofar Governorate
Frontier exploration in southern concession blocks generates appraisal drilling activity. Block 53 and other frontier areas require specialized high-temperature directional tools. Salalah port logistics infrastructure supports equipment mobilization for southern onshore operations.
Muscat Governorate
Corporate headquarters and engineering centers for international oilfield service companies cluster here. Petroleum Development Oman maintains procurement and technical standards offices in the capital. Rusayl industrial area manufactures bottomhole assembly components for regional supply.
Al Wusta Governorate
Central Oman carbonate fields sustain mature field redevelopment drilling programs. Enhanced oil recovery mandates from PDO require precise wellbore placement accuracy. Duqm SEZ fabrication yards construct specialized drilling equipment for deployment across the governorate.
Offshore Block 41
Arabian Sea deepwater exploration commands premium directional drilling service intensity. Salt tectonics and narrow pressure windows exceed onshore directional complexity. Higher per-well expenditure attracts tier-one service company deployment of advanced rotary steerable systems.
Oman Directional Drilling Market Competitive Landscape
Top-tier vendors anchor integrated service contracts, while mid-tier specialists compete on standalone directional packages. The market structures around three international oilfield service companies controlling telemetry capacity, with national oil company affiliates capturing local content advantages. Strategic archetypes include integrated asset managers, technology licensors, and workforce localization specialists. Competitive moves center on In-Country Value certification acceleration and artificial lift service bundling.
Among Houston-based oilfield service conglomerates, Baker Hughes Company, Halliburton Company, and Schlumberger Limited exemplify the technology-integrated tier. These entities occupy positions defined by rotary steerable system deployment and real-time geosteering capabilities. Petroleum Development Oman represents the operator-side procurement authority setting technical standards and localization thresholds. Royal Dutch Shell PLC and TotalEnergies SE sit within the international joint venture participant category, influencing drilling program specifications through Block 6 and other concession governance structures.
| Leading Market Players |
|---|
| Baker Hughes Company |
| Occidental Petroleum Corporation |
| Petroleum Development Oman |
| Royal Dutch Shell PLC |
| Oman Oil Company SAOC |
| TotalEnergies SE |
| Halliburton Company |
| Nabors Industries Ltd |
| Schlumberger Limited |
| Others |
Value Network & Pricing Analysis
Captive supply of rotary steerable telemetry electronics anchors both procurement leverage and premium pricing power for tier-one service companies operating in Oman's carbonate fields. Horizontal integration across drilling, completion, and artificial lift services allows integrated contractors to bundle offerings at price points that standalone directional specialists cannot match.
Pricing Analysis
Short lead-time premiums for rotary steerable systems command substantial markups over contracted scheduled deliveries in Oman's tight gas developments. Three-tier pricing structure across premium automated geosteering, standard measurement-while-drilling packages, and economy mud motor configurations reflects certification grade and real-time capability differentiation. Cost compression in conventional motor-based services is intensifying because independent operators in frontier blocks prioritize rate-over-reliability procurement. Independent operators exhibit highest price sensitivity; PDO's integrated asset management contracts demonstrate lowest sensitivity due to total-well-cost optimization mandates.
Supply Chain Analysis
Specialized electronics for high-temperature rotary steerable tools rest on manufacturing concentration in the United States, United Kingdom, and Japan. Critical inputs include gallium nitride semiconductors, lithium battery cells for downhole power, and tungsten carbide cutting structures. Single-source vulnerability for telemetry firmware creates exposure to export control restrictions on encryption-enabled drilling technology. Distribution runs through Schlumberger, Baker Hughes, and Halliburton's in-country engineering centers in Muscat and Sohar, with secondary sourcing via Dubai logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
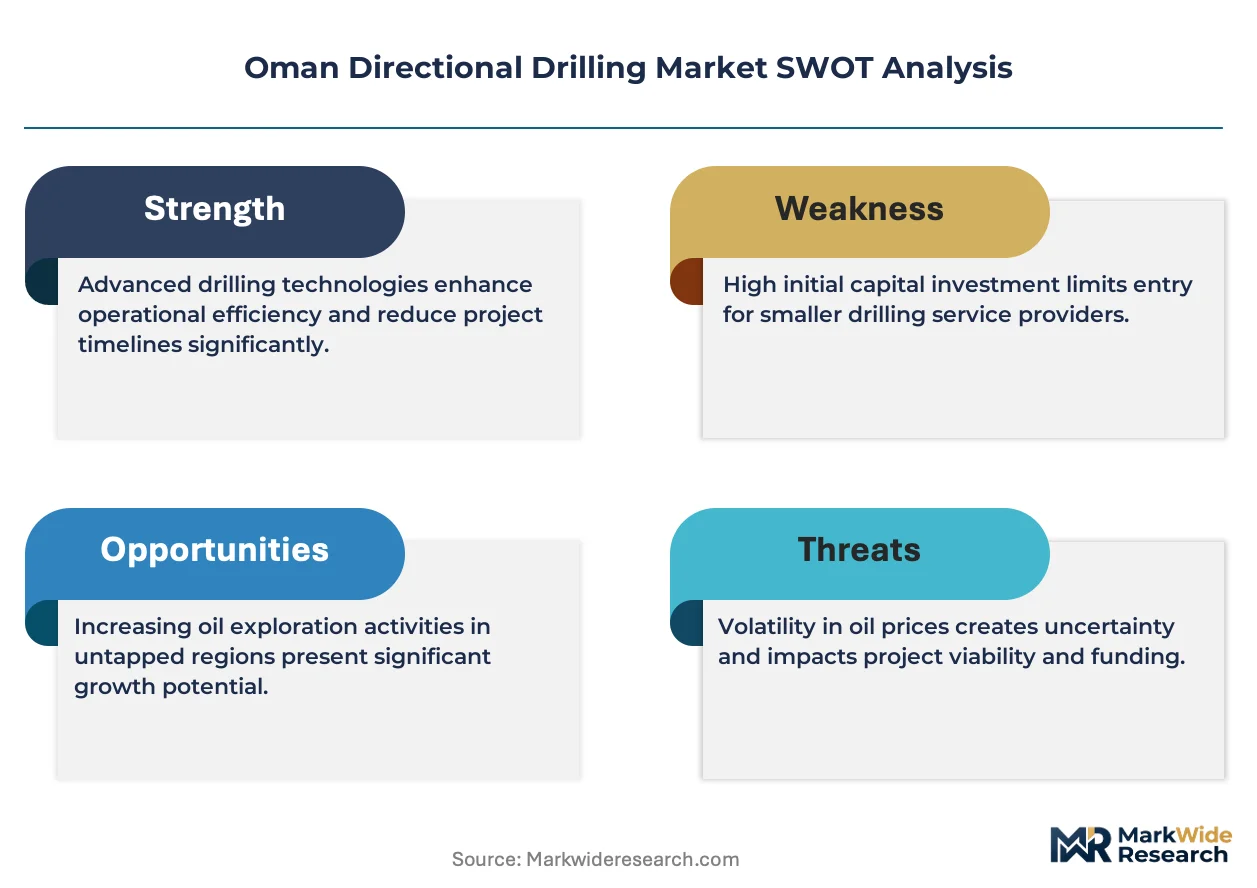
The Oman directional drilling market is becoming a vertical-integration race, with contractors pursuing captive supply of downhole electronics to capture margin pools currently flowing to third-party component vendors.
For Market Incumbents: Deepen backward integration into high-temperature electronics packaging to defend against emerging specialists from East Asian manufacturing bases. Secure long-term supply agreements for gallium nitride substrates before export licensing tightening. Invest in Muscat-based training center capacity to meet In-Country Value certification thresholds ahead of Ministry of Energy and Minerals audit cycles. For New Entrants and Emerging Players: Digital-channel route through remote geosteering advisory services offers low-capital entry into PDO's mature field redevelopment programs. Target Block 41 offshore appraisal campaigns where directional complexity exceeds tier-one capacity deployment. Pursue partnership structures with Omani drilling contractors lacking autonomous steering software capabilities. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated oilfield service conglomerates seeking Middle East directional drilling footprints. Long-term viability favors asset-light technology licensors over capital-intensive tool-owning contractors. Watch for Ministry of Energy and Minerals localization threshold increases as the inflection signal for mandatory joint venture restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Rotary Steerable System Localization | In-Country Value certification compliance opens PDO contract access for Omani-registered service entities. |
| High-Temperature Electronics Backward Integration | Captive packaging above 175°C eliminates warranty cost absorption for thermal failures in deep carbonate. |
| Artificial Lift Service Bundling | Combined ESP and wellbore placement packages differentiate commodity directional drilling offerings. |
| API Q2 Quality Certification Acceleration | Early petroleum industry service quality standard alignment accelerates PDO technical bid qualification. |
| Block 41 Deepwater Capability Buildout | Salt tectonics complexity in Arabian Sea exploration commands premium pricing unavailable onshore. |
Research Methodology
Independent corroboration across PDO drilling program disclosures, Ministry of Energy and Minerals procurement bulletins, and oilfield service company technical standards underwrites the qualitative findings. Primary interviews with drilling superintendents, geosteering petrophysicists, procurement managers at international joint venture operators, and In-Country Value compliance officers combined with secondary validation from SEC filings, API specification documents, and Oman trade registry data. Bottom-up well-count modeling and top-down operator expenditure triangulation anchored volume estimates.
Comparable-period anchoring to historical PDO drilling activity records established baseline trajectory assumptions across the projection horizon. Segmentation dimensions modeled include technology tier, service bundling intensity, operator scale category, and geographic application cluster. CAGRs derived from weighted averaging of operator capital commitment patterns and service company capacity expansion announcements. Forecast inputs incorporated carbonate reservoir complexity indices and In-Country Value threshold adjustment probabilities.
The model holds under stable PDO EOR mandate continuity and sustained Ministry of Energy and Minerals localization enforcement; deviation in international oil price collapse or export control tightening on drilling electronics would shift trajectory assumptions. A small set of named triggers—Block 41 commercialization pace, rotary steerable reliability above 175°C, and Omani workforce certification throughput—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas EPC Market
Oil & Gas
East Africa Oil and Gas Market
Oil & Gas
Offshore Drilling Fluid Market
Oil & Gas
Europe Oil and Gas Electric Submersible Pump Market
Oil & Gas
Well Intervention Service Market
Oil & Gas
Crude Oil Assay Testing Services Market
Oil & Gas
Italy Oil and Gas Market
Oil & Gas
Middle-East Oil and Gas Line Pipe Market
Oil & Gas
Norway Oilfield Equipment Rental Services Market
Oil & Gas
Latin America Coiled Tubing Market
Oil & Gas
Middle-East and Africa Liner Hanger System Market
Oil & Gas
Well Completion Market
Oil & Gas
Pumpjack Market
Oil & Gas
Unconventional Gas Market
Oil & Gas
Underreamers Market
Oil & Gas
Mineral Oil and Mineral Spirit Market