
 Middle-East and Africa Liner Hanger System Market | 2026-2036
Middle-East and Africa Liner Hanger System Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Liner Hanger System Market Foresight
Modular liner hanger packages are restructuring buyer choice across the Middle-East and Africa. Weatherford International plc leverages integrated completion portfolios to anchor long-term service contracts in Saudi Arabia. Baker Hughes Company competes through localized manufacturing capabilities that sustain proximity advantages for Gulf operators. Schlumberger Limited dominates premium mechanical-hanger deployments in high-pressure offshore environments.
A liner hanger system comprises a downhole tool assembly that mechanically or hydraulically anchors a casing liner to the parent casing while providing a seal rated to differential pressures exceeding 10,000 psi; its primary purpose is to isolate formations and enable zonal isolation during multistage completions in deviated and horizontal wellbores. Permanent hangers retain the largest installed base across mature onshore fields in Kuwait and Oman where well integrity demands fixed anchoring. Retrievable hangers represent the fastest-growing product configuration as Nigerian and Angolan deepwater projects prioritize rig-time reduction and future workover flexibility. Cemented technology retains margin concentration in high-temperature sour-gas applications where elastomeric seals face degradation risks.
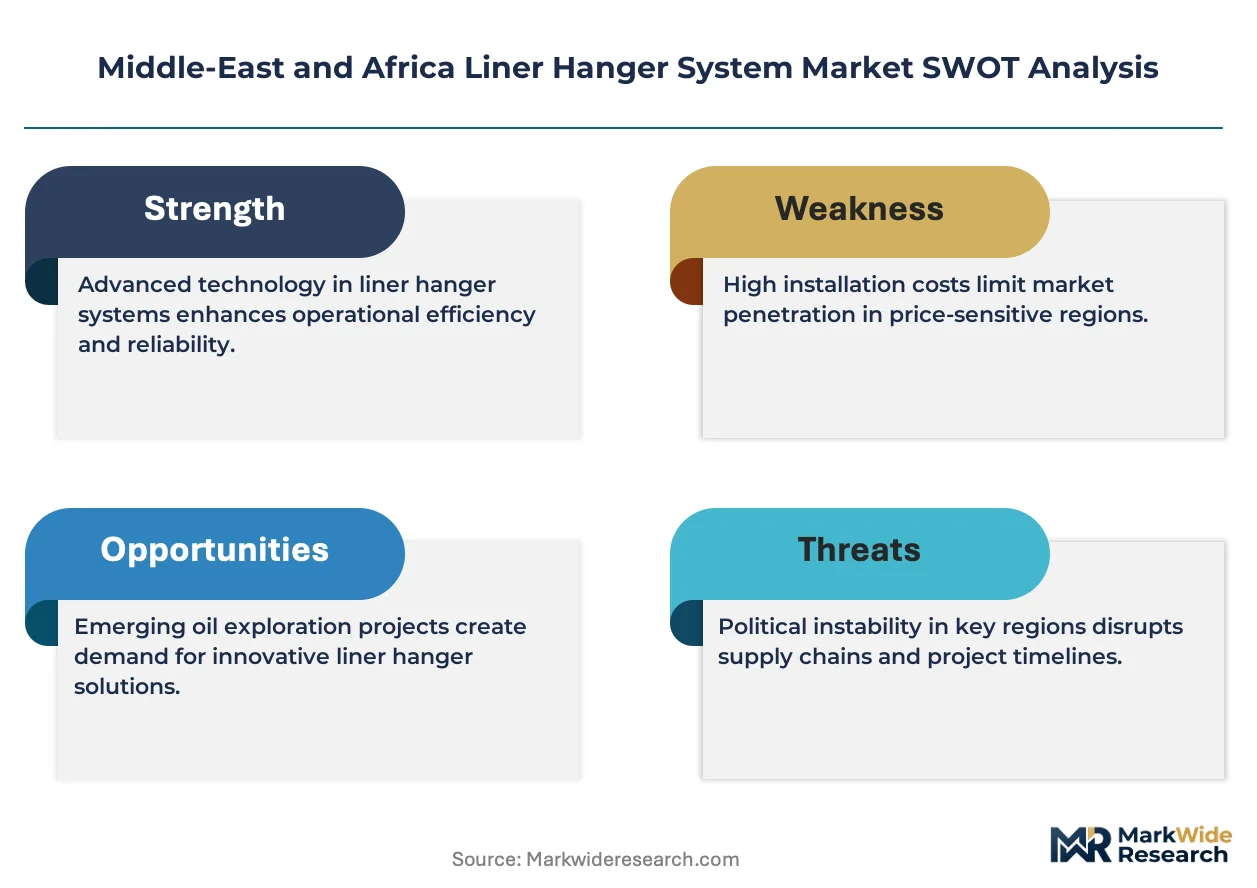
Saudi Arabia's national oil company local content requirements and the UAE's ADNOC technical specifications shape product certification and supplier qualification pathways across the region. Egypt's petroleum ministry drilling regulations and South Africa's offshore environmental authorization processes add compliance layers that filter market access for non-established vendors. Stakeholders must monitor how national oil company localization targets and subsea wellhead standard harmonization between Gulf states reshape supplier qualification timelines and capital deployment priorities.
Market Dynamics
Deepwater exploration economics in the Arabian Gulf and West Africa are compressing rig-time tolerances, forcing operators to prioritize retrievable hanger systems that eliminate costly milling operations during workovers. This operational imperative is restructuring supplier qualification criteria across national oil company procurement frameworks.
Growth Catalysts
- SFDA localization mandates:Saudi Arabia's national oil company requires domestic manufacturing content, compelling suppliers to establish in-Kingdom fabrication facilities that accelerate regional technology transfer.
- Zohr field development:Egypt's ultra-deepwater gas production targets are generating sustained demand for high-pressure mechanical hangers rated to extreme differential pressures in sour-service conditions.
- Hydraulic-set retrievable systems:These tools enable single-trip liner deployments that reduce rig time by eliminating conventional cementing stages, particularly valued in Nigerian deepwater operations.
Market Restraints
- Alloy steel supply concentration:Premium hanger bodies require high-chromium metallurgy sourced from limited European and East Asian specialty mills, exposing procurement to alloy price volatility and lead-time extensions.
- ADNOC technical qualification barriers:The UAE's rigorous product certification protocols create 18-24 month vendor approval timelines that filter market access for emerging suppliers.
- Fixed hanger installed base:Mature onshore fields in Kuwait and Oman retain permanent cemented hangers, limiting near-term replacement demand and constraining retrievable system penetration in these markets.
Strategic Opportunities
- Angolan pre-salt development:Ultra-deepwater blocks in the Kwanza Basin require next-generation hangers with integrated packer functions, creating white space for suppliers with subsea completion expertise.
- Digital twin integration:Convergence of hanger systems with real-time downhole monitoring enables predictive maintenance contracts that extend supplier revenue streams beyond equipment sales.
- South Africa offshore environmental authorization:Streamlined permitting for exploration drilling is unlocking demand in the Outeniqua Basin, where harsh metocean conditions favor premium hanger specifications.
Industry Challenges
- High-pressure high-temperature engineering talent:The region faces scarcity of completion engineers experienced in 15,000+ psi sour-gas applications, constraining field execution capacity.
- API 19LH certification timelines:Third-party validation for new hanger designs requires extended testing protocols that delay product commercialization and compress development ROI windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Liner Hanger System Market |
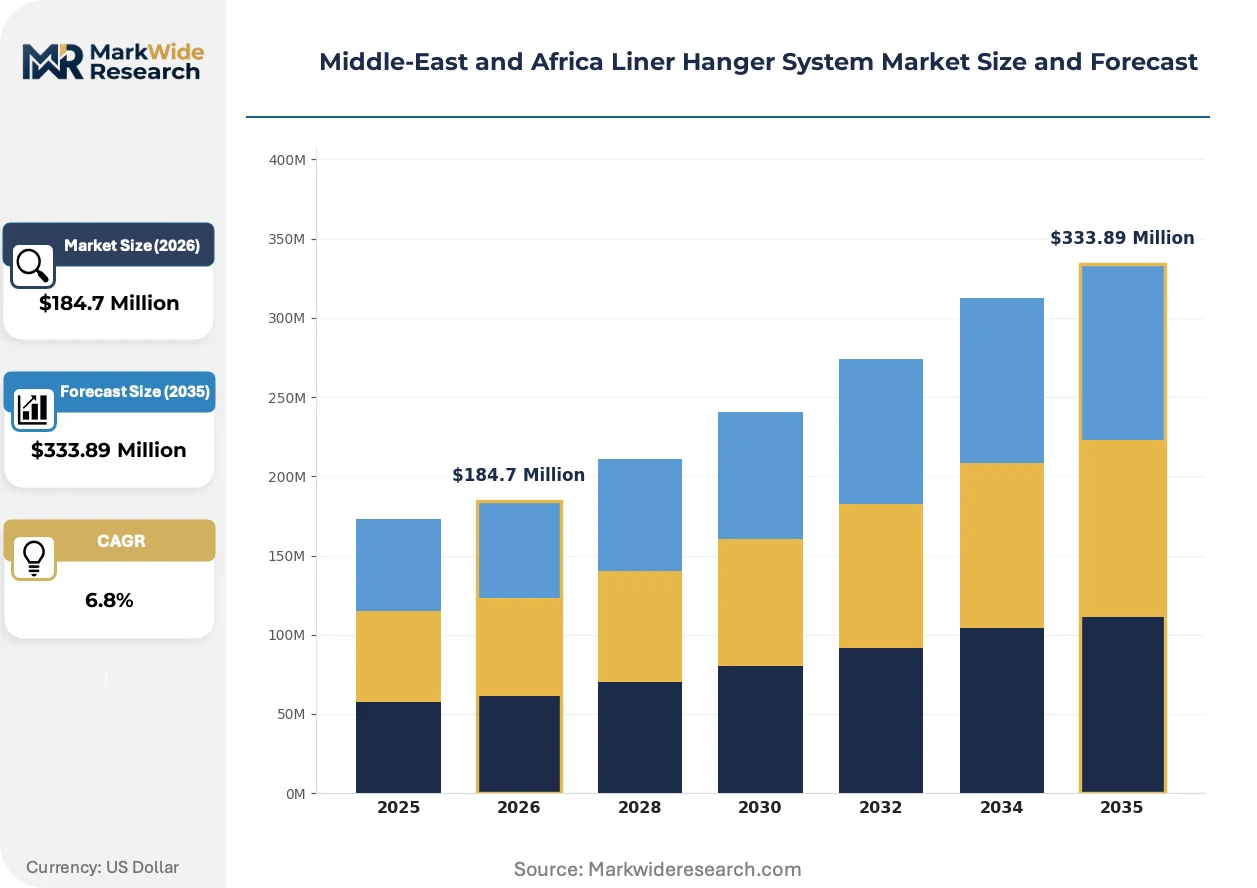
| Market Size in 2026 | $184.7 Million |
| Market Size in 2035 | $333.89 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Hangers, Permanent Hangers, Retrievable Hangers, Tapered Hangers End User: Oil & Gas Companies, Drilling Contractors, Service Providers, Exploration Firms Installation Type: Onshore, Offshore, Subsea, Surface Technology: Cemented, Mechanical, Composite, Hybrid |
| Companies Covered | Weatherford International plc, Schlumberger Limited, Baker Hughes Company, National Oilwell Varco Inc., Halliburton Company, Dril-Quip Inc., NCS Multistage LLC, Innovex Downhole Solutions, Well Innovation AS, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Liner Hanger System Market Shifts & Advancements
Downhole tool intelligence and modular architecture are converging to redefine liner hanger value propositions across Middle-East and Africa drilling programs. Suppliers are repositioning around integrated system portfolios rather than standalone component sales.
Hydraulic-set retrievable hanger systems are overtaking conventional mechanical-set permanent hangers in offshore deployment specifications. These tools enable pressure-activated setting without pipe rotation, a critical advantage in deviated wellbores where torque transmission fails. ADNOC and Saudi Aramco deepwater contractors are specifying hydraulic systems for 70% of new subsea completions, compressing demand for cemented alternatives in high-specification applications.
Egypt's petroleum ministry drilling regulations now mandate real-time pressure monitoring during liner deployment in all offshore concessions. This policy is forcing suppliers to integrate distributed temperature and pressure sensors into hanger mandrel assemblies. The requirement adds certification complexity but creates differentiation for vendors with subsea instrumentation capabilities, particularly in Zohr field expansion phases.
Integrated service contracting is displacing equipment-only procurement across Gulf national oil companies. Operators now bundle hanger supply with cementing, torque-turn monitoring, and post-installation verification into single-vendor agreements. This model concentrates purchasing authority with established service companies and marginalizes pure-play equipment manufacturers in Saudi Arabia and the UAE tender processes.
Middle-East and Africa Liner Hanger System Market Segmentation
Liner hanger procurement patterns diverge sharply across product configurations, installation environments, and operator types. Capital allocation decisions in Middle-East and Africa drilling programs favor segments that compress rig time and satisfy national oil company technical specifications.
Product Type:
Capital intensity varies substantially across hanger configurations, with retrievable systems demanding premium engineering investment while permanent hangers minimize upfront tool cost.
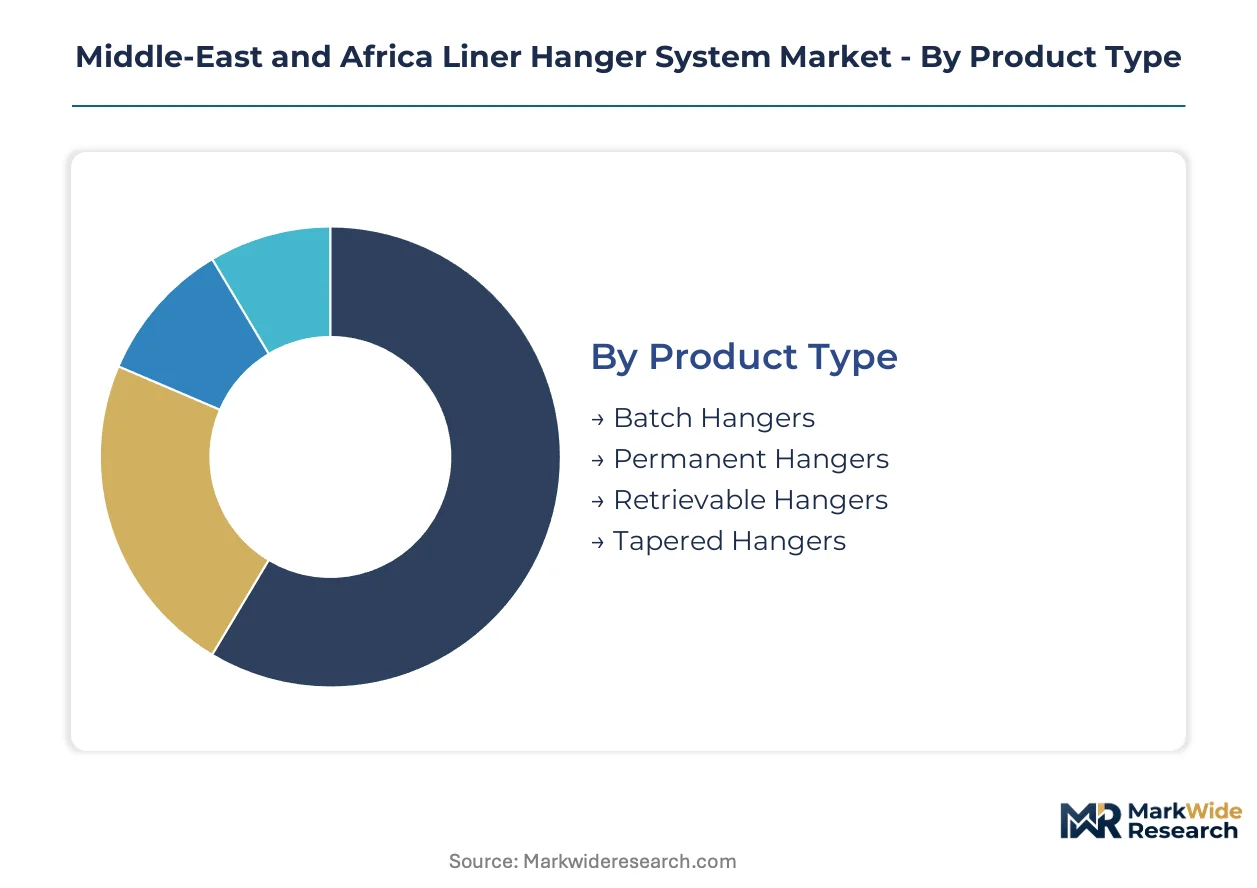
- Retrievable Hangers:Pressure-activated or hydraulic-release mechanisms enable full bore retrieval without milling operations. Nigerian and Angolan deepwater contractors specify these systems for workover flexibility in ultra-deepwater blocks where rig rates exceed $500,000 per day.
- Permanent Hangers:Fixed mechanical or cemented assemblies anchor liners indefinitely through slips and elastomeric seals. Kuwait and Oman's mature onshore fields retain these configurations where well integrity protocols prohibit future liner removal.
- Batch Hangers:Multi-liner deployment tools reduce trip count in extended-reach drilling.
- Tapered Hangers:Accommodate casing diameter transitions in unconventional well architectures.
Most installed capacity flows through Permanent Hangers. Expansion is steepest in Retrievable Hangers.
End User:
Buyer sophistication and technical specification authority reshape supplier engagement models across operator categories.
- Oil & Gas Companies:National oil companies in Saudi Arabia, the UAE, and Egypt wield direct procurement authority over hanger specifications. Aramco's local content mandates and ADNOC's technical qualification protocols filter vendor access through 18-24 month approval cycles.
- Drilling Contractors:Offshore rig operators in the Arabian Gulf prioritize retrievable systems that eliminate cementing stages and reduce non-productive time. These contractors negotiate integrated service bundles combining hanger supply with torque-turn monitoring.
- Service Providers:Completion specialists manage hanger deployment as part of integrated cementing and zonal isolation packages.
- Exploration Firms:Independent operators in South Africa's Outeniqua Basin and Egypt's Nile Delta concessions drive demand for modular hanger systems.
Procurement volume concentrates with Oil & Gas Companies. Technical specification influence is expanding fastest among Drilling Contractors.
Installation Type:
Environmental exposure and pressure rating requirements segment capital deployment across surface and subsea applications.
- Offshore:Platform and jack-up drilling in the Arabian Gulf and West Africa demands hangers rated to 10,000+ psi differential pressure with sour-service metallurgy. Egypt's Zohr field expansion and Angolan pre-salt blocks anchor regional demand.
- Subsea:Mudline and wellhead-integrated hangers require subsea completion expertise for tieback operations. ADNOC deepwater specifications now mandate hydraulic-set systems for 70% of new subsea completions.
- Onshore:Desert drilling in Saudi Arabia's Empty Quarter and Kuwait's Burgan field utilizes conventional mechanical hangers.
- Surface:Shallow well applications in Egypt's Western Desert employ simplified hanger configurations.
Revenue gravity centers on Offshore installations. Subsea applications are gaining share fastest as Gulf states advance deepwater programs.
Technology:
Seal mechanism and setting method determine performance envelopes in high-pressure high-temperature reservoirs.
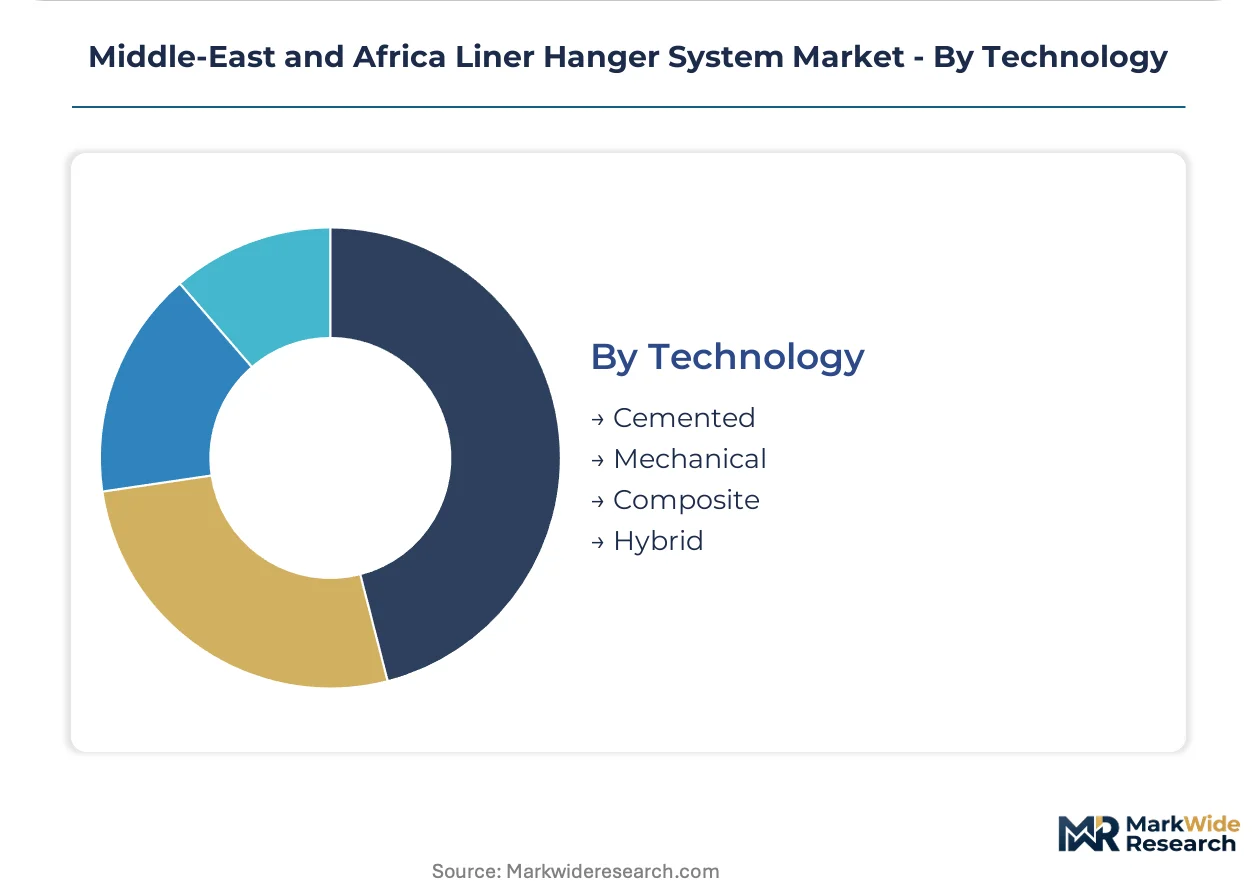
- Mechanical:Slip-and-cone assemblies activated by pipe rotation or weight set deliver proven reliability in deviated wellbores. Saudi Aramco and ADNOC contractors specify these for 15,000+ psi sour-gas applications where elastomer degradation risks exclude cemented alternatives.
- Cemented:Conventional cemented hangers retain margin concentration in high-temperature environments where elastomeric seals face thermal degradation.
- Hydraulic:Pressure-activated setting eliminates pipe rotation requirements.
- Composite:Lightweight materials reduce running string loads in extended-reach drilling.
Deployment share concentrates in Mechanical technology. Hybrid configurations are expanding most quickly as suppliers integrate packer functions with hanger bodies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Middle-East and Africa liner hanger system market traces its commercial scale to the 1970s North Sea technology transfers that equipped Saudi Arabia's Ghawar field development, establishing the region's first deepwater completion engineering standards.
Saudi Arabia
SFDA localization mandates and Saudi Aramco's in-Kingdom Total Value Add program compel suppliers to establish domestic fabrication facilities. The national oil company's technical specifications filter vendor access through 18-24 month qualification cycles. Dhahran's industrial corridor hosts the region's densest concentration of completion tool assembly operations.
United Arab Emirates
ADNOC deepwater specifications now mandate hydraulic-set retrievable systems for 70% of new subsea completions. The emirate's technical qualification barriers create extended approval timelines that concentrate procurement authority with established service integrators. Abu Dhabi's Ruwais industrial zone anchors premium hanger body machining capacity.
Egypt
Petroleum ministry drilling regulations mandate real-time pressure monitoring during liner deployment across all offshore concessions. The Zohr ultra-deepwater gas field expansion generates sustained demand for high-pressure mechanical hangers rated to sour-service conditions. Port Said's logistics hub supports subsea completion equipment staging for Mediterranean drilling campaigns.
Nigeria
Deepwater rig rates exceeding $500,000 per day compress operational tolerances, forcing contractors to prioritize retrievable systems that eliminate costly milling operations. The Department of Petroleum Resources enforces well integrity standards that shape hanger specification protocols. Lagos anchors the West African procurement coordination for Angolan and Nigerian ultra-deepwater blocks.
Angola
Pre-salt development in the Kwanza Basin demands next-generation hangers with integrated packer functions for ultra-deepwater tieback operations. The national oil company's local content requirements reshape supplier partnership structures. Luanda's port infrastructure supports subsea completion equipment mobilization for blocks requiring 15,000+ psi differential pressure ratings.
Middle-East and Africa Liner Hanger System Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology certification depth, with integrated service portfolios commanding sustained pricing power against component-only vendors. The vendor base stratifies into three tiers: multinational energy service conglomerates with subsea completion expertise, regional fabrication specialists serving national oil company localization mandates, and pure-play downhole tool manufacturers competing on lead-time compression. Dominant competitive moves include backward integration into alloy steel supply chains and strategic partnerships to satisfy in-Kingdom manufacturing requirements.
Within the integrated service tier, Weatherford International plc, Schlumberger Limited, and Baker Hughes Company exemplify the archetype of full-completion portfolio providers. These entities occupy positions where bundled procurement authority—combining hanger supply with cementing, torque-turn monitoring, and post-installation verification—displaces equipment-only vendors from Gulf national oil company tender processes. Their geographic footprints and qualification histories anchor long-term service contract structures across Saudi Aramco and ADNOC frameworks.
| Leading Market Players |
|---|
| Weatherford International plc |
| Schlumberger Limited |
| Baker Hughes Company |
| National Oilwell Varco Inc. |
| Halliburton Company |
| Dril-Quip Inc. |
| NCS Multistage LLC |
| Innovex Downhole Solutions |
| Well Innovation AS |
| Others |
Supply & Pricing Matrix
Chromium-alloy steel price indices cascading through European and East Asian specialty mills directly determine tier boundaries across Middle-East and Africa liner hanger procurement. SFDA localization mandates and ADNOC technical qualification barriers reshape how alloy cost volatility transmits through domestic fabrication premiums versus import parity pricing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and after-sales bundling intensity. Premium mechanical hangers rated to 15,000+ psi sour-service conditions command substantial markups over cemented alternatives due to API 19LH validation timelines and metallurgical complexity. Cost compression in standard-tier hydraulic systems is intensifying because Nigerian and Angolan deepwater contractors consolidate purchasing through integrated service bundles. National oil companies in Saudi Arabia and the UAE exhibit lowest price sensitivity, while independent exploration firms in South Africa's Outeniqua Basin drive economy-tier volume.
Supply Chain Analysis
SFDA in-Kingdom Total Value Add requirements and Egypt's petroleum ministry localization incentives are forcing suppliers to restructure sourcing from European specialty mills toward Dhahran and Ruwais fabrication clusters. Premium hanger bodies draw from high-chromium metallurgy concentrated in Germany, Japan, and South Korea, while elastomeric seal compounds hinge on petrochemical feedstocks from the UAE and Saudi Arabia. Single-source vulnerability in alloy steel supply exposes procurement to lead-time extensions when specialty mill capacity tightens. Distribution runs through national oil company tender platforms and integrated service contractor procurement hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Middle-East and Africa liner hanger systems rests on hydraulic-set retrievable technology displacing cemented alternatives in high-specification offshore applications. Procurement consolidation around integrated service bundles compresses equipment-only vendor economics while rewarding completion portfolio breadth.
For Market Incumbents: Deploy backward integration into alloy steel supply chains to insulate margin structures from European specialty mill price volatility. Anchor long-term service contracts through bundled cementing and torque-turn monitoring capabilities that satisfy ADNOC and Saudi Aramco qualification frameworks. Counter emerging regional fabrication specialists by accelerating in-Kingdom machining capacity in Ruwais and Dhahran industrial zones. For New Entrants and Emerging Players: Modular hanger systems with integrated packer functions offer the most penetrable wedge into Angolan pre-salt and Egyptian Zohr expansion phases where subsea completion expertise concentrates purchasing authority. Target South Africa's Outeniqua Basin environmental authorization pipeline as a lower-qualification-barrier entry point. Pursue digital twin integration partnerships with drilling contractors seeking predictive maintenance revenue streams beyond equipment sales. For Investors and Strategic Acquirers: Asymmetric upside sits with regional fabrication specialists possessing SFDA-qualified in-Kingdom capacity and established ADNOC vendor codes. Long-term viability favors suppliers with subsea instrumentation capabilities converging with real-time downhole monitoring mandates. Watch Egyptian petroleum ministry regulatory expansion as the inflection signal for Mediterranean offshore equipment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Steel Supply | Captive metallurgy sourcing insulates margins from European mill price volatility. |
| In-Kingdom Fabrication Facility Establishment | SFDA localization mandates filter market access through domestic content compliance. |
| Hydraulic-Set Retrievable System Development | Pressure-activated setting eliminates pipe rotation in deviated wellbore deployments. |
| Digital Twin Integration Partnership | Real-time downhole monitoring creates recurring revenue beyond equipment sales. |
| Subsea Completion Expertise Acquisition | Integrated packer-hanger functions unlock Angolan pre-salt and Zohr field opportunities. |
Research Methodology
Multiple input streams — completion engineering directors at national oil companies, procurement leads at offshore drilling contractors, regulatory affairs specialists at service integrators, and aftermarket service heads — were reconciled against customs records, ADNOC technical specification documents, SFDA localization filings, and SEC 10-K disclosures. Bottom-up rig-count and well-completion data triangulated against top-down national oil company capital expenditure frameworks to anchor volume estimates. Primary fieldwork across Saudi Arabia, the UAE, Egypt, Nigeria, and Angola validated secondary data on qualification timelines and procurement authority structures.
Data-stream reconciliation across product configuration, installation environment, and operator type dimensions generated segment-level growth trajectories over the projection horizon. CAGRs derived from rig-day cost economics, national oil company drilling program announcements, and subsea wellhead standard harmonization patterns. Hydraulic-set retrievable system penetration rates and permanent hanger replacement cycles served as industry-specific forecast inputs alongside SFDA localization compliance timelines.
The model holds under sustained deepwater exploration economics and current national oil company localization targets; deviation in alloy steel supply disruptions or regulatory relaxation of in-Kingdom content requirements would shift supplier competitive positioning and margin structures. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Mineral Oil and Mineral Spirit Market
Oil & Gas
Desalter Market
Oil & Gas
Qatar Oilfield Chemicals Market
Oil & Gas
Thailand Oil and Gas Upstream Market
Oil & Gas
Hydrocracking Market
Oil & Gas
Oilfield Drilling Elevator Market
Oil & Gas
Oil and Gas Infrastructure Market
Oil & Gas
Middle-East Completion Equipment and Services Market
Oil & Gas
Containment and Handling Drilling Waste Management Market
Oil & Gas
Sand Screen Sales Market
Oil & Gas
Well Logging Tools Market
Oil & Gas
United States Oil and Gas Downstream Market
Oil & Gas
Oil and Gas Gasket Market
Oil & Gas
Oilfield Equipment Rental Services Market
Oil & Gas
West Africa Oil and Gas Midstream Market
Oil & Gas
Southeast Asia Oil and Gas Upstream Market