
 Mineral Oil and Mineral Spirit Market | 2026-2036
Mineral Oil and Mineral Spirit Market Size, Share, and Industry Trends Forecast 2026-2036
Mineral Oil and Mineral Spirit Market Foresight
Buyer concentration in the automotive sector is broadening as electric vehicle manufacturers diversify supplier bases beyond traditional lubricant vendors. Sasol Limited leverages its Fischer-Tropsch synthesis expertise to produce high-purity synthetic mineral oils for precision applications. ExxonMobil Corporation sustains extensive refinery integration across the Gulf Coast, anchoring domestic supply security for industrial mineral spirits. TotalEnergies SE competes through specialized low-aromatic formulations that meet stringent European solvent standards.
Mineral oil and mineral spirit comprise refined petroleum distillates separated by boiling point range, with hydrocarbon oils typically containing C15-C50 aliphatic and naphthenic structures used for lubrication, insulation, and carrier applications. Light mineral oils serve pharmaceutical and cosmetic formulations requiring low viscosity and color stability, while heavy mineral oils dominate transformer insulation and metalworking fluid markets where thermal oxidation resistance proves critical. The paints application segment generates substantial volume demand from architectural and industrial coating producers seeking controlled evaporation rates. Chemical manufacturing end users represent a concentrated margin pool, particularly for high-purity mineral spirits employed as reaction solvents and extraction media in specialty chemical synthesis.
The EPA regulates volatile organic compound emissions from mineral spirits under Clean Air Act provisions, compelling reformulation toward low-VOC alternatives in industrial cleaning and coating applications. REACH restricts polycyclic aromatic hydrocarbon content in extender oils and rubber process oils sold within the European Economic Area, directly affecting product specifications for exporters. OSHA permissible exposure limits for n-hexane in mineral spirits mandate workplace ventilation investments across US manufacturing facilities. Stakeholders must monitor regulatory divergence between jurisdictions while evaluating backward integration into refinery operations to secure feedstock flexibility and specification control.
Market Dynamics
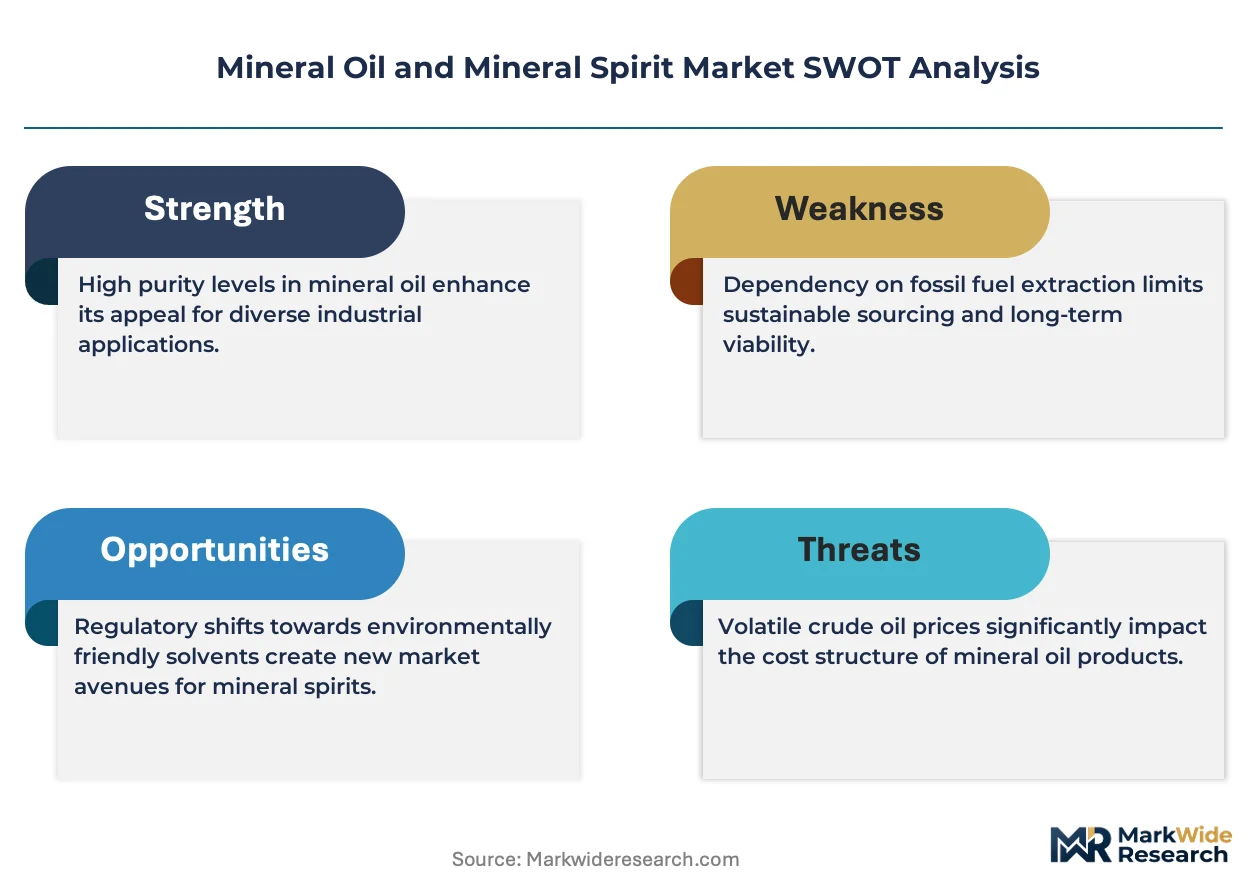
REACH compliance in Europe and EPA Clean Air Act enforcement in the United States are forcing simultaneous reformulation across mineral oil and mineral spirit product lines, compressing margins for non-integrated refiners while advantaging producers with captive hydrotreating capacity.
Growth Catalysts
- Electric vehicle thermal management fluids:Battery pack manufacturers specify synthetic mineral oils for dielectric cooling. Automotive OEMs in Germany and South Korea are qualifying new formulations.
- REACH PAH restrictions:Rubber process oil specifications below 1 mg/kg benzo(a)pyrene create premium tiers for hydrotreated extender oils. Tire producers pay compliance premiums.
- India's PLI scheme for chemicals:Domestic specialty chemical manufacturing capacity expansion drives solvent demand for extraction and reaction media. Mumbai-Pune chemical clusters anchor procurement.
Market Restraints
- Crude-linked feedstock volatility:Vacuum gas oil and waxy distillate prices track Brent differentials, compressing blender margins during upstream spikes.
- API Group I base oil refinery closures:North American and European Group I capacity rationalization concentrates supply among integrated majors, reducing spot market liquidity.
- Bio-based solvent substitution:Soy methyl ester and terpene formulations displace mineral spirits in parts cleaning where OSHA n-hexane exposure limits apply.
Strategic Opportunities
- Pharmaceutical-grade white oil certification:USP/NF and European Pharmacopoeia compliance opens cosmetic and food-contact applications with 3-4x standard industrial pricing.
- Transformer oil re-refining services:Utilities in Japan and South Korea contract for used oil regeneration, creating circular revenue streams independent of crude purchases.
- Low-aromatic mineral spirits for electronics:Semiconductor wafer cleaning specifications below 100 ppm aromatics favor Fischer-Tropsch synthetic routes over conventional refining.
Industry Challenges
- Hydrotreater catalyst replacement cycles:Nickel-molybdenum catalyst deactivation in severe service requires 18-24 month turnaround planning, constraining specification flexibility.
- Cross-jurisdiction formulation complexity:Separate product slates for EPA VOC regions, REACH-registered grades, and FDA 21 CFR 172.878 compliance multiply inventory positions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mineral Oil and Mineral Spirit Market |
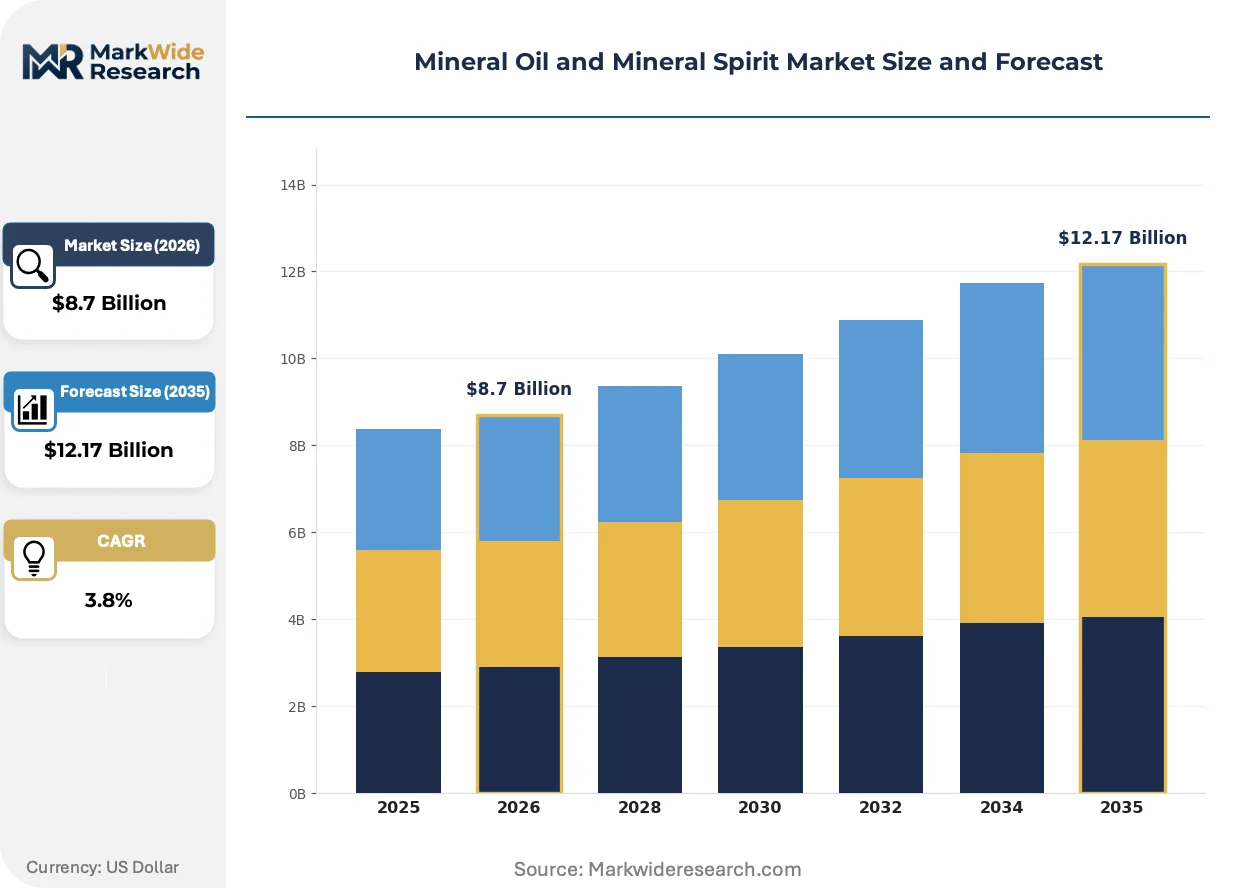
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.17 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocarbon Oils, Light Mineral Oils, Heavy Mineral Oils, Mineral Spirits Application: Paints, Adhesives, Cleaning Agents, Lubricants End User: Industrial, Automotive, Household, Chemical Manufacturing Packaging Type: Drums, IBCs, Containers, Bulk |
| Companies Covered | Chevron Corporation, Sasol Limited, ExxonMobil Corporation, PetroChina Company Limited, BP, Royal Dutch Shell plc, Phillips 66, Cepsa, TotalEnergies SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mineral Oil and Mineral Spirit Market Shifts & Advancements
Synthetic production routes and severe hydrotreating protocols are displacing conventional acid-clay refining, enabling tighter aromatic control and opening premium pharmaceutical and electronics applications previously closed to petroleum-derived products.
Gas-to-liquids Fischer-Tropsch synthesis is rewriting the competitive map for high-purity mineral oils. Sasol's Secunda facility and Shell's Pearl plant in Qatar supply near-zero aromatic base stocks. Precision lubricant blenders in Switzerland and Singapore specify these for aerospace and medical device applications. The technology compresses the addressable market for conventional solvent-refined grades above Group II quality thresholds.
REACH Annex XVII PAH restrictions on extender oils and rubber process oils entered full enforcement in 2022. Tire manufacturers serving European OEMs now require supplier certification below 1 mg/kg benzo(a)pyrene across eight regulated compounds. Korean and Thai rubber compounders have invested in hydrotreater capacity to maintain export eligibility, while non-compliant producers have exited the EU supply chain entirely.
Long-term supply agreements with fixed-price escalators are displacing spot procurement for industrial mineral spirits. Large coating manufacturers in the US Gulf Coast and Rotterdam-Antwerp corridor now contract 12-24 month volumes directly with refinery operators. This channel consolidation squeezes independent distributors and transfers inventory risk upstream, most visibly in architectural paints and industrial maintenance coatings procurement.
Mineral Oil and Mineral Spirit Market Segmentation
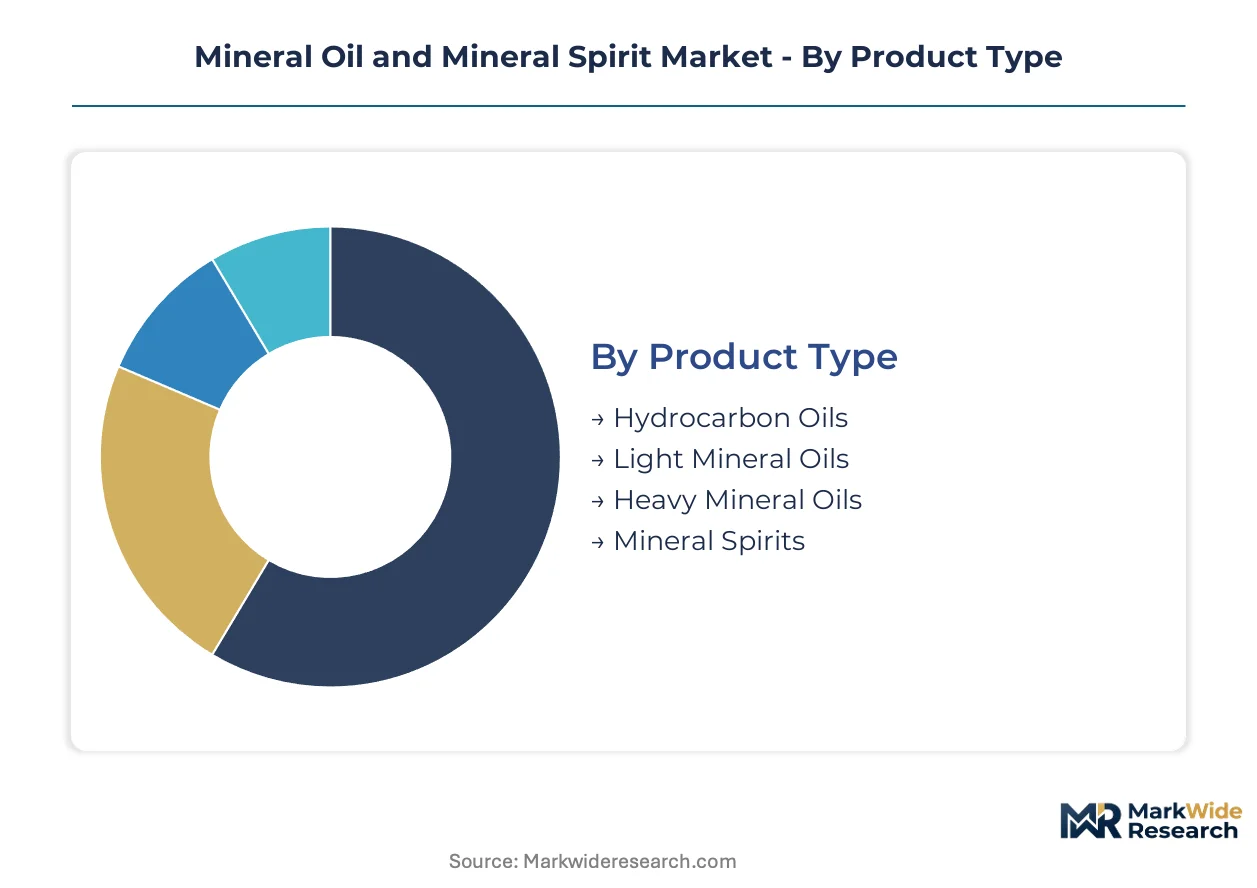
Segmentation in mineral oil and mineral spirit markets separates commodity-grade volumes from specification-controlled premiums. Refinery integration depth and hydrotreating capability determine which producers can access higher-margin tiers.
Product Type:
Supply concentration favors integrated refiners with vacuum gas oil flexibility and severe hydrotreating assets.
- Hydrocarbon Oils:Broad-cut petroleum distillates spanning C15-C50 carbon ranges serve as base stocks for lubricant blending and process oil formulations. Demand concentrates in German automotive OEM supply chains where Group I base oil rationalization has tightened spot availability.
- Light Mineral Oils:Low-viscosity, low-color variants refined through multi-stage hydrotreating meet USP/NF and European Pharmacopoeia specifications for pharmaceutical and cosmetic applications. Korean and Swiss precision blenders specify these for medical device lubrication, paying compliance premiums above industrial grades.
- Heavy Mineral Oils:High-viscosity grades dominate transformer insulation and metalworking fluid markets where thermal oxidation resistance proves critical.
- Mineral Spirits:Refined aliphatic solvents separated by controlled boiling point ranges supply paints, coatings, and industrial cleaning formulations.
Today's leader: Hydrocarbon Oils. Tomorrow's challenger: Light Mineral Oils.
Application:
Cost tier separation runs deepest in coatings, where architectural volume competes against electronics-grade purity premiums.
- Paints:Architectural and industrial coating producers consume substantial mineral spirit volumes for controlled evaporation rate formulations. US Gulf Coast and Rotterdam-Antwerp corridor manufacturers now contract 12-24 month volumes directly with refinery operators, squeezing independent distributors.
- Adhesives:Solvent-borne adhesive formulations in Asia-Pacific chemical manufacturing clusters specify low-aromatic mineral spirits for consistent drying properties. China's expanding petrochemical capacity anchors regional procurement growth.
- Cleaning Agents:Industrial parts cleaning faces bio-based substitution pressure where OSHA n-hexane exposure limits apply.
- Lubricants:Base oil demand splits between automotive engine oils and industrial machinery applications.
Paints commands current volume leadership. Electronics cleaning specifications are expanding fastest.
End User:
Customer type fragmentation creates divergent procurement patterns between contract-driven industrials and spot-market households.
- Industrial:Metalworking, textile processing, and general manufacturing operations specify technical-grade mineral oils for heat transfer and machinery lubrication. India's PLI scheme for chemicals drives domestic specialty chemical manufacturing capacity expansion, anchoring Mumbai-Pune cluster solvent demand.
- Automotive:Traditional engine lubricant demand faces structural pressure from electric vehicle transition, though battery thermal management fluids specify synthetic mineral oils for dielectric cooling. German and South Korean OEMs are qualifying new formulations.
- Household:Consumer-grade applications include furniture polishes and personal care products requiring cosmetic-grade certification.
- Chemical Manufacturing:Concentrated margin pool for high-purity mineral spirits employed as reaction solvents and extraction media in specialty chemical synthesis.
Industrial maintains installed base dominance. Chemical Manufacturing offers steepest expansion trajectory.
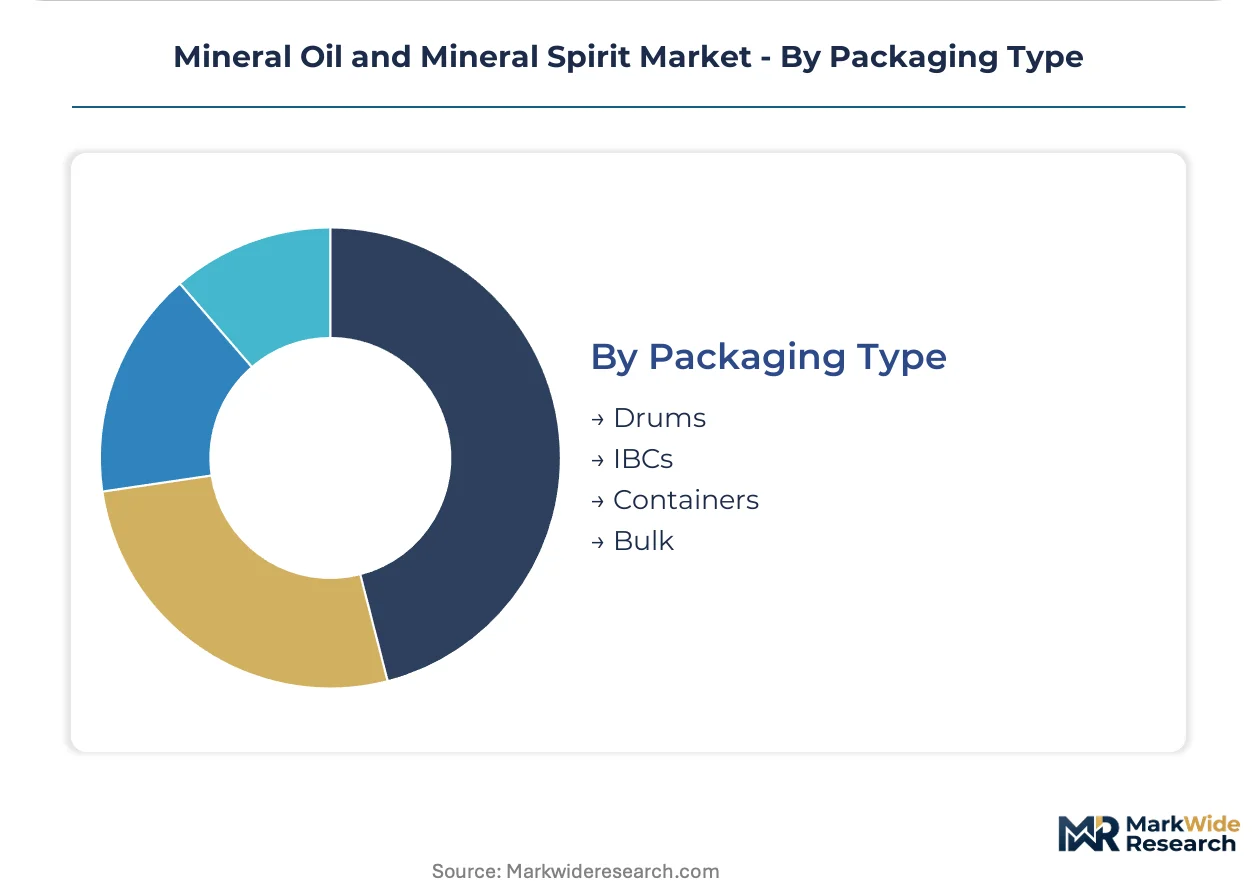
Packaging Type:
Volume scale and logistics infrastructure determine packaging economics across the value chain.
- Drums:Standard 200-liter steel drums serve mid-scale industrial users with moderate storage capacity and predictable consumption patterns.
- IBCs:Intermediate bulk containers reduce handling costs for coating manufacturers and chemical processors with integrated filling lines.
- Containers:Smaller-format packaging supplies household and specialty applications requiring precise dosing.
- Bulk:Direct refinery-to-blender transfers dominate large-volume lubricant and transformer oil procurement, eliminating packaging costs entirely.
Bulk defines cost efficiency at scale. IBCs are gaining share in just-in-time manufacturing supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's petrochemical capacity expansion outpaces India's specialty chemical manufacturing growth, while Germany's automotive OEM supply chains tighten Group I base oil availability. Regulatory divergence between EPA Clean Air Act enforcement and REACH PAH restrictions is fragmenting product specifications across these three markets.
China
Shanghai and Ningbo chemical clusters anchor solvent demand for adhesives and coatings manufacturing. The Ministry of Ecology and Environment enforces GB standards on volatile organic compound emissions, compelling reformulation of industrial mineral spirits. Yangtze River Delta petrochemical complexes are expanding hydrotreating capacity to serve domestic specialty chemical producers.
United States
Gulf Coast refinery operators contract directly with architectural coating manufacturers for 12-24 month mineral spirit volumes. EPA Clean Air Act provisions regulate VOC emissions from industrial cleaning applications, driving low-VOC alternative development. Houston and Corpus Christi blending facilities dominate domestic supply security for industrial mineral oils.
Germany
Automotive OEMs in Stuttgart and Munich specify synthetic mineral oils for precision lubrication and emerging battery thermal management systems. REACH Annex XVII restricts polycyclic aromatic hydrocarbon content in rubber process oils below 1 mg/kg benzo(a)pyrene. Ludwigshafen chemical corridor producers invest in severe hydrotreating to maintain EU market access.
India
Mumbai-Pune chemical clusters drive solvent demand for extraction and reaction media in specialty chemical synthesis. The PLI scheme for chemicals incentivizes domestic manufacturing capacity expansion. Domestic refiners are upgrading hydrotreater units to reduce import dependence for pharmaceutical-grade white oils.
South Korea
Ulsan and Yeosu petrochemical complexes supply high-purity synthetic base stocks for semiconductor wafer cleaning applications. MFDS pharmaceutical regulations align with USP/NF standards for cosmetic and medical device lubricants. Korean tire compounders have invested in hydrotreater capacity to meet REACH PAH export requirements.
Mineral Oil and Mineral Spirit Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a consolidating supplier base. Integrated majors with captive refinery assets and severe hydrotreating capacity command premium-tier positioning, while independent blenders face margin compression from crude-linked feedstock volatility. Three archetypes dominate: Gulf Coast-integrated refiners with domestic supply security, Fischer-Tropsch synthesis specialists with near-zero aromatic capabilities, and European low-aromatic formulators. Competitive moves center on backward integration into vacuum gas oil flexibility and long-term supply agreements with fixed-price escalators displacing spot procurement.
Within the integrated refiner tier, ExxonMobil Corporation and Chevron Corporation anchor Gulf Coast supply chains through extensive refinery networks. Sasol Limited occupies a distinctive position as a Fischer-Tropsch synthesis specialist, leveraging gas-to-liquids technology for high-purity synthetic mineral oils. TotalEnergies SE sits within the European formulation specialist archetype, competing through low-aromatic grades meeting stringent solvent standards.
| Leading Market Players |
|---|
| Chevron Corporation |
| Sasol Limited |
| ExxonMobil Corporation |
| PetroChina Company Limited |
| BP |
| Royal Dutch Shell plc |
| Phillips 66 |
| Cepsa |
| TotalEnergies SE |
| Others |
Supply & Pricing Matrix
Large coating manufacturers in the US Gulf Coast and Rotterdam-Antwerp corridor now contract 12-24 month mineral spirit volumes directly with refinery operators, entrenching contract-based long-term offtake as the dominant pricing model and squeezing independent distributors from margin participation.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for technical-grade mineral oils. Three-tier pricing structure across pharmaceutical-grade, industrial-grade, and commodity-grade levels separates USP/NF-certified white oils at 3-4x premiums from standard lubricant base stocks. Cost compression in Group I base oils is intensifying because North American and European refinery rationalization concentrates supply among integrated majors. Chemical manufacturing end users exhibit lowest price sensitivity due to specification-locked solvent requirements, while architectural paints procurement shows highest elasticity to crude-linked feedstock movements.
Supply Chain Analysis
Vacuum gas oil supply rests on integrated refinery complexes in the United States, China, and South Korea. Hydrotreating catalysts, waxy distillate feedstocks, and severe processing units constitute critical input dependencies. Single-source vulnerability concentrates in Fischer-Tropsch synthesis capacity anchored at Sasol's Secunda facility and Shell's Pearl plant in Qatar. Distribution runs through direct refinery-to-blender bulk transfers for large-volume lubricant procurement, with IBC and drum formats serving mid-scale coating manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through hydrotreater investments that unlock pharmaceutical-grade certification premiums and REACH-compliant rubber process oil tiers.
For Market Incumbents: Lock in captive vacuum gas oil flexibility through backward integration into refinery operations or long-term offtake agreements with Gulf Coast and Rotterdam-Antwerp corridor operators. Bio-based solvent substitution in parts cleaning applications threatens mineral spirit volumes; counter through low-aromatic formulation investments that meet semiconductor wafer cleaning specifications below 100 ppm aromatics. For New Entrants and Emerging Players: Specialty chemical manufacturers in India's Mumbai-Pune clusters represent an underserved buyer archetype with solvent demand for extraction and reaction media. Target pharmaceutical-grade white oil certification as the most penetrable tier, leveraging domestic hydrotreater upgrades to reduce import dependence. Pursue toll-manufacturing arrangements with established refiners to bypass capital-intensive distillation assets. For Investors and Strategic Acquirers: Integrated petrochemical conglomerates are the most active acquirer in this space, seeking hydrotreating capacity to secure REACH PAH compliance and synthetic base oil capabilities. Five-to-ten year viability hinges on electric vehicle thermal management fluid qualification progress at German and South Korean OEMs. Watch battery pack manufacturer formulation approvals as the critical inflection signal for synthetic mineral oil demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refinery Operations | Captive vacuum gas oil supply secures feedstock flexibility against Brent-linked price volatility. |
| Severe Hydrotreating Capacity Expansion | Enables REACH Annex XVII PAH compliance below 1 mg/kg benzo(a)pyrene for EU tire exports. |
| Pharmaceutical-Grade White Oil Certification | USP/NF and European Pharmacopoeia compliance opens cosmetic and food-contact applications. |
| Long-term Supply Agreement with Fixed-Price Escalators | Transfers inventory risk upstream from coating manufacturers to refinery operators. |
| Transformer Oil Re-refining Services | Used oil regeneration creates circular revenue streams independent of crude purchases for Japanese and South Korean utilities. |
Research Methodology
Direct dialogue with refinery operations managers, procurement leads at coating manufacturers, hydrotreater technology specialists, and specialty chemical synthesis directors grounded the qualitative assessment. Secondary validation drew from customs and trade flow data, American Chemistry Council and Cefic industry reports, SEC 10-K filings from integrated majors, and EPA Clean Air Act enforcement records. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers to ensure cross-verification.
Segment-level projections across the analysis window reflect disaggregated modeling of product type, application end-use, and regional production hub configurations. CAGRs were derived from elasticity-adjusted demand functions incorporating electric vehicle thermal management fluid adoption curves and REACH PAH restriction compliance timelines. Crude-linked feedstock volatility and hydrotreater catalyst replacement cycles informed scenario-weighted outputs.
Underlying measurement precision varies by segment; pharmaceutical-grade white oils and REACH-certified rubber process oils carry tighter precision than commodity-grade mineral spirits due to certification audit trails. Forecasts reflect documented assumptions around regulatory enforcement intensity and OEM qualification timelines. Crude price volatility, bio-based substitution acceleration, and Group I base oil refinery closure announcements constitute the small set of triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Flow Computer Oil Gas Market
Oil & Gas
United States Coiled Tubing Market
Oil & Gas
Floating Liquefied Natural Gas (FLNG) Terminals Market
Oil & Gas
Delayed Coker Unit Market
Oil & Gas
Gulf of Mexico Oil and Gas Midstream Market
Oil & Gas
Australia Oil and Gas Market
Oil & Gas
Drilling and Completion Fluids Market
Oil & Gas
Digital Oil Field Technology Market
Oil & Gas
United States Onshore Drilling Fluid Market
Oil & Gas
Oil Field Drill Bits Market
Oil & Gas
Asia- Pacific Drilling Market
Oil & Gas
Europe Oilfield Services Market
Oil & Gas
Wellhead System Market
Oil & Gas
United Arab Emirates Oil and Gas Downstream Market
Oil & Gas
Indonesia Oilfield Equipment Rental Services Market
Oil & Gas
Geothermal Drilling Market