
 Pumpjack Market | 2026-2036
Pumpjack Market Size, Share, and Industry Trends Forecast 2026-2036
Pumpjack Market Insights
The capital-intensity divergence between full-service energy technology conglomerates and specialized pumpjack manufacturers is bifurcating competitive dynamics across the artificial lift sector. Schlumberger Limited leverages integrated reservoir-to-surface capabilities to bundle pumpjack systems with diagnostic software and subsurface analytics, commanding premium positioning in complex brownfield environments. Weatherford International plc anchors its market presence through a focused artificial lift portfolio, sustaining manufacturing scale and aftermarket service density across North American shale basins. Jereh Petroleum Equipment Co., Ltd. competes aggressively on modular system architecture and regional supply chain proximity, particularly in Asian onshore markets where cost-sensitive independent operators dominate procurement decisions.
A pumpjack is a reciprocating piston pump mounted on the surface of an oil well, driven by an electric motor or internal combustion engine through a walking beam mechanism that converts rotational motion into vertical reciprocation to lift crude oil from subsurface reservoirs. The unit typically operates at stroke lengths of 54 to 192 inches and pumping speeds of 5 to 25 strokes per minute, with load capacities ranging from 3,200 to 36,500 pounds depending on well depth and fluid viscosity. Electric pumpjack configurations are gaining structural momentum as operators prioritize grid-connected or solar-hybrid power systems to reduce fuel logistics and emissions exposure in remote locations. Traditional pumpjack systems retain dominant installed-base share across mature onshore fields, though high-efficiency and variable frequency drive segments are capturing disproportionate margin pools through energy savings guarantees and reduced mechanical failure rates.
EPA methane emissions standards and API 11E structural design specifications shape equipment replacement timelines and manufacturing compliance costs for pumpjack suppliers serving the United States market. The EU F-Gas Regulation and national carbon intensity frameworks in European producing regions are progressively restricting gas-driven pumpjack deployments, redirecting procurement toward electrified alternatives with documented greenhouse gas footprints. Stakeholders must monitor regulatory divergence between methane-focused jurisdictions and carbon-pricing regimes, as equipment specification fragmentation threatens to complicate global product platform strategies and aftermarket parts standardization.
Market Dynamics
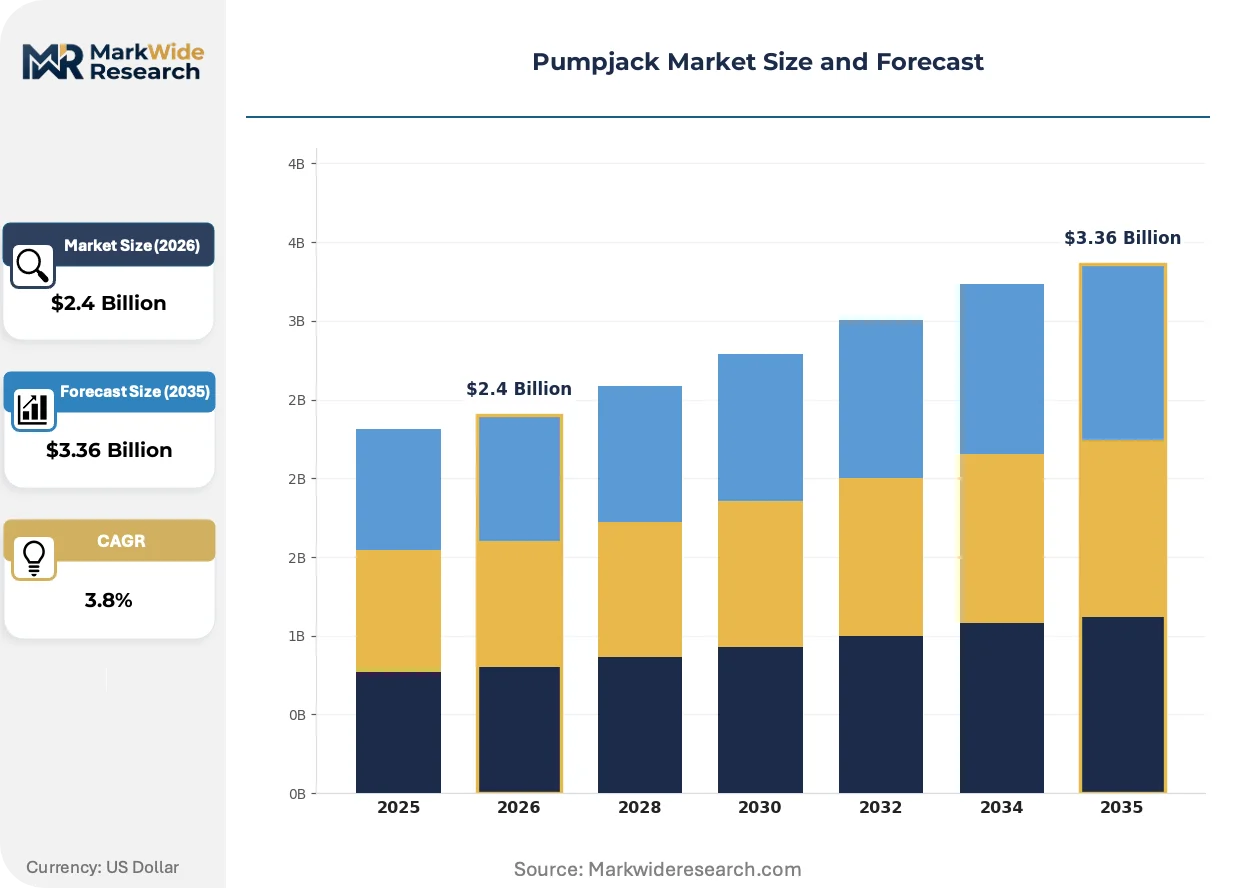
Artificial lift electrification is compressing replacement cycles across mature onshore basins as operators confront methane compliance deadlines and fuel cost volatility. Grid-connected and solar-hybrid configurations are displacing gas-engine units in regions with infrastructure access, while EPA enforcement timelines accelerate capital redeployment toward certified low-emission architectures.
Growth Catalysts
- Stripper well density in the Permian Basin:Texas and New Mexico host thousands of low-volume mature wells requiring continuous rod lift. Independent operators prioritize pumpjack reliability over production optimization, sustaining baseline equipment demand.
- EPA methane emissions standards:New source performance standards and OOOOa enforcement are forcing premature retirement of pre-2015 conventional units. Compliance-driven replacement now accounts for a substantial share of North American order flow.
- API 11E structural certification:Revised load-rating and fatigue-testing protocols are disqualifying non-certified manufacturers from federally leased operations. Certification barriers protect incumbent suppliers with established testing infrastructure.
Market Restraints
- Steel price volatility:Walking beam and structural frame fabrication depends on hot-rolled steel coil, with input cost swings compressing margin visibility for fixed-price contract manufacturers.
- Supply concentration in gearbox production:Specialized speed reducers for high-torque pumpjack applications source from a limited base of foundries in the US Great Lakes region, creating bottleneck risk during demand surges.
- Substitution by electric submersible pumps:ESP systems capture share in wells exceeding 3,000 feet true vertical depth where rod lift mechanical efficiency degrades.
Strategic Opportunities
- Electrification retrofit kits for legacy gas units:Bolt-on motor-drive packages enable methane compliance without full unit replacement, opening aftermarket revenue streams in the Appalachian Basin and Permian fringe.
- EU F-Gas Regulation alignment:European carbon intensity frameworks restrict gas-driven lift, creating first-mover advantage for electrified system suppliers with documented lifecycle emissions data.
- Remote monitoring convergence with SCADA:Integration of load-cell diagnostics and vibration analytics into existing wellsite automation platforms enables predictive maintenance subscriptions.
Industry Challenges
- Field technician shortage for rod-tubing optimization:Experienced pumpers capable of dynamometer analysis and pump-off controller tuning are aging out of the workforce faster than training programs replenish supply.
- Legacy unit interoperability with digital retrofit hardware:Pre-2000 mechanical pumpjacks lack standardized mounting interfaces for variable frequency drives and sensor packages, forcing custom fabrication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pumpjack Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.36 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Pumpjack, Helical Pumpjack, Electric Pumpjack, Gas-Driven Pumpjack Installation Type: Onshore, Offshore, Fixed Installation, Modular Installation Operational Efficiency: High-Efficiency, Variable Frequency Drive, Smart Pump, Standard Efficiency End User: Oil Companies, Independent Operators, Service Providers, Mining Corporations |
| Companies Covered | Schlumberger Limited, Halliburton Company, Weatherford International plc, National Oilwell Varco, Inc., Baker Hughes Company, Dover Corporation, Jereh Petroleum Equipment Co., Ltd., Cook Pump Company, Tenaris S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pumpjack Market Trends and Innovations
Equipment intelligence and powertrain electrification are converging to redefine lifecycle value propositions in artificial lift. Vendors now compete on energy consumption guarantees and remote diagnostic uptime rather than unit durability alone.
Variable frequency drive systems paired with permanent magnet motors are displacing conventional fixed-speed configurations across new installations. Supermajors and large independents in the Delaware Basin specify VFD packages as standard, accepting 15-20% capital premiums for documented kilowatt-hour reductions. The technology is displacing legacy NEMA motor inventory and compressing the addressable market for mechanical pump-off controllers.
EPA's OOOOa methane rule and state-level air quality mandates in Colorado and New Mexico are eliminating gas-engine pumpjack options on new permits. Operators face 95% emission reduction requirements or alternative compliance payments, redirecting procurement toward grid-tied or solar-battery electric systems. The regulatory pressure is most acute in the San Juan Basin, where coalbed methane stripper wells previously relied on small gas engines.
Service unbundling is fragmenting traditional equipment-plus-installation contracts. Large Permian operators now separate pumpjack supply from aftermarket optimization, awarding rod-tubing analysis and pump-off tuning to specialized artificial lift consultants. The shift compresses OEM service margins while elevating third-party diagnostic platforms with machine-learning failure prediction.
Pumpjack Market Segmentation
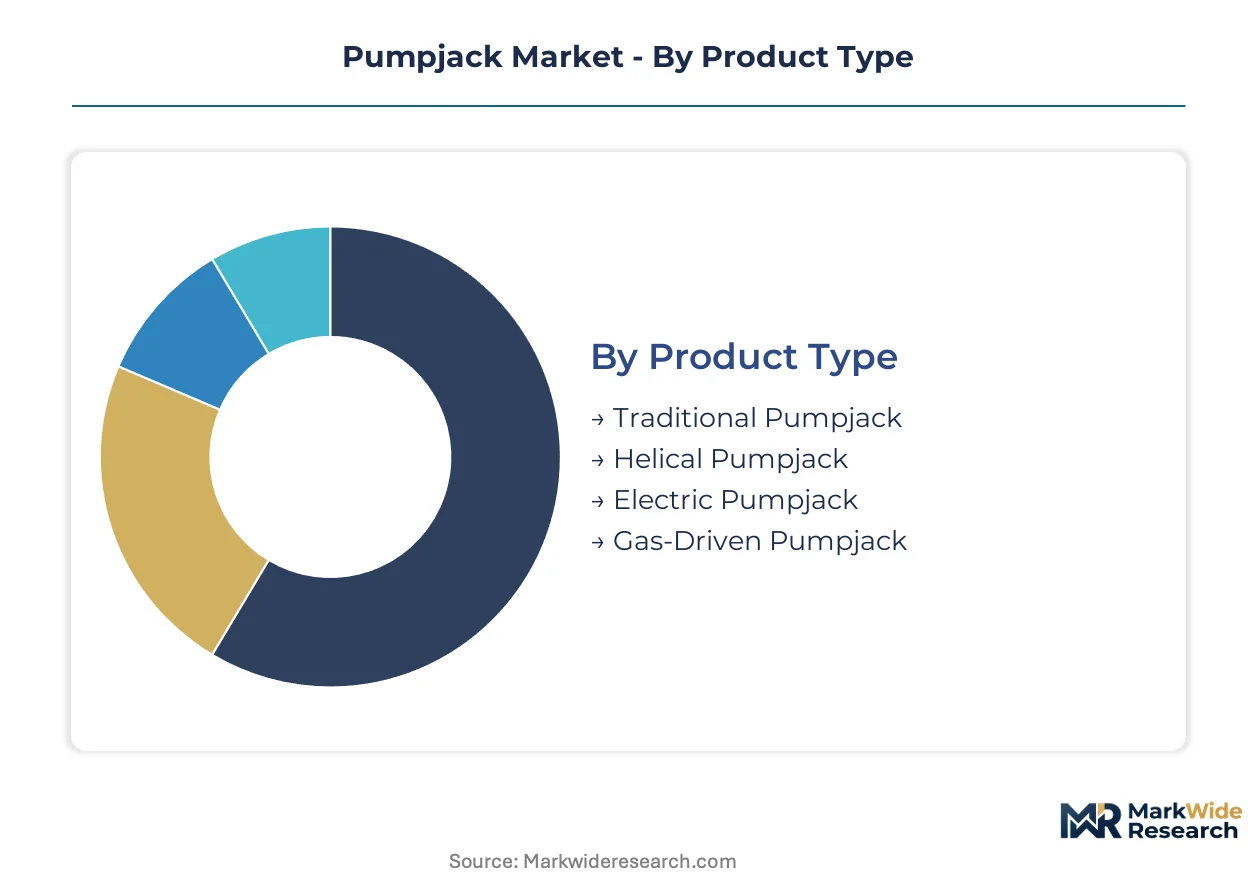
Pumpjack procurement decisions cluster around powertrain architecture, site constraints, and regulatory compliance obligations. Segment boundaries are hardening as EPA methane rules and API certification requirements disqualify non-compliant equipment categories from federally leased acreage.
Product Type:
EPA methane standards and API 11E structural specifications are bifurcating acceptable powertrain configurations across United States oilfields. Gas-driven architectures face permitting restrictions while electrified alternatives gain regulatory preference.
- Electric Pumpjack:Grid-connected or solar-hybrid permanent magnet motor systems eliminate methane venting and reduce fuel logistics burdens. Demand concentrates in the Permian Basin of Texas and New Mexico where independent operators face 95% emission reduction mandates under state-level air quality frameworks.
- Traditional Pumpjack:Conventional walking-beam units with NEMA induction motors or small gas engines retain dominant installed-base share across mature onshore fields. Replacement cycles are accelerating in the San Juan Basin as pre-2015 conventional units fail EPA OOOOa compliance deadlines.
- Helical Pumpjack:Progressive cavity pump surface drive systems handle high-viscosity crude and sand-laden production streams.
- Gas-Driven Pumpjack:Internal combustion engine configurations face procurement restrictions in Colorado and New Mexico permitting jurisdictions.
Established volume favors Traditional Pumpjack; emerging adoption favors Electric Pumpjack.
Installation Type:
Capital deployment patterns and site mobility requirements shape installation architecture selection across producing basins. Fixed infrastructure dominates brownfield redevelopment while modular systems serve exploration programs and marginal well portfolios.
- Onshore:Surface-mounted pumpjack installations across Texas, New Mexico, Oklahoma, and North Dakota account for the substantial majority of unit deployments. Stripper well density in the Permian sustains continuous replacement demand as independent operators prioritize reliability over production optimization.
- Modular Installation:Skid-mounted and containerized pumpjack packages enable rapid redeployment between marginal wells and minimize site preparation costs. Appalachian Basin operators favor bolt-on configurations for coalbed methane stripper wells with unpredictable production decline curves.
- Fixed Installation:Permanent concrete pad and anchored frame deployments serve long-life mature fields.
- Offshore:Platform-mounted artificial lift systems face salt spray corrosion and space constraints.
Fixed Installation anchors current revenue; Modular Installation offers the steepest expansion trajectory for cost-sensitive independents.
Operational Efficiency:
Energy consumption guarantees and predictive uptime commitments are displacing unit durability as the primary procurement criterion among large Permian operators. Technology tiers separate premium-priced intelligent systems from commodity standard-efficiency equipment.
- Variable Frequency Drive:VFD-equipped pumpjacks paired with permanent magnet motors enable stroke speed optimization and documented kilowatt-hour reductions. Supermajors in the Delaware Basin specify VFD packages as standard, accepting capital premiums for operational expenditure compression.
- Smart Pump:Sensor-integrated systems with load-cell diagnostics and vibration analytics feed predictive maintenance platforms. Large operators unbundle equipment supply from optimization services, awarding diagnostic subscriptions to specialized artificial lift consultants.
- High-Efficiency:Optimized mechanical linkages and reduced-friction bearings improve energy conversion ratios.
- Standard Efficiency:Conventional fixed-speed configurations serve price-sensitive procurement in marginal well portfolios.
Standard Efficiency retains volume leadership; Smart Pump is climbing the fastest as digital unbundling accelerates.
End User:
Buyer sophistication and capital access stratify demand across integrated supermajors, independents, and service intermediaries. Procurement authority is fragmenting as operators separate equipment acquisition from aftermarket optimization.
- Independent Operators:Privately held exploration and production companies dominate Permian Basin pumpjack demand, prioritizing equipment reliability and methane compliance over technology premiums. Family-owned operators in West Texas sustain baseline order flow for conventional rod lift systems.
- Oil Companies:Integrated supermajors and large independents specify electrified VFD architectures with documented lifecycle emissions data. Delaware Basin operators mandate API 11E certification and predictive maintenance integration as standard procurement requirements.
- Service Providers:Artificial lift consultants and equipment rental firms intermediate between manufacturers and wellsite operators.
- Mining Corporations:Non-petroleum extractive industries deploy pumpjack-derived pumping systems for dewatering and slurry handling.
Independent Operators anchor current procurement volume; Oil Companies drive specification escalation toward intelligent electrified systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across pumpjack procurement markets. United States operators absorb technology premiums for methane compliance, while Asian independents prioritize capital efficiency over specification escalation.
United States
Stripper well density in the Permian Basin of Texas and New Mexico sustains baseline demand for rod lift systems. EPA OOOOa methane standards and API 11E certification requirements disqualify non-compliant equipment from federally leased operations. Independent operators in West Texas prioritize reliability over production optimization, driving replacement cycles for pre-2015 conventional units.
Canada
Mature heavy oil fields in Alberta and Saskatchewan require continuous artificial lift for viscous crude production. Health Canada and provincial regulators enforce emissions disclosure for gas-driven installations, redirecting procurement toward electrified alternatives. Fabrication clusters in Calgary and Edmonton supply modular pumpjack packages for marginal well portfolios across the Western Canadian Sedimentary Basin.
China
State-directed redevelopment of aging onshore fields in Shengli and Daqing sustains demand for cost-optimized rod lift equipment. MIIT energy efficiency standards and SAMR equipment certification protocols shape domestic manufacturing compliance. Shandong Province pumpjack fabricators compete aggressively on modular system architecture for Central Asian export markets.
Russia
Western Siberian brownfields and Volga-Ural mature reservoirs anchor regional demand for high-capacity pumpjack systems. Domestic content requirements and import substitution policies protect local manufacturers from foreign competition. Equipment fabricators in Ufa and Omsk supply standardized walking-beam units for Rosneft and Lukoil field operations.
Brazil
Pre-salt marginal well redevelopment and onshore mature field optimization drive artificial lift procurement. ANVISA equipment registration and Petrobras technical specifications govern supplier qualification for national operator contracts. Manufacturing presence in São Paulo state serves Campos Basin offshore platform requirements and onshore Espírito Santo stripper well installations.
Pumpjack Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with full-service energy conglomerates commanding premium positioning through bundled reservoir-to-surface capabilities. The specialist tier competes on manufacturing scale, regional supply chain proximity, and aftermarket service density. Three archetypes dominate: integrated technology conglomerates with software-analytics bundling, focused artificial lift manufacturers with basin-specific service networks, and regional fabricators with modular cost-optimized architectures. Competitive moves concentrate on electrification retrofit partnerships and predictive maintenance platform integration.
Within the integrated tier, Schlumberger Limited and Halliburton Company exemplify full-service positioning through artificial lift portfolios embedded within broader energy technology ecosystems. Weatherford International plc anchors the focused specialist archetype with dedicated artificial lift manufacturing scale. Jereh Petroleum Equipment Co., Ltd. represents the regional modular fabricator model, competing on supply chain proximity in Asian onshore markets.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Weatherford International plc |
| National Oilwell Varco, Inc. |
| Baker Hughes Company |
| Dover Corporation |
| Jereh Petroleum Equipment Co., Ltd. |
| Cook Pump Company |
| Tenaris S.A. |
| Others |
Pricing and Supply Chain Analysis
Permanent magnet motor substitution for conventional NEMA induction systems is redrawing supply geography toward Asian magnet processing clusters while compressing pricing power for legacy motor manufacturers in North American shale basins. This displacement simultaneously elevates rare earth procurement risk and creates margin bifurcation between electrified system integrators and mechanical component fabricators.
Pricing Analysis
Aftermarket service contracts and predictive maintenance subscriptions now capture the majority of lifetime value across pumpjack deployments. Equipment vendors structure pricing around three-tier certification levels—API 11E certified premium systems, standard-efficiency mid-tier units, and non-certified economy configurations for marginal wells. Cost compression in the economy tier is intensifying because Chinese fabricators are exporting modular skid packages below North American steel-input costs. Independent operators in the Permian Basin exhibit highest price sensitivity, prioritizing unit reliability over electrification premiums, while Delaware Basin supermajors absorb technology premiums for methane compliance.
Supply Chain Analysis
Inventory cycles for high-torque gearboxes and permanent magnet motors currently stretch beyond typical field deployment timelines, creating order backlog vulnerability. Manufacturing concentration rests on China for rare earth magnet processing, the United States for specialized gearbox foundries in the Great Lakes region, and Texas for structural steel fabrication and final assembly. Hot-rolled steel coil and neodymium magnet supply constitute critical input dependencies. Tariff exposure on Chinese magnet imports presents structural risk for electrified system assemblers. Distribution runs through OEM direct sales for large operators and equipment rental intermediaries for independent stripper well portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized field technicians capable of dynamometer analysis and pump-off controller tuning are aging out of the workforce faster than training pipelines replenish, creating capability scarcity that threatens aftermarket service quality across mature North American basins.
For Market Incumbents: Fortify aftermarket service density through captive technician training programs and predictive maintenance platform integration. Incumbent suppliers should deepen backward integration into permanent magnet motor assembly to offset rare earth supply risk. Defensive positioning requires API 11E certification maintenance and VFD software stack development to repel modular Chinese entrants. For New Entrants and Emerging Players: Anchor in electrification retrofit kits for legacy gas-engine units across the Appalachian Basin and Permian fringe, where methane compliance deadlines outpace incumbent service capacity. The most penetrable white space lies in bolt-on motor-drive packages for pre-2015 conventional pumpjacks. A specialized artificial lift consultancy model—unbundling diagnostic optimization from equipment supply—offers lower capital barriers than full manufacturing entry. For Investors and Strategic Acquirers: Capital is best deployed toward regional fabricators with modular system architecture and established supply chain proximity in Asian growth markets. Long-term viability in this sector hinges on electrification transition execution and aftermarket service attach rates. The signal to watch is EPA enforcement intensity on OOOOa methane standards, which would accelerate replacement cycles and expand addressable market for compliant equipment suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Electrification Retrofit Partnership | Enables methane compliance without full unit replacement, opening aftermarket revenue in regulated basins. |
| Predictive Maintenance Platform Integration | Machine-learning diagnostics from Schlumberger and Weatherford compress unplanned downtime for Permian operators. |
| API 11E Certification Investment | Federally leased operations in Texas and New Mexico disqualify non-certified manufacturers from procurement. |
| Rare Earth Magnet Supply Agreement | Long-term offtake contracts with Chinese processors secure permanent magnet motor production for VFD systems. |
| Technician Training Program Expansion | Captive pump-off controller and dynamometer analysis instruction addresses workforce scarcity in rod lift optimization. |
Research Methodology
Operator-level perspectives from artificial lift engineers, field maintenance directors, independent E&P procurement managers, and aftermarket service technicians anchored the qualitative base for this study. Primary interview insights were cross-validated against secondary sources including EPA regulatory filings, API standards documentation, EIA production data, and SEC 10-K disclosures from listed energy technology conglomerates. Bottom-up unit deployment estimates from Permian Basin county-level production data were triangulated with top-down market sizing from artificial lift equipment trade flows.
Sensitivity analysis across steel price volatility scenarios, rare earth magnet cost trajectories, and regulatory enforcement intensity informed projection robustness. The analytical framework modeled demand across powertrain architecture, installation type, operational efficiency tier, and end-user sophistication throughout the forecast period. CAGRs were derived from replacement cycle analysis, brownfield redevelopment timelines, and electrification adoption curves. Forecast inputs incorporated stripper well decline rates, methane compliance deadline phasing, and VFD technology penetration assumptions.
Decision-makers should treat outputs as directional under base assumptions of sustained EPA OOOOa enforcement, moderate steel price volatility, and stable rare earth supply from Chinese processors; material deviation in regulatory stringency or trade policy would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Brazil Oil and Gas Market
Oil & Gas
Netherlands LNG Bunkering Market
Oil & Gas
Flow Computer Oil Gas Market
Oil & Gas
North America Shale Market
Oil & Gas
Smart Pipeline Pigging Market
Oil & Gas
Digital Oilfield Services Market
Oil & Gas
Iron Ore Mining Market
Oil & Gas
South and Central America Oil Field Services Market
Oil & Gas
East Africa Oil and Gas Market
Oil & Gas
Russian Federation Oil and Gas Midstream Market
Oil & Gas
Saudi Arabia Drilling Services Market
Oil & Gas
Africa Oil Refining Market
Oil & Gas
Oil and Gas Industry Turbomachinery Market
Oil & Gas
Drilling Services Market
Oil & Gas
Brazil Oil and Gas Midstream Market
Oil & Gas
North America Oil Country Tubular Goods Market