
 Norway Oilfield Equipment Rental Services Market | 2026-2036
Norway Oilfield Equipment Rental Services Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Oilfield Equipment Rental Services Market Analytics
Composite materials and corrosion-resistant alloys are repositioning equipment longevity economics in harsh North Sea conditions. Baker Hughes leverages integrated drilling and evaluation technologies to sustain its standing in Norway's high-specification rig market. Aker Solutions anchors its competitive stance through deep local fabrication and subsea installation expertise. National Oilwell Varco dominates the aftermarket and spare parts channel, extending its reach across the rental equipment lifecycle.
Oilfield equipment rental services encompass the short-term leasing of mobile drilling units, pressure control systems, power generation assets, and fluid handling equipment designed to API 4F and NORSOK D-001 standards for offshore hydrocarbon extraction. The primary commercial purpose centers on converting fixed capital expenditures into operational costs, enabling operators to scale asset deployment with reservoir prospectivity rather than balance sheet capacity. Drilling rigs and compressors command the largest revenue pools within the equipment type dimension, reflecting the capital intensity and mobilization complexity of jack-up and semi-submersible units serving Norway's mature basins. Time-charter and contract-drilled arrangements generate superior margins compared to bareboat structures, as bundled crews and maintenance obligations capture value from operator skill shortages.
Petroleumstilsynet (PSA) enforces facility and equipment safety standards across Norway's offshore installations, while NORSOK technical standards define material and performance benchmarks that rental assets must satisfy for market access. The EU Taxonomy's technical screening criteria for sustainable finance increasingly shape investment flows toward lower-emission drilling and electrification-ready rental fleets. Stakeholders must weigh the strategic trade-off between expanding low-carbon equipment portfolios and defending returns from conventional asset classes as regulatory stringency tightens.
Market Dynamics
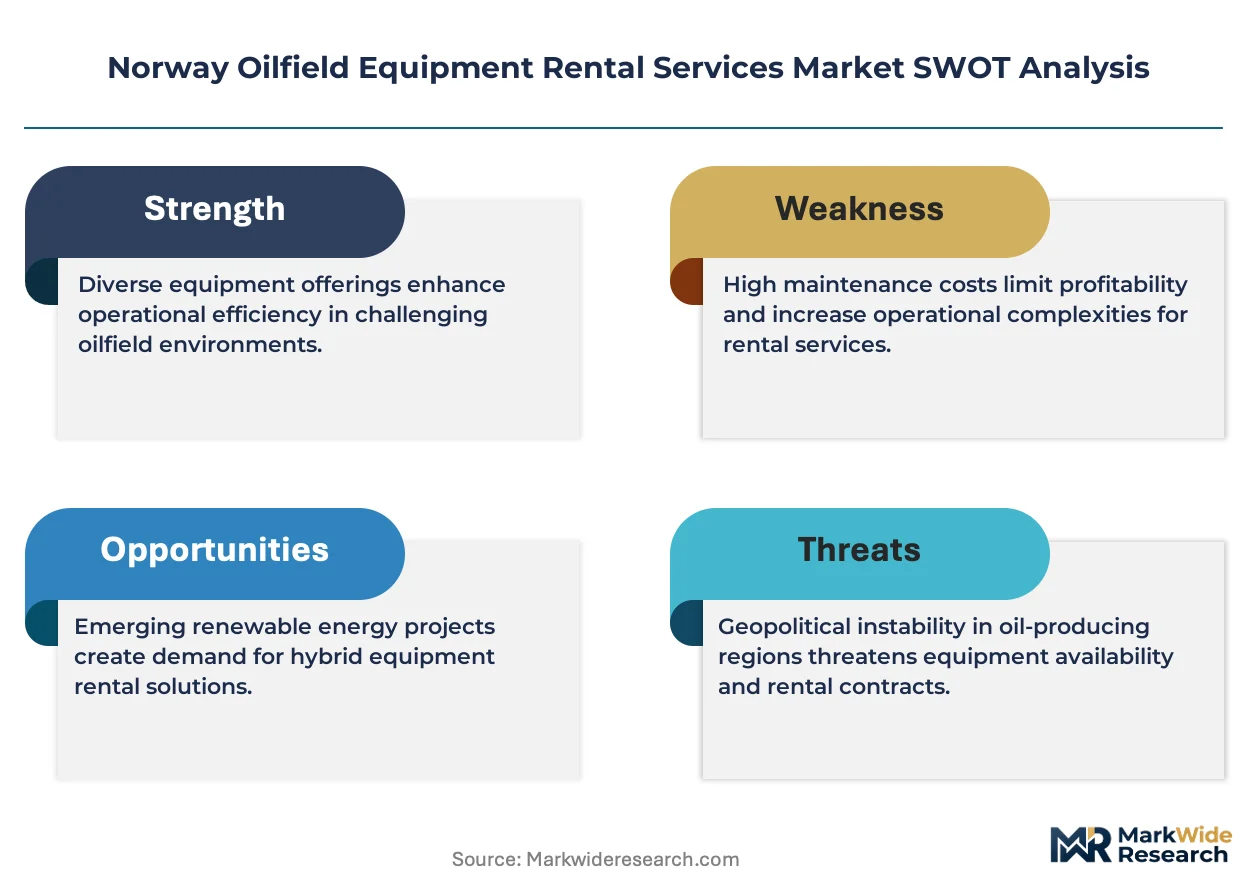
Petroleumstilsynet's tightening safety enforcement and the EU Taxonomy's technical screening criteria are forcing rental fleet operators to accelerate electrification-ready equipment retrofits while balancing returns from conventional drilling assets.
Growth Catalysts
- Subsea tieback electrification:Mature North Sea fields require flexible subsea production systems that rental models deploy faster than capital purchases. Operators in the Troll and Oseberg clusters favor short-cycle equipment commitments.
- Petroleum tax uplift allowances:Norway's uplift framework for capital-intensive projects reduces the net present cost of rental versus ownership for exploration companies. This fiscal structure directly incentivizes operational expenditure conversion.
- Corrosion-resistant alloy advances:New duplex and super-duplex stainless formulations extend equipment duty cycles in high-salinity North Sea conditions. Rental providers capture value from accelerated replacement cycles.
Market Restraints
- Steel alloy input volatility:Nickel and molybdenum price swings compress fabrication margins for pressure control equipment. Norwegian fabricators face margin pressure when quoting long-term rental contracts.
- Specialized labor scarcity:Stavanger and Bergen clusters compete for finite subsea installation technicians. Wage inflation in the Greater North Sea basin erodes project economics.
- Electrification infrastructure gaps:Shore power connection delays at Johan Sverdrup and Snorre fields postpone diesel-to-electric rig conversions. Rental fleets retain higher-emission assets longer than planned.
Strategic Opportunities
- Barents Sea frontier development:Goliat and Snøhvit expansions require Arctic-grade rental equipment with extended temperature ratings. Local fabrication capacity in Hammerfest remains underdeveloped relative to demand.
- Carbon capture integration:Offshore platform electrification creates demand for modular CO2 compression skids on rental terms. Equinor's Northern Lights project anchors early adoption.
- EU Taxonomy-aligned fleet financing:Green bond issuance for lower-emission drilling rigs opens preferential capital pools. Rental providers with documented emission reductions access cheaper funding than conventional asset owners.
Industry Challenges
- NORSOK D-001 recertification timelines:Updated drilling equipment standards require extensive third-party validation. Rental assets face 6-12 month certification delays that idle revenue-generating units.
- Legacy SCADA integration:New digital twin platforms must interface with 1990s-vintage platform control systems. Electrification projects stall when telemetry protocols prove incompatible.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Oilfield Equipment Rental Services Market |
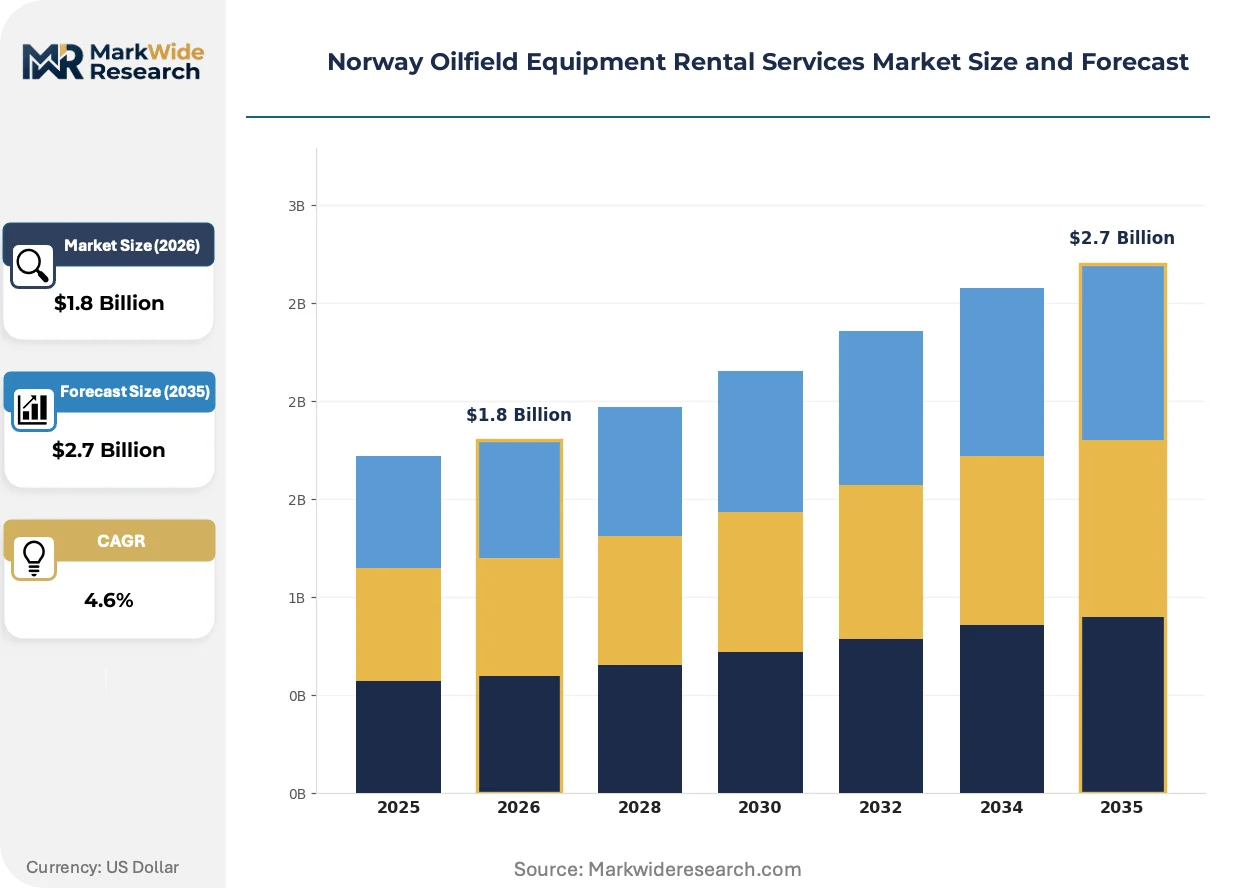
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Drilling Rigs, Compressors, Pumps, Generators Client Type: Exploration Companies, Oil & Gas Operators, Service Providers, Contractors Contract Type: Time-Charter, Bareboat, Contract-Drilled, Service-Driven Seasonality: Peak Season, Off-Peak Season, Maintenance Period, Mobilization Phase |
| Companies Covered | Baker Hughes Company, Aker Solutions, Transocean Ltd, National Oilwell Varco, Halliburton, Seadrill Ltd, Weatherford International PLC, TechnipFMC PLC, Schlumberger Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Oilfield Equipment Rental Services Market Evolving Landscape
Digitalization and decarbonization mandates are restructuring how Norwegian operators contract mobile assets, with modular architectures and outcome-based agreements displacing traditional bareboat structures.
Subsea production systems are modularizing around standardized connection interfaces and interchangeable power modules. Equinor and Aker BP are specifying rental configurations that reconfigure between tieback and standalone service without dry-dock intervention. This flexibility compresses field development timelines from sanction to first oil.
The EU Taxonomy's technical screening criteria for sustainable finance now governs institutional capital allocation to Norwegian offshore projects. Rental fleet operators must document lifecycle emission profiles to qualify for green-labeled debt instruments. Drilling contractors with electrification-ready jack-up rigs capture preferential contract terms in the Johan Sverdrup electrification cluster.
Integrated service contracts are displacing discrete equipment rentals among North Sea exploration companies. Bundled offerings that combine drilling units, managed pressure control, and real-time formation evaluation reduce interface risk for operators. This consolidation concentrates procurement authority with Stavanger-based technical teams and compresses vendor rosters to three or four integrated providers per major development.
Norway Oilfield Equipment Rental Services Market Segmentation
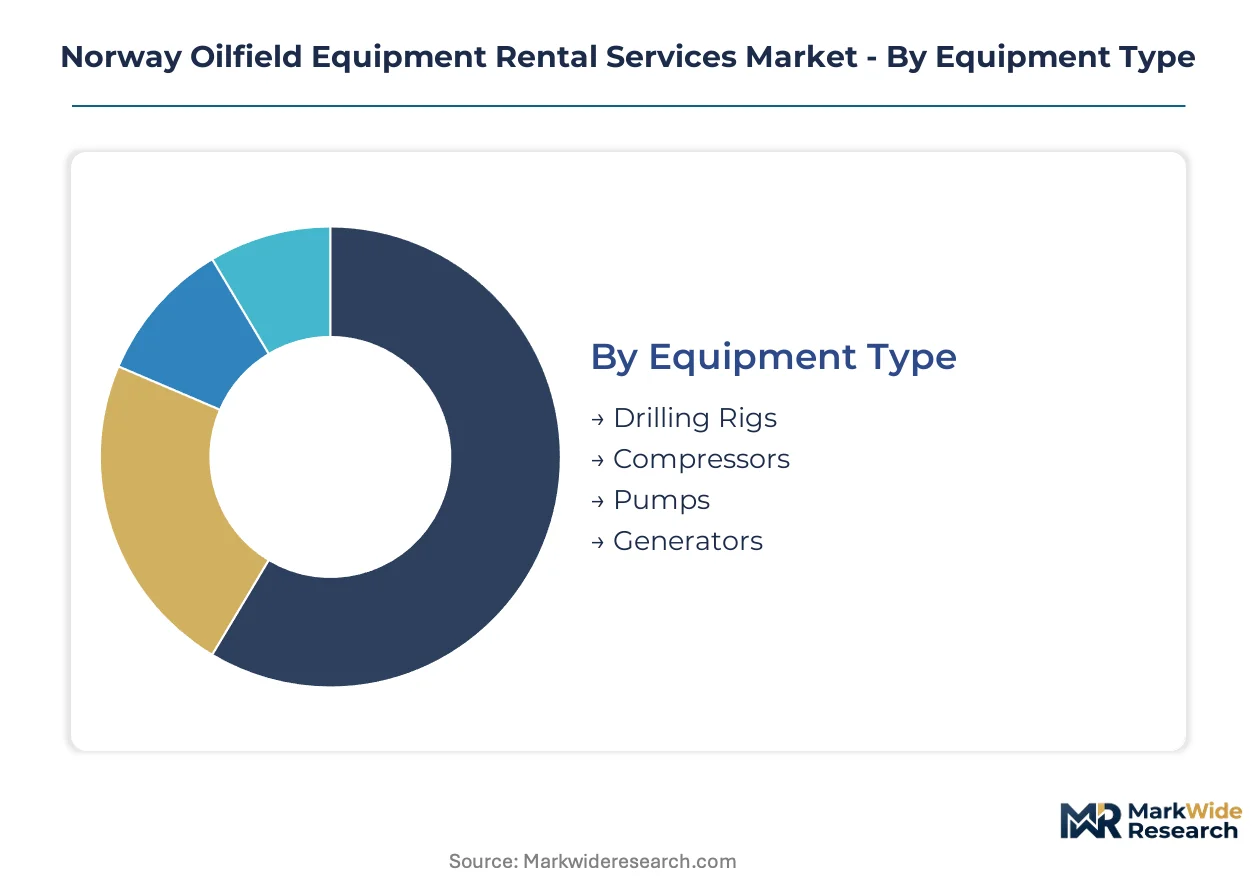
Segmentation in Norway's oilfield equipment rental market reveals how operator procurement strategies diverge across asset types and contractual structures. Tax incentives and electrification timelines reshape which equipment categories and contract forms operators favor in the North Sea basin.
Equipment Type:
Capital intensity and mobilization complexity drive rental decisions, with operators balancing upfront savings against operational control needs.
- Drilling Rigs:Jack-up and semi-submersible units dominate capital deployment in the Troll and Oseberg clusters. Operators favor time-charter arrangements here due to crew shortages and Petroleumstilsynet safety enforcement.
- Compressors:Modular gas compression skids serve mature field redevelopment and carbon capture integration at Equinor's Northern Lights project. Demand concentrates where platform electrification requires flexible gas handling capacity.
- Pumps:Subsea boosting and mud circulation systems deploy across tieback developments.
- Generators:Power modules support rig electrification and shore power transition delays.
Volume sits with Drilling Rigs; growth tilts toward Compressors.
Client Type:
Procurement authority concentrates with entities holding field equity and development sanction power.
- Oil & Gas Operators:Equinor and Aker BP dominate fleet contracting through integrated service agreements bundling multiple equipment categories. Their Stavanger-based technical teams compress vendor rosters to three or four providers per major development.
- Exploration Companies:Smaller equity holders in the Barents Sea frontier rely on rental models to preserve balance sheet capacity for drilling commitments. Goliat and Snøhvit expansions require Arctic-grade equipment without ownership burdens.
- Service Providers:Subcontractors rent specialized assets for discrete installation scopes.
- Contractors:Construction and maintenance firms source supplementary equipment during mobilization phases.
Contract concentration favors Oil & Gas Operators; Exploration Companies expand most quickly.
Contract Type:
Risk allocation and crew responsibility determine margin structures and operator preference.
- Time-Charter:Bundled crews and maintenance obligations capture premium pricing from operators facing Stavanger-Bergen technician shortages. This structure dominates jack-up rig deployment.
- Contract-Drilled:Performance-based drilling contracts shift geological risk to contractors while operators retain reservoir upside. Aker BP specifies these arrangements for high-cost exploration wells.
- Bareboat:Equipment-only rentals appeal to operators with captive technical capabilities.
- Service-Driven:Outcome-based agreements tie compensation to production targets or drilling efficiency metrics.
Revenue pools concentrate in Time-Charter; Contract-Drilled gains share fastest.
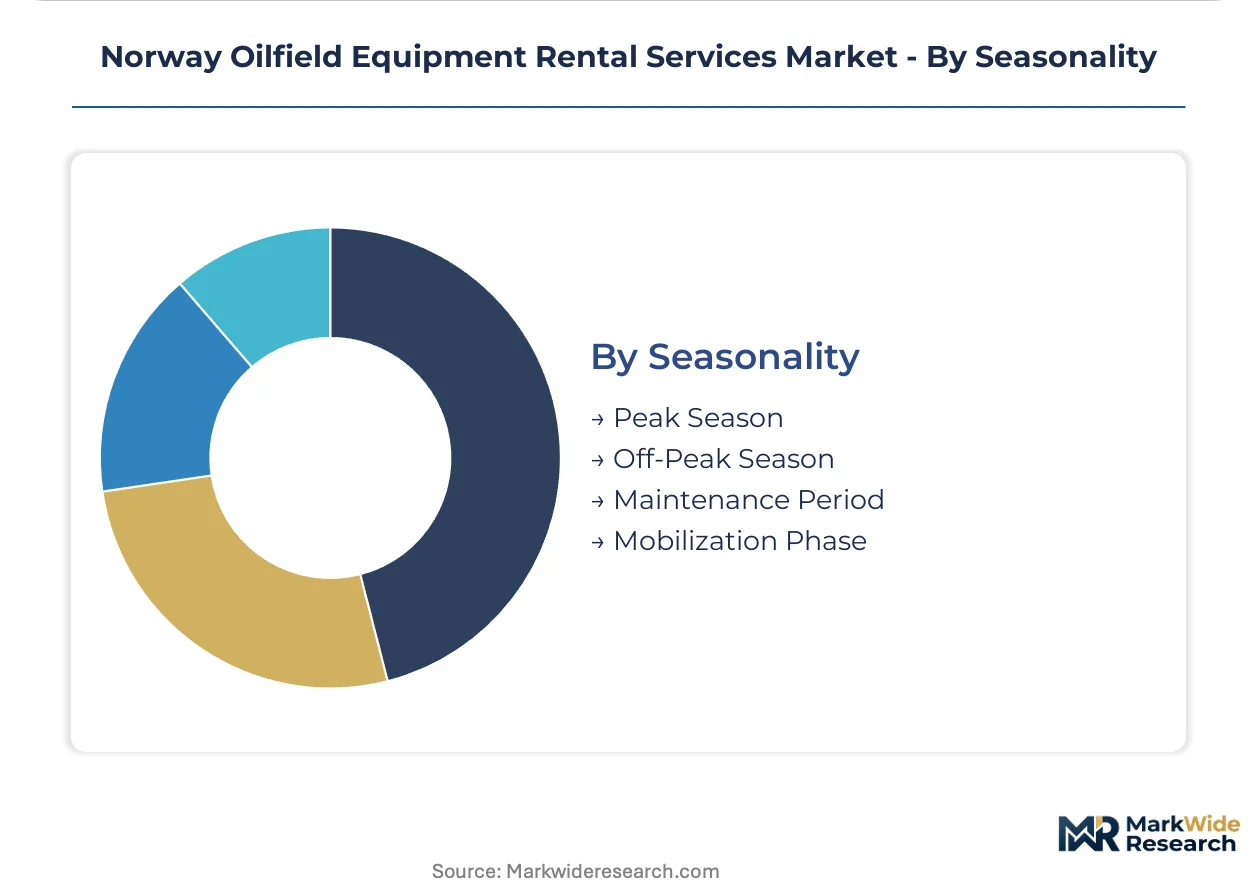
Seasonality:
Weather windows and maintenance cycles create predictable demand pulses across the Norwegian Continental Shelf.
- Peak Season:Summer drilling campaigns in the Barents Sea and North Sea drive maximum rig utilization. Arctic-grade equipment commands availability premiums during limited ice-free windows.
- Maintenance Period:Scheduled platform turnarounds concentrate demand for replacement compressors, pumps, and power generation. NORSOK D-001 recertification timelines often align with these windows.
- Off-Peak Season:Winter weather restrictions reduce offshore activity in frontier basins.
- Mobilization Phase:Field development sanctions trigger concentrated equipment positioning.
Activity peaks in Peak Season; rental rate premiums concentrate in Maintenance Period.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for oilfield equipment rental services concentrates along Norway's western coastline, where mature North Sea fields and emerging Barents Sea developments create distinct procurement patterns across sub-regional clusters.
Stavanger Region
The Stavanger cluster anchors Norway's offshore equipment procurement authority. Equinor and Aker BP base technical teams here that compress vendor rosters to three or four integrated providers per major development. Petroleumstilsynet maintains its headquarters in this region, tightening safety enforcement that accelerates electrification-ready fleet retrofits. Time-charter contracts for jack-up rigs dominate commercial activity.
Bergen Area
Subsea installation expertise concentrates around Bergen, where tieback developments for Troll and Oseberg fields require flexible production system rentals. The EU Taxonomy's technical screening criteria shape capital flows toward lower-emission drilling assets in this cluster. Local fabrication yards face capacity constraints during peak summer drilling campaigns.
Hammerfest
Arctic-grade equipment demand from Goliat and Snøhvit expansions outpaces local fabrication capacity in this northern outpost. Barents Sea frontier operators rely on rental models to preserve balance sheet capacity for drilling commitments. Extended temperature-rated assets command availability premiums during limited ice-free windows.
Tromsø Vicinity
Exploration companies position specialized assets here for rapid mobilization to Barents Sea prospects. Shore power infrastructure gaps at nearby fields postpone diesel-to-electric rig conversions, retaining higher-emission rental fleets longer than planned. Technician scarcity drives wage inflation across the Greater North Sea basin.
Oslo-Akershus
Corporate headquarters and capital markets activity concentrate in the Oslo region, where EU Taxonomy-aligned green bond issuance opens preferential funding pools for lower-emission drilling rigs. Rental providers with documented emission reductions access cheaper capital than conventional asset owners through this financial channel.
Norway Oilfield Equipment Rental Services Market Competitive Landscape
Integrated service bundling dominates the current landscape as operators consolidate procurement authority with fewer vendors. The market structure tilts toward concentrated relationships between major exploration companies and three or four full-service providers per development. Two strategic archetypes define competitive positioning: integrated technology conglomerates offering bundled drilling and evaluation services, and specialized subsea fabricators with deep local installation expertise. Portfolio diversification into carbon capture compression and electrification-ready assets represents the primary competitive move, alongside selective capacity expansion in Arctic-rated equipment.
Among US-based energy technology conglomerates, Baker Hughes Company and Halliburton exemplify the integrated service archetype, while National Oilwell Varco occupies a position anchoring aftermarket and spare parts channels across the rental equipment lifecycle. Aker Solutions represents the specialized Nordic fabricator model, leveraging deep regional fabrication expertise to secure subsea installation contracts. These three company profiles illustrate how geographic origin and organizational structure shape competitive access to Stavanger-based procurement teams and Barents Sea frontier developments.
| Leading Market Players |
|---|
| Baker Hughes Company |
| Aker Solutions |
| Transocean Ltd |
| National Oilwell Varco |
| Halliburton |
| Seadrill Ltd |
| Weatherford International PLC |
| TechnipFMC PLC |
| Schlumberger Limited |
| Others |
Value Network & Pricing Analysis
Equinor and Aker BP's Stavanger-based technical teams concentrate procurement authority with three or four integrated providers per major development, compressing vendor rosters and shifting commercial leverage toward bundled service contracts over discrete equipment rentals.
Pricing Analysis
Volume concentrates in bareboat arrangements for operators with captive technical capabilities, while margins concentrate in time-charter and contract-drilled structures that bundle crews and maintenance obligations. Price differentiation rests on NORSOK D-001 certification grade and Arctic-grade temperature ratings for Barents Sea deployment. Cost compression in jack-up rig dayrates is intensifying because Stavanger-Bergen technician scarcity drives wage inflation into bundled crew costs. Exploration companies in frontier basins exhibit highest price sensitivity; integrated operators with electrification mandates show lowest sensitivity to secure electrification-ready assets.
Supply Chain Analysis
Single-source vulnerability sits with Norwegian fabrication yards in Stavanger and Bergen for subsea production systems, with secondary concentration in German and Dutch component suppliers for pressure control equipment. Raw material dependencies draw from nickel and molybdenum feedstocks for duplex stainless formulations, plus specialized electronics for SCADA integration. Tariff exposure on steel alloy inputs compresses margins when quoting long-term rental contracts. Distribution runs through Stavanger-based procurement hubs that coordinate equipment positioning across the Norwegian Continental Shelf.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Norway oilfield equipment rental services market is becoming a vertical-integration race, with players pursuing upstream control over Arctic-grade fabrication capacity to secure preferential access to Barents Sea frontier developments.
For Market Incumbents: Anticipate EU Taxonomy enforcement accelerating fleet electrification timelines by 18-24 months, compressing returns from conventional diesel assets. Secure backward integration into Hammerfest-area fabrication capacity before Arctic-grade equipment demand outpaces supply. Defend vendor roster positions through integrated service bundling that reduces interface risk for Stavanger-based technical teams. For New Entrants and Emerging Players: Digital twin platforms for legacy SCADA integration offer a technology-first wedge into stalled electrification projects at Johan Sverdrup and Snorre fields. Target Hammerfest's underdeveloped fabrication capacity relative to Goliat and Snøhvit expansion demand. Pursue carbon capture compression skid rentals as the go-to-market angle, anchored by Equinor's Northern Lights project procurement cycles. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized subsea fabricators with NORSOK-certified installation capabilities in the Bergen cluster. Long-term viability over a 5-10 year window hinges on electrification-ready fleet exposure and documented emission reductions for green bond eligibility. Watch Petroleumstilsynet safety enforcement intensity as the inflection signal for accelerated recertification spending and fleet renewal cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Arctic-Grade Fabrication Capacity Expansion | Hammerfest yard development captures Barents Sea frontier demand from Goliat and Snøhvit operators. |
| Electrification-Ready Fleet Retrofit Program | EU Taxonomy alignment opens preferential green bond funding pools for documented emission reductions. |
| Integrated Service Contract Consolidation | Bundled drilling and subsea offerings concentrate procurement authority with Stavanger-based technical teams. |
| Carbon Capture Compression Skid Rental Fleet | Modular CO2 handling assets anchor early adoption from Equinor's Northern Lights project. |
| NORSOK D-001 Recertification Acceleration | Third-party validation partnerships reduce 6-12 month certification delays idling revenue-generating units. |
Research Methodology
Multi-period observation of rig utilization rates, electrification project timelines, and Petroleumstilsynet enforcement patterns anchored the trend analysis, supplemented by interviews with drilling contractors, subsea installation engineers, Stavanger-based procurement managers, and carbon capture project developers. Secondary validation drew from NORSOK technical standards documentation, EU Taxonomy technical screening criteria, Norwegian petroleum tax framework filings, and offshore project sanction databases. Bottom-up equipment deployment estimates triangulated against top-down operator capital expenditure disclosures.
Segment-weighting across equipment type, client archetype, contract structure, and seasonal demand windows informed the analytical framework over the projection horizon. CAGRs were derived from equipment replacement cycle analysis and electrification mandate acceleration curves. Modeled inputs included Petroleumstilsynet recertification timeline distributions, shore power infrastructure deployment schedules, and Barents Sea ice-free window constraints on Arctic-grade asset utilization.
Several conditions sit outside the modeled scope, including unannounced field development sanctions, abrupt shifts in Norwegian petroleum tax uplift allowances, and geopolitical disruptions to nickel and molybdenum supply corridors. Forecasts reflect documented assumptions about electrification technology cost curves and regulatory enforcement continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
US Oil and Gas Analytics Market
Oil & Gas
Uzbekistan Oil and Gas Market
Oil & Gas
Spacer Fluid Market
Oil & Gas
Middle-East and Africa Frac Stack Market
Oil & Gas
Oilfield Chemicals Market
Oil & Gas
Singapore LNG Storage Tank Market
Oil & Gas
Global Well Logging Equipment Market
Oil & Gas
Indonesia Oilfield Equipment Rental Services Market
Oil & Gas
Geothermal Drill Bits Market
Oil & Gas
Flow Computer Oil Gas Market
Oil & Gas
Asia-Pacific Liner Hanger System Market
Oil & Gas
Expandable Liner Hanger System Market
Oil & Gas
Offshore Drilling Fluid Market
Oil & Gas
Oil and Gas Engineering Services Market
Oil & Gas
Saudi Arabia Oil and Gas Midstream Market
Oil & Gas
Downhole Drilling Tools Market