
 Oil and Gas EPC Market | 2026-2036
Oil and Gas EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas EPC Market Intelligence
The consolidation of project awards by National Oil Companies into larger, more complex contracts is repositioning the competitive landscape for EPC contractors. TechnipFMC specializes in integrated subsea and offshore project delivery, from concept to commissioning. Bechtel Corporation leverages its immense scale for executing mega-projects in challenging environments like Kazakhstan and Australia. Meanwhile, Larsen & Toubro dominates its domestic market in India and expands its footprint across the Middle East.
Oil and Gas Engineering, Procurement, and Construction (EPC) is a project delivery model where one entity assumes responsibility for the entire lifecycle from design to commissioning. This process involves complex project management and detailed engineering using specialized software to deliver large-scale energy infrastructure. Lump Sum Turnkey (LSTK) contracts are prevalent, offering clients cost certainty on major capital projects. Front End Engineering Design (FEED) services represent a high-value, critical precursor to full EPC awards, with National Oil Companies constituting the primary client segment for these large-scale undertakings.
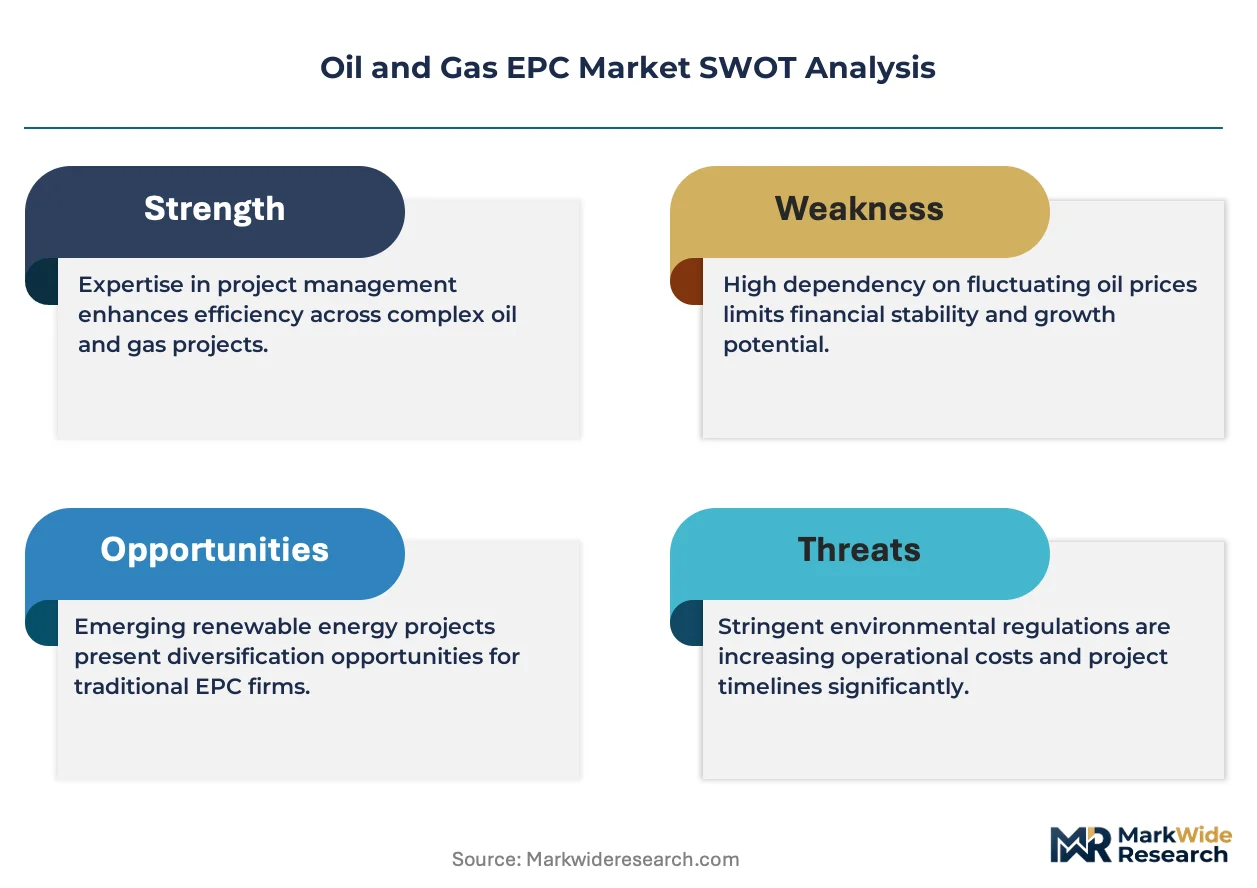
Regulatory frameworks, including the US EPA's methane rules and the EU's Corporate Sustainability Reporting Directive (CSRD), impose stringent environmental performance standards on new projects. These mandates, alongside China's 'dual carbon' goals overseen by the MEE, require EPC firms to incorporate advanced emissions control and monitoring technologies. Consequently, contractors face a strategic choice between optimizing for conventional hydrocarbon projects and investing in capabilities for emerging energy transition infrastructure.
Market Dynamics
The central tension between maximizing returns from conventional hydrocarbon assets and investing in capabilities for the energy transition is the primary structural force shaping the Oil and Gas EPC market, dictating strategic resource allocation and technology development priorities.
Growth Catalysts
- Energy Transition Mandates:Policy frameworks like the EU Green Deal and national net-zero targets are creating demand for EPC services in new infrastructure, particularly for carbon capture, utilization, and storage (CCUS) and green hydrogen production facilities.
- Petrochemical Integration:Sustained capital expenditure by petrochemical producers on building integrated refinery and chemical complexes, especially in Asia and the Middle East, provides a consistent pipeline of large-scale projects for EPC contractors.
- Upstream Project Sanctioning:National Oil Companies, particularly in Saudi Arabia and the UAE, are moving forward with significant investments in large-scale upstream and midstream projects to increase production capacity, awarding substantial contracts to qualified firms.
Market Restraints
- Lump Sum Contract Risk:The prevalence of Lump Sum Turnkey (LSTK) contracts transfers significant financial risk for cost overruns and project delays to EPC contractors, compressing margins especially in an environment of volatile material and labor costs.
- Regulatory Compliance Burden:Navigating disparate and stringent environmental regulations, such as the US EPA's methane rules and China's MEE-enforced 'dual carbon' policies, increases project complexity, cost, and lead times for EPC firms operating globally.
- Skilled Labor Scarcity:A persistent shortage of experienced engineers, project managers, and skilled craft labor capable of executing complex mega-projects creates bottlenecks and drives up wage costs, constraining the industry's capacity to deliver multiple large projects simultaneously.
Strategic Opportunities
- Digital Twin Services:Developing and offering digital twin and asset management services provides a high-margin, recurring revenue opportunity that extends beyond project commissioning, embedding EPC firms deeper into the operational lifecycle of client assets.
- Decarbonization Retrofits:A significant opportunity exists in retrofitting existing industrial facilities, such as refineries and power plants, with carbon capture technology, driven by incentives like the 45Q tax credit under the US Inflation Reduction Act.
- FEED Service Expansion:Expanding Front End Engineering Design (FEED) consultancy services into emerging LNG markets in regions like Southeast Asia and Africa allows EPC firms to secure early-stage involvement and influence on future large-scale project awards.
Industry Challenges
- Project Management Complexity:The increasing scale and technological integration of mega-projects, which often combine upstream, midstream, and downstream components, test the limits of project management systems and expose contractors to significant execution risk.
- Dual Supply Chain Management:EPC firms face the challenge of managing two distinct supply chains: a mature one for conventional oil and gas projects and a nascent, often unproven one for new energy technologies like hydrogen electrolyzers.
- Talent Development Gap:An aging workforce and a deficit of engineers trained in both traditional hydrocarbon processes and emerging energy systems like CCUS or advanced biofuels creates a critical skills gap that threatens project execution quality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas EPC Market |
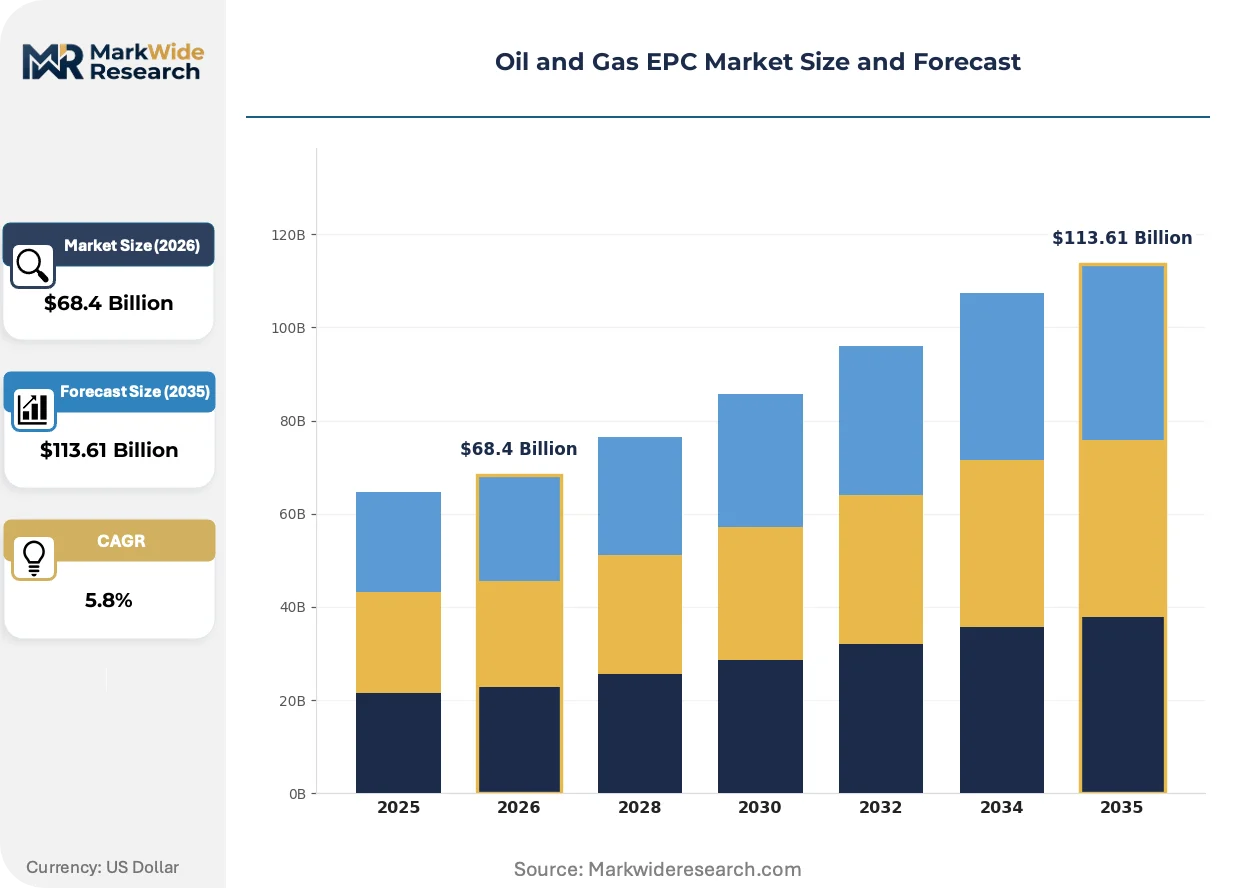
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Contract Type: Engineering Procurement Construction, Design & Build, Lump Sum Turnkey, Cost Plus, Time & Material Project Phase: Front End Engineering Design, Detailed Engineering, Procurement, Construction, Commissioning Service Type: Engineering Services, Procurement Services, Construction Services, Project Management, Quality Assurance Client Type: National Oil Companies, Independent Refiners, Exploration Firms, Petrochemical Manufacturers, Pipeline Operators |
| Companies Covered | TechnipFMC, Saipem, Bechtel Corporation, Worley, John Wood Group, Fluor Corporation, McDermott International, Larsen & Toubro, KBR Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas EPC Market Strategic Shifts & Innovations
The dual mandate to optimize fossil fuel asset delivery while building competencies for low-carbon infrastructure is driving innovation. Digitalization enhances efficiency in conventional projects, while new engineering solutions are being developed to meet decarbonization goals set by regulators and clients.
Modular construction and pre-fabrication involve shifting large portions of the construction process from the final project site to controlled factory environments. EPC contractors executing complex offshore platform and LNG train projects are the primary adopters of this model. This approach is decentralizing the physical build process, reducing on-site labor requirements and mitigating schedule risks in challenging or remote locations like offshore Australia.
European Union regulations, specifically the Corporate Sustainability Reporting Directive (CSRD), mandate detailed disclosure on environmental impacts. This forces EPC firms to provide clients with verifiable data on the lifecycle carbon footprint of newly constructed energy assets. Contractors bidding on European projects or serving EU-based clients are most affected, requiring new capabilities in emissions tracking and integrated sustainability reporting.
National Oil Companies are altering their contracting strategy by bundling multiple project scopes into single, integrated EPCI (Engineering, Procurement, Construction, and Installation) awards. This model favors large, full-service contractors with extensive balance sheets, displacing smaller, specialized engineering firms from prime contractor roles. This trend is most prominent in the Middle East, where NOCs in Saudi Arabia and the UAE use it for major offshore and onshore field development programs.
Oil and Gas EPC Market Segmentation
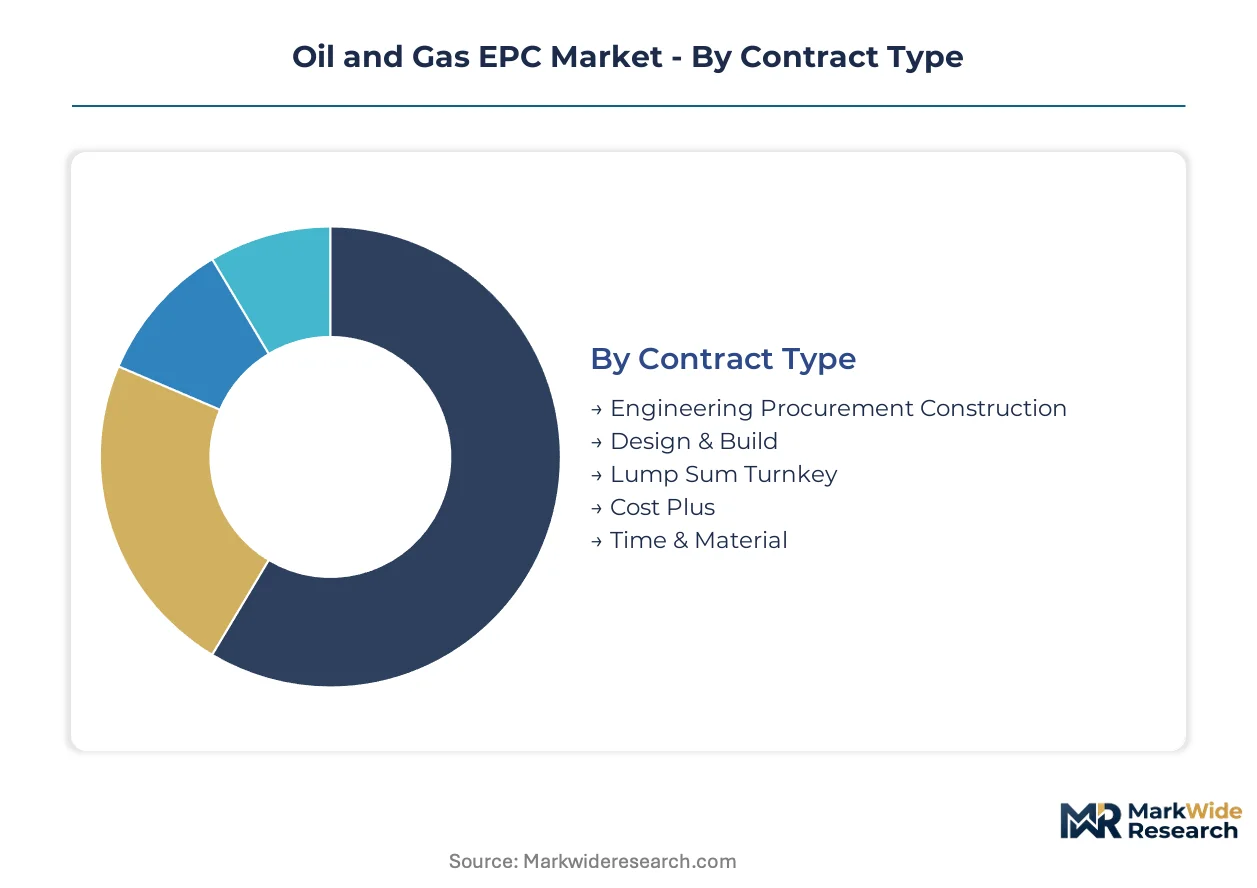
The Oil and Gas EPC market segments reflect the diverse project delivery models, specialized phases, and client requirements inherent in large-scale energy infrastructure development. Understanding these distinctions helps stakeholders identify specific areas of investment and operational focus within the industry.
Contract Type:
Client risk appetite and project certainty requirements differentiate the selection of contract types in the Oil and Gas EPC market.
- Lump Sum Turnkey (LSTK):This contract model places full responsibility for design, procurement, and construction on the EPC contractor for a fixed price. Demand concentrates in major capital projects for National Oil Companies seeking cost certainty on large-scale developments.
- Engineering Procurement Construction (EPC):This integrated delivery model covers design, equipment sourcing, and construction activities under a single contract. Project awards for integrated refinery and chemical plants, particularly in Asia, frequently utilize this comprehensive approach.
- Design & Build:This contract combines design and construction responsibilities under one entity, simplifying project coordination for clients.
- Cost Plus:This arrangement reimburses the contractor for actual costs incurred plus an agreed-upon fee, often used for projects with uncertain scopes.
- Time & Material:This contract type pays for labor at specified rates and for materials at cost, suitable for smaller, less complex projects or maintenance work.
Volume sits with Lump Sum Turnkey contracts; growth tilts toward integrated Engineering Procurement Construction models.
Project Phase:
Project complexity dictates the sequential engagement across these distinct project phases, each requiring specialized expertise.
- Front End Engineering Design (FEED):This critical early phase defines project scope, technical requirements, and cost estimates before full EPC awards. National Oil Companies frequently engage specialized firms for FEED services to de-risk major upstream and midstream developments.
- Construction:This phase involves the physical assembly and erection of facilities, including civil, mechanical, and electrical works on site. Large-scale infrastructure projects, such as LNG terminals in Australia, drive significant demand for specialized construction services.
- Detailed Engineering:This phase translates FEED outputs into comprehensive design packages, including all technical drawings and specifications for procurement and construction.
- Procurement:This involves sourcing and purchasing all necessary equipment, materials, and services, ensuring compliance with project specifications and schedules.
- Commissioning:This final phase validates system functionality and performance, ensuring the facility operates safely and efficiently before handover to the client.
Project execution success hinges on robust delivery in the Construction phase, while Front End Engineering Design secures future work.
Service Type:
Specialized expertise drives demand across distinct service offerings, supporting the entire project lifecycle from concept to operation.
- Engineering Services:This encompasses conceptual design, detailed engineering, and technical studies for complex energy infrastructure. Demand concentrates on advanced solutions for carbon capture, utilization, and storage (CCUS) projects, particularly in the EU.
- Construction Services:This involves on-site execution, including civil works, mechanical erection, and electrical installation. Mega-projects in Saudi Arabia and the UAE require extensive construction capabilities, often leveraging modularization techniques.
- Procurement Services:These services manage the global supply chain for materials and equipment, optimizing cost and delivery schedules for large-scale projects.
- Project Management:This service oversees all project aspects, ensuring timely delivery, budget adherence, and quality control through complex logistical coordination.
- Quality Assurance:This ensures all project deliverables meet specified standards and regulatory requirements, particularly critical for safety-sensitive oil and gas operations.
Core project delivery relies on Engineering Services and Construction Services, with specialized support enhancing overall project integrity.
Client Type:
The specific operational focus and investment strategies of each client group shape their distinct EPC requirements.
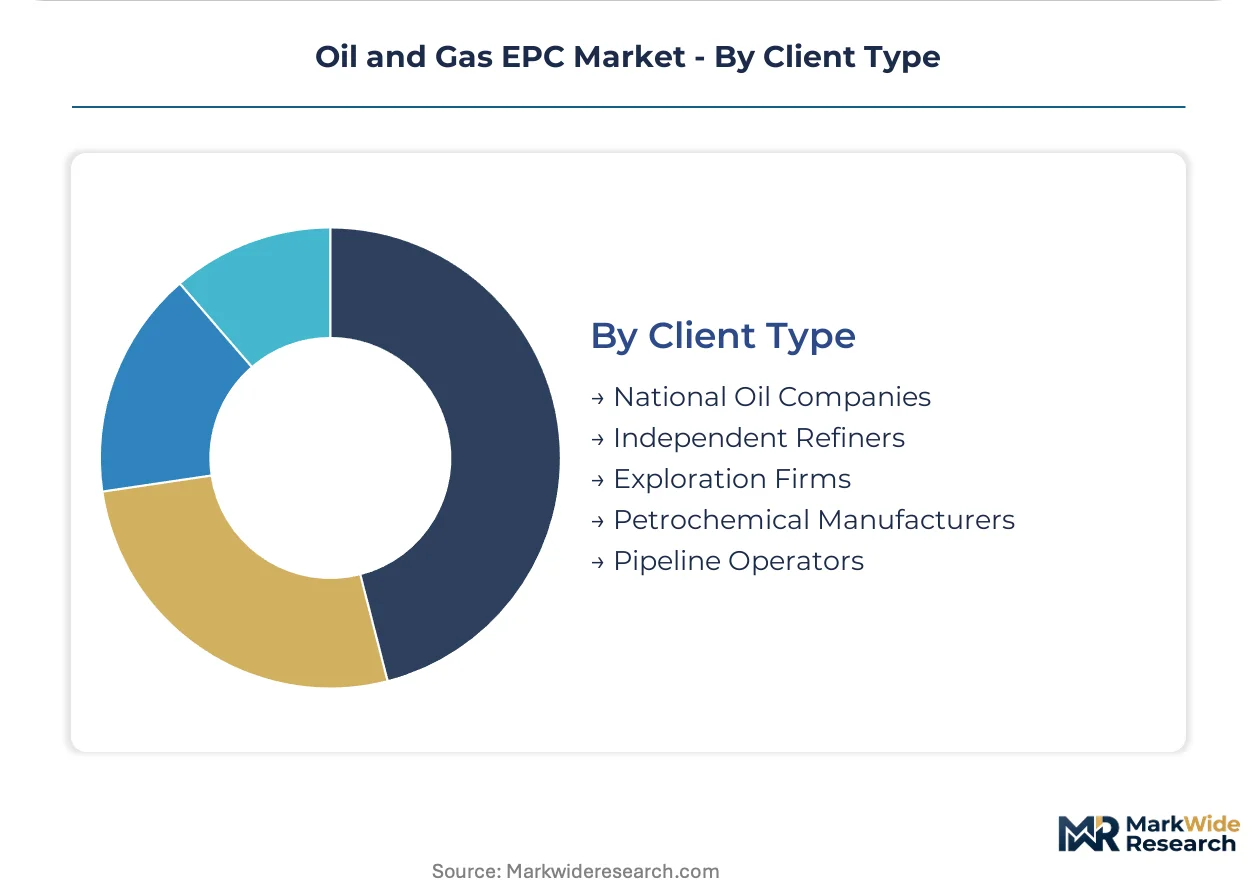
- National Oil Companies:These state-owned entities are primary clients, driving large-scale upstream and midstream investments to expand national production capacity. Saudi Aramco and ADNOC in the UAE represent significant sources of major project awards.
- Petrochemical Manufacturers:These clients invest heavily in integrated refinery and chemical complexes, particularly in Asia and the Middle East, to diversify product portfolios. Their capital expenditure creates a consistent pipeline for complex EPC projects.
- Independent Refiners:These private companies require EPC services for refinery upgrades, capacity expansions, and compliance-driven modernizations.
- Exploration Firms:These companies engage EPC contractors for early-stage field development, including subsea infrastructure and offshore platform construction.
- Pipeline Operators:These clients commission EPC firms for new pipeline construction, compressor station upgrades, and integrity management projects for crude oil and natural gas transportation.
Market activity is primarily driven by National Oil Companies, with Petrochemical Manufacturers expanding their project footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for Oil and Gas EPC services is evident in regions with substantial hydrocarbon reserves and aggressive expansion plans for energy infrastructure. National Oil Companies in the Middle East and major economies in Asia drive significant project awards. Regulatory shifts towards energy transition also create new infrastructure requirements across developed markets.
United States
Sustained investments in LNG export terminals and petrochemical facilities drive EPC demand in the United States. The US EPA's methane rules impose stringent emissions control requirements on new and existing oil and gas infrastructure. The Gulf Coast, particularly around Houston and Louisiana, remains a hub for large-scale refinery expansions and chemical plant projects.
Saudi Arabia
Saudi Aramco's substantial capital expenditure on upstream and midstream developments anchors significant EPC project awards in Saudi Arabia. The Kingdom's Vision 2030 initiatives emphasize diversification, leading to integrated refinery-to-chemicals complexes. The Eastern Province concentrates major oil and gas field development and processing facilities.
United Arab Emirates
ADNOC's strategic investments in increasing oil production capacity and gas processing capabilities fuel EPC market activity in the United Arab Emirates. The UAE's net-zero by 2050 strategic initiative encourages CCUS project development. Abu Dhabi serves as the primary center for large-scale energy projects, including offshore and onshore field expansions.
China
China's 'dual carbon' goals overseen by the MEE are creating demand for advanced emissions control and green hydrogen production facilities within its vast energy sector. Petrochemical manufacturers continue to invest in integrated refinery and chemical complexes to meet domestic demand. The Yangtze River Delta region is a key area for new chemical and energy infrastructure projects.
India
India's energy security objectives and growing industrial base drive continuous demand for refinery upgrades and new petrochemical plant construction. The country's national energy policies encourage domestic manufacturing and infrastructure development. Western India, particularly Gujarat and Maharashtra, leads in new refinery and petrochemical investments.
Oil and Gas EPC Market Key Industry Players
European producers anchor one tier, specializing in complex subsea and offshore technologies, while Asian specialists hold a strong position in large-scale onshore integrated projects. The market structure exhibits a tiered consolidation, with a few mega-contractors dominating the most complex projects. Archetypes include global mega-EPC firms, specialized subsea integrators, and regional powerhouses. Geographic expansion and portfolio diversification into new energy infrastructure are dominant competitive moves.
At the scale-driven end, Bechtel Corporation leverages its immense scale for executing mega-projects in challenging environments. TechnipFMC represents a specialized subsea integrator, delivering integrated subsea and offshore project delivery from concept to commissioning. Larsen & Toubro occupies a strong position as a regional powerhouse, dominating its domestic market in India and expanding its footprint across the Middle East for large-scale integrated projects.
| Leading Market Players |
|---|
| TechnipFMC |
| Saipem |
| Bechtel Corporation |
| Worley |
| John Wood Group |
| Fluor Corporation |
| McDermott International |
| Larsen & Toubro |
| KBR Inc. |
| Others |
Cost & Logistics Intelligence
Sovereign-backed National Oil Companies, as primary clients, dictate project specifications and contract terms, profoundly influencing both EPC supply behavior and pricing discipline across the market. Their large-scale, complex project awards often favor established contractors with extensive balance sheets.
Pricing Analysis
Volume-driven Lump Sum Turnkey (LSTK) contracts offer cost certainty to clients but compress EPC contractor margins. The dominant pricing model is project-based for major capital projects. Price differentiation stems from specialized engineering capabilities for complex infrastructure and geographic delivery costs in remote regions. Pricing pressure stems from the transfer of significant cost overrun risk to contractors, especially with volatile material and labor costs. National Oil Companies are least price-sensitive, while smaller independent refiners exhibit higher sensitivity for upgrades.
Supply Chain Analysis
Domestic-content mandates in Saudi Arabia and the UAE reshape sourcing strategies for major project components. Geographic supply concentrates in East Asia for specialized equipment and Europe for advanced engineering software. The EPC market relies on critical inputs like high-grade steel alloys, advanced control systems, and specialized piping. Supply chain risk stems from single-source vulnerability for highly specialized components, with project delivery often following a direct-to-site model.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Oil and Gas EPC market is a vertical-integration race, with contractors pursuing expanded Front End Engineering Design (FEED) services to secure early project influence. This strategic move aims to capture higher-value design work and de-risk subsequent full EPC awards.
For Market Incumbents: Hedge against the energy transition threat by investing in advanced capabilities for carbon capture, utilization, and storage (CCUS) projects. Consolidate market position through strategic acquisitions of specialized engineering firms focused on green hydrogen infrastructure. Diversify service portfolios beyond conventional hydrocarbons to mitigate long-term demand shifts and leverage existing mega-project execution expertise.
For New Entrants and Emerging Players: Specialized technology providers can partner with established EPC contractors to offer niche solutions for decarbonization retrofits in existing facilities. Target underpenetrated emerging LNG markets in Southeast Asia for FEED consultancy services. The most penetrable segment lies within smaller, compliance-driven projects requiring advanced emissions control technologies. Go-to-market via technology licensing agreements with regional engineering firms.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-sized engineering firms in Europe specializing in CCUS technology. The market retains long-term viability over a 5-10 year window, driven by sustained energy demand and transition infrastructure buildout. Target acquisition archetypes include firms with strong intellectual property in emissions control and modular construction capabilities. A signal to watch is the acceleration of national funding for green hydrogen projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Front End Engineering Design (FEED) Services | Securing early project involvement influences full EPC awards from National Oil Companies. |
| Invest in Carbon Capture, Utilization, and Storage (CCUS) Capabilities | Meeting EU Green Deal mandates creates new demand for specialized engineering solutions. |
| Develop Digital Twin and Asset Management Offerings | Recurring revenue from operational lifecycle services enhances client engagement beyond commissioning. |
| Adopt Modular Construction Techniques | Mitigating schedule risks in remote locations improves project delivery for offshore platforms. |
| Target Emerging LNG Markets in Southeast Asia | New project sanctioning provides growth opportunities for EPC firms in a developing region. |
Research Approach
Independent corroboration across industry reports, regulatory filings, and trade association data underwrites the qualitative findings and quantitative projections. Primary interviews with EPC project managers, National Oil Company procurement leads, and petrochemical R&D directors informed key market dynamics. Secondary validation analyzed company annual reports, IEA energy outlooks, and US EPA methane rule documentation, utilizing both bottom-up and top-down triangulation for data accuracy.
Anchored to comparable historical reference periods, the forecast established a robust baseline for future projections across the analysis window. Segmentation dimensions modeled included contract type, project phase, service type, and client type, alongside energy transition infrastructure. Compound Annual Growth Rates (CAGRs) were derived from multi-factor regression analysis integrating capital expenditure trends and global energy demand forecasts.
Caveats apply where geopolitical instability, fluctuating commodity prices, or accelerated energy transition policies could materially shift the outlook. Forecasts reflect assumptions on capital expenditure by National Oil Companies and petrochemical manufacturers. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Drilling Fluids Market
Oil & Gas
Algeria Oil and Gas Upstream Market
Oil & Gas
Europe Well Intervention Market
Oil & Gas
Deepwater Hydrocarbons Exploration Market
Oil & Gas
Middle East and North Africa Oilfield Services Market
Oil & Gas
South America Intelligent Pigging Market
Oil & Gas
Oman Directional Drilling Market
Oil & Gas
Floating Liquefied Natural Gas (FLNG) Terminals Market
Oil & Gas
Republic of Congo Oil and Gas Market
Oil & Gas
Russian Federation Oil and Gas Market
Oil & Gas
Asia-Pacific Underground Coal Gasification Market
Oil & Gas
Nigeria Wireline Logging Services Market
Oil & Gas
Asia-Pacific AI in Oil and Gas Market
Oil & Gas
Oil Field Drill Bits Market
Oil & Gas
Flare Gas Recovery System Market
Oil & Gas
North America Oil and Gas Electric Submersible Pump Market