
 Italy Oil and Gas Market | 2026-2036
Italy Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Oil and Gas Market Outlook
Market Overview
Italy's Adriatic offshore capacity build-out is narrowing the gap between declining onshore production and sustained domestic demand. Eni SpA leverages its integrated upstream-downstream position to control supply from the Val d'Agri and Basilicata fields. Edison SpA anchors the midstream gas segment through its extensive pipeline network and LNG terminal access. Saipem SpA competes internationally in offshore engineering while sustaining its domestic fabrication yards at Porto Marghera and Trieste.
Technical and Structural Dynamics
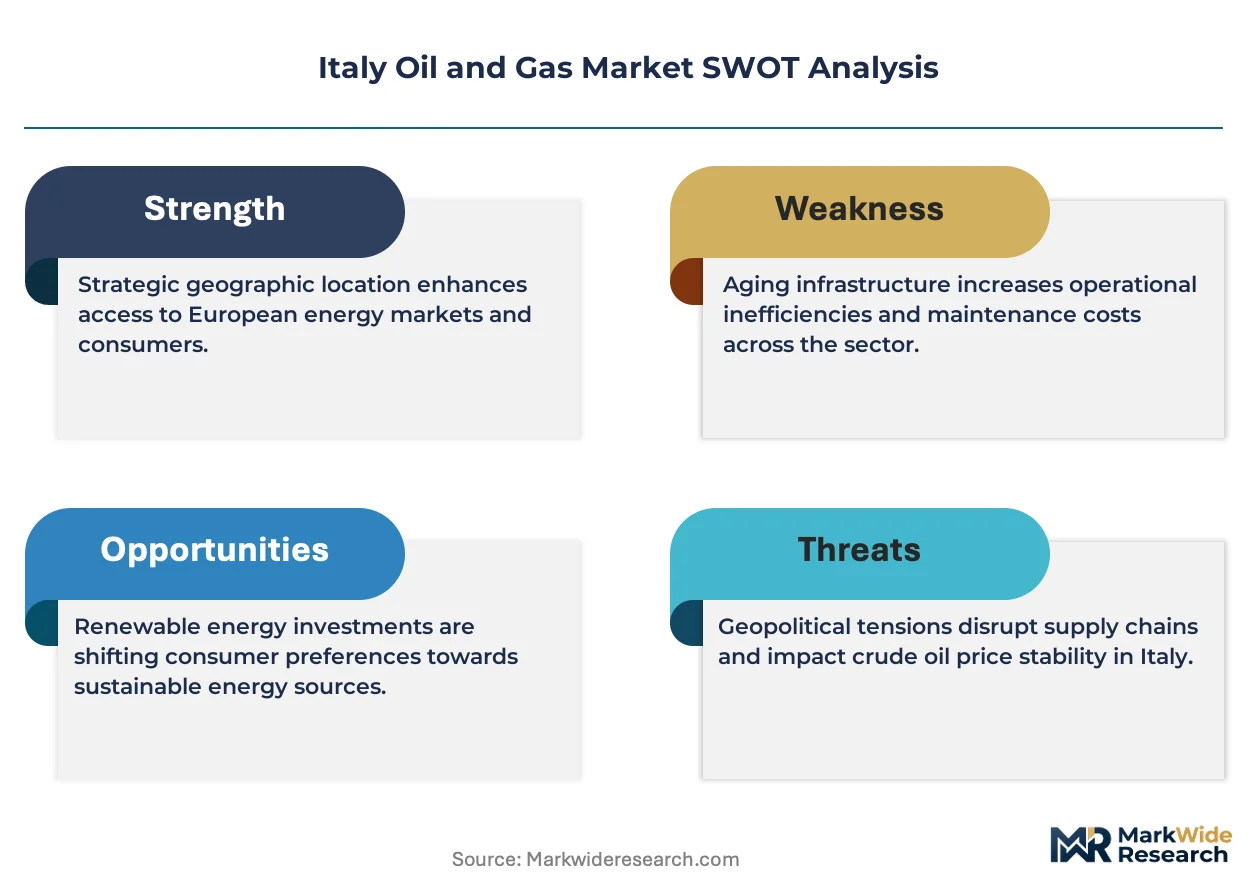
Italy oil and gas encompasses the exploration, extraction, refining, and distribution of hydrocarbons including crude oil with API gravities ranging from 33 to 45 degrees and natural gas with methane content typically exceeding 85 percent, serving power generation, industrial feedstock, and residential heating applications. The refining segment remains structurally mature with margin pools concentrated in complex conversion capacity at sites like Sannazzaro and Milazzo. Enhanced Oil Recovery technology is expanding fastest among technology categories as operators target stranded reserves in depleted Po Valley formations. Well services within the service type dimension command premium pricing due to specialized coiled tubing and hydraulic workover requirements in Italy's geologically fractured basins.
Regulatory Environment and Outlook
Italy's Ministry of Environment and Energy Security enforces licensing rounds under the National Mining Code while EU Green Deal targets and the F-Gas Regulation constrain new exploration approvals and mandate methane emissions monitoring. The country's national energy regulator ARERA shapes gas distribution tariffs and infrastructure access rules that determine midstream investment returns. Stakeholders must monitor whether Rome accelerates offshore drilling moratoriums or relaxes permitting for strategic gas discoveries in the Southern Adriatic.
Market Dynamics
Italy's oil and gas sector is compressing around stranded asset economics as the EU Green Deal tightens emissions ceilings and mature basin depletion accelerates. Operators now face simultaneous pressure to maximize recovery from depleted Po Valley formations while funding carbon capture retrofits at existing infrastructure.
Growth Catalysts
- Enhanced Oil Recovery:Operators deploy polymer flooding and CO2 injection in the Po Valley's depleted sandstone reservoirs. These techniques extend field life without new exploration permits.
- Power sector gas demand:Grid operators favor combined-cycle gas turbines as coal retirement accelerates under Italy's National Integrated Energy and Climate Plan. Baseload capacity requirements sustain offtake volumes.
- Adriatic offshore infrastructure:Existing pipeline networks and processing platforms at Ravenna and Bari reduce development costs for marginal discoveries. Brownfield tiebacks dominate new project economics.
Market Restraints
- F-Gas Regulation methane monitoring:The EU mandate for continuous emissions surveillance at production facilities imposes capital burdens on marginal field operators. Compliance costs erode returns on sub-scale assets.
- Basilicata supply concentration:Eni SpA controls the Val d'Agri processing center and associated pipeline corridors. Third-party access negotiations create bottlenecks for independent producers.
- Geological fracturing complexity:Italy's Apennine thrust belt formations require specialized coiled tubing and hydraulic workover capabilities. Service scarcity inflates well intervention pricing.
Strategic Opportunities
- Southern Adriatic deepwater:Untested carbonate plays off Puglia and Calabria offer material volume potential. Licensing round design under the National Mining Code may relax fiscal terms for strategic gas discoveries.
- Carbon capture integration:Depleted gas fields in the Po Valley provide proven storage geology. The EU Innovation Fund and Italy's transition mechanism subsidize pilot injection projects at operational sites.
- LNG terminal optimization:Panigaglia and offshore regasification assets can pivot from import dependency to hydrogen blending and bio-LNG handling. ARERA tariff frameworks are adapting to multi-product infrastructure.
Industry Challenges
- Subsurface characterization expertise:Italy's universities produce limited petroleum geoscience graduates. Operators compete for finite talent pools experienced in fractured carbonate and thrust belt interpretation.
- Permitting timeline compression:Environmental impact assessments under the Ministry of Environment and Energy Security now average 48 months. Project sanctioning delays erode commodity price assumptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Oil and Gas Market |
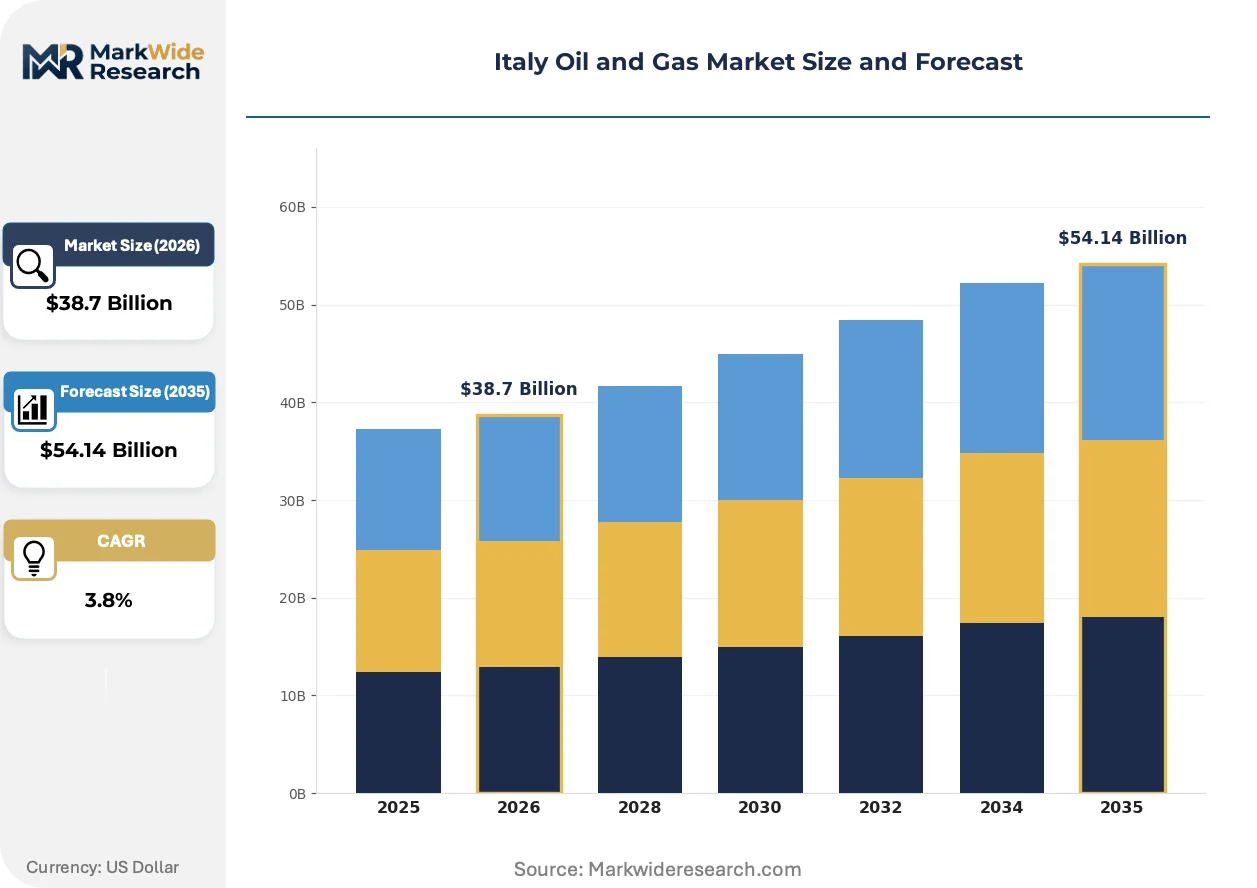
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $54.14 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Exploration, Production, Refining, Distribution Service Type: Well Services, Engineering, Construction, Supply Chain Management Technology: Seismic, Reservoir Simulation, Drilling Automation, Enhanced Oil Recovery End User: Utilities, Industrial, Transportation, Commercial |
| Companies Covered | Eni SpA, Edison SpA, Saipem SpA, Shell PLC, TotalEnergies SE, BP PLC, Engie SA, Schlumberger NV, Zenith Energy Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Oil and Gas Market Strategic Shifts
Digital reservoir characterization and emissions monitoring technologies are redefining operational economics in Italy's mature basins. These tools enable precision targeting of bypassed pay zones while satisfying tightening regulatory disclosure requirements.
Electrification of offshore platforms is hybridizing power systems across the Adriatic. Eni SpA and independent operators install subsea cable connections and battery storage to replace gas turbine generators. The Adriatic offshore segment adopts this configuration fastest due to proximity to coastal grid infrastructure. Platform electrification is hybridizing operational cost structures while enabling real-time emissions verification.
Italy's implementation of the EU Methane Regulation mandates quarterly LDAR surveys and satellite emissions verification for production facilities above threshold scale. The Ministry of Environment and Energy Security enforces penalties for uncertified venting events. Midstream gathering and processing operators face the steepest compliance burdens as they retrofit legacy compressor stations with sealed systems and continuous monitoring instrumentation.
Industrial offtake contracts are compressing price review cycles from annual to quarterly benchmarks. Petrochemical buyers at Ravenna and Porto Torres now index term supply to TTF front-month settlements rather than oil-linked formulas. This behavioral shift transfers volatility risk upstream while rewarding suppliers with integrated trading capabilities. The power generation segment exhibits this pattern most acutely as utility procurement functions centralize commodity exposure management.
Italy Oil and Gas Market Segmentation
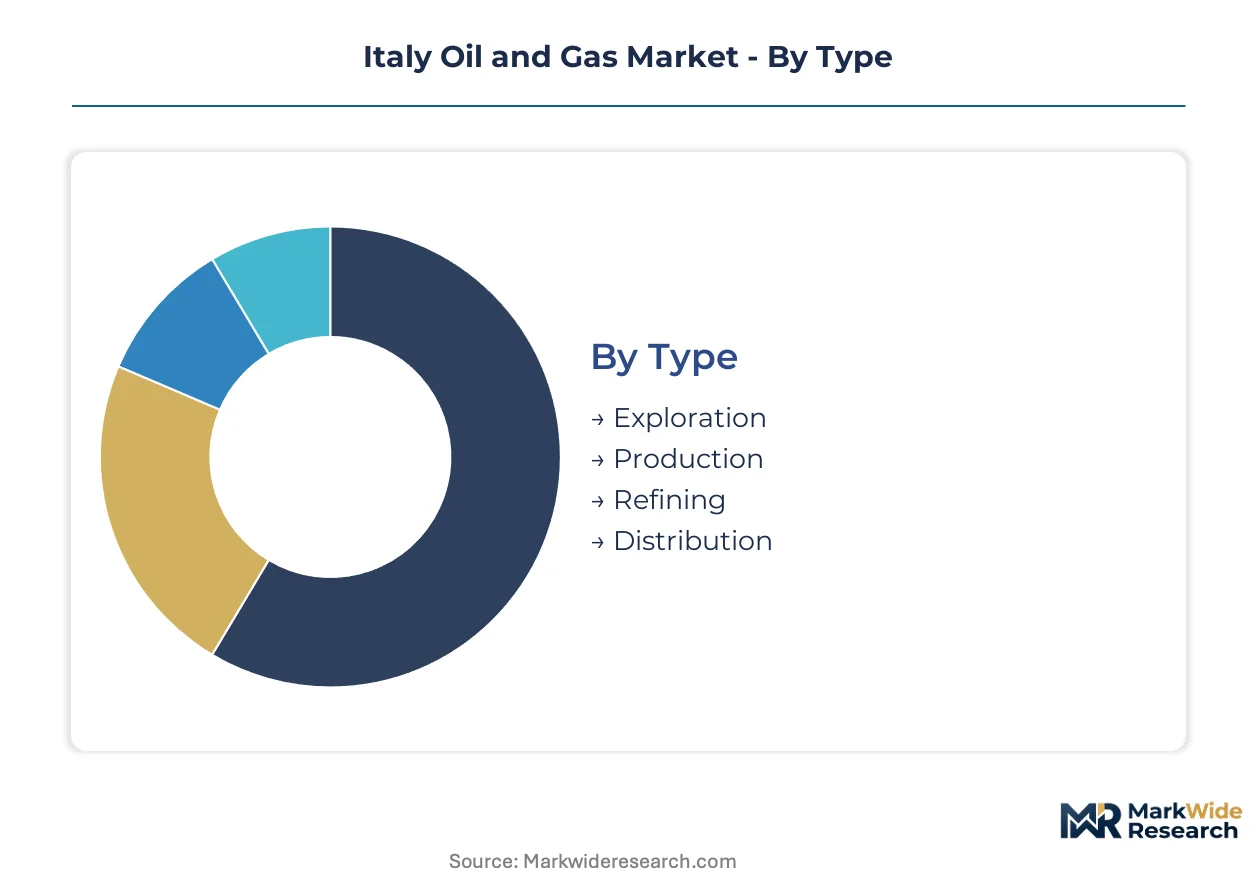
Italy's mature basin economics and regulatory constraints create divergent investment profiles across the value chain. Segmentation reveals where capital concentrates under emissions ceilings and where stranded asset risks reshape operational priorities.
Type:
Application across the hydrocarbon value chain determines capital intensity and regulatory exposure for Italian operators.
- Exploration:Seismic surveying and wildcat drilling target untested carbonate plays in the Southern Adriatic and deeper Po Valley structures. Licensing rounds under the National Mining Code face tightening environmental scrutiny, compressing permit timelines and elevating upfront risk capital requirements.
- Production:Extraction operations span Eni SpA's Val d'Agri processing complex, Edison SpA's Adriatic offshore platforms, and independent operators in depleted Po Valley fields. Brownfield optimization dominates investment as greenfield approvals stagnate under EU Green Deal targets.
- Refining:Complex conversion capacity at Sannazzaro and Milazzo facilities processes medium-sour crudes into transport fuels and petrochemical feedstock. Margin pools concentrate in hydrocracking and coking units as simple distillation economics erode.
- Distribution:Pipeline networks, storage terminals, and retail fuel stations deliver products to industrial clusters and residential consumers. ARERA tariff frameworks shape returns on gas distribution infrastructure while electrification pressures liquid fuel throughput.
Production commands the established base. The steepest expansion runs through distribution infrastructure repurposing for hydrogen and biofuel blending.
Service Type:
Margin capture in Italy's service market depends on technical specialization and asset specificity to fractured geology.
- Well Services:Coiled tubing interventions, hydraulic workovers, and wellbore maintenance address formation complexity in the Apennine thrust belt. Demand concentrates at Val d'Agri and Basilicata fields where Eni SpA and independent producers face escalating intervention frequency on aging wells.
- Engineering:Front-end design and project management for offshore platforms, processing facilities, and carbon capture retrofits. Saipem SpA anchors domestic capability through Porto Marghera and Trieste fabrication yards serving Adriatic developments.
- Construction:Field execution of pipelines, platforms, and onshore processing plants. Activity localizes around Ravenna's offshore supply base and Brindisi's deepwater logistics corridor.
- Supply Chain Management:Procurement coordination, inventory optimization, and logistics for remote operational sites. Digital tracking systems gain traction as operators reduce working capital buffers under margin pressure.
Well services anchor revenue stability. Engineering climbs fastest as electrification and carbon capture retrofits multiply project complexity.
Technology:
Technology deployment in Italian fields prioritizes reserve recovery over exploration risk given permitting constraints.
- Seismic:3D and 4D subsurface imaging for reservoir characterization in structurally complex carbonate and thrust belt formations. Acquisition focuses on Po Valley brownfield extensions rather than frontier exploration.
- Reservoir Simulation:Numerical modeling of fluid flow through fractured and heterogeneous formations. Operators deploy these tools to identify bypassed pay zones in mature Adriatic gas fields.
- Drilling Automation:Real-time data analytics and automated rig controls for directional drilling in deviated well profiles. Adoption accelerates offshore where day rates justify capital intensity.
- Enhanced Oil Recovery:Polymer flooding, CO2 injection, and gas cycling in depleted Po Valley sandstone reservoirs. This category expands most quickly as operators extend field life without new exploration permits under the EU Green Deal.
Seismic retains the installed base. Enhanced Oil Recovery gains share fastest as stranded reserve economics dominate capital allocation.
End User:
Customer type determines contract structures, price indexation, and decarbonization exposure across Italian offtake.
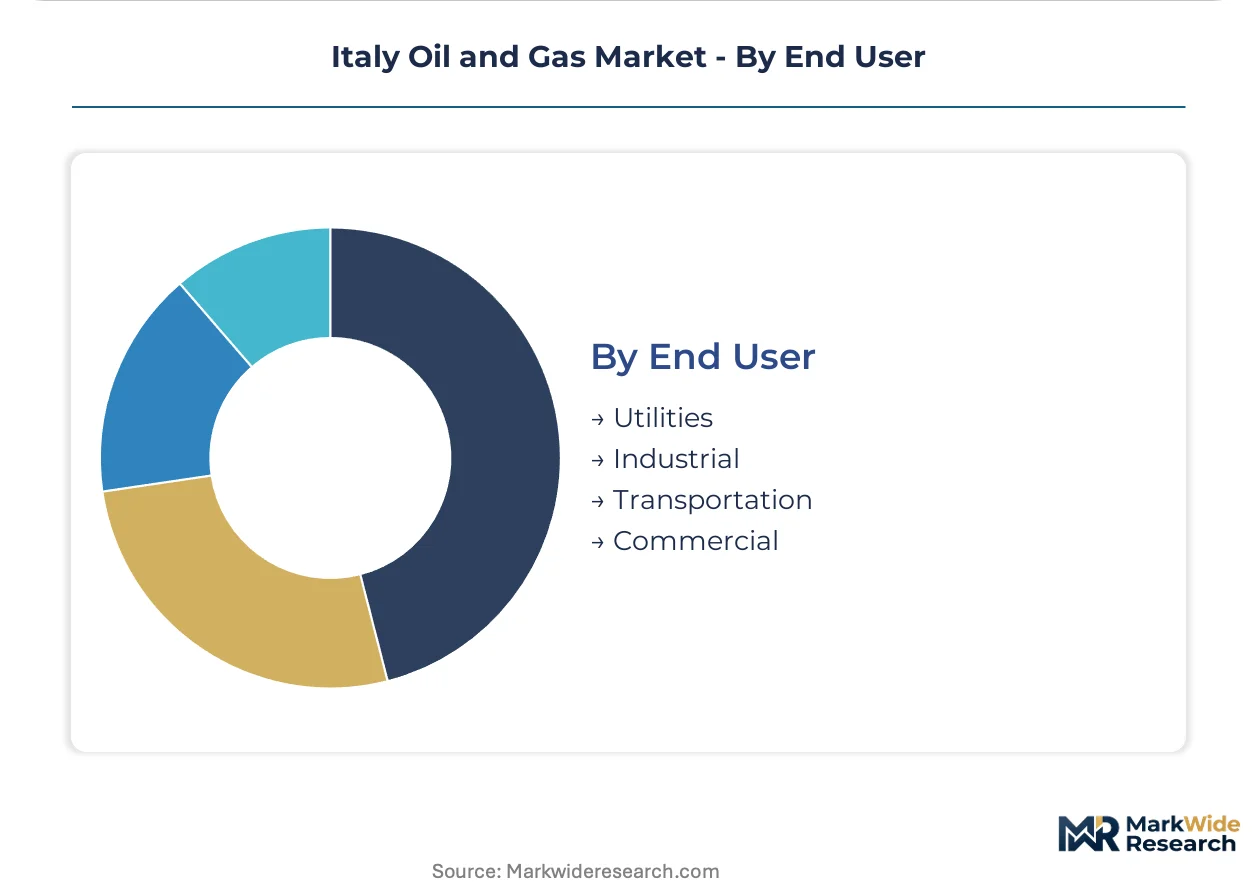
- Utilities:Power generation and gas distribution companies procuring feedstock for combined-cycle turbines and grid supply. TTF-linked pricing with quarterly review cycles now dominates term contracting as operators centralize commodity exposure management.
- Industrial:Petrochemical plants at Ravenna and Porto Torres, plus steel and cement manufacturers consuming fuel and feedstock. These buyers index supply to front-month benchmarks rather than oil-linked formulas, transferring volatility upstream.
- Transportation:Marine bunkering, aviation fuel, and road transport operators. Demand faces structural compression as electrification and biofuel mandates advance under Italy's National Integrated Energy and Climate Plan.
- Commercial:Retail fuel stations, heating oil distributors, and small-scale industrial consumers. This segment fragments across regional distributors with limited pricing power against integrated suppliers.
Utilities anchor volume commitments. Industrial offtake expands most quickly as petrochemical buyers lengthen term supply to secure feedstock under volatile TTF regimes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian hydrocarbon output clusters in the Po Valley basin and Adriatic offshore corridors where mature infrastructure supports incremental development. Eni SpA controls processing capacity at Val d'Agri while Edison SpA anchors midstream networks. Regional demand concentrates in northern industrial clusters and southern power generation hubs.
Lombardy
Petrochemical buyers in Milan's industrial ring sustain gas offtake for combined-cycle turbines and chemical feedstock. ARERA tariff frameworks govern distribution returns across the region's dense pipeline network. The Sannazzaro refinery complex processes medium-sour crudes into transport fuels and specialty products.
Emilia-Romagna
Ravenna's offshore supply base supports Adriatic platform maintenance and brownfield tieback projects. The Ministry of Environment and Energy Security licenses marginal discoveries through streamlined permitting for strategic gas volumes. Local fabrication yards specialize in subsea manifold assembly and pipeline spool fabrication.
Basilicata
Val d'Agri field operations dominate regional employment and tax revenue through Eni SpA's integrated production complex. EU Green Deal methane monitoring mandates impose capital burdens on gathering and processing infrastructure. Third-party producers negotiate pipeline access through regulated tariff structures.
Sicily
Milazzo refinery conversion capacity serves Mediterranean bunkering and regional petrochemical demand. Offshore exploration in the Sicily Channel remains stalled under environmental moratorium pressures. The Gela industrial cluster processes residual heavy fractions into asphalt and fuel oil for marine markets.
Veneto
Porto Marghera fabrication yards construct offshore platforms for Adriatic and international contracts. F-Gas Regulation compliance drives compressor station retrofits across the regional transmission network. Venice's LNG terminal access supports peak-shaving capacity for northern industrial load centers.
Italy Oil and Gas Market Competitive Environment
Integrated majors and specialized service providers split the market along upstream control versus technical execution lines. Consolidation concentrates around Eni SpA's captive infrastructure and Edison SpA's regulated midstream position. Three archetypes dominate: state-affiliated integrated operators controlling strategic reserves, independent upstream specialists targeting marginal fields, and international engineering houses leveraging domestic fabrication capacity. Competitive dynamics center on brownfield asset acquisitions and carbon capture retrofit partnerships.
Among Rome-headquartered operators, Eni SpA exemplifies the integrated archetype through its Val d'Agri processing complex and Basilicata pipeline corridors. Edison SpA occupies the regulated midstream tier with Adriatic offshore platforms and LNG terminal access. Saipem SpA represents the engineering specialist model, anchoring domestic capability through Porto Marghera and Trieste fabrication yards while competing internationally in offshore project execution.
| Leading Market Players |
|---|
| Eni SpA |
| Edison SpA |
| Saipem SpA |
| Shell PLC |
| TotalEnergies SE |
| BP PLC |
| Engie SA |
| Schlumberger NV |
| Zenith Energy Ltd |
| Others |
Value Chain & Pricing Dynamics
Overcapacity at Milazzo and Sannazzaro refineries compresses conversion margins while forcing suppliers to absorb logistics premiums for Adriatic crude deliveries. This utilization imbalance transfers pricing power downstream to petrochemical buyers at Ravenna and Porto Torres who now dictate TTF-linked quarterly benchmarks rather than oil-indexed formulas.
Pricing Analysis
ARERA tariff frameworks dictate the pricing tier structure across Italy's gas distribution network, segmenting rates by consumer class and infrastructure access priority. Premium pricing attaches to interruptible industrial supply contracts with real-time balancing obligations, while standard residential tariffs incorporate pass-through mechanisms for carbon adjustment costs. Cost compression in the refining segment intensifies as simple distillation economics erode against complex conversion margins. Petrochemical buyers at Ravenna exhibit highest price sensitivity due to feedstock substitution options, while utilities securing baseload gas supply show lowest sensitivity given capacity payment dependencies.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now dominate procurement negotiations between Adriatic offshore operators and Ravenna fabrication yards, straining working capital across the supplier base. Equipment sourcing draws from Germany for high-pressure compressors, South Korea for offshore platform modules, and Norway for subsea production systems. Steel plate and specialized alloys for wellhead equipment constitute critical input dependencies. Single-source vulnerability concentrates in hydraulic workover units for Apennine thrust belt interventions. Distribution runs through Eni SpA's captive pipeline corridors at Val d'Agri and Edison SpA's regulated transmission networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities proliferate as industrial offtake contracts compress to quarterly price reviews, creating niches for specialized traders with TTF hedging capabilities and integrated logistics offerings.
For Market Incumbents: Insulate processing margins at Sannazzaro and Milazzo by retrofitting hydrocracking units for biofeedstock co-processing ahead of EU Green Deal mandates. Consolidate gathering infrastructure in Basilicata to block third-party producer bypass routes. Carbon capture retrofit partnerships with EU Innovation Fund backing represent the critical defensive lever against stranded asset classification for Po Valley depleted fields. For New Entrants and Emerging Players: Establish a beachhead in Southern Adriatic deepwater engineering services where Saipem SpA's domestic capacity constraints create execution gaps for marginal carbonate discoveries. Target independent operators in depleted Po Valley fields requiring specialized coiled tubing interventions. Position through carbon capture pilot project alliances that access Italy's transition mechanism subsidies without requiring legacy asset ownership. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across carbon capture retrofit and platform electrification sub-segments as EU Methane Regulation compliance mandates multiply equipment requirements. Long-term viability favors brownfield production assets with proven storage geology for CO2 sequestration. Acquisition targets should display integrated pipeline access and ARERA-regulated tariff protections. The signal to monitor is licensing round design under the National Mining Code for Southern Adriatic fiscal term relaxation.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit Partnership | EU Innovation Fund subsidies de-risk pilot injection projects at Val d'Agri operational sites. |
| Platform Electrification Investment | Subsea cable connections to coastal grids replace gas turbine generators across Adriatic offshore assets. |
| Enhanced Oil Recovery Deployment | Polymer flooding and CO2 injection extend Po Valley field life without new exploration permits. |
| LNG Terminal Multi-Product Pivot | Panigaglia and offshore regasification assets adapt ARERA tariffs for hydrogen blending and bio-LNG handling. |
| Deepwater Licensing Round Positioning | National Mining Code fiscal terms for Southern Adriatic strategic gas discoveries attract risk capital. |
Study Parameters
A spread of perspectives from upstream field operators, ARERA regulatory specialists, EPC contractors at Porto Marghera, and petrochemical procurement managers converged on the working assumptions. Primary interviews with Edison SpA midstream planners and independent Po Valley producers supplied operational data on brownfield economics. Secondary validation incorporated Ministry of Environment and Energy Security licensing records, ARERA tariff determinations, EU Methane Regulation implementation guidance, and IEA European gas market reports. Bottom-up field-level production estimates triangulated against top-down demand projections from industrial cluster consumption patterns.
Demand-supply balance modeling across the projection horizon anchored volume forecasts in power sector gas displacement of coal capacity and petrochemical feedstock requirements. Segmentation dimensions encompassed hydrocarbon type, service specialization, technology deployment, and end-user contract structure. CAGRs derived from regression analysis against EU Green Deal implementation pacing and National Integrated Energy and Climate Plan target trajectories. Industry-specific inputs included F-Gas Regulation compliance cost curves and enhanced oil recovery incremental reserve recovery factors.
Sensitivities concentrate around offshore drilling moratorium extensions, Southern Adriatic licensing round cancellations, and carbon capture subsidy allocation delays. Forecasts reflect documented assumptions regarding EU Methane Regulation enforcement intensity and ARERA tariff recalibration cycles. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Middle East and Africa Pipeline Maintenance Market
Oil & Gas
Republic of Congo Oil and Gas Market
Oil & Gas
Gulf of Mexico Oil and Gas Upstream Market
Oil & Gas
India Oil and Gas Market
Oil & Gas
US Oil and Gas Infrastructure Market
Oil & Gas
Middle-East Enhanced Oil Recovery Market
Oil & Gas
Gulf of Mexico Oil and Gas Midstream Market
Oil & Gas
Indonesia Oilfield Equipment Rental Services Market
Oil & Gas
Oil and Gas Storage Market
Oil & Gas
Oil and Gas Data Monetization Market
Oil & Gas
Floating Liquefied Natural Gas (FLNG) Terminals Market
Oil & Gas
Canada Oil and Gas Market
Oil & Gas
Mexico Wireline Services Market
Oil & Gas
Oil and Gas Separation Equipment Market
Oil & Gas
Saudi Arabia Drilling Rigs Market
Oil & Gas
Oil Field Drill Bits Market