
 Well Intervention Service Market | 2026-2036
Well Intervention Service Market Size, Share, and Industry Trends Forecast 2026-2036
Well Intervention Service Market Analytics
Offshore brownfield rehabilitation is consolidating as the primary demand driver, while onshore shale workover activity retreats from peak levels. Halliburton Company leverages its integrated well intervention portfolio across deepwater basins in the Gulf of Mexico and West Africa. Baker Hughes Company anchors its position through advanced wireline diagnostics and permanent monitoring systems. Schlumberger Limited dominates subsea intervention with its riserless light well intervention vessels and remote-operated tool deployment.
Well intervention service encompasses engineered operations to restore, enhance, or terminate production from existing oil and gas wells, utilizing coiled tubing units rated to 15,000 psi, snubbing stacks with live-well capability, and electric-line conveyance for real-time downhole diagnostics. The primary industrial purpose is to maximize hydrocarbon recovery without drilling new wells, thereby deferring capital expenditure on greenfield developments. Pressure management services command the largest revenue share due to mandatory well control requirements across high-pressure high-temperature reservoirs. Coiled tubing technology leads growth velocity as operators deploy larger-diameter strings for milling and fracturing in extended-reach horizontals. Wireline services occupy a mature margin pool, with demand tied to routine logging and perforation maintenance rather than step-change innovation.
US operators navigate BSEE well control rules and EPA offshore discharge limitations that mandate dual mechanical barriers during live-well interventions. Norway's Petroleum Safety Authority enforces NORSOK D-010 well integrity standards that drive demand for barrier verification services and intervention system redundancy. Stakeholders must monitor regulatory divergence between prescriptive North Sea standards and performance-based Gulf of Mexico frameworks when allocating R&D and fleet positioning capital.
Market Dynamics
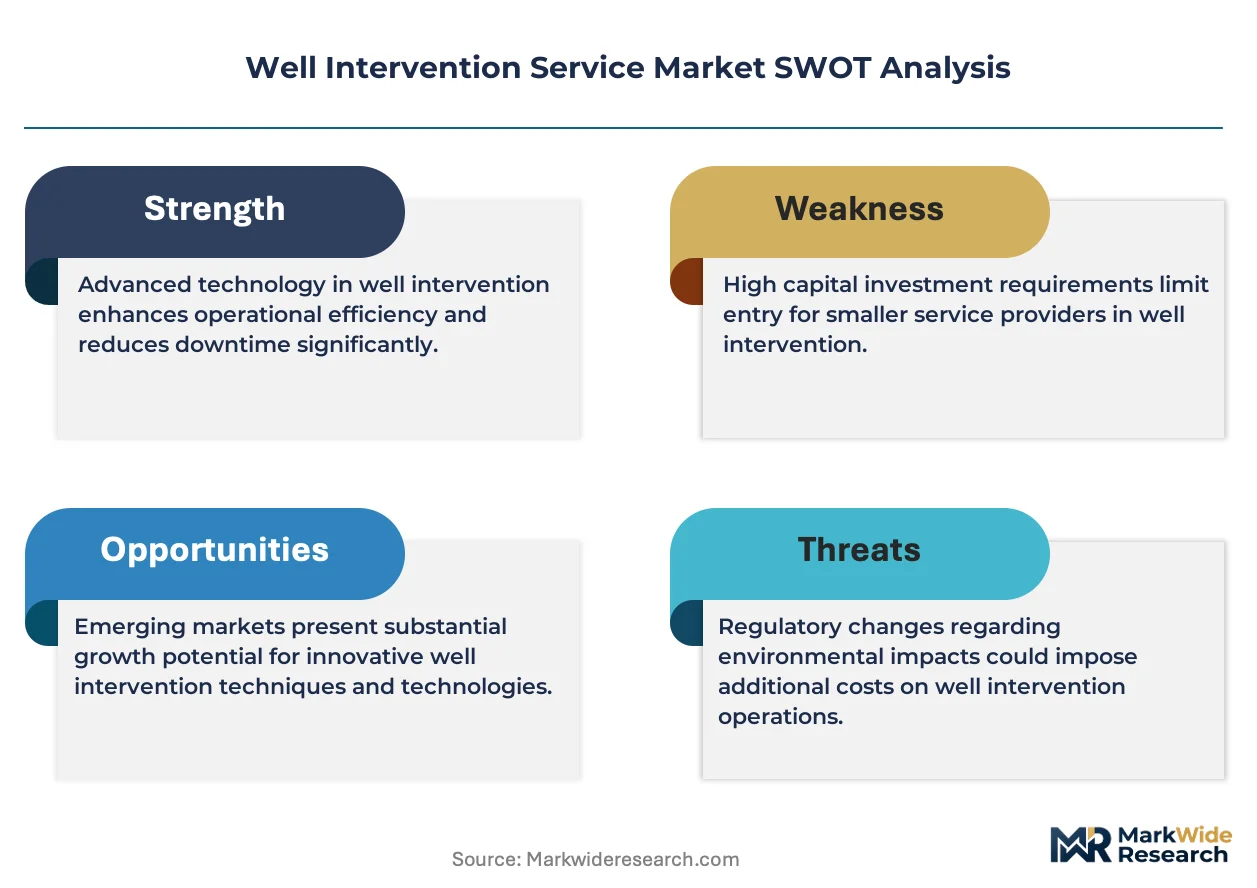
Offshore brownfield rehabilitation is consolidating as the dominant structural force, as aging subsea infrastructure across the North Sea and US Gulf of Mexico forces operators to prioritize intervention over greenfield drilling. Regulatory tightening on well integrity barriers is simultaneously reshaping service specifications and fleet deployment patterns.
Growth Catalysts
- BSEE Well Control Rules:The US Bureau of Safety and Environmental Enforcement mandates dual mechanical barriers during live-well interventions, creating mandatory demand for pressure management services and barrier verification systems across high-pressure reservoirs.
- Coiled Tubing Technology:Larger-diameter coiled tubing strings rated to 15,000 psi now enable milling and fracturing in extended-reach horizontals, expanding addressable intervention complexity without rig mobilization.
- North Sea Infrastructure Age:Subsea assets exceeding twenty years of operational life in the UK and Norwegian sectors generate concentrated demand for riserless light well intervention and subsea diagnostics.
Market Restraints
- Specialized Vessel Scarcity:Purpose-built intervention vessels with dynamic positioning and subsea crane capacity concentrate in the North Sea and Gulf of Mexico, limiting fleet mobility to emerging basins.
- Steel Alloy Input Volatility:High-grade chromium-molybdenum tubing strings face price instability from mining supply concentration, compressing service margin predictability for coiled tubing operators.
- NORSOK D-010 Compliance Burden:Norway's prescriptive well integrity standard imposes redundant barrier verification requirements that extend project timelines compared to performance-based Gulf of Mexico frameworks.
Strategic Opportunities
- West Africa Deepwater:Pre-salt and post-salt fields off Angola and Nigeria lack mature intervention infrastructure, creating first-mover advantage for vessels with remote-operated tool deployment capability.
- Real-Time Downhole Monitoring:Permanent fiber-optic sensing systems converging with electric-line conveyance enable continuous reservoir surveillance, shifting revenue from episodic wireline to subscription-based diagnostics.
- Plug and Abandonment Mandates:UK and Norwegian regulatory deadlines for aging well stock create dedicated demand for snubbing units with live-well capability and subsea cutting technologies.
Industry Challenges
- Subsea Robotics Integration:Intervention vessels must synchronize remotely operated vehicles with riserless systems, requiring cross-functional crews skilled in both marine operations and downhole tool control.
- Barrier Certification Timelines:Third-party verification of dual mechanical barriers under NORSOK and BSEE protocols extends pre-operation approval cycles, compressing effective vessel utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Well Intervention Service Market |
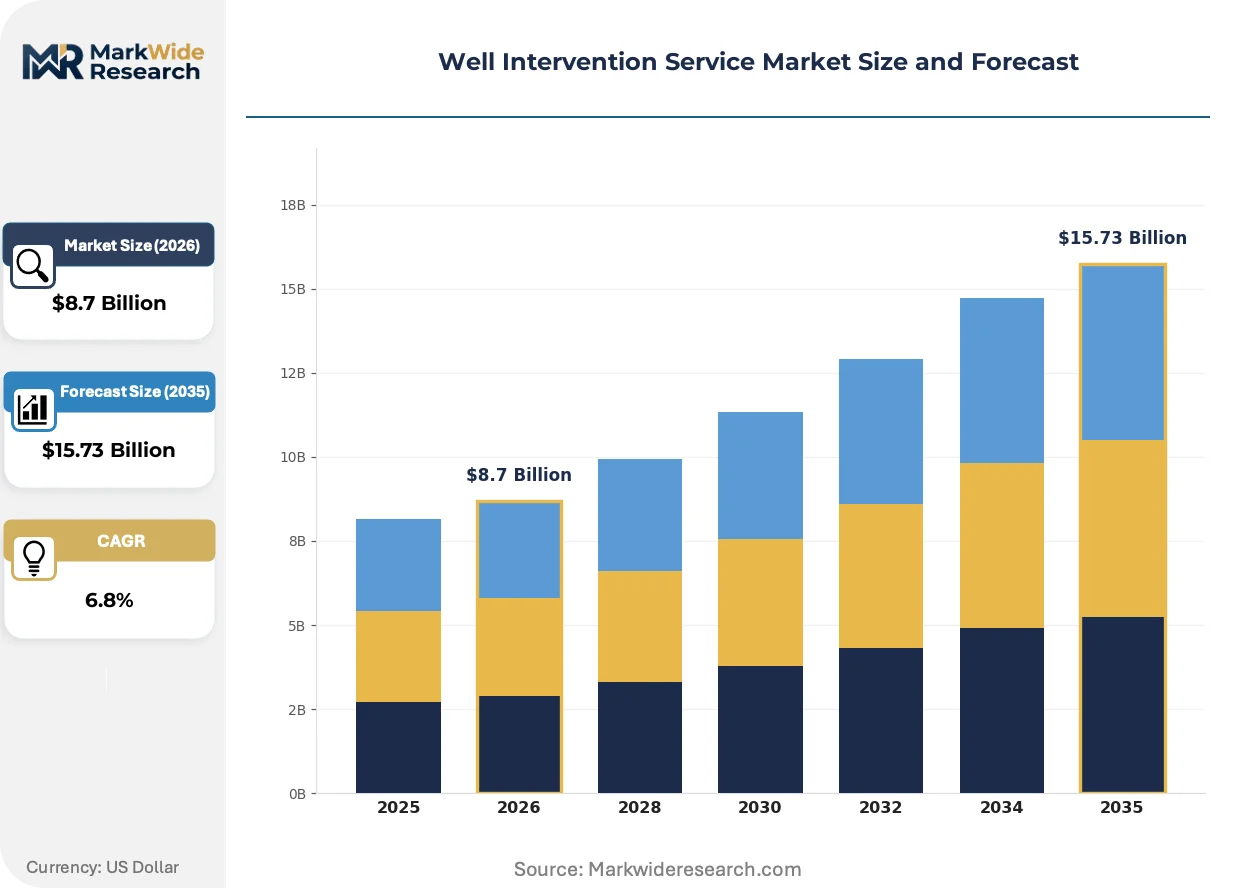
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Pressure Management, Well Stimulation, Fishing, Wireline Technology: Coiled Tubing, Snubbing, Slickline, Electric Line End User: Oil & Gas Operators, Service Companies, EPC Contractors, Independent Producers Phase: Planning, Execution, Maintenance, Decommissioning |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes Company, Weatherford International, Expro Group, TechnipFMC, Oceaneering International, National Oilwell Varco, Welltec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Well Intervention Service Market Evolving Landscape
Electrification of intervention systems is reshaping fleet specifications and operational economics. Real-time data transmission from seabed to surface is compressing decision cycles and enabling remote-operated deployment models that reduce personnel exposure.
Electric coiled tubing units with integrated power electronics are electrifying intervention economics by eliminating hydraulic fluid systems and reducing deck footprint. North Sea operators deploy these systems for subscale interventions where full rig mobilization is uneconomical. The technology is compressing minimum viable project size and expanding addressable well population.
REACH chemical authorization in the European Union is restricting traditional corrosion inhibitors and lubricants used in downhole fluids. Service providers reformulate intervention chemistry portfolios to maintain barrier performance under tightened environmental discharge standards. Norway's Petroleum Safety Authority enforces these constraints most stringently, driving regional differentiation in chemical service capabilities.
Asset owners now unbundle intervention contracts from drilling agreements, creating standalone procurement for wireline, coiled tubing, and snubbing services. Integrated service providers face disintermediation pressure as operators seek specialized boutiques for specific intervention modalities. This pattern concentrates in the UK North Sea, where supermajor divestment to private equity producers fragments purchasing authority and favors modular service sourcing.
Well Intervention Service Market Segmentation
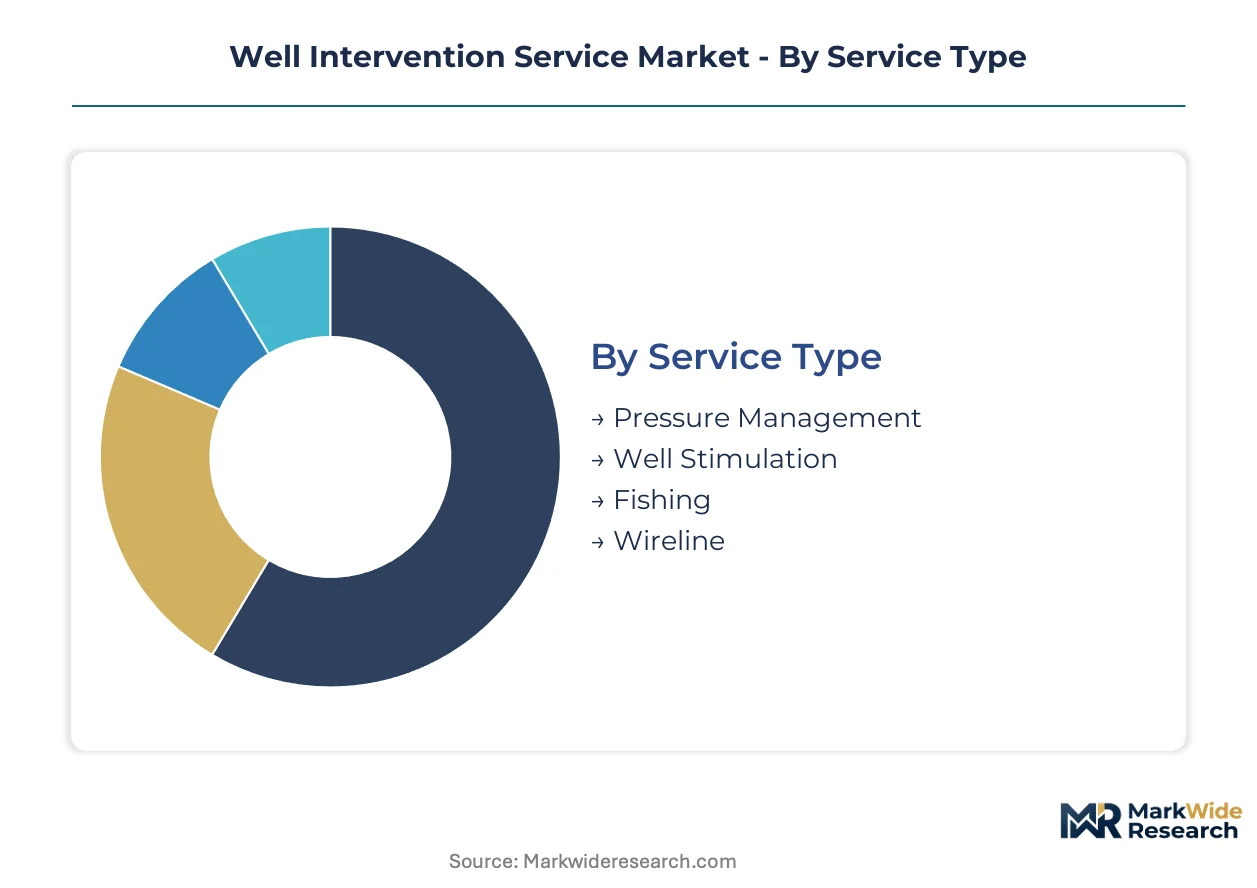
Well intervention services fragment across four structural dimensions that determine equipment specifications, contract structures, and margin profiles. Service type and technology selection dictate capital intensity and crew specialization, while end-user category and operational phase shape procurement authority and payment terms.
Service Type:
Standalone pressure management commands premium pricing as a discrete procurement category, whereas stimulation and fishing services embed more frequently within integrated drilling contracts.
- Pressure Management:Encompasses well control operations, barrier verification, and live-well interventions utilizing snubbing stacks and blowout preventers rated to 15,000 psi. Demand concentrates in the US Gulf of Mexico under BSEE dual-barrier mandates, where high-pressure high-temperature reservoirs require redundant mechanical isolation systems.
- Well Stimulation:Acidizing, fracturing, and chemical treatments restore or enhance formation permeability. North Sea operators deploy these services for brownfield rehabilitation of aging subsea wells where original completion designs limit natural flow capacity.
- Fishing:Retrieval of stuck pipe, tools, or debris from wellbores using magnetic, mechanical, or explosive techniques. Norwegian sector demand tracks NORSOK D-010 well integrity enforcement requiring debris-free barrier paths.
- Wireline:Electric-line and slickline conveyance for logging, perforating, and setting plugs. Routine maintenance applications dominate, with revenue tied to well count rather than intervention complexity.
Volume placements concentrate in Pressure Management; the faster expansion belongs to Well Stimulation.
Technology:
Cost tier stratification separates capital-intensive coiled tubing and snubbing systems from lower-footprint line-based conveyance methods.
- Coiled Tubing:Continuous steel tubing strings enable milling, fracturing, and nitrogen lifting without killing the well. Larger-diameter strings rated to 15,000 psi now address extended-reach horizontals previously requiring full rig workovers.
- Snubbing:Hydraulic workover rigs permit live-well intervention through tubing or casing under pressure. UK North Sea demand clusters around platform-based installations where vessel mobilization is uneconomical for subscale projects.
- Slickline:Solid mechanical wire for gauge cutting, plug setting, and memory logging. Mature margin pool with limited technology differentiation across service providers.
- Electric Line:Conductor cable enabling real-time data transmission and powered tool operation. Permanent monitoring convergence is shifting procurement from episodic to subscription-based revenue models.
Capital deployment concentrates in Coiled Tubing; the steepest expansion trajectory belongs to Electric Line.
End User:
Customer type determines contract duration, technical specification authority, and risk allocation between operator and service provider.
- Oil & Gas Operators:Supermajors and national oil companies with direct well ownership and full procurement authority. Gulf of Mexico independents unbundle intervention services from drilling agreements to optimize standalone project economics.
- Service Companies:Subcontractors accepting technical scope from primary drilling or completion contractors. Margin pressure intensifies as tier-one providers internalize more intervention capabilities.
- EPC Contractors:Engineering-procurement-construction firms integrating intervention planning into greenfield development schedules. Early engagement enables riserless system specification during subsea architecture design.
- Independent Producers:Private equity-backed operators with concentrated North Sea asset portfolios. Fragmented purchasing authority favors modular service sourcing over integrated packages.
Contract value concentrates in Oil & Gas Operators; the fastest share gains belong to Independent Producers.
Phase:
Maturity differentiation separates front-loaded engineering design from recurring maintenance and terminal decommissioning activities.
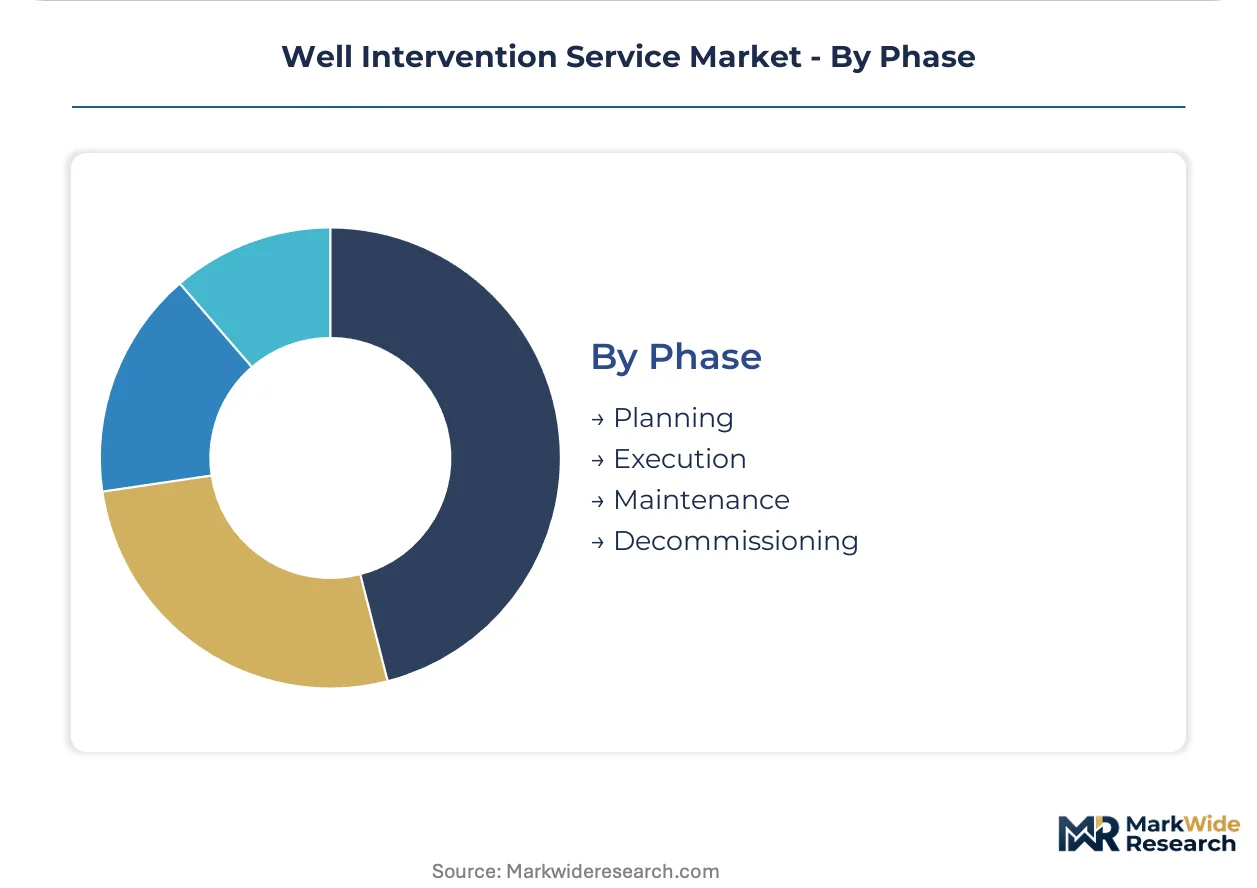
- Planning:Feasibility studies, barrier verification design, and vessel specification for complex interventions. Norway's Petroleum Safety Authority mandates redundant planning documentation under NORSOK frameworks.
- Execution:Live intervention operations including coiled tubing deployment, wireline logging, and snubbing workovers. Weather windows and vessel availability constrain effective utilization in offshore basins.
- Maintenance:Scheduled integrity verification and barrier testing to sustain production authorization. UK regulatory deadlines for aging well stock are extending maintenance program scope.
- Decommissioning:Plug and abandonment operations, subsea cutting, and barrier installation for well retirement. North Sea infrastructure age is accelerating phase transition from maintenance to decommissioning across asset portfolios.
Service revenue concentrates in Execution; the most rapid phase expansion belongs to Decommissioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Well intervention service consumption concentrates in offshore basins with aging infrastructure, while specialized vessel construction and coiled tubing manufacturing cluster in industrial port zones with heavy fabrication heritage. The production-consumption divide reflects capital-intensive asset positioning against geographically fixed reservoir locations.
United States
Gulf of Mexico brownfield rehabilitation and shale well workover activity drive demand across the US intervention market. BSEE well control rules mandate dual mechanical barriers during live-well operations, forcing operator expenditure on barrier verification systems. Houston anchors the national service provider ecosystem, with Port Fourchon serving as the primary offshore supply base for intervention vessel mobilization.
Norway
North Sea subsea infrastructure exceeding twenty years of operational life generates concentrated demand for riserless light well intervention. The Petroleum Safety Authority enforces NORSOK D-010 well integrity standards that impose redundant barrier verification requirements. Stavanger hosts the primary cluster of intervention engineering expertise, with service providers positioning riserless vessels at Ågotnes for rapid UK and Norwegian sector response.
United Kingdom
Regulatory deadlines for aging well stock accelerate plug and abandonment activity across the UK continental shelf. The North Sea Transition Authority mandates decommissioning timelines that compress project schedules for snubbing and cutting services. Aberdeen maintains its position as the intervention procurement hub, though supermajor asset divestment to private equity operators fragments purchasing authority.
Brazil
Pre-salt field development creates emerging demand for subsea intervention capability in Brazilian deepwater. ANP regulatory frameworks for well integrity are tightening as Petrobras expands production from carbonate reservoirs. Rio de Janeiro anchors the national oilfield service cluster, with Macaé serving as the primary logistics base for offshore intervention mobilization.
Saudi Arabia
Gas field development and mature oil reservoir management expand intervention requirements across Saudi onshore and offshore assets. Saudi Aramco technical specifications for well integrity drive regional standardization of barrier verification protocols. Dhahran concentrates engineering and procurement functions, with intervention service providers establishing permanent presence to capture long-term maintenance contracts.
Well Intervention Service Market Competitive Landscape
Top-tier vendors anchor integrated service provision, while specialized boutiques occupy niche technology segments. The market structures around three tiers: full-service providers with vessel fleets and downhole tool manufacturing, regional specialists with basin-specific expertise, and technology-focused innovators in electric-line and monitoring systems. Two dominant competitive moves define current positioning: fleet expansion through vessel newbuilds and conversion programs, and technology licensing agreements that transfer proprietary downhole tool designs to regional partners.
Among the full-service tier, Schlumberger Limited, Halliburton Company, and Baker Hughes Company represent the integrated archetype with capabilities spanning wireline, coiled tubing, and subsea intervention vessels. These entities exemplify the capital-intensive positioning required for deepwater brownfield rehabilitation, where riserless light well intervention and permanent monitoring system deployment demand synchronized marine and downhole expertise. Their geographic footprint reflects deliberate positioning in the North Sea and Gulf of Mexico, with emerging presence in West African basins where intervention infrastructure remains underdeveloped.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| Weatherford International |
| Expro Group |
| TechnipFMC |
| Oceaneering International |
| National Oilwell Varco |
| Welltec |
| Others |
Value Network & Pricing Analysis
REACH chemical authorization gates qualified supply and premium-tier pricing access for well intervention service providers, restricting traditional corrosion inhibitors and lubricants while elevating compliant chemistry portfolios to premium positioning. BSEE and NORSOK barrier verification mandates compound this gating effect, concentrating pricing power with certified suppliers capable of dual-mechanical barrier deployment.
Pricing Analysis
Margin tightening in standard-tier services reflects steel alloy input volatility and fleet overcapacity in the Gulf of Mexico. Three-tier pricing structure across premium, standard, and economy levels separates NORSOK-certified barrier verification from BSEE-compliant operations and non-regulated onshore workovers. Cost compression accelerates in standard-tier wireline maintenance as independent producers fragment purchasing authority. National oil companies exhibit lowest price sensitivity due to operational continuity requirements, while private equity-backed independents drive hardest bargain terms.
Supply Chain Analysis
API Q1 and ISO 13628-7 certification gating restricts qualified coiled tubing manufacturing to the United States, Norway, and Japan. High-grade chromium-molybdenum tubing strings and subsea control modules draw from mining supply concentration in South Africa and Kazakhstan. Single-source vulnerability concentrates in dynamic positioning system integration for intervention vessels. Distribution runs through Houston, Stavanger, and Aberdeen as primary logistics clusters for offshore mobilization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized intervention vessel scarcity props pricing power across the forecast window, with purpose-built fleet capacity concentrated in legacy basins and emerging West African demand outpacing newbuild delivery schedules.
For Market Incumbents: Extend fleet utilization through multi-well campaign contracting in the North Sea, locking preferred operator relationships before independent producers complete portfolio rationalization. Deepen upstream control over coiled tubing string manufacturing to defend margin position against steel alloy price volatility. Prioritize electric-line monitoring system R&D to capture subscription revenue migration from episodic wireline services. For New Entrants and Emerging Players: Launch via vessel-sharing partnerships with established North Sea operators to bypass capital-intensive fleet ownership barriers. West Africa deepwater presents the most penetrable geography, with pre-salt and post-salt fields off Angola and Nigeria lacking mature intervention infrastructure. Target first-mover positioning in riserless light well intervention capability as the specific go-to-market angle. For Investors and Strategic Acquirers: Norwegian Petroleum Safety Authority enforcement acceleration is the leading indicator that barrier verification service demand will outpace general intervention growth. Five-to-ten year viability favors acquisition targets with integrated vessel and downhole tool capabilities rather than pure-play equipment lessors. Monitor BSEE incident investigation frequency as the specific signal for regulatory tightening velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Vessel Fleet Expansion | Newbuild intervention vessels with dynamic positioning capture West African deepwater demand before competitor entry. |
| Backward Integration into Coiled Tubing Manufacturing | In-house production of 15,000 psi-rated strings insulates margin from chromium-molybdenum price volatility. |
| Electric-Line Technology Licensing | Permanent fiber-optic sensing system partnerships transfer proprietary designs to regional Norwegian and UK operators. |
| Multi-Well Campaign Contracting | Extended North Sea operator commitments improve vessel utilization rates against weather window constraints. |
| REACH-Compliant Chemistry Portfolio Development | Reformulated corrosion inhibitors maintain barrier performance under tightened EU environmental discharge standards. |
Research Methodology
Document review covered BSEE incident databases, NORSOK D-010 revision histories, and North Sea Transition Authority decommissioning schedules, complemented by interviews with offshore operations directors, subsea engineering managers, and intervention vessel fleet planners. Secondary validation drew from customs records for coiled tubing string imports, SEC filings of publicly traded service providers, and IHS Markit offshore project databases. Bottom-up well intervention activity counts triangulated against top-down operator expenditure surveys across the analysis window.
Segmented projections by service type, technology modality, end-user category, and operational phase fed into integrated revenue modeling. CAGRs derived from basin-specific activity intensity curves weighted by regulatory compliance cost escalators. Forecast inputs incorporated vessel day-rate trajectories and steel alloy price indices without year-specific anchoring.
Regulatory enforcement variance, fleet mobilization delays, and commodity price collapse are the dominant revision risks to intervention demand assumptions. A model refresh is warranted upon material change in BSEE barrier verification mandate scope or Norwegian well integrity standard revision timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Intelligent Completion Sales Market
Oil & Gas
Digital Oilfield Solutions Market
Oil & Gas
Norway Oil and Gas Upstream Market
Oil & Gas
Expandable Liner Hanger System Market
Oil & Gas
Proppant Market
Oil & Gas
Flexible Pipes for Oil and Gas Market
Oil & Gas
Global Upstream Petrotechnical Training Services Market
Oil & Gas
Norway Oilfield Equipment Rental Services Market
Oil & Gas
Wireline Logging Services Market
Oil & Gas
South America LNG Bunkering Market
Oil & Gas
Drilling and Completion Fluids Market
Oil & Gas
Global Oilfield Stimulation Chemicals Market
Oil & Gas
Oil and Gas Separation Equipment Market
Oil & Gas
Drilling Services Market
Oil & Gas
Oil Country Tubular Goods (OCTG) Market
Oil & Gas
South and Central America Oil Country Tubular Goods (OCTG) Market