
 Egypt Food Sweetener Market | 2026-2036
Egypt Food Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Food Sweetener Market Insights
Market Context
Project finance for industrial-scale fermentation and extraction facilities is tilting competitive dynamics toward capital-backed multinationals. Cargill Inc. leverages its Red Sea logistics infrastructure to control inbound raw material flows. Südzucker AG anchors its position through backward integration into beet sugar refining. Tate & Lyle PLC differentiates via specialized texturizing systems that pair sweeteners with mouthfeel modifiers.
Technical and Segment Structure
Food sweeteners encompass caloric and non-caloric substances added to confer sweetness, ranging from sucrose and fructose to high-intensity compounds such as sucralose and steviol glycosides with sweetness potencies hundreds of times that of sugar. These additives serve primarily to reduce manufacturing costs, manage glycemic response, and extend shelf stability in processed formulations. Natural sweeteners occupy the premium tier as Egyptian consumers associate plant-derived labels with clean eating, while artificial sweeteners retain volume leadership in mass-market beverages where cost minimization dominates procurement decisions. High-intensity sweeteners represent the fastest-expanding product category as reformulation mandates from multinational beverage brands cascade through Egyptian contract manufacturing networks.
Regulatory Framework
Egypt's national food safety regulator, the National Food Safety Authority, enforces compositional standards that govern maximum usage levels for synthetic sweeteners across 22 food categories. The Egyptian Organization for Standardization and Quality issues mandatory specifications for stevia extracts and monk fruit concentrates entering commercial channels. Compliance with these frameworks shapes import licensing timelines and local production qualification protocols. Stakeholders must monitor pending amendments to front-of-package labeling rules that would require explicit disclosure of all sweetener classes in Arabic text.
Market Dynamics
Multinational beverage brands are cascading reformulation mandates through Egyptian contract manufacturing networks, forcing rapid substitution of caloric sweeteners with high-intensity alternatives across Greater Cairo's processing corridor.
Growth Catalysts
- Labeling Differentiation Mandates:Egypt's National Food Safety Authority enforces Arabic-language front-of-package disclosure rules that elevate consumer awareness of natural versus artificial sweetener classes.
- Beverage Reformulation Programs:Soft drink and bottled water producers are accelerating procurement of steviol glycosides and sucralose to meet multinational parent company sugar-reduction targets.
- Red Sea Logistics Infrastructure:Port modernization at Ain Sokhna and Alexandria is compressing inbound raw material lead times for fermentation-derived sweeteners.
Market Restraints
- Beet Sugar Price Volatility:Domestic sucrose availability fluctuates with Nile Delta agricultural cycles, forcing formulators to maintain dual-sourcing strategies.
- Import Licensing Friction:Egyptian Organization for Standardization and Quality certification timelines for novel stevia extracts extend qualification periods by four to six months.
- Technical Blending Limitations:High-intensity sweeteners require companion texturizing systems to replicate sucrose mouthfeel, adding formulation complexity and cost.
Strategic Opportunities
- Upper Egypt Manufacturing Expansion:Greenfield production facilities in Sohag and Qena offer lower land and labor costs for natural sweetener extraction operations.
- Pharmaceutical-Grade Applications:Diabetic nutrition and pediatric formulation segments present untapped demand for precision-dosed sweetener systems.
- Clean Label Convergence:Monk fruit concentrates paired with erythritol are penetrating premium dairy and confectionery channels as Egyptian consumers associate plant-derived labels with quality.
Industry Challenges
- Specialized Fermentation Expertise Scarcity:Local universities produce insufficient biochemical engineers to staff industrial-scale microbial cultivation facilities.
- Legacy Equipment Retrofit Costs:Existing sucrose handling infrastructure requires capital-intensive modification to process hygroscopic high-intensity sweetener powders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Food Sweetener Market |
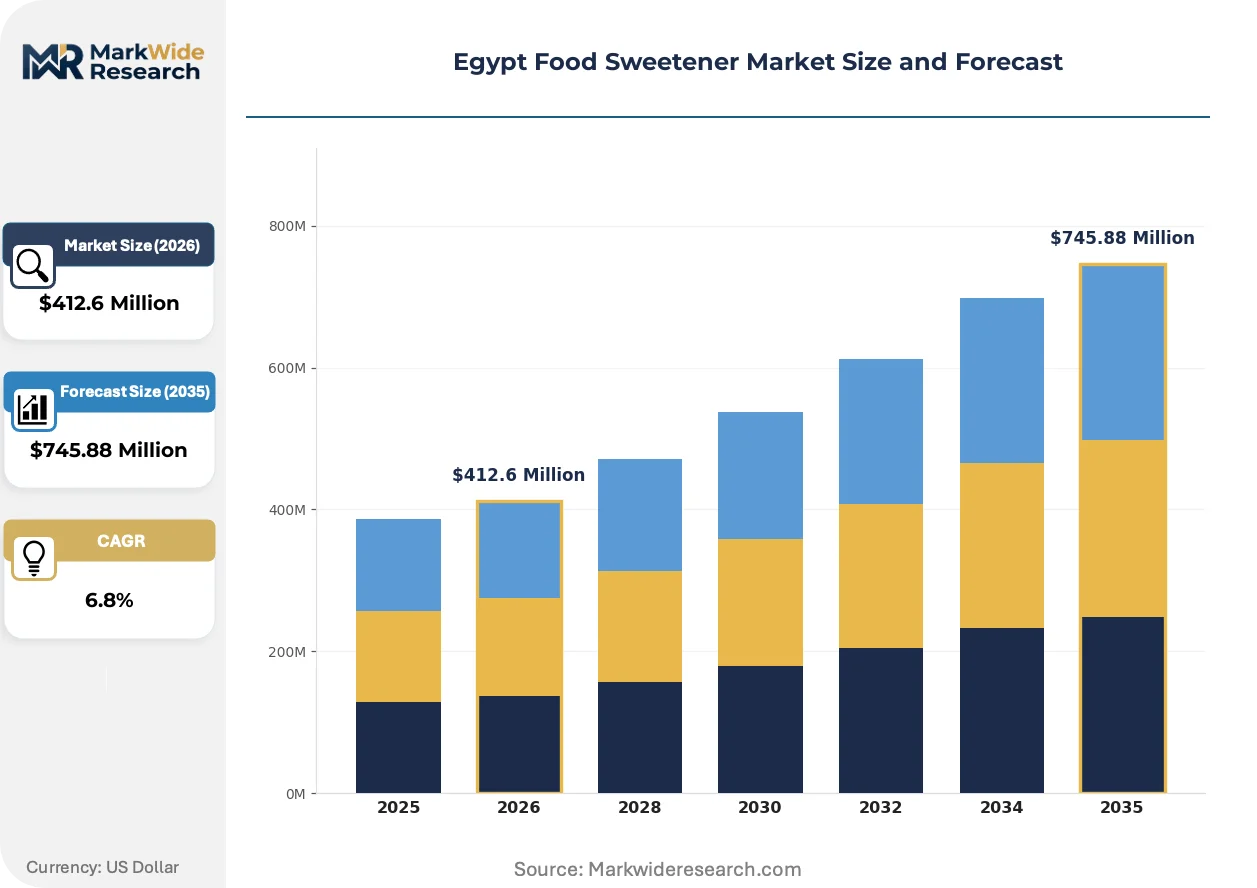
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Sweeteners, Artificial Sweeteners, Sugar Alcohols, High-Intensity Sweeteners Application: Beverages, Bakery Products, Dairy Products, Confectionery End User: Food Manufacturers, Beverage Producers, Retail Businesses, Health-Conscious Consumers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Koninklijke DSM N.V., Ajinomoto Co., Inc., Cargill Inc., JK Sucralose Inc., Südzucker AG, Tate & Lyle PLC, DuPont de Nemours Inc., Naturex, Ingredion Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Food Sweetener Market Trends and Innovations
Process control systems and formulation science are converging to enable real-time sweetness modulation in continuous manufacturing environments across Egypt's food processing sector.
Near-infrared spectroscopy paired with machine learning algorithms is digitizing quality assurance workflows in sweetener blending operations. Major condiment and sauce manufacturers in 10th of Ramadan City are deploying these systems to verify potency consistency batch-to-batch. The technology is compressing laboratory testing cycles from hours to minutes, allowing just-in-time adjustment of dosing protocols.
Egypt's pending amendments to front-of-package labeling rules will mandate explicit Arabic disclosure of all sweetener classes across 22 food categories. Industrial consequence includes reformulation of existing product lines to avoid negative consumer perception of artificial sweetener callouts. Beverage categories with high purchase frequency are responding fastest, with several manufacturers accelerating natural sweetener transition timelines.
Direct procurement relationships between food manufacturers and sweetener ingredient houses are displacing traditional distributor intermediaries in Greater Cairo. Large dairy processors in Obour City now negotiate volume contracts directly with Red Sea port operators for monk fruit and stevia raw materials. This channel compression is most visible in segments where annual sweetener spend exceeds threshold levels for dedicated logistics arrangements.
Egypt Food Sweetener Market Segmentation
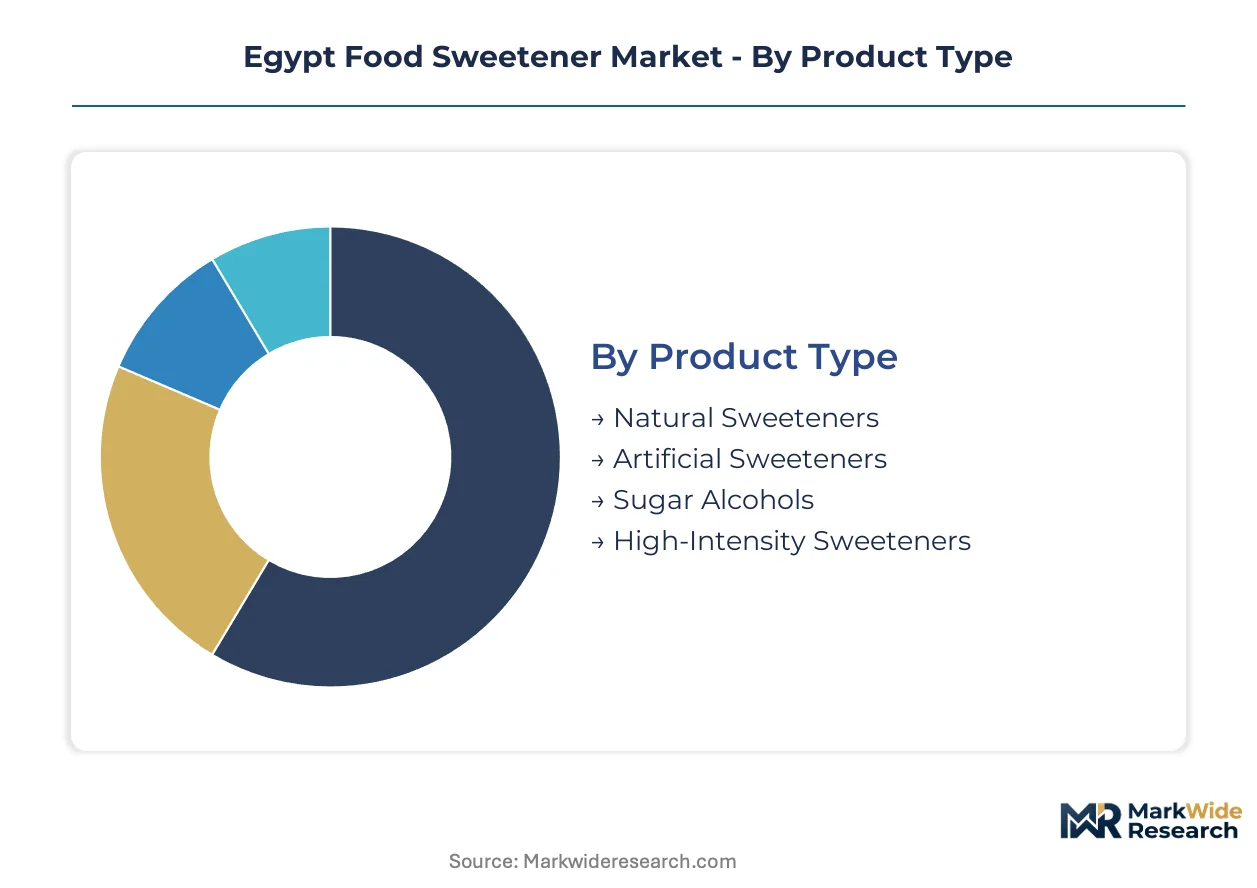
Sweetener procurement patterns in Egypt diverge sharply across product categories and end-use channels, with multinational beverage mandates driving premiumization in some segments while cost minimization dominates others. Understanding these fault lines enables suppliers to align technical capabilities with specific customer workflows across Greater Cairo's manufacturing corridor.
Product Type:
Mature commodity sweeteners coexist with emerging high-potency alternatives, creating a bifurcated supply landscape where fermentation expertise and agricultural sourcing determine competitive position.
- Natural Sweeteners:Steviol glycosides and monk fruit concentrates command premium positioning through Egyptian consumers' association of plant-derived labels with clean eating. Demand concentrates in premium dairy and confectionery channels in Obour City as manufacturers reformulate to avoid negative artificial sweetener callouts under pending NFSA labeling amendments.
- Artificial Sweeteners:Sucralose and aspartame formulations retain cost advantages in high-volume beverage applications. Procurement concentrates in 10th of Ramadan City's contract manufacturing networks where multinational parent companies mandate sugar-reduction targets without price escalation.
- Sugar Alcohols:Erythritol and xylitol serve as bulking agents in reduced-calorie confectionery, requiring specialized handling infrastructure for hygroscopic powders.
- High-Intensity Sweeteners:Sucralose and steviol glycosides with sweetness potencies hundreds of times that of sucrose are expanding fastest as reformulation mandates cascade through Egyptian processing facilities.
Artificial sweeteners retain volume leadership; high-intensity sweeteners hold the steepest expansion curve.
Application:
Cost tier stratification separates commodity-scale procurement from precision-formulation segments where technical service capabilities command premium pricing.
- Beverages:Soft drink and bottled water producers dominate procurement volumes, with multinational brands accelerating steviol glycoside adoption to meet parent-company sugar-reduction targets. Greater Cairo's processing corridor concentrates demand for high-intensity alternatives that replicate sucrose sweetness without caloric load.
- Bakery Products:Maillard reaction requirements and moisture retention needs limit artificial sweetener penetration, preserving sucrose dominance in traditional Egyptian flatbreads and pastries.
- Dairy Products:Flavored milk and yogurt manufacturers in Obour City are transitioning to monk fruit-erythritol blends for premium positioning.
- Confectionery:Hard candy and chocolate segments require specialized texturizing systems to compensate for bulk sugar removal.
Beverages capture the dominant procurement volume; dairy products are climbing the fastest as clean-label positioning penetrates premium channels.
End User:
Customer type determines service intensity, with large food manufacturers demanding dedicated technical support while retail channels prioritize packaging flexibility and minimum order efficiency.
- Food Manufacturers:Industrial-scale bakeries and confectioners in 10th of Ramadan City negotiate long-term contracts with volume-tier pricing and embedded formulation support.
- Beverage Producers:Contract manufacturers serving multinational brands require rapid qualification timelines and Red Sea port logistics integration.
- Retail Businesses:Supermarket private-label programs demand flexible packaging formats and shorter lead times for seasonal product launches.
- Health-Conscious Consumers:Direct-to-consumer channels for diabetic nutrition and ketogenic formulations represent an emerging segment with premium pricing tolerance.
Food manufacturers retain volume leadership; health-conscious consumers hold the steepest expansion curve.
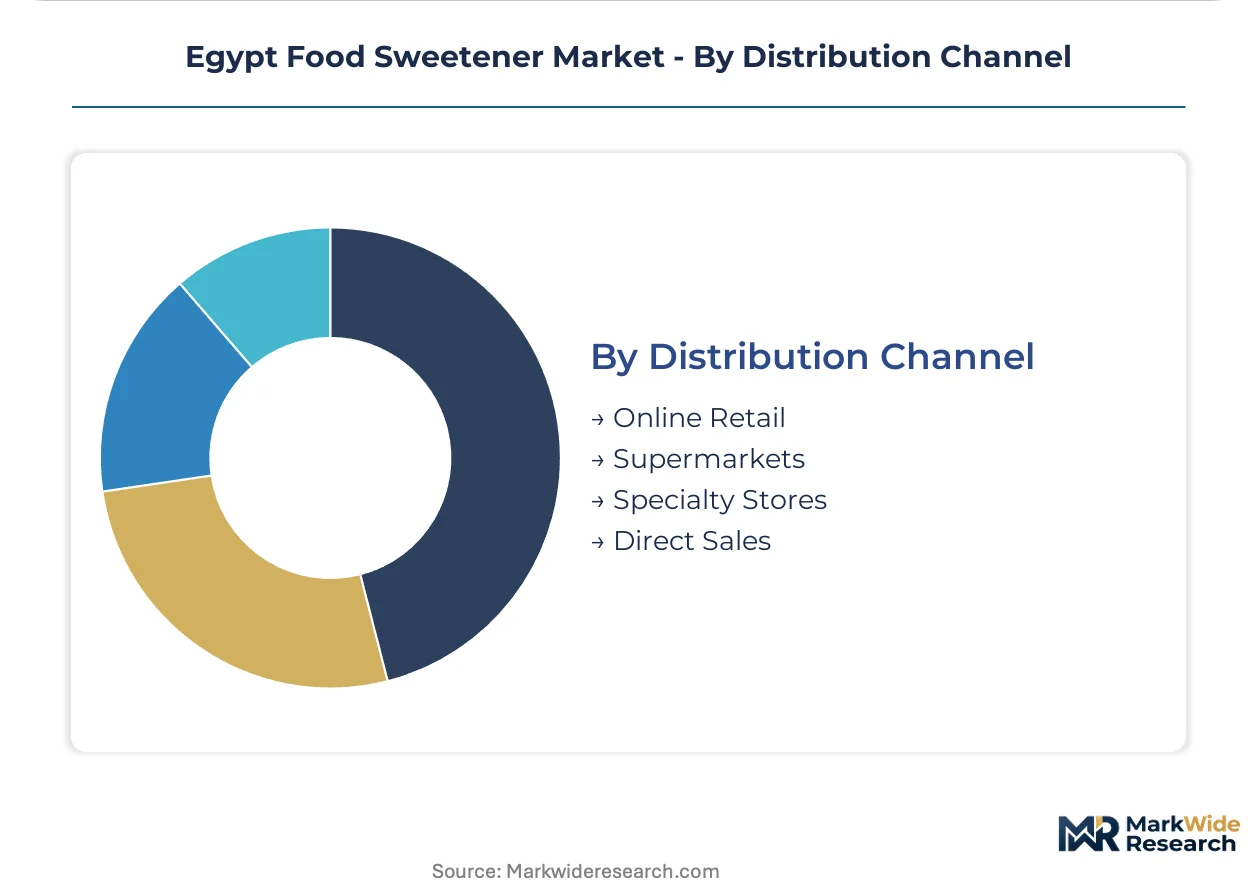
Distribution Channel:
Supply concentration patterns favor direct procurement relationships where annual sweetener spend exceeds threshold levels for dedicated logistics arrangements.
- Online Retail:E-commerce platforms serve health-conscious consumers seeking specialty natural sweeteners unavailable through conventional retail, with demand concentrated in Greater Cairo's affluent districts.
- Supermarkets:Mass-market retail channels drive volume for table-top sweetener packets and private-label alternatives, with shelf placement determined by NFSA-compliant Arabic labeling.
- Specialty Stores:Organic and health-food retailers in Zamalek and Maadi stock premium stevia and monk fruit concentrates targeting diabetic and weight-management consumers.
- Direct Sales:Large dairy and beverage processors in Obour City negotiate volume contracts directly with Red Sea port operators, displacing traditional distributor intermediaries.
Supermarkets retain volume leadership; direct sales are expanding most quickly as channel compression accelerates among large processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial sweetener procurement concentrates in Egypt's Nile Delta manufacturing belt, where beverage and dairy processors cluster near Alexandria and Cairo. Sub-regional specialization divides between Red Sea port logistics hubs and Upper Egypt agricultural processing zones.
Greater Cairo
Obour City and 10th of Ramadan City host the densest concentration of contract beverage manufacturers serving multinational brands. The National Food Safety Authority enforces Arabic front-of-package labeling standards that accelerate reformulation toward natural sweeteners. Dairy processors in this corridor negotiate direct volume contracts with Red Sea port operators for monk fruit and stevia raw materials.
Alexandria and the Northern Coast
Port modernization at Alexandria compresses inbound lead times for fermentation-derived high-intensity sweeteners. Beet sugar refineries in the surrounding Nile Delta agricultural zone supply sucrose to regional bakery and confectionery manufacturers. The Egyptian Organization for Standardization and Quality operates certification facilities here, extending import qualification timelines for novel stevia extracts.
Suez Canal Economic Zone
Ain Sokhna's deep-water port infrastructure anchors Red Sea logistics for Cargill and other multinationals controlling inbound raw material flows. Free zone incentives attract greenfield fermentation facility investments. Industrial-scale microbial cultivation operations here face staffing constraints as local universities produce insufficient biochemical engineers.
Upper Egypt
Sohag and Qena offer lower land and labor costs for natural sweetener extraction operations targeting premium dairy and confectionery channels. Agricultural cooperatives in this region supply raw botanical inputs for steviol glycoside processing. Infrastructure gaps limit scale, though pharmaceutical-grade applications for diabetic nutrition present niche expansion opportunities.
Red Sea Coastal Belt
Hurghada and Safaga serve as transshipment points for monk fruit concentrates arriving from Asian suppliers. Logistics providers here specialize in temperature-controlled handling of hygroscopic high-intensity sweetener powders. Direct procurement relationships between port operators and Greater Cairo food manufacturers are displacing traditional distributor intermediaries in this corridor.
Egypt Food Sweetener Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Egypt's bifurcated procurement landscape. Multinationals with Red Sea logistics infrastructure dominate volume contracts, while regional specialists capture premium natural sweetener segments. Three archetypes define competitive positioning: capital-backed multinationals with backward integration into agricultural inputs, fermentation technology specialists with proprietary microbial cultivation platforms, and natural extraction houses serving clean-label reformulation demand. Capacity expansion and direct port logistics integration represent the dominant competitive moves as manufacturers bypass traditional distribution layers.
Within the multinational tier, Cargill Inc. and Südzucker AG exemplify divergent sourcing strategies—Cargill leveraging Red Sea port control while Südzucker anchors through captive beet sugar refining. Tate & Lyle PLC occupies a position emphasizing formulation systems rather than commodity supply. These three companies represent the capital-intensive archetype that project finance for industrial-scale fermentation facilities increasingly favors.
| Leading Market Players |
|---|
| Koninklijke DSM N.V. |
| Ajinomoto Co., Inc. |
| Cargill Inc. |
| JK Sucralose Inc. |
| Südzucker AG |
| Tate & Lyle PLC |
| DuPont de Nemours Inc. |
| Naturex |
| Ingredion Incorporated |
| Others |
Pricing and Supply Chain Analysis
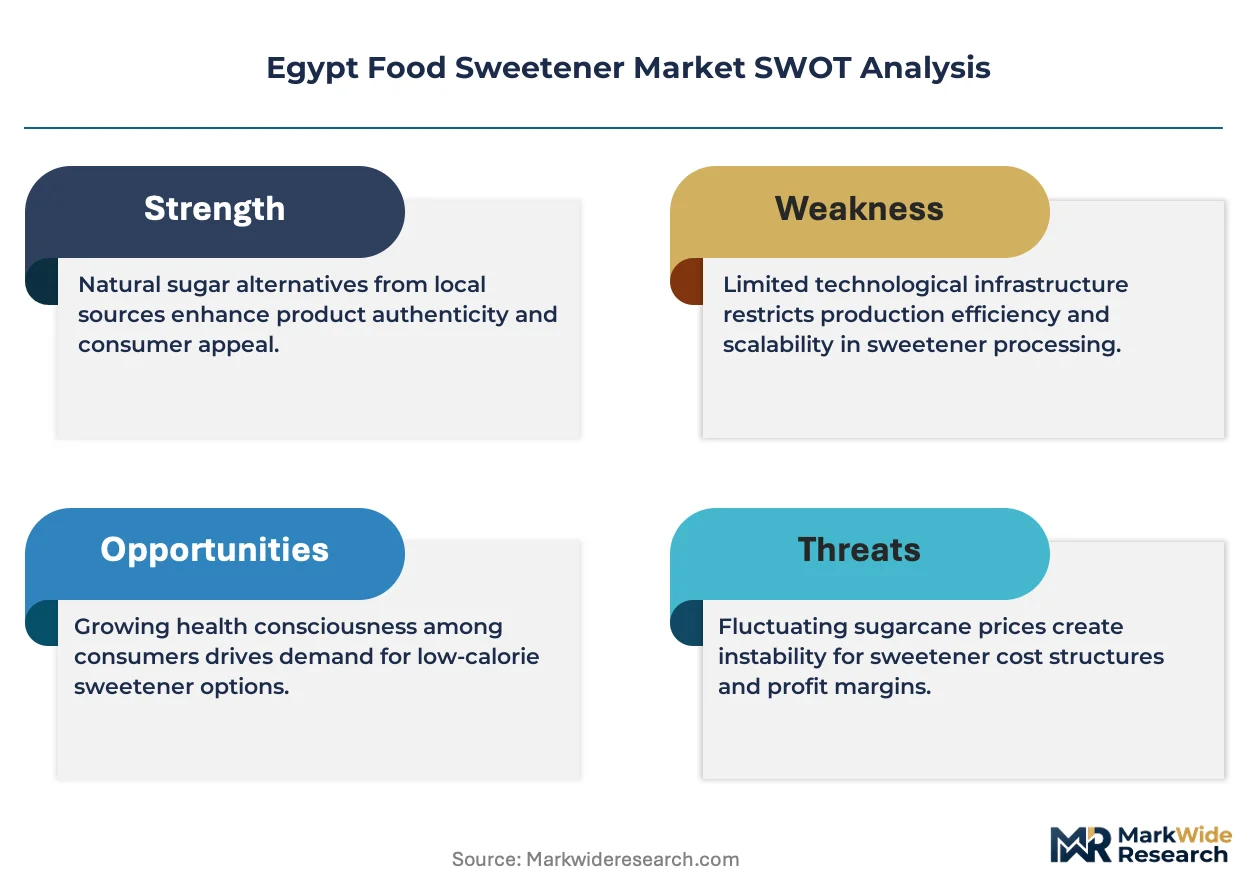
Greater Cairo's Obour City processing corridor concentrates fermentation-derived sweetener capacity, and this supply concentration grants established multinationals outsized leverage in contract negotiations with downstream beverage manufacturers.
Pricing Analysis
Cost-plus contracts indexed to Red Sea freight rates and Nile Delta beet sugar futures dominate procurement arrangements between large processors and ingredient houses. Price differentiation rests on certification grade and volume scale, with Egyptian Organization for Standardization and Quality-certified stevia extracts commanding premiums over uncertified alternatives. Cost compression in artificial sweetener tiers is intensifying because multinational parent companies are cascading sugar-reduction mandates without price escalation allowances. Mass-market beverage producers exhibit highest price sensitivity, while premium dairy manufacturers in Obour City tolerate elevated natural sweetener costs for clean-label positioning.
Supply Chain Analysis
Export-control regimes on fermentation technology and microbial strain IP limit flows of industrial-scale cultivation expertise into Egypt's Suez Canal Economic Zone. Geographic supply concentration centers on China for sucralose fermentation feedstocks, India for stevia raw botanicals, and Thailand for monk fruit concentrates. Raw material dependencies include molasses substrates, chromatographic resins for purification, and specialized desiccants for hygroscopic powder handling. Single-source vulnerability runs through Ain Sokhna's deep-water port infrastructure, where customs clearance delays disrupt just-in-time dosing protocols. Distribution runs through direct procurement relationships between Red Sea port operators and Greater Cairo food manufacturers, displacing traditional distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where National Food Safety Authority labeling mandates create switching costs that lock in qualified suppliers and disadvantage unlicensed competitors.
For Market Incumbents: Insulate market position through backward integration into Nile Delta beet sugar refining and captive Red Sea logistics infrastructure. The emergence of pharmaceutical-grade diabetic nutrition applications threatens to fragment technical service resources across multiple customer archetypes. Priority investment should target certification expansion under Egyptian Organization for Standardization and Quality protocols to preempt novel stevia extract qualification delays. For New Entrants and Emerging Players: Establish a beachhead in Upper Egypt's Sohag and Qena corridor, where lower land and labor costs offset infrastructure gaps for natural sweetener extraction operations. The most penetrable segment lies in specialty organic retailers serving Zamalek and Maadi health-conscious consumers, where direct-to-consumer channels bypass entrenched distributor relationships. A formulation-partnership go-to-market angle with Obour City dairy processors accelerates technical qualification timelines. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational agribusiness parents seeking to divest non-core sweetener ingredient divisions lacking fermentation technology differentiation. Long-term viability across the next decade hinges on positioning for clean-label convergence as Egyptian consumers associate plant-derived labels with quality. The signal to watch is acceleration in National Food Safety Authority front-of-package labeling amendments, which would force artificial sweetener reformulation and expand addressable market for natural alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Beet Sugar Refining | Südzucker AG's Nile Delta agricultural sourcing anchors cost position against volatile import dependencies. |
| Red Sea Port Logistics Control | Cargill Inc.'s Ain Sokhna infrastructure compresses inbound lead times for fermentation-derived sweeteners. |
| Natural Extraction Facility Expansion | Greenfield investments in Sohag and Qena capture Upper Egypt's lower operational cost base. |
| Pharmaceutical-Grade Certification Pathway | Precision-dosed sweetener systems for diabetic nutrition open premium pricing tolerance segments. |
| Direct Procurement Channel Development | Volume contracts between Obour City processors and port operators displace traditional distribution layers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of National Food Safety Authority regulatory filings, Egyptian Organization for Standardization and Quality certification databases, and Red Sea port customs records. Primary interviews engaged formulation scientists at beverage contract manufacturers, procurement directors at Obour City dairy processors, and distribution managers serving 10th of Ramadan City industrial zones. Secondary validation drew from trade flow data, agricultural cooperative export statistics, and industrial real estate transaction records. Bottom-up segment sizing triangulated against top-down macroeconomic consumption indicators.
Forecast inputs span product type segmentation across natural, artificial, sugar alcohol, and high-intensity sweetener categories; application channels including beverages, bakery, dairy, and confectionery; and end-user archetypes from multinational contract manufacturers to health-conscious direct consumers. CAGRs were derived through regression analysis of historical procurement volumes against reformulation mandate timelines and labeling regulatory evolution. Industry-specific inputs include Nile Delta agricultural yield cycles and Red Sea freight rate volatility indices.
Stress conditions across beet sugar price volatility, Egyptian Organization for Standardization and Quality certification timeline extensions, and Red Sea logistics disruption scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding multinational parent company sugar-reduction target persistence and National Food Safety Authority regulatory implementation schedules. Material shifts in front-of-package labeling amendment timing or Suez Canal transit capacity constraints would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Maltodextrin Market
Sweeteners
Food Sweetener Market
Sweeteners
China Allulose Market
Sweeteners
Argentina Food Sweetener Market
Sweeteners
North America Starch Sweetener Market
Sweeteners
Sugar Beet Juice Extract Market
Sweeteners
Smoked Sugar Market
Sweeteners
Middle East and Africa Sugar Substitutes Market
Sweeteners
Liquid Sugar Market
Sweeteners
Non Sugar Sweeteners Market
Sweeteners
Japan Allulose Market
Sweeteners
Middle East and Africa Food Sweetener Market
Sweeteners
Sucrose Esters Market
Sweeteners
Galactose Market
Sweeteners
Corn Syrup Market
Sweeteners
Sweeteners Market